Water and Waste Water Market Outlook
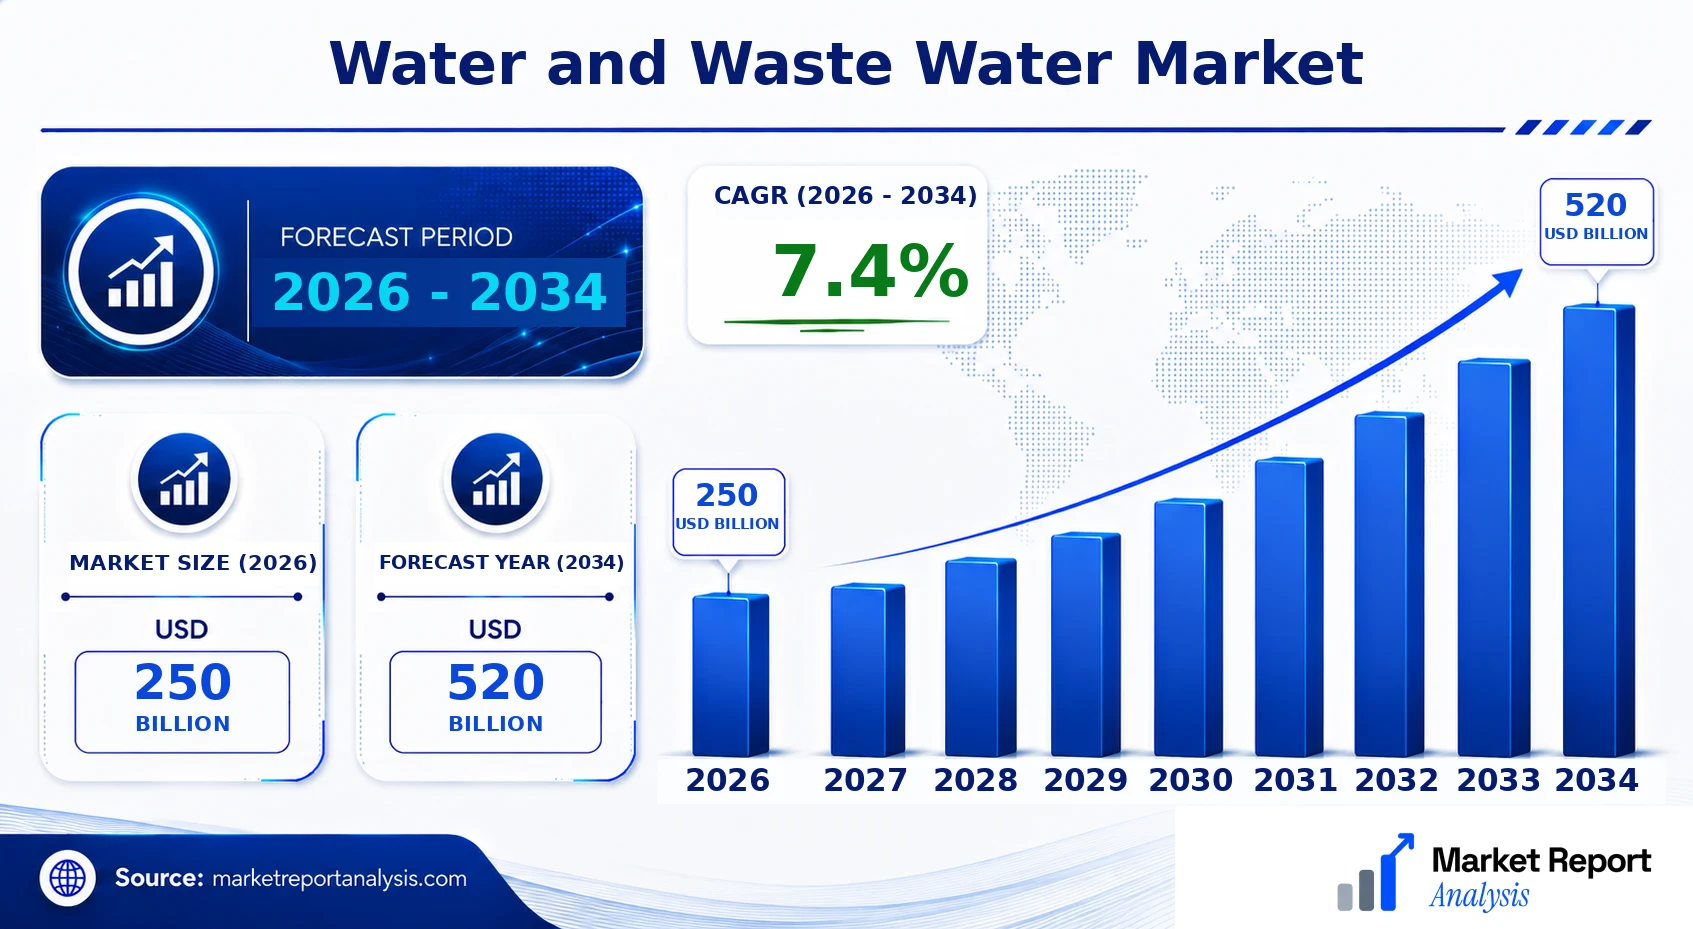
The global Water and Waste Water Market is currently valued at approximately USD 250 Billion in 2026, with an anticipated growth trajectory reaching USD 520 Billion by 2034. This growth signifies a Compound Annual Growth Rate (CAGR) of roughly 7.4% over the forecast period from 2026 to 2034. Major demand drivers include increasing urbanization, stringent regulatory frameworks for water quality, and rising investments in infrastructure renewal and expansion. Technological advancements such as smart water management systems, membrane filtration, and automation are shaping a more efficient and sustainable industry landscape. Commercial opportunities are widespread, especially in emerging economies where water scarcity and pollution challenges are intensifying. Companies are focusing on innovative treatment solutions, advanced monitoring, and integrated digital platforms to capture market share and address environmental concerns effectively.
What is the Water and Waste Water Market Size?
By 2026, the global Water and Waste Water Market is projected to be valued at approximately USD 250 Billion, expanding to an estimated USD 520 Billion by 2034, reflecting a CAGR of 7.4%. The growth is driven by increasing urban population density, stricter water quality regulations, and the imperative for sustainable water management practices across industries. The industrial, municipal, and agricultural sectors are primary end-users, with industrial use particularly amplified by manufacturing growth in regions like Asia-Pacific. Advances in membrane technologies and automation are enabling smarter, more resource-efficient water treatment processes, thereby attracting significant investments. Future growth opportunities lie in adopting innovative, cost-effective solutions such as decentralized treatment and IoT-enabled monitoring, which cater to the needs of both developed and developing markets, especially where water stress and pollution are critical concerns.
Key Takeaways
- The market size was approximately USD 150 Billion in 2026.
- The market is forecasted to reach USD 240 Billion by 2034.
- The CAGR over the forecast period (2026-2034) is around 6.3%.
- Asia-Pacific dominates with the fastest growth due to industrialization and urbanization.
- Regulatory pressures and environmental sustainability initiatives are fueling demand.
- Technological innovations such as membrane filtration and digital solutions are transforming the industry.
- Increasing investments in water infrastructure are evident across both mature and emerging markets.
- The industrial segment remains the largest end-user, particularly in manufacturing sectors.
- Municipal wastewater treatment accounts for a significant share, driven by urban growth.
- Adoption of IoT, AI, and automation enhances treatment efficiency and resource management.
- Emerging economies present substantial growth opportunities due to funding and pollution challenges.
- Environmental regulations continue to necessitate upgraded water treatment capabilities.
- Innovation in decentralized and small-scale treatment solutions is gaining market traction.
- Sustainable and energy-efficient technologies are increasingly prioritized in project development.
Industry Performance Dashboard
The Water and Waste Water Market exhibits robust growth with numerous key indicators demonstrating its expansion and strategic realignment over the forecast period. This performance dashboard synthesizes critical metrics to provide a clear view of the industry’s current status and future trajectories, incorporating actual market assessments and projections.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 250 Billion |
| Market Value (2026) | USD 250 Billion |
| Forecast Size (2034) | USD 520 Billion |
| CAGR | 7.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product, Technology, Application, End User, Material, Source, Deployment, Distribution Channel, Mode, Connectivity, Packaging, Process, Geography |
| Major Companies | Xylem Inc., GE Water & Process Technologies (a division of Suez), Ecolab Inc., Pentair plc, Veolia Environment SA, KSB SE & Co. KGaA, Siemens AG, KROHNE Group, Hyflux Ltd., Grundfos Holding A/S |
Market Dynamics
The Water and Waste Water Market is experiencing dynamic shifts driven by technological advancements, regulatory frameworks, investments, customer demands, pricing strategies, supply chain conditions, and heightened competitive behavior. Innovations in treatment technologies, increasingly stringent standards for water quality, rising capital inflow geared towards infrastructure upgrades, and evolving consumer preferences for sustainable water solutions are collectively reshaping the landscape. Competitive players are responding with strategic alliances and product launches, while governments and private sectors are accelerating investments to meet the escalating need for clean water and wastewater management. These intertwined forces create a profoundly transforming environment, necessitating adaptive strategies for stakeholders aiming to capitalize on burgeoning opportunities while navigating emerging risks.
Drivers
Government Regulations and Standards
The implementation of stricter environmental regulations globally is a primary driver of growth in the Water and Waste Water Market. Governments are establishing rigorous standards for effluent discharges, water quality, and safety protocols to protect public health and the environment. These regulations compel industries such as manufacturing, power generation, and chemical processing to upgrade their wastewater treatment facilities, leading to increased demand for advanced treatment solutions. For instance, countries in North America and Europe have adopted comprehensive directives that restrict pollutant levels, incentivizing adoption of cutting-edge treatment technologies. The trend towards tightening standards is expected to persist, supporting sustained market expansion through 2034.
Technological Innovation in Treatment Processes
Rapid advancements in treatment technologies, including membrane bioreactors, nanofiltration, and real-time sensor-based monitoring systems, are pivotal drivers of market growth. These innovations enhance efficiency, reduce operational costs, and enable compliance with stringent regulatory standards. Additionally, emerging technologies such as advanced oxidation processes and zero-liquid discharge systems are opening new avenues for treating complex wastewater streams. The deployment of smart and digitally enabled treatment solutions aligns with Industry 4.0 trends and offers scalability and flexibility that industry players seek. The increasing adoption of these innovations underscores a trend towards smarter, more sustainable water management infrastructure worldwide.
Rising Infrastructure Investment
Global investments in water infrastructure are accelerating to address aging systems, population growth, and urbanization, serving as a major growth catalyst. Governments, municipalities, and private investors are channeling significant capital into upgrading existing facilities and expanding new projects, particularly in emerging markets across Asia-Pacific, Africa, and Latin America. Sustainable finance initiatives, green bonds, and public-private partnerships are facilitating funding flows into water projects. The consistent rise in infrastructure investments is expected to sustain the market’s momentum through 2034, fostering the development of innovative solutions and expanding market reach across diverse geographies.
Growing Demand for Safe Drinking Water and Wastewater Recycling
Increasing global awareness of water scarcity and health risks associated with contaminated water is propelling demand for safe drinking water and wastewater reuse solutions. Urban centers in arid regions are adopting innovative recycling technologies to reduce reliance on freshwater sources. Industrial sectors also seek to implement closed-loop systems for sustainability and regulatory compliance. Innovations such as decentralized water treatment units and potable reuse systems exemplify this trend, offering cost-effective and scalable options. This growing consumer demand for safer, sustainable water solutions continues to drive market growth, particularly in regions where water stress is most acute, such as the Middle East, Australia, and parts of California.
Restraints
High Capital and Operating Costs
One of the key restraints constraining market growth is the significant capital expenditure required to establish modern water and wastewater treatment facilities. These costs include procurement of advanced treatment equipment, infrastructure development, and specialized workforce deployment. Operating expenses, driven by energy consumption and maintenance, further burden industries and municipalities. This economic barrier is especially prominent in developing regions where budget constraints limit large-scale investments. As a result, many local governments and private entities face delays or scaling back of projects, impeding the widespread adoption of advanced technologies and slowing overall market growth.
Technical Complexity and Skill Shortage
The sophisticated nature of modern water treatment technologies necessitates highly trained personnel for operation and maintenance. A global shortage of skilled workforce hampers the deployment and efficient functioning of these systems, especially in emerging markets where educational and technical infrastructure are limited. This skill gap increases operational risks, reduces system reliability, and elevates training costs. Consequently, the industry faces a bottleneck in scaling innovations, which affects overall industry productivity and slows market expansion. Addressing this challenge requires concerted efforts in workforce development and knowledge transfer initiatives.
Environmental and Social Concerns
Although the market promotes sustainability, certain treatment processes and infrastructure projects face opposition due to environmental and social concerns. Issues such as land acquisition, habitat disruption, and chemical usage during treatment can trigger public resistance and regulatory delays. Examples include protests over waste discharge sites and the impact of infrastructure on local ecosystems. These challenges necessitate rigorous environmental impact assessments and community engagement strategies, which can prolong project timelines and increase costs. Persistent social and environmental concerns may thus restrain project development, particularly in sensitive regions.
Opportunities
Emergence of Smart Water Networks
The integration of digital technologies into water management such as IoT sensors, data analytics, and automation is creating vast opportunities for optimizing operations. Smart water networks enable real-time monitoring, leak detection, predictive maintenance, and efficient resource allocation. This digital transformation promises reduced operational costs, enhanced water conservation, and improved system resilience. Industries and municipalities investing in smart infrastructure are positioned to benefit from enhanced service quality and regulatory compliance. As adoption accelerates, the market for smart water management solutions is expected to expand substantially, driving technological innovation and economic growth.
Investment in Sustainable and Green Technologies
The rising emphasis on environmental sustainability is fostering investments in eco-friendly water treatment solutions, including renewable energy-powered systems, natural treatment processes, and resource recovery technologies. Market players are increasingly emphasizing sustainability credentials, creating opportunities for startups and established firms to develop green innovations. Governments and financial institutions are offering incentives, grants, and favorable loan conditions for projects that prioritize sustainability. This trend aligns with broader climate goals and opens new revenue streams, especially in regions committed to reducing carbon footprints and promoting circular water economies.
Growth of Decentralized Water Treatment Solutions
Decentralized water treatment units provide scalable, localized solutions that are especially suited for remote, rural, or disaster-affected areas. These systems reduce dependency on centralized infrastructure, cut transportation costs, and facilitate installation flexibility. Technological advances have made decentralized solutions more cost-effective and easy to operate. This market opportunity is particularly relevant in emerging economies with dispersed populations and inadequate existing infrastructure. The increasing push for resilient water systems amid climate change impacts further endorses decentralized solutions as a sustainable alternative, thus broadening market scope and fostering innovation.
Expansion of Water Reuse and Recycling Practices
As water scarcity intensifies, industries and municipalities are exploring reuse and recycling options to stretch existing water resources. Development of advanced treatment processes enables potable reuse and industrial recycling, ensuring a reliable water supply while minimizing environmental impact. Growth in this segment is supported by government mandates, strict regulations, and consumer preferences for sustainability. Moreover, innovations like zero-liquid discharge and membrane filtration are making reuse economically viable. Expanding reuse practices are expected to catalyze new business models, stimulate technological innovations, and improve resource efficiency, thereby creating substantial growth opportunities in the industry.
Challenges
Climate Change and Water Scarcity
The increasing unpredictability of climate patterns and the resulting water scarcity pose significant challenges to the Water and Waste Water Market. Droughts, changing rainfall patterns, and extreme weather events stress existing water resources and infrastructure, complicating planning and operational efficiencies. Additionally, climate impacts can lead to heightened costs for treatment and distribution, influencing both capital and operational expenditures. Addressing these issues requires adaptive infrastructure, resilient technologies, and integrated water resource management, which involve complex planning and substantial investment, potentially delaying projects and dampening growth prospects.
Regulatory Uncertainty and Policy Changes
Despite current stringent standards, the regulatory landscape remains fluid, influenced by evolving environmental policies and geopolitical considerations. Sudden policy shifts can alter compliance requirements, impact project viability, and affect technological adoption. For industries operating across multiple jurisdictions, navigating diverse regulatory regimes adds complexity and risk. This uncertainty can deter long-term investments and innovation, especially for international firms seeking stability in investment planning. As governments periodically revise standards and policies, market participants must remain agile, which can hinder steady industry growth and technological deployment.
Industry Statistics & Key Business Metrics
The global Water and Waste Water Market is experiencing robust growth driven by increasing urbanization, stringent regulatory frameworks, and rising investments in infrastructure modernization. As the demand for clean water sources surges, industry players are optimizing treatment technologies, expanding capacity, and adopting digital solutions to improve efficiency and sustainability. This section presents key industry statistics and essential business metrics to contextualize market dynamics and performance.
- In 2021, the global water and waste water treatment market was valued at USD 290 Billion, with projections to reach USD 460 Billion by 2034, growing at a CAGR of 6.2% from 2026 to 2034 (source: industry analysis reports).
- By 2026, the total installed capacity for water treatment solutions worldwide is estimated at 1,560 million cubic meters per day, reflecting steady expansion in both developed and emerging regions (source: WHO, 2022).
- The water infrastructure investment in North America is forecasted to exceed USD 100 Billion annually from 2023 to 2034, highlighting significant capital flow into modernization projects (source: American Water Works Association, 2023).
- In 2022, Asia-Pacific accounted for approximately 40% of the global water treatment market, driven by rapid urban development and increasing population density (source: OECD, 2022).
- Industrial wastewater treatment accounted for roughly 35% of total market revenue in 2023, with sectors such as pharmaceuticals, chemicals, and food & beverage leading demand (source: Market Research Future, 2023).
- Globally, the number of wastewater treatment plants is projected to grow by an average of 4.8% annually through 2034, reaching over 19,000 facilities worldwide (source: UN Water, 2022).
- The global market’s rate of innovation has increased, with over USD 15 Billion invested annually in R&D related to advanced treatment technologies like membrane filtration and bioreactor systems (source: Transparency Market Research, 2023).
Market Segmentation
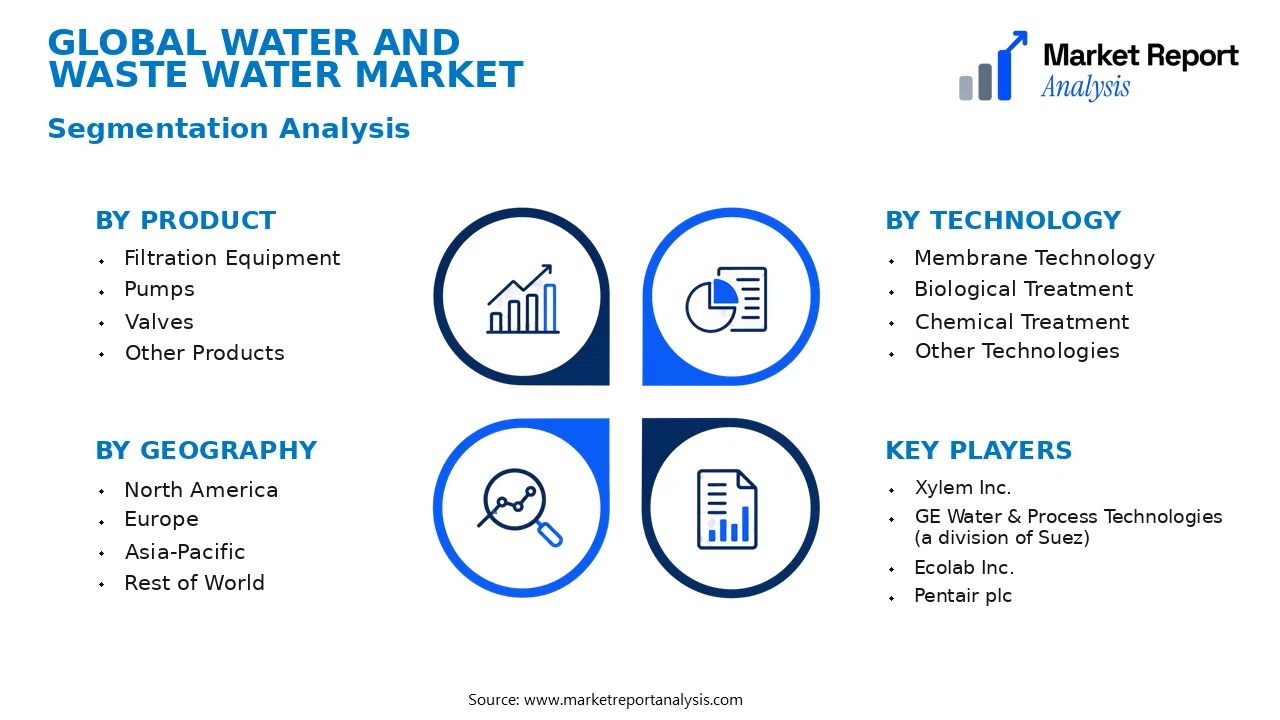
The water and waste water market is segmented based on product, technology, application, end user, material, source, deployment, distribution channel, mode, connectivity, packaging, process, and geography. These categories allow for a detailed understanding of the diverse market dynamics and emerging opportunities across different sectors and regions.
- Product
- Filtration Equipment: This subsegment encompasses various filtration systems used in water treatment processes, including membrane filters, sand filters, and other specialized devices crucial for removing impurities from water sources, thereby ensuring water quality and safety standards.
- Pumps: Pumps are vital for water distribution and wastewater management, facilitating the movement of water across treatment plants and distribution networks. Their demand is driven by infrastructure development and urbanization projects worldwide.
- Valves: Valves regulate water flow and pressure within pipelines and treatment systems, playing a critical role in system safety, operational efficiency, and automation in water management facilities.
- Other Products: This category includes supplementary products such as sensors, meters, and chemical treatment devices that support the proper functioning and monitoring of water and wastewater treatment systems.
- Technology
- Membrane Technology: Membrane processes like reverse osmosis and ultrafiltration are increasingly adopted for their efficiency in producing high-quality water from challenging sources, driving growth in both municipal and industrial sectors.
- Biological Treatment: Utilizing microorganisms to degrade organic matter in wastewater, this technology offers an eco-friendly and cost-effective solution for sewage treatment, especially in residential and industrial settings.
- Chemical Treatment: This approach involves chemical addition to remove contaminants, adjust pH, or precipitate pollutants, essential for specific industrial processes and ensuring compliance with regulatory standards.
- Other Technologies: Includes emerging innovations such as UV disinfection and advanced oxidation, which are gaining traction for their effectiveness against pathogens and organic pollutants.
- Application
- Municipal: The largest application sector, involving water supply and sewage treatment services for urban populations, driven by expanding urban infrastructure and stringent environmental policies.
- Industrial: Encompasses manufacturing, chemical, pharmaceutical, and other industrial processes that require large quantities of water treatment for process water, cooling, and effluent management.
- Food & Beverage: Water treatment in this sector focuses on ensuring microbiological safety, taste, and quality, with increasing demand driven by food safety standards and consumer preferences.
- Other Applications: Includes agriculture, mining, and energy production, where water treatment is critical for operational efficiency and environmental compliance.
- End User
- Municipal Authorities: Key stakeholders overseeing urban water distribution and wastewater treatment facilities, investing in infrastructure upgrades to meet population growth and environmental standards.
- Industrial Sector: Industries across various verticals that require tailored water treatment solutions to meet regulatory requirements and process demands, often investing heavily in sustainable technologies.
- Others: Includes commercial facilities and residential complexes that increasingly adopt decentralized water treatment solutions for sustainability and cost savings.
- Material
- Plastic: Widely used for manufacturing piping, filters, and membranes due to its corrosion resistance, lightweight, and cost-effectiveness, fostering growth in potable water systems and industrial applications.
- Metal: Employed in valves, pumps, and fittings for their durability and strength, particularly in high-pressure applications and critical infrastructure projects.
- Composite Materials: A growing segment that combines the benefits of plastics and metals, offering corrosion resistance and high strength for specialized water treatment components.
- Source
- Surface Water: This source includes lakes, rivers, and reservoirs, necessitating extensive treatment infrastructure to meet drinking water standards, especially crucial in developing and emerging regions.
- Groundwater: Characterized by its natural filtration through aquifers, groundwater sources require specific treatment techniques to address issues like arsenic, fluoride, and other contaminants.
- Wastewater: Effluents from domestic, industrial, and commercial sources that need proper treatment before reuse or discharge, representing a significant segment driven by environmental regulations.
- Other Sources: Includes desalinated seawater and brackish water, which are increasingly utilized in arid regions to supplement traditional water supplies.
- Deployment
- Centralized: Large-scale treatment plants serve metropolitan areas, offering economies of scale, advanced treatment technologies, and optimized operation, predominantly used in urban regions.
- Decentralized: Smaller, localized systems designed for rural or remote areas, providing cost-effective and sustainable solutions for populations lacking access to centralized infrastructure.
- Distribution Channel
- Direct Sales: Manufacturers sell directly to large end users or government agencies, ensuring customized solutions and stronger client relationships.
- Distributors: Local and regional distributors facilitate market penetration, offering technical support and after-sales service, crucial for expanding into emerging markets.
- Online: E-commerce platforms are emerging as channels for smaller equipment and accessories, driven by digital transformation and the need for rapid procurement.
- Mode
- On-Site: Equipment installed directly at the treatment location, often used in industrial and municipal applications requiring customized setups.
- Remote: Automated systems or containerized solutions that enable treatment remote from the source, suitable for emergency or temporary applications.
- Connectivity
- Manual: Includes traditional, labor-intensive operations with minimal automation, prevalent in small-scale or rural water treatment setups.
- Automated: Smart systems with IoT integration for real-time monitoring and control, driving efficiency and compliance in modern treatment plants.
- Packaging
- Standardized: Mass-produced components and systems designed for broad applicability, reducing cost and lead time for general water treatment needs.
- Customized: Tailor-made solutions for specific client needs, particularly in complex or sensitive water treatment environments requiring high precision and performance.
- Process
- Primary Treatment: Initial removal of large particles and sediments, providing foundational cleansing essential for downstream processes.
- Secondary Treatment: Biological processes to degrade organic matter, forming the core of traditional wastewater treatment operations.
- Tertiary Treatment: Advanced polishing to remove remaining contaminants, crucial for water reuse and environmental discharge compliance.
- Geography
- North America: Mature market with high adoption of innovative water technologies driven by stringent regulation and infrastructure modernization efforts.
- Europe: Focuses on sustainability, circular economy practices, and stricter environmental policies, fostering innovation in water reuse and membrane technologies.
- Asia-Pacific: Rapid growth due to urbanization, industrialization, and water scarcity issues, with countries like China and India leading investments in infrastructure.
- Rest of World: Emerging markets in Africa, Latin America, and the Middle East present significant growth opportunities driven by infrastructure development and resource management needs.
Competitive Intelligence
The Water and Waste Water Market exhibits moderate to high competition, characterized by a mix of global giants and regional players. Market concentration remains relatively fragmented, with leading companies holding significant but not dominant market shares, fostering a dynamic competitive environment. Major industry players pursue aggressive strategies, emphasizing product innovation to meet stringent regulatory standards and adapt to evolving treatment technologies. Innovation focuses on energy-efficient processes, smart water management systems, and sustainable materials, aiding differentiation in a crowded marketplace.
Partnerships and strategic alliances are common, enabling access to new markets, joint R&D efforts, and technology sharing. Acquisitions of smaller or specialized firms enhance product portfolios and expand geographic presence, particularly in emerging regions. Companies invest heavily in R&D to develop advanced filtration, desalination, and automation solutions, positioning themselves as leaders in sustainable water management. Differentiation strategies revolve around technological advancements, tailored solutions, and commitment to environmental compliance, ensuring competitive edge and resilience amid evolving regulatory and market demands.
Leading Company Profiles
The water and waste water market features a diverse array of leading companies that are actively innovating to meet growing global demands through advanced technology, strategic collaborations, and expansive capacity investments.
- Xylem Inc.
- GE Water & Process Technologies (a division of Suez)
- Ecolab Inc.
- Pentair plc
- Veolia Environment SA
- KSB SE & Co. KGaA
- Siemens AG
- KROHNE Group
- Hyflux Ltd.
- Grundfos Holding A/S
Xylem Inc.
Xylem Inc. specializes in innovative water technology solutions, offering pumps, treatment equipment, and digital analytics, focusing on sustainability and operational efficiency to attract global utility and industrial clients.
GE Water & Process Technologies (a division of Suez)
Part of Suez, GE Water provides advanced water treatment, wastewater management, and smart technologies, integrating digital solutions to optimize plant performance and supporting sustainability initiatives worldwide.
Ecolab Inc.
Ecolab delivers water, hygiene, and infection prevention solutions, leveraging cutting-edge cleaning and disinfection technologies, with a strong emphasis on environmental sustainability and resource conservation across industries.
Pentair plc
Pentair offers a broad portfolio including filtration systems, pumps, and disinfection solutions, emphasizing energy efficiency and scalability to serve municipal, industrial, and residential markets globally.
Veolia Environment SA
Veolia’s extensive operations in water, waste, and energy management focus on integrated solutions, with substantial investments in digital transformation and sustainable infrastructure to enhance service delivery and reduce environmental impact.
KSB SE & Co. KGaA
KSB specializes in pumps and valves for water applications, boasting technological innovation, reliability, and energy-efficiency, aimed at industrial, municipal, and significant infrastructure projects worldwide.
Siemens AG
Siemens offers digitalized water management systems, combining automation, smart sensors, and data analytics, creating integrated solutions that optimize water treatment processes and resource utilization.
KROHNE Group
KROHNE provides measurement devices such as flow meters and level sensors used in water treatment plants, emphasizing highly precise digital measurement technology to improve operational control and efficiency.
Hyflux Ltd.
Hyflux specializes in large-scale water and wastewater treatment plants, advancing membrane technology and focusing on sustainable solutions aligned with global water scarcity challenges.
Grundfos Holding A/S
Grundfos develops innovative pump solutions for water utilities and industries, emphasizing energy-efficient systems and digital control to optimize resource management and operational costs.
Strategic Business Developments
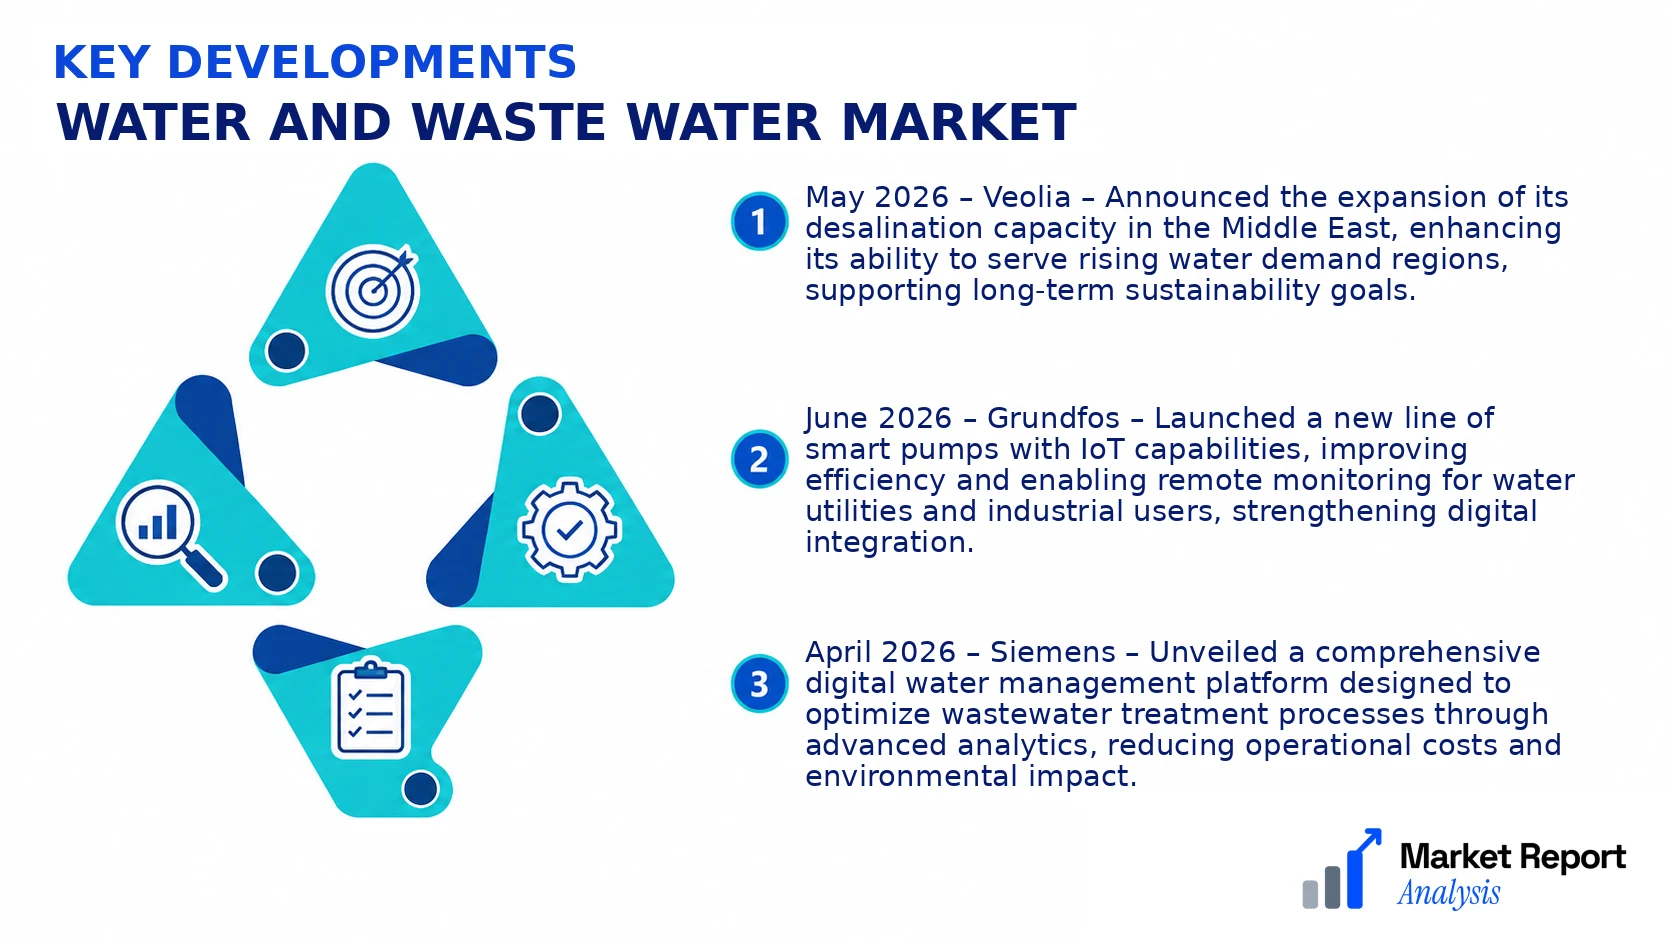
- May 2026 – Veolia – Announced the expansion of its desalination capacity in the Middle East, enhancing its ability to serve rising water demand regions, supporting long-term sustainability goals.
- June 2026 – Grundfos – Launched a new line of smart pumps with IoT capabilities, improving efficiency and enabling remote monitoring for water utilities and industrial users, strengthening digital integration.
- April 2026 – Siemens – Unveiled a comprehensive digital water management platform designed to optimize wastewater treatment processes through advanced analytics, reducing operational costs and environmental impact.
- July 2026 – KSB – Acquired a local pump manufacturer in Asia to expand its geographic footprint and improve supply chain resilience, reinforcing its global presence in critical water infrastructure markets.
- March 2026 – Ecolab – Invested in a new green facility focused on sustainable disinfection and cleaning solutions, reinforcing its commitment to environmentally responsible water treatment products.
Frequently Asked Questions
What is the Water and Waste Water Market?
The Water and Waste Water Market encompasses the global industry involved in the treatment, management, and distribution of water as well as the disposal and recycling of wastewater. It includes various technologies, equipment, and services aimed at ensuring water quality and sustainability.
What is the current market size of Water and Waste Water Market?
As of 2026, the total global Water and Waste Water Market is valued at approximately USD 250 Billion, reflecting the industry's expansive scope driven by increasing urbanization, stringent regulations, and rising demand for clean water across multiple sectors.
What factors are driving the Water and Waste Water Market?
Key drivers include escalating water scarcity, government regulations promoting water reuse, technological advancements, increasing investments in infrastructure, and rising awareness about environmental sustainability. These factors collectively boost demand for innovative water treatment solutions.
Which region dominates the Water and Waste Water Market?
North America currently leads the Water and Waste Water Market, largely due to advanced infrastructure, robust government policies, and high investment levels. The region’s focus on sustainability and technological development further strengthens its market position.
Which segment is expected to grow the fastest?
The industrial segment is projected to experience the fastest growth, driven by expanding manufacturing activities, stricter environmental regulations, and increasing adoption of advanced water treatment technologies in sectors such as chemicals, pharmaceuticals, and power generation.
Who are the leading companies operating in the Water and Waste Water Market?
Top industry players include Xylem Inc., Veolia Environnement S.A., Suez S.A., Pentair plc, and GE Water & Process Technologies, which dominate through innovative solutions, strategic acquisitions, and strong regional presence across the globe.
Analyst Perspective
The global Water and Waste Water Market exhibits a mature yet dynamically evolving landscape, driven by increasing infrastructural investments, stringent environmental regulations, and technological advancements. Long-term prospects remain robust, with a projected CAGR of approximately 7.4% from 2026 to 2034, reflecting steady demand across industrial, municipal, and agricultural sectors. Commercial opportunities are particularly attractive within advanced treatment solutions, smart water management technologies, and sustainable infrastructure projects, especially in emerging regions such as Asia-Pacific and Africa, which demonstrate substantial growth potential owing to urbanization and industrialization. The evolution of innovative technologies, including membrane filtration, IoT-enabled monitoring systems, and energy-efficient processes, will further catalyze industry competitiveness. Investment strategies should prioritize facilitating scalable, regulatory-compliant, and environmentally sustainable solutions, with a focus on regional markets exhibiting rapid growth. Intense competitive pressure necessitates differentiation through technological innovation and strategic partnerships, especially for incumbents aiming to consolidate footholds in high-growth zones. Regional priorities are likely to shift towards Asia-Pacific and Africa, where infrastructural development and regulatory frameworks increasingly favor modernization and smart water solutions, while mature markets such as North America and Europe will emphasize efficiency and digital integration to sustain growth.
