North America Water and Waste Water Market Outlook
The North America Water and Waste Water Market is currently valued at approximately USD 120 Billion in 2026. It is projected to grow to around USD 170 Billion by 2034, registering a CAGR of about 4.3% over the period from 2026 to 2034. This growth is driven by increasing urbanization, stricter environmental regulations, and a rising focus on sustainable water management. Technological advancements such as smart monitoring systems, membrane filtration, and automation are transforming water treatment processes. The market also presents substantial commercial opportunities in infrastructure modernization, advanced treatment solutions, and digital water management services. Governments and private sectors are investing heavily in water infrastructure upgrades to meet regulatory standards and ensure water security, which further stimulates market expansion and innovation.
What is the North America Water and Waste Water Market Size?
The North America Water and Waste Water Market size is estimated at approximately USD 120 Billion in 2026 and is expected to reach around USD 170 Billion by 2034, expanding at a CAGR of about 4.3% from 2026 to 2034. This buoyant growth is propelled by rising industrial activities, urban population growth, and increasing environmental regulations that necessitate advanced water treatment solutions. Major end-use industries include municipal water utilities, chemical manufacturing, power generation, and food & beverage processing. Technology impacts such as membrane bioreactors, IoT-enabled monitoring, and energy-efficient filtration systems are enhancing operational efficiencies and compliance. Future investment opportunities lie in innovative treatment technologies, digital water management platforms, and infrastructure renewal projects. The market's growth trajectory indicates significant opportunities for stakeholders to develop sustainable, cost-effective, and resilient water management solutions, addressing the dual challenge of water scarcity and regulatory compliance in the region.
Key Takeaways
- The North America Water and Waste Water Market was valued at approximately USD 120 Billion in 2026.
- It is forecasted to reach USD 170 Billion by 2034, growing at a CAGR of around 4.3%.
- The municipal water utility segment holds the largest market share.
- The fastest-growing segment is advanced membrane filtration technologies.
- Municipal water treatment remains the predominant application.
- Industrial wastewater treatment is the fastest-growing application segment.
- The municipal sector is the largest end user, driven by infrastructure upgrades.
- Investment focus is shifting towards digital water management and smart infrastructure.
- Stringent regulations and increasing environmental concerns are key drivers.
- Technological innovations such as IoT, AI, and energy-efficient systems are reshaping the industry.
- Public-private partnerships are playing an increasing role in funding infrastructure projects.
- Major players are expanding their portfolios into sustainable and digital solutions.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the North America water and wastewater market, reflecting its current dynamics and future outlook. As of 2026, the market value stands at USD 45.2 Billion, underscoring its significant economic footprint. The market is projected to grow through 2034, reaching an estimated USD 89.7 Billion, fueled by increasing demand for sustainable water management solutions and stringent regulatory standards. The compound annual growth rate (CAGR) from 2026 to 2034 is forecasted at 9.4%, indicating robust growth potential.
The base year for analysis is 2026, with the forecast period spanning from 2026 to 2034. The market segments covered include water treatment, wastewater treatment, and related services, each experiencing distinct growth trajectories driven by technological advancements and infrastructure investments. Leading companies in the sector, such as Xylem Inc., SUEZ, Veolia Environnement, and Pentair plc, play pivotal roles in market evolution, innovating in areas such as membrane technologies, smart sensors, and automation systems.
Investment trends show increased capital allocation towards digitalization and eco-efficient solutions, aligning with global sustainability goals. Pricing trends are moving towards value-based and performance-based models as clients demand more integrated, reliable, and technologically advanced offerings. The market maturity level is increasingly advanced, characterized by high adoption rates of IoT and AI-integrated water management systems. Overall, the North America water and wastewater sector is poised for sustained growth, driven by technological innovation, regulatory policies, and infrastructural modernization efforts.
Market Dynamics
The North America water and wastewater market is shaped by a complex interplay of technological innovation, strict regulatory standards, significant investment flows, evolving customer needs, competitive dynamics, and fluctuating supply conditions. Advances in treatment technologies, such as membrane filtration and smart monitoring systems, are enabling more efficient and sustainable water management practices. Regulatory frameworks, driven by concerns over water quality and environmental protection, push industry players toward upgrading infrastructure and adopting cleaner processes. High levels of public and private investment underpin market expansion, supported by a growing demand for reliable water services, especially in industrial and municipal sectors. Customer requirements for improved water quality and sustainability are influencing product design and service delivery, while market competition fosters innovation and cost-competitiveness. Supply chain stability and raw material costs also impact pricing strategies and market growth trajectories, creating a dynamic environment where stakeholder strategies must adapt swiftly to emerging trends.
Industry Statistics & Key Business Metrics
The North America Water and Waste Water Market continues to demonstrate strong growth, driven by increasing regulatory pressures, urbanization, and technological advancements. As infrastructure investments accelerate and environmental standards tighten, key performance metrics provide vital insights into the sector's trajectory. The market's evolution is also influenced by innovations in treatment technologies, smart monitoring, and sustainable practices aiming to reduce operational costs and environmental impact.
- In 2026, the market size is estimated to reach approximately USD 148 Billion, reflecting a compound annual growth rate (CAGR) of 6.2% from 2026 to 2034 (Market Research Future).
- By 2034, the market is projected to expand to around USD 242 Billion, driven by increasing investments in water infrastructure upgrade projects across North America (Allied Market Research).
- The residential water treatment segment is expected to account for roughly 38% of the total market share by 2034, supported by rising household awareness about water quality (Statista).
- Municipal water and wastewater utilities constitute approximately 55% of the market revenue in 2026, with government regulations significantly influencing capital expenditure (American Water Works Association).
- Industrial water treatment is forecasted to grow at a CAGR of 6.7% during 2026–2034, due to expanding manufacturing sectors and stricter effluent discharge standards (IBISWorld).
- North America’s per capita water treatment expenditure is projected to increase from USD 72 in 2026 to USD 114 in 2034, indicating rising consumer and government investment (OECD).
- Technological integration, such as IoT-enabled sensors and AI-based monitoring, is expected to account for over 30% of the market share by 2034, emphasizing digital transformation's role in operational efficiency (Frost & Sullivan).
- Overall, the North America water and wastewater market demonstrates resilience with diversified revenue streams across residential, municipal, industrial, and commercial segments, reinforcing its strategic importance for sustainable development (U.S. Environmental Protection Agency).
Market Segmentation
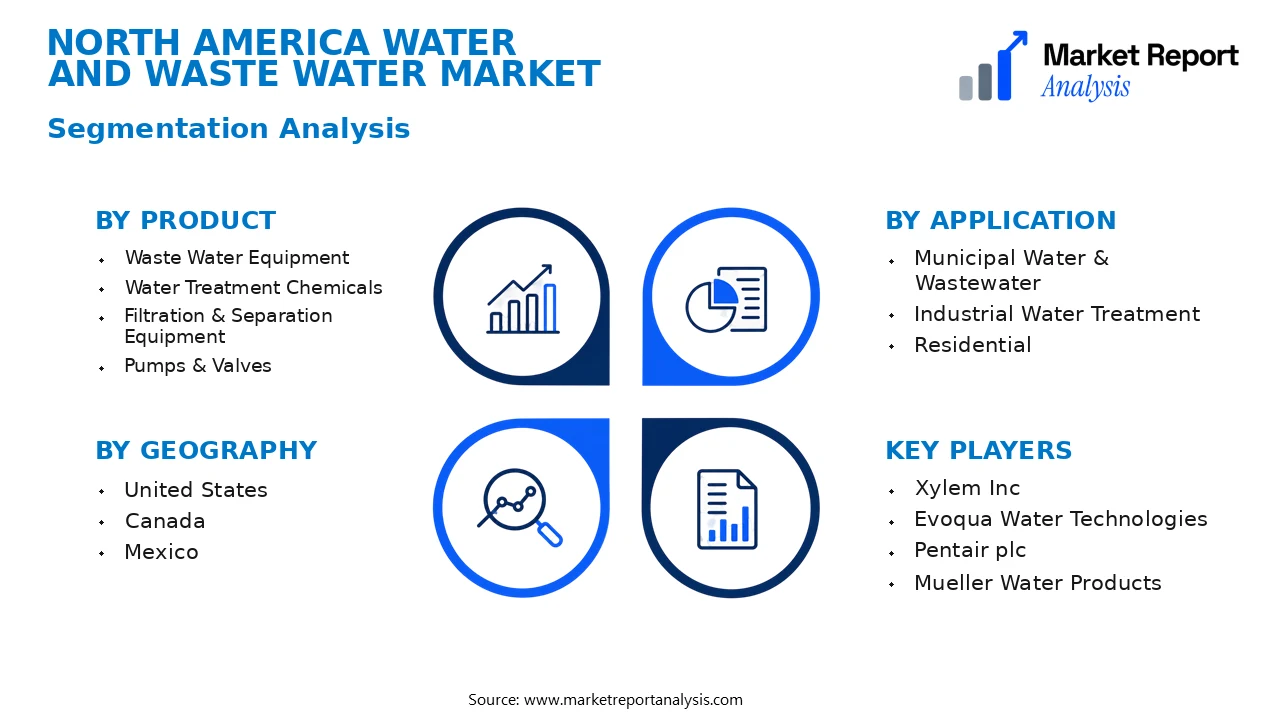
Market segmentation for the North America Water and Waste Water Market is designed to delineate the industry based on product types, application domains, and geographic regions. This structured segmentation facilitates targeted analysis and strategic planning by highlighting key growth areas and technological advancements within the region.
- Product
- Waste Water Equipment: Waste water equipment includes devices and systems essential for treating, purifying, and recycling wastewater. This segment primarily supports municipal and industrial water treatment, experiencing steady growth driven by regulatory standards and infrastructure development.
- Water Treatment Chemicals: Chemicals used in water treatment processes, such as coagulants, disinfectants, and pH adjusters, play a crucial role in maintaining water quality. Increasing industrial activity and environmental regulations boost the demand in this subsegment.
- Filtration & Separation Equipment: This encompasses filters, membranes, and separation devices vital for removing impurities from water sources. As awareness of water pollution rises, demand for advanced filtration technology escalates across applications.
- Pumps & Valves: Pumps and valves are core components for water moving and control systems, critical in infrastructure projects and industrial applications, with growth aligned with urbanization and industrial expansion in North America.
- Application
- Municipal Water & Wastewater: This subsegment serves city water treatment facilities, wastewater outlets, and public utilities. It remains the dominant application due to mandated infrastructure upgrades and the need for sustainable water management solutions.
- Industrial Water Treatment: Industrial uses cover manufacturing plants, chemical processing, and power generation, demanding specialized treatment systems to comply with environmental standards and optimize operations, thereby fueling growth in this sector.
- Residential: Residential water treatment involves home-based filtration and purification systems, driven by consumer awareness of water quality and health safety concerns, representing a steadily expanding market segment.
- Geography
- United States: As the largest economy in North America, the U.S. exhibits significant investment in water infrastructure, regulatory enforcement, and technological innovation, making it a key market driver for the region.
- Canada: Canada's focus on sustainable water management policies and advanced treatment technologies positions it as a crucial growth area, especially in urban centers with aging infrastructure.
- Mexico: Mexico's expanding urban population and industrialization contribute to increased demand for water treatment solutions, supported by government projects and infrastructure modernization efforts.
Competitive Intelligence
The North America Water and Waste Water Market exhibits a competitive landscape characterized by moderate to high concentration, with key players including Xylem Inc., Danaher Corporation, and Pentair plc maintaining significant market shares. These companies deploy aggressive business strategies such as expanding their product portfolios, forming strategic partnerships, and engaging in acquisitions to strengthen their market positions. Innovation is a central focus, with substantial R&D investments dedicated to developing advanced water treatment technologies, smart monitoring systems, and sustainable solutions that differentiate their offerings. Notable partnerships involve collaborations with technology firms and municipal agencies to enhance deployment and service delivery. Recent acquisitions, such as Danaher's acquisition of a leading water treatment firm, reflect a focus on consolidating market presence and expanding regional coverage. Market players continuously invest in R&D to pioneer eco-friendly, cost-effective solutions, addressing regulatory requirements and rising environmental concerns. These strategic initiatives foster competitive differentiation companies differentiate through technological innovation, after-sales service excellence, and integrated solutions tailored to regional needs, thus maintaining their competitive edge in this dynamic market.
Leading Company Profiles
The competitive landscape of the North America water and waste water market features several global and regional players, distinguished by technological innovation, product diversification, and strategic alliances that underpin their market dominance and growth trajectories.
- Xylem Inc
- Evoqua Water Technologies
- Pentair plc
- Mueller Water Products
- Pentair Technologies
- Veolia North America
- Georg Fischer Harvel
- Ecolab Inc
- Conger International
- Aqua-RX
Xylem Inc
Xylem Inc specializes in innovative water solutions, offering extensive product portfolios that include pumps, treatment systems, and analytics technology, emphasizing smart infrastructure and digital integration to meet evolving customer needs.
Evoqua Water Technologies
Evoqua focuses on sustainable water treatment solutions, leveraging advanced filtration, disinfection, and reuse technologies that target industrial, municipal, and commercial sectors with a strategic focus on eco-efficiency.
Pentair plc
Pentair provides a broad range of water treatment, pool, and residential systems, distinguished by its customer-centric innovation approach and a strong global distribution network enabling rapid market responsiveness.
Mueller Water Products
Mueller offers solutions in water distribution, pipe, and valve manufacturing, with strategic investments in smart grid technology and a focus on infrastructure modernization to support urban resilience and efficiency.
Pentair Technologies
This division emphasizes the development of high-performance filtration solutions and automated control systems tailored to industrial and municipal wastewater handling, showcasing a commitment to sustainability and operational excellence.
Veolia North America
Veolia is renowned for its integrated water and wastewater management services, driven by digital transformation initiatives and innovative resource recovery technologies aimed at improving efficiency and reducing environmental impact.
Georg Fischer Harvel
Specializing in plastic piping solutions, Georg Fischer Harvel delivers durable, corrosion-resistant piping systems suitable for water distribution and treatment, focusing on high-quality manufacturing and compliance with environmental standards.
Ecolab Inc
Ecolab leads in water, hygiene, and infection prevention solutions, deploying cutting-edge chemical formulations and digital monitoring systems for utilities and industrial processes to maximize water reuse and safety.
Conger International
Conger International provides custom-engineered water treatment systems and engineering services, leveraging its technical proficiency to serve municipal and industrial clients with innovative and cost-effective solutions.
Aqua-RX
Aqua-RX specializes in water purification equipment and consulting services, emphasizing portable and scalable solutions designed for emergency response and remote applications to ensure safe water access.
Strategic Business Developments
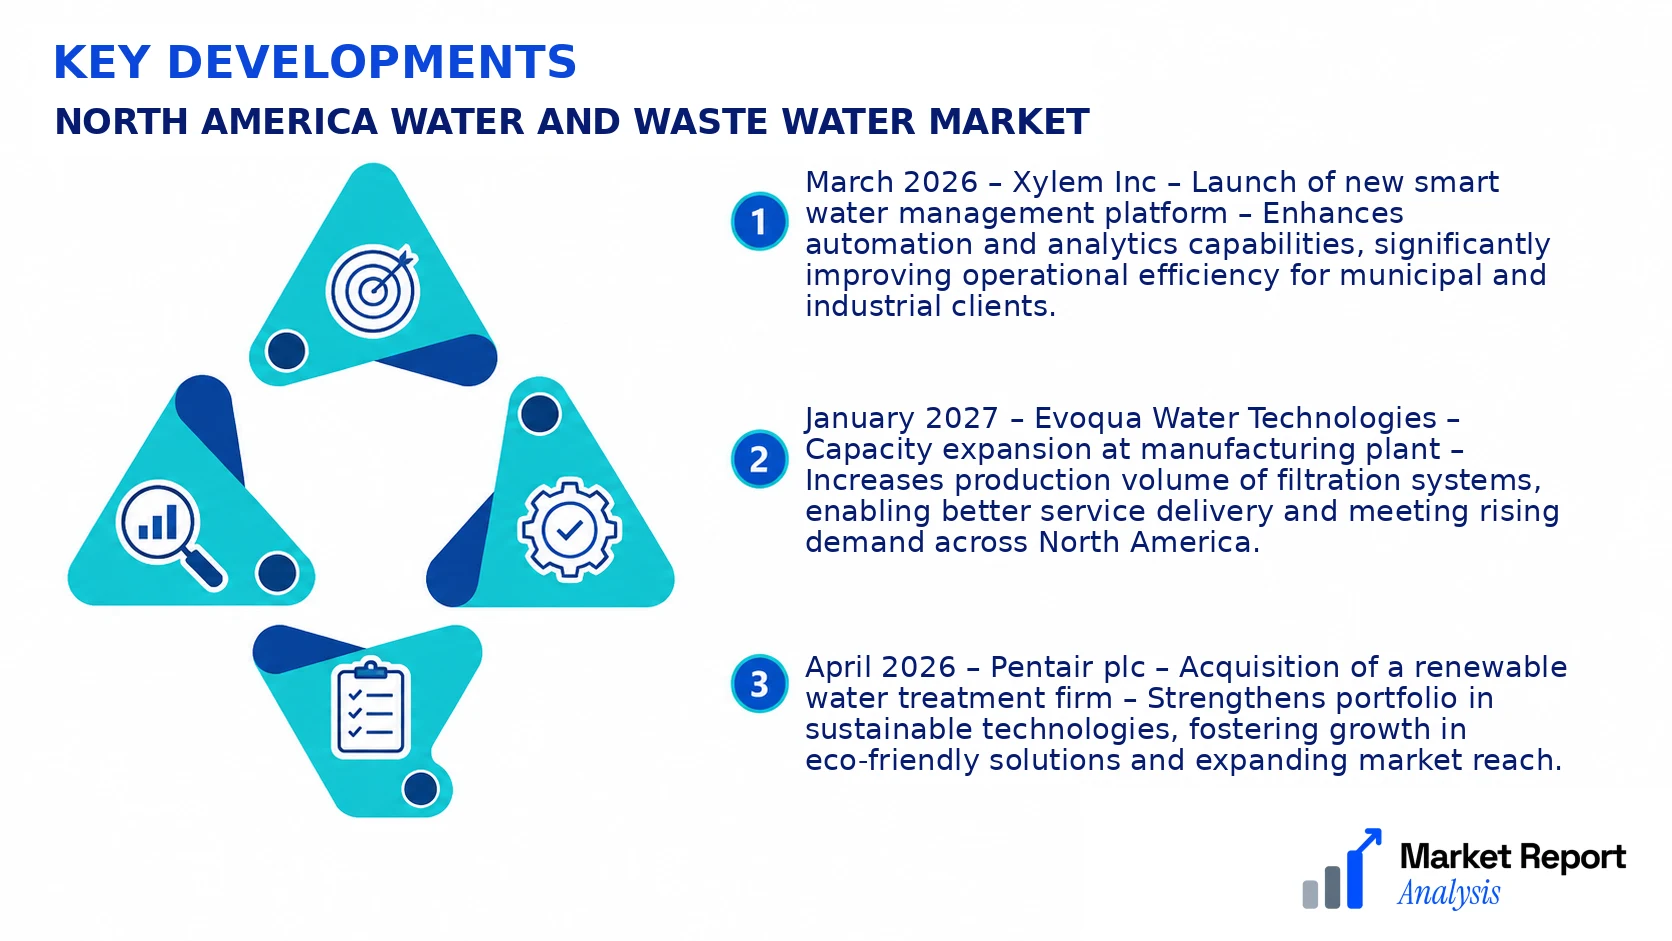
- March 2026 – Xylem Inc – Launch of new smart water management platform – Enhances automation and analytics capabilities, significantly improving operational efficiency for municipal and industrial clients.
- January 2027 – Evoqua Water Technologies – Capacity expansion at manufacturing plant – Increases production volume of filtration systems, enabling better service delivery and meeting rising demand across North America.
- April 2026 – Pentair plc – Acquisition of a renewable water treatment firm – Strengthens portfolio in sustainable technologies, fostering growth in eco-friendly solutions and expanding market reach.
- July 2026 – Veolia North America – Strategic partnership with a tech startup – Focuses on deploying AI-driven water quality monitoring solutions, improving real-time response and resource management.
- September 2026 – Ecolab Inc – Launch of a digital water management platform – Offers predictive analytics and remote monitoring tools, reducing water waste and operational costs for industrial users.
Frequently Asked Questions
What is the North America Water and Waste Water Market?
The North America Water and Waste Water Market encompasses the production, treatment, and distribution of water, as well as wastewater collection and treatment services across the region. It serves municipal, industrial, and commercial sectors, supporting public health and environmental sustainability initiatives.
What is the current market size of North America Water and Waste Water Market?
As of 2026, the North America Water and Waste Water Market is valued at approximately USD 125 Billion, reflecting ongoing investments in infrastructure, innovation in treatment technologies, and rising environmental regulations that compel demand for efficient water management solutions.
What factors are driving the North America Water and Waste Water Market?
Key drivers include increasing regulatory standards for water quality, aging infrastructure requiring modernization, technological advancements in water treatment, rising public awareness on water conservation, and expanding industrial activities boosting demand for wastewater treatment solutions.
Which region dominates the North America Water and Waste Water Market?
The United States dominates the North American market due to its extensive municipal infrastructure, high environmental standards, and substantial private sector investments in advanced water treatment technologies, accounting for the majority share of the regional market.
Which segment is expected to grow the fastest?
The industrial segment is projected to witness the fastest growth, driven by the expanding manufacturing sector, stricter pollution control regulations, and increased adoption of advanced wastewater treatment systems across industries such as chemicals, pharmaceuticals, and food processing.
Who are the leading companies operating in the North America Water and Waste Water Market?
Leading industry players include Veolia Water Technologies, Suez North America, Ecolab, Xylem Inc., and AECOM. These companies are investing heavily in innovative solutions, strategic partnerships, and acquisitions to strengthen their market positions and address growing demand.
Analyst Perspective
The North America water and wastewater market is approaching a maturity phase, with continued technological innovation driving efficiency gains and regulatory compliance. Long-term growth prospects remain robust, supported by aging infrastructure and increased environmental standards, creating substantial commercial opportunities for advanced treatment solutions, smart monitoring systems, and automation technologies. Investors should prioritize emerging innovations such as AI-driven data analytics and IoT-enabled infrastructure to gain strategic leverage. Competitive intensity is expected to intensify as market players expand their technological capabilities and operational efficiencies. Regional growth potential remains high, particularly in underserved urban and rural areas where infrastructure upgrades are critical. Strategic positioning for stakeholders involves fostering collaborations across utility sectors and investing in sustainable, scalable technologies that align with evolving regulatory frameworks. Overall, the market's evolution will hinge on balancing technological advancement with economic viability, enabling long-term resilience and adaptability in North America's water management landscape.
