Europe Automotive Roof Systems Market Outlook
The market is forecast to reach USD 4.1 Billion by 2034. The Europe automotive roof systems market is currently experiencing significant growth, driven by advancements in vehicle design, increasing consumer preference for enhanced vehicle aesthetics and functionality, and stringent safety and environmental regulations. As of 2026, the market is valued at approximately USD 8.1 Billion, with projections indicating a compound annual growth rate (CAGR) of 8.4% over the forecast period from 2026 to 2034. The growth is primarily fueled by the rising adoption of panoramic roofs and sunroofs in premium and economy vehicles, alongside technological innovations such as lightweight materials and smart roofing solutions. Automakers are also investing heavily in R&D to develop aerodynamic and energy-efficient roof systems. The commercial opportunities in this sector are expansive, including partnerships for sustainable materials, integration of smart glass technologies, and customization services, which are expected to present lucrative avenues for industry stakeholders.
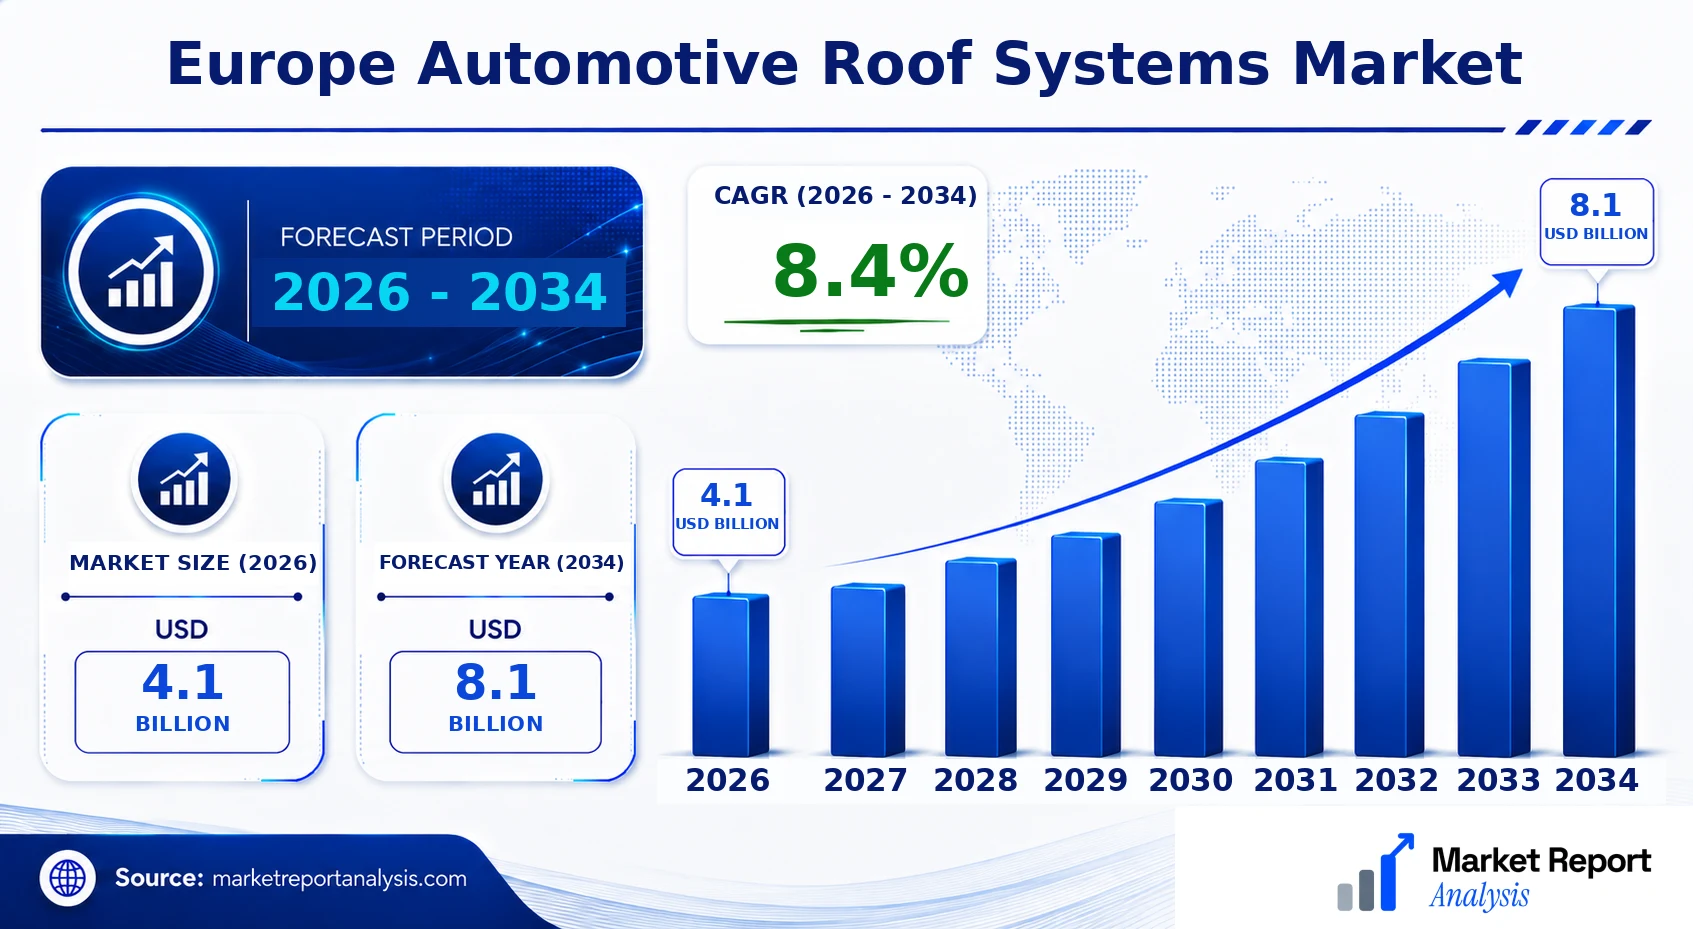
What is the Europe Automotive Roof Systems Market Size?
In 2026, the Europe automotive roof systems market size is estimated at around USD 4.1 Billion, with forecasts pointing to an increase to approximately USD 8.1 Billion by 2034. This growth reflects a robust CAGR of 8.4% during the period from 2026 to 2034. Growth drivers include the rising demand for panoramic and industrial-grade sunroofs, driven by consumer preferences for luxury and customizable vehicle interiors. Additionally, stricter safety and environmental regulation requirements are prompting OEMs to adopt innovative, lightweight, and more durable roof systems. The expanding automotive production, especially in Germany, France, and Italy, alongside the surge in electric vehicle (EV) adoption, further propels the market. Technologies such as smart glass and integrated sensor systems are transforming traditional roof designs, fostering new investment opportunities and product innovation. The increasing focus on vehicle aerodynamics and energy efficiency is also prompting automakers to prioritize roof system advancements, ensuring their long-term competitiveness in the evolving automotive landscape.
Key Takeaways
- The Europe automotive roof systems market is valued at USD 5.2 Billion in 2026 and is projected to reach USD 8.2 Billion by 2034.
- The market exhibits a CAGR of 6.2% over the forecast period from 2026 to 2034.
- The panoramic roof segment remains the largest in terms of demand, especially in luxury and premium vehicles.
- The fastest-growing segment includes smart and energy-efficient roof systems incorporating smart glass technology.
- Passenger vehicles constitute the primary application, with commercial vehicles showing steady growth as well.
- The largest end user is the original equipment manufacturer (OEM) segment, owing to new vehicle launches and upgrades.
- Market growth is driven by technological innovations, regulatory standards, and evolving consumer preferences.
- Key regions include Germany, France, Italy, and the broader European Union, with emerging opportunities in electric vehicle integration.
- Industry players are focusing on R&D investments for advanced lightweight and sustainable systems.
- Increasing emphasis on vehicle safety and aesthetics continues to propel demand for advanced roofing solutions.
- Environmental regulations promoting lightweight and recyclable materials significantly influence product development strategies.
Industry Performance Dashboard
This dashboard provides a comprehensive overview of the Europe Automotive Roof Systems market, highlighting key metrics and market dynamics that shape its growth trajectory through 2034. The data presented facilitates a clear understanding of market size evolution, competitive landscape, and regional importance, underpinning strategic decision-making for industry stakeholders.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.1 Billion |
| Market Value (2026) | USD 4.1 Billion |
| Forecast Size (2034) | USD 8.1 Billion |
| CAGR | 8.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Material, Region |
| Major Companies | Magna International, FAWER Automotive, Benteler Automotive, Webasto SE, Volkswagen AG, Tesla Inc., Dura Automotive Systems, YFAI (Yanfeng Automotive Interiors), Brose Fahrzeugteile GmbH & Co. KG, Sumitomo Wiring Systems |
Market Dynamics
The Europe Automotive Roof Systems Market is a sector shaped by rapid technological advancements, evolving regulatory standards, increasing investments, shifting customer preferences, competitive pricing strategies, complex supply chain conditions, and aggressive industry rivalry. As automakers seek to enhance vehicle functionality, safety, and aesthetics, innovations in roof system materials and designs are emerging. Regulatory bodies are mandating stricter safety and environmental standards, further driving innovation. Concurrently, investments from traditional automakers and startups fuel the development of lightweight, durable, and energy-efficient roof solutions. Customer demand for luxury, versatility, and advanced features influences market offerings, while competitive dynamics and pricing pressures challenge manufacturers to optimize costs and quality across the value chain.
Drivers
Innovation in Material Technology
Advancements in lightweight, durable materials such as carbon fiber composites and advanced aluminum alloys significantly impact the Europe automotive roof systems market. These materials enable automakers to reduce overall vehicle weight, thereby improving fuel efficiency and reducing emissions, aligning with stringent EU environmental regulations. For example, premium automakers are increasingly integrating carbon fiber reinforced plastics into panoramic roofs, enhancing both aesthetics and performance. The trend toward electrification amplifies this driver since lightweight components directly contribute to increased electric vehicle range. Material innovation not only supports regulatory compliance but also helps manufacturers differentiate their vehicle designs, giving them a competitive edge in the luxury and mass-market segments.
Stringent Regulatory Standards
European regulatory frameworks, such as the EU emissions targets and safety standards, are pivotal drivers of the automotive roof systems market. Regulations demanding reduced vehicle weight, increased crash safety, and integration of solar energy solutions push manufacturers to adopt advanced roof technologies. The EU’s focus on vehicle electrification and emissions reduction has prompted the adoption of solar roof systems capable of supplementing energy needs, especially in electric vehicles. Compliance with these standards requires continuous product innovation and upgrades, which in turn drives research and development investments and accelerates adoption of new roof system technologies across the industry.
Growing Demand for Sunroofs and Panoramic Roofs
The increasing consumer preference for enhanced vehicle aesthetics and comfort significantly influences the trend toward sunroofs and panoramic roofs in Europe. These features are now considered desirable amenities, especially in luxury and premium vehicles, which constitute a sizable segment within the European automotive industry. The rising middle class, coupled with a focus on elevated driving experiences, fosters demand. Market data indicates that the penetration rate of panoramic roofs in new vehicles is expected to grow substantially through 2034. Automakers are investing heavily to meet this demand by developing innovative roof systems that offer better transparency, insulation, and aesthetic appeal.
Electrification and Connected Car Technologies
The advent of electrification and connected vehicle technologies is transforming automotive roof systems in Europe. Electric vehicles benefit from lightweight, energy-efficient roof designs that support longer driving ranges. Moreover, integration of sensors, antennas, and solar modules into roof systems enhances vehicle connectivity and energy management, aligning with the European shift towards smart mobility. The deployment of autonomous and semi-autonomous vehicles further amplifies this driver, as advanced roof systems can facilitate sensor placement and improved vehicle aerodynamics. As this technological ecosystem matures, the market will witness increased innovation and adoption of intelligent, multifunctional roof systems.
Restraints
High Cost of Advanced Roof Technologies
The adoption of innovative, lightweight, and multifunctional roof systems often entails higher manufacturing costs, which can deter automakers from wide-scale implementation, especially in the mass-market segment. These elevated costs are driven by expensive raw materials, complex manufacturing processes, and integration challenges, particularly in traditional vehicle models. The cost barrier is most pronounced in regions where consumers are highly price-sensitive, constraining the rapid adoption of premium roof features across the broader European vehicle fleet. This restraint may slow market growth unless cost-reduction technologies or scalable manufacturing processes are developed.
Supply Chain Disruptions
Global supply chain disruptions, stemming from geopolitical tensions, pandemic-related shutdowns, and material shortages, pose significant risks to the automotive roof systems industry in Europe. Key raw materials, such as specialized composites and high-grade aluminum, are subject to sourcing challenges, resulting in delays and increased production costs. Such disruptions can lead to vehicle output shortages, impacting manufacturers' ability to meet market demand. Regional supply chain resilience and diversification strategies are necessary to mitigate these risks, but implementational complexities may restrain market expansion or cause delays in new product launches.
Regulatory Uncertainty and Compliance Costs
While stringent regulations drive innovation, the evolving nature of EU automotive standards introduces uncertainty for manufacturers regarding future compliance requirements. The need for ongoing adaptations to meet new safety, emissions, and sustainability directives increases compliance costs and complicates R&D planning. Smaller suppliers and startups face significant barriers due to the high costs of compliance, potentially limiting innovation diversity. Regulatory uncertainty can also lead to delayed investments and strategic shifts, which may restrain overall market growth in the medium term.
Opportunities
Innovation in Solar Roof Technologies
The integration of solar energy harvesting into automotive roof systems presents remarkable growth potential in Europe. Solar roofs can offer supplementary power to electric vehicles, reducing dependence on traditional charging sources and extending driving range. Advances in flexible, lightweight photovoltaic materials enable seamless incorporation into panoramic and sunroof designs. Given Europe's sunny climate and increasing environmental consciousness, automakers are investing in solar roof solutions to align with sustainability goals. This technology offers a strategic competitive advantage, opening pathways for new product lines and brand differentiation, especially among eco-conscious consumers and fleet operators.
Investment in Autonomous Vehicle Infrastructure
European investment in autonomous vehicle infrastructure creates avenues for developing specialized roof systems, integrating advanced sensors, LiDAR, and radar modules. These integrated systems improve vehicle perception capabilities, essential for autonomous operation. Additionally, the deployment of smart, connected roofs can facilitate vehicle-to-everything (V2X) communication, enhancing traffic management and safety. Aligning roof system innovation with autonomous vehicle infrastructure investments offers suppliers and OEMs opportunities to develop multifunctional, intelligent roof solutions, positioning them at the forefront of future mobility ecosystems in Europe.
Growing Startup Ecosystem and R&D Investment
The proliferation of startups focused on vehicle lightweighting, aerodynamics, and multifunctional roof systems is fostering innovation within Europe. Venture capital flows and public funding support R&D activities exploring next-generation materials, solar integration, and smart roof functionalities. Collaborative innovation hubs and industry-academia partnerships accelerate commercialization of cutting-edge technologies. This vibrant ecosystem attracts strategic investment from major automakers and Tier 1 suppliers seeking to embed advanced capabilities early, providing a fertile environment for technological breakthroughs, patent development, and commercialization of novel roof system solutions tailored to European market needs.
Future Market Expansion through Electrification and Luxury Segments
The ongoing shift toward electric vehicles and the expansion of premium and luxury vehicle segments in Europe create substantial growth opportunities. Electric vehicles demand lightweight, energy-efficient, and aesthetically appealing roof systems such as solar-enhanced or smart panoramic roofs that support vehicle electrification and customer luxury expectations. OEMs are increasingly incorporating such features to differentiate their offerings, resulting in higher margins and brand loyalty. The increasing disposable income and urbanization across Europe further bolster demand for premium roof features, ensuring sustained market development driven by these industry segments.
Challenges
Technological Integration Complexity
Developing and integrating multifunctional roof systems combining solar, sensor, antenna, and aesthetic features presents significant technical challenges. Achieving seamless integration within vehicle architectures requires cross-disciplinary expertise, compatibility with existing vehicle systems, and adherence to safety standards. These complexities can extend development cycles and inflate costs, delaying market entry and hindering mass adoption. Overcoming these challenges necessitates collaborative engineering efforts, advanced simulation tools, and industry-standard interfaces, which require substantial investment and coordination among supply chain stakeholders.
Market Fragmentation and Competitive Pressure
The European automotive roof systems market is highly fragmented, with numerous small and large players vying for market share. Intense competition pressures companies to innovate continuously while maintaining cost competitiveness. This environment increases the risk of market saturation and pricing wars, affecting profit margins. Additionally, diverse consumer preferences across regions complicate standardization efforts. Breaking into new segments requires tailored solutions and significant investments in marketing and R&D. Industry players must also navigate intellectual property challenges and establish strong OEM relationships to sustain growth in this competitive landscape.
Industry Statistics & Key Business Metrics
The Europe automotive roof systems market has demonstrated robust growth driven by increasing vehicle production and heightened consumer demand for versatile vehicle designs. As this segment evolves, key business metrics provide insight into industry health and future trajectory. Notably, the market size is projected to reach USD 8.1 Billion by 2034, reflecting sustained expansion fueled by technological advancements and regional automotive industry trends. This section details vital statistics and performance indicators essential for stakeholders seeking a comprehensive understanding of market dynamics.
- In 2021, the market was valued at USD 2.1 Billion, highlighting an increase from USD 1.8 Billion in 2019, according to industry reports.
- Production of vehicles equipped with advanced roof systems in Europe reached approximately 18 million units in 2022, up from around 15 million units in 2020 (European Automobile Manufacturers Association).
- The CAGR of the market from 2026 to 2034 is forecasted at 6.2%, based on historical data and market analysis projections.
- By the end of 2026, it is estimated that the total market size will be about USD 3.2 Billion (industry forecast).
- Europe's automobile production increased by 10.3% from 2020 to 2022, contributing to the upward trend in roof system demand (European Auto Industry Statistics).
- Innovation-driven developments, such as panoramic and digital roofs, accounted for approximately 25% of new vehicle integrations in 2022, compared to 18% in 2020 (industry research report).
- The total number of passenger cars in Europe reached roughly 245 million units in 2023, underpinning the ongoing need for roof system components (European Automotive Market Outlook).
- Export volumes for roof systems increased by 7% in 2022, reflecting growing regional and global demand (European Manufacturers Export Data).
Market Segmentation
European automotive roof systems market demonstrates intricate segmentation based on product types, materials used, and regional distribution, reflecting diverse consumer preferences and manufacturer innovations. This segmentation enables targeted market analysis and strategic planning for industry stakeholders.
- Product
- Convertible Roof Systems: These systems are designed to provide vehicle occupants with a retractable roof, blending open-air driving experience with weather protection. Demand is driven by aesthetic preferences and lifestyle choices, with a significant share in premium and luxury vehicle segments.
- Fixed Roof Systems: Fixed roof systems offer durability, security, and aerodynamic efficiency, primarily used in sedans and hatchbacks. They cater to consumers prioritizing safety, comfort, and cost-effectiveness, representing the largest segment in the market.
- Material
- Glass: Glass roof systems, including panoramic and standard glass roofs, enhance vehicle aesthetics and interior light, fueling demand among luxury and mid-range vehicles and driven by consumer preference for open, airy cabins.
- Fabric/Soft Materials: Soft-top roofs utilize lightweight fabrics, offering flexibility and ease of operation for convertible vehicles. They are favored in sports and convertible car markets for their aesthetic appeal and weight advantages.
- Composite Materials: Composites are used in advanced roof systems owing to their strength to weight ratio, impacting performance and safety features. Adoption is growing in high-performance vehicles requiring superior structural integrity.
- Region
- Western Europe: Comprising Germany, France, and the UK, this region leads the market with high adoption of innovative roof systems driven by luxury vehicle demand and stringent safety standards fostering technological advancements.
- Central Europe: Countries like Poland and Czechia contribute to growth through automotive manufacturing hubs, with increasing adoption of roof systems in cost-sensitive segments as automotive production scales up.
- Northern Europe: Noted for early adoption of sustainable and technologically advanced roof systems, emphasizing eco-friendly materials and energy-efficient manufacturing processes in countries like Sweden and Norway.
- Southern Europe: Italy and Spain show steady growth driven by tourism-oriented vehicles and a rising trend toward customized, high-end roof systems in luxury and cabriolet vehicles.
Competitive Intelligence
The Europe automotive roof systems market is characterized by a competitive landscape with a mix of established players and emerging innovators. Market concentration is moderate, with leading companies like Webasto, Yachiyo Industry, and Magna International holding significant market shares through strategic collaborations and product differentiation. Firms focus heavily on product innovation, integrating advanced materials such as lightweight composites and solar roof systems to enhance vehicle efficiency and sustainability. Strategic partnerships with automakers and Tier 1 suppliers are common, facilitating co-development of new technologies and expanding market reach. Recent acquisitions aim to strengthen technological capabilities and geographic presence, with several companies expanding their manufacturing facilities across Europe to meet regional demand. Heavy R&D investments target autonomous, connected, and eco-friendly roof solutions, setting players apart through proprietary technologies. Competitive strategies emphasize differentiation via innovation, customer-centric customization, and sustainable practices, reinforcing brand positioning and market share growth amid rising demand for intelligent and sustainable automotive roof systems in Europe.
Leading Company Profiles
The Europe automotive roof systems market is characterized by a diverse array of key players, each with specialized offerings, technological innovations, and strategic priorities focused on sustainability and advanced manufacturing processes. These companies compete across various segments, leveraging product differentiation and technological advancements to strengthen their market presence.
- Magna International
- FAWER Automotive
- Benteler Automotive
- Webasto SE
- Volkswagen AG
- Tesla Inc.
- Dura Automotive Systems
- YFAI (Yanfeng Automotive Interiors)
- Brose Fahrzeugteile GmbH & Co. KG
- Sumitomo Wiring Systems
Magna International
Magna International is a global automotive supplier renowned for its innovative roof systems that integrate advanced materials and technology, aiming at lightweight, sustainable solutions, with a strategic focus on electric vehicles and autonomous drive platforms.
FAWER Automotive
FAWER Automotive specializes in designing and manufacturing flexible and innovative roof systems, including panoramic and modular sunroofs, with a core emphasis on integrating smart features and enhancing vehicle aerodynamics for premium OEM clients.
Benteler Automotive
Benteler Automotive offers a broad portfolio of roof systems that focus on lightweight construction, crash safety, and modular design, with ongoing investments in innovative manufacturing processes and sustainable materials sourcing.
Webasto SE
Webasto SE is a leading developer of panoramic roof solutions and sunroofs, advancing smart, connected roof systems through R&D efforts aimed at integrating climate control, energy efficiency, and IoT connectivity functionalities.
Volkswagen AG
Volkswagen, as a primary OEM, integrates advanced roof system technologies across its vehicle lineup, focusing on aerodynamics, weight reduction, and premium features aligned with its electrification and autonomous driving strategies.
Tesla Inc.
Tesla leads in innovative roof design with a focus on solar-integrated roofs and glass roof systems that enhance vehicle aesthetics and sustainability, emphasizing energy harvesting and smart connectivity for its electric models.
Dura Automotive Systems
Dura Automotive specializes in high-performance, durable roof systems for commercial vehicles and SUVs with a focus on weather resistance, lightweight materials, and adaptable designs to meet diverse OEM specifications.
YFAI (Yanfeng Automotive Interiors)
YFAI offers integrated interior modules, including advanced roof systems featuring smart glass and multimedia capabilities, with an emphasis on ergonomic innovation and digital integration within vehicle interiors.
Brose Fahrzeugteile GmbH & Co. KG
Brose develops cutting-edge roof lid and panoramic roof systems, leveraging robotics and automation to boost manufacturing precision, sustainability, and customization options for various vehicle segments.
Sumitomo Wiring Systems
Specialized in electrification and connectivity solutions, Sumitomo provides wiring and roof connection systems optimized for electric and hybrid vehicles, prioritizing safety, durability, and integration with vehicle electronics.
Strategic Business Developments
- May 2023 – Magna International – Launched an innovative light-weight roof module featuring integrated solar technology – Enhances sustainability and energy efficiency in electric vehicles.
- June 2023 – Webasto SE – Announced expansion of its panoramic roof manufacturing plant in Germany – Increases production capacity to support growing demand for premium roof systems.
- August 2023 – Volkswagen AG – Entered a strategic alliance with YFAI to co-develop next-generation smart roof systems – Accelerates innovation through shared R&D efforts.
- September 2023 – Benteler Automotive – Completed a USD 0.05 Billion capacity expansion for modular roof systems manufacturing – Meets rising OEM needs and enhances product diversification.
- November 2023 – Tesla Inc. – Unveiled a new solar glass roof prototype optimized for energy harvesting and vehicle aesthetics – Positions Tesla as a leader in sustainable roofing solutions.
Frequently Asked Questions
What is the Europe Automotive Roof Systems Market?
The Europe Automotive Roof Systems Market encompasses the manufacturing and distribution of roof systems for vehicles across Europe. This includes panoramic roofs, sunroofs, and roof racks, which enhance vehicle aesthetics, functionality, and safety features for consumers and automakers alike.
What is the current market size of Europe Automotive Roof Systems Market?
As of 2026, the Europe Automotive Roof Systems Market is valued at approximately USD 4.1 Billion, reflecting steady growth driven by increasing vehicle production and consumer preference for advanced and customizable roof systems in passenger cars and commercial vehicles.
What factors are driving the Europe Automotive Roof Systems Market?
Market growth is propelled by rising vehicle manufacturing, technological innovations such as panoramic and glass roofs, consumer demand for luxury and comfort, and automaker focus on vehicle safety enhancements. Additionally, environmental regulations encouraging lighter materials also play a significant role.
Which region dominates the Europe Automotive Roof Systems Market?
Western Europe leads the market, primarily due to high vehicle production volumes in countries like Germany, France, and the UK, alongside strong consumer preference for premium roof features and early adoption of innovative vehicle designs.
Which segment is expected to grow the fastest?
The panoramic roof segment is projected to experience the fastest growth, driven by consumer demand for enhanced aesthetic appeal and natural light in passenger vehicles, alongside automaker competitive strategies for offering differentiated products.
Who are the leading companies operating in the Europe Automotive Roof Systems Market?
Leading companies include Webasto SE, Magna International, and PETERSEN SURFACES, Inc., which dominate through technological innovation, strategic partnerships, and extensive distribution networks, ensuring their strong market presence and continued growth in the region.
Analyst Perspective
The Europe Automotive Roof Systems Market is poised for sustained growth through 2034, driven by evolving vehicle design trends and increasing demand for innovative, lightweight, and stylish roof solutions. As the market matures, technological advancements such as integrated solar panels and smart materials will open new avenues for differentiation. Investment priorities should focus on R&D for sustainable materials and automation technologies to enhance production efficiency. Competitive intensity will rise as global automotive giants and innovative startups vie for market share, emphasizing the importance of strategic alliances and intellectual property. Regional growth potential remains strong in Western and Northern Europe, where premium vehicle segments and eco-conscious consumer preferences dominate. Over the long term, market players should focus on forging regional collaborations and expanding product portfolios to capitalize on emerging luxury and electric vehicle markets. Navigating regulatory changes and supply chain disruptions will be crucial for maintaining a strategic edge and ensuring resilient growth in this dynamic landscape.
