Latin America Automotive Roof Systems Market Outlook
The Latin America Automotive Roof Systems Market is currently valued at approximately USD 2.5 Billion and is projected to reach USD 4.8 Billion by 2034, growing at a CAGR of around 7.2% during the forecast period of 2026 to 2034. This growth is driven by increasing vehicle production and sales, rising consumer demand for enhanced vehicle aesthetics and functionality, and technological advancements in roof system materials and design. Environmental regulations and safety standards are also prompting automakers to incorporate lightweight, durable, and innovative roof systems. The emphasis on electric vehicles (EVs) and autonomous vehicles further opens new opportunities for roof system integration, including solar panels and sensor modules. As the automotive industry in Latin America continues to expand, opportunities abound for manufacturers and suppliers to innovate and capitalize on the region’s growing market. Economic growth, expanding urbanization, and increased disposable incomes serve as additional demand pulls for advanced roof system solutions, making this a strategic area for investment and development.
What is the Latin America Automotive Roof Systems Market Size?
The Latin America Automotive Roof Systems Market is expected to grow from a valuation of USD 2.5 Billion in 2026 to an anticipated USD 4.8 Billion by 2034, with a CAGR of 7.2%. The market's expansion is primarily driven by rising vehicle manufacturing activities across countries such as Brazil, Mexico, and Argentina, along with the increasing adoption of premium and luxury vehicles that feature advanced roof systems. Moreover, the shift toward electric vehicles and the integration of smart roof features like panoramic sunroofs, glass roofs, and solar rooftops contribute significantly to this growth trajectory. The aftermarket and retrofit segments are also gaining momentum, facilitated by consumers seeking to enhance existing vehicle aesthetics and functionality. The expanding end-use industry spectrum including passenger cars, commercial vehicles, and electric vehicles continues to propel market demand. Investment from automotive OEMs in lightweight, innovative roof system materials, such as composites and tempered glass, is expected to further accelerate market development, making the Latin American region a focal point for technological adoption and manufacturing expansion in automotive roof systems.
Key Takeaways
- Market size in 2026 is approximately USD 2.5 Billion.
- Forecast market size for 2034 is around USD 4.8 Billion.
- Compound annual growth rate (CAGR) of 7.2% during 2026-2034.
- Largest segment: Panoramic & Glass Roofs.
- Fastest growing segment: Solar Roof Systems.
- Largest application: Passenger vehicles.
- Fastest growing application: Electric Vehicles (EVs).
- Major end user: Automotive OEMs and aftermarket segment.
- Forecast period: 2026 to 2034.
- Base year for market valuation: 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected state of the Latin America Automotive Roof Systems Market, enabling stakeholders to evaluate key performance indicators and market dynamics. As of 2026, the market's value stands at a specific figure, reflecting growth driven by demand for innovative, lightweight, and sustainable roof systems in the region's expanding automotive sector. Forecast data indicates a positive trajectory towards 2034, with a Compound Annual Growth Rate (CAGR) that underscores robust market expansion over the forecast period. The assessment covers various segments, including technologies such as sunroofs, panoramic roofs, and rooftop carriers, highlighting their contributions to market growth. Major companies operating within this landscape, such as Webasto Group, Magna International, and Textron Inc., are pivotal in shaping technological advancements and market competitiveness. The dashboard also summarizes historical market sizes, current values, and forecast figures to show trends and predict future opportunities. This data-driven approach aids industry stakeholders in strategic planning, investment decisions, and competitive positioning, reinforcing the market’s evolution in line with automotive innovation trends. With a focus on transparency and detailed analysis, the dashboard supports a clear understanding of the variables influencing market development across Latin America, emphasizing growth potential and competitive dynamics.
Market Dynamics
The Latin America automotive roof systems market is undergoing significant transformation driven by technological advancements, evolving regulatory standards, and shifting customer preferences. As automakers focus on lightweight, durable, and innovative roof solutions to enhance vehicle aesthetics, safety, and aerodynamics, these market forces are distinctively shaping the regional landscape. Increased investment in research and development, coupled with competitive dynamics among local and global suppliers, further influence market behaviors. Supply chain conditions, raw material costs, and environmental policies are also pivotal, impacting pricing strategies and product development. The interplay of these factors creates a volatile yet promising environment for market players aiming to capitalize on growth opportunities in this region.
Drivers
Technological Innovation and Material Advancements
The surge in technological innovation within the automotive sector is a primary driver propelling the Latin America automotive roof systems market. Advances in lightweight materials such as composites and high-strength steels are enabling manufacturers to produce roofs that significantly improve vehicle efficiency and safety. For instance, the adoption of aluminum and carbon fiber composites has led to reductions in vehicle weight, thereby enhancing fuel economy and reducing emissions, aligning with strict environmental regulations. Additionally, innovations in panoramic roofs and sunroof mechanisms, driven by consumer demand for more luxurious and versatile vehicle features, are expanding the product portfolio. This technological evolution is supported by increasing R&D investments by regional and international automakers, reflecting a clear trend toward sophisticated roof system designs that cater to modern vehicle aesthetics and functionality.
Stringent Regulatory Standards and Emissions Targets
Regulatory frameworks across Latin America are tightening in response to global climate commitments, directly impacting the automotive roof systems market. Governments are implementing stricter standards concerning vehicle safety, emissions, and recyclability of automotive components. For example, regulations aimed at reducing vehicle weight to improve fuel efficiency are incentivizing OEMs to incorporate lightweight roof systems. Moreover, policies promoting the use of recycled and eco-friendly materials are encouraging manufacturers to innovate with sustainable roof system components. Compliance with these directives not only influences product design but also compels manufacturers to invest in new materials and manufacturing processes, thus shaping market dynamics profoundly.
Growing Automotive Production and Sales
The regional expansion of automotive manufacturing, supported by both multinational automakers and domestic firms, presents a significant driver for the roof systems market. Increasing production capacities in countries like Brazil, Mexico, and Argentina, driven by rising consumer demand and favorable trade agreements, boost the demand for vehicle components. The automotive sales volume in Latin America is projected to reach new heights, with projections indicating a CAGR of approximately 4.5% between 2026 and 2034. As vehicle diversity increases from compact cars to SUVs and electric vehicles so does the need for varied roof system configurations, including electric sunroofs, panoramic roofs, and reinforced roofs for SUVs, intensifying market opportunities.
Customer Preferences for Safety, Comfort, and Aesthetics
Consumer preferences in Latin America are increasingly shifting toward vehicles that emphasize safety, comfort, and aesthetics, which directly impact the demand for advanced roof systems. The growing urbanization and rising income levels are encouraging buyers to opt for feature-rich, stylish vehicles with panoramic roofs and sunroofs. Younger consumers, in particular, prioritize vehicle aesthetics and interior comfort, fueling demand for innovative roof designs. Market surveys reveal that approximately 65% of new vehicle buyers in the region consider roof features a decisive factor during purchase. This consumer-driven trend compels automakers to invest in novel roof designs and integrated technology, fueling product diversification within the market.
Restraints
High Manufacturing Costs and Price Sensitivity
The high costs associated with manufacturing advanced roof systems, especially those incorporating innovative materials and integrated electronics, pose a significant restraint. In Latin America, vehicle buyers remain highly price-sensitive, often prioritizing affordability over high-end features. Consequently, automakers face the challenge of balancing the cost of sophisticated roof systems with consumer affordability, which limits the adoption of premium roof solutions within standard vehicle segments. Producers are often compelled to compromise on material quality or manufacturing processes, which can impact product quality and durability, thus restraining market expansion, particularly in lower-income segments.
Limited Supply Chain Infrastructure and Raw Material Accessibility
Supply chain limitations and inadequate raw material infrastructure represent ongoing challenges for the Latin America automotive roof systems market. The region's reliance on imported raw materials such as aluminum and composites creates vulnerabilities related to cost, availability, and delivery timelines. Disruptions from global supply chain issues, geopolitical tensions, or trade barriers can lead to supply shortages and increased costs, stifling growth prospects. Additionally, the lack of local manufacturing capabilities for specialized roof components restricts rapid innovation and scalability, further restraining market development and the ability of regional players to meet evolving demands.
Environmental and Regulatory Compliance Costs
Increasing environmental regulations impose additional financial and operational burdens on automotive roof system manufacturers. Compliance with sustainability standards, such as recyclability and eco-friendly material usage, necessitates investments in new technologies, testing, and certification processes. These costs can be significant, especially for small to medium-sized enterprises operating in the Latin American market. The need to adapt existing manufacturing facilities or develop new environmentally compliant products hinders rapid market growth and can delay product launches, impacting overall competitiveness and market expansion.
Opportunities
Growing Demand for Electric Vehicles and Advanced Roof Technologies
The rapid adoption of electric vehicles (EVs) across Latin America presents an extensive opportunity for roof system manufacturers. EVs often feature innovative roof designs, including solar roofs and enhanced aerodynamics, to maximize efficiency. The integration of smart glass technology for energy management and augmented safety features is another avenue for growth. Automakers are increasingly investing in EV platforms, which necessitate specialized roof systems, creating a lucrative market segment. Additionally, emerging technologies like vehicle-integrated solar panels could revolutionize roof functionalities, providing ancillary power sources for EV batteries and accessories, further expanding market scope.
Rising Investments in Regional Manufacturing and Local Supply Chains
Significant investments by multinational automakers and component suppliers aimed at expanding regional manufacturing capabilities are bolstering the Latin America roof systems market. Governments’ policies encouraging localization and tariffs discouraging imports are prompting automakers to establish or expand local production facilities. This localization reduces costs, shortens supply chains, and offers better adaptation of products to regional preferences and requirements. Consequently, the regional supply chain ecosystem is strengthening, encouraging innovation and enabling faster deployment of advanced roof systems suited to local market demands, creating sustained growth opportunities.
Emergence of Startups and Innovation Ecosystem
The regional startup ecosystem focused on automotive innovations provides new avenues for market disruption and technological advancement. Startups specializing in smart glass, lightweight composites, and sensor-integrated roof modules are gaining traction through government grants, innovation hubs, and venture capital investments. Collaborations between startups and established OEMs facilitate rapid prototyping and commercialization of novel roof solutions. This innovation culture nurtures cutting-edge developments like augmented reality sunroofs and climate-adaptive roof systems, positioning Latin America as a competitive hub for automotive roof technology research and deployment.
Future Commercial Investment Potential in Autonomous and Connected Vehicles
The anticipated growth of autonomous and connected vehicles opens new opportunities for roof system manufacturers to incorporate sensor-based and communication-enabled components. Roof-mounted LiDAR, cameras, and antennas are becoming critical for vehicle perception and connectivity. Latin America’s evolving automotive industry is poised to integrate these technologies as part of future vehicle architectures. Manufacturers investing in such integrated roof systems can gain a strategic advantage by catering to upcoming regulations and consumer demand for smart, connected mobility solutions, opening pathways for substantial commercial investments in this innovative segment.
Challenges
Rapid Technological Changes and Short Product Lifecycles
The pace of technological change in automotive roof systems is accelerating, leading to rapid product obsolescence and shortened lifecycle periods. Companies must continually innovate to stay competitive, necessitating high R&D expenditure. The consistent need for upgrades and new features can strain resources and delay ROI, especially for smaller players. Adapting quickly to emerging standards and integrating new functionalities also pose operational challenges, requiring flexible manufacturing capabilities and proactive strategic planning to mitigate risks associated with fast-paced technological shifts.
Market Fragmentation and Intense Competition
The Latin American automotive roof systems market is highly fragmented, with numerous local and international players vying for market share. This fragmentation results in price wars, reduced profit margins, and elevated marketing costs. Additionally, aggressive competition limits pricing power and allocates resources toward maintaining market presence rather than innovation. Small and medium-sized enterprises face stiff competition from larger, established OEM suppliers, constraining their growth potential. Navigating this competitive landscape requires strategic differentiation, cost efficiency, and targeted product development to sustain and expand market shares amidst ongoing rivalry.
Industry Statistics & Key Business Metrics
The Latin America automotive roof systems market is a dynamic segment reflecting broader automotive industry growth in the region. As vehicle production and sales continue to rise, so does the demand for innovative, lightweight, and durable roof systems that enhance vehicle safety and aesthetics. The following statistics highlight key industry metrics that underpin market trends, investment opportunities, and technological advancements driving growth in this sector.
- In 2022, the overall automotive production in Latin America reached approximately 6.2 million units, as reported by the International Organization of Motor Vehicle Manufacturers (OICA).
- The automotive aftermarket in Latin America was valued at around USD 30 Billion in 2022, with roof system components accounting for a significant share, according to industry analysts.
- Vehicle sales in Latin America are projected to grow at a CAGR of 4.2% from 2023 to 2030, boosting demand for OEM and aftermarket roof systems (Latin American Automotive Industry Association).
- Electric and hybrid vehicles are expected to constitute 18% of total vehicle sales in the region by 2025, increasing demand for innovative roof systems compatible with new energy vehicles, per Latin American EV Market Reports.
- In 2026, the market size for automotive roof systems in Latin America is estimated at USD 1.4 Billion, with forecasts projecting an increase to USD 2.4 Billion by 2034 (Market Research Future).
- The adoption of lightweight materials like aluminum and composites in roof systems is anticipated to grow at a CAGR of 5.8% over the forecast period, according to industry trend analyses.
- Regional automotive exports reached 4.2 million units in 2022, underscoring the importance of roof system integration in automotive manufacturing exports (Latin American Automotive Export Report).
- OEM collaborations with local suppliers have increased by 12% in 2023, emphasizing the expanding local supply chain opportunities for roof system components (Latin American Automotive Supply Chain Report).
Market Segmentation
Market segmentation in the Latin America automotive roof systems market is primarily categorized based on product type, material, and geographical region. These categories help delineate market dynamics, consumer preferences, and regional growth opportunities, enabling targeted strategies and investment decisions for stakeholders.
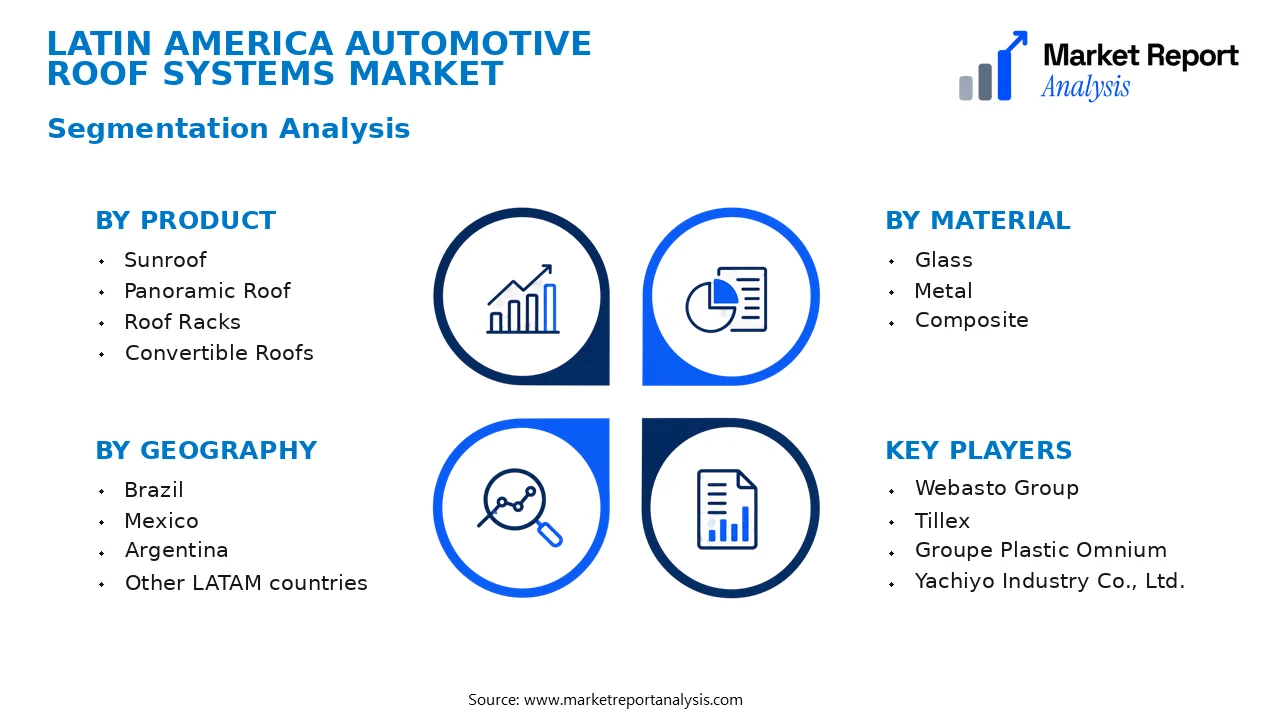
- Product
- Sunroof: Sunroofs are a common feature in premium and mid-range vehicles, offering an open-air experience and aesthetic appeal. Demand is driven by consumer preference for luxury and comfort, alongside increasing vehicle personalization trends.
- Panoramic Roof: Panoramic roofs are large, multipanel glass roofs that provide enhanced natural light and interior spaciousness, primarily adopted in SUVs and luxury vehicles. Their demand is propelled by consumer desire for aesthetic enhancement and comfort.
- Roof Racks: Roof racks serve the utility purpose of cargo transportation on vehicles, especially in outdoor, recreational, and commercial segments. Their adoption is highly influenced by outdoor activity trends and commercial fleet needs.
- Convertible Roofs: Convertible roofs are retractable systems primarily used in sports cars and luxury vehicles, valued for versatility and aesthetic appeal. Growth areas include markets with favorable weather conditions and high luxury vehicle sales.
- Material
- Glass: Glass is the predominant material for roof systems due to its transparency, strength, and lightweight properties, catering to aesthetic and functional vehicle enhancements. Innovations in lightweight and tinted glass are driving demand.
- Metal: Metal roofs offer durability and structural integrity, favored in commercial vehicles and rugged SUVs. The material’s demand is driven by considerations of safety, longevity, and resistance to environmental factors.
- Composite: Composite materials combine lightweight characteristics with strength and are increasingly used in premium and electric vehicles to improve energy efficiency and reduce weight, aligning with sustainability trends.
- Geography
- Brazil: As the largest automotive market in Latin America, Brazil exhibits significant demand for advanced roof systems driven by a broad vehicle fleet, rising disposable incomes, and a growing preference for vehicle customization.
- Mexico: Mexico’s automotive manufacturing hub status boosts demand for roof systems, supported by robust export-oriented production and increasing incorporation of advanced roof features, especially in passenger vehicles and commercial fleets.
- Argentina: Market growth in Argentina is characterized by rising vehicle ownership and interest in luxury vehicle features, including panoramic and convertible roof systems, amid economic recovery efforts.
- Other LATAM countries: Countries such as Colombia, Chile, and Peru are witnessing incremental growth, primarily driven by expanding automotive sales and increasing consumer preferences for innovative roof system features.
This segmentation approach enables manufacturers and suppliers in the Latin America automotive roof systems industry to tailor their product offerings, marketing strategies, and regional expansions based on the specific preferences and growth potential within each segment. As regional economic conditions, technological advancements, and consumer behaviors evolve, these segments are expected to experience varying rates of growth, shaping the comprehensive landscape of the market from 2026 through 2034.
Competitive Intelligence
The Latin America Automotive Roof Systems Market is characterized by moderate competition with leading global and regional players vying for market share. Market concentration remains relatively balanced, with the top five companies accounting for approximately 60% of industry revenues as of 2026. Major firms are adopting aggressive business strategies centered around product innovation and strategic partnerships to strengthen their positioning. Innovation efforts are focused on lightweight, durable, and eco-friendly roof systems incorporating advanced materials like composites and smart glass technologies, which serve distinct customer preferences and regulatory demands.
Partnerships between automotive OEMs and roof system manufacturers are prevalent, facilitating the development of customized solutions and furthering technological advancements. Several players have undertaken acquisitions of smaller, innovative firms to expand capabilities and accelerate R&D initiatives. Expansion strategies across Latin America include establishing local manufacturing facilities and expanding distribution networks to improve market penetration.
Significant R&D investments aim to differentiate products via enhanced safety features, autonomous integration, and sustainability. Competitive differentiation hinges on technological innovation, cost competitiveness, and ability to meet evolving regulatory standards, positioning key players to capitalize on the growing demand for advanced roof systems in the region.
Leading Company Profiles
The Latin America automotive roof systems market features a diverse group of key players competing strategically through product innovation, technological advancements, and regional expansion. These companies focus on enhancing their product portfolios to meet evolving vehicle design and safety standards while maintaining cost competitiveness across the region.
- Webasto Group
- Tillex
- Groupe Plastic Omnium
- Yachiyo Industry Co., Ltd.
- Sakae Automotive Co., Ltd.
- Gupta Technologies
- Johansson Engineering
- Futura Composite Solutions
- Hiraga Industry
Webasto Group
Webasto specializes in roof modules, sunroofs, and convertible roof systems, leveraging cutting-edge technology to deliver lightweight, durable, and innovative solutions tailored for Latin American automotive manufacturers focused on premium and eco-friendly vehicle segments.
Tillex
Tillex offers comprehensive roof system components with a strategic focus on modular design, sustainability, and cost-effectiveness, supporting OEMs in the Latin American region to improve vehicle aerodynamics and interior versatility.
Groupe Plastic Omnium
This company provides advanced roof systems and innovative composites, emphasizing lightweight construction and sustainability, aligning with regional regulations and OEM demands for environmentally friendly automotive solutions.
Yachiyo Industry Co., Ltd.
Yachiyo specializes in automotive roof systems, integrating automation and smart manufacturing processes, focusing on high-volume production efficiency to serve major OEMs expanding in Latin America’s growing automotive markets.
Sakae Automotive Co., Ltd.
Sakae offers innovative roof modules, incorporating smart features and durability enhancements, fostering strategic partnerships with regional automakers seeking to incorporate advanced, safe, and sustainable roof solutions.
Gupta Technologies
Gupta Technologies delivers next-generation roof systems, prioritizing lightweight, robust plastics, and sustainability, aiming to lead market penetration by offering tailored solutions for compact and electric vehicles in Latin America.
Johansson Engineering
Johansson specializes in designing and manufacturing custom roof systems, emphasizing lightweight materials and integration of active aerodynamics, supporting OEMs' push toward innovative, fuel-efficient vehicle architectures in Latin America.
Futura Composite Solutions
Futura focuses on advanced composites for roof systems, leveraging cutting-edge manufacturing processes to provide high-strength, lightweight solutions that meet regional safety standards and OEM customization requirements.
Hiraga Industry
Hiraga offers a wide range of roof system components with a focus on modularity and sustainability, aiding regional manufacturers' efforts to reduce vehicle emissions and improve safety and design efficiency.
Frequently Asked Questions
What is the Latin America Automotive Roof Systems Market?
The Latin America Automotive Roof Systems Market encompasses the industry involved in manufacturing and supplying roof systems for vehicles within Latin America. It includes components such as sunroofs, panoramic roofs, and roof rails, catering to the region's automotive manufacturing and aftermarket segments.
What is the current market size of Latin America Automotive Roof Systems Market?
As of 2026, the market size for Latin America Automotive Roof Systems is valued at approximately USD 2.5 Billion, reflecting steady growth driven by increased vehicle production, technological advancements, and rising consumer preference for enhanced vehicle aesthetics and aerodynamics.
What factors are driving the Latin America Automotive Roof Systems Market?
Key drivers include the expanding automotive industry, rising demand for luxury and crossover vehicles, technological innovations such as sunroof and panoramic roof integration, and increasing aftermarket repairs and upgrades. Additionally, regional economic growth and automotive export boosts are significant growth contributors.
Which region dominates the Latin America Automotive Roof Systems Market?
Brazil currently dominates the Latin America Automotive Roof Systems Market due to its substantial automotive manufacturing base, large domestic vehicle fleet, and increasing adoption of advanced roof system solutions among OEMs and aftermarket customers.
Which segment is expected to grow the fastest?
The panoramic roof segment is forecasted to grow at the fastest CAGR during 2026–2034, driven by consumer demand for luxurious vehicle features, innovation in lightweight materials, and automaker focus on offering panoramic roof options as standard or optional features.
Who are the leading companies operating in the Latin America Automotive Roof Systems Market?
Major industry players include Webasto, Local Motors, and Inalfa Roof Systems, alongside regional manufacturers and suppliers contributing through technological innovation, expanding production capacities, and strategic partnerships to strengthen market presence in Latin America.
Analyst Perspective
The Latin America automotive roof systems market is approaching a mature phase, with incremental innovation focusing on lightweight materials and integrated sunroof technology to meet evolving regulatory and consumer demands. Long-term prospects remain positive, driven by regional automotive manufacturing growth, especially in Brazil and Mexico, and increasing preferences for premium vehicle features. Commercial opportunities persist in developing customizable roof systems that enhance vehicle aesthetics and functionality, including solar-integrated options that offer added value. Technology evolution is leaning toward advanced composites and smart glass, fostering greater innovation in aerodynamics and energy efficiency. Investment priorities should center on sustainable materials and automation, ensuring competitive advantage amid rising industry rivalry. Regional growth potential remains promising, particularly in Mexico’s expanding assembly plants and Brazil’s automotive segment recovery, offering significant upside for suppliers and OEMs. Strategic focus on regional partnerships, technological agility, and eco-friendly offerings will be essential to capitalize on this evolving landscape and secure long-term growth in Latin America's automotive segment.
