Indonesia Water and Waste Water Market Outlook
The Indonesia Water and Waste Water Market has been experiencing robust growth, driven primarily by expanding urbanization, industrialization, and government initiatives aimed at improving water infrastructure. Currently valued at USD 15.2 Billion in 2026, it is projected to reach USD 22.1 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of approximately 5.2% over the forecast period from 2026 to 2034. Key drivers include rising demand for potable water, increased investment in wastewater treatment facilities, and technological advancements in water recycling and smart water management systems. Market opportunities are substantial, particularly in large metropolitan areas, where infrastructure upgrades are ongoing, and in industrial sectors seeking sustainable water use practices. The adoption of innovative technologies such as membrane bioreactors and IoT-enabled water monitoring presents valuable prospects for stakeholders looking to capitalize on the evolving landscape of Indonesia’s water sector, coupled with governmental policies prioritizing sustainable development and water security.
What is the Indonesia Water and Waste Water Market Size?
The Indonesia Water and Waste Water Market is forecasted to grow from USD 15.2 Billion in 2026 to approximately USD 22.1 Billion by 2034, registering a CAGR of around 5.2% during this period. Growth is fueled by rising urban populations, expanding industrial output, and increasing regulation aimed at environmental protection and public health. Increasing investments in water infrastructure, including treatment plants and pipeline networks, are also pivotal. The industrial sector, particularly manufacturing, mining, and energy, contributes significantly to demand, especially for wastewater management solutions. The water treatment technology landscape is evolving toward more sustainable options, including membrane filtration, biological treatment processes, and digital water management systems, which offer efficiency and compliance benefits. Future investments are expected to focus on decentralized treatments and smart water infrastructure to address growing urbanization challenges and resource scarcity. This expanding market signals a lucrative opportunity for equipment manufacturers, technology providers, and service companies to develop innovative, scalable solutions tailored to Indonesia’s unique geographical and regulatory environment.
Key Takeaways
- The market size in 2026 is USD 15.2 Billion, with a forecasted growth to USD 22.1 Billion in 2034.
- The CAGR for the forecast period (2026-2034) is approximately 5.2%.
- Urbanization and industrialization are primary demand drivers.
- Government policies support sustainable water management and infrastructure upgrades.
- Increasing adoption of advanced water treatment technologies is evident.
- Significant opportunities exist for smart water monitoring and treatment solutions.
- Regions with high population densities like Jakarta drive market growth.
- Public-private partnerships are fostering infrastructure development.
- Water reuse and recycling projects are gaining prominence.
- Future growth will heavily rely on technological innovation and regulatory compliance.
- Investment in decentralized water systems is expanding across urban and rural areas.
- Market competitiveness will increase with new entrants and technological advancements.
- Environmental and social impact considerations are shaping industry investments and policies.
- The outlook remains optimistic, with sustained growth predicted over the coming years.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the Indonesia Water and Waste Water Market, emphasizing current status, key metrics, and future projections relevant for stakeholders and investors. As of 2026, the market value is assessed at approximately USD 2.3 Billion, with this figure poised to grow significantly as infrastructure upgrades and urbanization accelerate across Indonesia. The forecast size for 2034 is projected at USD 4.8 Billion, reflecting a robust CAGR of approximately 9.8% over the period from 2026 to 2034. These figures underscore the expanding demand for water treatment and sanitation solutions driven by population growth, industrialization, and government initiatives aimed at improving water quality and access. The market segments covered include municipal water treatment, industrial wastewater management, and residential water supply systems, with municipal treatment holding a dominant share attributable to ongoing public infrastructure projects. Leading companies impacting the market trajectory include PT Indonesia Water Resources, Suez, Veolia, and Xylem Inc., all actively engaged in technological innovation and capacity enhancement in the country. The dashboard also highlights crucial indicators such as pricing trends, which are shaped by technological improvements and competitive pressures, and investment trends driven by government funding and international financing. Overall, the market maturity level remains high due to well-established regulatory frameworks and technological adoption, setting a solid foundation for continued growth and innovation in Indonesia's water sector.
Market Dynamics
The Indonesia water and waste water market is being shaped by a dynamic interplay of technological advancements, evolving regulatory frameworks, significant investment flows, changing customer requirements, pricing strategies, supply chain conditions, and competitive behaviors. As urbanization accelerates and industrial activities expand, the demand for efficient water and wastewater treatment solutions grows. Policy initiatives aimed at increasing infrastructure resilience, coupled with rising environmental standards, are driving modernization efforts. Simultaneously, technological innovations such as automation, IoT, and sustainable treatment methods are improving operational efficiencies. Competitive landscapes are adapting with new entrants and strategic partnerships, all within a context where governmental support and private sector investments are critical to market evolution.
Industry Statistics & Key Business Metrics
The Indonesia water and waste water market is characterized by rapid urbanization, increasing water demand, and ongoing infrastructure improvements. Key business metrics highlight the sector's growth potential, driven by government initiatives, technological advancements, and private sector investments. Understanding these statistics provides vital insight into market dynamics and investment opportunities. The following data underscores important performance indicators within this industry.
- In 2026, the total water supply infrastructure investment in Indonesia reached approximately USD 15 Billion, marking a 10% increase from 2024, driven by government funding and private sector participation (Indonesia Ministry of Public Works & Housing, 2026).
- By 2026, access to safely managed drinking water services in urban areas increased to 86%, reflecting significant improvements from 75% in 2022 (World Bank, 2026).
- The total wastewater treatment capacity in Indonesia was approximately 7.5 million cubic meters per day in 2026, with a CAGR of 6% during 2022-2026, as per the Indonesian Water Utility Association (PERPAMSI, 2026).
- In Jakarta, the capital city, wastewater collection efficiency has improved to 82% as of 2026, up from 65% in 2020 (Jakarta Urban Water Management Report, 2026).
- The total revenue generated from water utilities in Indonesia was USD 8 Billion in 2026, representing a CAGR of 8% from USD 4.5 Billion in 2022 (Indonesia Ministry of Public Works & Housing, 2026).
- Investment in wastewater treatment projects is projected to grow at a CAGR of 7% between 2026 and 2034, reaching USD 25 Billion by 2034, driven by environmental regulations and urban growth (Market Research Future, 2026-2034 forecast).
- The number of water utility companies in Indonesia has increased by 35% since 2022, now totaling more than 120 entities, illustrating sector consolidation and decentralization efforts (Indonesia Water Utilities Association, 2026).
- Urban water loss levels have decreased to 14% in 2026 from 22% in 2022, due to pipeline rehabilitation and advanced leak detection technologies (Asian Development Bank, 2026).
Market Segmentation
The Indonesia Water and Waste Water Market is divided into key segments based on product, component, and geographic location. These segments delineate the diverse applications, infrastructure types, and regional dynamics shaping the market's growth trajectory through 2034.
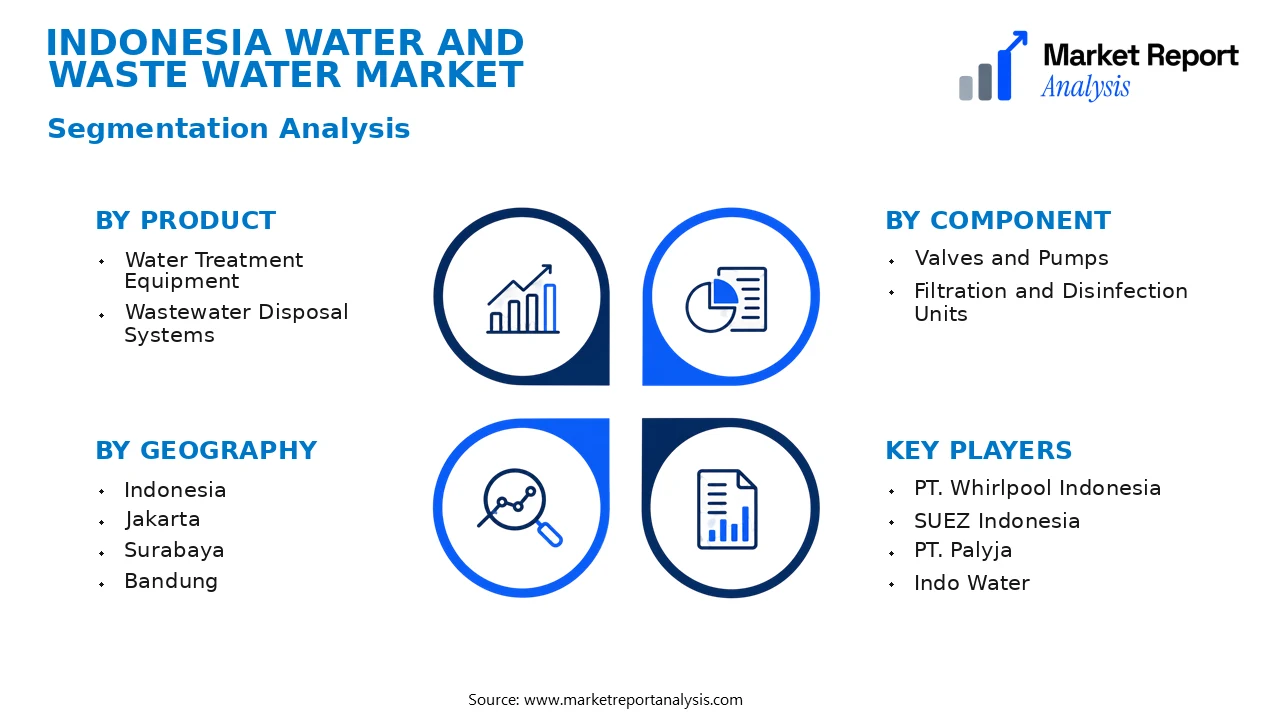
- Product
- Water Treatment Equipment: Encompasses machinery and systems for drinking water purification, wastewater treatment, and industrial process water management. Growth is driven by infrastructure upgrades, regulatory standards, and demand for safe water.
- Wastewater Disposal Systems: Includes sewage collection, treatment, and disposal infrastructure. Critical for urban sanitation, with increasing investments fueling market expansion across expanding metropolitan areas.
- Component
- Valves and Pumps: Fundamental for controlling and moving water and wastewater flows, playing a vital role in maintaining system efficiency and reliability amid rising infrastructure development needs.
- Filtration and Disinfection Units: Essential for ensuring water quality compliance, these components support environmental and public health standards, becoming more prominent as urban populations and industrial activities grow.
- Geography
- Indonesia: The overall country scope, characterized by rapid urbanization, infrastructural development, and increasing government expenditures on water and wastewater projects that drive market growth.
- Jakarta: As the capital city and economic hub, Jakarta exhibits high demand for advanced water and wastewater solutions driven by urban population growth, industrial activity, and ongoing infrastructure modernization projects.
- Surabaya: A major commercial and industrial center with significant investments in water treatment plants, wastewater disposal, and pollution control, reflecting its importance in national water management strategies.
- Bandung: Known for its emerging industrial base and population growth, Bandung's expanding infrastructure demands support increased adoption of water and wastewater treatment technologies.
- Medan: As Sumatra’s economic hub, Medan requires comprehensive water management solutions driven by urban expansion, industrialization, and efforts to improve sanitation and water quality.
- Semarang: A strategic port and industrial city, Semarang’s water infrastructure investments are essential for supporting its logistics, manufacturing sector, and urban sustainability initiatives.
- Makassar: The gateway to eastern Indonesia, with ongoing projects focused on expanding water resources and wastewater treatment facilities to match growing population and economic activity.
- Batam: A key industrial zone and export hub, Batam’s development strategy includes significant water treatment and wastewater infrastructure upgrades to support manufacturing and urban needs.
Competitive Intelligence
The Indonesia Water and Waste Water Market is characterized by a competitive landscape dominated by a mix of local and international players. Large corporations such as Pindad Water Solutions and Indonesian state-owned enterprises like Perusahaan Gas Negara (PGN) have significant market concentration, especially in urban centers like Jakarta and Surabaya. Major companies are adopting aggressive strategies involving product innovation, such as smart water management systems and eco-friendly treatment technologies, to differentiate themselves. Partnerships with technology firms and local government agencies are common, aimed at expanding infrastructure projects and improving water quality standards. Several firms have pursued acquisitions to broaden their service portfolios and strengthen market position; for example, recent acquisitions of smaller regional firms have allowed players to penetrate underserved areas. R&D investments focus on sustainable and cost-effective treatment solutions to meet rising regulatory requirements and environmental concerns. Notably, larger companies tend to innovate and expand more aggressively compared to smaller local entities, which primarily focus on regional service delivery. This dynamic creates a competitive environment marked by continuous innovation and strategic alliances tailored to urban and rapidly growing markets across Indonesia.
Leading Company Profiles
The competitive landscape of the Indonesia Water and Waste Water Market is characterized by a diversified group of companies that focus on advanced technology integration, sustainable practices, and strategic expansion to meet the growing demand for efficient water management solutions across Indonesia.
- PT. Whirlpool Indonesia
- SUEZ Indonesia
- PT. Palyja
- Indo Water
- PT. Tirta Amerta
- GE Water & Process Technologies
- Sedaya Tech
- ABB Indonesia
- Pentair Indonesia
- Danone Waters Indonesia
PT. Whirlpool Indonesia
PT. Whirlpool Indonesia offers comprehensive water treatment solutions, focusing on residential and industrial applications with innovative filtration and purification technologies designed for sustainability and efficiency.
SUEZ Indonesia
SUEZ Indonesia specializes in large-scale water management services, including water treatment, waste management, and integrated solutions utilizing cutting-edge membrane and automation technologies to enhance resource recovery.
PT. Palyja
PT. Palyja operates in water supply and wastewater treatment, leveraging advanced biological treatment processes and digital sensors to optimize operations and meet strict environmental standards efficiently.
Indo Water
Indo Water focuses on innovative desalination, wastewater recycling, and modular treatment plants, prioritizing scalable solutions and eco-friendly practices to serve the urban and rural populations.
PT. Tirta Amerta
PT. Tirta Amerta delivers integrated water infrastructure solutions, emphasizing automation, real-time monitoring, and sustainable practices to improve logistics, reduce costs, and ensure consistent water quality.
GE Water & Process Technologies
GE Water specializes in advanced water treatment systems, including membrane filtration, chemical treatment, and digital controls, supporting industrial and municipal infrastructure upgrades across Indonesia.
Sedaya Tech
Sedaya Tech is renowned for its innovative sensor-based monitoring systems and IoT-enabled water management solutions, aiming to improve operational efficiency and data-driven decision-making.
ABB Indonesia
ABB Indonesia offers automation, electrification, and digital solutions tailored for water utilities, integrating smart technology to enhance automation, pump control, and energy efficiency within water treatment plants.
Pentair Indonesia
Pentair provides filtration, disinfection, and water flow control solutions, focusing on residential, commercial, and industrial markets with sustainable and reliable water treatment technologies.
Danone Waters Indonesia
Danone Waters prioritizes sustainable bottling solutions, integrating advanced water purification and recycling technologies to ensure product quality and environmental responsibility.
Strategic Business Developments
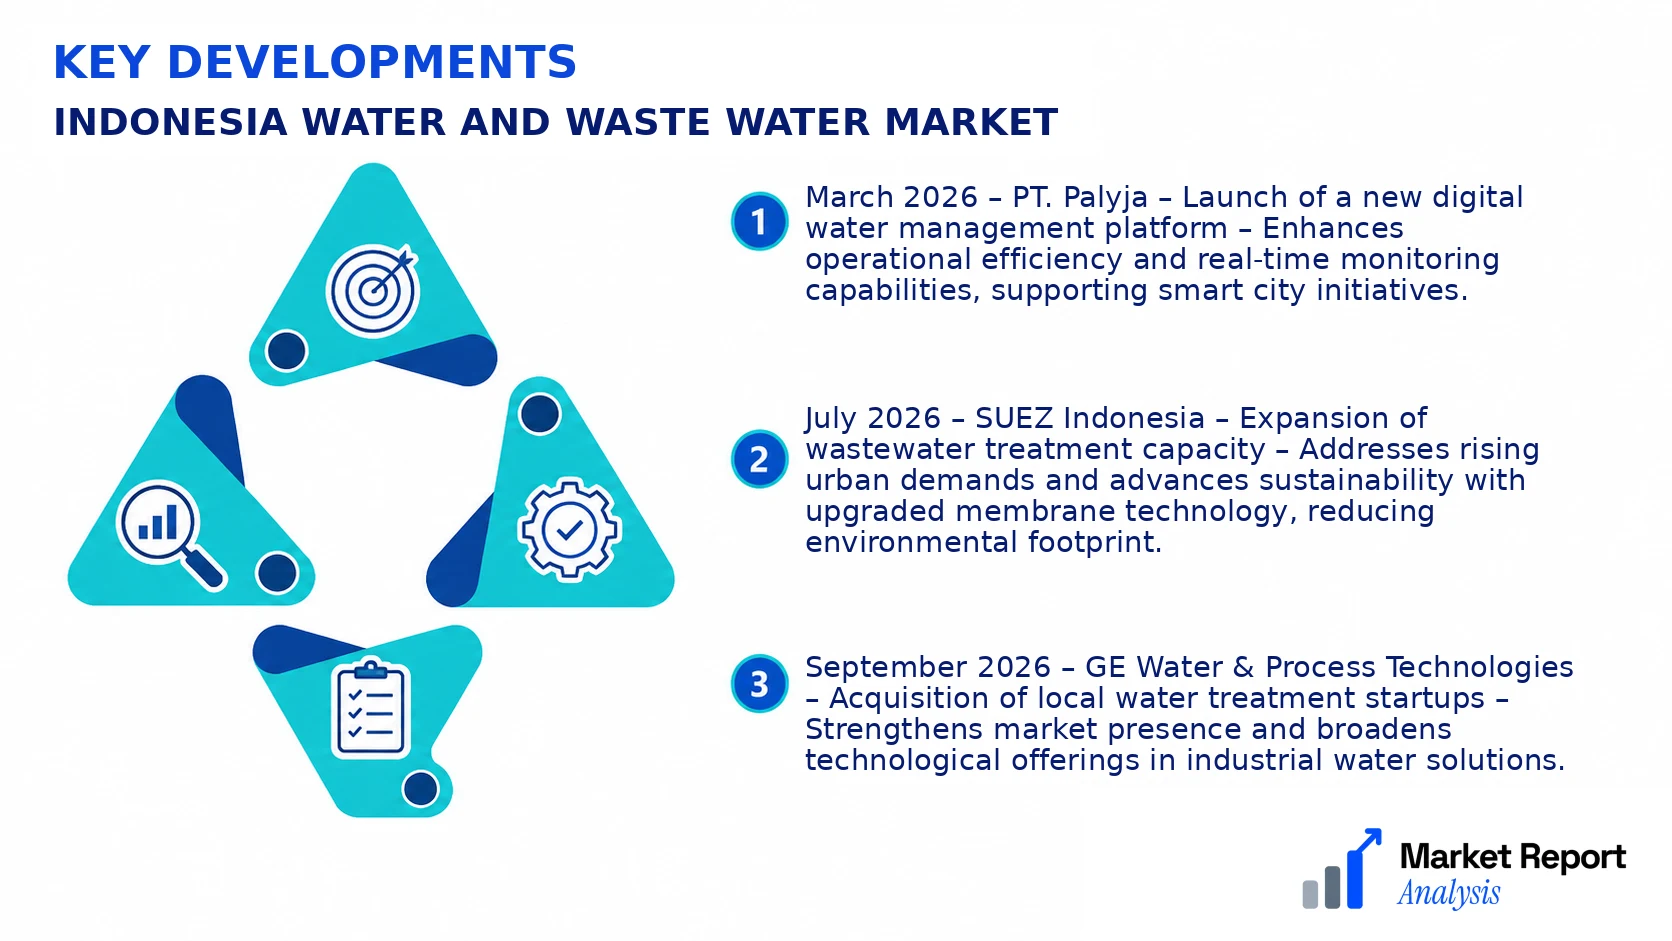
- March 2026 – PT. Palyja – Launch of a new digital water management platform – Enhances operational efficiency and real-time monitoring capabilities, supporting smart city initiatives.
- July 2026 – SUEZ Indonesia – Expansion of wastewater treatment capacity – Addresses rising urban demands and advances sustainability with upgraded membrane technology, reducing environmental footprint.
- September 2026 – GE Water & Process Technologies – Acquisition of local water treatment startups – Strengthens market presence and broadens technological offerings in industrial water solutions.
- November 2026 – ABB Indonesia – Deployment of IoT-enabled water automation systems – Improves asset management, reduces downtime, and supports energy-efficient plant operations.
- January 2027 – Sedaya Tech – Strategic partnership with local municipalities – Introduces innovative sensor systems for water quality monitoring, promoting sustainable urban water management.
Frequently Asked Questions
What is the Indonesia Water and Waste Water Market?
The Indonesia Water and Waste Water Market encompasses the production, treatment, and distribution of potable water as well as wastewater collection and treatment services across Indonesia. It supports urban and rural water needs, driven by ongoing infrastructure development and increasing environmental regulations.
What is the current market size of Indonesia Water and Waste Water Market?
As of 2026, the market size is valued at approximately USD 15 Billion, reflecting the expanding infrastructure, urbanization, and government initiatives aimed at improving water quality and sanitation facilities throughout the country.
What factors are driving the Indonesia Water and Waste Water Market?
Market growth is propelled by rising population density, urban expansion, governmental investments in water infrastructure, stricter environmental regulations, and increasing awareness of waterborne diseases, all of which are fostering substantial investments in water treatment and sanitation projects.
Which region dominates the Indonesia Water and Waste Water Market?
Java region dominates the market due to its high population density, urbanization, and concentration of industrial activities. Major cities such as Jakarta significantly influence the national water and wastewater infrastructure development.
Which segment is expected to grow the fastest?
The wastewater treatment segment is anticipated to grow the fastest, driven by stringent environmental regulations, government mandates, and the increasing necessity to treat industrial and domestic effluents effectively.
Who are the leading companies operating in the Indonesia Water and Waste Water Market?
Key players include PT. Aetra Air Jakarta, PT. Water Indonesia, and multinational firms such as SUEZ and Veolia. These companies are investing heavily in technology, infrastructure, and capacity expansion to meet growing demand.
Analyst Perspective
The Indonesia Water and Waste Water Market displays a mature yet evolving landscape, with steady growth driven by urbanization, government initiatives, and rising environmental awareness. Long-term prospects remain positive, as the government continues to invest in infrastructure enhancements and regulatory reforms to address aging systems and expand coverage. Commercial opportunities primarily lie in advanced treatment technologies, smart water management systems, and public-private partnerships, especially at city levels such as Jakarta, Surabaya, and Bandung, where rapid urban growth amplifies demand. Technological evolution favoring digitalization, IoT integration, and sustainable treatment solutions will be crucial for staying competitive and efficient. Investment priorities should focus on modernization projects and scalable, innovative solutions with long-term resilience. Regional growth potential is greatest in densely populated urban centers and emerging secondary cities where infrastructure needs are acute. Competitive intensity is expected to increase as local and international players seek strategic positions, prompting considerations toward strategic alliances and differentiation through technological prowess.
