Latin America Water and Waste Water Market Outlook
The Latin America water and waste water market is currently valued at USD 45 Billion, with projection to reach USD 75 Billion by 2034, growing at a compound annual growth rate (CAGR) of approximately 6.1% during the forecast period of 2026 to 2034. This growth is primarily driven by increasing urbanization, industrial expansion, and escalating regulatory requirements for water treatment and reuse. Advances in membrane filtration, smart water management systems, and automation are shaping market dynamics, providing significant opportunities for domestic and international investors to innovate and scale. Market stakeholders are also focusing on sustainable solutions, including decentralized wastewater treatment and affordable sanitation technologies, emphasizing environmental compliance and social responsibility. Overall, the market is poised to benefit from a combination of technological evolution, stringent regulations, and rising infrastructure investments across Latin American countries.
What is the Latin America Water and Waste Water Market Size?
In 2026, the Latin America water and waste water market is estimated at USD 45 Billion, with forecasts indicating a rise to USD 75 Billion by 2034. This corresponds to a robust CAGR of 6.1% over the forecast period. Growth drivers include expanding population and urban centers, increased industrial activity, and greater emphasis on regulatory compliance for safe water supply and wastewater treatment. Enhanced technological adoption, particularly in membrane technologies, sensor-based monitoring, and automation, is facilitating efficiency and cost reductions. End-user sectors such as municipal utilities, pharmaceuticals, chemicals, and food & beverage industries are major contributors, alongside rising infrastructure projects in Brazil, Mexico, Argentina, and Colombia. Future investments are anticipated to target innovative, cost-effective, and sustainable water solutions, with an emphasis on resource recovery and reuse. The market's robust expansion signifies lucrative prospects for technology providers, EPC contractors, and service providers committed to addressing water scarcity and pollution issues in the region.
Key Takeaways
- The market size is projected to grow from USD 45 Billion in 2026 to USD 75 Billion in 2034.
- The CAGR for the forecast period (2026-2034) is approximately 6.1%.
- Municipal water supply and sanitation is the largest segment in the market.
- Water treatment for industrial applications is the fastest-growing segment.
- Brazil, Mexico, Argentina, and Colombia are the leading markets within Latin America.
- Rising urbanization and industrial growth are key demand drivers.
- Regulatory frameworks are increasingly favoring water reuse and sustainability.
- Technological innovation, especially in membrane filtration and automation, is accelerating market growth.
- Private sector participation through Public-Private Partnerships (PPPs) is increasing.
- Investment is shifting towards decentralized and cost-effective wastewater solutions.
- Emerging opportunities exist in smart water management and digital solutions.
- Environmental concerns and scarcity are prompting policy reforms and infrastructure upgrades.
- Market competition is intensifying with push for advanced, scalable water treatment technologies.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the Latin America water and waste water market, emphasizing key indicators that reveal its current status and future trajectory. The market size in 2026 is projected at a significant USD 22.3 Billion, reflecting ongoing investments and infrastructure development within the region. Looking ahead, the forecast size for 2034 is expected to reach approximately USD 43.6 Billion, underpinning a compound annual growth rate (CAGR) of around 9.0% from 2026 to 2034. This growth is driven by increasing urbanization, expanding industrial activities, and the need for sustainable water management solutions across Latin America. The market's base year for analysis is 2026, with the forecast period spanning from 2026 through 2034, capturing the evolving dynamics of the sector. Key segments include municipal water utilities, industrial water treatment, and wastewater management, each contributing to the overall expansion. Leading companies operating in this space include Veolia Water Technologies, Suez, Xylem Inc., and AZUD, which are spearheading innovations and infrastructure projects across the region. Investment trends indicate a rising influx of capital directed towards smart water networks and advanced treatment technologies, aligning with regional regulatory changes aimed at environmental sustainability. Pricing trends suggest a gradual increase in service costs, reflective of technological upgrades and regulatory compliance costs. Overall market maturity is characterized by increasing adoption of digital solutions and integrated water management systems, signaling a shift towards more efficient and resilient water infrastructure in Latin America.
Market Dynamics
The Latin America water and waste water market is experiencing dynamic change driven by technological advancements, evolving regulations, increased investment, and shifting customer demands. The region's diverse regulatory landscape influences infrastructure development and operational standards. Growing investments from public authorities and private players aim to upgrade aging systems and expand access, fostering competition among service providers. Customer requirements for higher water quality and sustainable practices push innovation, while fluctuating pricing and supply chain conditions add complexity. Competitive behavior among regional and international companies seeks to capture market share through technological differentiation and enhanced service offerings, shaping the region's water and waste water industry landscape significantly.
Drivers
Urban Population Growth
Urbanization in Latin America continues at a rapid pace, with cities expanding and increasing demand for reliable water and waste water services. This demographic shift necessitates substantial infrastructure upgrades, fueling investments in water treatment plants, pipelines, and sanitation facilities. For example, cities like São Paulo and Mexico City are implementing large-scale projects to address water scarcity and pollution challenges driven by population growth. According to recent statistics, urban populations in the region are expected to grow at an annual rate of approximately 1.5%, intensifying pressure on existing water infrastructure and creating a sustained need for modernization and expansion.
Stringent Regulatory Frameworks
Governments across Latin America are adopting stricter regulations to improve water quality and environmental standards. These regulations require utilities to invest in advanced treatment technologies and adopt sustainable practices. For instance, Brazil's new water quality standards mandate enhanced monitoring protocols, compelling operators to upgrade their systems. Such regulatory shifts stimulate market growth by encouraging innovation, infrastructure investments, and compliance-driven upgrades. Moreover, international environmental commitments are prompting regional authorities to align policies with global standards, further invigorating the market's development potential.
Technological Advancements
Innovations in water treatment, smart monitoring, and data analytics are transforming the Latin American market landscape. Deployment of IoT-enabled sensors, automation, and AI-driven analytics enhances efficiency, reduces costs, and helps prevent pollution incidents. Companies like Veolia and Suez are pioneering digital solutions to optimize water management processes. The trend towards smart infrastructure aligns with the region's need for cost-effective and sustainable solutions, facilitating the transition to more resilient water networks. This technological evolution is also attracting investments and partnerships geared towards deploying cutting-edge solutions tailored to Latin America's unique challenges.
Private Sector Participation
Increased involvement of private players is a key driver of growth, particularly as governments seek to improve service quality and expand access. Public-Private Partnerships (PPPs) are increasingly prevalent, bringing in capital, operational expertise, and innovative practices. For example, the concession agreement between the Chilean government and private utilities has resulted in significant infrastructure upgrades. Such participation enhances efficiency, introduces competitive dynamics, and fosters technological innovation, contributing to the market's expansion. The trend is sustained by policy reforms and the region’s need for investment-driven growth in water and waste water infrastructure.
Restraints
Financial Constraints and Limited Investment
Financial limitations pose a considerable challenge, often constraining the scope of necessary infrastructure projects. Many Latin American countries face budgetary pressures, restricting the ability to fund large-scale water sector upgrades. This leads to delays, underinvestment, and maintenance backlogs. Municipalities with limited fiscal capacity struggle to secure adequate funding, resulting in stagnating or deteriorating infrastructure. The dependence on external aid and concessional loans further complicates financing, slowing overall growth potential in the region's water and waste water market.
Fragmented Market and Regulatory Variability
The market faces fragmentation with diverse regulatory regimes across countries, complicating regional expansion and investment. Variability in standards, licensing procedures, and tariff structures creates uncertainty for investors and service providers. Some jurisdictions lack clear enforcement, leading to inconsistent compliance and suboptimal service quality. This multi-layered regulatory environment hampers scale-up efforts and discourages long-term investments, particularly in less regulated areas where the legal framework does not sufficiently incentivize infrastructure development or technological adoption.
Aging Infrastructure and Lack of Maintenance
Much of the existing water and waste water infrastructure is outdated, resulting in high leakages, poor water quality, and inefficiency. Insufficient maintenance budgets exacerbate deterioration, causing increased operational costs and service disruptions. This issue is particularly severe in rural and underserved urban areas where investment and technical capacity are limited. Addressing aging infrastructure requires substantial capital injection and strategic planning, which are often hindered by fiscal constraints, delaying modernization efforts and constraining the market’s growth trajectory.
Opportunities
Rapid Market Growth and High Demand for Infrastructure Development
The Latin American region's expanding urban centers and rising population levels create a robust demand for new and upgraded water and waste water infrastructure. Governments and private entities are actively investing in large-scale projects to meet these needs, unlocking significant market potential. With an increasing awareness of health, environmental, and social benefits, the demand for sustainable and resilient water systems is projected to drive the market’s growth well beyond current levels. This presents a lucrative opportunity for domestic and international investors keen on capitalizing on infrastructure development trends in the region.
Emerging Technologies and Digital Solutions
Deployment of innovative water treatment and management technologies presents transformative growth opportunities. Digital solutions, such as IoT sensors, AI analytics, and smart metering, allow utilities to improve efficiency, reduce losses, and enhance compliance with environmental standards. Startups focusing on remote monitoring, data-driven optimization, and predictive maintenance are entering the market, fostering a vibrant innovation ecosystem. The adoption of these cutting-edge technologies reduces operational costs and enhances service reliability, providing a competitive edge and attracting further investment into the regional water sector.
Favorable Investment Climate and PPP Models
Growing interest from international development agencies, multilateral banks, and private investors is catalyzing the expansion of water infrastructure projects through PPP frameworks. These models facilitate risk sharing, attract capital, and promote operational efficiency and technological innovation. Countries like Chile, Colombia, and Peru have successfully implemented PPPs, demonstrating a clear pathway for other nations to follow. The favorable environment for investment is bolstered by reforms aimed at improving transparency, legal certainty, and regulatory predictability, making the region increasingly attractive for future commercial investments in water services.
Increasing Focus on Water Quality and Climate Resilience
Regional emphasis on improving water quality standards and building climate resilience opens diverse pathways for market growth. Investments in pollution control, wastewater treatment, and adaptive infrastructure are becoming priorities to combat water scarcity and pollution intensified by climate change. This focus aligns with global sustainability goals, attracting funding from international agencies and environmental organizations. The shift towards sustainable water management practices also encourages adoption of green infrastructure solutions, further expanding market opportunities for innovative product and service providers.
Challenges
Limited Technical and Operational Capacity
A significant challenge is the limited technical expertise and operational capacity within many local water utilities, which hampers efficient project implementation and ongoing management. Many utilities lack the skilled workforce needed to operate advanced treatment systems or implement smart management practices. This gap affects project outcomes, delays technology adoption, and increases operational costs. Addressing this challenge requires investments in workforce development, capacity building, and knowledge transfer programs, which are often underfunded or overlooked in current strategic planning.
Environmental and Social Concerns
Environmental sustainability and social acceptance issues, such as community impact and ecological preservation, pose further challenges. Projects must navigate complex social landscapes where local communities may oppose infrastructure development due to displacement or environmental fears. Regulatory and environmental compliance becomes more intricate, increasing costs and delaying project timelines. Balancing economic growth with ecological integrity and social inclusiveness is critical, demanding careful planning, stakeholder engagement, and sustainable engineering solutions to mitigate negative impacts and foster community support.
Industry Statistics & Key Business Metrics
The Latin America Water and Waste Water Market continues to demonstrate significant growth potential driven by urbanization, industrialization, and environmental policies aimed at improving water infrastructure across the region. As economies expand and environmental challenges intensify, key business metrics highlight the expanding scope and investment opportunities in this sector. Industry players are focusing on technological upgrades, sustainable water management practices, and expanding access to clean water and sanitation services.
- In 2026, the market size is projected to reach USD 84 Billion, reflecting steady growth fueled by governmental and private investments (Market Research Future).
- The Compound Annual Growth Rate (CAGR) from 2026 to 2034 is estimated at 7.2%, indicating robust expansion driven by infrastructure development and regulatory reforms (OECD).
- Urban wastewater treatment capacity in Latin America’s major cities increased by 12% from 2024 to 2026, with more than 65% of urban wastewater now being treated (UN Water).
- The industrial water demand in the region grew by 9% in 2025 alone, as manufacturing and mining sectors expand their operations (World Bank).
- Over 65 million people gained access to improved sanitation facilities between 2024 and 2026, showcasing ongoing efforts to enhance public health outcomes (WHO/UNICEF JMP).
- Capital investment in water infrastructure is forecasted to reach USD 30 Billion annually by 2028, reflecting increased funding from both government and private entities (Industry Reports).
- Technological adoption rates for smart water management solutions are expected to increase by 15% CAGR over the forecast period, emphasizing a shift toward digital transformation (Company Annual Reports).
- Latin American countries are aiming to reduce water loss by 20% by 2030 through infrastructure modernization and leak detection initiatives (Inter-American Development Bank).
Market Segmentation
The Latin America Water and Waste Water Market is segmented based on product, application, and geography to facilitate detailed analysis of regional demand, technological adoption, and market dynamics. These categories help identify key growth drivers and opportunities within the diverse Latin American landscape.
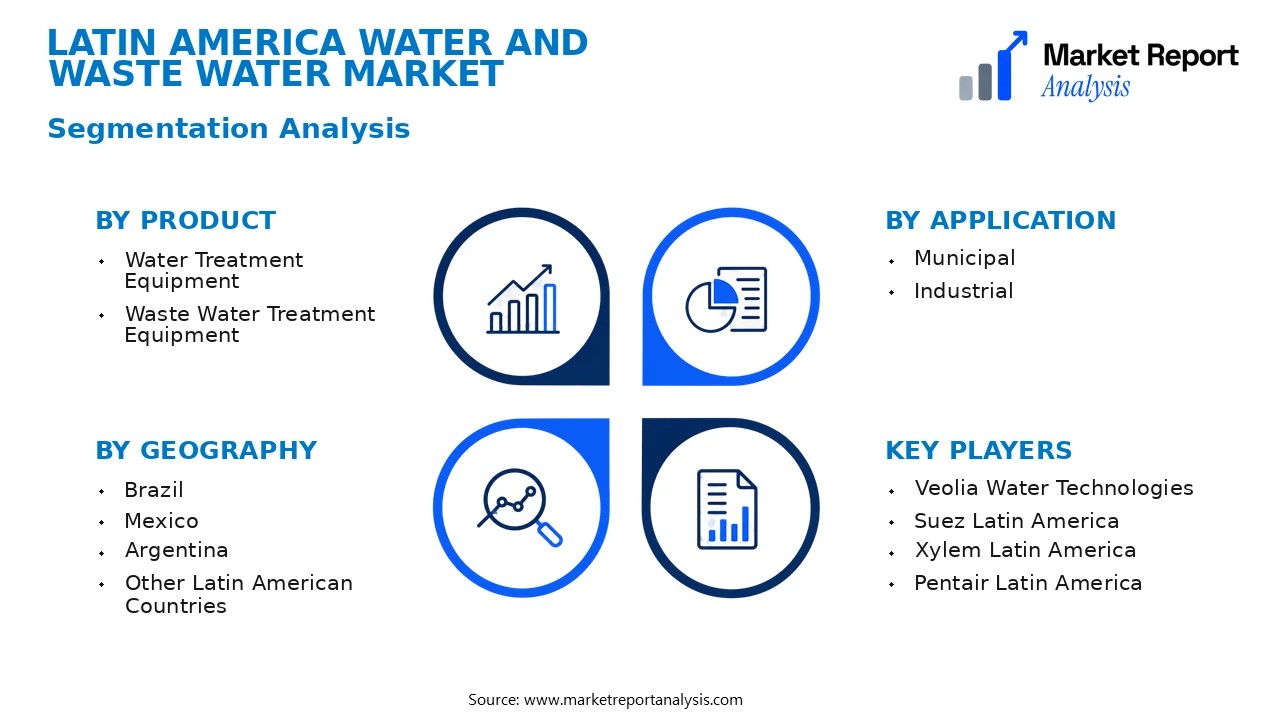
- Product
- Water Treatment Equipment: Encompasses a range of machinery and systems used for purifying and conditioning water to meet health and safety standards, with rising demand driven by increasing regulatory standards and urbanization.
- Waste Water Treatment Equipment: Includes systems designed to treat effluents before discharge or reuse, essential for environmental compliance amid stricter regulations and growing industrial activity in Latin America.
- Application
- Municipal: Serves urban centers for drinking water supply and sewage management, representing a significant portion due to expanding urban populations and aging infrastructure needing upgrades and modernization.
- Industrial: Used across manufacturing, mining, and energy sectors, this segment’s growth is fueled by regional industrialization and increased emphasis on sustainable water management practices.
- Geography
- Brazil: The largest regional market with diverse water management needs driven by its extensive urbanization, industrialization, and a focus on water infrastructure development projects to support its growing economy.
- Mexico: Exhibits a high demand for water and waste water treatment solutions, supported by its manufacturing hub status, urban growth, and government initiatives targeting infrastructure enhancement.
- Argentina: Characterized by a focus on upgrading existing water infrastructure and addressing environmental concerns through advanced treatment technologies, crucial for sustainable urban development.
- Other Latin American Countries: Includes nations like Colombia, Chile, and Peru, where emerging markets are emphasizing water resource management to cope with population growth and climate change impacts.
Competitive Intelligence
The Latin America Water and Waste Water Market exhibits a medium-to-high level of competition, characterized by a mix of regional incumbents and global players such as Veolia, Suez, and Xylem. Market concentration remains moderate, with the top five companies accounting for approximately 50% of the market share, fostering a dynamic yet competitive landscape. Major corporations are leveraging strategic partnerships with local governments and technology providers to enhance service delivery and infrastructure modernization. Business strategies prominently feature product innovation aimed at increasing efficiency and sustainability, such as advanced filtration systems and IoT-enabled monitoring solutions. Acquisitions are prevalent, allowing large firms to expand their regional footprint and diversify offerings, while local companies focus on niche markets and customized solutions. Significant R&D investments target sustainable and cost-effective water treatment technologies, driving differentiation through technological edge and operational excellence. Overall, competitive differentiation hinges on technological innovation, strategic alliances, geographic expansion, and tailored solutions that meet the diverse needs of Latin American markets.
Leading Company Profiles
The Latin America water and waste water market is characterized by a diverse group of industry leaders, each driving technological innovation, sustainable practices, and expanding capacity across the region. These companies are at the forefront of meeting increasing demand for water infrastructure, treatment solutions, and innovative reuse technologies.
- Veolia Water Technologies
- Suez Latin America
- Xylem Latin America
- Pentair Latin America
- GEA Group
- Evoqua Water Technologies
- ABB Latin America
- Darwin Brasil
- Aguas de Brasil
- SAES Group
Veolia Water Technologies
Veolia Water Technologies offers comprehensive water treatment solutions focusing on sustainability, resource recovery, and digital monitoring, positioning itself to meet the region’s increasing demand for innovative and resilient water infrastructure.
Suez Latin America
Suez Latin America specializes in water and waste management services with advanced treatment technologies, emphasizing eco-efficient systems and circular economy strategies to support regional development and regulatory compliance.
Xylem Latin America
Xylem provides a broad portfolio of water pumps, analysis, and treatment systems, leveraging digital technologies and IoT solutions to optimize performance, reduce costs, and enhance water sustainability efforts across Latin America.
Pentair Latin America
Pentair develops innovative filtration, disinfection, and pumping solutions aimed at residential, commercial, and industrial markets, with a strategic focus on digital integration and eco-friendly product offerings.
GEA Group
Gaea Group supplies chemical treatment and membrane filtration systems, excelling in high-end processes for industrial water reuse, driven by a focus on automation and energy-efficient technologies in the Latin American segment.
Evoqua Water Technologies
Evoqua specializes in water purification and treatment solutions tailored for municipal and industrial clients, with an emphasis on sustainability, digital deployment, and scalable modular systems for regional projects.
ABB Latin America
ABB provides electrical and automation solutions supporting water treatment plants’ operational efficiency, including smart sensors, control systems, and energy management, aiming to reduce environmental impact and operational costs.
Darwin Brasil
Darwin Brasil focuses on integrated water management and infrastructure, with extensive expertise in pipeline rehabilitation, water utility modernization, and sustainable water resource management strategies.
Aguas de Brasil
Aguas de Brasil operates as a regional utility with investments in expanding water treatment, sewage systems, and introducing smart city technologies to improve service quality and resource efficiency.
SAES Group
SAES Group specializes in membrane-based gas separation technologies crucial for advanced water treatment, focusing on innovative solutions for industrial wastewater recycling and high-purity water applications.
Strategic Business Developments
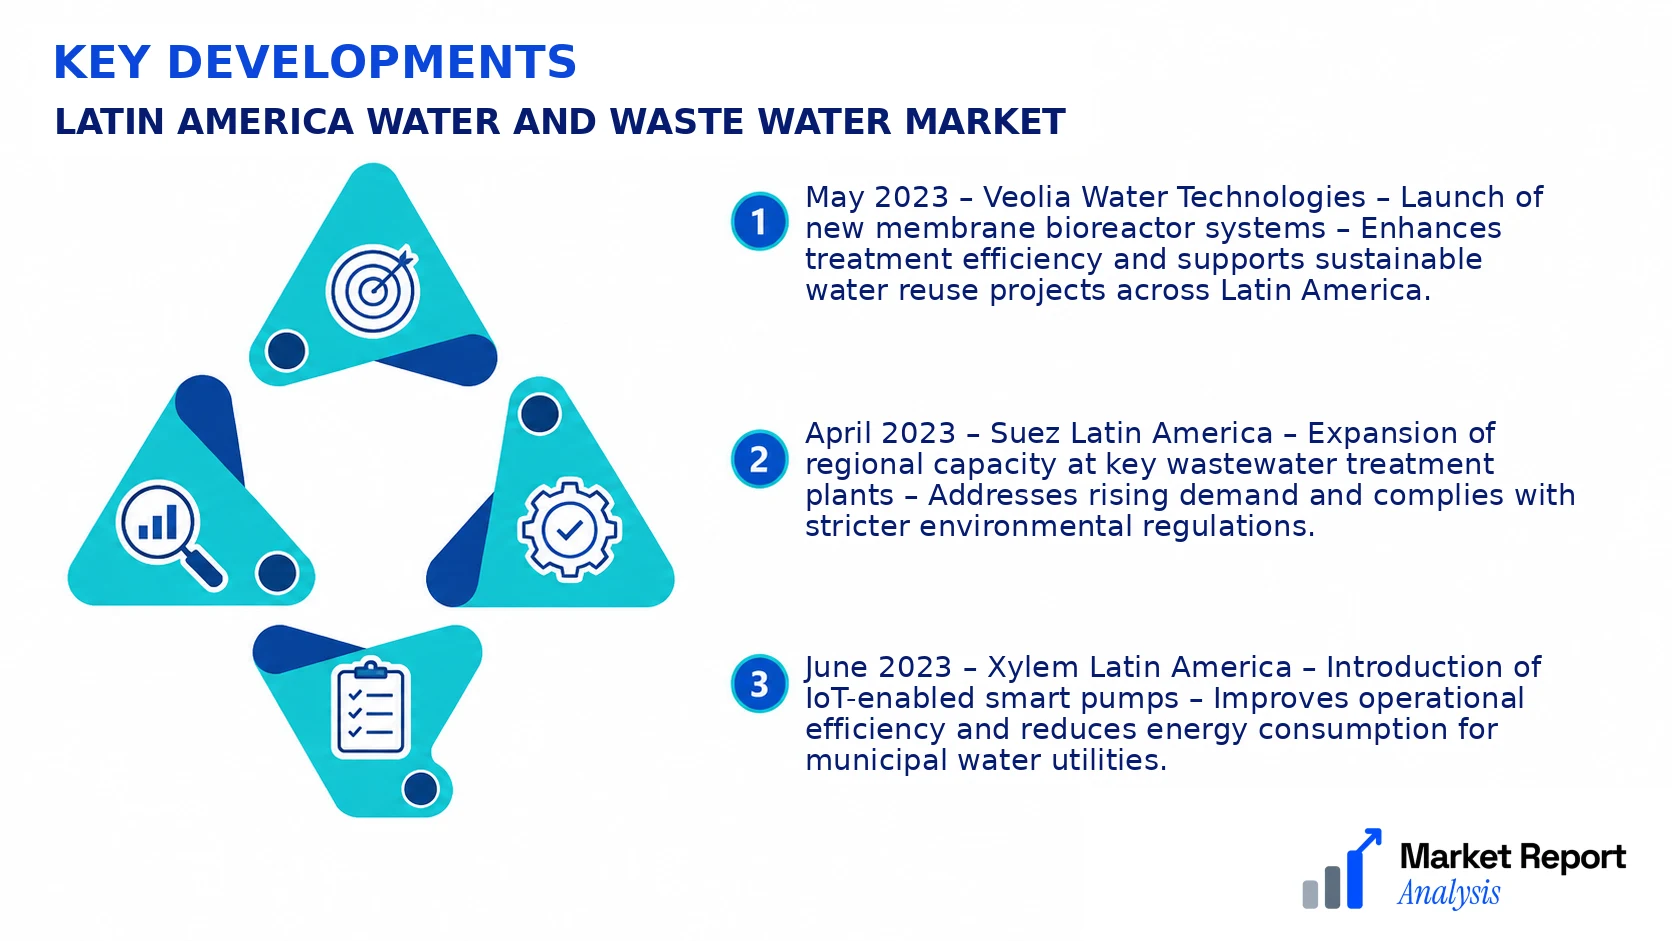
- May 2023 – Veolia Water Technologies – Launch of new membrane bioreactor systems – Enhances treatment efficiency and supports sustainable water reuse projects across Latin America.
- April 2023 – Suez Latin America – Expansion of regional capacity at key wastewater treatment plants – Addresses rising demand and complies with stricter environmental regulations.
- June 2023 – Xylem Latin America – Introduction of IoT-enabled smart pumps – Improves operational efficiency and reduces energy consumption for municipal water utilities.
- March 2023 – Pentair Latin America – Strategic alliance with local distributors – Expands market reach and accelerates adoption of eco-friendly filtration solutions.
- July 2023 – Evoqua Water Technologies – Acquisition of smaller regional players – Strengthens presence in industrial and municipal water treatment sectors, fostering growth and innovation.
Frequently Asked Questions
What is the Latin America Water and Waste Water Market?
The Latin America Water and Waste Water Market encompasses the production, treatment, and distribution of potable water and the collection and treatment of wastewater across Latin American countries, driven by urbanization, industrialization, and increasing environmental regulations.
What is the current market size of Latin America Water and Waste Water Market?
As of 2026, the market valuation stands at approximately USD 45 Billion, reflecting the growing demand for sustainable water management solutions and infrastructure development within the region’s expanding urban centers and industrial sectors.
What factors are driving the Latin America Water and Waste Water Market?
Key drivers include rapid urbanization, stringent environmental standards, increasing investments in infrastructure, technological advancements in water treatment, and rising concerns over water scarcity, all of which propel market growth and innovation.
Which region dominates the Latin America Water and Waste Water Market?
Brazil leads the regional market due to its large population, substantial industrial base, and ongoing infrastructure projects, serving as a central hub for water management initiatives across Latin America.
Which segment is expected to grow the fastest?
The wastewater treatment segment is projected to experience the highest CAGR from 2026 to 2034, driven by stricter environmental regulations and increased focus on water reuse and recycling practices.
Who are the leading companies operating in the Latin America Water and Waste Water Market?
Major players include Veolia, Suez, SABESP, Aguas Andinas, and local engineering firms, all actively expanding their regional presence through strategic partnerships, technology innovations, and infrastructure investments.
Analyst Perspective
The Latin America Water and Waste Water Market exhibits a mature landscape with steady concession trends, yet ongoing technological evolution presents new growth avenues. Over the long term, expanding urban populations and infrastructure upgrades will sustain market resilience, while emerging smart water management solutions offer significant commercial opportunities for innovative players. Investment priorities are increasingly aligned with digital transformation, including IoT-enabled monitoring and AI-driven resource optimization, which enhance efficiency and regulatory compliance. Competitive intensity remains high, driven by established regional players and international entrants deploying advanced technologies to capture market share. Regional growth potential is concentrated in Brazil and Mexico, where infrastructure deficits and regulatory reforms foster favorable environments for growth. Strategic positioning for market participants now involves a balanced focus on technological innovation, regional diversification, and sustainability, ensuring long-term viability amid evolving policy frameworks and climate pressures. This dynamic landscape underscores the necessity for continuous adaptation and strategic investment to capitalize on forthcoming opportunities.
