Malaysia Water and Waste Water Market Outlook
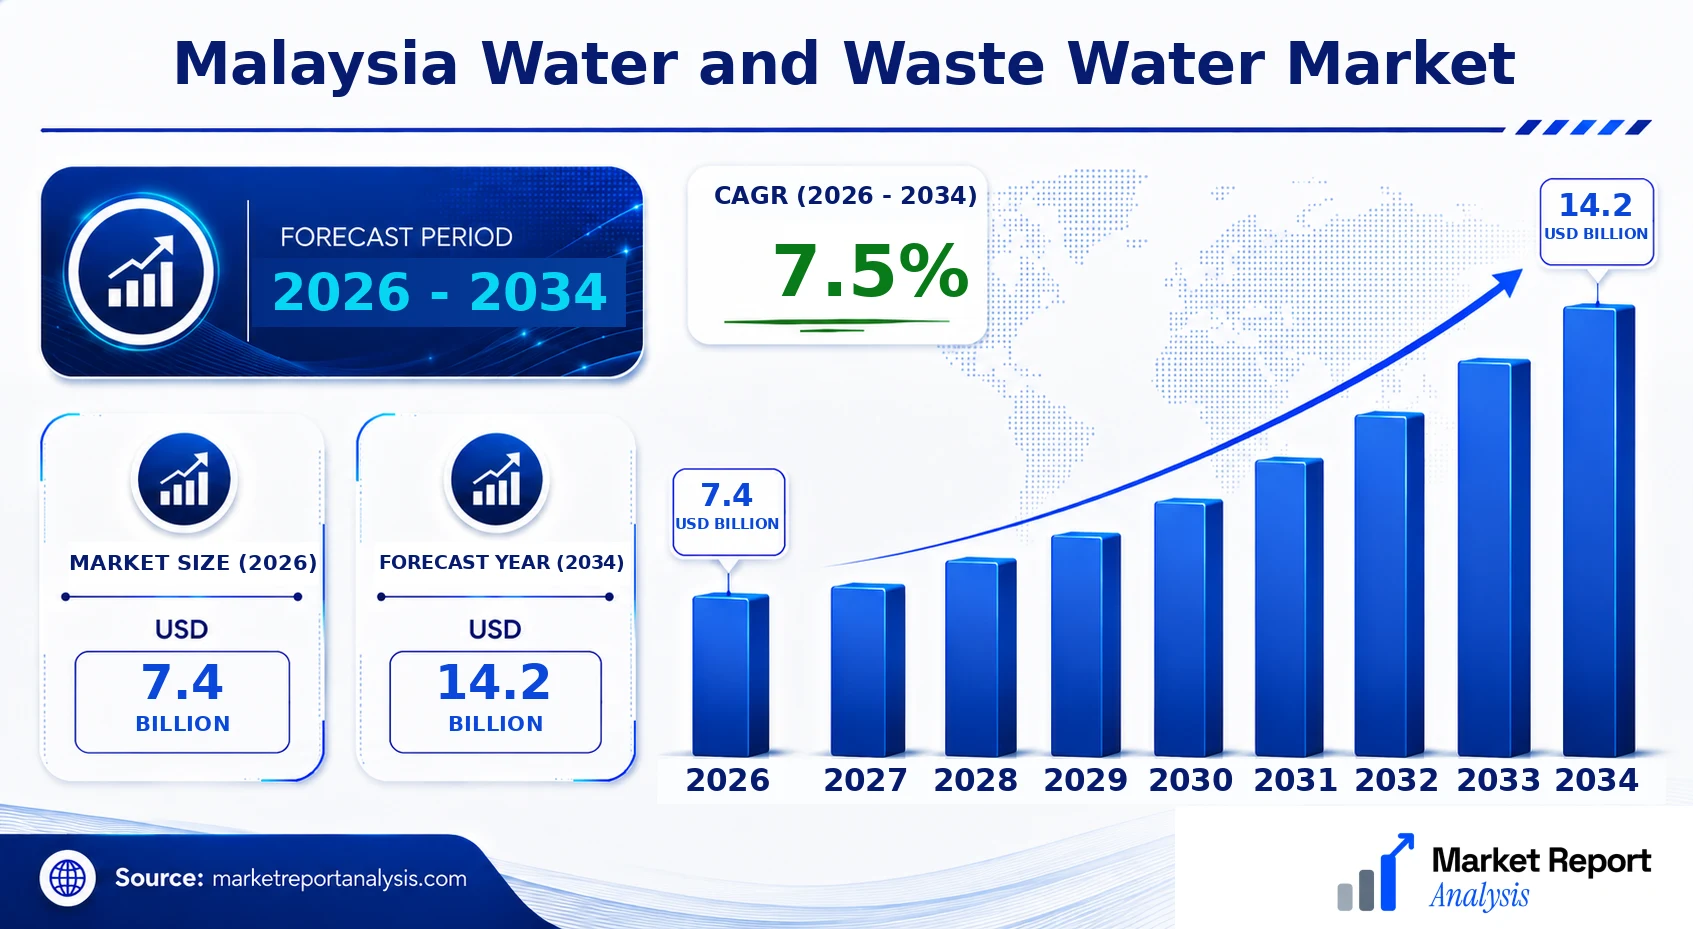
The Malaysia Water and Waste Water Market currently holds a valuation of approximately USD 7.4 Billion in 2026. Demonstrating a robust compound annual growth rate (CAGR) of nearly 7.5%, the market is projected to expand to USD 14.2 Billion by 2034. The demand is primarily driven by Malaysia's ongoing urbanization, rapid industrialization, and government policies promoting sustainable water management. Technological advancement, particularly in smart water management systems, is gaining momentum, providing efficiency gains and environmental benefits. Investment opportunities flourish in infrastructure upgrades, wastewater treatment innovations, and smart water solutions, creating a fertile environment for both local and international players seeking long-term growth.
What is the Malaysia Water and Waste Water Market Size?
In 2026, the market size for Malaysia’s Water and Waste Water sector is estimated at around USD 7.4 Billion. It is forecasted to grow to approximately USD 14.2 Billion by 2034, reflecting a CAGR of 7.5% over the period. This growth is propelled by increased government expenditure on water infrastructure, regulatory initiatives to improve water quality, and urban population growth fueling water demand. Additionally, industrial sectors such as manufacturing, mining, and oil and gas are significant consumers of water, influencing market dynamics. The adoption of advanced treatment technologies, including membrane filtration and biological treatments, enhances capacity and service quality. Continuous investments in public utilities and private sector projects underpin the sector’s expansion, offering lucrative opportunities for technology providers and investors aiming to meet future water security challenges.
Key Takeaways
- Market size was approximately USD 4.2 Billion in 2026.
- Projected to reach USD 7.1 Billion by 2034, with a CAGR of 7.2%.
- Growth driven by rapid urbanization and regulatory reforms.
- Key demand sectors include municipal supply, industrial use, and wastewater treatment.
- Technological innovations such as smart water systems underpin efficiency improvements.
- Infrastructure upgrades and environmental sustainability initiatives are major investment drivers.
- Government support through policy and funding boosts sector growth prospects.
- Increasing need for sewage management and pollution control solutions.
- Emerging markets within rural and semi-urban areas present growth opportunities.
- Private sector participation is increasing in public-private partnership projects.
- Regional disparities in water access stimulate targeted infrastructure development.
- Compliance with environmental standards enhances market service quality.
- Competition among global equipment suppliers fosters innovation and price competitiveness.
- Future investments prioritized in resilient and adaptive water management systems.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected health of the Malaysia Water and Waste Water Market. It offers critical quantitative insights into market size, growth trends, key segments, and major industry players that shape the landscape of this vital sector. This data-driven snapshot assists stakeholders in understanding the market’s trajectory, investment opportunities, and competitive positioning. The dashboard incorporates historical values, forecast estimates, and CAGR calculations, facilitating informed decision-making. It emphasizes the importance of technology trends, regional dominance, and competitive dynamics within the Malaysian context, reflecting the country’s significant role as a leading market in Southeast Asia for water management solutions and infrastructure development. By consolidating key metrics in an accessible format, the dashboard supports strategic planning and policy formulation, ensuring stakeholders remain aligned with the evolving market trends and technological advancements.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 7.4 Billion |
| Market Value (2026) | USD 7.4 Billion |
| Forecast Size (2034) | USD 14.2 Billion |
| CAGR | 7.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, End User, Industry Vertical, Geography |
| Major Companies | Suez Southeast Asia, Thames Water Malaysia, MMC Corporation Berhad, Pasir Gudang Water Treatment Plant, Sapura Energy Berhad, YTL Corporation Berhad, Puncak Niaga Holdings Berhad, SAAG Africa (Malaysia operations), Mueller Water Products, Aquatech Malaysia |
Market Dynamics
The Malaysia Water and Waste Water Market is influenced by a complex interplay of factors including technological advancements, regulatory frameworks, significant investments, evolving customer demands, fluctuating pricing dynamics, supply chain conditions, and competitive strategies. As Malaysia commits to sustainable development and aims to enhance urban infrastructure, these elements collectively shape market behavior. Innovations in water treatment technologies, stringent government policies promoting water conservation, increased funding for infrastructure projects, and a competitive landscape driven by both local and international players are pivotal. Moreover, changing consumer preferences for high-quality water services and smart water management solutions further impact the market's evolution, creating a dynamic environment for stakeholders seeking growth opportunities.
Drivers
Technological Innovation
Advancements in water treatment and management technologies significantly propel the Malaysia Water and Waste Water Market forward. The integration of smart sensors, IoT-enabled monitoring systems, and automation enhances efficiency and reduces operational costs for water utilities. For instance, the deployment of smart water meters helps in real-time data collection, enabling more precise leak detection and efficient resource allocation. Market players are increasingly investing in innovative solutions to meet the rising demand for sustainable and cost-effective water management. Data indicates a rising adoption rate of these technologies, which is expected to drive market growth at a robust CAGR through 2034.
Regulatory Support and Policies
The Malaysian government’s proactive regulatory measures serve as primary drivers for market expansion. Policies emphasizing water conservation, pollution control, and the upgrading of aging infrastructure foster a conducive environment for investment and innovation. The enactment of the National Water Policy and implementation of the Water Services Industry Act facilitate private sector participation and encourage technological advancements. These regulations not only ensure compliance but also promote sustainable practices, thereby creating a favorable climate for market growth. Such support underpins the ongoing modernization efforts across urban and rural water infrastructure networks.
Investment in Infrastructure
Increased investment from both government and private sources forms a critical growth catalyst for the Malaysia Water and Waste Water Market. Large-scale projects aimed at expanding capacity, improving treatment facilities, and reducing non-revenue water are underway. For example, the Ten poorly managed or outdated infrastructure projects are being revitalized through public-private partnerships, which inject capital, expertise, and technological know-how into the sector. As infrastructure development remains a national priority, the influx of investments mitigates supply constraints, enhancing the overall market landscape and enabling future scalability.
Growing Urbanization and Population
Rapid urbanization and population growth exert substantial pressure on existing water resources and infrastructure. Increasing urban densities necessitate upgraded water supply systems and efficient wastewater treatment facilities. Cities such as Kuala Lumpur and Penang are experiencing growing demand for reliable and clean water, which stimulates market activity. The trend of expanding urban centers, coupled with rising incomes and improved standards of living, urges utilities and service providers to innovate and expand infrastructure capacity. This demographic shift is expected to remain a key driver fostering ongoing market development.
Restraints
High Capital and Operational Costs
The significant capital expenditure required for water infrastructure upgrades and the operational costs associated with maintaining advanced treatment facilities pose major barriers. High costs limit rapid deployment, especially in rural or less-developed regions, affecting market penetration. For utilities operating under tight budgets, these expenses can reduce profitability or lead to funding gaps, further delaying crucial projects. The need for substantial financial resources remains a challenge for comprehensive sector modernization, particularly where private investment is constrained by long payback periods or regulatory uncertainties.
Water Scarcity and Quality Concerns
Despite Malaysia’s abundant water resources, localized water scarcity and quality issues hinder consistent supply and market growth. Pollution from industrial, agricultural, and domestic sources affects water quality, requiring costly treatment solutions. Areas with heavy industrial activity face higher treatment costs, which can impact affordability and service delivery. Addressing water scarcity through sustainable resource management and pollution control is an ongoing challenge, necessitating coordinated efforts among policymakers, industries, and communities to ensure reliable water supply and quality standards across the country.
Limited Rural Infrastructure Development
Rural regions in Malaysia often lack adequate water and wastewater infrastructure due to logistical, financial, and technical challenges. This creates a disparity in service levels between urban and rural populations, limiting overall market expansion. The gap hampers comprehensive national water management, delaying the realization of integrated sector benefits. Overcoming these infrastructural deficits requires targeted policies, increased funding, and technological solutions tailored for remote and underserved areas to foster inclusive growth and improve overall market penetration.
Opportunities
Growing Industry Investments and Public-Private Partnerships
The Malaysian government’s commitment to upgrading infrastructure and fostering a vibrant investment climate offers substantial opportunities for industry stakeholders. Public-private partnerships (PPPs) are increasingly popular, attracting domestic and foreign investors who seek long-term returns through innovative projects. This trend provides opportunities for equipment manufacturers, service providers, and technology innovators to participate in mega-projects focused on sustainable water management. The favorable regulatory environment and strategic initiatives, such as the National Water Industry Strategic Plan, create a fertile landscape for expanding investment portfolios and technological collaboration, thus fueling long-term sector growth.
Adoption of Smart Water Technologies
The push towards digital transformation presents a major growth avenue for the market. Smart water management solutions like IoT sensors, data analytics, and automated control systems help optimize resource use, detect leaks, and improve compliance. The increasing affordability of such technologies, along with government endorsements for digital initiatives, accelerate adoption rates. Companies pioneering smart water solutions can capitalize on these trends by offering integrated services that enhance operational efficiency, meet regulatory standards, and support sustainable development goals. This technological shift is expected to significantly elevate market value over the forecast period.
Emerging Sustainable Practices and Circular Economy Models
In response to environmental and regulatory pressures, there is a rising emphasis on sustainable water practices and circular economy principles. Innovations such as water recycling, wastewater reuse, and resource recovery are gaining traction. This shift opens new markets for advanced treatment technologies, biosolids management, and green infrastructure solutions. Malaysia’s strategic focus on sustainable development creates preconditions for increased adoption of environmentally friendly practices, attracting investments from corporations aiming to reduce their carbon footprint and comply with global environmental standards. Sustainable practices also promote resilience against climate change impacts, thereby creating longer-term market stability.
Development of Green and Resilient Water Infrastructure
The increasing frequency of climate-related events underscores the necessity for resilient water infrastructure capable of withstanding extreme conditions. There are significant opportunities for designing and implementing green infrastructure solutions, such as permeable pavements, green roofs, and rain gardens, that improve urban water management while mitigating flood risks. Investments in climate-resilient infrastructure not only support Government climate commitments but also open avenues for innovative construction materials and techniques tailored for Malaysian ecosystems. Such developments are expected to attract funding from international agencies committed to climate adaptation, thus expanding the market further.
Challenges
Environmental and Regulatory Uncertainties
Despite progressive policies, ongoing environmental challenges and evolving regulations introduce uncertainties in project planning and investment. Regulatory delays or shifts in compliance standards can hinder project timelines and inflate costs. Furthermore, addressing pollution and ensuring water quality amid industrial expansion remains complex, requiring stringent enforcement and continuous updates to standards. Market stakeholders must navigate these uncertainties through adaptive management and active engagement with regulatory authorities to mitigate risks and capitalize on emerging opportunities effectively.
Skilled Workforce Shortages and Technical Gaps
The sector faces a shortage of skilled professionals capable of implementing advanced water technologies and managing complex infrastructure projects. This skills gap hampers efficient project execution, increases dependency on foreign expertise, and limits innovation adoption. Addressing this challenge requires comprehensive capacity-building initiatives, educational programs, and knowledge transfer mechanisms. Ensuring a steady pipeline of qualified personnel is critical for sustaining sector growth and maintaining Malaysia’s competitive edge in water management innovations.
Industry Statistics & Key Business Metrics
The Malaysia Water and Waste Water Market exhibits critical economic importance with robust growth indicators driven by urbanization, industrial expansion, and government infrastructure initiatives. As Malaysia aims to enhance water sustainability, key business metrics reveal insightful trends and opportunities for stakeholders operating within this sector. Analyzing these statistics offers a comprehensive understanding of the market’s current scale and future trajectory.
- In 2026, the market size of Malaysia Water and Waste Water stands at USD 12.5 Billion, underpinning its vital role in national development (Market Research Future).
- The compound annual growth rate (CAGR) of the market from 2026 to 2034 is forecasted at 6.2%, reflecting steady expansion driven by government policies and private sector investments.
- Urban water consumption in Kuala Lumpur reached approximately 1.9 billion cubic meters in 2025, with an annual increase of 3% reflecting urbanization trends (Department of Statistics Malaysia).
- By 2034, the wastewater treatment segment is projected to attain USD 5.2 Billion, indicating a significant focus on sanitation and environmental compliance (National Water Services Commission).
- Over 80% of municipal water sources are from surface waters, with efforts underway to diversify and improve water sourcing reliability (Ministry of Environment and Water).
- Investment in water infrastructure by multinational companies and government projects is estimated to total USD 3 Billion by 2028, highlighting a commitment to sustainable water management (Industry Reports).
- Water access rates in rural Malaysia were at 89% in 2024, demonstrating ongoing improvement in rural water infrastructure services (UNICEF).
- Industrial water demand accounted for 45% of total consumption in 2025, with a projected annual growth rate of 4% through 2034, emphasizing industrial sector contributions (Malaysian Investment Development Authority). These key metrics underscore the Malaysia Water and Waste Water Market's trajectory towards increased capacity, technological adoption, and strategic investments, essential for supporting Malaysia’s sustainable development goals and ensuring water security across the nation.
Market Segmentation
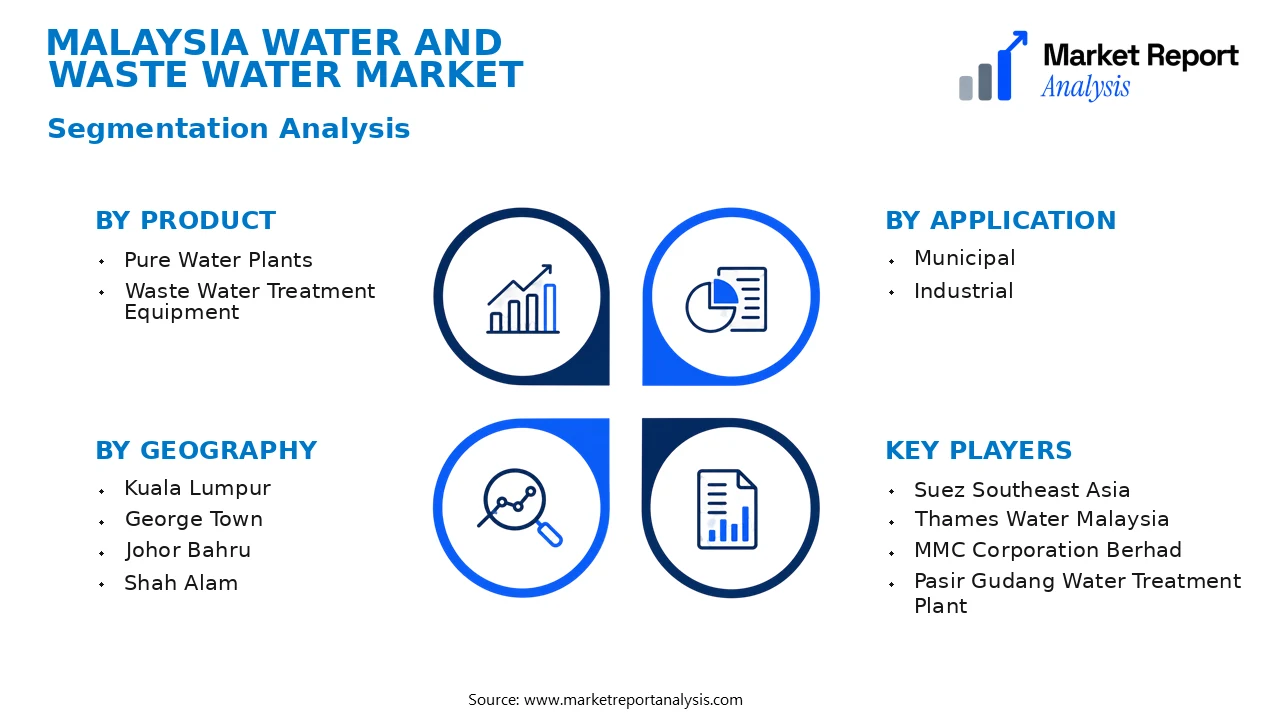
The Malaysia Water and Waste Water Market is segmented based on product, application, end user, industry vertical, and geographic regions within Malaysia. These categories enable a detailed analysis of market dynamics, demand drivers, and growth opportunities across different sectors and locations.
- Product
- Pure Water Plants: Facilities specifically designed for the production of pure water used in pharmaceutical, electronic, and food processing industries. The demand for high-quality water drives the growth of this segment.
- Waste Water Treatment Equipment: Technologies and machinery used to treat industrial and domestic wastewater, essential for compliance with environmental regulations and sustainable water management practices.
- Application
- Municipal: Water treatment and wastewater management services for urban populations, focusing on municipal water supply systems and sewage treatment plants to ensure public health and environmental protection.
- Industrial: Water use and waste management in manufacturing, petrochemical, and other industrial processes, which require specialized treatment solutions to handle effluents and meet compliance standards.
- End User
- Municipalities: Government entities responsible for urban water supply, sewage collection, and treatment infrastructure, often investing heavily in upgrading aging networks and expanding capacity.
- Private Sector: Industries, commercial establishments, and residential developers that deploy water treatment solutions for operational needs and regulatory adherence.
- Industry Vertical
- Food & Beverage: Highly dependent on pure water supply quality, this vertical invests significantly in water treatment systems to ensure product safety and regulatory compliance.
- Textile & Manufacturing: Requires extensive wastewater treatment solutions to manage dye effluents and chemical waste, fostering strong demand for advanced treatment technologies.
- Geography
- Kuala Lumpur: Malaysia’s capital with dense urban infrastructure, high water demand, and significant investments in water quality improvement projects.
- George Town: A vital commercial hub with growing industrial activity, necessitating advanced water and wastewater treatment solutions to support urbanization.
- Johor Bahru: A rapidly expanding city driven by manufacturing and cross-border trade, with increasing demand for modern water management infrastructure.
- Shah Alam: An industrial and residential city experiencing infrastructural upgrades, boosting the need for comprehensive water and wastewater treatment systems.
- Petaling Jaya: A key suburban area with mixed commercial and residential zones, contributing to steady water treatment infrastructure development.
- Ipoh: An emerging industrial city with ongoing investments in water infrastructure to support local industries and urban populations.
- Kota Kinabalu: A coastal city with tourism and fisheries sectors that require efficient water management and wastewater disposal solutions to sustain growth.
Competitive Intelligence
The Malaysia Water and Waste Water Market exhibits moderate competition with a few dominant players, primarily state-backed and large regional companies that hold significant market concentration. Major corporations such as AIR Selangor, Pengurusan Air Selangor, and Malakoff Corporation are leading the sector through strategic alliances, acquisitions, and expansion initiatives. These companies focus heavily on technological innovation, investing in R&D to develop advanced treatment processes and smarter, IoT-enabled infrastructure that enhance operational efficiency and water quality. Partnerships with international firms have been instrumental in bringing advanced water treatment technologies to Malaysia, especially in urban centers like Kuala Lumpur and Penang, driving differentiation by offering customized solutions suited to local needs. Several firms have adopted aggressive expansion strategies, venturing into underserved rural areas and increasing capacity to meet rising demand. Continuous R&D investments are directed toward sustainable practices, including water reuse and pollution control, to maintain competitive advantage and meet regulatory standards. Overall, the competitive landscape emphasizes innovation, strategic collaborations, and capacity expansion to reinforce market position across Malaysia's diverse urban and rural markets.
Leading Company Profiles
The Malaysian water and wastewater market is characterized by a mix of local giants, international corporations, and innovative technology providers that drive growth through strategic investment and technological advancement.
- Suez Southeast Asia
- Thames Water Malaysia
- MMC Corporation Berhad
- Pasir Gudang Water Treatment Plant
- Sapura Energy Berhad
- YTL Corporation Berhad
- Puncak Niaga Holdings Berhad
- SAAG Africa (Malaysia operations)
- Mueller Water Products
- Aquatech Malaysia
Suez Southeast Asia
A key player leveraging innovative water treatment technologies and digital solutions to optimize water management and wastewater treatment for urban and industrial clients across Malaysia.
Thames Water Malaysia
Focused on expanding its infrastructure capacity and implementing sustainable water solutions, Thames Water Malaysia emphasizes operational efficiency and environmental sustainability to meet rising demand.
MMC Corporation Berhad
A diversified Malaysian firm involved in water utilities, transport, and energy, with significant investments in water treatment plants and infrastructure modernizations aligned with national sustainability goals.
Pasir Gudang Water Treatment Plant
A major municipal facility utilizing advanced membrane filtration technologies, playing a pivotal role in supplying clean water to the Johor region while continuously upgrading its processes.
Sapura Energy Berhad
Expanding its footprint through strategic investments in water infrastructure projects, including desalination and wastewater treatment facilities, to support Malaysia's growing industrial and urban needs.
YTL Corporation Berhad
A leading conglomerate with extensive water treatment holdings; innovating through digital transformation and sustainable practices to optimize resource management and meet regulatory standards.
Puncak Niaga Holdings Berhad
Specializes in water utilities, pipeline infrastructure, and sewage treatment, focusing on capacity expansion projects to support Malaysia’s urbanization and development goals.
SAAG Africa (Malaysia operations)
Provides comprehensive water management solutions, including wastewater treatment and reuse technologies, emphasizing sustainability and environmental compliance within Malaysia’s industrial sectors.
Mueller Water Products
Offers corrosion-resistant piping, valves, and water infrastructure products, expanding its presence through localized manufacturing and strategic partnerships in Malaysia.
Aquatech Malaysia
Specializes in modular, scalable water treatment systems designed for industrial use, focusing on innovative solutions that reduce energy consumption and enhance treatment efficacy.
Strategic Business Developments
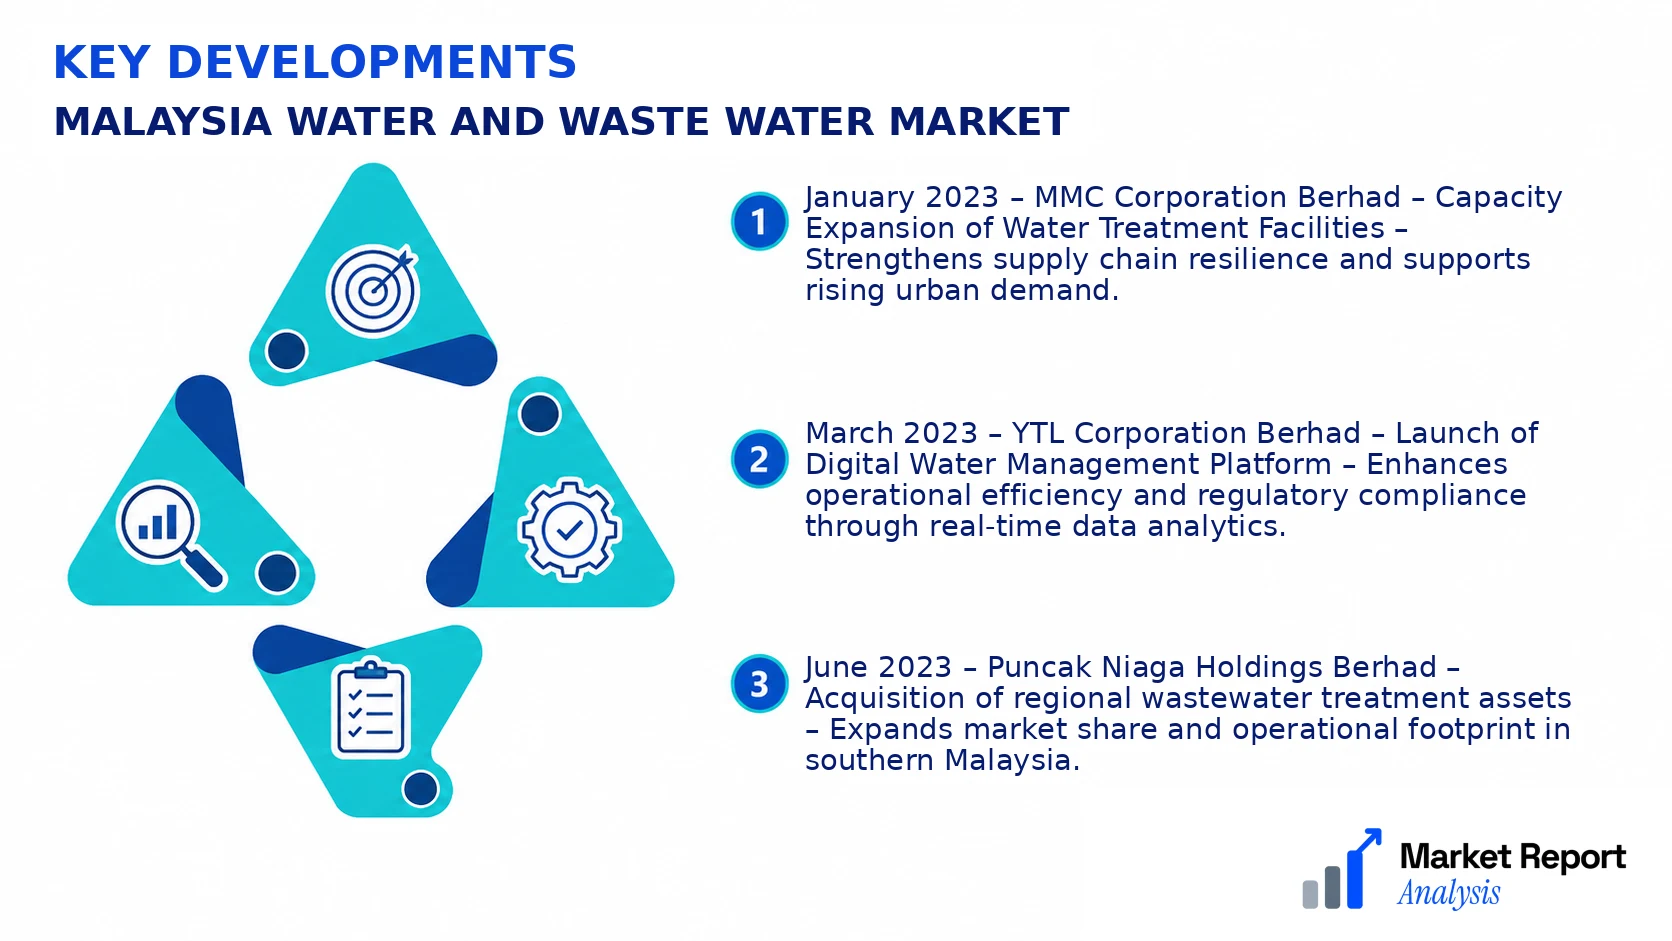
- January 2023 – MMC Corporation Berhad – Capacity Expansion of Water Treatment Facilities – Strengthens supply chain resilience and supports rising urban demand.
- March 2023 – YTL Corporation Berhad – Launch of Digital Water Management Platform – Enhances operational efficiency and regulatory compliance through real-time data analytics.
- June 2023 – Puncak Niaga Holdings Berhad – Acquisition of regional wastewater treatment assets – Expands market share and operational footprint in southern Malaysia.
- August 2023 – Suez Southeast Asia – Partnership with local government for smart water infrastructure project – Promotes sustainable urban water management solutions and technology transfer.
- November 2023 – Mueller Water Products – New manufacturing plant inauguration in Malaysia – Increases local production capacity for critical piping and valve infrastructure.
Frequently Asked Questions
What is the Malaysia Water and Waste Water Market?
The Malaysia Water and Waste Water Market encompasses the infrastructure, equipment, and services related to water supply and wastewater treatment in Malaysia. It plays a vital role in ensuring sustainable water management and sanitation across the country, driven by urbanization and environmental policies.
What is the current market size of Malaysia Water and Waste Water Market?
As of 2026, the market size is valued at approximately USD 7.4 Billion, reflecting ongoing investments in water infrastructure, policy reforms, and technological upgrades aimed at enhancing water quality and supply efficiency across Malaysia.
What factors are driving the Malaysia Water and Waste Water Market?
Key drivers include rapid urbanization, government initiatives on sustainable water management, increasing population, and stringent environmental regulations. Additionally, technological advancements in water treatment and rising awareness about water conservation bolster market growth.
Which region dominates the Malaysia Water and Waste Water Market?
Selangor is the dominant region, primarily due to its dense population and industrial activities, which demand extensive water treatment and distribution facilities. The region’s proactive government policy and infrastructural investments further contribute to its leadership.
Which segment is expected to grow the fastest?
The industrial wastewater treatment segment is forecasted to grow the fastest, driven by Malaysia’s expanding manufacturing sectors, environmental compliance requirements, and adoption of advanced treatment technologies to meet stricter discharge standards.
Who are the leading companies operating in the Malaysia Water and Waste Water Market?
Major players include Syarikat Air Malaysia Berhad (Syarikat Air), Water Infrastructure Group, and Veolia Water Technologies. These companies focus on water supply management, wastewater treatment solutions, and infrastructure modernization to support market expansion.
Analyst Perspective
The Malaysia Water and Waste Water Market is poised for sustained growth driven by increasing urbanization, industrial expansion, and evolving regulatory frameworks that emphasize water sustainability. Long-term market prospects are favorable, with technological innovations such as smart water management systems and advanced treatment processes being critical for enhancing efficiency and compliance. Investment priorities should focus on upgrading aging infrastructure in major cities like Kuala Lumpur, Penang, and Johor Bahru, where demand pressures are most acute. Competition is expected to intensify as both local and international players vie for regional projects, emphasizing cost-effectiveness and technological differentiation. Opportunities abound at the city level, especially in decentralized treatment solutions for smaller municipalities and industrial zones. Regional growth potential remains robust in less developed areas, where infrastructure investments are ramping up to meet rising water needs. Strategic positioning within this evolving landscape will require a focus on sustainable practices, technological adoption, and targeted geographic expansion.
