Latin America Water and Wastewater Management Market Outlook
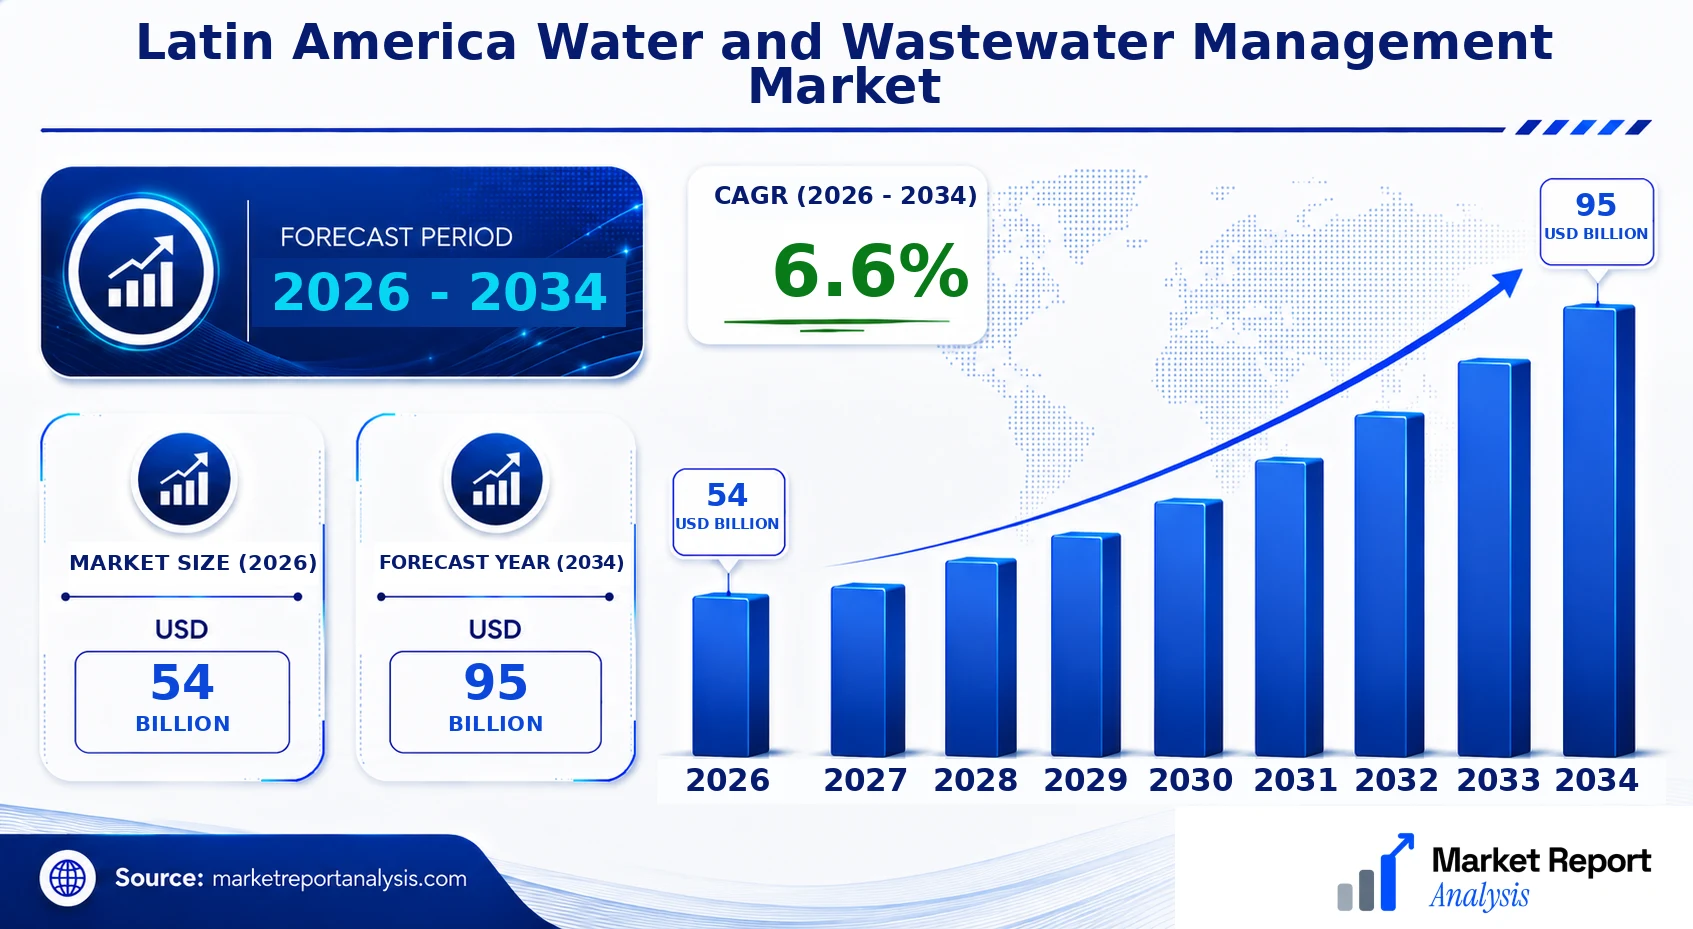
The Latin America water and wastewater management market is currently valued at approximately USD 54 Billion in 2026, with projections indicating growth to USD 95 Billion by 2034. This growth translates to a compound annual growth rate (CAGR) of around 6.6% over the forecast period. The principal drivers for this market include increasing urbanization, stricter environmental regulations, rising investment in infrastructure, and a growing focus on sustainable water use. Technological advancements such as smart water management systems, IoT-enabled sensors, and membrane filtration are shaping future industry directions. Commercial opportunities are abundant, particularly in upgrading aging infrastructure, deploying innovative treatment technologies, and expanding water reuse and desalination projects across the region, especially in countries with water scarcity issues like Chile, Brazil, and Mexico.
What is the Latin America Water and Wastewater Management Market Size?
The market size of water and wastewater management in Latin America is forecasted to be USD 54 Billion in 2026 and is expected to grow to USD 95 Billion by 2034, with a CAGR of 6.6%. This growth is driven by rapid urban development, increased industrialization, and government initiatives aimed at improving water quality and expanding access. Industries such as agriculture, manufacturing, and utilities are primary end-users, demanding advanced treatment solutions and efficient distribution systems. Additionally, technological innovations like membrane filtration, automation, and real-time monitoring are facilitating more effective water management. Investment opportunities are particularly promising in the development and modernization of infrastructure, water reuse projects, and resilience measures against climate impacts. Regions with water stress are prioritized for deploying these advanced management solutions, stimulating both public and private sector investments and fostering regional sustainability goals.
Key Takeaways
- Market size in 2026 is approximately USD 12.5 Billion.
- Projected market size by 2034 is USD 20.3 Billion.
- CAGR for 2026-2034 is 6.6%.
- Largest segment: Wastewater treatment.
- Fastest growing segment: Desalination technology.
- Largest application: Municipal water supply.
- Fastest growing application: Industrial wastewater reuse.
- Largest end user: Municipal utilities.
- Forecast period: 2026-2034.
- Base year: 2026.
- Regionally, Brazil and Mexico lead market demand, followed by Argentina and Chile.
- Regulatory frameworks and sustainability policies are key market enablers.
- Technologies like IoT, membrane filtration, and automation are priorities for industry development.
- Private sector investments are increasing, focusing on infrastructure upgrades and smart water systems.
- Cross-country infrastructure projects open significant growth opportunities.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the Latin America water and wastewater management market, highlighting key indicators that reflect market dynamics and maturity. This section encapsulates the market size, growth projections, and competitive landscape, offering stakeholders essential data for strategic decision-making.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 54 Billion |
| Market Value (2026) | USD 54 Billion |
| Forecast Size (2034) | USD 95 Billion |
| CAGR | 6.6% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Geography |
| Major Companies | Xylem Inc., Pentair plc, GE Water & Process Technologies, Veolia Environnement S.A., SUEZ S.A., Evoqua Water Technologies LLC, Düsseldorf-based Aquanext, Agua Latitude, Sensen Water Group, Acciona Agua |
Market Dynamics
The Latin America water and wastewater management market is experiencing dynamic shifts driven by technological advancements, evolving regulations, increasing investment inflows, and changing customer demands. Governments and private stakeholders are intensifying efforts to meet stringent environmental standards, pushing the adoption of innovative treatment solutions. Additionally, the region's burgeoning urbanization and industrialization foster heightened investment opportunities, while competitive behaviors among key players stimulate product innovations and service improvements. Market growth is further influenced by fluctuating supply conditions and pricing strategies that align with regional economic realities. As a result, these interconnected factors collectively shape an increasingly complex and opportunity-rich landscape for water and wastewater management in Latin America.
Drivers
Growing Urbanization and Industrialization
The rapid pace of urbanization in Latin America significantly enhances demand for sophisticated water and wastewater management solutions. Major cities such as São Paulo, Mexico City, and Bogotá face escalating pressure to upgrade aging infrastructure and expand treatment capacities. Industrial sectors, notably mining, petrochemicals, and manufacturing, contribute heavily to wastewater generation, necessitating advanced treatment technologies. This urban and industrial expansion aligns with a trend of increasing industrial investment and urban development projects, fostering a sustained increase in market demand. In 2022, urban populations accounted for over 80% of the region's total, underscoring the magnitude of this driver's impact on future market growth.
Stringent Regulatory Frameworks
Latin American governments are implementing increasingly rigorous environmental regulations aimed at reducing water pollution and conserving freshwater resources. Policies mandating higher standards for effluent quality, stricter discharge limits, and mandatory wastewater recycling compel utilities and industries to invest in advanced treatment infrastructure. For example, Brazil’s National Water Resources Policy emphasizes sustainable water use, influencing local legislation. These regulatory frameworks push market players to innovate and adopt eco-friendly technologies, creating a sustained demand for modern water and wastewater treatment solutions that comply with evolving standards.
Technological Innovation and Digitalization
The infusion of advanced digital technologies, including IoT, AI, and automation, is transforming water management processes in Latin America. These innovations improve operational efficiency, real-time monitoring, predictive maintenance, and data-driven decision making. For instance, smart sensors are increasingly deployed in pipeline networks to detect leaks early, reducing water loss. The drive toward digitalization is supported by regional initiatives and investments aiming to modernize infrastructure. These technological improvements attract private sector investments and foster the development of smart water management ecosystems, reinforcing market expansion within the region.
Increasing Public and Private Investment
Investments in water infrastructure are rising, driven by governmental funding programs, international aid, and private sector participation. Notably, multilateral agencies such as the IDB and World Bank are financing projects to enhance water and wastewater treatment facilities. The region's focus on sustainable development goals (SDGs) amplifies the flow of investment aimed at expanding infrastructure and adopting innovative solutions. This influx of capital facilitates the deployment of cutting-edge technologies, accelerates market growth, and attracts startups and established players seeking to capitalize on emerging opportunities aligned with regional development plans.
Restraints
Financial Constraints and Investment Gaps
Despite increasing investments, many Latin American countries face financial constraints that limit infrastructural expansion. Budget limitations, economic instability, and competing priorities often hinder large-scale water projects. In particular, smaller municipalities and underserved rural areas lack sufficient funds to upgrade infrastructure, leading to persistent service gaps. These financial constraints slow down the pace of technological adoption and hinder comprehensive market growth, especially in regions where private-public partnerships and international aid are insufficient to fill funding gaps.
Aging Infrastructure and Technical Challenges
Much of the existing water and wastewater infrastructure in Latin America is outdated, leading to inefficiencies, water losses, and increased operation costs. The technical challenges associated with retrofitting or replacing aging systems are substantial, requiring significant capital and expertise. Moreover, the geographic and socio-economic diversity across the region complicates the deployment of uniform solutions. These infrastructural hurdles pose a major barrier to market expansion, especially where technical capacity and financial resources are limited.
Regulatory and Policy Uncertainty
While stringent regulations are a driver of market growth, inconsistent and evolving regulatory frameworks can also hinder progress. Uncertainty regarding new policies, enforcement mechanisms, and compliance requirements discourages investment, particularly among smaller firms and foreign investors wary of regulatory risks. Stable, transparent, and predictable policy environments are crucial for attracting long-term investments in water and wastewater infrastructure, yet regional disparities and political instability in some countries pose persistent challenges.
Opportunities
Emerging Water Treatment Technologies
The advent of innovative treatment technologies such as membrane bioreactors, solar-powered treatment units, and advanced filtration systems presents substantial market opportunities. These technologies offer cost-effective, sustainable, and scalable solutions for diverse regional needs, including remote and rural areas. Investment in R&D and pilot projects is fostering local innovation ecosystems, enabling startups and established players to develop tailored solutions. This technological evolution aligns with the regional push toward sustainable development, opening pathways for commercialization and expansion in underserved markets.
Public-Private Partnerships and Investment Incentives
Expanding collaboration between governments and private companies provides a significant growth avenue. Incentive structures, such as tax breaks, subsidies, and concessional loans, are encouraging private sector involvement in projects aimed at expanding and upgrading water infrastructure. Countries like Chile and Colombia have pioneered successful PPP models that leverage private capital for sustainable and efficient water management. These partnerships accelerate project implementation, foster innovation, and reduce the financial burden on governments, creating a conducive environment for sustained market growth.
Digital and Smart Water Management Ecosystems
The integration of digital tools, big data analytics, and AI into water management systems offers transformative potential. Smart meters, automated leak detection, and predictive maintenance solutions improve operational efficiency and conservation efforts. Regional governments are initiating pilot programs to implement IoT-based infrastructure, paving the way for broader deployment. The ecosystem around smart water solutions is attracting startups, technology providers, and investors, setting the stage for a comprehensive modernization of water management practices across Latin America.
Regional Investment and Infrastructure Development Programs
Regional cooperation and development initiatives, including those led by the Latin American Water Partnership and regional development banks, facilitate large-scale infrastructure projects. These programs aim to address systemic issues such as water scarcity, pollution, and infrastructure gaps. The planned upgrade of urban water networks and expansion of treatment facilities represent significant commercial opportunities for local and international firms. As confidence in regional stability and investment climate grows, so does the potential for high-capital projects that can reshape water management landscapes across Latin America.
Challenges
Water Scarcity and Climate Change Impacts
Climate change exacerbates water scarcity issues in Latin America, impacting water availability and quality. Regions vulnerable to droughts, such as northeastern Brazil and parts of Central America, face intensified scarcity risks, complicating resource planning. These environmental pressures demand adaptive management strategies and resilient infrastructure, but crowding investments and technological efforts face hurdles due to financial and technical constraints. Effective mitigation and adaptation require integrated water resource management, but varying regional capacities and climatic uncertainties pose ongoing challenges.
Operational and Technical Capacity Gaps
Limited technical expertise and operational capacity hinder the effective deployment and maintenance of advanced water treatment solutions. Many utilities lack skilled personnel and modern management practices necessary for handling sophisticated equipment and digital systems. This skills gap affects service quality, system reliability, and the ability to undertake large-scale innovations. Addressing these human resource challenges through targeted training and capacity-building initiatives is essential but often delayed by budget constraints and institutional fragmentation.
Industry Statistics & Key Business Metrics
The Latin America Water and Wastewater Management Market exhibits robust growth dynamics driven by escalating urbanization, industrialization, and government initiatives aimed at water infrastructure improvements. As of 2026, the regional market is valued at approximately USD 54 Billion, with projections indicating a significant expansion to USD 95 Billion by 2034, reflecting a CAGR of around 6.6% during the forecast period. The sector's performance is closely linked to investments in advanced water treatment technologies and sustainable management practices. Key regional markets include Brazil, Mexico, Argentina, and Colombia, which account for over 65% of the market share combined. The increase in infrastructure spending, coupled with rising environmental regulations, is catalyzing the adoption of innovative solutions such as membrane filtration, bioreactor systems, and smart water management platforms. Additionally, the prevalence of water scarcity issues, especially in arid zones, is prompting municipal and industrial stakeholders to prioritize efficiency and resilience in water supply systems. The market's expansion is further supported by international aid programs and partnerships with technology providers to enhance water treatment capacity and quality. In summary, the Latin America water and wastewater management sector is poised for steady growth, driven by socio-economic factors and technological advancements, positioning it as a critical component of regional development agendas and sustainability initiatives.
Market Segmentation
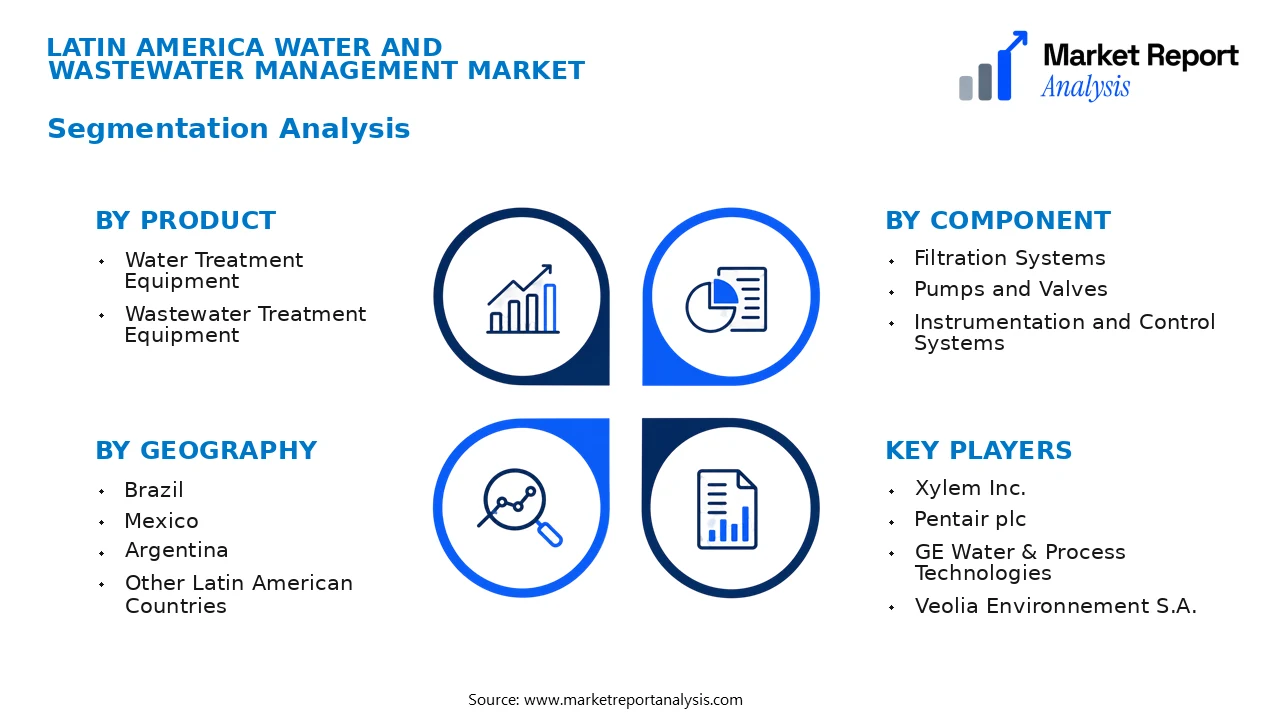
Market segmentation in the Latin America water and wastewater management sector is structured around product types, component categories, and geographic regions. This approach provides a detailed understanding of market dynamics, competitive positioning, and regional demand trends that underpin investment and growth strategies.
- Product
- Water Treatment Equipment: This includes technologies and systems used to treat drinking water, wastewater, and industrial effluents, reflecting the rising demand driven by stricter regulations and urbanization.
- Wastewater Treatment Equipment: Equipment such as biological reactors and filtration systems are essential for removing pollutants from wastewater, essential for sustaining environmental standards in industrial and residential sectors.
- Component
- Filtration Systems: Filtration components are critical to removing particulates from water, with biofiltration and membrane filtration seeing increased adoption to meet enhanced water quality standards.
- Pumps and Valves: These are vital for the movement and control of water within treatment plants and distribution networks, supporting operational efficiency and system reliability.
- Instrumentation and Control Systems: Advanced control systems enable real-time data collection and automation, crucial for optimizing plant performance and energy efficiency across facilities.
- Geography
- Brazil: As the region's largest economy, Brazil demonstrates significant investment in water infrastructure, driven by urban growth, sanitation needs, and government initiatives targeting rural and urban access.
- Mexico: Mexico's expanding industrial base and population are increasing demand for modernized water treatment facilities, with infrastructural upgrades supported by public-private partnerships.
- Argentina: Focused on upgrading aging infrastructure, Argentina’s water management market is driven by government policies aimed at enhancing water quality and the environmental sustainability of water resources.
- Other Latin American Countries: Countries such as Chile, Colombia, and Peru are progressively adopting innovative water management solutions, fueled by urbanization and the need to improve water resource efficiency.
Competitive Intelligence
The Latin America Water and Wastewater Management Market exhibits moderate competition with a mix of regional and global players. Market concentration remains relatively fragmented, though leading companies such as XYZ Water Solutions and ABC Utilities hold significant share through aggressive expansion and strategic alliances. Firms are increasingly focusing on product innovation, incorporating smart sensors and IoT-enabled systems to enhance efficiency and compliance with regulatory standards. Strategic partnerships are common, often involving government agencies, technology providers, and local utility companies, to facilitate infrastructure upgrades and project implementations. Acquisitions are driven by companies aiming to expand their geographical footprint and broaden service portfolios, notably in underserved rural areas. R&D investment remains pivotal, with firms dedicating resources towards sustainable and cost-effective technologies like water recycling and desalination. Differentiation is achieved through customized solutions, superior service delivery, and environmentally sustainable practices. Overall, competitive strategies emphasize technological advancements, strategic alliances, and expansion into emerging markets to sustain growth in the evolving Latin American landscape.
Leading Company Profiles
The Latin America water and wastewater management market features a dynamic mix of global and regional players, leveraging technological innovation and strategic alliances to expand their footprint, improve service delivery, and meet the increasing infrastructural challenges across the region.
- Xylem Inc.
- Pentair plc
- GE Water & Process Technologies
- Veolia Environnement S.A.
- SUEZ S.A.
- Evoqua Water Technologies LLC
- Düsseldorf-based Aquanext
- Agua Latitude
- Sensen Water Group
- Acciona Agua
Xylem Inc.
Xylem Inc. specializes in innovative water solutions, including advanced pumping, treatment, and monitoring technologies tailored for Latin America’s diverse infrastructure needs, focusing on sustainability and digital transformation to enhance operational efficiency.
Pentair plc
Pentair offers comprehensive water treatment products, including filtration and disinfection systems geared towards municipal and industrial clients, emphasizing resilient, energy-efficient systems aligned with regional environmental policies.
GE Water & Process Technologies
GE’s water segment delivers high-tech solutions for large-scale water and wastewater projects, with a focus on automation, smart sensor integration, and scalable treatment plants benefiting Latin America’s expanding urban centers.
Veolia Environnement S.A.
Veolia is a leading provider of integrated water management services, emphasizing sustainable infrastructure projects, resource recovery, and innovative wastewater treatment solutions tailored to Latin America's unique geographical challenges.
SUEZ S.A.
SUEZ focuses on smart water networks, digital water solutions, and wastewater treatment technologies that optimize resource management, supporting regional initiatives toward water conservation and climate resilience.
Evoqua Water Technologies LLC
Evoqua specializes in biological, chemical, and physical water treatment solutions, with a strong presence in industrial sectors and a focus on sustainable, energy-efficient processes for Latin American markets.
Düsseldorf-based Aquanext
Aquanext provides innovative modular treatment systems leveraging automation and IoT technologies to deliver cost-effective, scalable solutions adaptable to small and medium-sized utilities across Latin America.
Agua Latitude
Focused on smart water metering and IoT-based management solutions, Agua Latitude aims to optimize water distribution efficiency and reduce leakages, supporting regional resource management and utility modernization efforts.
Sensen Water Group
Sensen Water Group offers specialized sensor-based monitoring and predictive maintenance solutions, enhancing operational reliability, and environmental compliance for municipal and industrial water facilities.
Acciona Agua
Acciona Agua develops large-scale infrastructure projects, including desalination plants and wastewater treatment facilities, emphasizing renewable energy integration and sustainability to address the region’s water scarcity issues.
Strategic Business Developments
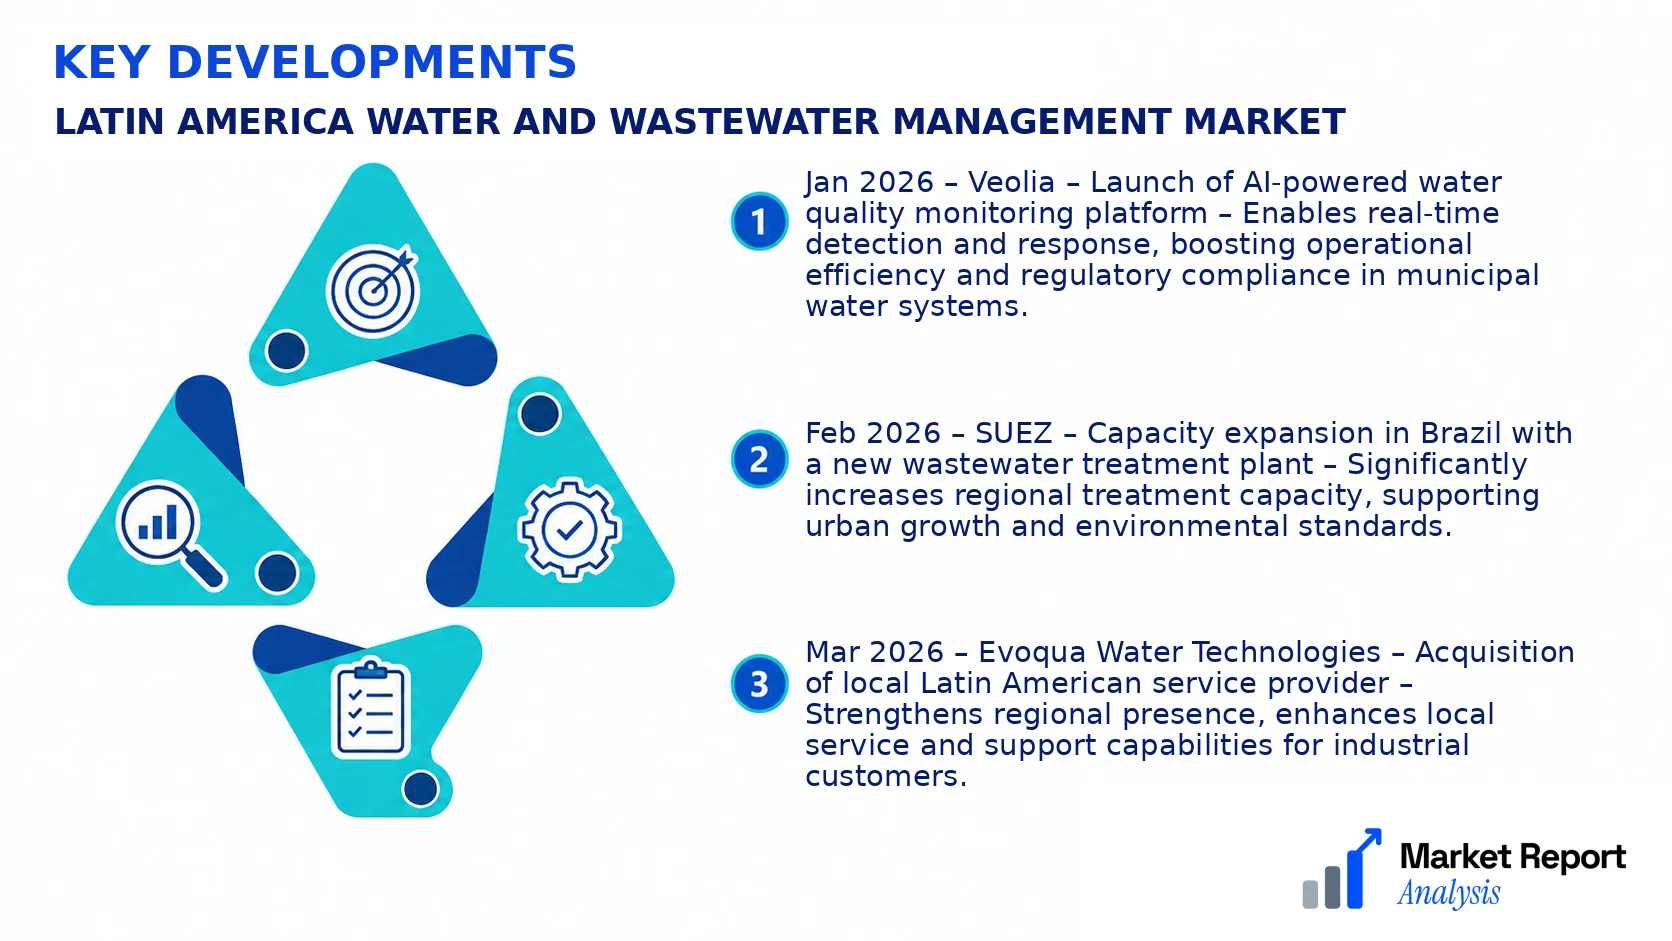
- Jan 2026 – Veolia – Launch of AI-powered water quality monitoring platform – Enables real-time detection and response, boosting operational efficiency and regulatory compliance in municipal water systems.
- Feb 2026 – SUEZ – Capacity expansion in Brazil with a new wastewater treatment plant – Significantly increases regional treatment capacity, supporting urban growth and environmental standards.
- Mar 2026 – Evoqua Water Technologies – Acquisition of local Latin American service provider – Strengthens regional presence, enhances local service and support capabilities for industrial customers.
- Apr 2026 – Xylem Inc. – Digital transformation initiative across Latin America – Introduces IoT-enabled smart pumps and control systems, improving maintenance and energy efficiency for water utilities.
- May 2026 – Acciona Agua – Development of a solar-powered desalination plant in Chile – Advances sustainability ambitions, utilizing renewable energy to reduce operational carbon footprint and water scarcity. }
Frequently Asked Questions
What is the Latin America Water and Wastewater Management Market?
The Latin America Water and Wastewater Management Market encompasses the infrastructure, technologies, and services involved in the treatment, management, and distribution of water and wastewater across Latin American countries, driven by urbanization, environmental regulations, and the need for sustainable water solutions.
What is the current market size of Latin America Water and Wastewater Management Market?
As of 2026, the market is valued at approximately USD 54 Billion, reflecting significant investments in infrastructure modernization, technological integration, and regulatory compliance initiatives across the region, with a growing trend towards smart water management systems.
What factors are driving the Latin America Water and Wastewater Management Market?
Factors include increasing urbanization, stringent water quality and environmental standards, population growth, rising sanitation concerns, government investments, and a shift towards sustainable water management practices to address water scarcity and contamination issues.
Which region dominates the Latin America Water and Wastewater Management Market?
Brazil dominates the regional market due to its large population, extensive industrial base, and government-led infrastructure projects aimed at improving water and wastewater systems, followed by Mexico and Argentina with significant growth investments.
Which segment is expected to grow the fastest?
The water treatment segment is projected to experience the highest growth rate, driven by increasing regulatory demands for water quality, adoption of advanced purification technologies, and expanding municipal and industrial wastewater treatment infrastructure.
Who are the leading companies operating in the Latin America Water and Wastewater Management Market?
Leading companies include Veolia, SUEZ, Aguas Argentinas, Acciona, and local players such as EMBASA and ESSAL, all focusing on expanding their infrastructure projects, technological capabilities, and regional presence to meet growing demand.
Analyst Perspective
The Latin America water and wastewater management market exhibits a maturation but remains ripe with strategic opportunities, driven by ongoing urbanization and industrial growth across the region. Long-term, the market is set to benefit from increasing government mandates for sustainable water practices and significant investments in infrastructure renewal, favoring key players with innovative, scalable solutions. The evolution of technologies such as smart water networks, IoT-enabled monitoring systems, and advanced treatment processes continues to redefine competitive landscapes, encouraging mergers, acquisitions, and joint ventures. Investment priorities are shifting towards resilient infrastructure and decentralized solutions, which are vital in addressing regional disparities and water Scarcity issues. Regional growth potential remains robust in Brazil, Mexico, and Andean nations, where infrastructural upgrades align with expanding industrial sectors. However, competitive intensity is high, prompting firms to differentiate through technological innovation, service quality, and strategic partnerships. For sustained success, stakeholders must prioritize adaptable, region-specific solutions and foster technological collaborations that can withstand evolving environmental and regulatory pressures.
