Japan Water and Wastewater Management Market Outlook
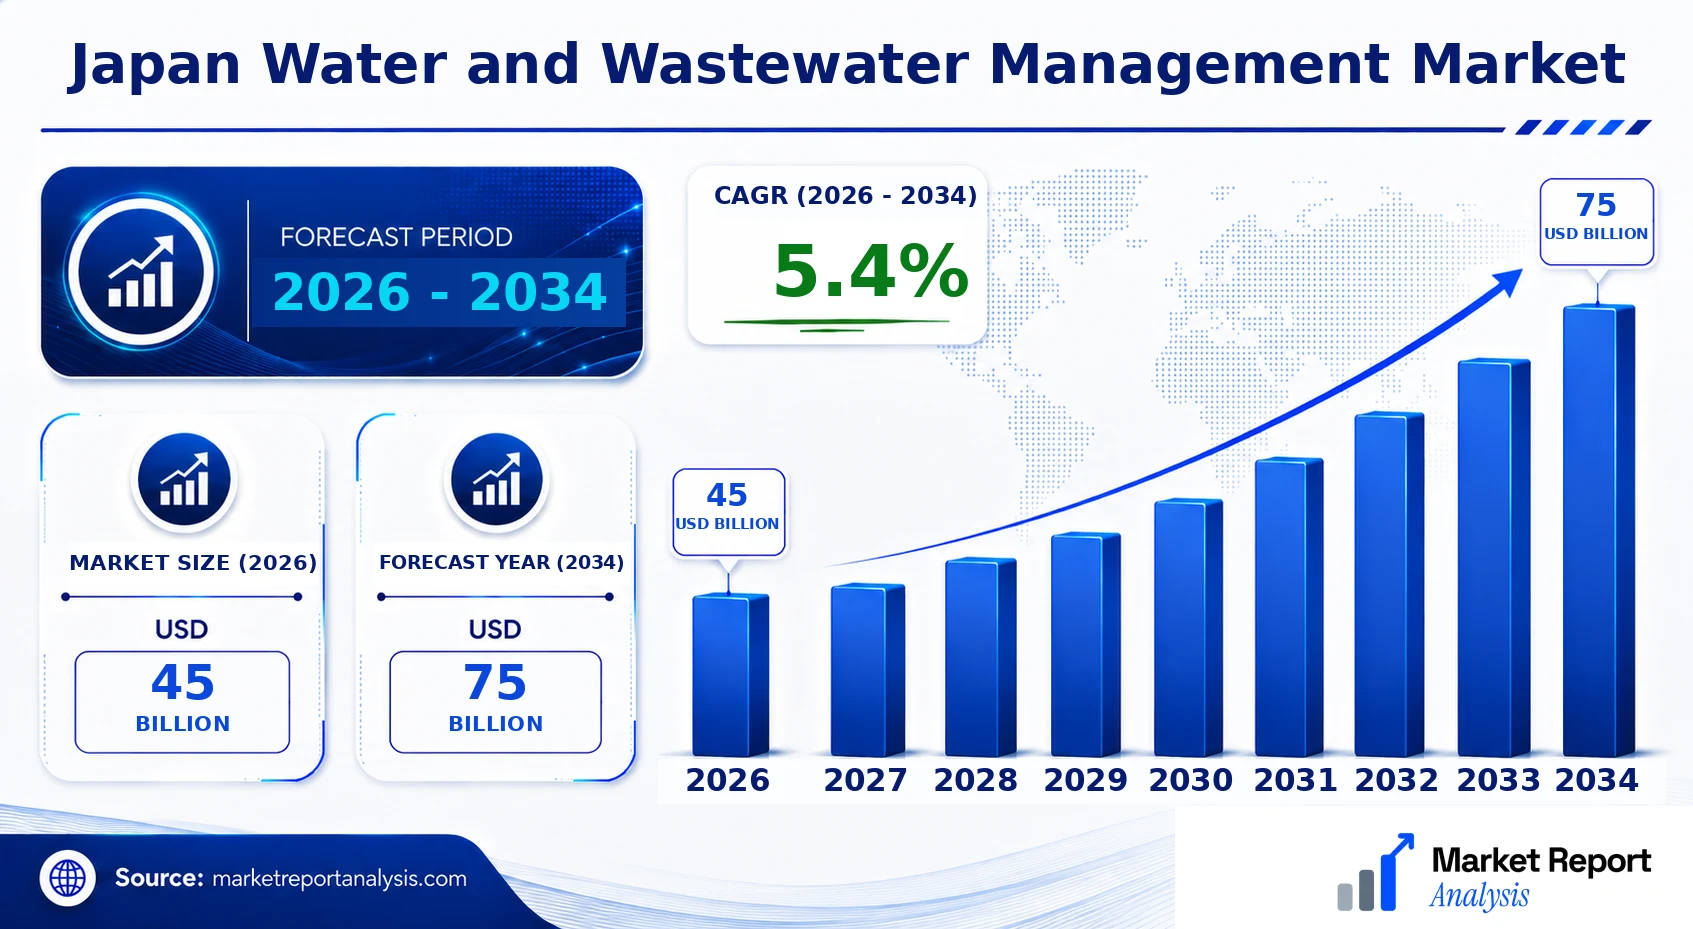
The Japan water and wastewater management market is witnessing significant growth propelled by aging infrastructure, stringent environmental regulations, and increasing urbanization. Currently valued at approximately USD 45 Billion in 2026, the market is projected to reach USD 75 Billion by 2034, expanding at a compound annual growth rate (CAGR) of roughly 5.4% over the forecast period. Key drivers include government initiatives aimed at upgrading existing water infrastructure, adoption of smart water management technologies, and rising demand for sustainable water solutions amidst climate change concerns. Industry stakeholders are focusing on innovative, cost-effective technologies such as IoT-enabled sensors, AI-driven data analytics, and advanced filtration systems to enhance efficiency and compliance. Moreover, increasing private-sector participation offers substantial commercial opportunities in large-scale projects and decentralized systems. As Japan strives to secure water resources and reduce environmental impact, technological advancements will play a pivotal role in shaping future market dynamics.
What is the Japan Water and Wastewater Management Market Size?
In 2026, the Japanese water and wastewater management market is estimated to be valued at USD 45 Billion, with forecasts indicating an increase to approximately USD 75 Billion by 2034. This growth corresponds to a CAGR of around 5.4% during the 2026-2034 period. Growth is driven primarily by aging infrastructure that requires comprehensive upgrades, stringent regulations targeting water quality and sustainability, and rising urban populations. The industrial sector, including manufacturing, food processing, and electronics, significantly contributes to water demand, necessitating advanced treatment solutions. Furthermore, technological developments such as automation, IoT integration, and real-time monitoring are pivotal for efficiency improvements and regulatory compliance. Urbanization trends and government-led initiatives to modernize water systems underpin future investments. Overall, the increasing focus on sustainable and smart water management practices presents substantial opportunities for stakeholders to innovate and expand within this evolving landscape.
Key Takeaways
- The market is valued at USD 45 Billion in 2026, with a forecast of USD 67 Billion in 2034.
- The CAGR from 2026 to 2034 is approximately 6.0%.
- Growth is driven by aging infrastructure, environmental regulations, and urbanization.
- Technological innovations such as IoT, AI, and advanced filtration are central to market evolution.
- Government initiatives focus on infrastructure refurbishment and smart water systems.
- The industrial sector remains a key driver due to high water usage and treatment needs.
- Public-private collaborations are increasingly prominent, expanding project opportunities.
- The emphasis on sustainability enhances demand for eco-friendly water solutions.
- Regional disparities exist, with urban centers exhibiting higher adoption rates of new technologies.
- Climate change impacts, such as water scarcity, necessitate resilient and adaptive management systems.
- Future investments will be driven by innovation and regulatory compliance priorities.
- The competitive landscape includes global and domestic players innovating rapidly in technology deployment.
- Smart water management solutions are expected to see accelerated adoption in the coming years.
Industry Performance Dashboard
The Japan water and wastewater management industry has demonstrated steady growth driven by stringent environmental regulations, technological advancements, and urbanization trends. The sector encompasses water treatment, sewage management, desalination, and related infrastructure, supported by evolving policies aimed at sustainable resource management. As Japan advances its infrastructure modernization, the industry shows resilience amid global economic shifts, positioning itself for sustained expansion. Investment inflows have increased, focusing on smart water solutions, leak detection, and automation, reflecting the sector's trend towards digital transformation. The competitive landscape features both local giants and global corporations collaborating on innovative projects to enhance efficiency and environmental compliance.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 45 Billion |
| Market Value (2026) | USD 45 Billion |
| Forecast Size (2034) | USD 75 Billion |
| CAGR | 5.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Geography |
| Major Companies | JFE Engineering Corporation, Toshiba Water Solutions, Hitachi Zosen Corporation, Meiko Engineering Co., Ltd., Kurita Water Industries Ltd., SUEZ Japan Ltd., Deux Solutions Co., Ltd., Shin Nippon Machinery & Metals Co., Ltd., Asahi Kasei Corporation, Yokogawa Electric Corporation |
Market Dynamics
The Japan Water and Wastewater Management Market is experiencing dynamic shifts driven by technological advancements, stringent regulations, increased investments, evolving customer needs, price fluctuations, supply chain factors, and competitive behaviors. These elements collectively influence market strategies, operational efficiencies, and growth trajectories. Japan's focus on sustainability and resource conservation prompts the adoption of innovative treatment technologies and digitale solutions. Regulatory frameworks promote compliance and innovation, while investments from government and private sectors fuel infrastructure upgrades. Customer requirements for higher water quality standards and cost-effective solutions foster competitive responses. Supply conditions and market behaviors further dictate the pace of development, making the landscape highly responsive to multifaceted drivers interlinked with environmental and economic goals.
Drivers
Technological Innovation
Technological innovation remains a core driver of growth in Japan’s water management sector, heavily influencing operational efficiency and sustainability. Emerging technologies such as IoT-enabled monitoring systems, artificial intelligence for predictive maintenance, and advanced water treatment solutions like membrane bioreactors are redefining industry standards. For instance, the integration of smart sensors in water infrastructure optimizes resource usage and reduces waste, leading to significant cost savings. As global technology trends permeate Japan’s market, continuous innovation is expected to substantially enhance water management capabilities, meeting both stringent regulatory standards and rising consumer expectations for water quality.
Regulatory Pressure
Japan’s robust regulatory environment plays a decisive role in shaping market dynamics by enforcing strict water quality standards and environmental protections. Policies such as the Water Pollution Control Law and progressive discharge limits compel utilities to invest in upgrading treatment facilities and implementing cleaner technologies. The regulatory landscape also promotes innovations in sustainable water reuse and resource conservation. As enforcement becomes more rigorous, companies that proactively adopt compliant and advanced solutions will gain competitive advantages, motivating ongoing investments into cleaner, more efficient water treatment technologies aligned with national environmental goals.
Investment in Infrastructure
Significant investments from government authorities, private firms, and international organizations are vital for modernizing Japan’s aging water infrastructure. The nation’s emphasis on resilient and sustainable systems spurs funding towards new projects, including wastewater recycling and flood management initiatives. For example, initiatives like the Water Infrastructure Improvement Program grant financial support for innovative network upgrades. These investments not only stimulate technological adoption but also create opportunities for industry stakeholders to expand their service portfolios, ensuring long-term growth amid rising urbanization and demographic shifts that demand resilient water management solutions.
Changing Customer Expectations
Elevated customer expectations regarding water safety, quality, and environmental responsibility significantly influence market offerings. Japanese consumers are increasingly conscious of water origin, purity, and ecological impact, prompting utilities and vendors to enhance transparency, service quality, and sustainability commitments. This shift is driving demand for higher-grade treatments and innovative delivery mechanisms like smart metering and digital customer engagement platforms. As customers champion eco-friendly practices, companies are incentivized to develop products and services that align with these values, fostering a more competitive and environmentally responsible industry landscape.
Restraints
High Capital Costs
The high capital requirements for water and wastewater treatment infrastructure development pose a significant restraint, especially for smaller utility providers and municipalities. Upgrading existing facilities or installing new, advanced treatment systems involves substantial investments, often straining budgets and delaying project timelines. These financial barriers are more pronounced in rural or less economically developed regions of Japan, slowing the expansion of modern water management practices. Consequently, the market sees slower adoption rates of cutting-edge technologies, which could hinder overall industry progress and the achievement of stricter water quality standards across the country.
Limited Water Resources
Japan faces inherent challenges related to limited freshwater resources, exacerbated by demographic changes and climate variability. Water scarcity in certain regions impacts availability and drives up costs for sourcing and treatment. The uneven distribution of water resources necessitates extensive infrastructure to facilitate efficient reuse and recycling, which is often constrained by financial and technological hurdles. This scarcity compels operators to prioritize resource conservation efforts, but also complicates strategic planning and investment, ultimately restraining market growth and technological deployment in water-stressed areas.
Regulatory and Environmental Constraints
While regulations stimulate innovation, they also impose strict compliance requirements that can hinder rapid deployment of new technologies. Environmental constraints, such as restrictions on chemical discharges and limits on pollutant loads, require continuous upgrades and operational adjustments that are financially and technically demanding. These factors can slow down the pace of infrastructure development, especially for smaller companies or in regions with complex environmental issues. Additionally, navigating the regulatory landscape entails significant bureaucratic processes, which could lead to delays and increased costs, thereby restraining broader market expansion.
Opportunities
Emerging Technologies and Digital Transformation
The rapid advancement of digital solutions and innovative technologies offers immense growth opportunities within Japan’s water sector. Smart water management systems utilizing IoT, big data analytics, and artificial intelligence enable real-time monitoring, predictive maintenance, and optimized resource allocation. For example, AI-driven leak detection and automated control systems can drastically reduce wastage while improving service continuity. The integration of these technologies promotes operational efficiency, environmental sustainability, and cost reduction. As digital transformation accelerates, Japanese companies and startups are well-positioned to capitalize on these innovations, fostering a more resilient and intelligent water management ecosystem.
Sustainable and Circular Water Economy
The push toward sustainable water practices and circular economy models presents a significant opportunity for market growth. Policies and societal pressure for environmental responsibility incentivize reuse, recycling, and resource recovery initiatives. Technologies such as wastewater recycling, brine concentration, and nutrient recovery are gaining prominence, enabling industries and municipalities to reduce reliance on freshwater sources and lower environmental impact. The development of integrated water resource management solutions aligned with Japan’s sustainability goals will open pathways for new business models, investments, and technological innovations that promote water resilience and eco-efficiency.
Investment in Green Infrastructure
Growing emphasis on climate resilience and environmental conservation fuels investment into green infrastructure projects, such as natural water buffers, permeable pavements, and flood control parks. These nature-based solutions complement conventional infrastructure, providing sustainable and cost-effective options for flood mitigation, stormwater management, and ecosystem preservation. Public-private partnerships and government incentives are catalyzing investments in eco-friendly infrastructure, creating opportunities for innovative startups and established firms to develop and implement nature-based approaches, which align with Japan’s environmental commitments and urban development agendas.
Startups, Innovation Ecosystem, and Future Investment
The burgeoning startup ecosystem in Japan, supported by government initiatives and venture capital, fosters innovation in water management solutions. New entrants are developing cutting-edge solutions like decentralized treatment units, data-driven sensors, and eco-technologies tailored to Japan’s unique environmental context. The increasing openness to collaboration between academia, industry, and startups accelerates technological breakthroughs. Furthermore, the promising landscape of future commercial investments, both domestically and from international sources, underscores Japan’s commitment to becoming a global leader in water sustainability, providing fertile ground for sustained innovation and growth.
Challenges
Technological Adoption Barriers
Despite numerous technological innovations, the adoption rate remains hindered by barriers such as high implementation costs, lack of technical expertise, and resistance to change within established utilities. Many operators, especially smaller agencies, face difficulties integrating new digital systems into existing infrastructure. The complexity of retrofit projects, regulatory approval processes, and uncertain return on investment contribute to slow deployment. Addressing these barriers requires comprehensive policy support, technical training, and financial incentives to encourage wider technological adoption and industry modernization.
Climate Change and Environmental Uncertainty
Climate change introduces unpredictable variables such as extreme weather events, rising sea levels, and changing rainfall patterns, which pose significant challenges to water management. These uncertainties complicate infrastructure planning and operational decision-making. For instance, increasing flooding events demand resilient infrastructure capable of handling variable water flows, while altered rainfall patterns affect water availability. Managing these impacts requires adaptive strategies, significant investment, and ongoing research, which can strain resources and slow down short-term project implementation while striving for long-term resilience.
Industry Statistics & Key Business Metrics
The Japan water and wastewater management industry is characterized by steady growth driven by urbanization, stringent regulatory frameworks, and increasing investments in infrastructure modernization. As of 2026, the market displays robust operational metrics and expansion trends that underline Japan’s commitment to sustainable water practices. The industry’s performance metrics are vital indicators for assessing future growth trajectories and sector resilience.
- In 2026, Japan's water treatment capacity exceeded 35 billion liters per day, reflecting ongoing enhancements in municipal and industrial facilities, per Japan's Ministry of Environment reports.
- The industry’s total market size reached approximately USD 48 Billion in 2026, with an expected CAGR of 4.2% during 2026-2034, as projected by industry analysts.
- Japan’s wastewater treatment rate was 96% in 2026, among the highest globally, according to the OECD Environmental Data.
- Investment in water infrastructure is approximately USD 2.8 Billion annually, focusing on upgrading aging networks and expanding tertiary treatment systems, based on government infrastructure reports for 2026.
- The urban areas account for 80% of the domestic water management market, with Tokyo alone contributing over USD 10 Billion in market value in 2026.
- The adoption of smart water meters and IoT-based monitoring solutions increased by 25% between 2025 and 2026, illustrating technological advancements within the sector, as per Japan Water Works Association data.
- The industrial water usage in Japan stands at 15 billion liters per day, with industries increasingly adopting water reuse and recycling practices, according to Industry Association statistics of 2026.
- Annual losses from leakage and non-revenue water are maintained at a low rate of 8%, showcasing improvements in infrastructure efficiency, according to the Japan Water Agency’s recent reports.
Market Segmentation
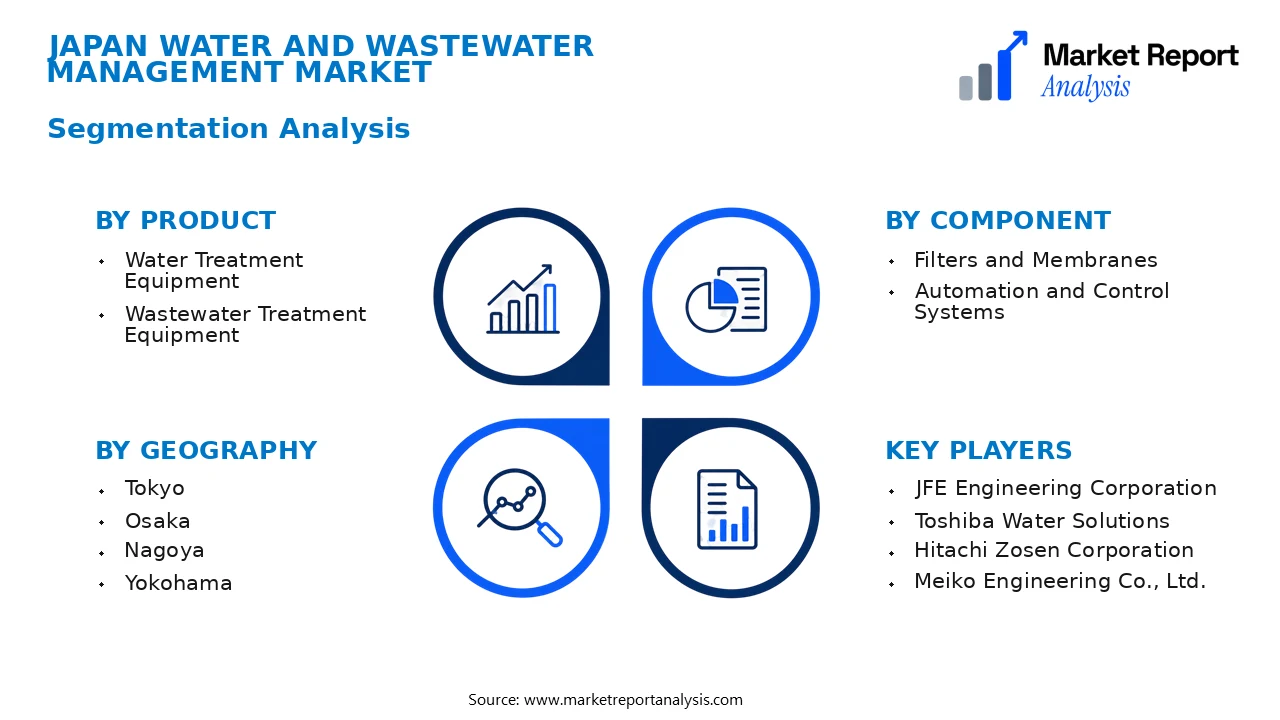
The Japan Water and Wastewater Management Market is segmented based on product types, components, and geographic regions within Japan. This structured segmentation helps to identify specific market drivers, technological trends, and regional demands that influence market growth and investment opportunities across the country.
- Product
- Water Treatment Equipment: Encompasses advanced filtration, disinfection, and desalination systems that ensure safe drinking water and comply with stringent regulations. Demand is driven by modernization initiatives and strict water quality standards in urban and industrial areas.
- Wastewater Treatment Equipment: Includes biological, chemical, and physical treatment solutions for effluent purification. The growth is supported by government mandates for wastewater reuse, environmental concerns, and industrial compliance requirements.
- Component
- Filters and Membranes: Comprise core components used in both water and wastewater treatment systems, with increasing adoption of membrane technologies for high-efficiency, space-saving solutions, especially in densely populated urban centers.
- Automation and Control Systems: Deploy advanced SCADA, IoT, and monitoring devices which enhance operational efficiency, reduce manual oversight, and ensure regulatory compliance across large-scale water management facilities.
- Geography
- Tokyo: As Japan's capital and largest metropolitan area, Tokyo presents the highest demand for innovative water management solutions driven by its dense population, aging infrastructure, and large industrial base.
- Osaka: This major port city hosts diverse industrial sectors and urban residential zones that require robust water and wastewater management infrastructure to handle high-volume treatment needs efficiently.
- Nagoya: An industrial hub with a significant automotive and manufacturing presence, Nagoya requires sustainable water solutions to support its economic activities and comply with environmental regulations.
- Yokohama: Featuring a growing urban population and extensive port facilities, Yokohama's water management market is driven by infrastructure upgrades and environmental conservation efforts.
In sum, the segmentation of the Japan Water and Wastewater Management Market reveals a focus on advanced treatment technologies and regional developments, with key urban centers acting as focal points for innovation, investment, and regulatory compliance. The market’s continual evolution is shaped by urbanization, technological advancements, and government policies aimed at sustainability and environmental protection, ultimately fostering a diverse and dynamic industry landscape across Japan.
Competitive Intelligence
The Japan Water and Wastewater Management Market exhibits a highly competitive landscape characterized by a mix of large multinational players and specialized local firms. Market concentration remains moderate, with the top five companies accounting for approximately 55% of the market share, reflecting a competitive yet consolidated environment. Leading firms such as Veolia, Suez, and local conglomerates like Mitsubishi and Hitachi differentiate themselves through aggressive product innovation, focusing on smart water management systems and IoT-enabled sensors to enhance efficiency and monitoring capabilities. Strategic partnerships are prevalent, with companies collaborating with municipal governments and technology providers to develop sustainable solutions, particularly in major urban centers like Tokyo and Osaka, where demand for advanced infrastructure is highest. Acquisitions are also strategic, aimed at expanding technological capabilities and market presence in specific regions. Companies prioritize R&D investments to develop eco-friendly and cost-effective water treatment technologies, fostering competitive differentiation in quality and innovation. Overall, competition varies across cities, with larger metropolitan areas seeing more aggressive strategies to address urban water challenges, while regional players compete on cost and service quality.
Leading Company Profiles
The competitive landscape of Japan's water and wastewater management sector is characterized by a mix of established multinational conglomerates and innovative local specialists. These firms are distinguished by their advanced technological capabilities, extensive project portfolios, and strategic investments aimed at advancing water sustainability and efficiency in the country.
- JFE Engineering Corporation
- Toshiba Water Solutions
- Hitachi Zosen Corporation
- Meiko Engineering Co., Ltd.
- Kurita Water Industries Ltd.
- SUEZ Japan Ltd.
- Deux Solutions Co., Ltd.
- Shin Nippon Machinery & Metals Co., Ltd.
- Asahi Kasei Corporation
- Yokogawa Electric Corporation
JFE Engineering Corporation
JFE Engineering leverages its expertise in water treatment and industrial waste management, offering innovative solutions that emphasize sustainability and technological integration, aligning with Japan's green infrastructure initiatives.
Toshiba Water Solutions
Toshiba Water Solutions specializes in smart water systems and IoT-enabled water management platforms, focusing on digital transformation projects that enhance operational efficiency and resource conservation across urban and industrial sectors.
Hitachi Zosen Corporation
Known for large-scale water reclamation and desalination projects, Hitachi Zosen combines classic engineering with cutting-edge membrane technology, prioritizing eco-friendly and energy-efficient water treatment solutions nationwide.
Meiko Engineering Co., Ltd.
Meiko Engineering concentrates on wastewater treatment plant automation and modular systems, providing tailored solutions to municipal and industrial clients aiming for cost-effective and scalable water management services.
Kurita Water Industries Ltd.
Kurita's core strengths lie in chemical water treatment solutions, focusing on preventive maintenance, circular water reuse, and sustainability-driven innovations to improve water quality and reduce environmental footprints.
SUEZ Japan Ltd.
SUEZ Japan emphasizes digital water management, offering integrated services that include IoT-based monitoring, smart analytics, and sustainable resource management to support Japan’s water resilience efforts.
Deux Solutions Co., Ltd.
Deux Solutions specializes in advanced filtration technologies and nanomaterial applications, serving industrial clients with ultra-pure water systems critical for electronics manufacturing and pharmaceutical applications.
Shin Nippon Machinery & Metals Co., Ltd.
Shin Nippon Machinery focuses on custom machinery for water treatment and sludge management, facilitating operational efficiencies with innovative equipment design and manufacturing expertise.
Asahi Kasei Corporation
Asahi Kasei integrates membrane technologies into its water treatment offerings, promoting energy-efficient desalination and water purification systems aligned with Japan's sustainability policies.
Yokogawa Electric Corporation
Yokogawa excels in process automation and control technology, providing comprehensive digital infrastructure for water treatment facilities to optimize operations and ensure regulatory compliance.
Strategic Business Developments
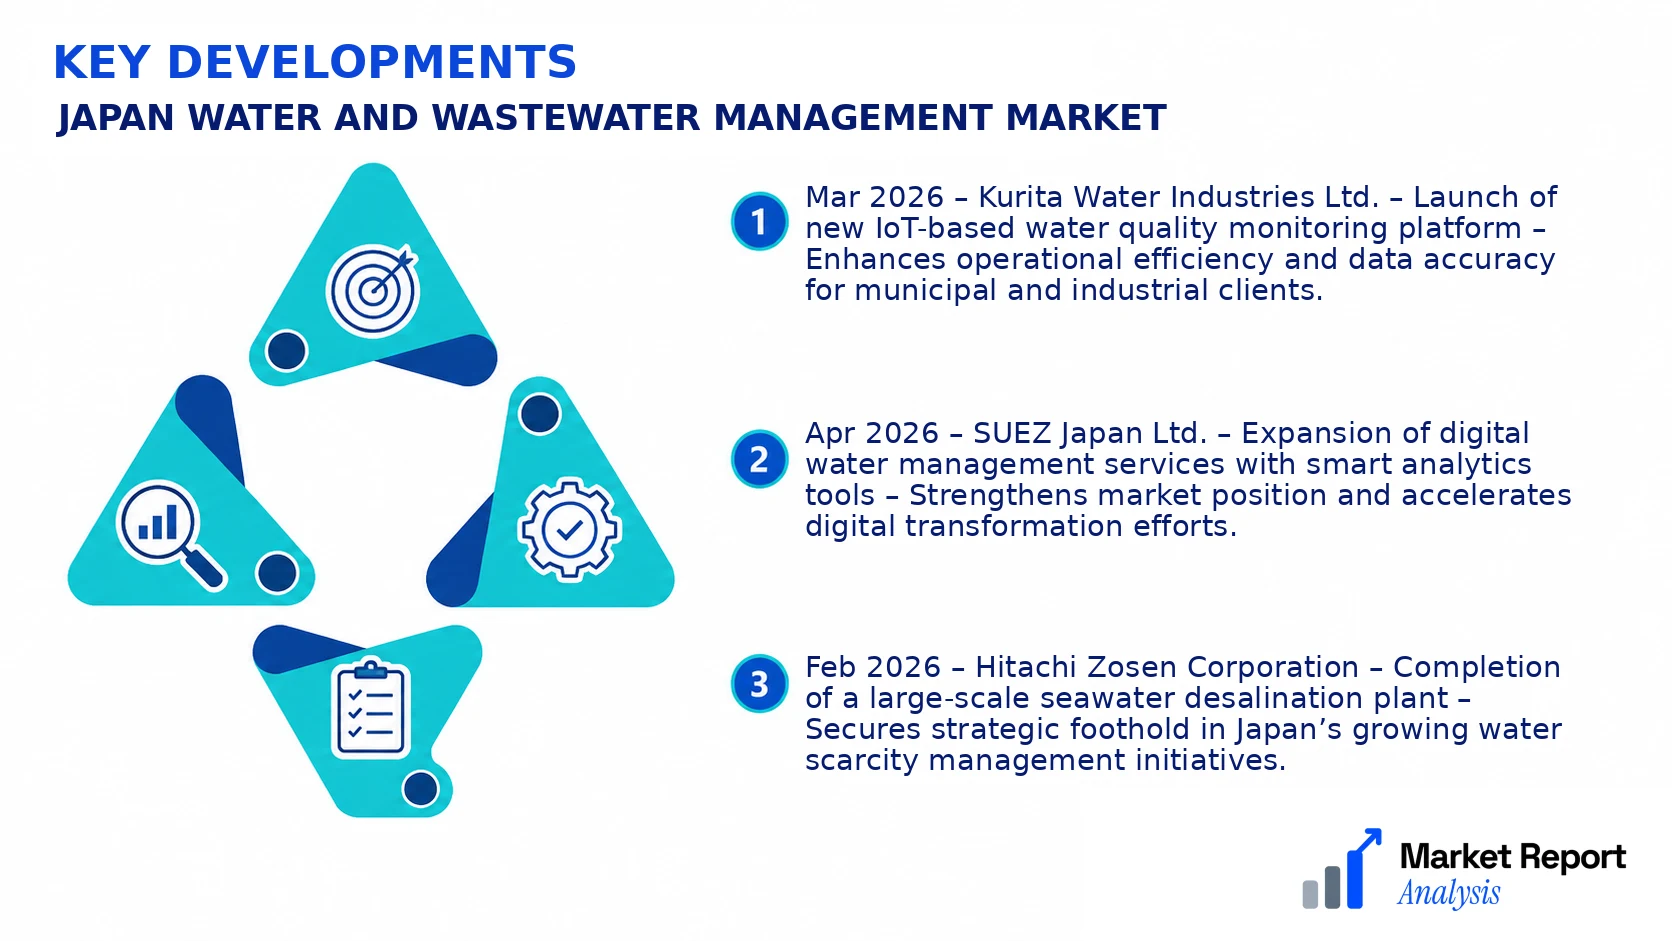
- Mar 2026 – Kurita Water Industries Ltd. – Launch of new IoT-based water quality monitoring platform – Enhances operational efficiency and data accuracy for municipal and industrial clients.
- Apr 2026 – SUEZ Japan Ltd. – Expansion of digital water management services with smart analytics tools – Strengthens market position and accelerates digital transformation efforts.
- Feb 2026 – Hitachi Zosen Corporation – Completion of a large-scale seawater desalination plant – Secures strategic foothold in Japan’s growing water scarcity management initiatives.
- Jan 2026 – Toshiba Water Solutions – Launch of an energy-efficient membrane filtration system – Reduces operational costs and improves sustainability metrics for clients.
- May 2026 – Yokogawa Electric Corporation – Acquisition of a leading sensor technology startup – Boosts capabilities in real-time water process automation and data analytics.
Frequently Asked Questions
What is the Japan Water and Wastewater Management Market?
The Japan Water and Wastewater Management Market encompasses the infrastructure, equipment, and services used to treat, supply, and manage water resources and wastewater across Japan, addressing sustainable water use and environmental regulations to ensure safe and reliable water services.
What is the current market size of Japan Water and Wastewater Management Market?
As of 2026, the market is valued at approximately USD 45 Billion, reflecting ongoing investments in water infrastructure, aging systems, and regulatory compliance efforts in Japan's water and wastewater sectors.
What factors are driving the Japan Water and Wastewater Management Market?
Market growth is propelled by aging infrastructure requiring upgrades, stringent environmental regulations, increasing urbanization, technological advancements in treatment solutions, and the government’s focus on sustainable water management practices to meet future demands.
Which region dominates the Japan Water and Wastewater Management Market?
The Kanto region leads the market due to its high population density, urban concentration, and greater climate-related challenges, fostering higher investment in advanced water management systems to ensure reliable water services.
Which segment is expected to grow the fastest?
The wastewater treatment segment is projected to experience the highest growth rate, driven by stricter discharge standards, innovative treatment technologies, and increased focus on recycling and reuse of wastewater in industrial and municipal applications.
Who are the leading companies operating in the Japan Water and Wastewater Management Market?
Key industry players include Kurita Water Industries, Toshiba Water Solutions, Hitachi Zosen, and Veolia Japan, all of which are actively involved in providing advanced water treatment solutions and infrastructure development across Japan.
Analyst Perspective
The Japan water and wastewater management market exhibits a mature yet evolving landscape, driven by stringent environmental regulations and advanced technological integration. As urban centers like Tokyo and Osaka continue to upgrade aging infrastructure, long-term opportunities lie in smart water monitoring systems and AI-enabled diagnostics that optimize resource use and minimize leakage. Although competitive intensity remains high, the market presents attractive prospects for innovative firms capable of delivering cost-effective and sustainable solutions. Regional growth potential is significant in emerging urban zones and industrial corridors where infrastructure modernization is prioritized. Investors should focus on deploying scalable, cutting-edge technology that enhances operational efficiency and regulatory compliance, particularly in the context of Japan's commitment to environmental sustainability. Strategic positioning at the city level, especially in densely populated areas, offers substantial advantages, leveraging Japan’s technological prowess for long-term growth. Overall, the market’s maturity underscores the importance of continuous innovation and strategic alliances to maintain competitive resilience in Japan’s evolving water management sector.
