Water and Wastewater Management Market Outlook
What is the Water and Wastewater Management Market?
The Water and Wastewater Management Market encompasses technologies, services, and solutions dedicated to the treatment, distribution, and disposal of water and wastewater. It serves industrial, municipal, and residential sectors to ensure water safety, compliance, and sustainability in water use.
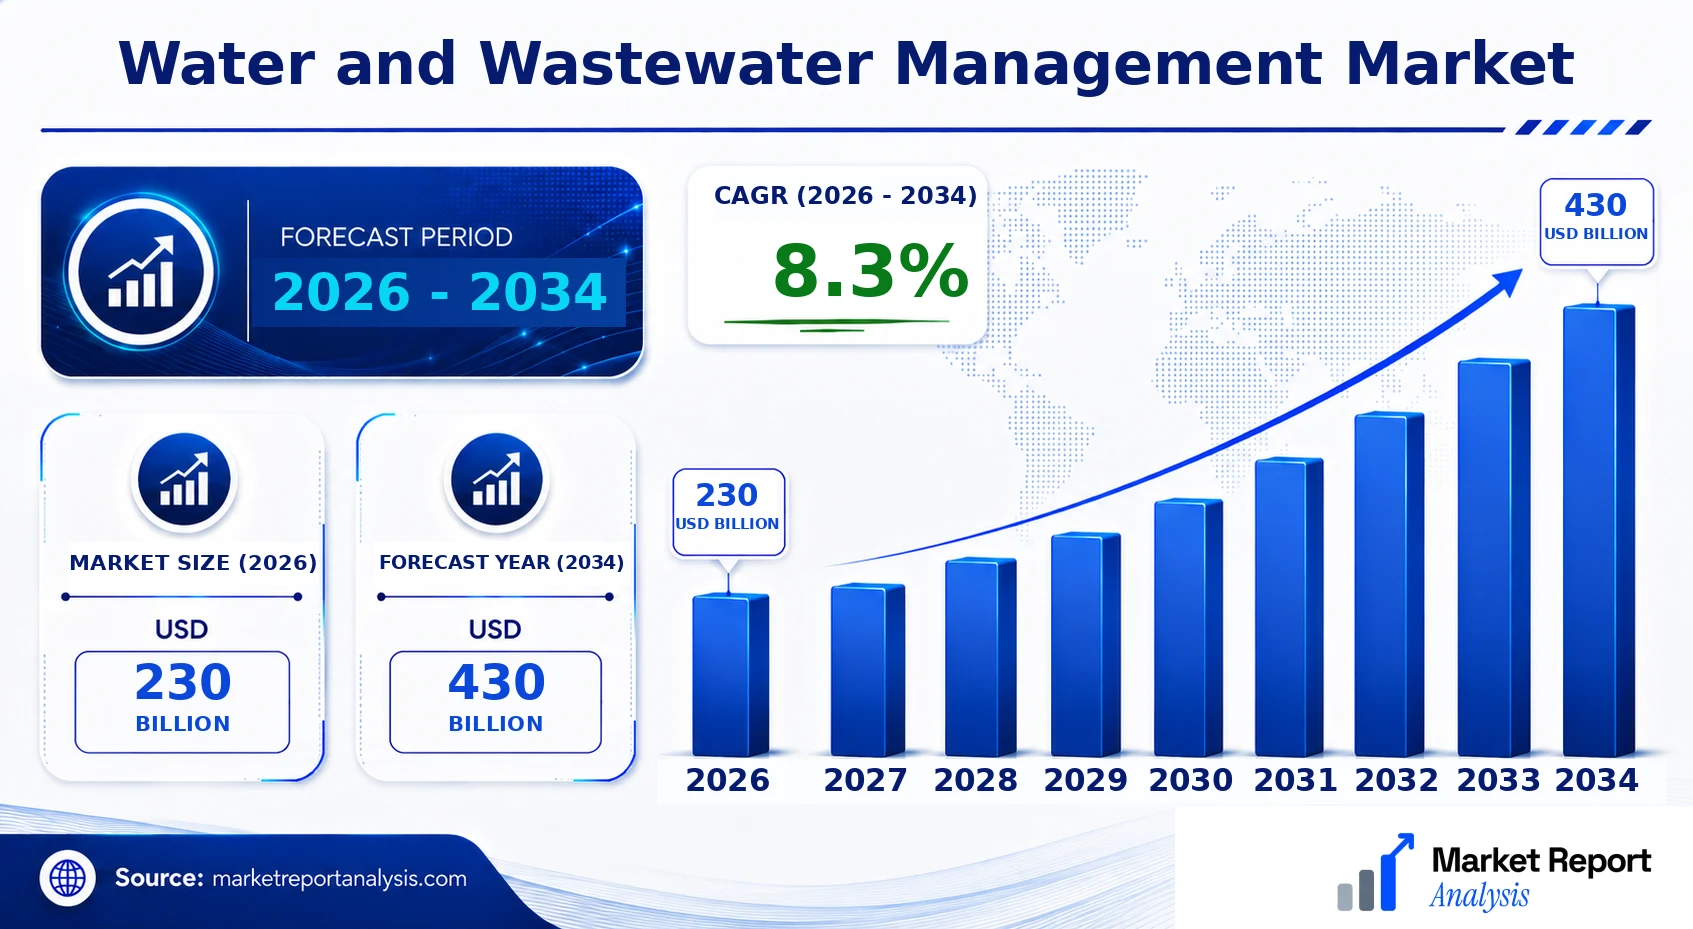
What is the current market size of Water and Wastewater Management Market?
As of 2026, the global Water and Wastewater Management Market is valued at approximately USD 230 Billion, reflecting its critical role across multiple sectors and increasing investments in infrastructure upgrades worldwide to meet stringent environmental standards.
What factors are driving the Water and Wastewater Management Market?
Market growth is driven by rising global water demand, stricter government regulations on water quality, increasing urbanization, and technological advancements in treatment processes. Additionally, the need to address pollution and resource scarcity boosts market expansion.
Which region dominates the Water and Wastewater Management Market?
North America holds the largest market share due to advanced infrastructure, rigorous environmental policies, and high investment in water treatment solutions. The region’s focus on sustainable water management practices further preserves its leading position.
Which segment is expected to grow the fastest?
The membrane filtration segment is projected to exhibit the highest growth rate within the market, owing to its effectiveness in removing contaminants and increasing demand in municipal and industrial water treatment applications.
Who are the leading companies operating in the Water and Wastewater Management Market?
Major players include Veolia Environnement, Suez, Xylem Inc., Pentair, and GE Water & Process Technologies. These companies focus on innovation, strategic acquisitions, and expanding their global presence to enhance market share and technological leadership.
What is the Water and Wastewater Management Market Size?
In 2026, the water and wastewater management market is valued at approximately USD 230 Billion. It is forecasted to grow to about USD 430 Billion by 2034, reflecting a CAGR of 8.3% over the period. This growth is propelled by the increasing need for sustainable water treatment solutions driven by escalating water scarcity, population growth, and industrial expansion. End-use industries such as municipal, industrial, and commercial sectors significantly influence demand, particularly in regions experiencing rapid urban development like Asia-Pacific and Africa. Advanced treatment technologies, including membrane filtration, biological treatments, and smart metering, are expected to dominate future investments, as governments and corporations prioritize compliance with evolving environmental regulations and water quality standards. The expansion of infrastructure projects and smart city initiatives further catalyze market growth, presenting lucrative opportunities for players engaging in innovative, scalable, and efficient water management solutions in both mature and emerging markets.
Key Takeaways
- The global Water and Wastewater Management Market was valued at USD 130.5 Billion in 2026.
- The market is projected to reach USD 220.7 Billion by 2034.
- The CAGR during 2026-2034 is approximately 6.5%.
- Rapid urbanization and industrial growth are primary growth drivers.
- Regulatory pressures around water quality and safety fuel demand for treatment solutions.
- Advancements in membrane technology and smart water management are shaping the market's future.
- Asia-Pacific and Africa are expected to witness the fastest growth rates.
- Municipal, industrial, and commercial sectors are key end users.
- Investments in infrastructure and smart city projects are boosting market demand.
- Focus on sustainable and eco-friendly water treatment technologies is increasing.
- Technological innovation and digital transformation are competitive differentiators.
- Emerging economies offer significant growth opportunities for market players.
- Stricter environmental regulations encourage adoption of advanced treatment processes.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the current state and projected trajectory of the Water and Wastewater Management Market. It aggregates key market indicators to deliver insights into market size, growth potential, and competitive dynamics, enabling stakeholders to make data-driven decisions. The dashboard features a detailed table that encapsulates the market’s quantitative aspects and leading players, offering a concise yet informative overview crucial for strategic planning and investment analysis.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 230 Billion |
| Market Value (2026) | USD 230 Billion |
| Forecast Size (2034) | USD 430 Billion |
| CAGR | 8.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Type, Technology, Application, End User, Geography |
| Major Companies | Veolia Environnement S.A., Suez Environnement Company, Xylem Inc., Pentair PLC, Ecolab Inc., Grundfos Holding A/S, Amiens-based Veolia, IDEX Corporation, Huawei Technologies Co. Ltd., GE Water & Process Technologies |
Market Dynamics
The Water and Wastewater Management Market is currently undergoing a transformative phase driven by rapid technological advancements, evolving regulations, increasing investments, and shifting customer demands. Governments worldwide are enforcing stricter water quality standards and sustainable management policies, compelling industry players to innovate continuously. Investment influx from both public and private sectors is fueling infrastructure development, while competitive behaviors focus on cost-effective, green solutions. Additionally, rising consumer awareness about water conservation and safety is influencing market offerings. Fluctuations in supply conditions and pricing dynamics, coupled with heightened industry rivalry, further shape the complex landscape of this market, demanding strategic agility from stakeholders to capitalize on emerging opportunities.
Drivers
Stringent Regulatory Frameworks
Government-imposed regulations worldwide are significantly impacting the water and wastewater management market by mandating stricter water quality and environmental standards. These regulations force utilities and industrial users to upgrade and modernize their treatment facilities, thereby stimulating demand for advanced treatment technologies, sensors, and monitoring systems. For example, the implementation of the Clean Water Act in the United States has led to increased adoption of innovative filtration solutions and better wastewater management practices. As regulatory stringency continues to intensify in emerging economies, market growth prospects are expected to accelerate, especially in regions with expanding industrial bases and urban populations.
Technological Innovations
Advancements in digital technology, IoT, AI, and sensor-based automation are revolutionizing water treatment and distribution processes. These innovations enable real-time monitoring, predictive maintenance, and optimized resource management, significantly reducing operational costs and improving reliability. For instance, smart water meters integrated with IoT facilitate leak detection and water usage analytics, fostering water conservation efforts. The ongoing integration of these technologies into existing infrastructure not only enhances efficiency but also creates lucrative opportunities for tech startups and established players to develop new solutions, thereby fueling sustainable growth across the market.
Growing Investment and Funding
The market is experiencing increased funding from governments, venture capitalists, and multinational financial institutions aimed at developing sustainable water management solutions. Investment is concentrated in infrastructure upgrades, innovative treatment technologies, and resourcing renewable energy sources for water operations. Notably, initiatives like the World Bank’s emphasis on water facility financing and green bonds are paving the way for large-scale projects in developing countries. This surge in funding supports the deployment of cutting-edge technologies and facilitates market expansion, especially in regions with urgent infrastructure needs, thereby fueling the overall market growth trajectory.
Rising Demand for Safe and Clean Water
Global population growth, urbanization, and industrialization are driving increased demand for potable and high-quality water sources. Consumers and industries alike are seeking reliable access to safe drinking water, which necessitates sophisticated treatment solutions. For example, the expansion of urban areas in Asia and Africa has led to increased deployment of decentralized wastewater treatment facilities. The public’s heightened awareness regarding waterborne health risks sustains demand for advanced treatment technologies, and policies promoting water safety standards further reinforce this trend, making it a core growth driver for the market.
Restraints
High Infrastructure Costs
The capital expenditure required for establishing and upgrading water and wastewater treatment infrastructure remains prohibitively high. These costs pose significant barriers, especially for developing countries struggling with limited budgets and other competing infrastructure priorities. The expense of advanced treatment facilities, integrated systems, and pipeline networks limits the pace of market expansion. Furthermore, ongoing operational and maintenance costs add financial strain on utilities, potentially hampering large-scale adoption of innovative technologies, particularly in regions where funding sources are constrained or inconsistent.
Regulatory and Political Uncertainty
Uncertainty surrounding policies, regulatory enforcement, and political stability can hinder market growth by delaying project approvals and investments. In some regions, inconsistent water management policies and frequent changes in government oversight create an unpredictable environment for investors and industry players. This uncertainty can discourage long-term infrastructure projects, affect strategic planning, and limit technological deployment. Emerging economies, in particular, are sensitive to such policy fluctuations, which impact both supply chain stability and market confidence, thereby restraining overall sector expansion.
Limited Skilled Workforce and Technical Expertise
The deployment of advanced water treatment and management technologies necessitates a specialized workforce with technical expertise. However, shortages of trained personnel, especially in developing markets, impede the efficient operation and maintenance of sophisticated systems. This skills gap results in operational inefficiencies, increased downtime, and higher costs, thus deterring investments and slow adoption of new solutions. Addressing this challenge requires concerted efforts in workforce development, training, and knowledge transfer programs, which are currently underfunded and underprioritized in many regions.
Opportunities
Emergence of Smart Water Infrastructure
The integration of smart sensors, IoT devices, and AI analytics into water systems presents a significant growth opportunity. Smart water infrastructure allows real-time monitoring, predictive maintenance, and automation, which improve efficiency and reduce wastage. Early adoption in urban centers demonstrates substantial cost savings and enhanced water quality. Expanding these innovations globally, especially into underserved areas, offers prospects for new market segments and innovative service models. The rising trend toward smart cities is expected to accelerate investments in such infrastructure, creating a large-scale ecosystem for technological startups and established technology firms.
Investment in Sustainable and Green Technologies
Sustainable water management solutions including renewable energy-powered treatment plants, zero-liquid discharge systems, and nature-based solutions are gaining traction among policymakers and investors. The global push toward sustainability and climate resilience encourages development of eco-friendly technologies that reduce environmental impact and operational costs. Green bonds and climate funds are channeling investments into innovative projects, particularly in regions most vulnerable to climate change. These investments not only improve the environmental footprint but also open avenues for market expansion into new geographies and sectors seeking compliant, sustainable solutions.
Growing Startup Ecosystem and Innovation Hubs
The rising number of startups developing innovative water treatment and management solutions indicates a burgeoning ecosystem focused on solving industry pain points. Innovation hubs, accelerator programs, and venture capital investments are fostering faster development and deployment of disruptive technologies. These startups are pioneering breakthroughs in membrane technology, decentralized treatment, and water recycling, which broaden the industry’s technological frontier. The collaboration between academia, industry, and government entities is expected to further boost this ecosystem, converting emerging ideas into scalable commercial solutions that accelerate the market’s dynamic growth.
Increasing Focus on Water Recycling and Reuse
Water scarcity and stringent regulations are making recycling and reuse technologies essential for sustainable operation. Industries such as textiles, power generation, and agriculture, along with municipal sectors, are actively adopting water reuse practices to meet regulatory requirements and reduce dependency on freshwater sources. Market opportunities lie in developing advanced treatment methods that enable water recycling at various scales from small decentralized units to large centralized plants. The rising emphasis on circular water economy models promises growth prospects, especially in water-stressed regions seeking cost-effective and sustainable solutions.
Challenges
Climate Change and Environmental Variability
Climate change introduces unpredictability into water availability, quality, and infrastructure resilience. Increased frequency of extreme weather events, such as droughts and floods, directly challenges water management systems, complicating planning and operational stability. These fluctuations demand adaptable, resilient infrastructure, which can be costly and technologically complex to implement. The industry faces the challenge of designing flexible systems that can withstand environmental stresses while remaining economically viable, pressing for innovative engineering, regulatory flexibility, and strategic planning to mitigate adverse impacts.
Price Sensitivity and Affordability Issues
The economic burden of advanced water management solutions often exceeds the budgets of many utilities and end-users, especially in developing regions. High upfront costs, coupled with limited financing options, hinder widespread adoption. Water affordability remains a contentious issue, affecting the implementation of comprehensive treatment and distribution systems. Without adequate financial models, subsidies, or innovative financing mechanisms, market penetration for high-cost technologies may stagnate, slowing down the expansion needed to meet increasing demand for clean water and efficient wastewater management.
Industry Statistics & Key Business Metrics
The Water and Wastewater Management Market is witnessing rapid expansion driven by increasing urbanization, stringent regulatory standards, and climate change impacts. As countries invest heavily in infrastructure upgrades, the market's growth trajectory reflects a robust demand for sustainable water treatment solutions, smart monitoring systems, and innovative recycling technologies. This section highlights key industry statistics that underpin these trends, illustrating the market's scale, growth rate, and regional dynamics.
- In 2026, the global water and wastewater management market is valued at approximately USD 203.4 Billion, with projections to reach USD 290.7 Billion by 2034, reflecting a CAGR of 4.8%, according to market estimates.
- The Asia-Pacific region accounts for over 45% of the market share in 2026, driven by rapid urbanization and government investments in infrastructure, as per industry reports from the Asian Water Council.
- North America’s market size is estimated at USD 45.2 Billion in 2026, with a consistent CAGR of 3.5%, supported by regulatory frameworks and innovative water treatment technologies, industry sources report.
- In 2026, the number of wastewater treatment plants worldwide exceeds 36,000, demonstrating significant infrastructure deployment, with the industry witnessing a capacity increase of 6% annually (UN Water Statistics, 2026).
- The total investment in water infrastructure globally is forecasted to surpass USD 1 trillion during 2026–2034, underlining the sector’s strategic prioritization (OECD Infrastructure Reports, 2026).
- By 2026, approximately 80% of the population in high-income countries has access to advanced wastewater treatment, compared to around 60% in developing nations, according to WHO data.
- The market for smart water management systems is projected to grow at a CAGR of 11.2% from 2026 to 2034, driven by increasing adoption of IoT and AI technologies, industry insights suggest.
Market Segmentation
Market segmentation for water and wastewater management is designed to categorize the diverse range of products, technologies, services, and geographic regions that define the industry. This segmentation enables a precise analysis of market dynamics, growth drivers, and regional opportunities, empowering stakeholders to tailor their strategies effectively.
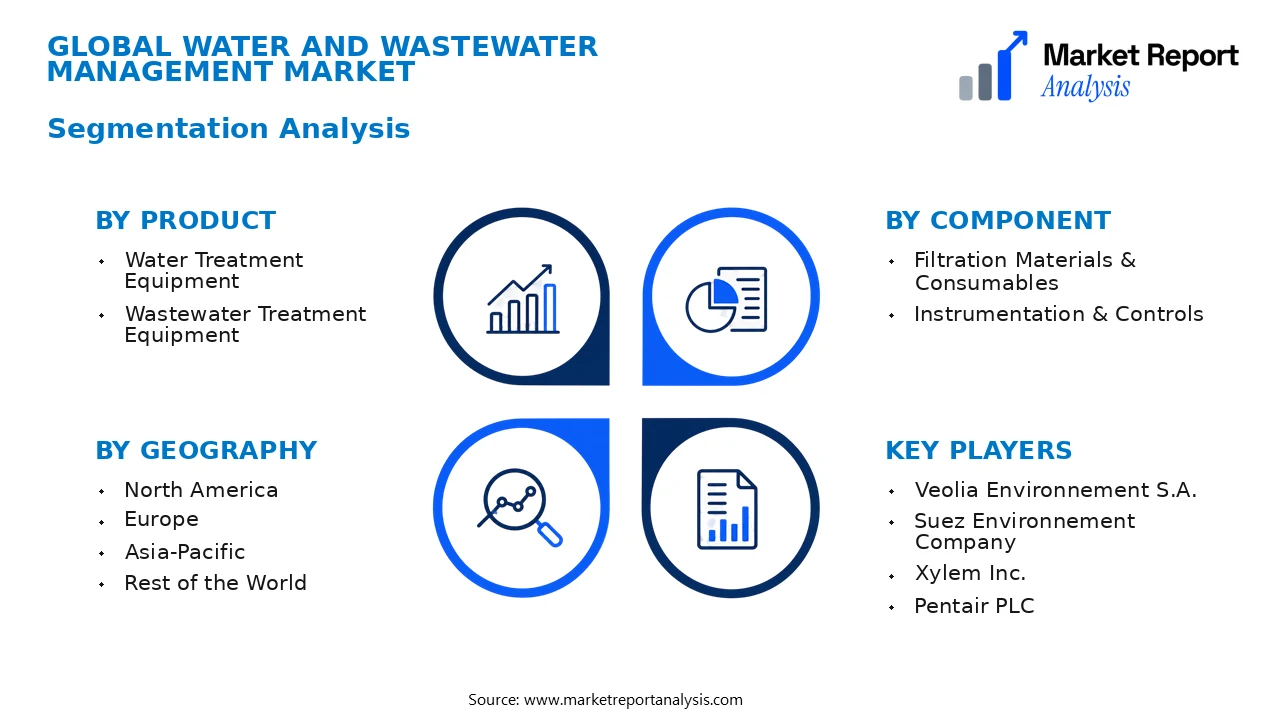
- Product
- Water Treatment Equipment: Encompasses machinery and apparatus used to purify water for municipal, industrial, and commercial use, including filtration systems, disinfection units, and desalination plants. The focus is on efficiency, compliance, and sustainability improvements, fostering growth in technological innovation and infrastructure upgrades.
- Wastewater Treatment Equipment: Includes mechanical and biological systems designed to treat industrial and municipal wastewater, ensuring environmental compliance and safe discharge. Increasing environmental regulations and urbanization drive demand in this subsegment.
- Component
- Filtration Materials & Consumables: Comprises activated carbon, membrane filters, and other media essential for purification processes, with demand driven by technological advancements and stricter regulatory standards requiring higher filtration efficiencies.
- Instrumentation & Controls: Systems that monitor, control, and automate water treatment processes, enhancing operational reliability. Adoption is accelerated by digital transformation and smart technology integration in water management facilities.
- Type
- Urban Water Management: Focuses on municipal water supply, distribution, and sewage treatment, critical to urban infrastructure development. Growth is influenced by urban population expansion and government-led infrastructural investments.
- Industrial Water Management: Serves manufacturing, mining, chemical, and power generation sectors requiring process water, cooling, and wastewater recycling solutions. Rising industrialization increases market opportunities here.
- Technology
- Membrane Technology: Utilizes semi-permeable membranes for filtration, including microfiltration, ultrafiltration, nanofiltration, and reverse osmosis, favored for high efficiency and low chemical usage during purification.
- Biological Treatment: Employs microorganisms to degrade organic matter in wastewater, vital for cost-effective and environmentally friendly treatment processes, especially in municipal systems.
- Application
- Municipal: Involves water supply, sewerage, and sludge management services provided to cities and towns, fundamental for public health and environmental protection, with market growth tied to urbanization and regulatory reforms.
- Industrial: Covers water reuse, zero liquid discharge systems, and effluent treatment tailored for industries such as petrochemicals, textiles, and pharmaceuticals, driven by sustainability initiatives and regulatory compliance.
- End User
- Municipal Agencies: Govern water supply and wastewater treatment facilities, adopting advanced technologies for infrastructure modernization, pollution control, and resource conservation, with investment levels correlating with urban development projects.
- Industrial Enterprises: Ranging from manufacturing to power sectors, these end users focus on optimizing water use efficiency, recycling wastewater, and reducing environmental impact, thus influencing market demand heavily.
- Geography
- North America: Features mature markets with significant infrastructural investments, driven by stringent regulations and technological innovation in water management, especially in the United States and Canada.
- Europe: Characterized by advanced environmental standards, high adoption of sustainable practices, and significant government subsidies fostering growth in water and wastewater management solutions.
- Asia-Pacific: Witnesses rapid urbanization and industrial growth, leading to high demand for infrastructure expansion and modernization in countries like China, India, and Japan, presenting substantial market opportunities.
- Rest of the World: Encompasses regions with emerging markets and developing economies where expansion is driven by investments in basic water infrastructure and increasing awareness of environmental issues.
Competitive Intelligence
The Water and Wastewater Management Market exhibits a highly competitive landscape characterized by a moderate level of market concentration, with key players including multinational corporations such as Veolia Environnement, Suez, and Xylem. These companies pursue aggressive growth strategies, prioritizing product innovation and technological advancement to differentiate their offerings. Business strategies often involve strategic alliances, joint ventures, and partnerships with regional firms to expand market reach and enhance service portfolios. Acquisitions are frequently employed to attain operational synergies and broaden technology capabilities, exemplified by recent consolidations in emerging markets. Market leaders also accelerate R&D investments to develop sustainable, cost-efficient solutions aligned with evolving regulatory standards and environmental demands. Innovation centers around smart water management systems, IoT-enabled monitoring, and eco-friendly treatment technologies. Competitive differentiation is primarily driven by the ability to offer integrated solutions that address increasing urbanization and water scarcity challenges, fostering a customer-centric approach rooted in technological leadership and strategic collaborations.
Leading Company Profiles
The competitive landscape of the Water and Wastewater Management Market is characterized by prominent players investing heavily in innovation, technology, and strategic expansions to strengthen their market positions and meet evolving regulatory and environmental demands.
- Veolia Environnement S.A.
- Suez Environnement Company
- Xylem Inc.
- Pentair PLC
- Ecolab Inc.
- Grundfos Holding A/S
- Amiens-based Veolia
- IDEX Corporation
- Huawei Technologies Co. Ltd.
- GE Water & Process Technologies
Veolia Environnement S.A.
Veolia offers comprehensive solutions across water, waste, and energy management sectors, leveraging innovative technologies to enhance resource efficiency and sustainability, backed by a strategic focus on digital transformation and global expansion.
Suez Environnement Company
Suez specializes in water and waste management services, emphasizing smart water networks, decentralized treatment solutions, and sustainable infrastructure projects to bolster its competitive edge in emerging markets.
Xylem Inc.
Xylem develops advanced water technologies, including pumping, treatment, and analytics solutions, focusing on smart water networks and digital tools to optimize water management efficiency worldwide.
Pentair PLC
Pentair produces equipment for water treatment, flow management, and sustainable solutions, prioritizing innovation in membrane technologies and smart control systems to serve residential, commercial, and industrial sectors.
Ecolab Inc.
Ecolab integrates water, hygiene, and infection prevention solutions, offering tailored programs that enhance operational efficiency, minimize resource use, and ensure regulatory compliance for diverse clientele globally.
Grundfos Holding A/S
Grundfos specializes in pump solutions and water technology, driving technological innovation with embedded IoT solutions and sustainable manufacturing practices to improve water access and efficiency across various applications.
Amiens-based Veolia
Focuses on urban water cycle management, infrastructure upgrades, and digital water services, strengthening its market share through strategic alliances in the European water and wastewater domain.
IDEX Corporation
Provides fluid handling and precision delivery solutions, emphasizing automation and IoT-enabled platforms to enhance water process control and operational efficiency for industrial clients.
Huawei Technologies Co. Ltd.
Expanding into water management with smart water solutions featuring predictive analytics, IoT sensors, and integrated digital platforms, aiming to capitalize on digital infrastructure in water utilities.
GE Water & Process Technologies
GE offers innovative water treatment and automation solutions, focusing on sustainable, energy-efficient systems tailored for industrial-scale applications and municipal water treatment facilities, advancing digital water management.
Strategic Business Developments
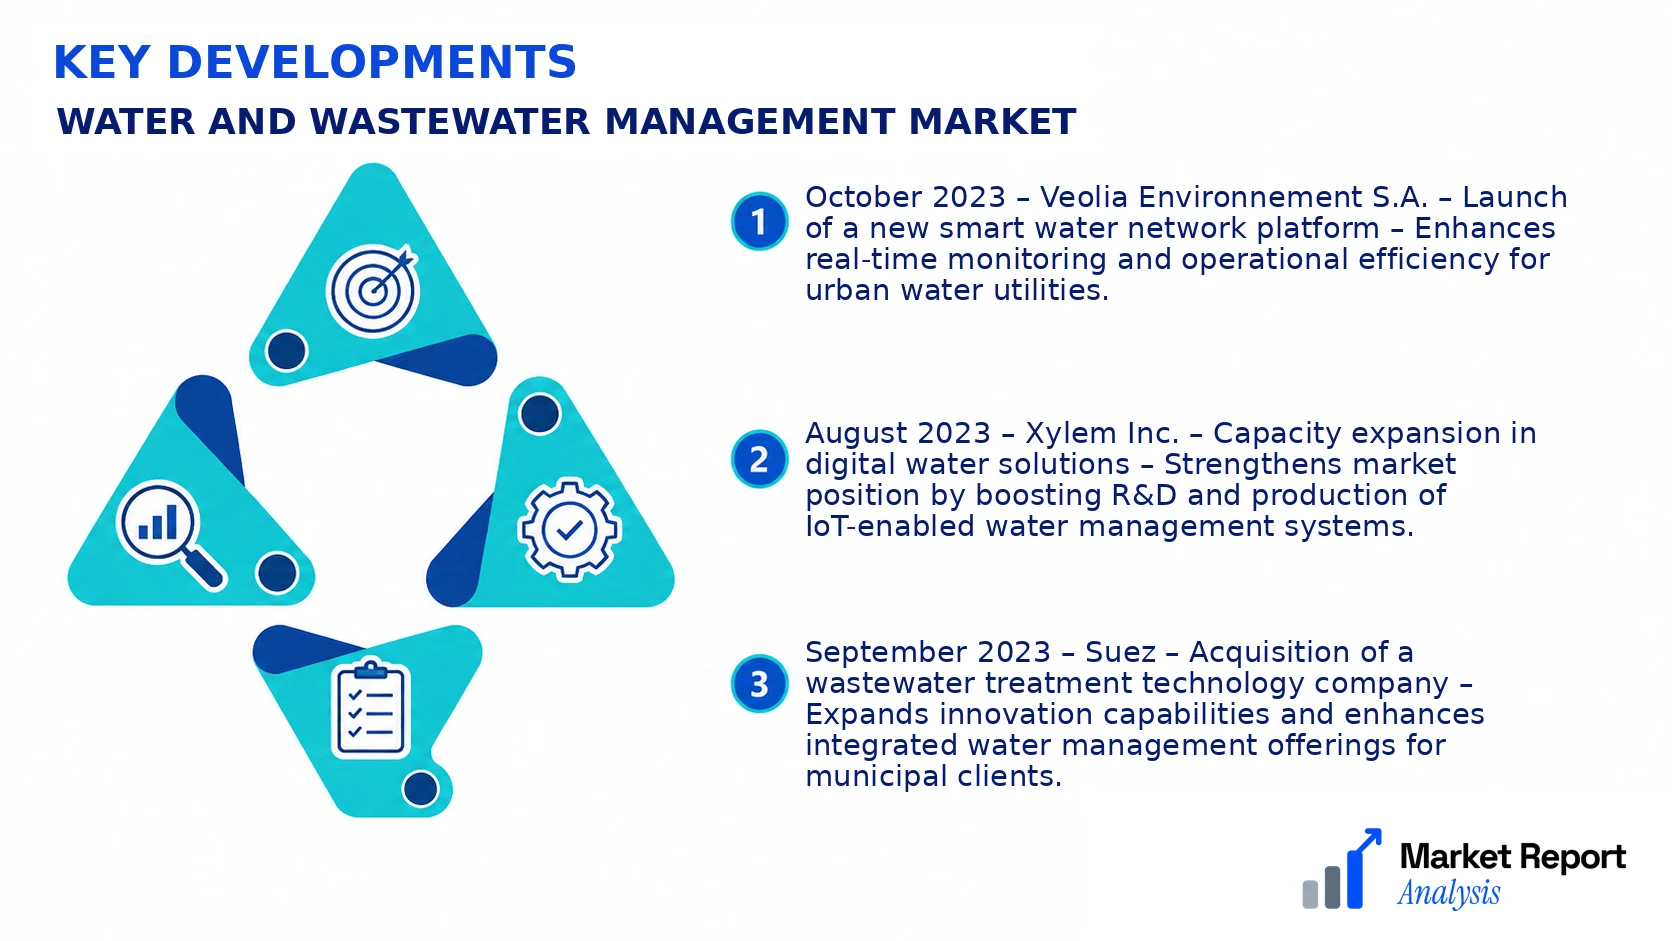
- October 2023 – Veolia Environnement S.A. – Launch of a new smart water network platform – Enhances real-time monitoring and operational efficiency for urban water utilities.
- August 2023 – Xylem Inc. – Capacity expansion in digital water solutions – Strengthens market position by boosting R&D and production of IoT-enabled water management systems.
- September 2023 – Suez – Acquisition of a wastewater treatment technology company – Expands innovation capabilities and enhances integrated water management offerings for municipal clients.
- July 2023 – Pentair PLC – Launch of a sustainable membrane technology line – Aims to improve membrane longevity and energy efficiency, supporting global sustainable water initiatives.
- November 2023 – Grundfos – Strategic partnership with IoT platform provider – Integrates smart pumping solutions with digital controls for smart water infrastructure projects.
Analyst Perspective
The water and wastewater management market is approaching a mature stage, yet it offers substantial growth prospects driven by technological advancements and increasing regulatory demands across regions. Long-term, the industry is expected to evolve with the integration of smart water management systems, leveraging IoT and AI to optimize operational efficiency and sustainability. Commercial opportunities will emerge notably in regions like Asia-Pacific and Africa, where urbanization and industrialization accelerate infrastructure development. Innovation in membrane technologies, water recycling, and decentralized treatment solutions will be pivotal, attracting strategic investments aligned with environmental, social, and governance (ESG) criteria. Competitive dynamics are intensifying as established players merge with or acquire innovative startups, fostering a dynamic landscape. Regional growth will be uneven, with North America and Europe leading in adoption of advanced, sustainable technologies, while emerging markets will present opportunities for lower-cost solutions. Overall, success hinges on strategic agility, technological leadership, and regional market adaptation.
