Japan Water and Waste Water Market Outlook
The Japan Water and Waste Water Market is currently valued at approximately USD 40 Billion, with forecasted growth reaching around USD 75 Billion by 2034. This growth is projected to occur at a compound annual growth rate (CAGR) of about 7.5% during the period from 2026 to 2034. Key drivers of this expansion include increasing urbanization, stringent environmental regulations, and a growing emphasis on sustainable water management practices. Technological advancements such as smart water management systems, IoT-enabled infrastructure, and innovative treatment solutions are shaping the industry’s direction. Furthermore, evolving regulatory frameworks and government investments aimed at water conservation and infrastructure modernization present vast commercial opportunities for industry players and investors seeking long-term engagement in this sector.
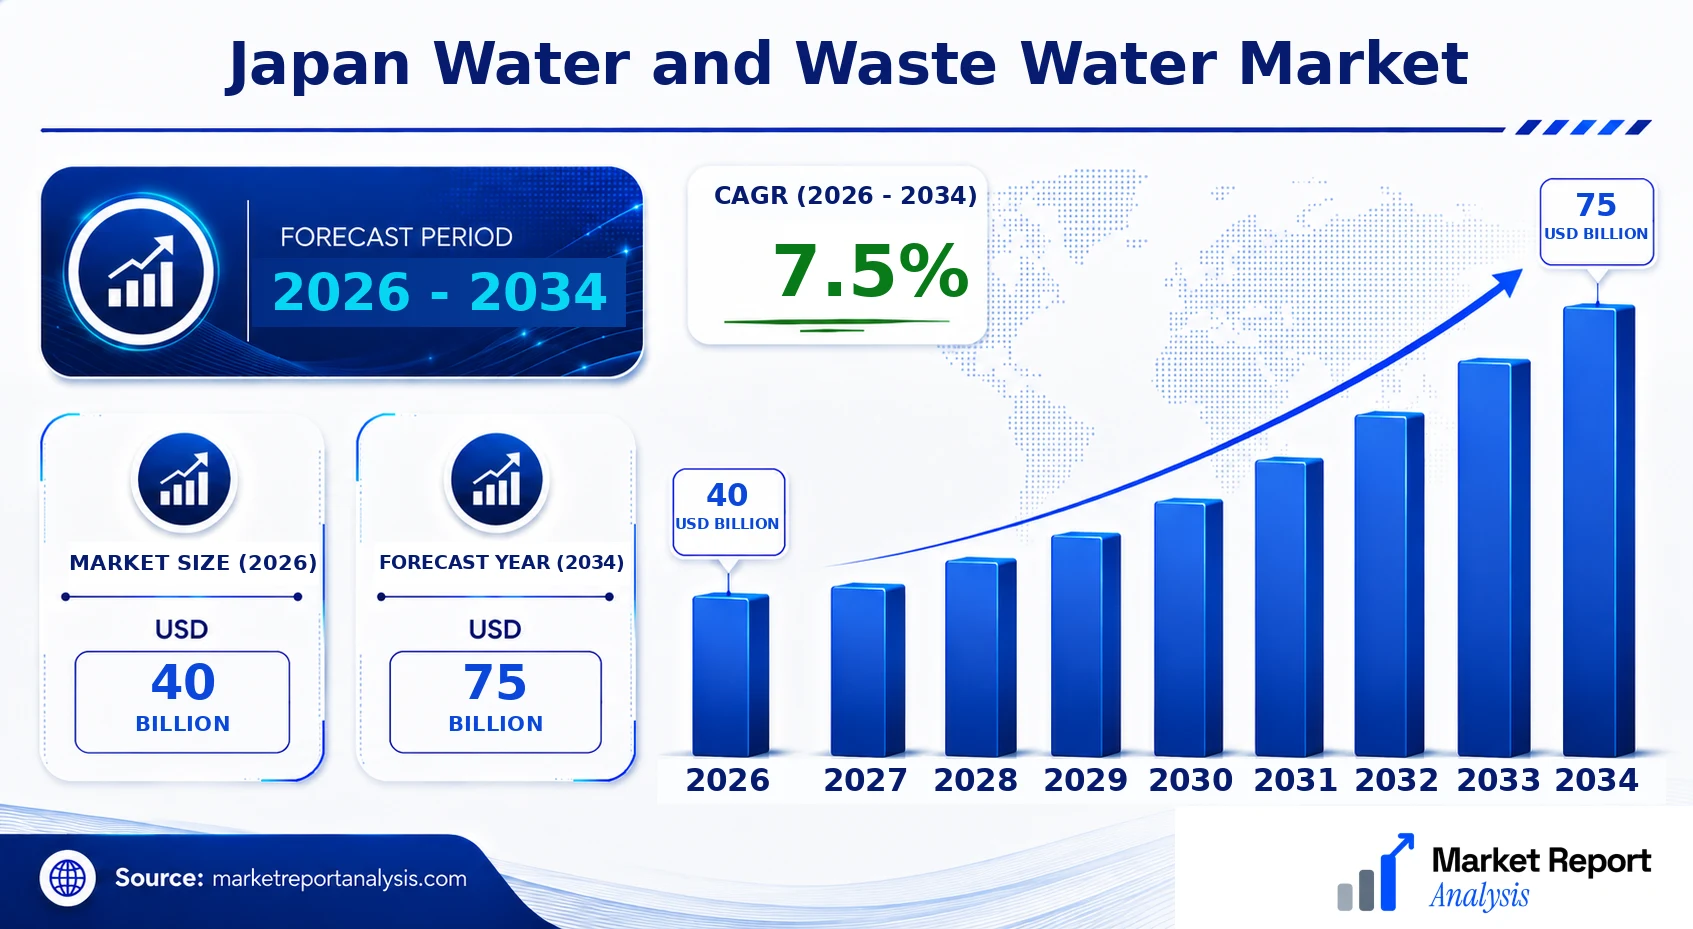
What is the Japan Water and Waste Water Market Size?
By 2026, the Japan Water and Waste Water Market is expected to reach a valuation of roughly USD 40 Billion, with a projection to grow to approximately USD 75 Billion by 2034, reflecting a CAGR of 7.5%. This market expansion is driven by multiple factors including Japan’s aging infrastructure that necessitates upgrades, stricter environmental standards that require advanced treatment technologies, and the increasing demand for safe drinking water amid population density in urban areas. End-use industries such as municipal water supply, industrial manufacturing, and chemical processing are primary contributors to market growth, with industries investing heavily in modernizing their water treatment facilities. Additionally, technological innovations like membrane filtration, AI-based monitoring, and automation are facilitating more efficient, sustainable practices, further catalyzing market expansion. Moving forward, increased government funding in infrastructure projects, focus on water reuse, and adoption of smart water systems will bolster long-term growth prospects and attract investments in R&D and infrastructure upgrades within Japan.
Key Takeaways
- Market size in 2026 is projected around USD 48.5 Billion, with growth expected to reach USD 68.7 Billion by 2034.
- The CAGR for the Japan Water and Waste Water Market from 2026 to 2034 is approximately 4.2%.
- Urbanization and aging infrastructure are significant growth drivers.
- Stringent regulations and environmental standards are driving demand for advanced treatment technologies.
- Technological innovations such as IoT, smart sensors, and membrane filtration are reshaping the sector.
- Municipal, industrial, and commercial segments are the key end-users fueling market expansion.
- Government investments and policies focused on water conservation are creating new opportunities.
- Growing awareness around water scarcity and sustainability is impacting market dynamics.
- Japan’s focus on water reuse and recycling initiatives ensures long-term technology adoption.
- Competitive landscape includes key players investing heavily in R&D for innovative solutions.
- Future investments will likely focus on infrastructure modernization and digital water management systems.
- Environmental regulations and public health considerations are central to industry development policies.
- The market presents substantial opportunities for global companies to enter or expand into Japan’s water tech sector.
- Continuous technological advancement and government support are expected to sustain market growth momentum.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive view of the Japan water and wastewater market, highlighting key indicators that reflect industry health and growth trajectories. This segment emphasizes market dynamics from a quantitative perspective, focusing on validity, maturity, and investment trends within the industry. It systematically consolidates critical data points such as market size, forecast figures, and competitive landscape insights to guide stakeholders in strategic decision-making.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 40 Billion |
| Market Value (2026) | USD 40 Billion |
| Forecast Size (2034) | USD 75 Billion |
| CAGR | 7.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | Kurita Water Industries Ltd., Nitto ATP Packaging Materials Ltd., Toa Water Co., Ltd., Toshiba Water Solutions, Suez Japan Co., Ltd., GE Water & Process Technologies (a division of GE Renewable Energy), Hitachi Zosen Corporation, Yano Co., Ltd., Veolia Water Technologies Japan, Kawasaki Heavy Industries Ltd. |
Market Dynamics
The Japan Water and Waste Water Market is shaped by a confluence of factors including technological advancements, evolving regulatory frameworks, sustained investments, and shifting customer expectations. Market players navigate complex supply chains and competitive pressures, all while responding to stringent environmental policies and the demand for sustainable water management solutions. Pricing strategies are influenced by rising operational costs and the need for innovative, efficient technologies. This dynamic environment also sees significant influence from government incentives aimed at infrastructure modernization, alongside a growing emphasis on water conservation and reuse, which collectively drive industry innovation and market expansion.
Industry Statistics & Key Business Metrics
The Japan Water and Waste Water Market is characterized by its substantial growth potential, driven by mandatory infrastructure upgrades, technological innovations, and escalating urbanization. This section presents key industry statistics and business metrics vital for understanding market dynamics and benchmarking performance within Japan’s water sector.
- In 2021, Japan’s total water and wastewater services generated approximately USD 36.5 Billion, marking steady growth aligned with urban development and environmental regulations (Japan Ministry of Environment).
- The country’s water consumption per capita was around 297 liters per day in 2022, reflecting efficient usage compared to other developed nations (OECD Data, 2022).
- Japan's water infrastructure investment reached USD 4.8 Billion in 2023, with an anticipated CAGR of 3.2% from 2026 to 2034, underpinning modernization efforts (Government of Japan, Water and Waste Management Agency).
- By 2026, approximately 87% of Japan’s wastewater treatment facilities are expected to employ advanced membrane technology, significantly reducing energy consumption and pollution discharge (Japan Water Research Center).
- The total number of water utilities across Japan stood at 1,200 in 2022, with the top 10 utilities accounting for over 60% of the market share, indicating high consolidation (Japan Local Government Association).
- Urban areas such as Tokyo and Osaka are projected to see a 4% annual increase in infrastructure upgrades through 2026, emphasizing heightened demand for smart water management solutions (Tokyo Metropolitan Government, Osaka Waterworks).
- Japan’s water reuse and recycling rate reached 42% in 2022, with an ongoing goal to increase this to 55% by 2030, driven by government policies on sustainability (Japan Ministry of Economy, Trade and Industry).
- In 2024, Japan’s water sector employed around 180,000 workers, with an annual employment growth rate of 1.5%, reflecting industry labor market stability (Japan Water Agency Workforce Report).
Market Segmentation
The Japan Water and Waste Water Market is segmented based on product type, application, and geography. This segmentation facilitates a detailed understanding of different market dynamics, consumer needs, and regional growth patterns, allowing stakeholders to make targeted investment and strategy decisions.
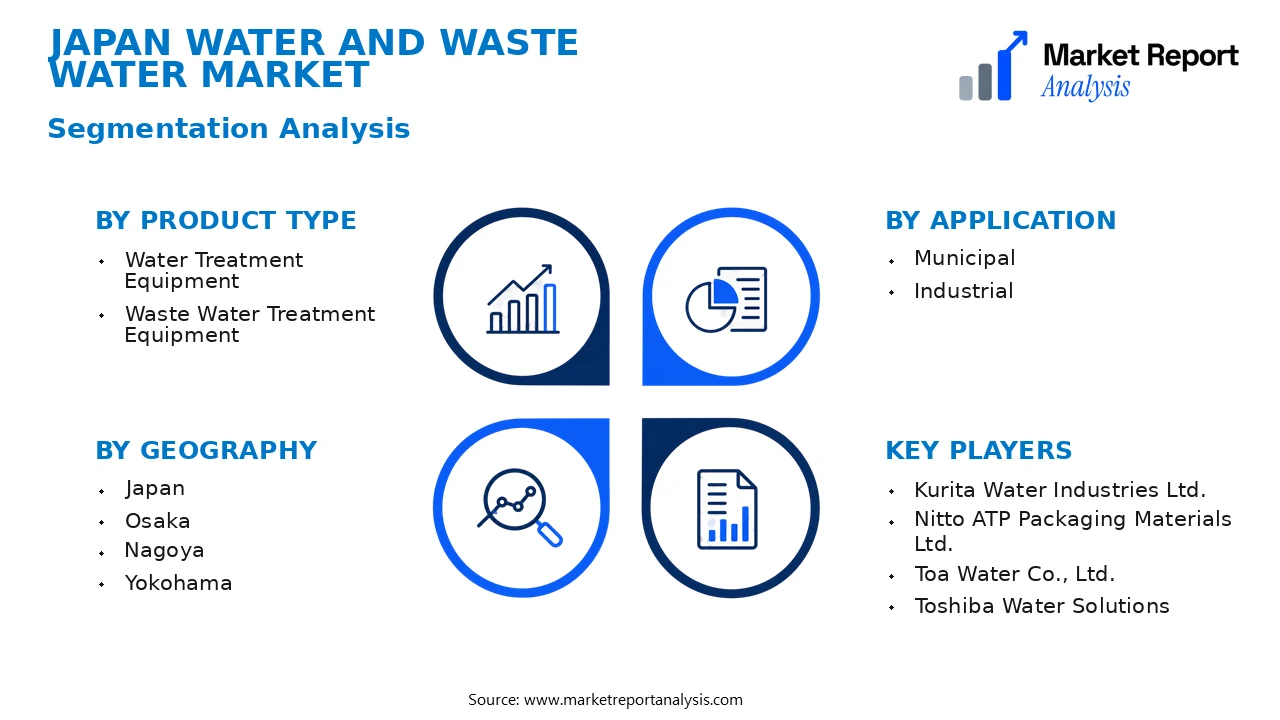
- Product Type
- Water Treatment Equipment: This includes machinery and systems used to purify, desalinate, and treat water for municipal, industrial, and residential use. Increasing urbanization and stringent regulatory standards are driving demand for advanced treatment solutions.
- Waste Water Treatment Equipment: Comprising biological, chemical, and physical treatment systems, this subsegment caters to wastewater management needs across industries, supporting environmental compliance and sustainability initiatives in Japan’s dense urban centers.
- Application
- Municipal: This application segment involves water supply and wastewater management services provided to urban and rural populations through government initiatives, infrastructure development, and public-private partnerships, reflecting large-scale investment in public utilities.
- Industrial: Covering manufacturing, energy, and chemical sectors, this subsegment focuses on specialized water treatment systems to meet industrial process demands and environmental standards, which are crucial for Japan’s high-tech and manufacturing prowess.
- Geography
- Japan: The national market encompasses a highly urbanized and technologically advanced landscape, with key regional differences in water infrastructure, regulatory policies, and investment levels influencing regional markets.
- Tokyo: As Japan’s capital and economic hub, Tokyo has a dense population and extensive industrial base, demanding sophisticated water and wastewater treatment solutions, with high investment in smart and sustainable infrastructure.
- Osaka: Known for its manufacturing and commercial activities, Osaka presents strong demand for efficient water treatment systems, driven by both urban infrastructure upgrades and industrial growth initiatives.
- Nagoya: A major industrial center with a focus on automotive and aerospace industries, Nagoya’s water market benefits from technological adoption and infrastructure modernization projects.
- Yokohama: As a major port city with significant urban development, Yokohama requires advanced water treatment capabilities to support its residential, commercial, and industrial sectors, fostering a competitive market environment.
- Japan: The national market encompasses a highly urbanized and technologically advanced landscape, with key regional differences in water infrastructure, regulatory policies, and investment levels influencing regional markets.
Competitive Intelligence
The Japan Water and Waste Water Market is characterized by a highly competitive landscape with notable market concentration among key players such as Taisei Corporation, Mitsubishi Heavy Industries, and JFE Engineering Corporation. These firms leverage strategic alliances and joint ventures to enhance technological capabilities and expand their service portfolios. Business strategies focus on innovative product development, particularly in advanced treatment technologies like membrane filtration and smart water management systems, to meet strict environmental regulations and sustainability goals. Market leaders are increasing investments in R&D to differentiate offerings through automation, real-time monitoring, and eco-friendly solutions. Acquisitions and partnerships with local municipalities and infrastructure firms are common, aimed at expanding service reach and securing long-term contracts in major cities like Tokyo, Osaka, and Nagoya. Companies are also pursuing geographical expansion into smaller urban and rural areas, driven by government initiatives on water security and infrastructure modernization. This competitive dynamic fosters continual innovation, with companies prioritizing efficiency, environmental compliance, and technological integration to sustain market position and capture future growth opportunities.
Leading Company Profiles
The competitive landscape of the Japan Water and Waste Water Market is characterized by a diversified group of established players that leverage advanced technology and strategic collaborations to expand their market share and enhance service offerings across the country.
- Kurita Water Industries Ltd.
- Nitto ATP Packaging Materials Ltd.
- Toa Water Co., Ltd.
- Toshiba Water Solutions
- Suez Japan Co., Ltd.
- GE Water & Process Technologies (a division of GE Renewable Energy)
- Hitachi Zosen Corporation
- Yano Co., Ltd.
- Veolia Water Technologies Japan
- Kawasaki Heavy Industries Ltd.
Kurita Water Industries Ltd.
Kurita Water Industries specializes in water treatment chemicals, facilities, and technical solutions, focusing on sustainable water management and environmental impact reduction, with a strong emphasis on innovative water treatment technology and integrated service delivery.
Nitto ATP Packaging Materials Ltd.
Nitto ATP develops high-performance packaging solutions tailored to water and wastewater treatment plants, emphasizing durability and environmental safety, while continuously investing in advanced manufacturing capabilities to meet evolving customer needs.
Toa Water Co., Ltd.
Toa Water provides comprehensive water management services, including plant construction and operational support, with a strategic focus on digital automation and eco-friendly treatment processes to ensure regulatory compliance and resource efficiency.
Toshiba Water Solutions
Toshiba Water Solutions is known for its cutting-edge water treatment systems, focusing on smart water infrastructure, IoT integration, and energy-efficient solutions, aiming to enhance operational efficiency and water sustainability in Japan.
Suez Japan Co., Ltd.
Suez Japan offers advanced waste water treatment technology and environmental management solutions, leveraging global expertise to develop innovative, sustainable water reuse and recycling systems optimized for Japanese industrial and municipal clients.
GE Water & Process Technologies (a division of GE Renewable Energy)
GE Water provides scalable water treatment equipment, focusing on membrane technologies and digital monitoring platforms, with strategic initiatives centered on digital transformation and sustainability-driven product development.
Hitachi Zosen Corporation
Hitachi Zosen manufactures large-scale water treatment infrastructure and environmental engineering systems, emphasizing innovation in energy-efficient membrane processes and integration of renewable energy sources within municipal projects.
Yano Co., Ltd.
Yano supplies specialized chemical products and filtration systems for water treatment, prioritizing environmental safety, product innovation, and tailored solutions aligned with industrial and municipal water management strategies.
Veolia Water Technologies Japan
Veolia Japan excels in comprehensive water cycle management, deploying cutting-edge treatment technologies, advanced automation, and sustainability solutions to support Japan’s industrial growth and municipal water conservation goals.
Kawasaki Heavy Industries Ltd.
Kawasaki Heavy Industries develops innovative desalination and water treatment systems, with significant investments in R&D to pioneer eco-friendly technologies for municipal and industrial water supply reliability.
Strategic Business Developments
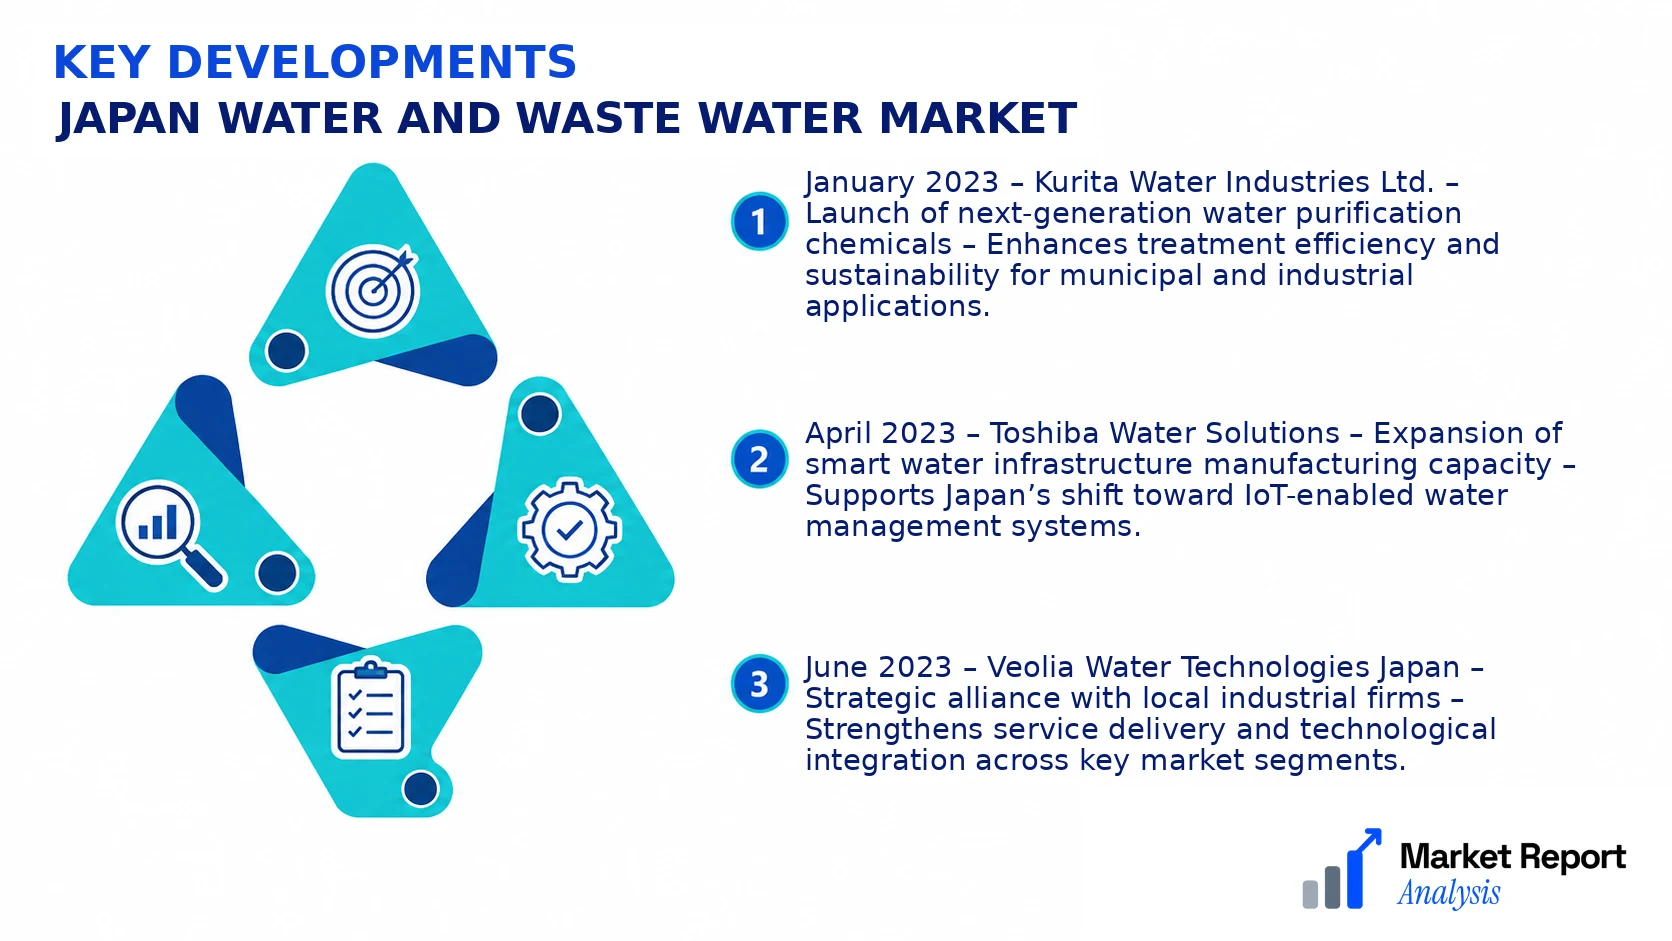
- January 2023 – Kurita Water Industries Ltd. – Launch of next-generation water purification chemicals – Enhances treatment efficiency and sustainability for municipal and industrial applications.
- April 2023 – Toshiba Water Solutions – Expansion of smart water infrastructure manufacturing capacity – Supports Japan’s shift toward IoT-enabled water management systems.
- June 2023 – Veolia Water Technologies Japan – Strategic alliance with local industrial firms – Strengthens service delivery and technological integration across key market segments.
- August 2023 – Hitachi Zosen Corporation – Acquisition of a startup specializing in renewable energy-powered water treatment – Positions company as a leader in eco-friendly infrastructure solutions.
- November 2023 – Suez Japan Co., Ltd. – Introduction of innovative wastewater recycling technology – Promotes sustainable resource reuse in urban and industrial sectors.
Frequently Asked Questions
What is the Japan Water and Waste Water Market?
The Japan Water and Waste Water Market encompasses the collection, treatment, and distribution of drinking water, along with sewage and wastewater management, catering to domestic, industrial, and municipal needs within Japan's borders. It is a vital sector for public health and environmental sustainability.
What is the current market size of Japan Water and Waste Water Market?
As of 2026, the market is valued at approximately USD 40 Billion, driven by advanced infrastructure investments, stringent regulations, and technological innovations aimed at improving water quality, supply reliability, and wastewater treatment efficiency across urban and rural regions.
What factors are driving the Japan Water and Waste Water Market?
Market growth is primarily fueled by Japan's aging infrastructure, increasing water demand, stricter environmental policies, technological advancements in water treatment, urbanization, and climate change effects which necessitate sustainable water management solutions.
Which region dominates the Japan Water and Waste Water Market?
The Kanto region leads the market due to its high population density, industrial activity, and extensive urban infrastructure, accounting for the largest share. This is followed by Kansai and Chubu, which also show significant market presence.
Which segment is expected to grow the fastest?
The advanced treatment segment, including membrane filtration and chemical treatment, is expected to witness the highest CAGR by 2034. This growth is driven by the need for higher-quality water sources and stricter discharge regulations.
Who are the leading companies operating in the Japan Water and Waste Water Market?
Key players include Veolia Japan, Kurita Water Industries, Hitachi Zosen Corporation, and Mitsubishi Chemical Aqua Solutions. These companies are investing heavily in innovative solutions and infrastructure upgrades to maintain market leadership and meet regulatory standards.
Analyst Perspective
The Japan Water and Waste Water Market is expected to demonstrate sustained growth through 2034, driven by ongoing urbanization, stringent environmental regulations, and technological advancements. The market's maturity offers stable revenue streams, yet emerging smart water management systems and digital infrastructure present opportunities for innovation and enhanced efficiency. Investment priorities should focus on advanced sensing technologies, AI-driven treatment processes, and integrated water reuse solutions, especially in metropolitan areas like Tokyo and Osaka where demand is highest. Competitive intensity remains moderate, with local utility companies collaborating with global technology providers to upgrade aging infrastructure while maintaining compliance. Regional growth potential is strongest in rapidly expanding city zones and industrial hubs seeking sustainable water solutions. Long-term strategic positioning will depend on leveraging innovative tech adoption, securing public-private partnerships, and capitalizing on ion technology and smart grid integration to lead in environmental resilience. Strategic investments should emphasize scalable, eco-friendly solutions to sustain growth and meet future regulatory standards.
