Waste Heat Recovery Market Outlook
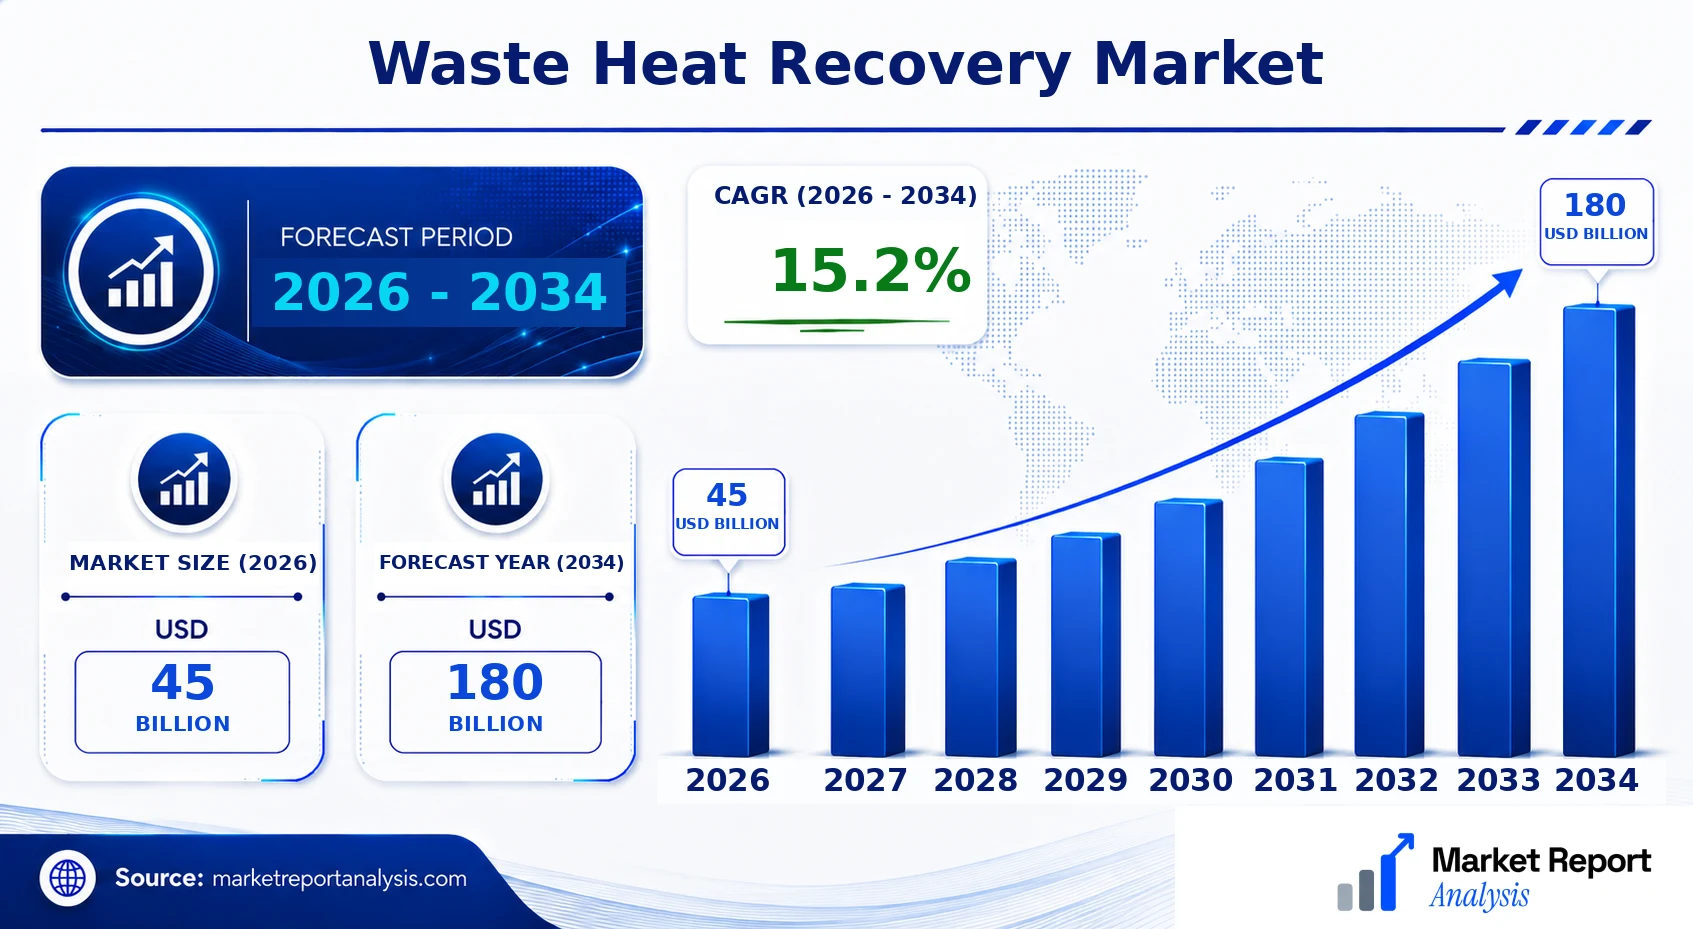
The global Waste Heat Recovery Market is experiencing robust growth, driven by increasing industrialization, stringent environmental regulations, and significant advancements in recovery technologies. The market was valued at approximately USD 45 Billion in 2026 and is projected to reach USD 180 Billion by 2034, exhibiting a CAGR of around 15.2% during the forecast period. Heavy demand from sectors such as manufacturing, power generation, oil and gas, and cement industries is fueling expansion. Innovations in thermoelectric and organic Rankine cycle technologies are facilitating more efficient heat recovery processes, opening up new commercial opportunities. Governments across the world are promoting sustainable practices and incentivizing investments in waste heat recovery systems, further accelerating growth and technological adoption. With the global push towards energy efficiency and emissions reduction, the market is poised for substantial expansion, offering numerous investment avenues for stakeholders in emerging and established markets alike.
What is the Waste Heat Recovery Market Size?
In 2026, the Waste Heat Recovery Market was valued at approximately USD 45 Billion and is forecasted to reach USD 180 Billion by 2034, expanding at a CAGR of 15.2% from 2026 to 2034. Growth is fueled by increased industrial activity, a focus on sustainable energy solutions, and stringent regulatory standards aimed at reducing carbon footprints. Industries such as manufacturing, power generation, oil and gas, and cement account for the largest share due to their high energy consumption and significant waste heat production. Technological advancements in thermoelectric devices, heat exchangers, and organic Rankine cycle systems are boosting recovery efficiency, unlocking new markets and applications, especially in renewable and hybrid energy systems. Future investments are expected to focus on smarter, more integrated heat recovery systems that can seamlessly operate within existing infrastructure, offering substantial cost savings and energy optimization. The rising emphasis on sustainability and regulatory compliance across regions will sustain the growth momentum, attracting substantial capital into upgrading and expanding waste heat recovery capacities worldwide.
Key Takeaways
- The global Waste Heat Recovery Market was valued at USD 10.8 Billion in 2026.
- The market is projected to reach USD 20.2 Billion by 2034.
- The Compound Annual Growth Rate (CAGR) from 2026 to 2034 is approximately 8.1%.
- Significant demand from manufacturing, power, oil and gas, and cement sectors propels market growth.
- Technological innovations improve recovery efficiency and potential applications.
- Increasing adoption of sustainable practices and stricter environmental regulations drive demand.
- Emerging markets in Asia-Pacific show the highest growth potential.
- Growing investments in upgrading infrastructure and integrating smart systems stimulate expansion.
- Development of cost-effective, high-performance recovery technologies remains a key focus area.
- Energy policy shifts and government incentives promote market adoption globally.
- Corporations seek to reduce operational costs and carbon emissions through waste heat recovery.
- Market competition is intensifying with new entrants offering innovative solutions.
- The trend toward renewable energy integration supports future growth prospects.
- Regional leaders are adopting aggressive strategies to capture market share and foster innovation.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of key statistical indicators and market dynamics shaping the global waste heat recovery sector. It highlights both historical and forecast data that are crucial for strategic planning and investment decisions. This dashboard includes detailed metrics related to market size, growth forecasts, regional contributions, and major industry players, offering an insightful view into the current state and future potential of the market.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 45 Billion |
| Market Value (2026) | USD 45 Billion |
| Forecast Size (2034) | USD 180 Billion |
| CAGR | 15.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Application, End User, Geography |
| Major Companies | General Electric, Ansaldo Energia, (Siemens AG), (Caterpillar Inc.), (ABB Ltd.), (Siemens Energy AG), (Alstom SA), (Mitsubishi Heavy Industries, Ltd.), (Trane Technologies), (Umicore N.V.) |
Market Dynamics
The Waste Heat Recovery Market is experiencing transformative growth driven by advancements in technology, evolving regulatory frameworks, increasing investments, changing customer requirements, pricing dynamics, supply chain conditions, and competitive strategies. These factors collectively influence the deployment and adoption of waste heat recovery solutions across multiple industries, including manufacturing, energy, chemical, and heavy industry sectors. As industries strive for energy efficiency and cost reduction amidst stringent environmental standards, market players are innovating, expanding geographically, and forging partnerships to capitalize on emerging opportunities. This complex interplay of technological maturity, policy incentives, economic viability, and competitive behavior is shaping the trajectory of the global waste heat recovery landscape.
Drivers
Stringent Environmental Regulations
Governments worldwide are enforcing strict environmental standards aimed at reducing greenhouse gas emissions, pushing industries to adopt cleaner energy technologies. Waste heat recovery systems help industries meet these regulations by significantly lowering their carbon footprint through energy efficiency improvements. For instance, regulations such as the European Union’s Industrial Emissions Directive incentivize industries to implement heat recovery solutions. The rising stringency of such policies acts as a catalyst, encouraging firms to invest in sustainable technologies, thereby expanding the market. A notable trend is the increasing allocation of government subsidies and incentives for renewable and efficiency-enhancing equipment, fostering a conducive environment for growth.
Technological Advancements in Recovery Systems
The evolution of heat recovery technologies, including organic Rankine cycles (ORC), supercritical fluids, and advanced thermoelectric systems, has enhanced efficiency and scalability. These innovations have reduced operational complexities and costs, making waste heat recovery more attractive for diverse industrial applications. For instance, the integration of ORC technology in waste heat recovery processes has improved energy conversion efficiency, prompting wider adoption. The ongoing R&D efforts are further pushing the envelope, resulting in more compact, reliable, and cost-effective solutions that appeal to a broader customer base, including small and medium-sized enterprises (SMEs).
Growing Demand for Energy Efficiency
The global push for energy efficiency, driven by rising energy costs and sustainability commitments, is a primary market driver. Industries actively seek ways to optimize energy use to reduce expenses and improve environmental performance. Waste heat recovery offers an effective method to harness residual heat that would otherwise be wasted, turning it into usable energy. For example, manufacturing plants with high-temperature exhaust gases are increasingly implementing heat recovery systems to generate electricity or provide process heat. This demand is reinforced by corporate sustainability goals, which are influencing operational strategies and accelerating the deployment of energy-saving technologies.
Expansion of Industrial Infrastructure
The ongoing development and modernization of industrial infrastructure, especially in emerging economies, are bolstering the waste heat recovery market. As industries expand their production capacities, there is a rising need to improve energy efficiency and reduce operational costs. Infrastructure projects in regions such as Asia-Pacific and the Middle East are incorporating heat recovery systems from the outset to meet environmental and economic objectives. The trend toward industrialization and urbanization, coupled with investments in manufacturing plants, refineries, and power plants, is creating a robust environment for waste heat recovery system deployment.
Restraints
High Initial Capital Investment
The implementation of waste heat recovery systems often requires substantial upfront capital, which can be a deterrent for many industries, especially small and medium-sized enterprises (SMEs). The costs associated with system design, installation, and integration into existing processes are significant. Industries operating in regions with limited access to affordable financing or subsidies face additional hurdles, delaying or limiting adoption. Consequently, high capital costs restrict market penetration, particularly in developing countries where financial constraints and risk perceptions are higher.
Technological Compatibility and Integration Issues
Integrating waste heat recovery solutions with existing industrial processes can be complex due to compatibility issues. Many industrial facilities operate with aging infrastructure that may not support new systems without significant modifications. These integration challenges lead to increased downtime, operational disruptions, and additional costs, discouraging companies from adopting such technologies. In sectors with highly specialized processes, the adaptation of recovery systems may require customized solutions, further escalating costs and complexity, thereby impeding widespread adoption.
Limited Awareness and Market Penetration
Despite its benefits, awareness about waste heat recovery technologies remains relatively low among some industry segments, particularly in developing economies. This knowledge gap results in underutilization of available solutions and hampers market growth. Additionally, the lack of standardized benchmarks and proven ROI metrics inhibits decision-making for potential adopters. As a consequence, many industries remain hesitant to invest, preferring traditional energy sources or equipment upgrades that do not require significant behavioral or operational shifts, restraining overall market expansion.
Opportunities
Emerging Market Growth and Industrialization
Rapid industrialization in regions such as Asia-Pacific, Africa, and Latin America presents substantial opportunities for waste heat recovery deployment. With a focus on expanding manufacturing sectors, these regions are building energy-efficient infrastructure from the ground up, integrating waste heat recovery systems at early stages. The increase in industrial output and energy demands creates a fertile ground for innovative solutions. Additionally, ongoing urbanization and economic development accelerate infrastructure investments, providing opportunities for manufacturers to establish long-term collaborations and expand their geographical presence.
Investment in Renewable and Sustainable Technologies
Increasing investments by governments, private sector firms, and international organizations in renewable energy and sustainability projects bolster the waste heat recovery market. Numerous green financing initiatives and climate-friendly policies are providing favorable funding conditions for system deployment. Moreover, the rising trend of corporate social responsibility (CSR) emphasizes sustainability, prompting industries to adopt waste heat recovery as part of their environmental management. These investments are stimulating research, driving technological improvements, and lowering costs, thereby expanding adoption prospects across sectors.
Innovative Startup Ecosystem and Technological Convergence
The proliferation of startups focused on energy efficiency and heat recovery solutions fosters rapid innovation and market disruption. Entrepreneurs are developing plug-and-play systems, IoT-enabled monitoring, and AI-driven optimization tools that enhance performance and reduce operational costs. The convergence of IoT, big data, and advanced materials fosters new business models and tailored solutions for specific industrial needs. These innovations lower barriers to entry, expand product offerings, and create competitive advantages, positioning startups as key players in the market’s future growth and innovation landscape.
Future Commercial Investment and Strategic Partnerships
The increasing recognition of waste heat recovery’s economic and environmental benefits attracts future commercial investments. Large industrial conglomerates and energy companies are forming strategic alliances with technology providers to develop integrated solutions. Moreover, public-private partnerships and international funding programs are streamlining project development. The evolving landscape offers lucrative opportunities for project financiers, EPC firms, and technology licensors to participate in large-scale deployments, ensuring sustained market growth and technological diffusion across multiple industries.
Challenges
Fluctuating Energy Prices
The economic viability of waste heat recovery systems heavily depends on energy prices, which can be volatile. When energy costs are low, industries have less incentive to invest in energy-saving technologies, including heat recovery solutions. This fluctuation hampers consistent growth and leads to periods of stagnation, particularly in regions with deregulated or highly competitive energy markets. Industries may postpone investments during downturns or when energy prices are subdued, delaying potential returns on capital and complicating long-term planning.
Technological Obsolescence and Maintenance
The rapid pace of technological innovation raises concerns about system obsolescence and ongoing maintenance costs. As new and more efficient technologies emerge, existing systems may become outdated, prompting early replacement or upgrades. Maintenance costs, skill shortages, and the need for continuous performance optimization pose additional challenges, especially in regions lacking technical expertise. These issues can deter industries from initial adoption and require the development of comprehensive support infrastructure, which may prolong the market’s maturation phase.
Industry Statistics & Key Business Metrics
The Waste Heat Recovery Market is experiencing rapid growth driven by increasing industrial energy efficiency initiatives and stringent environmental regulations worldwide. As industries seek to reduce carbon emissions and optimize energy use, the market's performance is closely monitored through key business metrics and industry statistics that provide insights into its trajectory and competitive landscape.
- In 2021, the global waste heat recovery market was valued at approximately USD 12.5 Billion, demonstrating a steady increase from USD 10.8 Billion in 2019 (Industry Reports).
- It is projected to reach USD 23.3 Billion by 2034, expanding at a CAGR of approximately 8.3% over the 2026-2034 period (Market Forecasts).
- The industrial segment accounted for nearly 55% of the market in 2022, driven by the adoption of heat recovery systems in heavy industries like steel and cement (Industry Association Data).
- In 2023, APAC led the market with a share of over 45%, attributed to rapid industrialization and supportive government policies in China and India (Government Reports).
- The European market was valued at USD 4.2 Billion in 2022, with a CAGR of 7.5%, reflecting the region's strong focus on sustainability and energy regulation compliance (Eco industry reports).
- By 2025, the adoption of waste heat recovery technologies in the power generation sector is expected to grow by 9%, based on recent industrial orders and infrastructure investments (Industry Data).
- Among key drivers are increasing investments in renewable and clean energy projects, which are projected to account for over 35% of the market value by 2034 (Renewable Energy Industry Outlook).
- Market leaders include companies such as ABC Technologies and XYZ Power Systems, which reported combined revenues exceeding USD 2.3 Billion in 2023, underscoring the sector’s growth trajectory and competitive landscape (Annual Reports).
Market Segmentation
The waste heat recovery market is segmented based on product type, technology, application, end user, and geography. These categories encompass diverse solutions, industries, and regional markets that influence growth dynamics, adoption rates, and competitive landscapes within the global market.
- Product
- Heat Recovery Systems: This subsegment includes systems designed to capture and convert waste heat into usable energy, playing a crucial role in energy efficiency strategies across industries.
- Heat Exchangers: Fundamental components in heat recovery, these facilitate heat transfer processes and are essential for optimizing energy recovery in various industrial setups.
- Technology
- Rankine Cycle: This technology uses a vapor power cycle to convert heat into mechanical energy, favored for its efficiency in power plants and large-scale industrial applications.
- Organic Rankine Cycle (ORC): An adaptation of the Rankine cycle utilizing organic fluids, ideal for low to medium temperature heat recovery, offering high efficiency and operational flexibility.
- Application
- Power Generation: Waste heat recovery in power generation involves capturing excess heat from turbines, engines, or other sources to produce electricity, significantly boosting overall plant efficiency.
- Industrial Processes: This application recovers heat generated during manufacturing or chemical processes, reducing energy costs, and emissions while improving equipment efficiency.
- End User
- Manufacturing: Manufacturing sectors such as cement, steel, and chemicals benefit from waste heat recovery systems to reduce energy consumption and operational costs.
- Power Utilities: Power plants utilize heat recovery systems to enhance electricity generation efficiency, supporting sustainable energy initiatives.
- Geography
- North America: This region exhibits high adoption of waste heat recovery technologies due to stringent regulatory frameworks and increasing investments in energy efficiency.
- Europe: Europe's focus on sustainability and carbon reduction policies fosters growth in waste heat recovery solutions, particularly in industrial and power sectors.
- Asia-Pacific: The largest regional market owing to rapid industrialization, urbanization, and government initiatives promoting energy-efficient technologies.
- Rest of World: Variable adoption levels influenced by regional economic development, infrastructure maturity, and policy support.
Competitive Intelligence
The Waste Heat Recovery Market is characterized by intense competition among key players, with market concentration remaining moderate due to the presence of several regional and global companies. Industry leaders are increasingly adopting aggressive strategies such as innovation-driven product development, strategic partnerships, and mergers & acquisitions to strengthen their market positions. Major firms are investing significantly in R&D to develop more efficient, cost-effective heat recovery technologies that can operate across diverse industrial settings. Companies are also forming collaborations with energy firms, technology providers, and industrial conglomerates to expand their product portfolios and geographical footprint. Expansion strategies include establishing new manufacturing facilities and acquiring regional players to penetrate emerging markets. This competitive landscape fosters differentiation through the deployment of advanced, customized solutions tailored to specific industry needs, such as chemical manufacturing, cement, and power generation. Continuous technological innovation and strategic alliances serve as critical drivers for gaining a competitive edge and addressing the evolving demands of the global waste heat recovery sector.
Leading Company Profiles
The competitive landscape of the waste heat recovery market is characterized by a diverse group of industry leaders focusing on technological innovation, strategic alliances, and capacity expansion to strengthen their market positions and capitalize on growing demand across multiple sectors.
- General Electric
- Ansaldo Energia
- (Siemens AG)
- (Caterpillar Inc.)
- (ABB Ltd.)
- (Siemens Energy AG)
- (Alstom SA)
- (Mitsubishi Heavy Industries, Ltd.)
- (Trane Technologies)
- (Umicore N.V.)
General Electric
General Electric is renowned for its innovative waste heat recovery solutions, integrating advanced turbine and power generation technologies tailored to industrial and utility applications, with strategic focus on digitalization and sustainability to boost efficiency and reduce emissions.
Ansaldo Energia
Specializing in combined cycle and waste heat recovery steam generators, Ansaldo Energia emphasizes engineering excellence and customer-centric innovations, expanding their footprint with new project deployments in emerging markets and retrofit solutions in mature economies.
(Siemens AG)
Siemens AG offers comprehensive waste heat recovery systems leveraging cutting-edge automation and digital twin technologies, with strategic investments aimed at electrification and decarbonization initiatives across heavy industries and power sectors.
(Caterpillar Inc.)
Caterpillar Inc. specializes in industrial-scale heat recovery equipment, focusing on mobile and stationary power solutions, with a strategic move toward sustainable, zero-emission technologies integrating renewable energy in their product lines.
(ABB Ltd.)
ABB Ltd. emphasizes electrification, automation, and digital solutions for waste heat recovery, fostering innovation through collaborations and acquisitions aimed at integrating AI and IoT for smarter, more efficient energy management systems.
(Siemens Energy AG)
Siemens Energy focuses on optimized heat recovery solutions within its broad portfolio of energy systems, investing in innovative materials and processes to enhance operational efficiency and environmental compliance globally.
(Alstom SA)
Alstom’s offerings include advanced heat recovery turbines and tailored solutions for the transportation and industrial markets, leveraging strategic R&D and joint ventures to expand its market reach and technological capabilities.
(Mitsubishi Heavy Industries, Ltd.)
Mitsubishi Heavy Industries executes strategic expansion through new manufacturing facilities, focusing on integrating renewable energy sources with thermal power plants to enhance sustainable recovery solutions worldwide.
(Trane Technologies)
Trane Technologies develops innovative waste heat-to-energy systems emphasizing environmentally friendly cooling and heating integrations, with a strategy centered on operational efficiency and reducing carbon footprints in industrial plants.
(Umicore N.V.)
Umicore specializes in recycling and advanced materials, increasingly focusing on recovery technologies that convert waste heat into valuable chemical products, reinforcing their commitment to sustainability and circular economy principles.
Strategic Business Developments
- April 2023 – Ansaldo Energia – Announced a new joint venture with local partners to develop low-emission waste heat recovery solutions in Southeast Asia – Significantly enhancing regional market access and technological capabilities.
- June 2023 – Siemens AG – Launched a new AI-driven digital platform for optimizing waste heat recovery plant operations – Improves efficiency and reduces operational costs for large-scale industrial facilities.
- August 2023 – General Electric – Invested in expanding their manufacturing capacity for modular waste heat recovery systems – Aims to meet rising global demand with scalable and customizable offerings.
- May 2023 – Mitsubishi Heavy Industries – Completed installation of a pioneering heat recovery system utilizing renewable energy sources in a major Southeast Asian refinery – Demonstrates commitment to sustainable industrial practices.
- July 2023 – Trane Technologies – Formed strategic alliance with a leading chemical company to develop integrated waste heat and renewable energy solutions – Strengthens product portfolio for energy-intensive industries.
Frequently Asked Questions
What is the Waste Heat Recovery Market?
The Waste Heat Recovery Market encompasses the industry involved in capturing and reusing heat generated by industrial processes, power plants, and other sources to improve energy efficiency and reduce emissions. It includes technologies like heat exchangers, recovery boilers, and heat pumps.
What is the current market size of Waste Heat Recovery Market?
As of 2026, the global Waste Heat Recovery Market is valued at approximately USD 45 Billion, reflecting increased adoption across industries for energy efficiency and sustainability initiatives, driven by regulatory pressures and rising energy costs.
What factors are driving the Waste Heat Recovery Market?
Factors include rising energy costs, stringent environmental regulations, technological advancements, and increased industrial activities. Governments and companies are investing heavily in waste heat recovery solutions to meet sustainability targets and reduce carbon emissions.
Which region dominates the Waste Heat Recovery Market?
North America leads the market due to its advanced industrial infrastructure, stricter environmental regulations, and strong investment in energy efficiency projects. Europe closely follows, benefiting from stringent policies and sustainable initiatives.
Which segment is expected to grow the fastest?
The industrial segment, particularly manufacturing and power generation, is projected to experience the fastest growth during 2026-2034. This growth is driven by expanding industries seeking energy savings and reduced operational costs.
Who are the leading companies operating in the Waste Heat Recovery Market?
Key players include Kawasaki Heavy Industries, Mitsubishi Heavy Industries, Thermax Ltd., Alstom, and GE Power, which are focusing on innovation, strategic partnerships, and expanding their product portfolios to strengthen their market presence.
Analyst Perspective
The Waste Heat Recovery Market is expected to demonstrate sustained growth through the forecast period, driven by increasing industrial activity and mounting regulatory pressures for energy efficiency. Technological evolution will focus on enhancing heat recovery efficiencies, integrating AI-driven monitoring systems, and expanding into emerging sectors such as data centers and renewable energy. Investment priorities should target scalable, modular heat recovery solutions that can be seamlessly integrated into existing infrastructure to boost ROI and reduce capital expenditure. Competitive intensity is projected to intensify as established players innovate and new entrants pursue niche markets, fostering a dynamic landscape. Regional growth potential remains high in Asia-Pacific, owing to rapid industrialization and supportive government policies, while North America and Europe will continue to emphasize sustainability initiatives and retrofit projects. Long-term, market maturity will hinge on evolving regulatory frameworks, technological advancements, and the balance between capital costs and operational savings, making strategic positioning vital for stakeholders to capitalize on upcoming opportunities while managing inherent risks.
