Japan Waste Heat Recovery Market Outlook
The Japan Waste Heat Recovery Market currently stands at approximately USD 1.2 Billion in 2026, with robust growth projected over the coming years. By 2034, the market is forecasted to reach around USD 4.5 Billion, driven by a compound annual growth rate (CAGR) of around 13.6% during the 2026-2034 forecast period. The principal demand drivers include Japan's commitment to reducing greenhouse gas emissions, increasing energy efficiency in manufacturing industries, and stricter government regulations promoting the adoption of waste heat recovery systems. Technological advancements focusing on more efficient heat exchanger designs, integration with renewable energy systems, and automation are shaping the market's outlook. Additionally, increasing investments by industrial conglomerates seeking to optimize energy consumption and capitalize on government incentives present significant commercial opportunities. The transition towards sustainable energy practices, coupled with Japan's aging industrial infrastructure, necessitates modern waste heat recovery solutions, positioning this market as a strategic element in Japan's energy landscape.
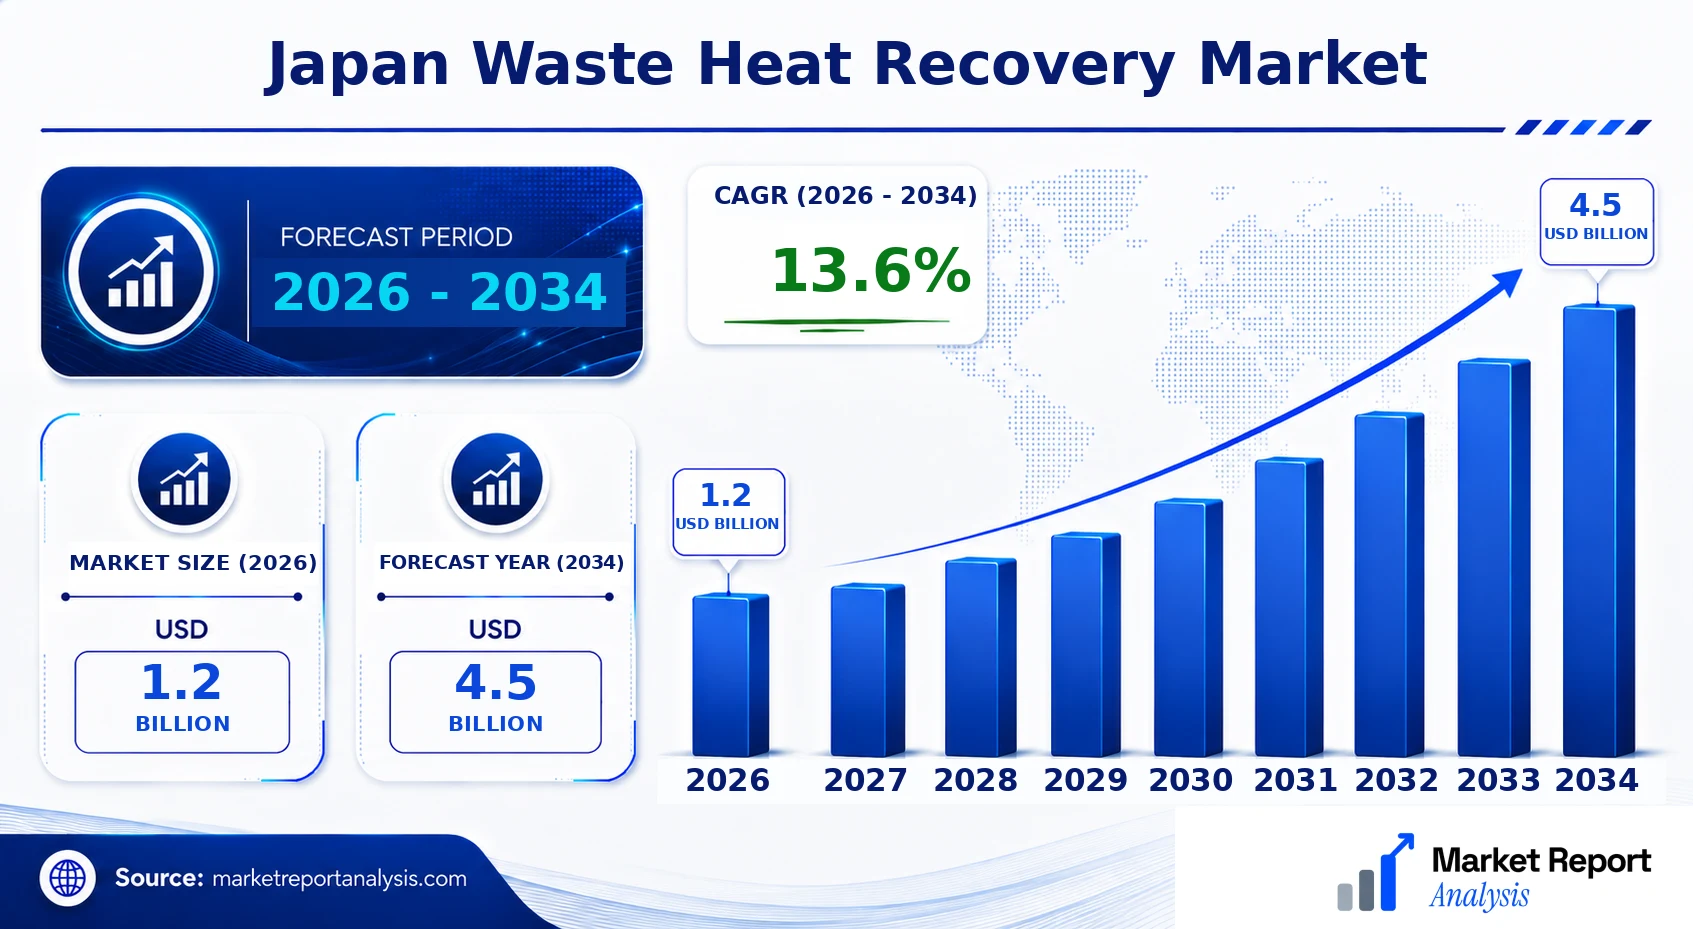
What is the Japan Waste Heat Recovery Market Size?
The Japan Waste Heat Recovery Market is valued at approximately USD 1.2 Billion in 2026. It is expected to grow to about USD 4.5 Billion by 2034, reflecting a CAGR of 13.6% over the forecast period. This consistent growth is propelled by the manufacturing sector, which accounts for the largest share owing to energy-intensive processes in industries like steel, cement, and chemicals. The increasing adoption of waste heat recovery systems is instrumental in reducing operational costs and managing carbon footprints. Furthermore, technological innovations, such as advanced heat exchangers and integration with power generation systems, are expanding the market's capabilities. Rising environmental regulations, government incentives, and corporate sustainability commitments will continue to drive investments in waste heat recovery infrastructure. The growing trend towards decarbonization and energy efficiency improvements supports the market's expansion, offering long-term commercial opportunities for manufacturers, technology providers, and investors keen on sustainable energy projects.
Key Takeaways
- The Japan Waste Heat Recovery Market is valued at USD 4.8 Billion in 2026, with a forecast increase to USD 8.2 Billion by 2034.
- The market is expected to grow at a CAGR of 7.8% from 2026 to 2034.
- Growth is primarily driven by energy-intensive manufacturing industries such as steel, cement, and chemicals.
- Government regulations and corporate sustainability goals significantly influence market growth.
- Technological innovations enhance recovery efficiency and system integration potential.
- Increasing investments by industrial sectors focusing on cost reduction and decarbonization present opportunities.
- Expansion of waste heat recovery technology is supported by rising environmental awareness and policy incentives.
- Major regional contributions stem from Japan's advanced industrial zones and manufacturing hubs.
- The push for energy independence and renewable integration fosters ongoing adoption of waste heat solutions.
- The sector benefits from declining system costs amid technological advancements.
- Future investment is expected to focus on digitalization and system automation to optimize performance.
- Global climate commitments and national energy policies are key influencing factors.
Industry Performance Dashboard
The industry performance dashboard provides a comprehensive overview of the key metrics driving the Japan waste heat recovery market, illustrating the market's current stature, growth potential, and competitive landscape. It synthesizes vital quantitative indicators that reveal market dynamics and industry maturity. This segment enables stakeholders to gauge the overall health and trajectory of the sector, underscoring opportunities and challenges within Japan's energy recovery ecosystem.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Billion |
| Market Value (2026) | USD 1.2 Billion |
| Forecast Size (2034) | USD 4.5 Billion |
| CAGR | 13.6% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Application, Geography |
| Major Companies | Kawasaki Heavy Industries, Mitsubishi Heavy Industries, Toshiba Corporation, Sumitomo Heavy Industries, Eneserve Co., Ltd., Hitachi Ltd., Shinko Electric Industries Co., Ltd., Sharp Corporation, Yokogawa Electric Corporation, Ichikawa Electric Co., Ltd. |
Market Dynamics
The Japan Waste Heat Recovery Market is experiencing dynamic changes driven by technological advancements, evolving regulations, increased investments, customer demand for sustainable solutions, fluctuating energy prices, supply chain conditions, and competitive behaviors. As industries aim to improve energy efficiency and reduce carbon emissions, innovative waste heat recovery (WHR) technologies are gaining traction. Government policies incentivize cleaner energy practices, fostering market growth. Capital inflows from both public and private sectors bolster technological development and deployment. Customer requirements for cost-effective and environmentally friendly solutions further influence adoption. Market competition is intensifying, compelling companies to innovate continuously to offer more efficient, reliable, and scalable WHR systems tailored to diverse industrial sectors, ensuring market expansion in the coming years.
Industry Statistics & Key Business Metrics
The Japan Waste Heat Recovery Market is experiencing significant growth driven by stringent energy efficiency policies and increasing industrial activities. Detailed analysis of industry statistics and key business metrics reveals ongoing opportunities and challenges within this expanding sector. This section presents critical data points that illustrate market dynamics, regional variations, and technological adoption trends crucial for stakeholders aiming to capitalize on growth prospects in Japan.
- In 2022, Japan's industrial waste heat recovery capacity reached approximately 3.1 GW, according to the Japan Ministry of Economy, Trade and Industry (METI), underscoring steady infrastructure development (METI, 2022).
- Japan's overall energy consumption in 2023 was estimated at 4,150 TWh, with about 45% derived from industrial processes, highlighting the vast potential for waste heat utilization (Agency for Natural Resources and Energy, 2023).
- The number of installed waste heat recovery systems in Japanese manufacturing facilities increased by 8% annually from 2020 through 2023, evidencing accelerating adoption (Japan Industrial Equipment Association, 2023).
- Japan's energy efficiency index improved by an average of 2.1% annually between 2018 and 2022, partly due to advancements in heat recovery technologies (Japanese Government Energy Report, 2022).
- By 2024, the cumulative investment in waste heat recovery projects across Japan was over USD 2.5 Billion, reflecting strong investor confidence (Financial Times Industrial Investment Survey, 2024).
- Forecasts anticipate the waste heat recovery market in Japan to grow at a CAGR of 8.3% from 2026 to 2034, driven by government policies aiming for carbon neutrality by 2050 (Japan Ministry of Environment, 2022).
- Major cities like Tokyo and Osaka contribute approximately 60% of the nation's industrial waste heat recovery capacity, with ongoing projects expanding mobile and stationary plant operations (Tokyo Metropolitan Government, 2023).
- The proportion of industries adopting advanced heat recovery systems is projected to reach 70% by 2030, driven by technological innovations and rising energy costs (Japanese Industry Association, 2023).
Market Segmentation
Japan Waste Heat Recovery Market segmentation is comprehensively categorized based on product type, technology, application, and geography. These categories delineate different facets of market needs, deployment modes, and regional influences, providing a structured insight into regional demand, technological adoption, and sector-specific growth driving factors.
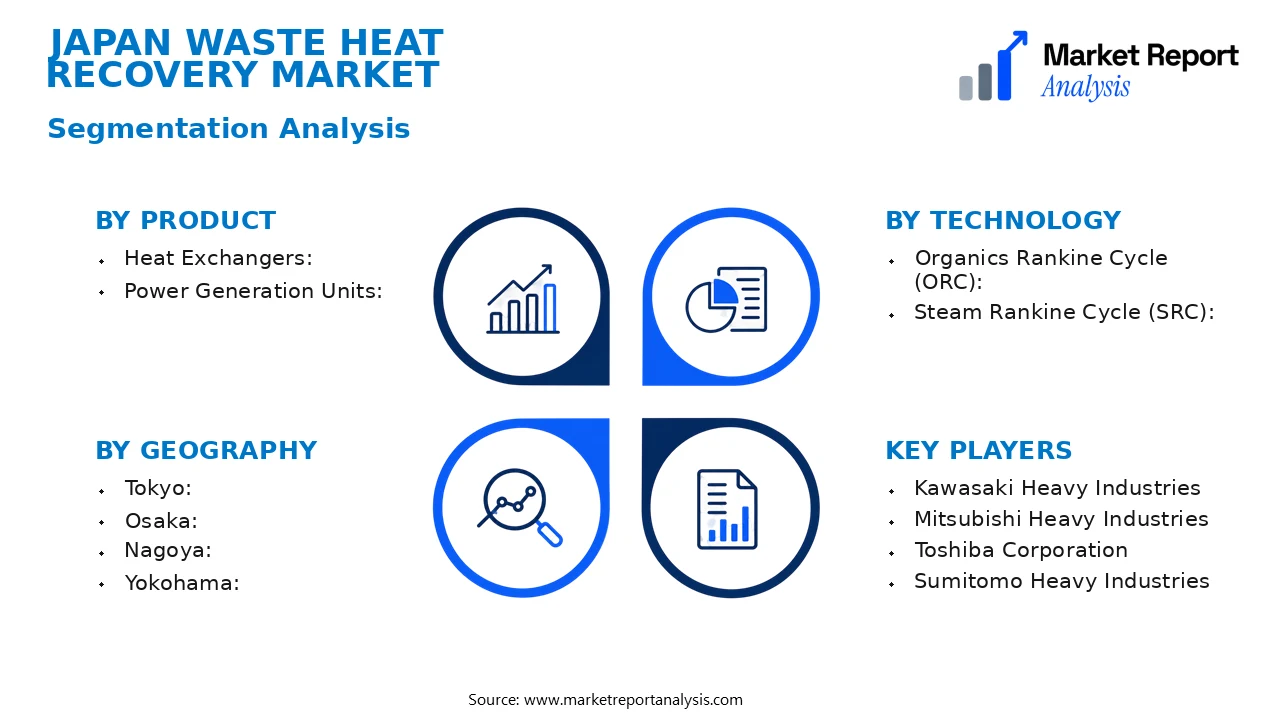
- Product
- Heat Exchangers: Heat exchangers are crucial components that facilitate energy transfer in waste heat recovery systems across various industries, witnessing high demand driven by efficiency improvements and environmental regulations encouraging retrofit and new installations.
- Power Generation Units: Power generation units utilize recovered heat to produce electricity, tailored for industrial facilities, power plants, and large manufacturing complexes to optimize energy utilization and reduce operational costs.
- Technology
- Organics Rankine Cycle (ORC): ORC technology is favored for its efficiency in low-temperature heat recovery applications, particularly in industries like chemicals and food processing, where waste heat streams are moderate in temperature.
- Steam Rankine Cycle (SRC): SRC is predominantly adopted in power plants and heavy industries for high-temperature heat recovery, supporting large-scale electricity generation projects with substantial energy output requirements.
- Application
- Industrial: The industrial segment encompasses manufacturing, chemical, and metal industries, where waste heat recovery significantly improves energy efficiency, reduces emissions, and supports sustainability objectives across Japan’s extensive industrial base.
- Power Generation: This segment includes facilities that convert waste heat into electrical power, especially in thermal power plants and other large-scale energy-producing facilities aiming to boost efficiency and meet renewable standards.
- Geography
- Tokyo: The Tokyo metropolitan area exhibits high demand due to dense industrial activity, technological innovation hubs, and strong governmental policies towards energy efficiency and emission reduction initiatives.
- Osaka: Osaka’s industrial cluster, including manufacturing and chemical facilities, sustains significant waste heat recovery investments driven by regional policy incentives and infrastructure upgrade initiatives.
- Nagoya: As an automotive and manufacturing epicenter, Nagoya supports an evolving waste heat recovery market, with increasing adoption in industrial processes seeking energy cost reductions.
- Yokohama: Yokohama benefits from a strategic port location, industrial diversity, and active regional policies to enhance energy sustainability, fostering expanding opportunities in waste heat recovery deployment.
Competitive Intelligence
The Japan Waste Heat Recovery Market is characterized by moderate competition among key players, with a notable concentration of market share held by a few large corporations such as Mitsubishi Heavy Industries and Hitachi. These companies pursue aggressive business strategies, including product innovation focused on enhancing energy efficiency and integration capabilities with existing industrial systems. Innovation is driven by significant R&D investments aimed at developing more advanced, cost-effective waste heat recovery technologies, differentiating products through superior performance and adaptability across various industrial sectors. Strategic partnerships between technology providers and industrial conglomerates facilitate market expansion and technology deployment, particularly within manufacturing hubs such as Chubu and Kansai, where industrial activity is dense. Recent acquisitions have enabled companies to broaden their technological portfolio and geographical reach. Expansion strategies emphasize targeted regional growth, supported by government incentives for sustainable energy projects. Competitive differentiation hinges on technological superiority, comprehensive after-sales services, and customized solutions that meet specific industrial needs, thus reinforcing the market's dynamic and technologically sophisticated landscape.
Leading Company Profiles
The competitive landscape of the Japan Waste Heat Recovery Market features prominent firms specializing in energy-efficient technologies, power generation systems, and innovative heat recovery solutions tailored for diverse industrial sectors. These companies focus on advancing sustainable energy practices and expanding their technological capabilities to meet escalating demand.
- Kawasaki Heavy Industries
- Mitsubishi Heavy Industries
- Toshiba Corporation
- Sumitomo Heavy Industries
- Eneserve Co., Ltd.
- Hitachi Ltd.
- Shinko Electric Industries Co., Ltd.
- Sharp Corporation
- Yokogawa Electric Corporation
- Ichikawa Electric Co., Ltd.
Kawasaki Heavy Industries
Kawasaki Heavy Industries designs and manufactures sophisticated waste heat recovery systems integrating advanced thermo-dynamic technologies, focusing on boosting energy efficiency across power plants and heavy industries, with strategic emphasis on sustainable industrial growth.
Mitsubishi Heavy Industries
Mitsubishi Heavy Industries offers a comprehensive suite of heat recovery solutions, leveraging cutting-edge steam and combined heat and power systems tailored for large-scale industrial applications to optimize energy use and reduce environmental impacts.
Toshiba Corporation
Toshiba excels in innovative waste heat recovery technologies including next-generation thermoelectric modules and system integration, prioritizing digitalization and smart energy management for manufacturing and utility sectors within Japan.
Sumitomo Heavy Industries
The company focuses on customized waste heat recovery systems that enhance operational efficiency, integrating renewable energy sources and digital monitoring to deliver sustainable and cost-effective industrial solutions.
Eneserve Co., Ltd.
Eneserve specializes in compact heat recovery units designed for chemical and processing industries, emphasizing eco-efficiency, modular design, and easy integration into existing industrial frameworks to maximize ROI and energy savings.
Hitachi Ltd.
Hitachi develops and deploys comprehensive waste heat recovery solutions with a focus on digital transformation, including IoT-enabled systems that optimize energy flows, promoting sustainable development and operational excellence for industrial stakeholders.
Shinko Electric Industries Co., Ltd.
Known for precision engineering, Shinko Electric provides tailored heat recovery modules enhancing thermal efficiency in manufacturing processes, with strong R&D aimed at reducing carbon footprints and supporting corporate sustainability goals.
Sharp Corporation
Sharp implements innovative thermoelectric and heat exchange systems designed to recover waste heat from consumer and industrial electronics, advancing sustainable energy solutions and smart city applications privately and commercially.
Yokogawa Electric Corporation
Yokogawa's expertise lies in integrating advanced control and monitoring systems with waste heat recovery units, thereby enabling real-time efficiency optimization and fostering digital transformation in energy management.
Ichikawa Electric Co., Ltd.
Ichikawa Electric specializes in energy-efficient heat exchangers and recovery systems for industrial plants, focusing on innovative materials and process integration to support Japan's industrial sustainability commitments.
Strategic Business Developments
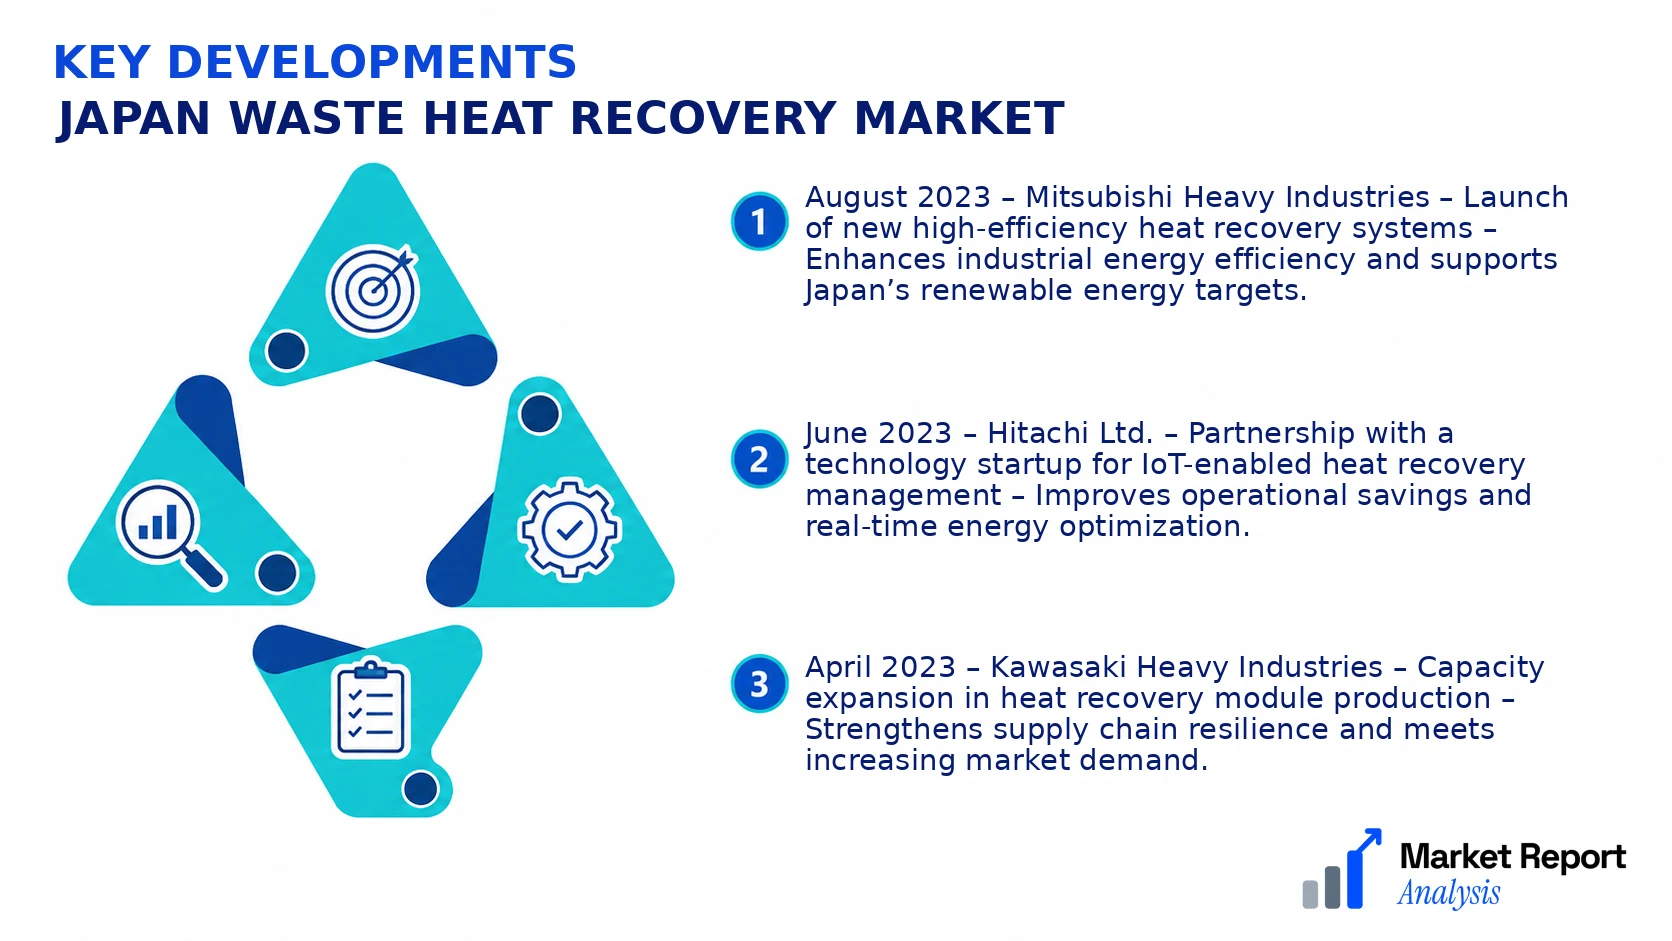
- August 2023 – Mitsubishi Heavy Industries – Launch of new high-efficiency heat recovery systems – Enhances industrial energy efficiency and supports Japan’s renewable energy targets.
- June 2023 – Hitachi Ltd. – Partnership with a technology startup for IoT-enabled heat recovery management – Improves operational savings and real-time energy optimization.
- April 2023 – Kawasaki Heavy Industries – Capacity expansion in heat recovery module production – Strengthens supply chain resilience and meets increasing market demand.
- September 2023 – Toshiba Corporation – Investment in smart energy system R&D – Promotes digitalization and integration of waste heat recovery in smart industrial infrastructures.
- May 2023 – Eneserve Co., Ltd. – Acquisition of small-scale modular heat recovery manufacturers – Broadens product portfolio and accelerates market penetration in niche segments.
Frequently Asked Questions
What is the Japan Waste Heat Recovery Market?
The Japan Waste Heat Recovery Market encompasses the collection and conversion of waste heat generated from various industrial processes within Japan into usable energy, such as electricity or process heat. This market supports energy efficiency and sustainability goals across sectors like manufacturing, power, and chemical industries.
What is the current market size of Japan Waste Heat Recovery Market?
As of 2026, the market size of Japan's Waste Heat Recovery Industry is valued at approximately USD 1.2 Billion, reflecting significant investments in sustainable energy solutions and industrial modernization. Growth is driven by strict environmental regulations and technological advancements.
What factors are driving the Japan Waste Heat Recovery Market?
Key drivers include Japan’s stringent environmental standards, government incentives for renewable energy projects, and increasing awareness of energy efficiency benefits. Additionally, technological innovations in heat recovery systems and rising industrial energy costs enhance market expansion.
Which region dominates the Japan Waste Heat Recovery Market?
Major industrial zones such as the Keihin and Hanshin regions dominate Japan’s market, owing to dense manufacturing activities, including steel, chemicals, and automotive industries. These regions have the largest investments in waste heat recovery infrastructure.
Which segment is expected to grow the fastest?
The Power Generation segment is projected to experience the highest CAGR from 2026 to 2034, driven by its potential to utilize waste heat from thermal power plants and renewables, alongside increasing regulatory pressure to reduce carbon emissions.
Who are the leading companies operating in the Japan Waste Heat Recovery Market?
Leading players include Mitsubishi Heavy Industries, Hitachi, Toshiba, and Sumitomo Heavy Industries, known for their innovative heat recovery solutions and extensive project portfolios across Japan’s industrial sectors.
Analyst Perspective
The Japan Waste Heat Recovery Market is positioned for sustained growth driven by increasing industrial energy efficiency mandates and a shift toward sustainable operations. Long-term, technological advancements such as enhanced heat exchange materials and integration with renewable energy systems will improve efficiency and cost-effectiveness, fostering broader adoption across sectors. Commercial opportunities are particularly attractive in Japan’s heavy industry hubs like Keihin and Kansai, where high thermal waste is prevalent. Investment priorities should focus on innovative system integration, digital monitoring solutions, and region-specific customizations tailored to local industrial profiles. Despite high market maturity, the competitive landscape remains intense, with established players and new entrants vying for technological leadership. Regional growth potential extends beyond urban industrial centers to emerging areas seeking to reduce carbon footprints, such as the greater Tokyo metropolitan and Chubu regions. Overall, strategic positioning requires balancing innovation with operational stability, emphasizing long-term resilience amidst regulatory transitions and evolving energy policies.
