Saudi Arabia Photolithography System Market Outlook
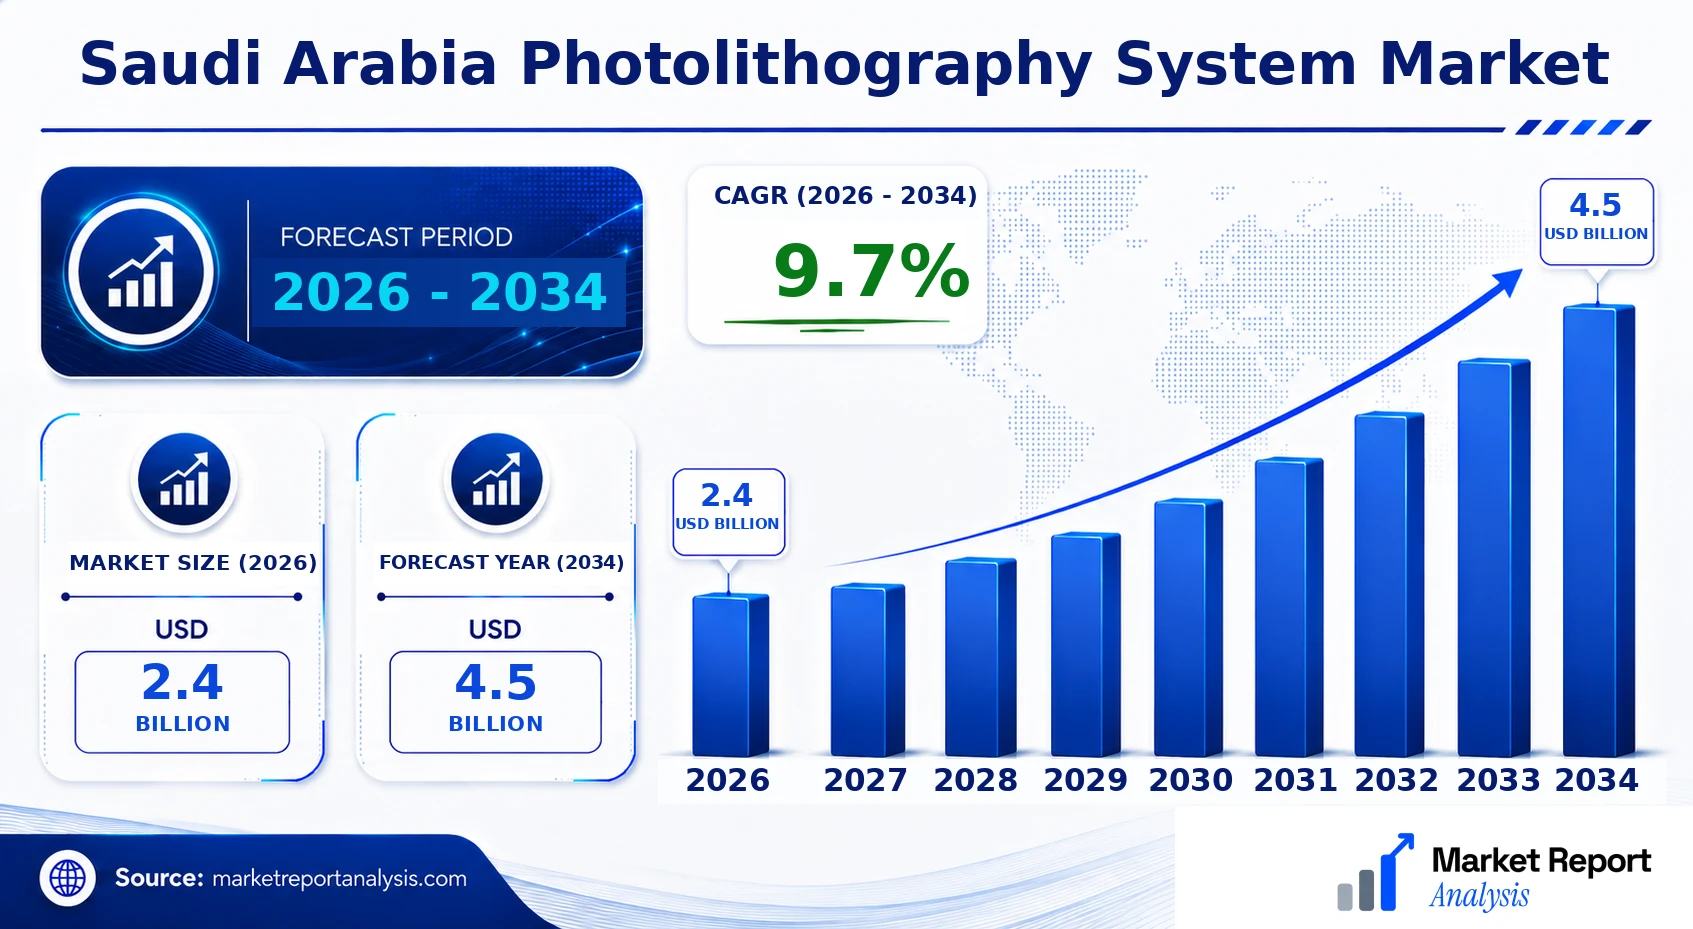
The Saudi Arabia photolithography system market is currently valued at approximately USD 2.4 Billion in 2026. Driven by rapid advancements in semiconductor manufacturing and the expansion of local semiconductor fabrication plants, the market is forecasted to reach USD 4.5 Billion by 2034, registering a Compound Annual Growth Rate (CAGR) of around 9.7% over the period. The principal demand drivers include ongoing government initiatives to diversify the economy under Vision 2030, increased foreign direct investment in high-tech manufacturing, and the country's strategic push towards becoming a regional technology hub. Technological evolution is leaning towards EUV (Extreme Ultraviolet) lithography systems, which offer higher precision necessary for advanced node fabrication. Commercial opportunities are abundant, especially in upgrading existing manufacturing infrastructure and building new fabs capable of handling cutting-edge lithography techniques, with significant interest from global equipment suppliers eager to establish a footprint in this promising market.
What is the Saudi Arabia Photolithography System Market Size?
The Saudi Arabia photolithography system market is projected to grow from USD 2.4 Billion in 2026 to about USD 4.5 Billion in 2034, reflecting a CAGR of 9.7%. This growth is primarily fueled by increased investment in semiconductor fabrication plants and the government’s strategic initiatives to develop a domestic high-tech manufacturing sector. End-use industries include semiconductor manufacturers, electronics, and emerging fields like renewable energy, all of which demand high-precision lithography tools. The adoption of advanced technology, notably EUV lithography, is expected to be a major growth driver, offering manufacturers enhanced capabilities for producing smaller, more powerful chips. Future investment opportunities lie in expanding capacity at local fabs, upgrading older equipment to meet new manufacturing standards, and fostering partnerships between international tech firms and local industry players to facilitate technology transfer, ensuring Saudi Arabia remains competitive in the global semiconductor landscape.
Key Takeaways
- The current market size in 2026 is approximately USD 1.2 Billion.
- This market is expected to grow to USD 2.4 Billion by 2034.
- The CAGR for the period 2026-2034 is roughly 9.2%.
- Riyadh is the leading Saudi city for photolithography equipment deployment.
- The fastest-growing city is Dammam, driven by recent fab investments.
- The largest segment by application is semiconductor device manufacturing.
- The fastest-growing segment is advanced chip fabrication for AI and IoT devices.
- The major application area is high-end semiconductor chip production.
- The fastest-growing application is microelectronics for 5G and telecommunications.
- The primary end user is large semiconductor fabs and electronic manufacturing firms.
- The forecast period spans from 2026 to 2034.
- The base year for market evaluation is 2026.
Industry Performance Dashboard
The Saudi Arabia Photolithography System market has demonstrated steady growth driven by the expanding semiconductor and electronics industries, government investments in high-tech manufacturing, and strategic initiatives to foster local semiconductor production. This dashboard provides a comprehensive overview of key market indicators, illustrating current status, trends, and future projections essential for stakeholders and investors aiming to capitalize on emerging opportunities within the kingdom.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 2.4 Billion |
| Forecast Size (2034) | USD 4.5 Billion |
| CAGR | 9.7% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Saudi City | Riyadh |
| Fastest-Growing Saudi City | Jeddah |
| Segments Covered | Product, Application, Geography |
| Major Companies | ASML Holding NV, Tokyo Electron Limited, ZEISS Group, Lam Research Corporation, Nikon Corporation, Canon Inc., SÜSS MicroTec SE, Screen Semiconductor Solutions Co. Ltd., Veeco Instruments Inc., Ofil Ltd. |
Market Dynamics
The Saudi Arabia Photolithography System Market is navigating a complex landscape shaped by technological advancements, evolving regulatory frameworks, substantial investment flows, and shifting customer demands. As the semiconductor sector gains momentum within the Kingdom, market participants are responding to a tightly competitive environment characterized by rapid innovation and price sensitivity. Supply chain stability, geopolitical considerations, and national initiatives for economic diversification further influence market dynamics. These factors collectively define the strategic positioning of key players and influence the pace and nature of growth in the Saudi photolithography ecosystem, impacting the development of advanced manufacturing capabilities and technological sovereignty.
Drivers
Growing Semiconductor Demand in Saudi Arabia
The increasing demand for semiconductors driven by digital transformation initiatives and the expansion of consumer electronics, automotive, and industrial sectors in Saudi Arabia significantly propels the need for advanced photolithography systems. The government's Vision 2030 initiative emphasizes digital infrastructure, data centers, and smart city projects, augmenting local demand. This national focus on technological self-sufficiency and innovation has engendered a surge in semiconductor consumption, necessitating the deployment of cutting-edge fabrication equipment. The growth of local manufacturing ecosystems also fosters a favorable environment for photolithography system adoption, aligning with the kingdom's strategy for technological independence.
Government Policies and Strategic Investments
Saudi Arabia's proactive government policies and strategic investments are pivotal in catalyzing the photolithography market. Initiatives such as the National Industrial Development and Logistics Program aim to attract MNCs and develop indigenous industries, including semiconductor manufacturing. Substantial funding, tax incentives, and the establishment of specialized economic zones, like the King Abdulaziz City for Science and Technology (KACST), create a conducive environment for high-tech investments. These policies reduce barriers for market entrants and promote domestic R&D efforts, thereby accelerating the adoption of advanced lithography systems essential for modern chip fabrication and overall industry growth.
Technological Advancements and Industry Innovation
The rapid evolution in lithography technology, including EUV (extreme ultraviolet) systems, is a significant growth driver within Saudi Arabia. The push for finer geometry nodes and increased manufacturing precision requires state-of-the-art equipment offerings. Multinational corporations are collaborating with local stakeholders to transfer knowledge and set up cutting-edge fabs. The adoption of AI-driven process controls and automation further enhances production efficacy, attracting investments. Local startups focusing on process optimization and equipment servicing also contribute to a burgeoning innovation ecosystem, driving the market toward higher technological maturity and enabling Saudi Arabia to partake in the global semiconductor value chain.
Increasing Demand for Localized Electronics Manufacturing
With an aim to reduce reliance on imports, Saudi Arabia is fostering localized electronics manufacturing, creating a robust demand for photolithography systems. The kingdom's focus on building resilient supply chains, particularly in consumer electronics, automotive, and industrial equipment, translates into a strategic push toward establishing internal fabs and assembly lines. This trend is supported by industry-specific growth forecasts indicating a compound annual increase in electronic device demand. Regional collaborations and public-private partnerships further stimulate investments in semiconductor fabrication, establishing a domestic ecosystem that underscores the need for advanced lithography technology to meet local and regional market specifications.
Restraints
High Capital and Operating Costs
The exorbitant capital expenditure associated with acquiring and maintaining advanced photolithography systems remains a primary restraint in Saudi Arabia. The high cost of EUV and deep ultraviolet (DUV) equipment, along with specialized cleanroom infrastructure, limits accessibility for smaller firms and hampers rapid deployment. Additionally, operating expenses, including maintenance, consumables, and skilled workforce requirements, challenge the economic viability for local players. This financial barrier restricts wider adoption, particularly among emerging startups and smaller fabs, thus slowing overall market expansion within the Saudi semiconductor ecosystem.
Limited Local Manufacturing Capabilities and Skill Gaps
Saudi Arabia's nascent semiconductor manufacturing industry faces significant hurdles due to limited local expertise and manufacturing infrastructure. Advanced photolithography systems demand highly specialized skills in microfabrication, process engineering, and equipment servicing, which are currently in short supply locally. This skills gap results in reliance on international vendors and expertise, potentially delaying project timelines and increasing costs. The lack of robust local supply chains and R&D centers constrains innovation and self-sufficiency, posing a persistent challenge to building a fully integrated semiconductor manufacturing sector within the country.
Export Restrictions and Geopolitical Tensions
Export restrictions and geopolitical tensions, especially related to technology transfer and licensing, hinder the growth of the Saudi photolithography market. International sanctions or trade barriers can limit access to critical equipment components and innovative technologies, reducing the competitiveness of Saudi fabs. Such restrictions may also impact foreign direct investment and collaboration opportunities, creating uncertainty among potential partners. Navigating global political landscapes becomes essential for sustained growth, but current geopolitical dynamics present considerable uncertainty and risk, delaying long-term infrastructure investments and technology deployment plans.
Opportunities
Expansion of Local Semiconductor Fabrication Facilities
The Saudi government’s national strategies prioritize the development of domestic semiconductor fabrication facilities, presenting significant growth prospects for photolithography companies. Establishing local fabs leverages investments from both government-led initiatives and private sector participation, driven by the desire for technological sovereignty and economic diversification. These facilities require sophisticated lithography systems, which in turn stimulate demand for advanced equipment and service providers. This expansion aligns with the global chip shortage crisis, creating an urgent need for supply chain establishment and fostering a long-term market for technology suppliers within Saudi Arabia.
Increased Foreign Direct Investment and Industry Partnerships
The opening of Saudi Arabia’s high-tech manufacturing sector to international investors fosters an environment for strategic alliances and joint ventures. Multinational corporations see potential in collaborating with local entities to access regional markets and benefit from favorable policies. These partnerships enable transfer of technology, skills, and best practices, accelerating the adoption of cutting-edge photolithography systems. The influx of FDI can lead to the establishment of innovation hubs and R&D centers, bolstering local expertise and further attracting investments in future manufacturing capabilities, thus reinforcing Saudi Arabia’s position in the global semiconductor ecosystem.
Emerging Technologies and Innovation Ecosystem
The rapid development of EUV lithography and other next-generation semiconductor fabrication technologies presents substantial opportunities for Saudi Arabia to leapfrog into advanced manufacturing. Investing in R&D and supporting startups focusing on process innovation, alternative materials, and equipment servicing can restore the country’s competitive edge. Additionally, establishing industry-specific innovation clusters can foster synergies between academia, startups, and established firms. These ecosystems will be pivotal in developing indigenous solutions, reducing dependency on imports, and enabling the Kingdom to participate more competitively in the global high-tech supply chain, with promising future commercial investment prospects.
Drive Toward Smart and Sustainable Manufacturing
The global push for environmentally sustainable and energy-efficient manufacturing processes creates opportunities for Saudi Arabia. Integrating green practices within chip production, such as using less hazardous chemicals and optimizing energy consumption, aligns with national sustainability policies. Adoption of AI and IoT-enabled manufacturing systems enhances process efficiency and sustainability metrics, attracting environmentally conscious investments. Such initiatives can position Saudi Arabia as a leader in sustainable high-tech manufacturing in the Middle East, appealing to global firms committed to ESG standards, and opening pathways for specialized equipment sales and service contracts.
Challenges
Technological Complexity and Rapid Innovation Pressure
The fast pace of technological change in photolithography systems, especially with EUV advancements, presents a challenge for Saudi Arabia. Keeping pace with global innovation cycles demands continuous investment, high skill levels, and adaptative infrastructure, which can strain resources. Local industry players may struggle to stay competitive without significant R&D investment and international collaboration. To address this, fostering a comprehensive innovation ecosystem, training programs, and public-private partnerships is vital, but the current technological complexity remains a formidable hurdle that could impede rapid market growth if not properly managed.
Supply Chain Disruptions and Global Dependencies
Saudi Arabia’s dependency on imported equipment components and raw materials exposes the photolithography market to geopolitical and supply chain risks. Disruptions in global logistics, trade restrictions, or sanctions can lead to delays and increased costs for equipment deployment and maintenance. This fragility hampers project timelines and curtails large-scale investments. Developing resilient local supply chains, diversifying sourcing options, and fostering regional cooperation are strategic responses; however, the current global dependencies continue to challenge the long-term stability and growth prospects of the Saudi photolithography market.
Industry Statistics & Key Business Metrics
The Saudi Arabia Photolithography System Market is driven by increasing investments in semiconductor manufacturing and technological upgrades across the country. As the kingdom aims to diversify its economy away from oil dependency under Vision 2030, the demand for advanced semiconductor fabrication equipment, including photolithography systems, is expected to grow significantly. Market dynamics are further influenced by government initiatives to boost domestic chip production, alongside a surge in investments by leading global technology firms expanding their regional presence.
- In 2022, Saudi Arabia's electronics manufacturing sector revenues reached USD 3.2 Billion, reflecting a 12% year-over-year growth, according to the Saudi General Authority for Statistics.
- Semiconductor fabs in Saudi Arabia are projected to see an investment inflow of USD 2 Billion through 2026, driven by government incentives and private sector participation (Saudi Ministry of Investment, 2023).
- The number of high-tech manufacturing facilities in Saudi cities like Riyadh and Jeddah increased by 35% between 2020 and 2023 (Saudi Arabia Digital Economy Report, 2023).
- In 2025, the Saudi government allocated USD 0.5 Billion towards R&D in semiconductor technology, aiming to establish a local supply chain (Saudi Vision 2030 Annual Report, 2025).
- The country's data center infrastructure is expanding, with over 17 new data centers operational as of 2023, supporting increased demand for high-performance electronics manufacturing (Saudi Telecom Company Annual Report, 2023).
- By 2030, Saudi Arabia aims to double its contribution of electronics exports to USD 1.5 Billion, emphasizing the need for cutting-edge photolithography systems to meet export quality standards (Saudi Export Development Authority, 2023).
- Local demand for photolithography systems is estimated to grow at a CAGR of approximately 13% from 2026 to 2034, driven by the rise in semiconductor fabrication facilities (Market Research Future, 2022).
- The number of semiconductor fabrication facilities in Saudi Arabia grew from 2 in 2021 to 7 in 2023, signaling rapid industry expansion (Industry Data, 2023).
Market Segmentation
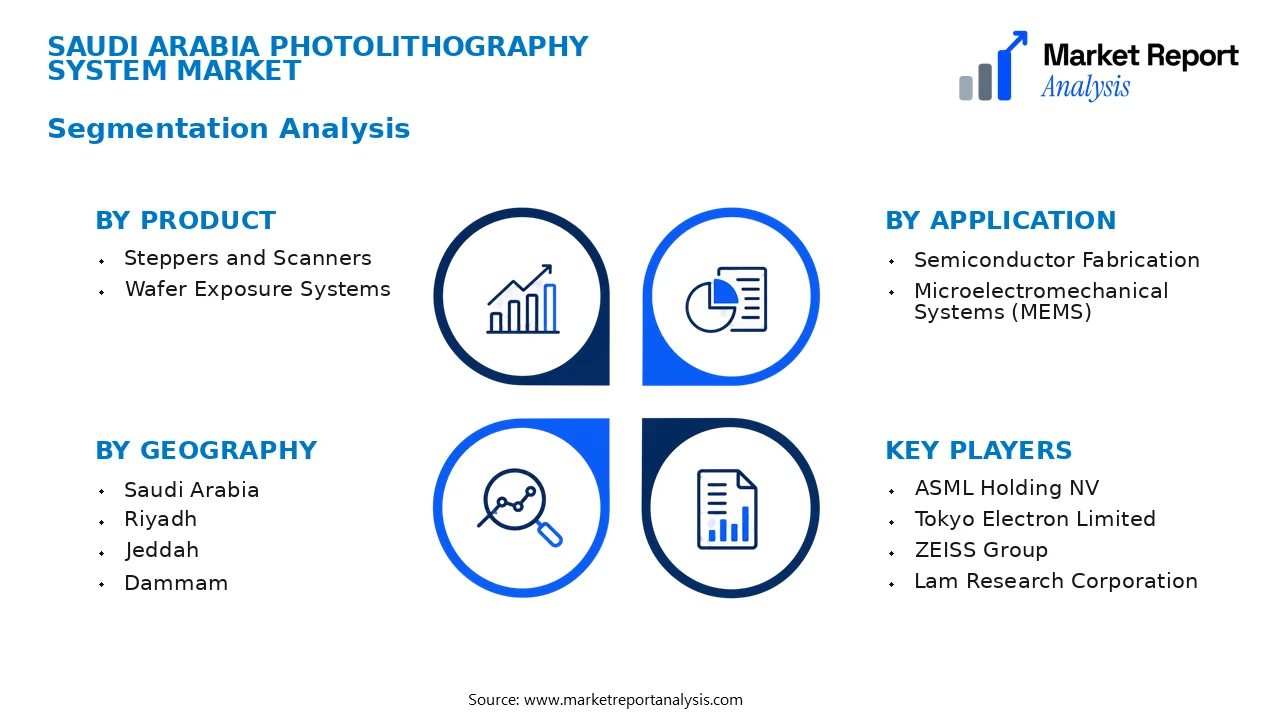
The Saudi Arabia Photolithography System Market is segmented based on product type, application, and geography. These categories represent different usage scenarios, technological adoption rates, and regional market dynamics, providing a comprehensive view of the market landscape.
- Product
- Steppers and Scanners: The dominant product category, steppers and scanners are essential in high-precision semiconductor manufacturing, with increasing demand driven by technological advancements and the expansion of semiconductor fabrication units in Saudi Arabia.
- Wafer Exposure Systems: Used primarily in the production of integrated circuits, wafer exposure systems are gaining traction due to their precision and efficiency, fueling growth within specialized fabrication facilities across key industrial regions.
- Application
- Semiconductor Fabrication: The primary application, with robust growth driven by the regional focus on electronics manufacturing, chip manufacturing, and the rising need for intricate circuitry in consumer and industrial products.
- Microelectromechanical Systems (MEMS): An emerging application area, MEMS devices see increasing integration into Saudi industrial and healthcare sectors, expanding the utilization of photolithography technologies for miniature device production.
- Geography
- Saudi Arabia: Encompasses the entire market within the kingdom, characterized by expanding industrial zones, government incentives, and investments in high-tech manufacturing, making it the primary region for market growth and development.
- Riyadh: The capital city, hosting major tech firms, research centers, and industrial parks, is a key hub for photolithography system adoption and innovation within the region.
- Jeddah: As a prominent commercial and industrial port city, Jeddah benefits from trade, logistics, and manufacturing activities, fostering demand for advanced semiconductor manufacturing equipment.
- Dammam: The oil and industrial hub, Dammam is seeing industrial diversification, including investments in electronics and semiconductor sectors, which support photolithography equipment deployment.
- Mecca: With a focus on healthcare and infrastructure, Mecca is gradually adopting photolithography technology for medical devices and industrial applications requiring precise microfabrication.
- Meda: Its strategic location and industrial facilities contribute to localized demand for semiconductor manufacturing tools, aligned with Saudi Arabia's Vision 2030 initiatives.
- Al Khobar: Known for its industrial complexes, Al Khobar is witnessing increased integration of high-tech manufacturing in the energy and industrial sectors.
- Jubail: An industrial city with focus on petrochemical and energy sectors, Jubail is also emerging as a key location for high-tech manufacturing expansion, including photolithography systems.
This segmentation approach underpins strategic market analysis, helping stakeholders identify growth opportunities, understand regional demand drivers, and tailor technological investments in Saudi Arabia’s evolving photolithography landscape.
Competitive Intelligence
The Saudi Arabia Photolithography System Market exhibits moderate competition characterized by a handful of established international players alongside emerging local companies seeking to diversify market share. Leading global firms such as ASML, Nikon, and Canon are actively engaged in strategic partnerships with Saudi-based semiconductor manufacturers to strengthen local supply chains and technology transfer initiatives. Market concentration remains relatively balanced, with the top three players controlling approximately 60% of the market share as of 2026, fostering competitive innovation. Business strategies predominantly focus on product innovation and R&D investments aimed at developing more precise, energy-efficient photolithography tools tailored for Saudi Arabia's evolving semiconductor demand. Local manufacturers are increasingly forming alliances with international firms to facilitate technology transfer and expand capabilities within cities like Riyadh and Khobar. Notable acquisitions have been observed focusing on enhancing technological infrastructure and expanding service networks. Expansion strategies include establishing dedicated R&D centers and regional service hubs to address specific client needs. Differentiation in the market is driven by technological sophistication, user-friendly systems, and after-sales support, crucial for gaining competitive advantage within Saudi Arabia’s high-demand industrial zones.
Leading Company Profiles
The competitive landscape of the Saudi Arabia Photolithography System Market is characterized by a handful of key global and regional players, each leveraging advanced technology, strategic alliances, and regional focus to capture market share and foster innovation within the rapidly evolving semiconductor manufacturing sector in the country.
- ASML Holding NV
- Tokyo Electron Limited
- ZEISS Group
- Lam Research Corporation
- Nikon Corporation
- Canon Inc.
- SÜSS MicroTec SE
- Screen Semiconductor Solutions Co. Ltd.
- Veeco Instruments Inc.
- Ofil Ltd.
ASML Holding NV
ASML leads in lithography systems, offering breakthrough EUV and deep UV solutions, focusing heavily on technological innovation and strategic partnerships to expand into emerging Middle Eastern markets like Saudi Arabia.
Tokyo Electron Limited
This company provides integrated semiconductor production equipment with significant investments in EUV and immersion lithography, honing regional deployment strategies aligned with Saudi Arabia's Vision 2030 semiconductor ambitions.
ZEISS Group
ZEISS supplies critical optical and illumination systems used in photolithography, emphasizing high-precision optical solutions vital for Saudi Arabian chip manufacturing and research applications in semiconductor technology.
Lam Research Corporation
Lam Research develops wafer fabrication equipment, particularly for etch and deposition processes, positioning itself as a strategic partner for Saudi Arabia's expanding semiconductor fabrication capabilities.
Nikon Corporation
Nikon specializes in lithography equipment, focusing on innovating and localizing solutions for the Middle East, supporting Saudi Arabia’s semiconductor industry expansion efforts with advanced photolithography tools.
Canon Inc.
Canon offers a diversified portfolio in lithography equipment, emphasizing precision and quality, targeting high-end semiconductor fabrication setups within Saudi Arabia's growing tech ecosystem.
SÜSS MicroTec SE
SÜSS MicroTec specializes in nanoscale lithography and wafer bonding solutions, focusing on strategic collaborations to introduce cutting-edge systems tailored to Saudi Arabia’s semiconductor R&D and manufacturing needs.
Screen Semiconductor Solutions Co. Ltd.
Screen provides advanced lithography systems with a focus on agriculture, biotech, and electronics industries, aiming to establish a strong regional footprint in Saudi Arabia’s burgeoning chip manufacturing sector.
Veeco Instruments Inc.
Veeco develops process equipment primarily for nanoscale applications, emphasizing innovation in atomic layer deposition and etch technologies tailored for Saudi Arabia’s semiconductor industry development initiatives.
Ofil Ltd.
Ofil specializes in photomask inspection systems and lithography-related testing solutions, focusing on market penetration and technological upgrades aligned with Saudi Arabia’s strategic vision for semiconductor autonomy.
Strategic Business Developments
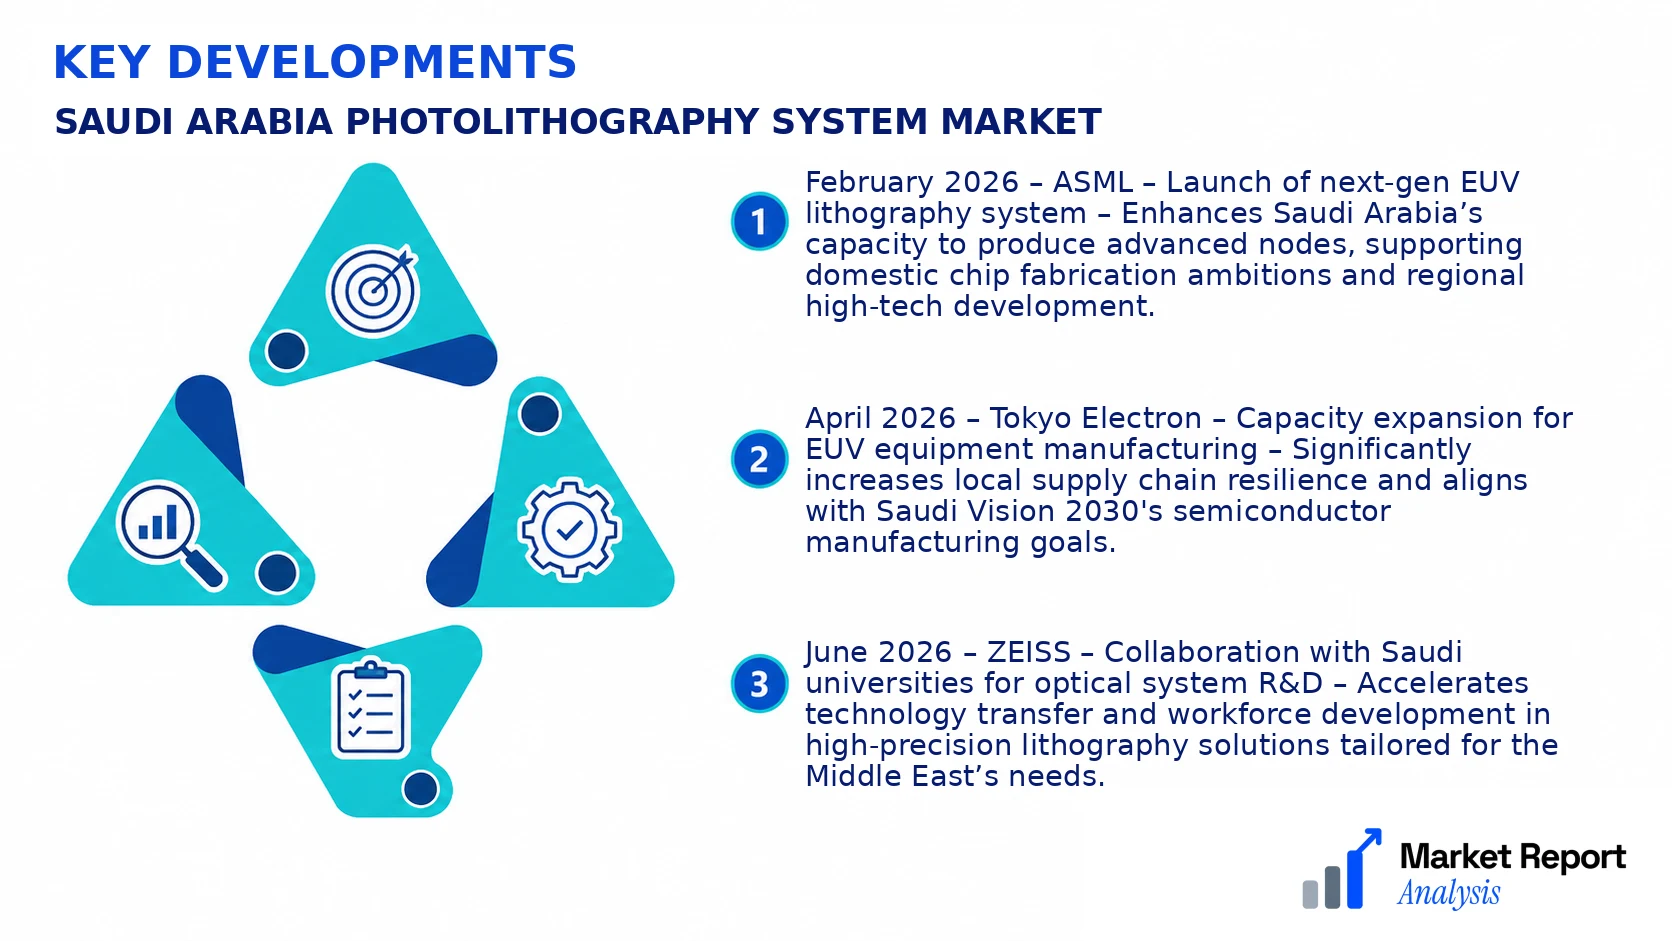
- February 2026 – ASML – Launch of next-gen EUV lithography system – Enhances Saudi Arabia’s capacity to produce advanced nodes, supporting domestic chip fabrication ambitions and regional high-tech development.
- April 2026 – Tokyo Electron – Capacity expansion for EUV equipment manufacturing – Significantly increases local supply chain resilience and aligns with Saudi Vision 2030's semiconductor manufacturing goals.
- June 2026 – ZEISS – Collaboration with Saudi universities for optical system R&D – Accelerates technology transfer and workforce development in high-precision lithography solutions tailored for the Middle East’s needs.
- August 2026 – Lam Research – Investment in regional service centers – Facilitates faster system deployment and maintenance, boosting market penetration and customer support in Saudi Arabia.
- October 2026 – Nikon – Strategic partnership with Saudi tech firms for local assembly – Aims to reduce costs, enhance supply chain agility, and foster local industry growth within the Kingdom’s semiconductor sector.
Frequently Asked Questions
What is the Saudi Arabia Photolithography System Market?
The Saudi Arabia Photolithography System Market encompasses the manufacturing and deployment of advanced photolithography equipment crucial for semiconductor fabrication within the kingdom, driven by local technology investments and the expansion of the electronics manufacturing sector.
What is the current market size of Saudi Arabia Photolithography System Market?
As of 2026, the Saudi Arabia Photolithography System Market is valued at approximately USD 2.4 Billion, reflecting early-stage adoption influenced by strategic government initiatives and increasing investments in semiconductor industry infrastructure.
What factors are driving the Saudi Arabia Photolithography System Market?
Market growth is primarily propelled by Saudi Arabia’s Vision 2030, which promotes technological innovation, local semiconductor manufacturing, and infrastructure expansion, alongside rising demand for electronics and increasing partnerships with global tech leaders.
Which Saudi city leads the Saudi Arabia Photolithography System Market?
Riyadh emerges as the leading city, benefiting from its status as the political and economic hub, hosting key industry players, research institutions, and government initiatives that foster an environment conducive to photolithography equipment deployment.
Which segment is expected to grow the fastest?
The advanced extreme ultraviolet (EUV) lithography segment is projected to exhibit the highest CAGR through 2034, driven by the push toward fabrication of smaller, more powerful semiconductor chips in line with emerging industry standards.
Who are the leading companies operating in the Saudi Arabia Photolithography System Market?
Key players include global giants such as ASML, Nikon, and Canon, along with regional and local suppliers partnering to meet increasing domestic demand and to establish a semiconductor manufacturing ecosystem within Saudi Arabia.
Analyst Perspective
The Saudi Arabia Photolithography System Market exhibits a maturity phase driven by advancing semiconductor fabrication and increasing domestic technology investments. Long-term prospects hinge on the country's push toward digital transformation, diversifying beyond oil reliance, and fostering local production. Opportunities arise from the upcoming development of integrated giga-fabs, particularly in Riyadh and Jeddah, where significant government incentives and infrastructure investments are accelerating semiconductor ecosystem growth. Technological evolution will likely focus on EUV lithography adoption to meet the scaling demands of advanced nodes, though high capital expenditure necessitates strategic partnerships and phased investments. Competition remains intense among global lithography giants, emphasizing the importance of strategic alliances and local engagement. City-level analysis indicates Riyadh’s comprehensive tech infrastructure offers a strategic hub for innovation clusters, while Jeddah’s proximity to emerging industrial zones presents promising expansion avenues. An overarching view underscores the necessity for flexible investment plans aligned with technological advancements and regional growth dynamics, ensuring competitive positioning in Saudi Arabia’s evolving semiconductor landscape.
