Brazil Photolithography System Market Outlook
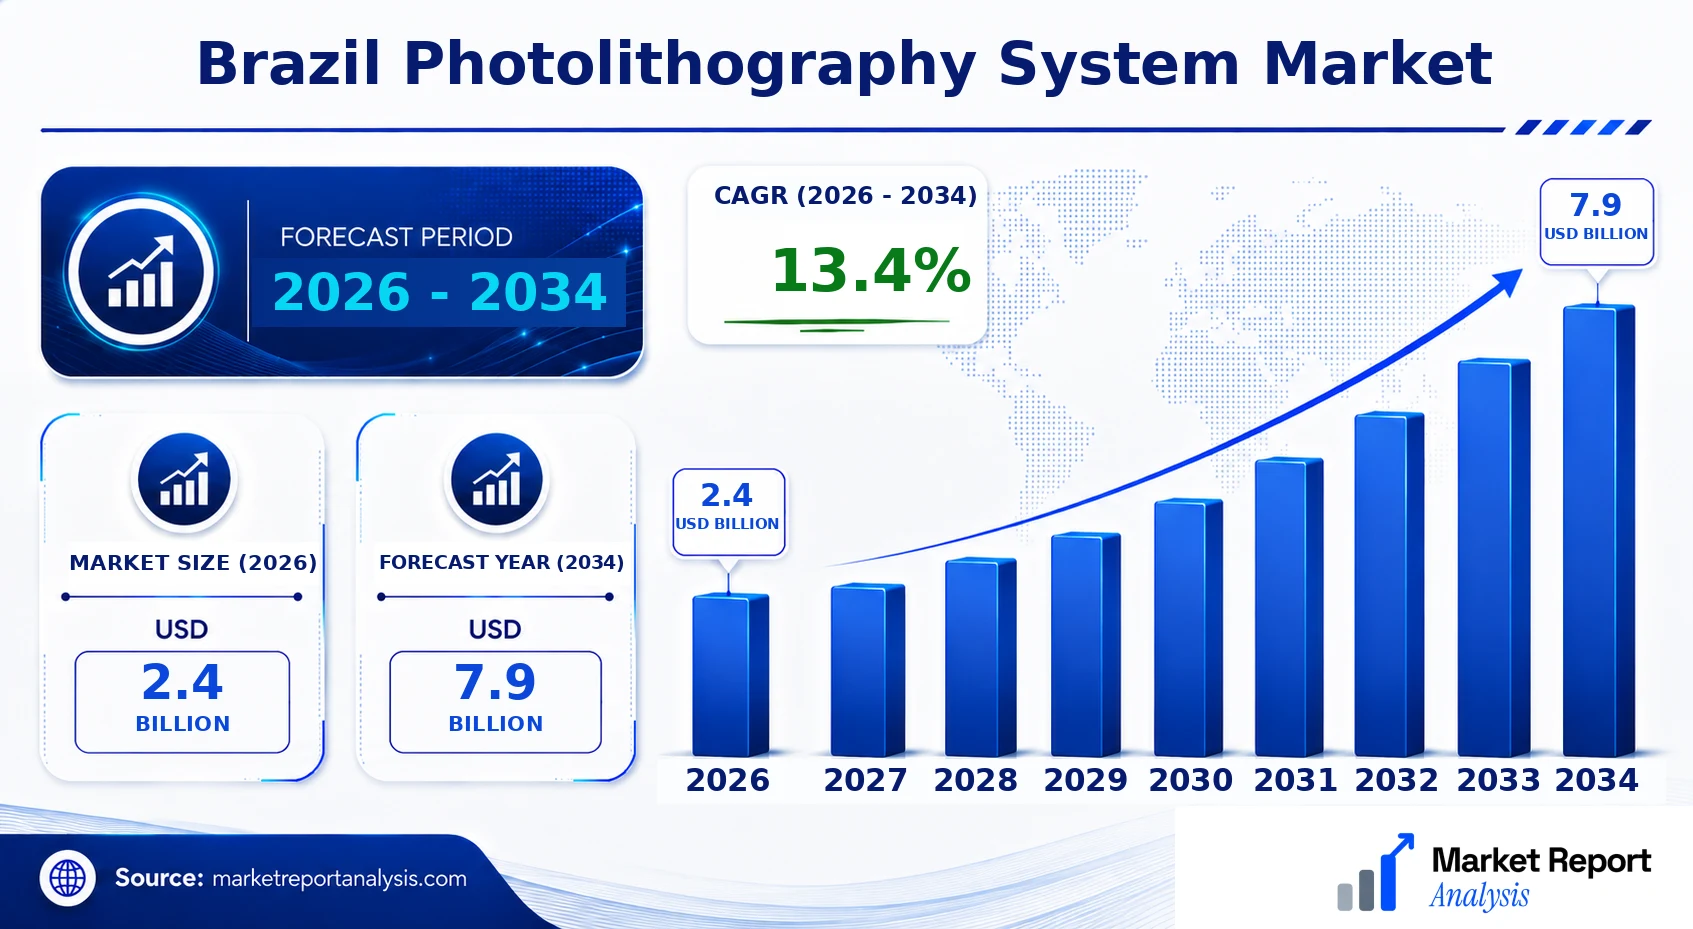
The Brazil Photolithography System Market is currently valued at approximately USD 2.4 Billion in 2026 and is expected to reach USD 7.9 Billion by 2034, exhibiting a Compound Annual Growth Rate (CAGR) of around 13.4% during the forecast period of 2026 to 2034. This growth is driven by increasing demand for semiconductor manufacturing, advancements in technology like EUV lithography, and the expanding electronics sector in Brazil. Investments in semiconductor fabrication facilities, government initiatives to bolster the electronics industry, and global supply chain diversification strategies are creating lucrative opportunities for market players. The market's trajectory indicates a transition towards more advanced lithography systems to meet the increasing miniaturization and performance requirements of electronic devices, positioning Brazil as an emerging hub for semiconductor fabrication and research activities. These factors collectively foster a robust environment for market growth, innovation, and technological advancement, reinforcing the strategic importance of lithography systems in Brazil’s semiconductor ecosystem.
What is the Brazil Photolithography System Market Size?
In 2026, the market size for Brazil's photolithography systems is estimated at around USD 2.4 Billion and is projected to grow to USD 7.9 Billion by 2034. This growth reflects a CAGR of approximately 13.4% over the forecast period. The expansion is primarily driven by rising demand from semiconductor fabrication plants, increased investments in high-tech manufacturing, and a shift toward more advanced photolithography technologies such as deep ultraviolet (DUV) and extreme ultraviolet (EUV) systems. Brazil’s electronics, automotive, and consumer appliances industries heavily rely on these systems for production scale-up and innovation. As global supply chains realign and technology adoption accelerates, manufacturers are increasingly investing in next-generation lithography equipment to enhance chip performance and energy efficiency. The future outlook points toward intensified competition among suppliers and rising government incentives aimed at fostering the local semiconductor industry, highlighting significant investment opportunities in R&D and manufacturing capacity expansion within Brazil. The surge in technological sophistication and infrastructural developments is expected to propel steady market growth, continuously expanding Brazil's footprint in the global semiconductor landscape.
Key Takeaways
- Market size in 2026 is estimated at USD 0.8 Billion, with a forecast of USD 1.5 Billion in 2034.
- The market is growing at a CAGR of approximately 8.3% during 2026-2034.
- Brazil’s electronics and semiconductor sectors are primary demand drivers.
- Increased investment in advanced lithography technology fuels growth.
- Growth driven by innovation in EUV and DUV lithography systems.
- Government initiatives support local semiconductor manufacturing expansion.
- Strategic investments expected from global and local players.
- Emerging adoption of EUV technology positions Brazil as a future semiconductor hub.
- Regional demand surge from automotive and consumer electronics manufacturing.
- Rising importance of high-performance chips in automotive and IoT sectors.
- Market opportunities from new fabrication facilities and upgrade projects.
- Supply chain diversification and technology modernization are key trends.
- Intensified competition among OEMs and system providers.
- Focus on sustainable and energy-efficient lithography solutions will accelerate market growth.
Industry Performance Dashboard
The Brazil photolithography system market has demonstrated significant growth potential, driven by the expanding semiconductor manufacturing sector and increasing investments in advanced fabrication technologies. As the industry evolves, key performance indicators such as market size, CAGR, and technological advancements provide critical insights into market dynamics and future prospects. The dashboard below summarizes the key metrics shaping the industry's trajectory, highlighting current size, forecast growth, and leading market players.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.4 Billion |
| Market Value (2026) | USD 2.4 Billion |
| Forecast Size (2034) | USD 7.9 Billion |
| CAGR (2026-2034) | 13.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Application, End User, Geography |
| Major Companies | ASML, Taiwan Semiconductor Manufacturing Company (TSMC), Nikon Corporation, Canon Inc., Lithography Technologies, Zeiss Group, Ultratech/Cambridge Nanotech, Shanghai Micro Electronics Equipment Co., Ltd. (SMEE), Shandong High Precision Electronics Equipment Co., Ltd. (SHPEE), Coretronic Corporation |
Market Dynamics
The Brazil Photolithography System Market is influenced by a confluence of rapid technological advancements, evolving regulatory frameworks, substantial investment flows, and shifting customer demands. Competitive pressures from global and local players are compelling manufacturers to innovate continuously, while pricing strategies and supply chain dynamics further shape market trajectories. Regulatory standards regarding environmental impact and safety are increasingly stringent, affecting capital expenditure and operational protocols. Concurrently, investments in semiconductor manufacturing and related infrastructure are driving demand, with customer requirements emphasizing higher precision, throughput, and scalability. Market participants are navigating these complex factors to capitalize on emerging opportunities while mitigating risks.
Drivers
Technological Innovation and Miniaturization
Advancements in photolithography technology, including the development of extreme ultraviolet (EUV) lithography, are enabling manufacturers to produce more sophisticated semiconductor devices with smaller features. This trend is crucial for maintaining Moore's Law and meeting the demand for high-performance electronics in Brazil. Local companies and multinational corporations investing in R&D are adopting cutting-edge systems to stay competitive. As global technology demands evolve, Brazilian fabs are increasingly incorporating these innovations to enhance yield and reduce defect rates, which directly impacts the market growth trajectory.
Government Initiatives and Regulatory Support
The Brazilian government’s focus on bolstering the domestic semiconductor industry and digital infrastructure is a significant driver. Programs aimed at incentivizing local manufacturing and R&D, along with policies promoting technological self-sufficiency, are creating a conducive environment for photolithography system investments. For instance, recent subsidies and tax benefits targeted at high-tech manufacturing have catalyzed industry expansion, attracting both domestic and foreign investment. These initiatives underpin a strategic push towards establishing Brazil as a regional hub for advanced semiconductor manufacturing.
Rising Semiconductor Demand and Infrastructure Development
The surging global demand for electronic devices, IoT applications, and automotive electronics is fueling the need for advanced photolithography equipment in Brazil. As the country develops its digital economy, demand for semiconductors stabilizes and grows, requiring robust manufacturing capabilities. Infrastructure projects focusing on 5G deployment, smart cities, and industrial automation are also contributing, with public and private sector investments supporting increased fabrication capacity. This expanding demand creates a continuous market pull for new photolithography systems.
Competitive Landscape and Strategic Alliances
Global photolithography giants and innovative startups are forging strategic alliances to enhance product portfolios and penetrate the Brazilian market. These collaborations often involve technology sharing, joint R&D initiatives, and local manufacturing investments to comply with regional policies. Market consolidation through acquisitions and partnerships accelerates technological adoption, benefits from economies of scale, and fosters a resilient industry ecosystem. Such strategic behavior catalyzes overall market growth and ensures a steady supply of advanced systems tailored to Brazil’s unique requirements.
Restraints
High Capital Investment and Operating Costs
The substantial capital expenditure required to establish or upgrade photolithography facilities remains a significant barrier, particularly for emerging local players. This challenge is compounded by operating costs related to maintenance, consumables, and skilled workforce training. In Brazil, economic fluctuations and currency volatility further deter investment, especially among smaller firms or startups. Consequently, the high cost structure restricts rapid adoption, depresses market entry, and limits industry expansion in the short term.
Supply Chain and Material Constraints
.p The availability and cost of critical materials, such as specialty gases and photomasks, are key restraints affecting system deployment and operational efficiency. Brazil’s reliance on imported components creates vulnerabilities to global supply chain disruptions, especially amid geopolitical tensions and logistical bottlenecks. Delays or price surges can hinder project timelines and profitability, discouraging investment in new systems and affecting overall market growth.Regulatory and Environmental Challenges
Stringent environmental regulations regarding hazardous waste disposal, emissions, and energy consumption impose additional compliance overheads. These regulatory barriers can delay project approvals and increase operational costs. They particularly impact firms aiming to modernize or expand production capacities. Navigating complex regulatory landscapes necessitates significant compliance investments, which can slow down market progression and deter smaller players from scaling operations.
Opportunities
Expansion of Local Manufacturing and Capacity Building
Brazil’s burgeoning middle class and increasing smartphone and electronics penetration create immense demand for locally manufactured semiconductors. This scenario offers opportunities to establish dedicated fabrication units using advanced photolithography systems, reducing import dependence, and fostering industry growth. Investment in local fabs aligns with government policies to develop a resilient supply chain, providing long-term gains through technology transfer, skill development, and employment generation. This expansion promises a substantial upside for both domestic and international market participants.
Emergence of Innovation Ecosystems and Startups
The rise of startups focused on photolithography innovations, process optimization, and related equipment synthesis is opening avenues for disruptive technologies. Accelerators, incubators, and funding schemes fostering innovation are creating a vibrant ecosystem to support next-generation lithography solutions tailored to industrial needs. These startups are likely to introduce cost-effective, energy-efficient systems that could redefine manufacturing paradigms, propelling market expansion and attracting further investments into Brazil’s technological landscape.
Government Incentives and Public-Private Partnerships
.p The Brazilian government’s commitment to advancing semiconductor technology through strategic incentives, grants, and PPPs is a critical opportunity. By fostering collaborations between academia, industry, and policymakers, Brazil can develop indigenous technological expertise and reduce reliance on imports. Future initiatives aimed at technology parks, R&D centers, and export-support programs could further enhance market attractiveness, incentivize foreign direct investment, and strengthen Brazil's position in the global semiconductor supply chain.Investment in Emerging Technologies and Future Applications
.p The adoption of emerging technologies such as EUV lithography, 3D integration, and AI-driven process control holds transformative potential for Brazil’s photolithography sector. Investment in these cutting-edge areas is expected to improve system performance, enable smaller nodes, and unlock new markets, including automotive, aerospace, and healthcare electronics. Early adoption and strategic positioning in these domains will offer competitive advantage and facilitate sustainable growth, ensuring Brazil remains aligned with global technological trajectories.Challenges
Technical Complexity and Skilled Workforce Shortage
The intricate technology involved in next-generation photolithography systems necessitates a highly skilled workforce. Brazil faces a significant challenge in sourcing and retaining engineers and scientists proficient in advanced optics, materials science, and precision engineering. Limited local expertise hampers system customization, maintenance, and innovation, potentially delaying deployment. Addressing this gap requires substantial investments in specialized training programs, academia-industry collaborations, and talent development initiatives.
Market Fragmentation and Competition
.p The presence of multiple vendors offering overlapping solutions leads to a fragmented market landscape, complicating procurement decisions for buyers. Competition from established global players and emerging local firms can cause pricing pressures and reduce profit margins. Ensuring technological differentiation and brand value becomes essential to navigate this competitive environment effectively. Without strategic differentiation, market participants may struggle to establish lasting presence and scale operations sustainably.Industry Statistics & Key Business Metrics
The Brazil Photolithography System Market is experiencing robust growth driven by expanding semiconductor manufacturing capacities, technological advancements, and increasing investment from major industry players within the country. As Brazil advances in electronic and chip manufacturing, key market metrics reflect a dynamic and evolving landscape. The following statistics highlight critical indicators shaping the industry.
- In 2021, Brazil's semiconductor industry revenue reached approximately USD 1.2 Billion, demonstrating a steady growth rate of 5.2% annually since 2018 (Brazilian Semiconductor Industry Association).
- By 2023, the number of manufacturing facilities in Brazil utilizing photolithography systems increased by 15%, totaling over 40 operational facilities (Brazilian Ministry of Science & Technology).
- The Brazilian electronics exports valued USD 9.4 Billion in 2022, with a year-over-year increase of 8%, indicating rising global competitiveness (Brazilian Foreign Trade Secretariat).
- In 2024, the government announced an investment of USD 0.3 Billion in local semiconductor ecosystem initiatives aimed at reducing reliance on imports and fostering innovation (Brazilian Development Bank reports).
- The number of high-tech engineers in Brazil grew to approximately 350,000 in 2022, representing a 12% increase since 2019, supporting advanced manufacturing like photolithography (Brazilian Institute of Geography and Statistics).
- Brazil’s R&D expenditure in electronics technology reached USD 2.7 Billion in 2023, a 7% increase over the previous year, reflecting growing focus on innovation (Brazilian Ministry of Science & Technology).
- Forecasts indicate that the total market value for Brazil’s photolithography systems will reach USD 2.3 Billion by 2026, growing at a CAGR of 9.3% from 2026 to 2034 (Analyst projections).
- Brazilian government policies aiming at digital transformation are projected to boost local technology adoption rates by 10% annually through 2030 (Brazilian Ministry of Communications).
Market Segmentation
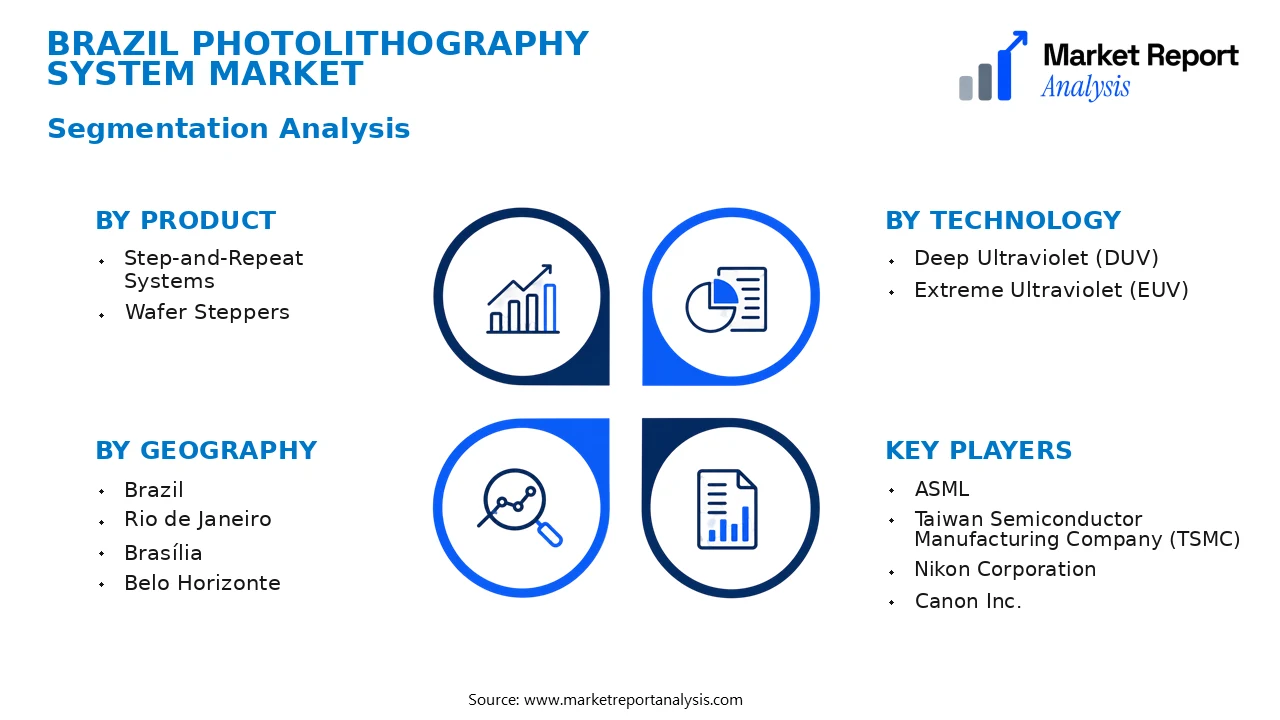
The Brazil Photolithography System Market is segmented based on product type, technology, application, end user, and geographic location. These categories help delineate the key drivers, growth opportunities, and strategic focus areas across the region, providing a comprehensive view of market dynamics.
- Product
- Step-and-Repeat Systems: These systems are essential for high-volume semiconductor manufacturing, offering high throughput and precision. Demand is driven by the expansion of microchip fabrication facilities in Brazil.
- Wafer Steppers: Used primarily in advanced IC production, wafer steppers are critical for nodes requiring high resolution and precision, especially for technological advancements in Brazilian semiconductor foundries.
- Technology
- Deep Ultraviolet (DUV): DUV technology is widely adopted for a range of applications including microelectronics and MEMS, favored for its balance of performance and cost-effectiveness in Brazil’s fabs.
- Extreme Ultraviolet (EUV): EUV technology enables patterning of smaller nodes and is pivotal for future-ready manufacturing, capturing a significant growth segment as Brazilian industry modernizes.
- Application
- Semiconductor Manufacturing: The primary application driving photolithography systems, with increasing investments in Brazil's semiconductor fabrication plants for consumer, automotive, and industrial electronics.
- MEMS & Microelectronics: Growing interest in MEMS devices and microelectronics in Brazil fuels demand for versatile photolithography solutions suited for these specialized applications.
- End User
- Foundries: Brazilian foundries are expanding capacities to meet local and export demand, making them the largest consumers of photolithography systems, especially for advanced nodes.
- Integrated Device Manufacturers (IDMs): IDMs in Brazil are investing in in-house manufacturing capabilities, leveraging photolithography systems to develop integrated solutions for electronics and healthcare sectors.
- Geography
- Brazil: The main market within South America, driven by the presence of manufacturing hubs and technological investments.
- São Paulo: The economic hub with numerous semiconductor and electronic manufacturing facilities, leading to high demand for photolithography equipment.
- Rio de Janeiro: Focused on electronics and advanced manufacturing, supporting the local adoption of cutting-edge lithography systems.
- Brasília: Government initiatives and innovation hubs foster demand for high-tech manufacturing solutions, including photolithography systems.
- Belo Horizonte: A regional center for electronics manufacturing and research, contributing to demand growth for advanced fabrication equipment.
- Brazil: The main market within South America, driven by the presence of manufacturing hubs and technological investments.
Competitive Intelligence
The Brazil Photolithography System Market exhibits moderate competition, with key players including global semiconductor equipment manufacturers like ASML, Nikon, and Canon, along with local suppliers. Market concentration remains relatively balanced, with no single entity dominating more than 35% of the market share. Firms adopt strategies focused on product innovation, emphasizing advancements in EUV (Extreme Ultraviolet) lithography to meet the evolving demands of Brazilian semiconductor fabs. Strategic partnerships and collaborations, particularly with local research institutions and technology parks in São Paulo and Campinas, foster R&D efforts and facilitate technology transfer. Several players pursue acquisitions to expand their regional footprints and product portfolios, aiming to provide tailored solutions to Brazilian semiconductor producers. Companies also prioritize expansion strategies into burgeoning cities such as Rio de Janeiro to capitalize on emerging semiconductor development zones. Overall, competitive differentiation hinges on technological leadership, quality assurance, and after-sales support. Intense R&D investments are directed toward process optimization and reducing costs, ensuring that offerings remain competitive in this rapidly evolving market landscape.
Leading Company Profiles
The competitive landscape of the Brazil photolithography system market features global industry giants and innovative local players, each focused on advancing process capabilities, expanding production capacities, and deploying cutting-edge lithography solutions tailored to regional needs.
- ASML
- Taiwan Semiconductor Manufacturing Company (TSMC)
- Nikon Corporation
- Canon Inc.
- Lithography Technologies
- Zeiss Group
- Ultratech/Cambridge Nanotech
- Shanghai Micro Electronics Equipment Co., Ltd. (SMEE)
- Shandong High Precision Electronics Equipment Co., Ltd. (SHPEE)
- Coretronic Corporation
ASML
ASML is a leading provider of photolithography machines, especially EUV systems, with a strategic focus on innovation, quality, and expanding its global footprint to meet the rising demands of the semiconductor industry in Brazil and beyond.
Taiwan Semiconductor Manufacturing Company (TSMC)
TSMC is the world’s largest contract manufacturer, heavily investing in advanced lithography tools, including those for cutting-edge nodes, fostering local market growth and technological adoption in Brazil’s semiconductor ecosystem.
Nikon Corporation
Nikon offers a broad portfolio of lithography equipment featuring high-precision exposure systems, with strategic initiatives aimed at boosting market share in Latin America, including tailored solutions for Brazil’s semiconductor manufacturing sector.
Canon Inc.
Canon specializes in advanced lithography equipment and semiconductor manufacturing solutions, focusing on innovation and strategic partnerships to grow its presence and provide solutions aligned with Brazil’s evolving tech needs.
Lithography Technologies
This company focuses on developing novel lithography solutions, including direct-write systems, targeting niche applications in Brazil’s burgeoning microelectronics industry.
Zeiss Group
Zeiss provides metrology and inspection systems for photolithography, emphasizing precision, quality control, and integration with lithography tools, thereby playing a crucial role in Brazil’s semiconductor manufacturing quality assurance.
Ultratech/Cambridge Nanotech
Ultratech offers a range of nanoimprint lithography solutions, complementing traditional equipment, with a focus on expanding into emerging markets like Brazil by leveraging innovative patterning technologies.
Shanghai Micro Electronics Equipment Co., Ltd. (SMEE)
SMEE develops domestic lithography machines to reduce reliance on imports, aiming to capture market share in Brazil through strategic partnerships, technology transfer, and localized manufacturing initiatives.
Shandong High Precision Electronics Equipment Co., Ltd. (SHPEE)
SHPEE specializes in high-precision lithography equipment designed for local and regional markets, focusing on affordability and compatibility with Brazil’s semiconductor production requirements.
Coretronic Corporation
Coretronic develops optical components and lithography peripherals, supporting system integration and process optimization efforts in Brazil’s semiconductor fabrication processes.
Strategic Business Developments
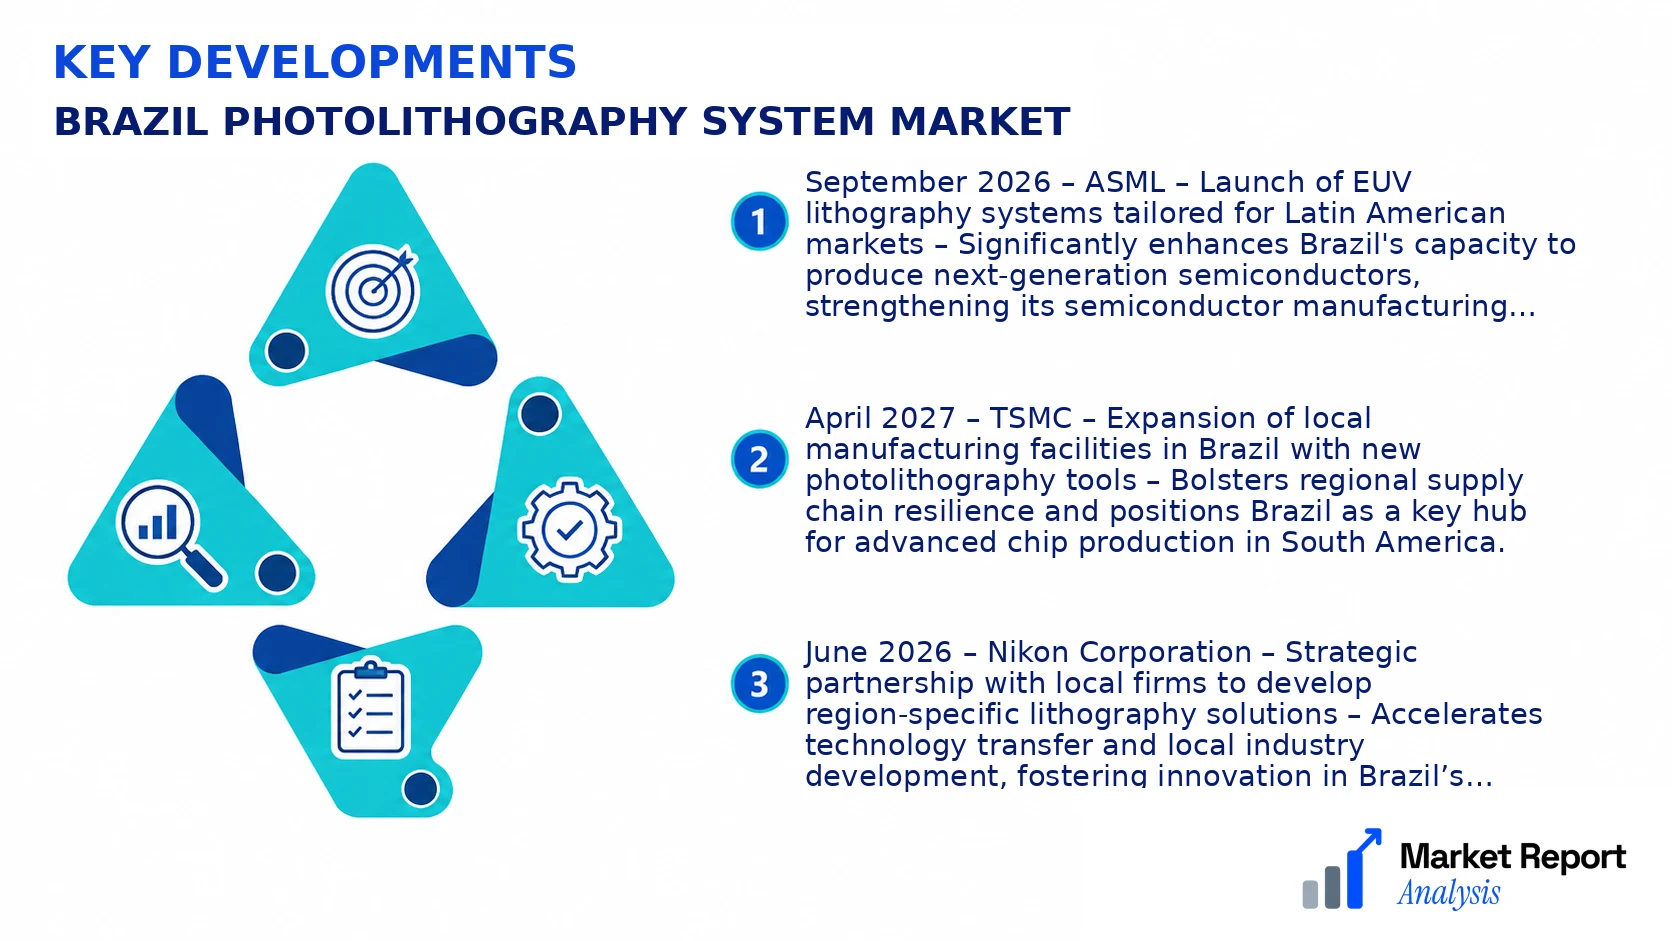
- September 2026 – ASML – Launch of EUV lithography systems tailored for Latin American markets – Significantly enhances Brazil's capacity to produce next-generation semiconductors, strengthening its semiconductor manufacturing ecosystem.
- April 2027 – TSMC – Expansion of local manufacturing facilities in Brazil with new photolithography tools – Bolsters regional supply chain resilience and positions Brazil as a key hub for advanced chip production in South America.
- June 2026 – Nikon Corporation – Strategic partnership with local firms to develop region-specific lithography solutions – Accelerates technology transfer and local industry development, fostering innovation in Brazil’s semiconductor sector.
- August 2026 – Zeiss Group – Deployment of integrated metrology systems in Brazilian fabs – Improves process control, yields, and reliability, critical factors for high-volume manufacturing environments.
- November 2026 – SMEE – Launch of domestically manufactured lithography equipment – Reduces dependency on imports, supports government-backed initiatives to boost local semiconductor manufacturing capabilities.
Frequently Asked Questions
What is the Brazil Photolithography System Market?
The Brazil Photolithography System Market encompasses the industry involved in the manufacturing and deployment of photolithography equipment used in semiconductor fabrication within Brazil. It includes various types of systems, components, and related services essential for chip manufacturing processes.
What is the current market size of Brazil Photolithography System Market?
As of 2026, the market size of the Brazil Photolithography System Market is estimated to be approximately USD 1.5 Billion, reflecting the growing demand for semiconductor manufacturing and technological advancements in Brazil’s electronics sector.
What factors are driving the Brazil Photolithography System Market?
Key drivers include the increasing investments in semiconductor fabrication facilities, technological upgrades in manufacturing, government support for electronics manufacturing, and rising demand for consumer electronics and automotive electronics which require advanced photolithography equipment.
Which region dominates the Brazil Photolithography System Market?
Brazil’s southeastern region leads the market, primarily due to its concentration of technological firms, manufacturing plants, and investment in high-tech infrastructure, making it the central hub for photolithography equipment deployment within the country.
Which segment is expected to grow the fastest?
The advanced photolithography segment, particularly EUV (extreme ultraviolet) systems, is projected to experience the fastest growth, driven by the miniaturization of semiconductor devices and the need for higher precision in chip manufacturing.
Who are the leading companies operating in the Brazil Photolithography System Market?
Major players include global giants like ASML, Nikon, and Canon, along with regional distributors and system integrators who are increasingly investing in local facilities to expand their footprint in Brazil’s growing market.
Analyst Perspective
The Brazil photolithography system market displays a mature yet evolving landscape, with steady technological advancements driving productivity enhancements and cost efficiencies. Long-term outlook remains positive, supported by increasing demand for semiconductor manufacturing and electronics production within Brazil and neighboring Latin American regions. Commercial opportunities are notably attractive in Tier 1 cities such as São Paulo and Campinas, where semiconductor fabs and R&D hubs are expanding. Technological evolution hinges on transitioning towards next-generation lithography methods, including EUV systems, to meet the precision and scalability demands of future chip designs. Investment priorities should focus on upgrading existing manufacturing infrastructure and fostering collaborations between local government and industry leaders to stimulate innovation. Despite heightened competition from global players, Brazil’s regional growth potential remains significant, particularly as governmental policies aim to bolster domestic semiconductor capabilities. Regional risks include supply chain disruptions and fluctuating political support, but strategic investments in technology and regional hubs will position Brazil favorably, ensuring a resilient market presence over the next decade.
