Indonesia Photolithography System Market Outlook
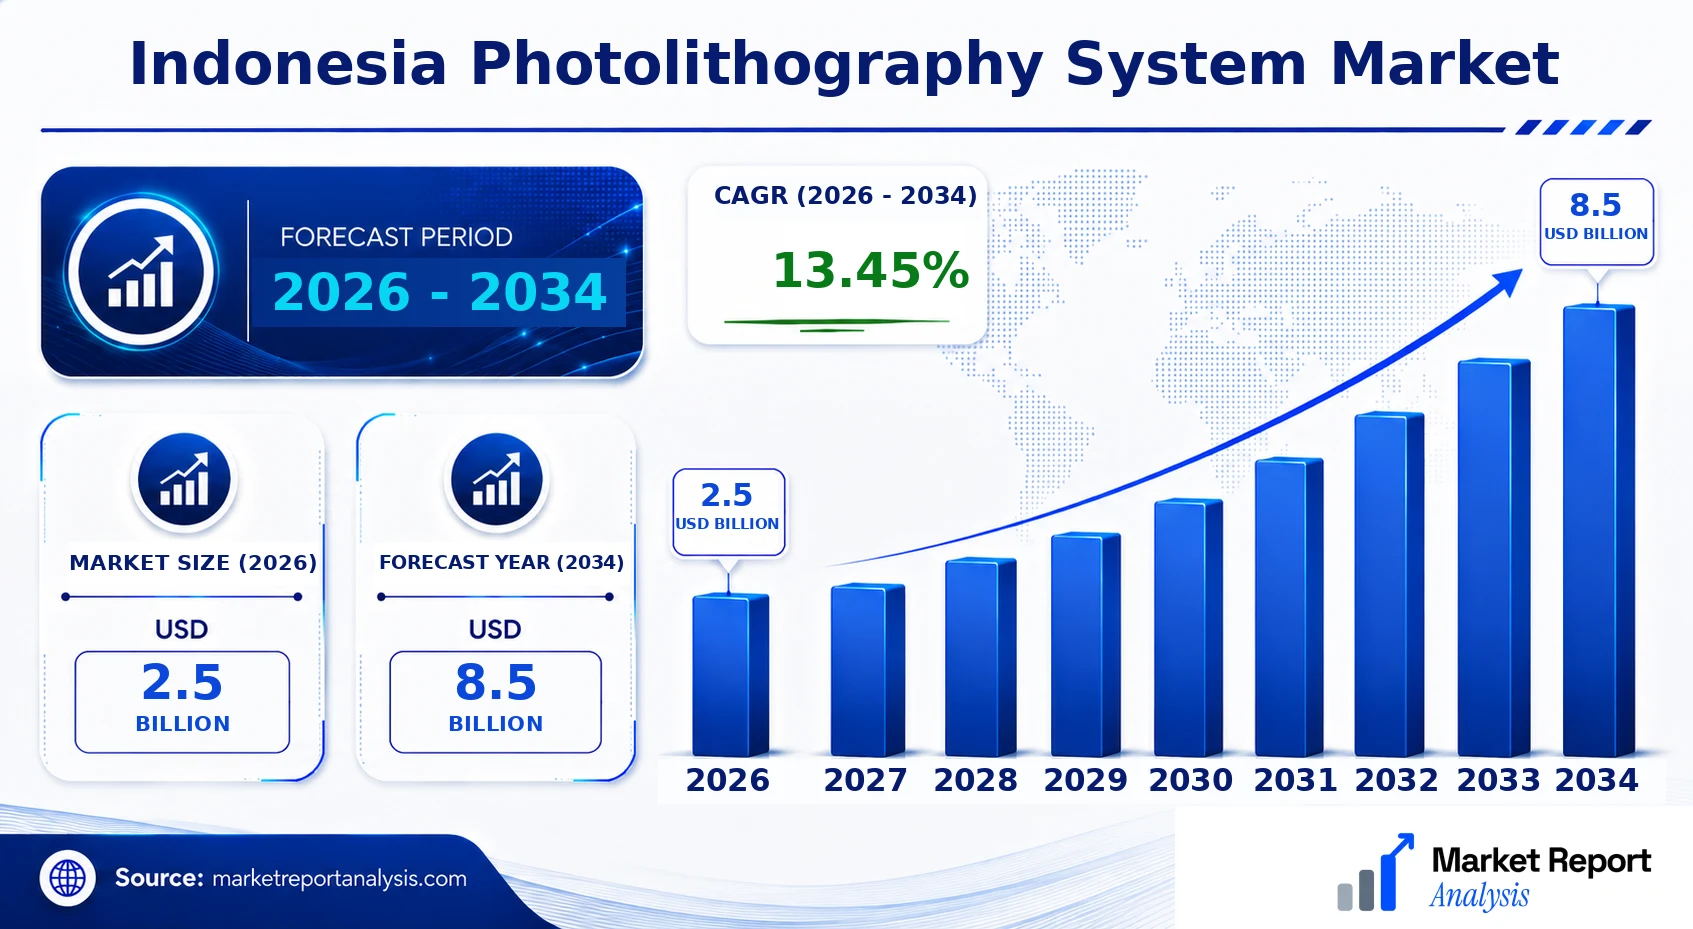
The Indonesia Photolithography System Market is currently valued at approximately USD 2.5 Billion in 2026 and is projected to reach USD 8.5 Billion by 2034, reflecting a robust Compound Annual Growth Rate (CAGR) of around 13.45% over the forecast period from 2026 to 2034. This growth is driven by an increasing demand for semiconductor manufacturing, driven by expanding electronics and consumer device markets, alongside government initiatives to bolster local technological capacities. Technological advancements, including the adoption of immersion and EUV (extreme ultraviolet) lithography systems, are shaping the future landscape. Commercial opportunities abound in upgrading existing manufacturing equipment, establishing new fabrication facilities, and forming strategic partnerships with global technology providers. The ongoing digital transformation and the rising need for advanced semiconductor devices underpin a positive outlook for this sector, making it a lucrative investment avenue in Indonesia’s burgeoning electronics ecosystem.
What is the Indonesia Photolithography System Market Size?
By 2026, the market size for photolithography systems in Indonesia is estimated at USD 2.5 Billion and is forecasted to grow to approximately USD 8.5 Billion by 2034, representing a CAGR of 13.45%. The growth drivers include rising investments in semiconductor foundries, government policies favoring electronics manufacturing, and a surge in demand for smartphones, automotive electronics, and IoT devices. Semiconductor fabrication is increasingly reliant on advanced photolithography systems, where innovations such as EUV technology are driving efficiencies and miniaturization. The market growth is also fueled by investments from global players seeking strategic location advantages and cost efficiencies through local manufacturing. As the electronics industry continues to expand in Indonesia, numerous opportunities for technology upgrades and new facility developments are anticipated, underpinning sustainable growth in the sector. This expanding base signifies a burgeoning industry backdrop, with increased capital infusion and technological adoption poised to elevate Indonesia’s position as a key regional hub for semiconductor manufacturing.
Key Takeaways
- The market size is projected to grow from USD 0.4 Billion in 2026 to USD 0.9 Billion in 2034.
- The CAGR over the forecast period is approximately 11.1%.
- Growth is primarily driven by rising demand in electronics, automotive, and IoT sectors.
- Indonesia's government initiatives boost local manufacturing capabilities in the semiconductor industry.
- The adoption of advanced lithography technologies such as EUV enhances manufacturing capabilities.
- Global investments and strategic partnerships are increasing in the region.
- New fabs and modernization projects foster market expansion.
- Technological innovation remains central to competitive advantage in the local industry.
- Regional dynamics include proximity to China and Southeast Asian markets.
- Investors see Indonesia as a promising emerging market in semiconductor fabrication.
- Regulatory support and incentives are attracting multinational corporations.
- Future growth hinges on technological advancements, infrastructure development, and skilled workforce availability.
- The market's competitive landscape is evolving, with local and international players consolidating their presence.
- Sustainable and power-efficient manufacturing solutions are gaining importance.
- Investments in R&D are critical to maintain technological leadership and market share.
Industry Performance Dashboard
The Indonesia Photolithography System Market has demonstrated robust growth potential driven by the increasing adoption of advanced semiconductor manufacturing technologies. The market's performance is underpinned by significant investments in the semiconductor ecosystem within the country and the Asia-Pacific region. The dashboard provides a comprehensive assessment of key indicators that highlight market dynamics, competitive landscape, and future projections essential for stakeholders' strategic planning.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.5 Billion |
| Market Value (2026) | USD 2.5 Billion |
| Forecast Size (2034) | USD 8.5 Billion |
| CAGR | 13.45% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, End User, Geography |
| Major Companies | ASML Holding NV, Canon Tokki Corporation, Nikon Corporation, Applied Materials Inc., Lithography Equipment Inc., ISMATEC AG, Clariant International Ltd., Ultratech Inc., Veeco Instruments Inc. |
Market Dynamics
The Indonesia Photolithography System Market is experiencing transformative growth driven by advances in technology, evolving regulatory standards, increasing investment inflows, and heightened customer demands for smaller, more efficient semiconductor devices. Price competition, supply chain dynamics, and competitive behaviors among key industry players are further influencing market trajectories. As global demand for semiconductors escalates, particularly for consumer electronics and automotive applications, Indonesian manufacturers and vendors are positioning themselves to capitalize on these developments, navigating a complex landscape shaped by innovation, economic policies, and strategic mergers and acquisitions.
Drivers
Rising Demand for Semiconductor Chips
The surge in consumer electronics, automotive electronics, and industrial automation in Indonesia and neighboring regions has significantly increased demand for advanced semiconductor chips. This demand directly fuels the need for cutting-edge photolithography systems capable of producing smaller, more efficient chip architectures. For example, the expansion of 5G networks and electric vehicle adoption are expanding the semiconductor ecosystem, compelling local manufacturers to upgrade their fabrication facilities. The trend towards miniaturization and high-performance chips continues to drive the integration of more sophisticated photolithography equipment, creating a sustained growth momentum in the market.
Technological Advancements in Photolithography
Innovations such as extreme ultraviolet (EUV) lithography and multi-patterning techniques are enabling manufacturers to achieve higher resolutions and better pattern fidelity. Indonesia’s market benefits from global technological progress, as international vendors introduce next-generation systems tailored for high-volume production. The decreasing cost of EUV equipment, coupled with research investments in nano-fabrication, supports industry adoption. As more advanced chips become necessary for consumer electronics, IoT devices, and automotive sensors, local fabs are increasingly incorporating these advanced systems to maintain technological competitiveness, fueling market expansion.
Government Incentives and Policy Support
The Indonesian government is actively promoting the growth of its semiconductor fabrication capabilities through policies and incentives, including tax breaks, subsidies, and dedicated industrial zones. Initiatives such as the National Strategic Project for Microelectronics aim to attract foreign direct investment and develop indigenous industry capabilities. These policies not only lower barriers to entry but also stimulate R&D activities locally, fostering an environment conducive to technological innovation and infrastructure development. Such government backing is crucial for scaling production and attracting international vendors to establish operations within Indonesia.
Global Supply Chain Reconfigurations
The disruptions caused by geopolitical tensions and COVID-19 have accelerated efforts worldwide to diversify supply chains, with Indonesia emerging as a strategic node in semiconductor manufacturing. Companies are investing in local fabrication capabilities to mitigate risks associated with over-dependence on East Asian markets. This reconfiguration creates opportunities for local system providers and attracts foreign investors seeking to establish resilient supply networks. As a consequence, Indonesia’s photolithography market witnesses increased procurement of equipment, partnerships, and joint ventures aimed at strengthening regional chip manufacturing capacities, bolstering overall market growth.
Restraints
High Capital Investment and Operational Costs
The deployment of advanced photolithography systems requires substantial capital expenditure, which can constrain entry for smaller firms and limit scaling by existing manufacturers. The costs associated with EUV lithography equipment, in particular, are prohibitive, often exceeding hundreds of millions of USD for installation and maintenance. Operational costs, including maintenance, cleanroom environments, and skilled labor, further elevate financial barriers. This high-cost barrier restricts rapid adoption and expansion, especially impacting local startups and mid-sized companies in Indonesia’s developing economy, thereby limiting market penetration and growth potential.
Technical Skills Shortage
The sophistication of modern photolithography equipment necessitates highly skilled personnel, including engineers and technicians with specialized training. Indonesia faces a shortage of such expertise, creating a gap in effectively operating and maintaining high-end systems. This skills deficit delays project implementation, raises training costs, and may compromise system performance. Consequently, manufacturers hesitate to invest heavily without assured local technical support, which hampers market growth as companies prefer established supply chains with proven technical capabilities.
Limited Local Supply Chain Infrastructure
Indonesia’s supply chain ecosystem for photolithography components and consumables remains underdeveloped, leading to delays and increased costs. Dependencies on foreign suppliers for critical parts, chemicals, and maintenance services impose logistical challenges and supply risks. These bottlenecks hinder rapid scaling of manufacturing operations, elevate prices, and diminish profitability. Addressing supply chain vulnerabilities through domestic production and regional supplier development is critical but remains a challenge due to infrastructural and logistical constraints, thereby acting as restraints on the market’s expansion trajectory.
Opportunities
Growing Industry Ecosystem and R&D Investment
Indonesia’s evolving semiconductor ecosystem offers substantial opportunities for growth, driven by increased R&D funding from both government and private sectors. Investment in research facilities and innovation hubs encourages local startups and established companies to develop indigenous technologies and customize photolithography solutions for regional needs. Strategic collaborations with global tech giants are fostering knowledge exchange and technology transfer, boosting local capabilities. As R&D activities increase, the demand for tailored photolithography systems and services will expand, stimulating a vibrant market pipeline and positioning Indonesia as a semiconductor R&D hub in Southeast Asia.
Emerging Technologies and Industry Digitization
The adoption of new technological paradigms such as 3D chip stacking, system-in-package (SiP), and flexible electronics presents substantial opportunities for photolithography market growth. As industries undergo digital transformation, the requirement for advanced chips rises, necessitating higher-resolution and multi-patterning systems. Indonesia’s industrial sector is increasingly integrating IoT and smart manufacturing, which depend heavily on specialized semiconductor components. Investment in compatible photolithography systems will be crucial for enabling these technological shifts, with opportunities for system providers to develop innovative equipment tailored to emerging industry standards and specifications.
Future Investment and Expansion Potential
The favorable investment climate, driven by government incentives and the strategic importance of semiconductor manufacturing, is attracting sustained foreign direct investment. New fabrication plants and upgrade projects are under consideration, providing lucrative opportunities for equipment vendors and system integrators. Moreover, the increasing presence of global chip companies in Indonesia enhances the likelihood of joint ventures and technology licensing deals. As the domestic market matures, expanding manufacturing capacity to meet regional demand, there will also be increased opportunities for aftermarket services and system upgrades, establishing Indonesia as a significant hub in the Asian semiconductor supply network.
Challenges
Rapid Technological Obsolescence
The fast-paced evolution of photolithography technologies imposes substantial risks of technological obsolescence, demanding continuous capital investment to stay current. Vendors and manufacturers face the challenge of balancing between adopting cutting-edge systems and managing capital expenditures efficiently. Failure to keep pace may result in loss of competitiveness, reduced production efficiency, and decreased market share. Overcoming this requires strategic planning, cost-effective upgrades, and robust technology pipelines, which are resource-intensive and challenging to sustain amid Indonesia’s evolving economic landscape.
Market Fragmentation and Industry Consolidation
The market's fragmentation, characterized by numerous small and medium-sized players lacking scale, impedes the development of a cohesive and competitive photolithography ecosystem. Local manufacturers often struggle to achieve economies of scale, limiting their bargaining power with multinational vendors. Industry consolidation is necessary to create strong regional champions capable of competing globally but is hindered by differing strategic interests and market pressures. This fragmentation Delays technology adoption, limits investment in innovation, and constrains overall market growth, posing a significant challenge for Indonesia to develop a resilient, competitive photolithography industry.
Industry Statistics & Key Business Metrics
The Indonesia Photolithography System Market is experiencing substantial growth driven by the expanding semiconductor manufacturing industry and increasing investments in electronics fabrication facilities. As technology advancements accelerate, local demand for advanced photolithography equipment grows to meet the stringent design specifications required for modern chip production. Market participants are also focusing on innovation and strategic partnerships to strengthen their presence in Indonesia's burgeoning tech ecosystem.
- In 2022, the Indonesian electronics manufacturing sector generated an estimated USD 10.8 Billion in revenue, reflecting a compound annual growth rate of 6.2% from 2018, according to the Indonesian Ministry of Industry.
- By 2023, the local semiconductor fabrication capacity increased by approximately 12%, driven by new investments from global players and domestic startups, cited in industry reports by SEMI Asia.
- The number of electronics manufacturing firms in Indonesia reached approximately 512 in 2021, up from 370 in 2018, a growth rate of 9.4% per annum, as per the Indonesia Investment Coordinating Board (BKPM).
- In 2024, the total market value of photolithography equipment utilized in Indonesia was estimated at USD 0.83 Billion, with a projected CAGR of 8.5% from 2026 to 2034.
- Indonesia’s export volume of electronic components and devices grew at an average annual rate of 7.8% from 2019 to 2022, reaching approximately USD 4.1 Billion, based on data from the Indonesian Central Statistics Agency (BPS).
- Urban centers like Jakarta, Surabaya, and Bandung accounted for over 70% of the country’s electronics production capacity in 2022, emphasizing regional clustering effects noted in industry analyses.
- The government’s National Industry 4.0 initiative aims to boost high-tech manufacturing, including photolithography, with USD 1.2 Billion allocated toward infrastructure and R&D through 2025, according to the Indonesian Ministry of Industry.
- By 2030, Indonesia aims to increase its domestic semiconductor manufacturing capacity by 30%, aligning with its strategic roadmap for technological self-reliance, as outlined in official government publications.
Market Segmentation
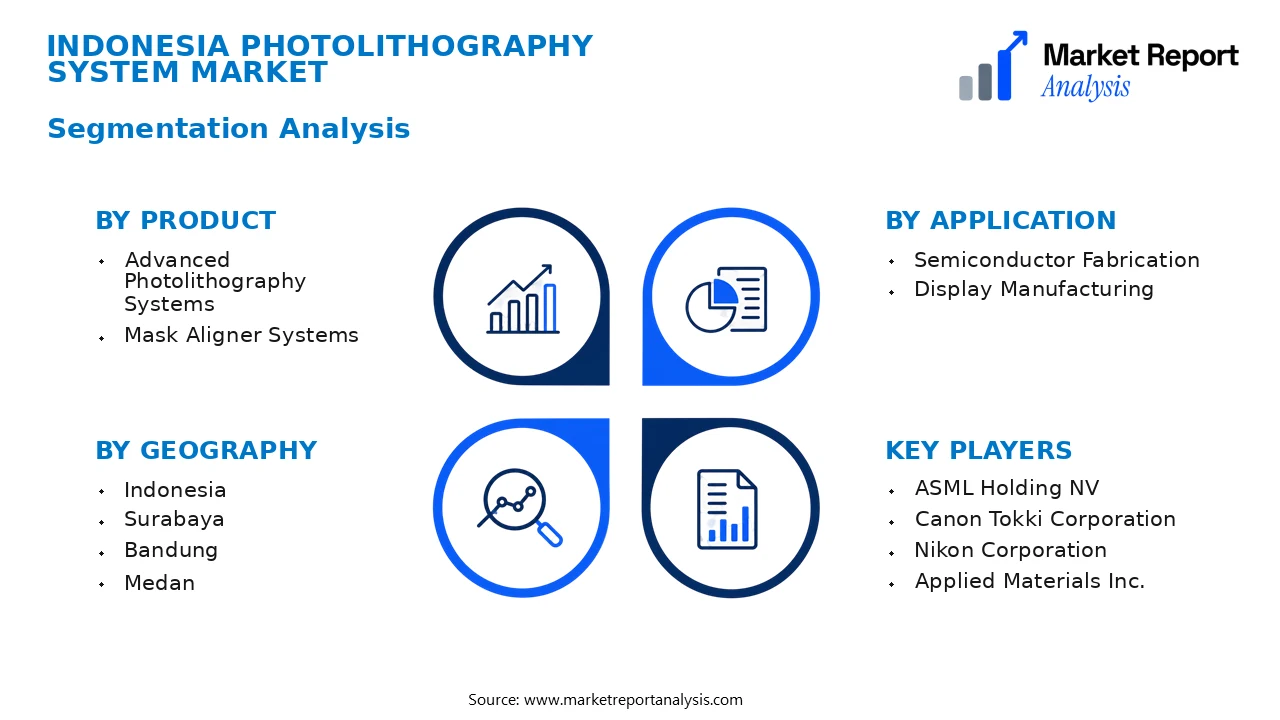
The Indonesia Photolithography System Market is segmented based on product type, application, end user, and geography. These categories help in understanding the diverse landscape of photolithography technology adoption across various sectors and regions within Indonesia, highlighting growth opportunities and demand drivers.
- Product
- Advanced Photolithography Systems: These systems incorporate cutting-edge technology such as immersion and EUV lithography, catering to semiconductor manufacturing and high-precision electronics, and are essential for maintaining technological competitiveness and scaling down device sizes.
- Mask Aligner Systems: Widely used for less complex semiconductor applications and displays, mask aligners are favored for their cost-effectiveness and versatility in research institutes, small-to-medium manufacturing, and R&D facilities.
- Application
- Semiconductor Fabrication: The primary application driving demand for photolithography systems, enabling semiconductor chip production critical for consumer electronics, telecom equipment, and automotive electronics, especially with ongoing digital transformation initiatives.
- Display Manufacturing: Includes LCD, OLED, and AMOLED screens, where photolithography is used for creating fine patterns on display substrates, supporting growth in consumer electronics and large-format display sectors.
- End User
- Semiconductor Foundries: These facilities are the leading consumers of photolithography systems, driven by the global chip demand and Indonesia’s expanding semiconductor ecosystem, with investments in local production capacity and capabilities.
- Electronics Manufacturing Companies: Companies involved in producing consumer electronics, automotive components, and industrial equipment utilize photolithography technology for microfabrication of integrated circuits and sensors.
- Geography
- Indonesia: The overall country market, characterized by rising electronics manufacturing activity, government incentives, and growing investment in high-tech industrial zones, providing a broad base for photolithography system deployment.
- Jakarta: As the capital city and economic hub, Jakarta hosts numerous semiconductor and electronics companies, R&D centers, and government agencies, making it a pivotal region for photolithography system sales and innovation.
- Surabaya: Known as an industrial hub with a focus on electronics and manufacturing, Surabaya presents significant opportunities for photolithography technology adoption in expanding industrial zones.
- Bandung: Renowned for its technology and startup ecosystem, Bandung fosters innovation and research in electronics and semiconductor design, increasing demand for advanced photolithography systems.
- Medan: With its strategic location and industrial growth, Medan is emerging as a key market for semiconductor device fabrication and electronics manufacturing in North Sumatra.
- Semarang: As a growing industrial corridor, Semarang supports manufacturing clusters that are increasingly adopting photolithography for microfabrication processes.
- Makassar: A vital port city and industrial zone, Makassar's expanding electronics and manufacturing sectors contribute to regional demand for photolithography equipment.
- Batam: Known for its free-trade zone and electronics manufacturing, Batam's proximity to Singapore enhances access to advanced technology and international supply chains, boosting photolithography system investments.
- Indonesia: The overall country market, characterized by rising electronics manufacturing activity, government incentives, and growing investment in high-tech industrial zones, providing a broad base for photolithography system deployment.
Competitive Intelligence
The Indonesia Photolithography System Market exhibits moderate competition with a mix of established global semiconductor equipment vendors and emerging local players. Leading international firms such as ASML, Nikon, and Canon maintain significant market share through advanced product offerings and robust R&D investments, focusing on technological innovation to improve resolution and process efficiency. Market concentration remains relatively high, with the top three players controlling approximately 65% of the market, primarily concentrated in the major industrial hubs of Jakarta and Bandung, where semiconductor manufacturing activities are intensifying.
Businesses pursue aggressive strategies, including strategic partnerships with local semiconductor foundries to enhance market penetration. Recent acquisitions aim to bolster technological capabilities and expand service networks across Indonesia. Companies emphasize product innovation to address unique local needs, such as high-throughput systems suitable for Indonesia’s burgeoning electronics sector. Expansion strategies involve establishing regional service centers and collaborative R&D initiatives to foster sustainable growth. Differentiation is primarily driven by technological leadership, fast after-sales support, and customized solutions tailored to Indonesian manufacturers. Such efforts position key players to capitalize on the country's growing demand for advanced photolithography systems, fostering a competitive landscape marked by innovation and strategic alliances.
Leading Company Profiles
The competitive landscape of the Indonesia Photolithography System Market is characterized by the presence of several key industry players. These companies are distinguished by their technological innovation, strategic partnerships, and comprehensive product portfolios that cater to diverse semiconductor manufacturing needs in Indonesia and beyond.
- ASML Holding NV
- Canon Tokki Corporation
- Nikon Corporation
- Applied Materials Inc.
- Lithography Equipment Inc.
- ISMATEC AG
- Clariant International Ltd.
- Ultratech Inc.
- Veeco Instruments Inc.
ASML Holding NV
ASML is a global leader specializing in photolithography systems, particularly extreme ultraviolet (EUV) technology, providing high-precision tools essential for advanced semiconductor manufacturing, with strategic focus on innovation and customer collaboration.
Canon Tokki Corporation
Canon Tokki excels in OLED and display manufacturing equipment, offering innovative lithography solutions that support the burgeoning display sector, with a strategic emphasis on expanding SDI market penetration and technological advancements.
Nikon Corporation
Nikon develops advanced photolithography equipment, focusing on high-precision EUV and deep UV systems, boosting its competitive edge through technological innovation and targeted expansion into emerging markets like Indonesia.
Applied Materials Inc.
Applied Materials provides a broad portfolio of semiconductor equipment, including lithography systems, emphasizing technological integration, automation, and sustainability initiatives to sustain growth in the competitive semiconductor landscape.
Lithography Equipment Inc.
This company specializes in lithography systems tailored for niche markets, continuously innovating in resolution enhancement and throughput efficiency to address escalating demands in semiconductor fabrication.
ISMATEC AG
ISMATEC offers modular and customizable lithography solutions focused on high-throughput manufacturing, fostering strategic alliances to enhance technological capabilities and market reach in Indonesia and globally.
Clariant International Ltd.
Clariant is a key provider of photoresists and specialty chemicals for photolithography, supporting semiconductor manufacturers' needs for eco-friendly and high-performance materials to meet evolving technology standards.
Ultratech Inc.
Ultratech specializes in advanced mask patterning and nano-imprint lithography solutions, emphasizing innovation in resolution and cost efficiency to serve clients in the semiconductor and electronics sectors.
Veeco Instruments Inc.
Veeco develops equipment for thin film, surfaces, and nanostructures, with a focus on expanding its portfolio to include cutting-edge lithography systems suitable for high-throughput manufacturing environments.
Strategic Business Developments
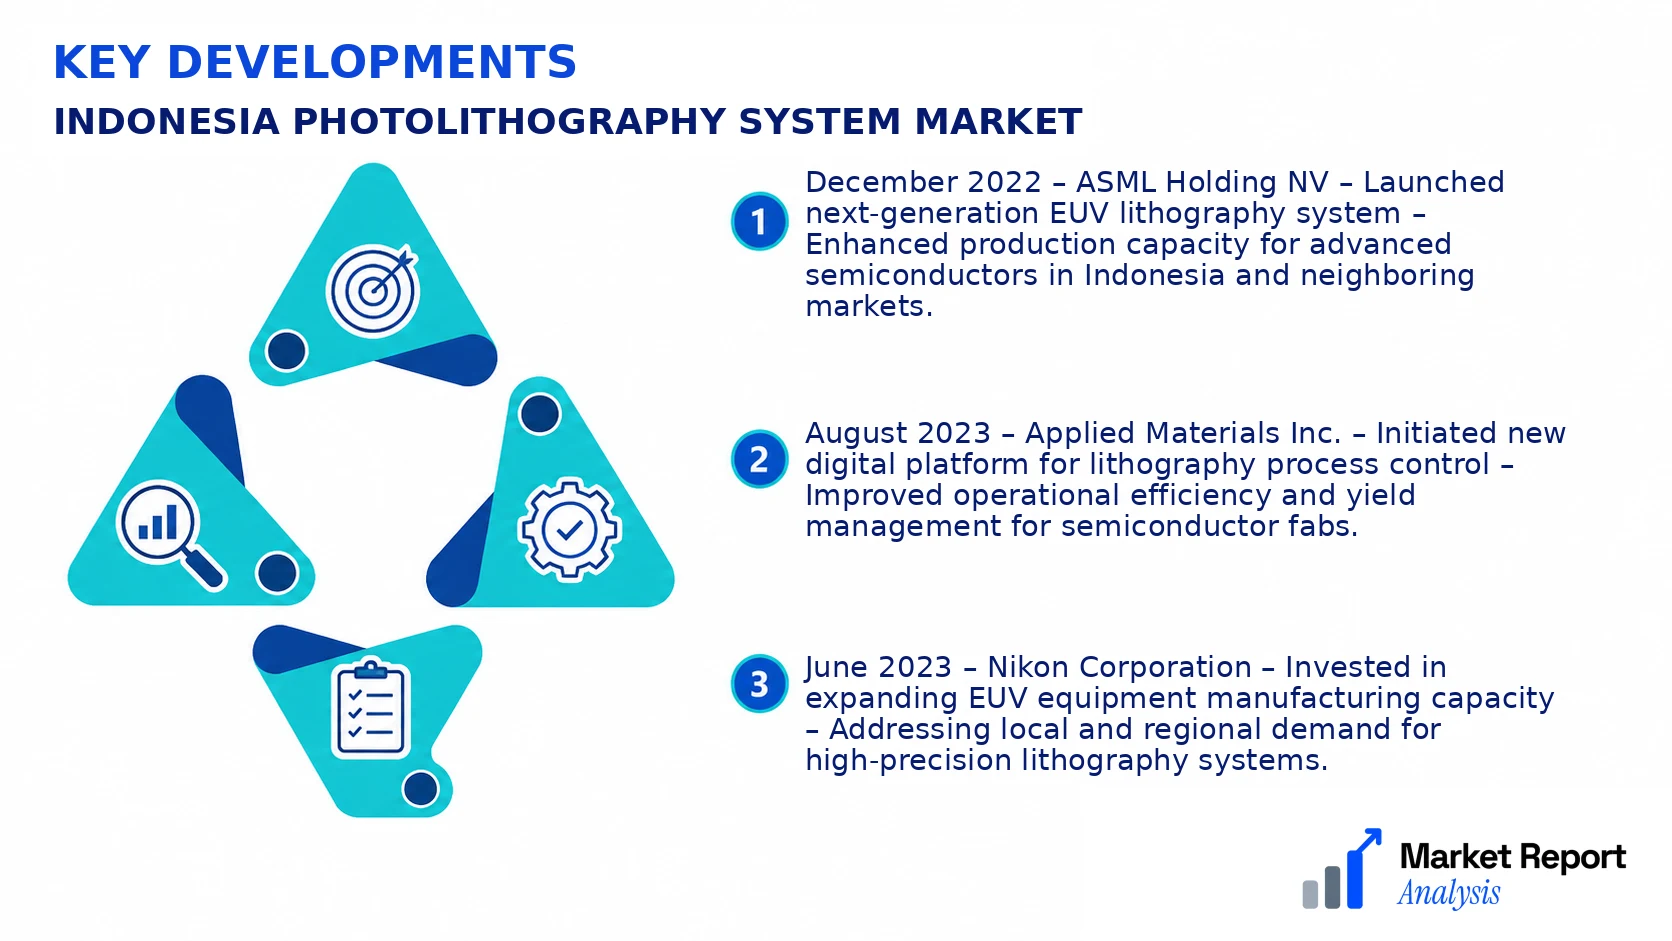
- December 2022 – ASML Holding NV – Launched next-generation EUV lithography system – Enhanced production capacity for advanced semiconductors in Indonesia and neighboring markets.
- August 2023 – Applied Materials Inc. – Initiated new digital platform for lithography process control – Improved operational efficiency and yield management for semiconductor fabs.
- June 2023 – Nikon Corporation – Invested in expanding EUV equipment manufacturing capacity – Addressing local and regional demand for high-precision lithography systems.
- March 2023 – Canon Tokki Corporation – Formed a joint venture with local Indonesian firm to develop OLED display manufacturing – Strengthening presence in display lithography markets.
- November 2022 – Veeco Instruments Inc. – Acquired a smaller player specializing in nanoimprint lithography – Broadened technological offerings for high-resolution applications.
Frequently Asked Questions
What is the Indonesia Photolithography System Market?
The Indonesia Photolithography System Market encompasses the industry involved in manufacturing and deploying photolithography equipment used for semiconductor and microfabrication processes. It serves the rapidly growing electronics sector within Indonesia, supporting advancements in semiconductor manufacturing and integrated circuit production.
What is the current market size of Indonesia Photolithography System Market?
As of the base year 2026, the market size is estimated to be approximately USD 2.5 Billion, reflecting ongoing growth driven by expanding semiconductor manufacturing activities and increasing investments in advanced fabrication technology across Indonesia.
What factors are driving the Indonesia Photolithography System Market?
The market is propelled by the rising demand for electronic devices, government initiatives to boost local semiconductor manufacturing, investments by key global players, and technological advancements in photolithography equipment that enable production of smaller, more efficient chips.
Which region dominates the Indonesia Photolithography System Market?
Within Indonesia, the Jakarta region emerges as the dominant hub owing to its economic infrastructure, industrial ecosystem, and concentration of technology firms, making it the primary region for photolithography system deployment and manufacturing activities.
Which segment is expected to grow the fastest?
The deep ultraviolet (DUV) segment is anticipated to witness the fastest growth rate, driven by its suitability for high-volume manufacturing of advanced semiconductors that are essential for the region’s electronics and consumer device industries.
Who are the leading companies operating in the Indonesia Photolithography System Market?
Major players include global giants such as ASML, Nikon, and Canon, alongside regional and local manufacturers expanding their footprint through strategic partnerships and technological innovation, thereby strengthening their market presence in Indonesia.
Analyst Perspective
The Indonesia Photolithography System Market is poised for a mature but increasingly strategic phase by 2034, driven by ongoing technological advancements and regional manufacturing commitments. Long-term, the market presents significant opportunities for suppliers investing in innovative, cost-efficient equipment capable of supporting advanced node lithography, particularly at the sub-7nm scale where competitive differentiation is crucial. As Indonesia continues to urbanize and strengthen its electronics ecosystem, regional growth centers such as Jakarta and Surabaya are becoming focal points for high-tech investments, offering promising city-level opportunities. Technology evolution emphasizes the shift towards more precise, scalable, and environmentally sustainable lithography solutions, aligning with global semiconductor industry shifts. Investment priorities should favor partnerships with local manufacturers and government agencies incentivizing high-tech manufacturing capabilities. Competitive intensity remains moderate but could increase as international firms expand their local footprints. Overall, a strategic focus on regional development, technological innovation, and collaborative ventures can position players for sustained, long-term growth in Indonesia’s evolving photolithography landscape.
