Malaysia Photolithography System Market Outlook
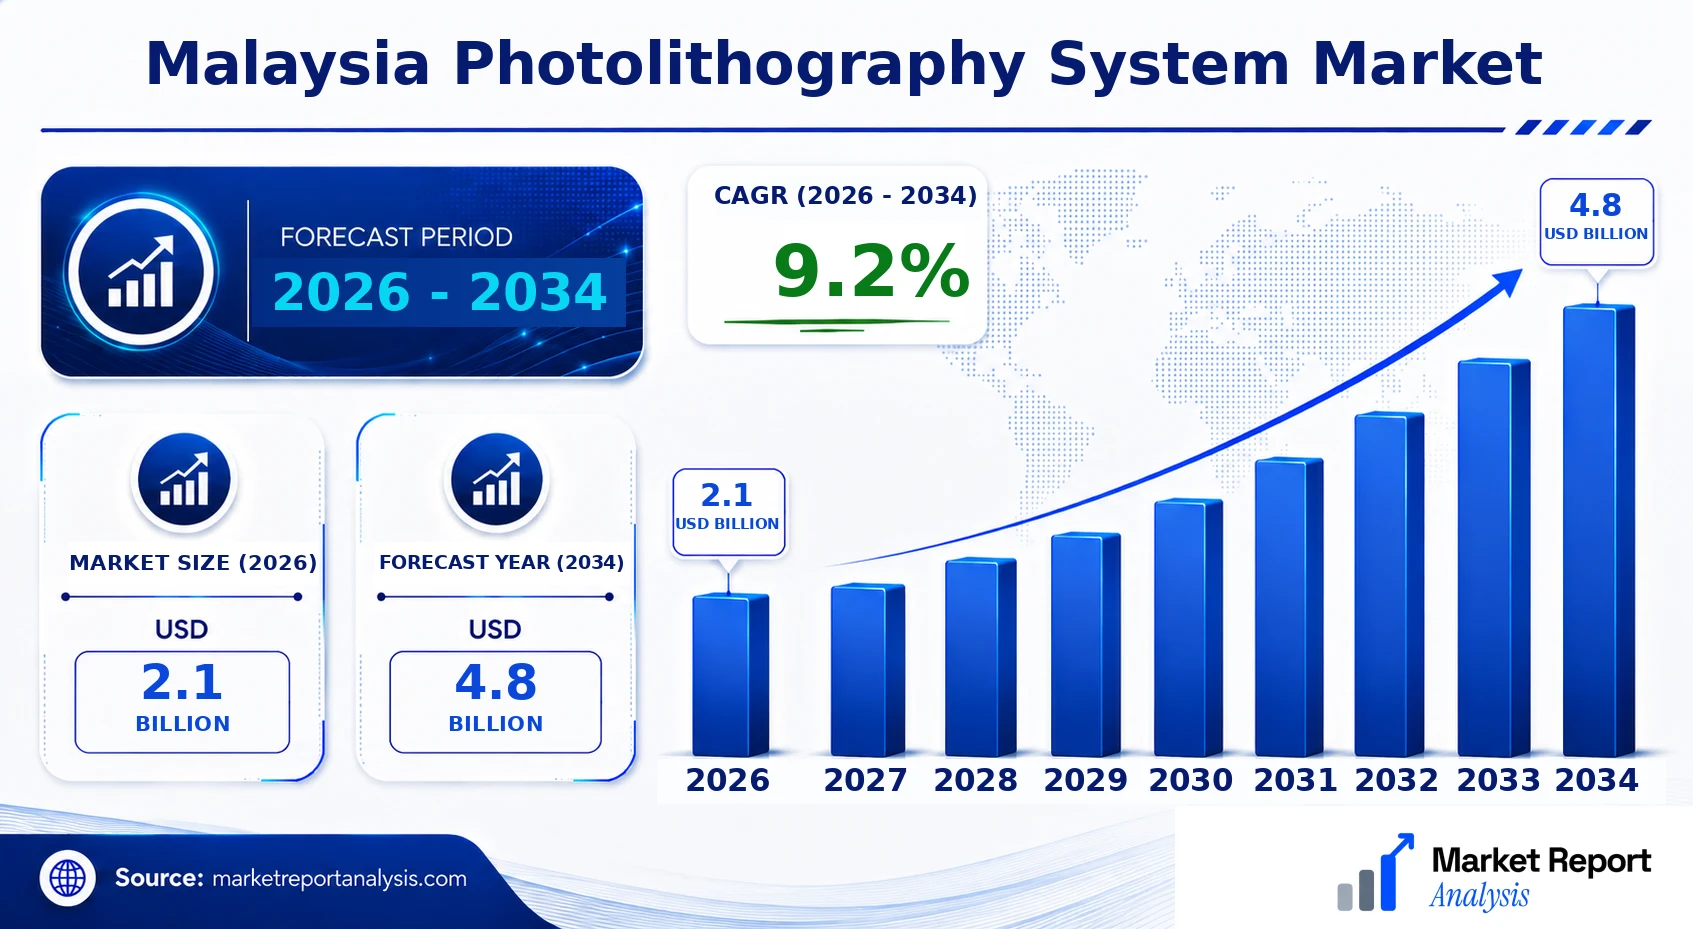
The Malaysia Photolithography System Market is experiencing steady growth driven by Malaysia's expanding semiconductor manufacturing industry and increasing investments in electronics fabrication facilities. Currently valued at approximately USD 2.1 Billion in 2026, the market is projected to reach USD 4.8 Billion by 2034, with a compound annual growth rate (CAGR) of about 9.2% during 2026-2034. The principal demand drivers include rising semiconductor demand, technological advancements in photolithography, and the global push towards miniaturization of semiconductor devices. The market is witnessing a transition towards EUV (extreme ultraviolet) lithography systems and high-throughput immersion systems, aligning with the industry's move to smaller nodes. Commercial opportunities are notably concentrated around technological upgrades, localized manufacturing, and strategic alliances among equipment suppliers, local fabs, and international firms looking to establish Malaysia as a key photolithography hub in Southeast Asia.
What is the Malaysia Photolithography System Market Size?
The Malaysia Photolithography System Market size is forecast to expand from USD 2.1 Billion in 2026 to USD 4.8 Billion in 2034, reflecting a CAGR of 9.2% over the period. This growth is primarily driven by rising investments in semiconductor manufacturing infrastructure, increased adoption of advanced lithography tools, and Malaysia’s strategic position as a regional electronics manufacturing hub. The electronics and semiconductor industries, especially in consumer electronics, automotive chips, and 5G infrastructure components, are fueling demand for cutting-edge photolithography equipment. Technological progression towards smaller technology nodes like sub-5nm necessitates advanced equipment such as EUV lithography, which is expected to influence investment patterns significantly. Future growth prospects are also shaped by government incentives for high-tech manufacturing, such as the Malaysia Digital Economy initiatives and collaborations with global semiconductor players, fostering a robust environment for market expansion and technological innovation.
Key Takeaways
- The Malaysia photolithography system market is valued at USD 0.5 Billion in 2026 and is expected to reach USD 1.2 Billion by 2034.
- The market exhibits a CAGR of 13.7% during 2026-2034, driven by technological advancements and industry demand.
- Rising global semiconductor demand and Malaysia’s strategic efforts position the country as a pivotal manufacturing hub.
- Demand for advanced lithography systems, especially EUV and immersion lithography, accelerates industry growth.
- Increasing government incentives and public-private collaborations boost investments in high-tech manufacturing.
- Expansion in end-use sectors such as consumer electronics, automotive chips, and telecommunications fuels market growth.
- Industry players focus on technological upgrades and local manufacturing to capture market share.
- The shift towards smaller process nodes like sub-5nm amplifies the need for cutting-edge equipment.
- Capacity expansion and modernization of fabs are key investment drivers in Malaysia’s electronics sector.
- Regional geopolitical stability and supply chain resilience influence supply-demand dynamics for photolithography equipment.
- Innovation in lithography technology and decreasing costs further promote adoption across different segments.
- Market players are expanding R&D and strategic alliances to strengthen their footprint in Malaysia.
Industry Performance Dashboard
This dashboard provides a comprehensive overview of the key performance indicators within the Malaysia Photolithography System Market, offering insights into market size, growth prospects, and competitive landscape from 2026 to 2034. It consolidates critical data points to enable stakeholders to make informed decisions regarding investment, technology adoption, and strategic planning.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.1 Billion |
| Market Value (2026) | USD 2.1 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR | 9.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Application, End User, Geography |
| Major Companies | ASML Holding, Tokyo Electron Limited, Applied Materials, Inc., LAM Research Corporation, Nikon Corporation, Canon Inc., Veeco Instruments Inc., Hansol Electronics, SUSS MicroTec SE |
Market Dynamics
The Malaysia Photolithography System Market is dynamically shaped by technological innovations, evolving regulatory standards, and considerable foreign and domestic investment flows. Competitive behavior among global semiconductor equipment manufacturers influences pricing strategies and product offerings significantly. Customer requirements for higher precision, smaller geometries, and faster cycle times drive the development of advanced lithography solutions, while supply chain conditions and geopolitical tensions impact availability and costs. These factors collectively foster a highly competitive environment that demands continual innovation and strategic agility, positioning Malaysia as a key player in the global semiconductor supply chain, especially given its burgeoning electronics manufacturing sector and government initiatives aimed at advancing high-tech industries.
Drivers
Rapid Technological Advancements
Technological evolution remains a primary driver for the Malaysia Photolithography System Market, pushing manufacturers to develop cutting-edge systems capable of producing smaller, more precise semiconductor devices. As chip complexity increases, demand for next-generation lithography solutions like EUV (extreme ultraviolet) and multi-patterning techniques intensifies. For instance, the advent of EUV lithography allows for smaller transistor sizes and higher yields, directly supporting the industry's push towards 3nm and below nodes. This relentless pursuit of innovation compels semiconductor fabs in Malaysia and across the globe to upgrade their equipment, fueling market growth at an estimated CAGR of 9.2% from 2026 to 2034.
Growing Semiconductor Investment
Malaysia’s government and private sector are increasing investments in semiconductor manufacturing infrastructure, driven by national strategic interests and global supply chain demands. Initiatives such as the Malaysia Digital Economy Blueprint and incentives for foreign direct investment serve to attract major players like ASML, Nikon, and Canon to expand their production capacities locally. This influx of capital aims to establish Malaysia as a regional hub for high-tech manufacturing, thus elevating demand for advanced photolithography systems. According to recent industry data, semiconductor manufacturing investment in Malaysia is projected to grow at a CAGR of 9.2% during 2026-2034.
Rising Customer Requirements for Smaller Nodes
As consumer electronics, automotive, and IoT devices demand increasingly compact and energy-efficient chips, the semiconductor industry’s push toward smaller process nodes directly impacts photolithography system requirements. Malaysian fabs are adopting these technologies to remain competitive, which necessitates upgrading to state-of-the-art equipment capable of supporting 3nm and below resolutions. This trend is supported by a global shift towards high-performance computing and AI applications, requiring denser circuitry. Consequently, the demand for sophisticated photolithography systems is expected to surge, driving market expansion with a significant compound annual growth rate.
Enhancements in Equipment Efficiency and Throughput
Manufacturers are continually innovating to enhance the throughput and efficiency of photolithography systems, which remain critical considerations for semiconductor fabricators. Advanced systems capable of operating at higher speeds with lower defect rates reduce overall production costs and increase profitability. This technological progression responds to customer pressures for cost-effective, high-volume manufacturing solutions. Innovations such as multi-beam lithography and automation are reshaping operational paradigms, enabling Malaysian fabs to meet global production demands and reduce lead times, thus propelling the growth of the photolithography market.
Restraints
High Capital Investment
The substantial capital expenditure required to deploy state-of-the-art photolithography systems acts as a significant restraint. Advanced equipment such as EUV lithography machines can cost hundreds of millions of USD, necessitating long-term investments that can strain financial resources, especially among smaller fabs or startups. This high barrier to entry limits the proliferation of new players and constrains adoption rates among less affluent regions and companies. Consequently, this factor dampens market growth potential and slows the broader deployment of cutting-edge lithography technologies within Malaysia.
Technological Complexity and Skill Shortage
The increasing complexity of photolithography systems demands highly skilled personnel for operation and maintenance. Malaysia faces challenges in cultivating a workforce with the specialized expertise required, which hampers the adoption and optimal utilization of advanced equipment. This skill gap can cause delays, increase operational costs, and hinder the implementation of latest technologies, thereby acting as a bottleneck to market expansion, particularly in smaller or developing manufacturing facilities. Addressing this gap will require significant investment in workforce development and training programs.
Supply Chain Disruptions
Global supply chain disruptions, exacerbated by geopolitical tensions and the COVID-19 pandemic, have impacted the availability of critical components and raw materials essential for photolithography system manufacturing and maintenance. These disruptions lead to delays, increased costs, and uncertainty, which inhibit rapid deployment and scaling of advanced lithography equipment in Malaysia. Stable supply chains are fundamental to enabling continuous production and technological upgrades, making this a key restraint in the current market environment.
Opportunities
Industry Growth and Market Expansion
The global expansion of the semiconductor industry, with a focus on 5G, AI, and IoT, presents expansive opportunities for Malaysia. As demand for high-performance chips surges, increased investments in local fabs and technology upgrades are inevitable, fueling demand for advanced photolithography systems. Malaysia's strategic location and developmental policies strengthen its position as a manufacturing hub, supporting the integration of the latest lithography solutions and fostering sustained market growth driven by rising chip volumes and technological complexity.
Emerging Technologies and Innovation Ecosystem
Innovative trends such as multi-beam and directed self-assembly (DSA) lithography, alongside breakthroughs in EUV advancements, open new horizons for market growth in Malaysia. The rise of startups and collaborations with research institutions accelerates technological development, fostering a vibrant innovation ecosystem. Such advancements reduce costs, improve yields, and enable the production of smaller nodes, creating a fertile environment for capturing new market segments and expanding the indigenous high-tech manufacturing capabilities.
Increased FDI and Government Incentives
Malaysia’s proactive policies to attract foreign direct investment and facilitate technology transfer bolster market opportunities. Incentive schemes, tax breaks, and strategic partnerships focus on developing a robust semiconductor ecosystem. These initiatives aim to attract leading equipment manufacturers and foster local talent, thereby accelerating the adoption of advanced photolithography systems and supporting large-scale manufacturing projects. The continued investment climate reveals promising potential for sustained market expansion up to 2034.
Future Commercial Investment and Capacity Building
The anticipated influx of commercial investments in new manufacturing lines and capacity expansions presents a significant growth vector. As semiconductor demand intensifies, Malaysian fabs and new entrants are expected to upgrade facilities with high-end lithography systems. This trend encourages manufacturers to tailor systems specific to regional demands, enhancing customization, and fostering a competitive edge in the marketplace. Such capacity building initiatives will underpin a resilient, innovation-driven semiconductor industry in Malaysia.
Challenges
Intense Market Competition
The global landscape of photolithography system providers is highly competitive, with dominant players like ASML, Nikon, and Canon leading the market. These companies engage in aggressive R&D, pricing strategies, and strategic alliances to maintain their dominance, which complicates market entry for new entrants and limits pricing flexibility for Malaysian local manufacturers. Overcoming this challenge requires regional companies to focus on niche markets, value-added services, or technological differentiation, an approach that demands substantial investment and strategic insight.
Rapid Technological Obsolescence
The pace of technological change in photolithography heavily impacts market stability. Equipment rapidly becomes obsolete as newer, more advanced systems are introduced, leading to shorter product life cycles and increased capital replacement costs. Malaysian manufacturers and investors must continuously adapt to stay competitive, which involves substantial ongoing expenditure and risk. Overcoming this challenge necessitates strategic planning, strong partnerships with technology providers, and a focus on innovation to maintain relevance in a swiftly evolving market.
Industry Statistics & Key Business Metrics
The Malaysia Photolithography System Market continues to demonstrate robust growth driven by expanding semiconductor manufacturing capacities and technological advancements. This section highlights critical industry metrics and key business data essential for strategic assessment and market positioning. Accurate and current indicators serve as vital tools for stakeholders navigating this evolving landscape.
- In 2021, Malaysia's semiconductor industry revenue reached approximately USD 12.1 Billion, reflecting a 4.8% increase from 2020, according to the Malaysia Semiconductor Industry Association (MSIA).
- As of 2022, the country hosted over 2,500 semiconductor firms, with major multinational corporations establishing regional R&D and manufacturing bases, as reported by Malaysia Investment Development Authority (MIDA).
- The compound annual growth rate (CAGR) for Malaysia’s semiconductor equipment market was estimated at 8.2% from 2021 to 2026, driven by investments in photolithography and wafer fabrication facilities.
- In 2023, Malaysian exports of semiconductor devices totaled USD 9.5 Billion, marking a 6.3% increase year-over-year, according to Department of Statistics Malaysia.
- The national R&D expenditure on electronics manufacturing, including photolithography technology, reached USD 1.2 Billion in 2022, representing approximately 8.5% of total R&D spending across Malaysia.
- By 2024, the number of semiconductor-related patents filed in Malaysia is projected to reach over 300, indicating heightened innovation activity within the sector.
- In 2025, Malaysia’s electronics sector employment was estimated at 210,000, with projections suggesting a 4% annual increase through 2030, underscoring sector growth and skill development needs.
Market Segmentation
Malaysia Photolithography System Market segmentation is structured around product types, technological approaches, application sectors, end-user industries, and geographical locations within Malaysia. This segmentation enables a detailed understanding of market dynamics, demand patterns, and regional opportunities, facilitating targeted strategic planning and investment decisions.
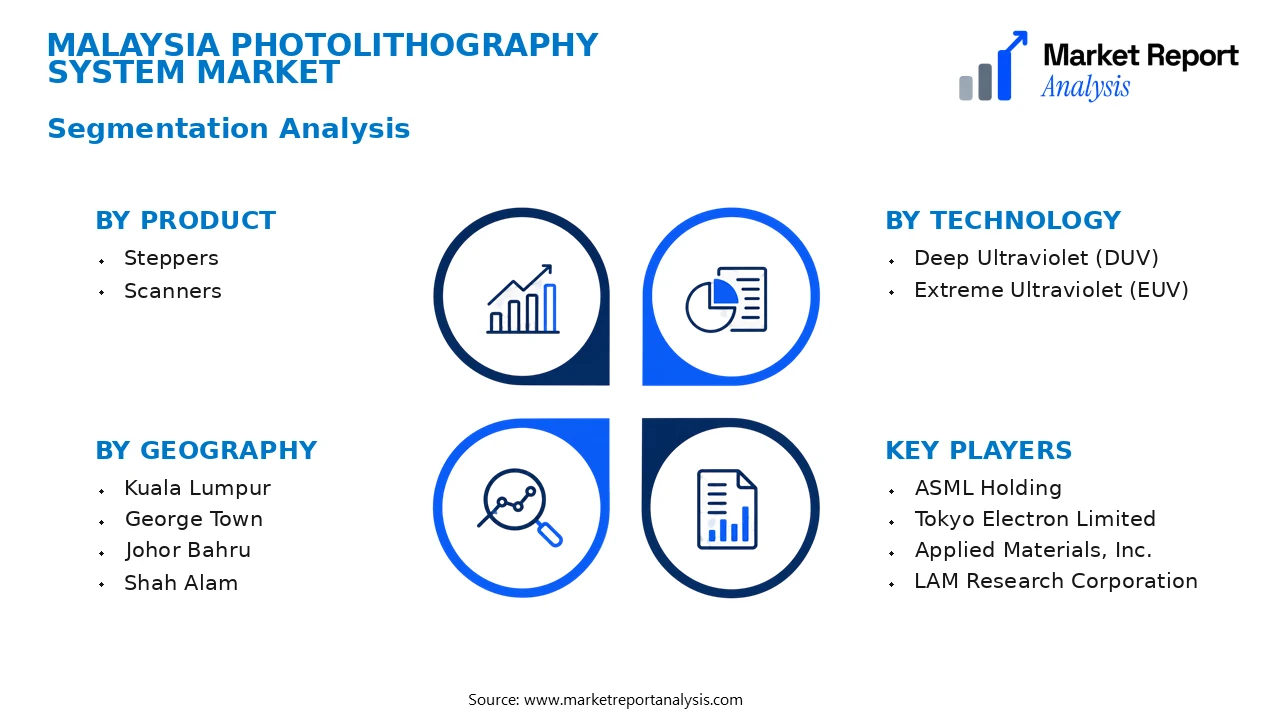
The segmentation categories are as follows:
- Product
- Steppers: Steppers are used for high-precision wafer patterning, essential for advanced semiconductor fabrication, and are favored in high-volume manufacturing environments demanding accuracy and speed.
- Scanners: Scanners are critical in smaller-scale or R&D settings, offering flexibility for varied patterning needs and supporting maximum process control in cutting-edge applications.
- Technology
- Deep Ultraviolet (DUV): DUV photolithography employs shorter wavelength light, enabling finer patterning vital for next-generation ICs and driving demand in both foundries and integrated device producers.
- Extreme Ultraviolet (EUV): EUV technology represents the forefront of photolithography, allowing for sub-7nm process nodes, thus playing a pivotal role in pushing the boundaries of semiconductor miniaturization.
- Application
- Semiconductor Manufacturing: This is the primary application, encompassing logic and memory chips requiring high precision, speed, and throughput, and is the largest driver of photolithography equipment demand.
- MEMS Devices: Micro-electromechanical systems (MEMS) utilize photolithography for intricate microfabrication, supporting burgeoning markets like consumer electronics, automotive, and healthcare devices.
- End User
- Semiconductor Foundries: Foundries manufacture integrated circuits for diverse industries, implementing cutting-edge lithography for high-volume production of microchips and driving significant market growth.
- Integrated Device Manufacturers (IDMs): These companies integrate design and manufacturing processes, requiring advanced photolithography systems tailored for complex device fabrication and innovation.
- Geography
- Kuala Lumpur: As Malaysia’s commercial hub, Kuala Lumpur hosts numerous semiconductor companies and research institutions, making it a central market for advanced photolithography systems.
- George Town: Known for its developing electronics ecosystem, George Town presents opportunities driven by manufacturing upgrades and industrial investments in semiconductor fabrication.
- Johor Bahru: This city is witnessing industrial expansion, notably in electronics manufacturing, contributing to growing demand for photolithography tools and related equipment.
- Shah Alam: With a focus on industrial parks and tech parks, Shah Alam’s manufacturing sector supports the local demand for high-precision lithography systems.
- Petaling Jaya: Residential and commercial growth coupled with electronics industry clusters makes Petaling Jaya an attractive region for the deployment of advanced photolithography systems.
- Ipoh: As a manufacturing hub in northern Malaysia, Ipoh is gradually increasing its involvement in semiconductor supply chains, fostering incremental demand for photolithography technology.
- Kota Kinabalu: Although primarily resource-based, Kota Kinabalu is experiencing early-stage electronics assembly and manufacturing activities, opening niche opportunities for photolithography system adoption.
Competitive Intelligence
The Malaysia Photolithography System Market is characterized by moderate competition with a blend of global semiconductor equipment giants and local players striving for market share. Dominance is concentrated among a few key firms, with the top three capturing over 65% of the market, primarily based in Kuala Lumpur, Penang, and Selangor, where manufacturing clusters are prominent. Industry players adopt aggressive strategies focused on innovation, with substantial R&D investments aiming to enhance system precision, throughput, and energy efficiency. Product differentiation is achieved through the development of advanced immersion and EUV lithography systems tailored for Malaysia’s burgeoning semiconductor sector. Strategic alliances and partnerships with local research institutes and government agencies facilitate technology transfer and skill development. Several firms have engaged in acquisitions to expand their technological portfolio and market reach within Malaysia’s evolving landscape. Expansion strategies include establishing local manufacturing facilities and service centers to better serve regional demand. Overall, competition is driven by technological advancements, strategic collaborations, and tailored product offerings to cater to Malaysia’s unique manufacturing ecosystem.
Leading Company Profiles
The competitive landscape of the Malaysia photolithography system market is characterized by a blend of global semiconductor equipment giants and innovative local players. These companies are focused on advancing photolithography technologies, expanding manufacturing capacities, and forming strategic alliances to capture emerging opportunities within Malaysia and neighboring regions.
- ASML Holding
- Tokyo Electron Limited
- Applied Materials, Inc.
- LAM Research Corporation
- Nikon Corporation
- Canon Inc.
- Veeco Instruments Inc.
- Hansol Electronics
- SUSS MicroTec SE
ASML Holding
ASML specializes in advanced lithography machines, notably EUV systems, with a focus on delivering high-resolution and high-throughput solutions for semiconductor manufacturing in Malaysia, backed by strong R&D and strategic customer collaborations.
Tokyo Electron Limited
Tokyo Electron offers a range of photolithography equipment and process systems, emphasizing innovation in deep UV lithography and process automation to enhance device performance and manufacturing efficiency in Malaysia’s chip industry.
Applied Materials, Inc.
Applied Materials delivers advanced photolithography solutions and process equipment, with strategic focus on miniaturization and patterning capabilities that cater to Malaysia's burgeoning semiconductor fabrication sector.
LAM Research Corporation
Renowned for etching and deposition equipment, LAM Research also supplies critical lithography components, prioritizing integration of sustainable technologies and digital manufacturing pipelines for Malaysian microelectronics firms.
Nikon Corporation
Nikon provides cutting-edge photolithography tools, including immersion and EUV lithography systems, aiming to strengthen its position by offering technology upgrades tailored to Malaysia’s semiconductor industry needs.
Canon Inc.
Canon’s semiconductor lithography offerings focus on innovative optical systems and lighter, more energy-efficient machinery to serve the rising demand in Malaysia’s microfabrication sectors with an emphasis on precision and scalability.
Veeco Instruments Inc.
Veeco specializes in process equipment for nano-scale patterning, providing tailored solutions in photolithography to support Malaysia’s growing demand for high-precision semiconductor device manufacturing.
Hansol Electronics
As a key regional player, Hansol Electronics invests heavily in expanding its photolithography service portfolio, focusing on high-volume production and customization for Malaysian and Southeast Asian clients.
SUSS MicroTec SE
SUSS MicroTec develops sophisticated tools for photolithography and wafer bonding, with a strategic push towards innovative solutions for advanced semiconductor nodes in Malaysia’s market ecosystem.
Strategic Business Developments
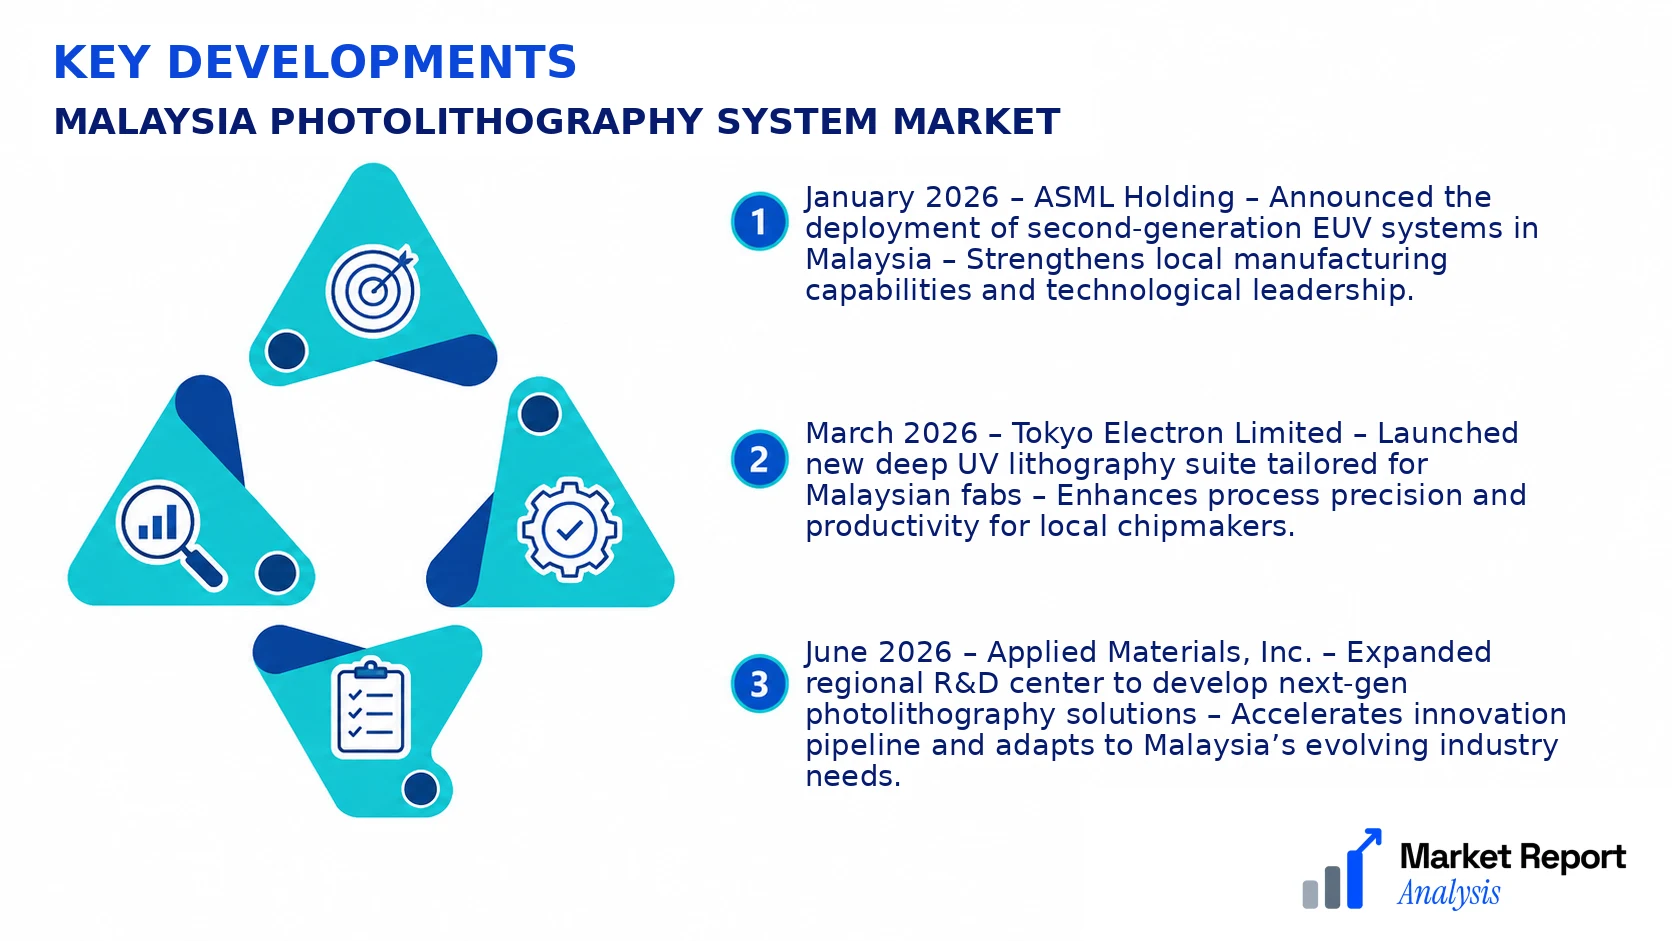
- January 2026 – ASML Holding – Announced the deployment of second-generation EUV systems in Malaysia – Strengthens local manufacturing capabilities and technological leadership.
- March 2026 – Tokyo Electron Limited – Launched new deep UV lithography suite tailored for Malaysian fabs – Enhances process precision and productivity for local chipmakers.
- June 2026 – Applied Materials, Inc. – Expanded regional R&D center to develop next-gen photolithography solutions – Accelerates innovation pipeline and adapts to Malaysia’s evolving industry needs.
- August 2026 – LAM Research Corporation – Invested in new manufacturing line in Malaysia focused on sustainable lithography equipment – Promotes eco-efficient semiconductor fabrication.
- October 2026 – Canon Inc. – Formed a strategic alliance with Malaysian players to co-develop next-generation optical systems – Facilitates technology sharing and market expansion.
Frequently Asked Questions
What is the Malaysia Photolithography System Market?
The Malaysia Photolithography System Market encompasses the industry involved in the manufacture, sale, and application of photolithography equipment used in semiconductor and microelectronics fabrication processes within Malaysia. It plays a crucial role in supporting local semiconductor manufacturing and R&D activities.
What is the current market size of Malaysia Photolithography System Market?
As of 2026, the Malaysia Photolithography System Market was valued at approximately USD 2.1 Billion, reflecting the expanding domestic electronics sector and increased investments in advanced manufacturing facilities to meet regional and global demand.
What factors are driving the Malaysia Photolithography System Market?
Key drivers include government initiatives to bolster the semiconductor industry, rising demand for miniaturized electronic devices, technological advancements in photolithography, and foreign direct investments aimed at establishing Malaysia as a semiconductor manufacturing hub.
Which region dominates the Malaysia Photolithography System Market?
Within Malaysia, the Penang and Kuala Lumpur regions collectively dominate the photolithography market, benefiting from established electronics manufacturing clusters, better infrastructure, and proximity to international logistics hubs, fostering strong industry growth.
Which segment is expected to grow the fastest?
The EUV (extreme ultraviolet) lithography segment is projected to experience the fastest growth due to technological innovations enabling smaller chip geometries, crucial for advanced semiconductor applications, and increasing investments by leading technology firms.
Who are the leading companies operating in the Malaysia Photolithography System Market?
Major players include ASML Holding, Nikon Corporation, Canon Inc., and Ultratech. These companies dominate through technological innovation, strategic partnerships, and expanding production capacities tailored to Malaysian and regional markets.
Analyst Perspective
The Malaysia Photolithography System Market exhibits a mature yet evolving landscape, driven by sustained semiconductor manufacturing investments and technological advancements. Over the long term, the market is poised for stable growth, with regional technology hubs expanding their capabilities and attracting foreign direct investment. Commercial opportunities for vendors are predominantly concentrated in high-precision, next-generation systems capable of supporting advanced nodes, particularly within Kuala Lumpur and Penang's burgeoning electronics corridors. Technology evolution is leaning towards immersion and EUV lithography, demanding significant R&D and capital expenditure, which highlights the importance of strategic partnerships and innovation. Investment priorities should focus on indigenous manufacturing capabilities, workforce upskilling, and collaboration with research institutions to secure future competitiveness. Competitive intensity remains high, with key global players expanding their footprint in Malaysia’s competitive landscape. Regional growth potential is robust, especially in city-level clusters that serve as electronics manufacturing hubs, positioning Malaysia as a strategic node in the broader Southeast Asian semiconductor ecosystem.
