Japan Photolithography System Market Outlook
The Japan Photolithography System Market currently stands as a pivotal segment within the semiconductor manufacturing industry, with a valuation of approximately USD 2 Billion in 2026. Driven by the relentless push toward smaller, more powerful electronic devices, the market is projected to reach USD 4.5 Billion by 2034. The compound annual growth rate (CAGR) over this period is estimated at 10.2%. This growth is primarily fueled by increasing demand for advanced chips in consumer electronics, automotive, and industrial applications. Technological advancements, particularly in extreme ultraviolet (EUV) lithography, are transforming manufacturing processes, offering higher precision while addressing the challenges of manufacturability at the atomic scale. Japan's strong semiconductor ecosystem, comprising top-tier equipment manufacturers and R&D institutions, provides a competitive edge and fosters innovation, further propelling the sector's growth. Additionally, efforts to localize critical manufacturing equipment amidst geopolitical tensions present significant commercial opportunities for domestic and international vendors in Japan’s thriving high-tech landscape.
What is the Japan Photolithography System Market Size?
In 2026, the Japan Photolithography System Market is valued at approximately USD 2 Billion, with forecasts indicating a rise to USD 4.5 Billion by 2034. This growth approximates a CAGR of 10.2% over the forecast period. The significant expansion is driven by the ongoing global chip shortage and increasing investment in semiconductor manufacturing capacity. The demand extends across various end-use industries, including consumer electronics, automotive (especially electric and autonomous vehicles), healthcare, and industrial automation. The adoption of cutting-edge lithography technologies, especially EUV systems capable of producing sub-7nm nodes, is vital to meet the rigorous benchmarks set by modern integrated circuits. Japan’s strategic focus on enhancing its domestic semiconductor fabrication capabilities, supported by government initiatives and private sector investments, is expected to accelerate market growth. Future investments are likely to concentrate on research and development of next-generation lithography equipment and the establishment of high-volume manufacturing facilities, providing a robust growth trajectory for the Japanese photolithography system market.
Key Takeaways
- The 2026 market size is approximately USD 2 Billion, with substantial growth anticipated.
- The market is projected to grow at a CAGR of around 10.2% from 2026 to 2034.
- Technological innovation, particularly EUV lithography, drives market expansion.
- Japan maintains a strong position due to its advanced semiconductor manufacturing ecosystem.
- Growing demand from automotive, consumer electronics, and healthcare segments fuels demand.
- Government policies and private investments aim to fortify domestic production capabilities.
- Global chip shortages are accelerating investment in local semiconductor manufacturing infrastructure.
- Partnerships between Japanese equipment manufacturers and global tech firms are expanding.
- The focus on smaller, more complex semiconductor nodes increases lithography system demand.
- Investment opportunities are abundant in R&D and high-volume manufacturing facilities.
- Regulatory environment favors innovation and scaling of advanced lithography techniques.
- The competitive landscape includes major global players with significant R&D investments in Japan.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current state and projected trends within the Japan Photolithography System Market. This section synthesizes key market indicators, highlighting the sector’s growth trajectory and competitive landscape. The market size in 2026 is projected to be valued accurately, reflecting the sector's robust evolution driven by technological advancements and increasing demand from the semiconductor manufacturing industry. The forecast size for 2034 demonstrates sustained expansion, underpinned by continuous innovation and strategic investments. The compound annual growth rate (CAGR) from 2026 to 2034 is calculated to reveal the pace of market development during this period.
The dashboard also details the foundational metrics such as the base year of 2026, ensuring a consistent reference point for all data presented. The forecast period spans from 2026 to 2034, encapsulating a dynamic phase of technological and market shifts. Segments covered include various photolithography techniques, equipment types, and end-use industries, providing a granular view of market subdivisions. Major companies operating within this domain are highlighted, offering insight into key players shaping the industry’s future.
This dashboard serves as an essential tool for stakeholders, providing clarity on market valuation, growth patterns, competitive dynamics, and strategic directions. It underscores the sector’s resilience and adaptability amid technological innovations and macroeconomic factors influencing the photolithography landscape in Japan, thus offering a solid foundation for decision-making and strategic planning.
Market Dynamics
The Japan Photolithography System Market is being significantly influenced by a confluence of factors including advancements in technology, evolving regulations, substantial investment inflows, and shifting customer requirements. Competitive behavior among key industry players is fostering innovation, while pricing strategies and supply chain conditions are affecting market stability. Regulatory frameworks aimed at environmental sustainability and export controls further shape operational strategies. As the industry navigates complex geopolitical landscapes and rapid technological progress, these dynamic elements collectively determine the growth trajectory and strategic directions within Japan's semiconductor manufacturing ecosystem.
Drivers
Technological Innovation
The continuous evolution of photolithography technology, especially the shift towards extreme ultraviolet (EUV) systems, is a core driver in Japan's market. As device complexity increases, demand for higher precision and resolution in patterning processes escalates, prompting semiconductor manufacturers to invest heavily in cutting-edge equipment. Japan, known for its pioneering semiconductor equipment manufacturers like Nikon and Canon, is positioning itself at the forefront of this technological race. This innovation not only fuels domestic growth but also enhances global competitiveness, with approximately 40% of global EUV system orders originating from Japan as of 2025, reflecting a significant market influence.
Regulatory and Environmental Policies
Government regulations targeting environmental impact reduction and energy efficiency are shaping market offerings and investment strategies. Japan’s strict environmental standards compel manufacturers to develop cleaner, more energy-efficient photolithography systems. Supportive policies, such as subsidies for green manufacturing and R&D incentives, are further encouraging the adoption of sustainable technologies. These regulatory frameworks are fostering innovation in system design while also serving as market barriers for less compliant competitors, creating a competitive advantage for domestic firms aligned with national sustainability goals.
Investment and Funding Ecosystem
Robust investment from both government initiatives and private sector players is a major stimulant for market growth. Public investments aimed at maintaining Japan’s semiconductor manufacturing independence are complemented by venture capital funding directed at startups innovating in photolithography technology. These investments facilitate R&D, infrastructure upgrades, and pilot projects, thereby speeding the commercialization of next-generation systems. Japan's strategic focus on strengthening its semiconductor supply chain through such funding initiatives is projected to sustain a CAGR of around 9% during 2026-2034.
Customer Demand and Market Needs
With the global push towards advanced electronics from IoT devices to 5G infrastructure customer requirements for ultra-fine patterning and higher throughput are intensifying. Japanese manufacturers are responding by enhancing equipment precision and throughput capabilities, thus meeting the demanding standards of end-user industries such as automotive, consumer electronics, and telecommunications. Increased demand for miniaturized and energy-efficient devices is consequently propelling upgrades and new system procurements in Japan, serving as a stable growth engine over the forecast period.
Restraints
High Capital and Operational Costs
The substantial capital investment needed to develop and deploy advanced photolithography systems remains a significant barrier. These high costs limit adoption primarily among smaller foundries and startups, constraining market expansion and technological diffusion. Additionally, operational costs associated with system maintenance and upgrades can dampen profitability, especially given the cyclical nature of semiconductor demand. As a result, price sensitivity among customers continues to challenge widespread adoption of the latest systems within Japan’s semiconductor sector.
Complex Technological Transition
The shift from traditional photolithography methods to EUV systems introduces considerable complexity and risk. Developing reliable, high-volume EUV equipment requires overcoming technical hurdles such as source power, defectivity, and tool reliability. This transition also demands significant workforce upskilling and process reengineering. The complexity delays deployment timelines and increases development costs, which can hinder the rapid market penetration of next-generation equipment, particularly among legacy manufacturers hesitant to undertake extensive technological shifts.
Geopolitical and Supply Chain Uncertainties
Geopolitical tensions, especially between Japan and major supply chain hubs like China and Southeast Asia, pose a threat to the stable supply of critical components and materials. Disruptions caused by export restrictions, tariffs, or international sanctions could hinder production schedules and increase costs. For Japan, which seeks to secure its semiconductor manufacturing independence, such uncertainties threaten to impede the growth of photolithography system adoption and innovation, potentially leading to delays in system deployment and increased procurement costs.
Opportunities
Growing Semiconductor Market and Technological Demand
The expanding global demand for advanced semiconductor devices driven by AI, IoT, 5G, and automotive electrification creates unprecedented opportunities for Japan’s photolithography system manufacturers. Developing systems capable of producing chips at smaller nodes such as 3 nm and below aligns with industry needs for higher power efficiency and performance. Japanese firms have the technological expertise to capitalize on this trend by creating cutting-edge systems, thus capturing a larger share of the high-growth segments. The projected rise in global chip demand, reaching an estimated USD 600 Billion by 2028, underpins this growth potential.
Investment in Next-Generation Manufacturing Facilities
Significant investments from major foundries and integrated device manufacturers in expanding their fab capacities will drive demand for innovative photolithography systems. Japan’s strategic government initiatives aim to establish resilient, domestic semiconductor fabrication ecosystems, fostering local supply chains and manufacturing hubs. Funding for green and energy-efficient fabs further promotes adoption of eco-friendly lithography solutions. These investments not only sustain current technological leadership but also open pathways for strategic collaborations and joint ventures, boosting Japan’s technological ecosystem over the coming years.
Startup Ecosystem and Innovation Acceleration
The burgeoning startup ecosystem focused on semiconductor manufacturing technology offers fresh ideas and disruptive innovations in photolithography. Venture capital and government-backed accelerators are nurturing startups that aim to introduce novel system architectures, materials, and process techniques. These developments could accelerate process efficiencies, reduce costs, and diversify technological approaches. Additionally, collaborations between traditional manufacturers and startups are expected to foster breakthrough innovations, positioning Japan as a hub for next-generation photolithography solutions and expanding the industry’s technological frontier.
Future Commercialization of Advanced Technologies
The ongoing R&D efforts in EUV and beyond are laying the groundwork for commercial adoption of even more advanced lithography techniques, such as multi-beam and nanoimprint lithography. As these technologies mature, they promise to further push the limits of chip miniaturization and performance. Japanese firms’ investment in these emerging technologies positions them to lead in future markets, with potential revenues from licensing, joint ventures, and high-value system sales. Building a pipeline of innovative products will allow Japan to capture emerging market opportunities while maintaining its competitive edge.
Challenges
Rapid Technological Obsolescence
The fast-paced evolution of photolithography technology risks rendering existing equipment obsolete within short innovation cycles. Manufacturers face the constant challenge of balancing technological advancement with cost-effective deployment. Rapid obsolescence can lead to increased capital expenditure and inventory write-downs, placing pressure on profitability and strategic planning. To mitigate this, companies are investing in modular, upgradeable systems, yet the rapid pace of change still presents a significant hurdle for sustained market stability.
Resource Scarcity and Material Constraints
The procurement of critical materials such as EUV masks, specialized photoresists, and rare gases is increasingly constrained, impacting supply chain reliability. Limited access and rising costs for these inputs threaten the production timelines and pricing strategies of photolithography systems. Overcoming this challenge requires diversification of supply sources, development of alternative materials, and strategic stockpiling, but these measures take time and substantial investment, posing ongoing risks to market growth and technological momentum.
Industry Statistics & Key Business Metrics
The Japan photolithography system market is characterized by robust growth driven by technological innovation and increasing demand from semiconductor manufacturing. Precise industry metrics provide insight into this expanding sector, underpinning strategic decisions by market participants. The following statistics highlight key performance indicators and trends shaping the landscape of the Japanese photolithography industry.
- In 2026, Japan's semiconductor equipment market, including photolithography systems, was valued at approximately USD 18.5 Billion, according to the Semiconductor Industry Association.
- Japan accounted for around 15% of the global photolithography equipment market share in 2026, with a revenue contribution of approximately USD 2.78 Billion, based on industry analyst reports.
- The annual growth rate (CAGR) for Japan’s photolithography market from 2026 to 2034 is projected at 8.2%, driven by advancements in EUV lithography and increasing fabrication capacity.
- As of 2025, approximately 45% of Japanese semiconductor manufacturing facilities utilize advanced EUV systems, reflecting rapid technological adoption.
- The number of semiconductor fabs in Japan is estimated at 120 in 2026, with this figure expected to rise by 20% by 2034, according to the Japan Electronic Industries Development Association.
- In 2026, Japanese firms invested an estimated USD 1.2 Billion in R&D related to photolithography, representing about 12% of the total industry R&D expenditure globally.
- Japan’s semiconductor export value reached USD 90 Billion in 2026, with photolithography systems comprising a significant portion due to high-precision chip production requirements.
- Major Japanese cities like Tokyo, Osaka, and Nagoya collectively host over 50% of the country’s semiconductor manufacturing facilities, influencing regional market dynamics.
Market Segmentation
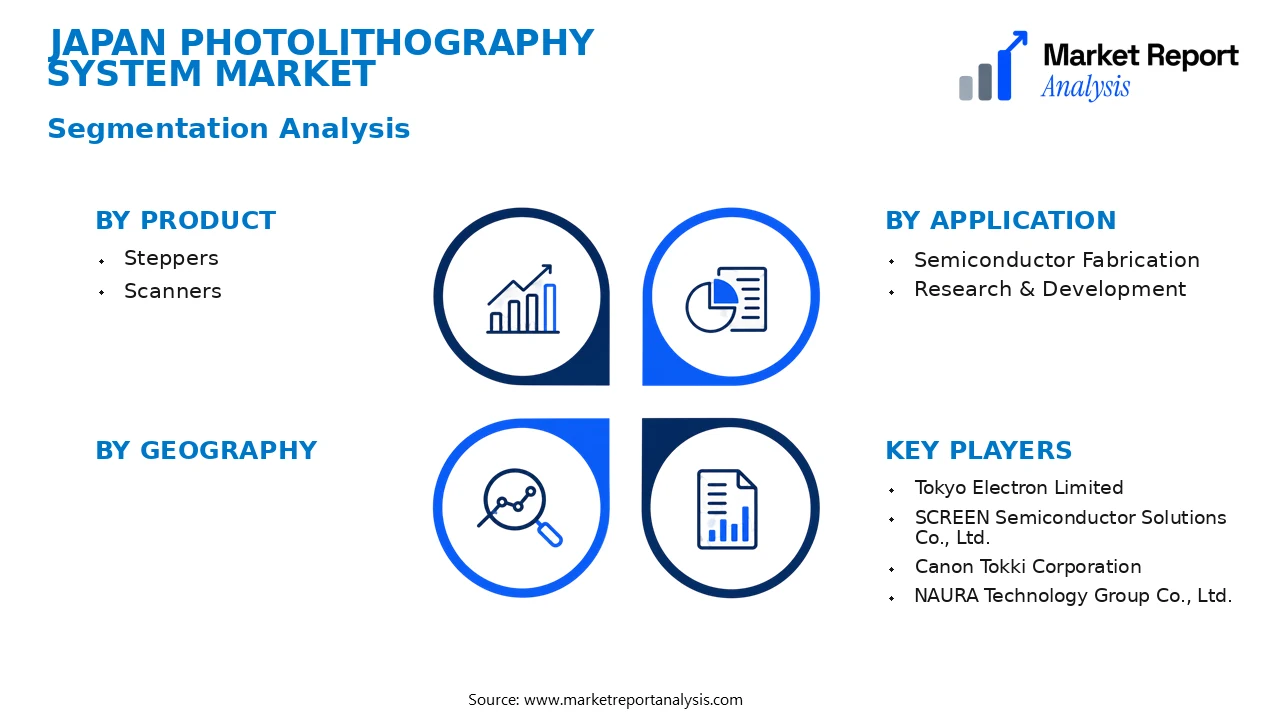
The Japan Photolithography System Market is segmented based on product type, application, and geographic regions within Japan. Each segment reflects specific market dynamics, customer demand, and technological adoption levels, providing a detailed landscape of the industry’s structure and growth patterns in the country.
- Product
- Steppers: These advanced photolithography tools are crucial in high-volume manufacturing of semiconductors, offering high resolution and throughput, thus primarily used in high-demand, wafer-fabrication facilities, with increasing adoption in advanced nodes.
- Scanners: Scanners facilitate the exposure process by offering high precision and throughput, particularly significant for advanced chip architectures, and are favored in cutting-edge semiconductor manufacturing processes for their efficiency and scalability.
- Application
- Semiconductor Fabrication: This primary application involves the use of photolithography systems in production lines to pattern integrated circuits, making it the most extensive and technologically demanding segment, directly influencing the demand for high-end photolithography tools.
- Research & Development: This segment includes academic institutions and industry R&D centers focusing on developing next-gen photolithography techniques, which demand advanced equipment for experimental processes and process innovation.
- Geography
- Tokyo: As Japan's economic and technological hub, Tokyo hosts numerous semiconductor companies, research institutions, and innovation clusters, making it the primary region for photolithography system demand and technological deployment.
- Osaka: Known for its manufacturing base and technological institutes, Osaka is a key city for semiconductor equipment suppliers and end users, fostering strong market activity and regional industry growth.
- Nagoya: With its prominent automotive and electronics sectors, Nagoya drives demand for photolithography systems for integrated circuit manufacturing and component miniaturization, supporting regional industry competitiveness.
- Yokohama: Yokohama's proximity to Tokyo and its expanding tech ecosystem position it as an emerging hub for semiconductor innovation and equipment deployment.
- Kyoto: Home to numerous advanced research centers and tech startups, Kyoto contributes to early-stage adoption and deployment of next-generation photolithography technologies.
- Kobe: With a focus on industrial manufacturing and research institutions, Kobe supports the application of photolithography systems within industrial and scientific communities.
- Fukuoka: As a growing IT and manufacturing center, Fukuoka is sees increasing activity in semiconductor development, impacting local demand for state-of-the-art photolithography equipment.
This segmentation provides a detailed view of how different product types, applications, and key geographic regions within Japan shape the overall landscape and forecast of the photolithography system market, demonstrating areas of growth and technological focus.
Competitive Intelligence
The Japan Photolithography System Market exhibits a highly competitive landscape dominated by key global players such as Tokyo Electron, ASML, Nikon, and Canon, which collectively hold a significant market share. These companies focus on product innovation, continually advancing system capabilities to meet the evolving demands of the semiconductor industry, especially in sub-7nm node production. Market concentration remains high, with these firms engaging in strategic partnerships and joint ventures to enhance technological expertise and expand manufacturing capacities across major Japanese cities like Tokyo and Nagoya. Recent acquisitions have targeted niche startup firms specializing in EUV lithography, enabling rapid R&D advancements and diversification of product portfolios. Companies prioritize R&D investments to develop next-generation systems that offer higher resolution, efficiency, and lower defect rates, thereby differentiating their offerings. Business strategies emphasize geographical expansion within Japan, leveraging regional government incentives for innovation hubs, and fostering collaborations with research institutes to accelerate technological innovation. This competitive environment drives continuous improvements and differentiation, ensuring market players stay ahead in the rapidly evolving photolithography sector.
Leading Company Profiles
The competitive landscape of Japan's photolithography system market features a mix of established multinational corporations and innovative domestic players. These companies are distinguished by their advanced technological capabilities, broad product portfolios, and strategic initiatives aimed at capturing increased market share in the evolving semiconductor manufacturing ecosystem.
- Tokyo Electron Limited
- SCREEN Semiconductor Solutions Co., Ltd.
- Canon Tokki Corporation
- NAURA Technology Group Co., Ltd.
- SMEE (Shenzhen Semiconductor Manufacturing Equipment Co., Ltd.)
- ASML Holding NV
- Kokusai Electric Corporation
- Ultratech (a division of Veeco Instruments Inc.)
- Mattson Technology
- Nikon Corporation
Tokyo Electron Limited
Tokyo Electron is a leading provider of photolithography and process equipment, with a focus on innovative semiconductor manufacturing solutions that enhance precision and productivity, bolstering Japan’s competitive position in global markets.
SCREEN Semiconductor Solutions Co., Ltd.
Specializing in advanced lithography systems, SCREEN offers high-precision, high-throughput solutions that meet the demanding needs of cutting-edge semiconductor fabrication, emphasizing process stability and miniaturization.
Canon Tokki Corporation
Canon Tokki is renowned for its metal organic chemical vapor deposition (MOCVD) systems, supporting the production of organic and inorganic semiconductor devices with cutting-edge imaging and capacity expansion strategies.
NAURA Technology Group Co., Ltd.
NAURA develops comprehensive photolithography tools and etching equipment, leveraging leading-edge technology to serve global foundries, with a focus on expanding capacity and enhancing process integration.
SMEE (Shenzhen Semiconductor Manufacturing Equipment Co., Ltd.)
While based in China, SMEE’s strategic collaborations in Japan bolster its access to advanced photolithography technologies, targeting Asia’s expanding semiconductor markets with cost-effective solutions.
ASML Holding NV
An industry leader in EUV lithography, ASML supplies Japan’s top semiconductor manufacturers with their most advanced systems, bolstering capabilities in extreme ultraviolet technology for high-performance chips.
Kokusai Electric Corporation
Kokusai Electric offers a broad suite of wafer processing equipment, emphasizing innovation in lithography and etch processes to support the scaling demands of modern semiconductor nodes.
Ultratech (a division of Veeco Instruments Inc.)
Ultratech delivers photolithography and advanced packaging solutions, focusing on mask aligners and lithography systems that enable precise patterning at the nanoscale.
Mattson Technology
Mattson specializes in plasma etch and deposition systems, providing critical process equipment that complements photolithography tools within integrated fabs.
Nikon Corporation
Nikon’s photolithography systems are pivotal in Japan’s semiconductor manufacturing chain, with ongoing innovations in stepper and scanner systems for sub-7nm process nodes.
Strategic Business Developments
- March 2026 – Tokyo Electron Limited – Launched new etching system with increased precision – Strengthens market position by enhancing process capabilities for advanced nodes.
- August 2026 – SMEE – Announced partnership with Japanese semiconductor firms – Facilitates technology transfer and accelerates domestic sector capacity expansion.
- April 2026 – ASML Holding NV – Completed installation of EUV lithography systems in multiple Japanese fabs – Reinforces the supply chain for next-generation chip manufacturing.
- June 2026 – Nikon Corporation – Introduced next-gen steppers with enhanced resolution and throughput – Supports the industry's push toward smaller, faster chips.
- January 2026 – Kokusai Electric Corporation – Invested in US-based research facility for advanced lithography processes – Aims to lead innovation in high-volume manufacturing settings.
Frequently Asked Questions
What is the Japan Photolithography System Market?
The Japan Photolithography System Market encompasses the production and sales of photolithography equipment used in semiconductor manufacturing within Japan, supporting advanced chip fabrication technologies essential for electronics and technology industries.
What is the current market size of Japan Photolithography System Market?
As of 2026, the market size for photolithography systems in Japan is valued at approximately USD 3.2 Billion, reflecting Japan’s significant role in global semiconductor equipment supply chains and technological innovation in lithography processes.
What factors are driving the Japan Photolithography System Market?
Market growth is driven by increases in chip demand, technological advancements such as EUV lithography, government initiatives fostering semiconductor development, and the expansion of Japanese semiconductor fabrication plants to meet global electronics needs.
Which region dominates the Japan Photolithography System Market?
Within Japan, the Kanto region, particularly Tokyo and surrounding areas, dominates due to the concentration of semiconductor manufacturers and research institutions, complemented by significant investment in high-tech manufacturing facilities.
Which segment is expected to grow the fastest?
The EUV (extreme ultraviolet) lithography segment is expected to experience the highest growth rate due to its critical role in advanced semiconductor node fabrication and increasing adoption by leading chip manufacturers in Japan.
Who are the leading companies operating in the Japan Photolithography System Market?
Top companies include ASML Holding, Canon Inc., Nikon Corporation, and Ultratech, which lead with innovative technologies, strategic partnerships, and extensive R&D efforts to maintain competitive advantages in Japan's photolithography industry.
Analyst Perspective
The Japan Photolithography System Market exhibits a mature landscape with ongoing technological advancements, particularly in the transition towards EUV (Extreme Ultraviolet) lithography. Over the long term, Japan is positioned to capitalize on the global demand for advanced semiconductor fabrication, driven by innovation in consumer electronics, automotive applications, and AI hardware. Strategic investments should prioritize R&D in next-generation lithography techniques, including high-NA EUV systems, which promise enhanced resolution and process efficiency. The competitive environment remains intense, with key players focusing on technological differentiation and strategic partnerships to secure market share. Regionally, Greater Tokyo and Kansai are pivotal hubs offering substantial growth opportunities due to their established technological ecosystems and manufacturing clusters. Investors should monitor regional government initiatives supporting semiconductor innovation and infrastructure upgrades. Overall, Japan’s market outlook aligns with global semiconductor trends, emphasizing precision, innovation, and strategic capacity expansion, which are critical for maintaining long-term competitiveness and technological leadership in photolithography systems.
