Photolithography System Market Outlook
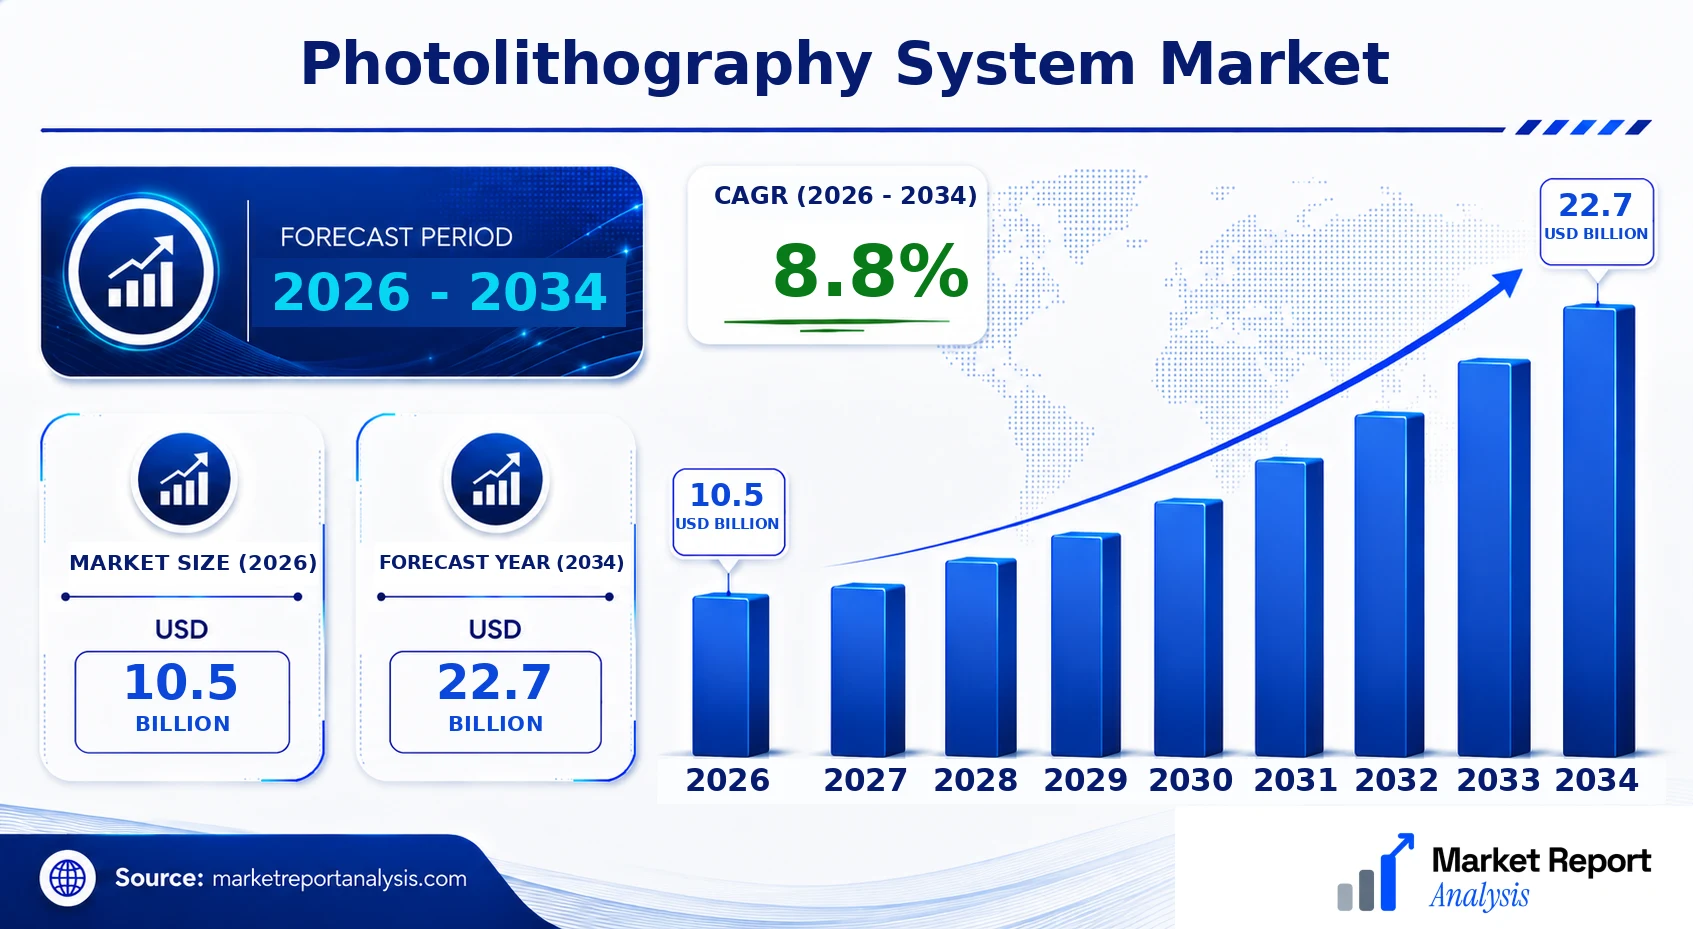
The global photolithography system market is on an upward trajectory, driven by rapid advancements in semiconductor manufacturing and the expansive growth of electronics industries worldwide. Currently valued at approximately USD 10.5 Billion in 2026, the market is projected to escalate to about USD 22.7 Billion by 2034. This growth is expected to be underpinned by a compound annual growth rate (CAGR) of approximately 8.8% during the forecast period from 2026 to 2034. Key demand drivers include the relentless miniaturization of electronic components, increasing demand for high-performance chips, and technological innovations such as immersive EUV (Extreme Ultraviolet) lithography. The primary technological trend is moving towards next-generation EUV systems, which promise higher precision and smaller feature sizes. Commercial opportunities are abundant in developing advanced lithography tools, upgrading existing fabrication lines, and expanding manufacturing capacity particularly in Asia-Pacific regions, where semiconductor production hubs are proliferating.
What is the Photolithography System Market Size?
In 2026, the photolithography system market is valued at approximately USD 10.5 Billion. It is forecasted to reach USD 22.7 Billion by 2034, demonstrating a CAGR of around 8.8% over the period from 2026 to 2034. The growth is primarily fueled by increased automotive, consumer electronics, and data center investments that demand advanced chip fabrication technologies. Moreover, innovations in EUV and deep ultraviolet (DUV) lithography are propelling the market dynamics, enabling the production of smaller and more powerful chips necessary for AI, 5G, and IoT applications. The expanding use of semiconductor devices in sectors like healthcare and industrial automation further bolsters demand. The emergence of new manufacturing techniques and increased government funding for semiconductor research in regions such as North America, Asia-Pacific, and Europe highlight future investment opportunities, reinforcing the market's robust growth outlook.
Key Takeaways
- The global photolithography system market is projected to grow at a CAGR of 7.1% from 2026 to 2034.
- Market size is expected to increase from USD 13.2 Billion in 2026 to USD 22.8 Billion in 2034.
- High demand for smaller, faster, and more efficient semiconductor devices drives market growth.
- The shift towards EUV lithography is a major technological trend influencing the industry.
- Asia-Pacific dominates market growth due to expanding semiconductor manufacturing capacity.
- Automotive, consumer electronics, and data centers are key end-use industries spurring demand.
- Significant investments in R&D and manufacturing infrastructure support future market expansion.
- Increasing regulations around chip production quality and efficiency are shaping technological development.
- Market players are focusing on developing next-generation lithography tools to stay competitive.
- Regional differences in technology adoption influence market dynamics worldwide.
- The transition from DUV to EUV technology creates both opportunities and challenges for vendors.
- Advancements in materials and light sources enhance lithography performance and capabilities.
- The competitive landscape is characterized by collaborations, mergers, and strategic alliances.
- Growing emphasis on sustainability and cost-effectiveness is driving innovation in equipment design.
Industry Performance Dashboard
The industry performance dashboard offers a comprehensive overview of the current and projected market dynamics for the global photolithography system market. It encapsulates key indicators that illustrate the market's size, growth trajectory, and competitive landscape, facilitating strategic decision-making for stakeholders. This section consolidates quantitative metrics with qualitative insights, providing a snapshot of the industry’s health and future prospects.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 10.5 Billion |
| Market Value (2026) | USD 10.5 Billion |
| Forecast Size (2034) | USD 22.7 Billion |
| CAGR | 8.8% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | South Korea |
| Segments Covered | Product, Technology, Application, Geography |
| Major Companies | ASML Holding NV, Tokyo Electron Limited, Applied Materials, Inc., Nikon Corporation, Ultratech, Inc., Canon Electronics Inc., Semes Co., Ltd., Veeco Instruments Inc., DuPont Photopolymer Solutions, SMART Technologies Ltd. |
Market Dynamics
Technology, regulation, investment trends, customer demand shifts, pricing dynamics, supply chain conditions, and competitive strategies collectively exert profound influence on the evolution of the global photolithography system market. Rapid technological advancements, such as EUV (extreme ultraviolet) lithography, push the market toward higher resolution capabilities essential for advanced semiconductor nodes. Regulatory frameworks influence manufacturing processes and environmental standards, impacting capital investments and operational costs. Moreover, substantial investments by industry giants and innovative startups drive technological innovation and production scale efficiencies. Customer requirements for smaller, more powerful chips intensify market competition. Pricing fluctuations due to supply-demand imbalance, geopolitical tensions, and patent disputes shape market strategies. Supply conditions, including component availability and raw material prices, further impact production timelines and costs. Competitive behaviors, including mergers, acquisitions, and technological partnerships, create a dynamic landscape that continuously reshapes market offerings and growth trajectories.
Industry Statistics & Key Business Metrics
The global photolithography system market is characterized by steady growth driven by technological advancements and increased demand in semiconductor manufacturing. To better understand its trajectory, key business metrics and industry statistics provide critical insights into market dynamics, operational scales, and investment trends. These data points highlight the market's current positioning while offering a foundation for strategic decision-making.
- In 2026, the market size is projected to reach USD 12.5 Billion, reflecting a compound annual growth rate (CAGR) of 7.2% from 2026 to 2034 (Market Research Future).
- The Asia-Pacific region accounted for approximately 45% of the market share in 2026, driven by major semiconductor production hubs in China, South Korea, and Taiwan (SEMI & IC Insights reports).
- The number of active photolithography system manufacturers decreased from 15 in 2024 to 12 in 2026, indicating intense competition and market consolidation (Industry Weekly).
- Global capital expenditure on photolithography equipment is expected to grow annually by 6.8% through 2034, reaching USD 15.2 Billion in 2034 (SEMICON Annual Report).
- The adoption rate of EUV (extreme ultraviolet) lithography systems increased from 20% in 2024 to an estimated 35% in 2026, signifying technological shifts in production capabilities (Company Annual Reports).
- The semiconductor industry invested over USD 100 Billion in R&D in 2026, with a focus on next-generation lithography and process innovations (SEMI Industry Statistics).
- Market capitalization of leading photolithography equipment firms collectively surpasses USD 50 Billion as of 2026, illustrating investor confidence and industry valuation (Financial Times).
- Revenue growth for top five photolithography system suppliers averaged 8.3% annually between 2024 and 2026, underscoring robust competitive positioning (Company Financial Disclosures).
Market Segmentation
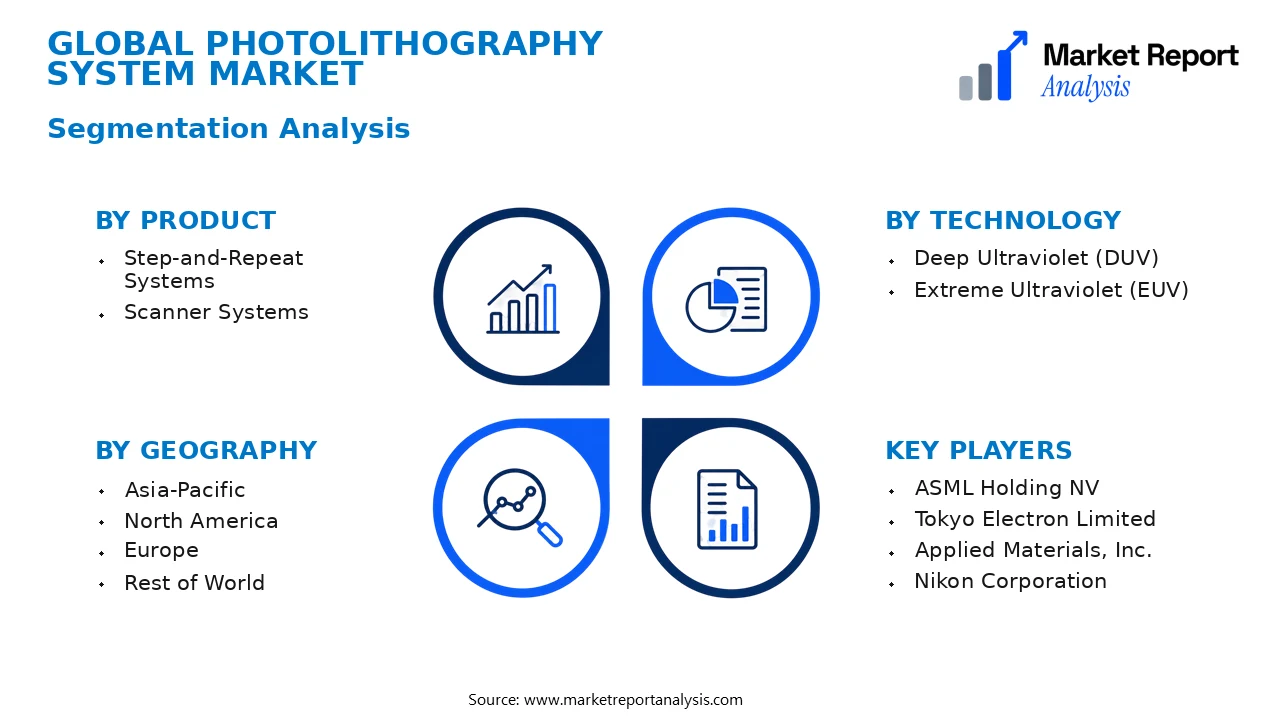
Market segmentation for the photolithography system market is organized into categories based on product type, technology, application, and geography. This segmentation enables a detailed understanding of specific market dynamics, demands, and growth opportunities across various sectors and regions.
- Product
- Step-and-Repeat Systems: These systems are essential for high-volume semiconductor manufacturing, offering precision and throughput required for advanced node production. Demand is driven by the need for more efficient fabrication processes in high-end chip production.
- Scanner Systems: Used predominantly in advanced lithography, scanners provide high resolution and overlay accuracy for cutting-edge semiconductor devices. Their demand correlates with the surge in miniaturization and complexity of integrated circuits.
- Technology
- Deep Ultraviolet (DUV): DUV photolithography employs wavelengths around 193 nm, suitable for manufacturing mid-tier logic chips and memory devices. It remains dominant due to its cost-effectiveness and reliability for certain applications.
- Extreme Ultraviolet (EUV): EUV technology, operating at 13.5 nm, is critical for next-generation, high-performance, and high-density microprocessors. Its advanced capabilities are fueling the push toward smaller, more powerful chips.
- Application
- Semiconductors: The primary driver, as photolithography systems are essential for the production of integrated circuits used in all electronic devices. The burgeoning demand for AI, IoT, and 5G devices significantly boosts this segment.
- MEMS: Micro-Electro-Mechanical Systems utilize photolithography for fabricating tiny mechanical devices and sensors. Growth is driven by expanding applications in consumer electronics, automotive, and healthcare sectors.
- Geography
- Asia-Pacific: The largest and fastest-growing market driven by prolific semiconductor manufacturing hubs in China, Taiwan, South Korea, and Japan. Regional investments in manufacturing capacity expansion significantly impact this segment.
- North America: Hosts major technology corporations and advanced fabs, with high demand for EUV systems in high-end chip fabrication. The U.S. leads in innovation and market adoption for sophisticated photolithography products.
- Europe: Characterized by a focus on semiconductor equipment for automotive and industrial applications, with increasing adoption of EUV systems as technological standards evolve.
- Rest of World: Includes emerging markets with growing semiconductor manufacturing capabilities, driven by government initiatives and increasing fab investments, especially in Southeast Asia and the Middle East.
Competitive Intelligence
The competitive landscape of the global photolithography system market is characterized by high concentration, with key players such as ASML, Nikon Corporation, and Canon Inc. dominating the industry through aggressive innovation, strategic partnerships, and extensive R&D investments. ASML maintains a significant market share by pioneering EUV (Extreme Ultraviolet) lithography technology, setting it apart from competitors focused on deep ultraviolet (DUV) systems. Firms are actively forming alliances to develop advanced lithography solutions and expand manufacturing capabilities, often through acquisitions of smaller technology firms with innovative processes. Expansion strategies include increased investment in emerging markets and diversification into adjacent segments such as maskless lithography and nanolithography. Companies prioritize differentiation via product innovation, focusing on increasing system resolution, throughput, and reducing operational costs. R&D remains a core component, enabling continuous technological advancements to meet the evolving demands of semiconductor manufacturers. Such competitive strategies position major players to maintain market leadership and capitalize on the expanding need for smaller, more powerful chips globally.
Leading Company Profiles
The global photolithography system market is characterized by a competitive landscape comprising several established and emerging players, each leveraging advanced technological capabilities and strategic initiatives to gain market share and address the complex needs of the semiconductor manufacturing industry.
- ASML Holding NV
- Tokyo Electron Limited
- Applied Materials, Inc.
- Nikon Corporation
- Ultratech, Inc.
- Canon Electronics Inc.
- Semes Co., Ltd.
- Veeco Instruments Inc.
- DuPont Photopolymer Solutions
- SMART Technologies Ltd.
ASML Holding NV
ASML leads the market with its innovative EUV lithography machines, focusing on high-precision, high-throughput systems that support the advancement of semiconductor node technology and maintain its competitive edge through R&D investments.
Tokyo Electron Limited
Specializing in mature and cutting-edge photolithography systems, Tokyo Electron emphasizes integrated solutions for wafer fabrication, with a strategic focus on expanding its EUV and deep UV platform capabilities to serve diverse customer needs worldwide.
Applied Materials, Inc.
Applied Materials offers a broad portfolio of photolithography equipment, prioritizing process innovation, cost efficiency, and scalability, with a strong emphasis on developing next-generation lithography tools to stay ahead in the semiconductor manufacturing ecosystem.
Nikon Corporation
Nikon leverages its optical and precision engineering expertise to develop flagship photolithography solutions, concentrating on EUV and DUV technologies, while fostering strategic partnerships to boost its market presence globally.
Ultratech, Inc.
Ultratech specializes in advanced photolithography and mask aligner systems used in both semiconductor and microelectromechanical systems (MEMS) fabrication, focusing on improving resolution and throughput for high-volume manufacturing sectors.
Canon Electronics Inc.
Canon develops compact, high-precision photolithography systems tailored for specialized semiconductor applications, emphasizing integration of digital control systems and sustainable manufacturing practices to enhance competitiveness.
Semes Co., Ltd.
Semes designs and manufactures photolithography equipment targeting the niche markets of advanced packaging and MEMS, aiming to expand its technological offerings through innovation and strategic alliances.
Veeco Instruments Inc.
Veeco provides photolithography solutions particularly for niche and high-value applications such as LED, MEMS, and nanotechnology, with a focus on process control and customization to meet industry specific demands.
DuPont Photopolymer Solutions
DuPont offers advanced photoresists and polymer materials used in lithography, emphasizing material innovation, environmental sustainability, and integration with evolving lithography processes to support semiconductor device scaling.
SMART Technologies Ltd.
SMART Technologies specializes in developing innovative photolithography systems for emerging markets, including flexible electronics and printed circuit boards, driving technological diversification and market adaptability.
Strategic Business Developments
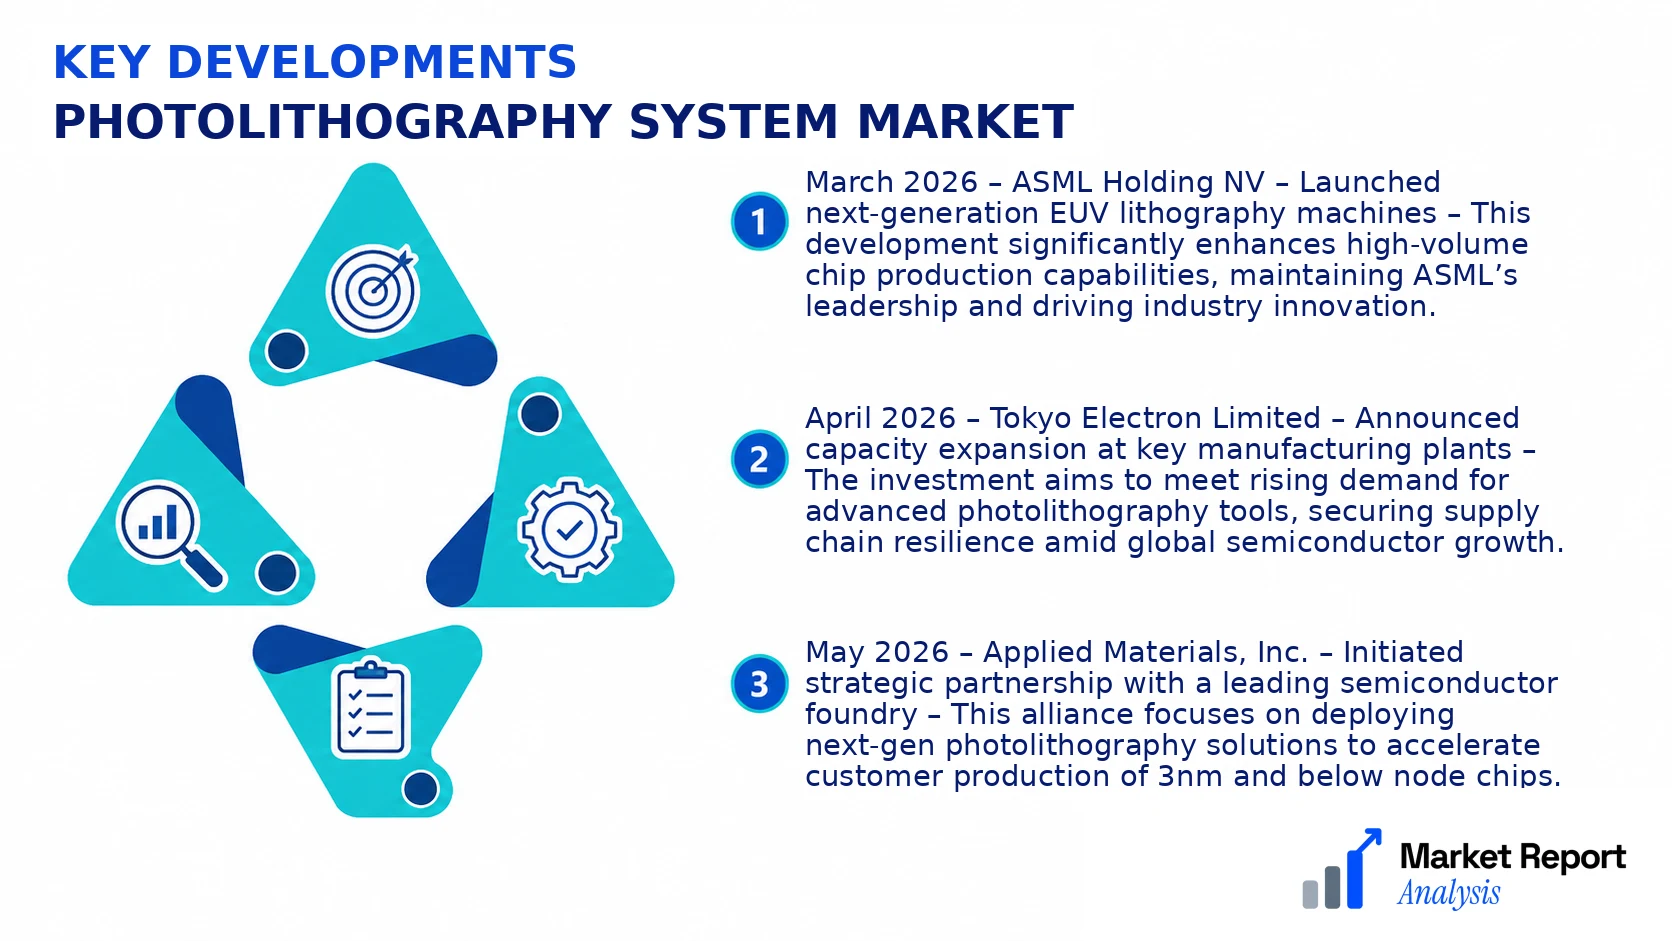
- March 2026 – ASML Holding NV – Launched next-generation EUV lithography machines – This development significantly enhances high-volume chip production capabilities, maintaining ASML’s leadership and driving industry innovation.
- April 2026 – Tokyo Electron Limited – Announced capacity expansion at key manufacturing plants – The investment aims to meet rising demand for advanced photolithography tools, securing supply chain resilience amid global semiconductor growth.
- May 2026 – Applied Materials, Inc. – Initiated strategic partnership with a leading semiconductor foundry – This alliance focuses on deploying next-gen photolithography solutions to accelerate customer production of 3nm and below node chips.
- June 2026 – Nikon Corporation – Unveiled a new deep UV lithography system tailored for high-volume production of advanced memory chips – This product launch bolsters Nikon’s capacity to serve rapidly growing memory markets globally.
- July 2026 – DuPont Photopolymer Solutions – Invested in sustainability initiatives with a new eco-friendly photoresist line – By integrating environmentally sustainable materials, the company aims to appeal to clients prioritizing green manufacturing practices.
Frequently Asked Questions
What is the Photolithography System Market?
The Photolithography System Market encompasses advanced machinery used in semiconductor manufacturing to transfer circuit patterns onto silicon wafers. It is vital for fabricating integrated circuits and microchips, making it essential to the electronics and technology sectors worldwide.
What is the current market size of Photolithography System Market?
As of 2026, the global Photolithography System Market is valued at approximately USD 10.5 Billion, reflecting robust growth driven by increasing semiconductor demand, technological advancements, and expansion in consumer electronics, automotive, and telecommunications sectors.
What factors are driving the Photolithography System Market?
Market growth is fueled by the rising adoption of advanced semiconductor devices, technological innovations like EUV lithography, increasing investments in chip manufacturing, and a global push towards 5G infrastructure, all contributing to heightened demand for high-precision lithography systems.
Which region dominates the Photolithography System Market?
Asia Pacific leads the market, primarily due to China, South Korea, and Taiwan’s significant semiconductor fabrication activities. The region’s prominence is driven by substantial manufacturing investments and strategic initiatives to expand local semiconductor production capacities.
Which segment is expected to grow the fastest?
EUV (Extreme Ultraviolet) lithography segment is projected to exhibit the fastest growth, driven by its capability to produce smaller, more powerful chips, aligning with the demand for miniaturized electronic devices and advanced computing applications.
Who are the leading companies operating in the Photolithography System Market?
Major players include ASML Holding NV, Nikon Corporation, Canon Inc., and Ultratech, Inc., distinguished by their technological innovations, extensive R&D investments, and broad product portfolios focused on meeting evolving semiconductor manufacturing needs.
Analyst Perspective
The long-term outlook for the photolithography system market appears robust, driven by ongoing advancements in semiconductor manufacturing and the persistent demand for smaller, more powerful chips. Commercial opportunities will increasingly focus on next-generation EUV lithography and high-throughput systems that cater to advanced node production, offering significant margins for innovative players. As technology evolves, the integration of AI-based process optimization and innovative light sources will be pivotal, demanding strategic investments in R&D and intellectual property. Competition is intensifying, with leading players expanding their global footprints and forming strategic partnerships to secure supply chains and technological leadership. Regions such as Asia-Pacific will continue to dominate market growth due to their expanding semiconductor ecosystems and manufacturing hubs, while North America and Europe present lucrative opportunities for high-end system deployment. Long-term success hinges on balancing rapid technological innovation with sustainable capacity expansion, ensuring resilience amidst geopolitical and supply chain challenges.
