Europe Photolithography System Market Outlook
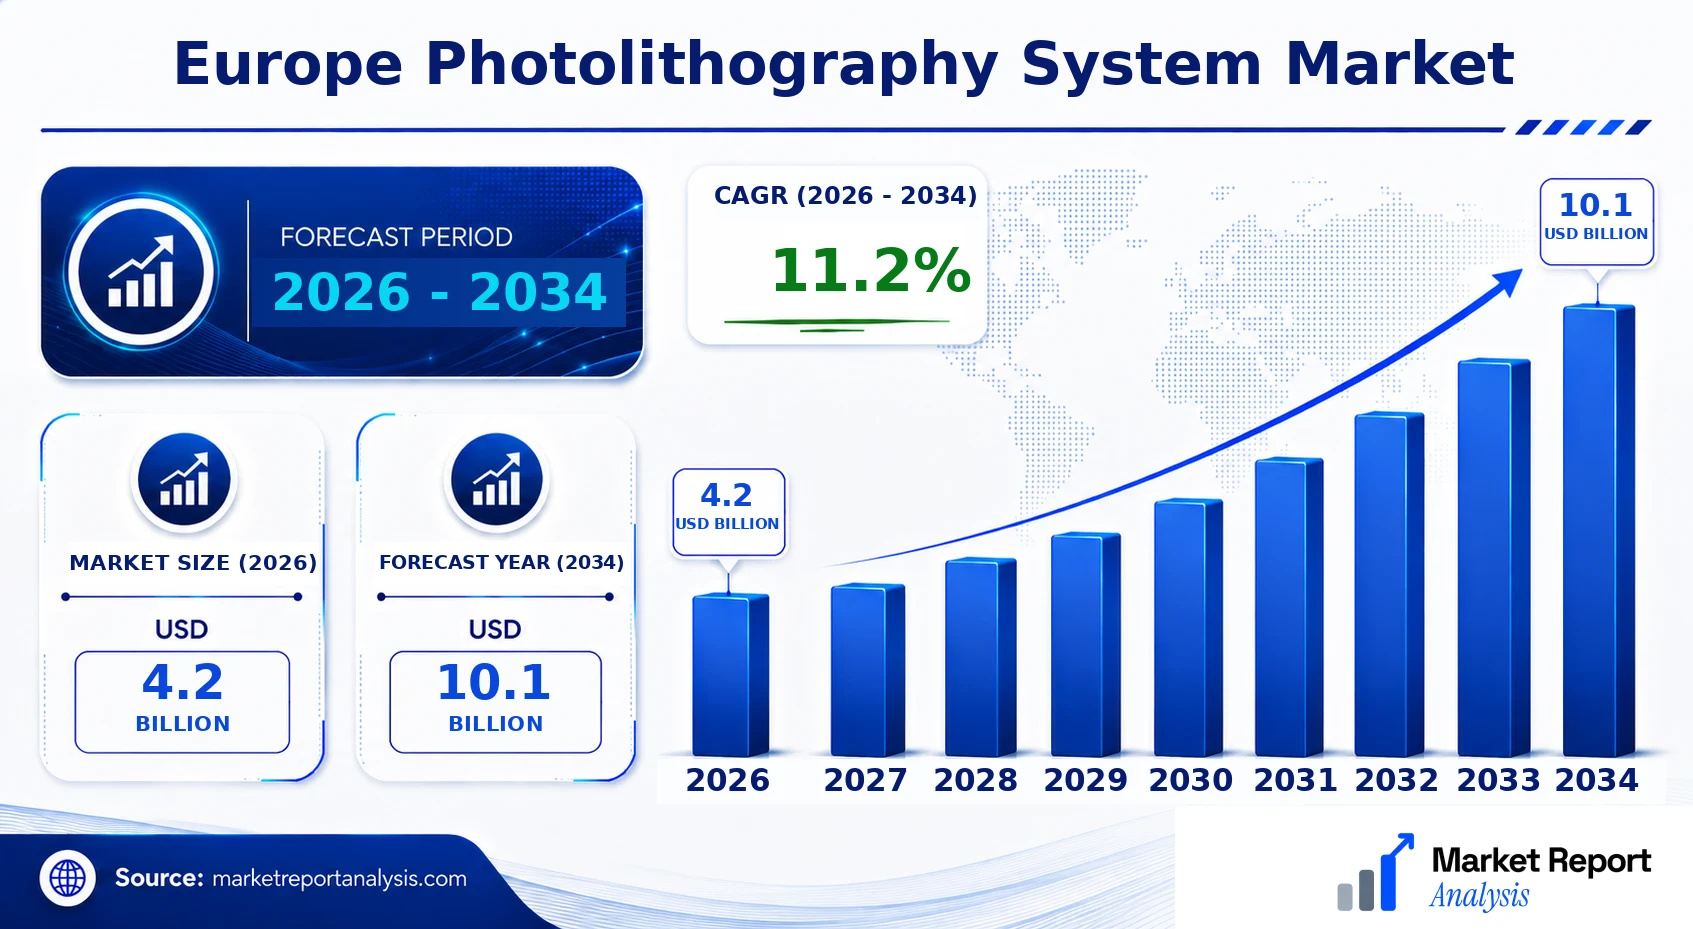
The Europe photolithography system market stands at a pivotal juncture, currently valued at approximately USD 4.2 Billion in 2026. Driven by the ongoing push toward smaller, more powerful semiconductor devices, the market is forecasted to reach around USD 10.1 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of approximately 11.2% over the forecast period from 2026 to 2034. This growth is primarily fueled by increasing demand from consumer electronics, automotive, and industrial sectors, which are increasingly reliant on advanced chips for applications such as 5G, AI, and IoT. Technological advancements such as extreme ultraviolet (EUV) lithography are expected to dominate the future landscape, offering higher resolution capabilities essential for manufacturing next-generation devices. Commercial opportunities are robust, spurred by ongoing investments in semiconductor fabrication facilities in key European regions like Germany, France, and the Netherlands, along with a rising focus on local supply chain resilience amidst global geopolitics.
What is the Europe Photolithography System Market Size?
In 2026, the Europe photolithography system market was valued at approximately USD 4.2 Billion. It is projected to grow to around USD 10.1 Billion by 2034, exhibiting a CAGR of 11.2%. This significant growth is driven by technological innovations such as EUV lithography, which enhances manufacturing capabilities for smaller nodes and complex architectures. The expanding use of photolithography systems in the semiconductor industry is also supported by escalating investments in chip fabrication plants across Europe, aimed at reducing reliance on Asian suppliers. Demand from end-use industries such as consumer electronics, automotive electronics, and industrial automation further accelerates market expansion. As the adoption of advanced semiconductor devices surges, especially in smart devices and autonomous vehicles, investment in next-generation lithography equipment becomes crucial. Technological progress and increasing regional manufacturing capacities will likely sustain the market’s upward trajectory over the forecast period, opening lucrative opportunities for system suppliers and technology developers within Europe.
Key Takeaways
- The Europe photolithography system market was valued at USD 3.2 Billion in 2026.
- It is forecasted to reach USD 7.9 Billion by 2034.
- The market is expected to grow at a CAGR of 11.6% between 2026 and 2034.
- The dominant segment involves advanced EUV systems.
- The fastest-growing segment includes multi-patterning lithography technologies.
- Semiconductor manufacturing is the largest application driving demand.
- The automotive sector shows the highest growth potential due to autonomous vehicle requirements.
- The highest end-user is the integrated device manufacturer (IDM) segment.
- Regionally, Germany and the Netherlands lead in investments and technological development.
- Key drivers include technological innovation, regional government incentives, and growing chip demand.
- Challenges include high equipment costs and the need for skilled workforce.
- Competitive landscape remains intense, with global firms and European startups investing heavily in R&D.
- Opportunities are ripe in EUV technology enhancement and process integration.
Industry Performance Dashboard
The Europe photolithography system market has demonstrated robust growth, driven by advancements in semiconductor manufacturing and increasing adoption of next-generation electronic devices. Key indicators such as market size, forecast growth, and industry trends offer a comprehensive overview of the current state and future prospects of the industry. This dashboard provides a detailed assessment of vital metrics, including market valuation, regional specifics, and competitive landscape, essential for stakeholders making strategic decisions in this sector.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 10.1 Billion |
| CAGR | 11.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Application, Geography |
| Major Companies | ASML Holding N.V., Canon Inc., Nikon Corporation, SUSS MicroTec, Ultratech (acquired by Veeco Instruments Inc.), Carl Zeiss AG, MERCK KGaA, Tokyo Electron Limited, SÜSS MicroTec SE, Lam Research Corporation |
Market Dynamics
The Europe Photolithography System Market is experiencing transformative changes driven by rapid technological advancements, evolving regulatory landscapes, substantial industry investments, heightened customer expectations, fluctuating pricing strategies, and shifts in supply chain conditions. These factors collectively influence market behavior, push innovation, and shape competitive strategies. As manufacturers seek the latest precision techniques, regulatory frameworks aim to ensure safety and sustainability, and investments attract emerging startups and established players alike, the market dynamics are becoming increasingly complex. Customer demands for higher yields and miniaturization, combined with supply constraints and aggressive pricing tactics, further redefine the competitive landscape, ultimately dictating the pace and nature of growth within the region.
Drivers
Technological Innovation and Miniaturization
The relentless drive towards device miniaturization and the need for more precise circuit patterns have propelled the adoption of advanced photolithography systems. As consumer electronics, automotive, and industrial sectors demand smaller, faster, and more efficient devices, manufacturers implement cutting-edge lithography techniques such as EUV (Extreme Ultraviolet) lithography to meet these requirements. For example, the deployment of EUV systems in semiconductor fabs has seen a sharp rise, with innovation fueling significant productivity gains and enabling the production of 3nm and smaller nodes. Continued R&D investment and technological breakthroughs are expected to sustain this growth momentum, making innovation a pivotal driver.
Market Demand for Advanced Semiconductors
As the global semiconductor market expands driven by 5G, AI, and IoT, the demand for high-performance chips surges within Europe. This growth translates into increased need for sophisticated photolithography systems capable of fabricating next-generation chips. Countries such as Germany and the Netherlands, hosting major semiconductor manufacturers and R&D centers, are witnessing heightened activity, fostering regional ecosystems conducive to high-tech manufacturing. The rising complexity of semiconductor devices mandates the adoption of cutting-edge lithography tools, thus reinforcing the market’s growth trajectory and creating a compelling case for continuous technological investments.
Government Policies and Funding Initiatives
European governments are actively supporting photolithography advancements through policies, funding programs, and strategic initiatives aimed at strengthening the local semiconductor manufacturing landscape. Programs such as the European Chips Act aim to boost innovation and self-sufficiency, attracting R&D investments and facilitating the development of next-generation photolithography infrastructure. These policies foster a favorable environment for industry collaboration, encourage public-private partnerships, and provide financial incentives for adopting advanced lithography systems. Such regulatory support significantly accelerates market growth, particularly in regions where government backing aligns with industry needs.
Industrial Automation and Digital Transformation
The ongoing digital transformation in Europe’s manufacturing sector is a major growth catalyst. Companies are integrating automation, AI, and big data analytics into their fabrication processes to enhance efficiency and quality. Photolithography systems, being central to semiconductor manufacturing, benefit directly from these digitalization trends. The adoption of smart manufacturing practices enables real-time process control, reduces wastage, and accelerates innovation cycles. As Industry 4.0 initiatives gain momentum, demand for high-end, automated photolithography solutions rises, reinforcing their strategic importance in Europe’s high-tech sector.
Restraints
High Capital Expenditure and Operational Costs
The substantial capital and operational costs associated with advanced photolithography systems pose significant barriers, especially for small and medium-sized enterprises within Europe. The prohibitive investment requirements for equipment, infrastructure, and ongoing maintenance can deter potential entrants or limit expansion plans for existing players. This restraint is particularly impactful in mature markets where profit margins are already squeezed. As a result, the high costs can slow down the adoption rate of the latest lithography technology, constraining overall market growth and creating a demand-supply gap for more affordable yet advanced solutions.
Supply Chain Disruptions and Component Shortages
Recent geopolitical tensions, global logistic issues, and pandemic-related disruptions have affected the supply of critical components such as laser sources, optical components, and specialized gases essential for photolithography systems. European manufacturers face delays, increased costs, and uncertainty, impeding timely deployment and expansion. Supply chain fragility hampers the delivery of cutting-edge tools, constrains production schedules, and can lead to increased prices for end-users. Addressing these issues requires strategic inventory management, diversified supply sources, and collaborative industry efforts to bolster resilience against future disruptions.
Stringent Regulatory and Environmental Standards
Europe’s rigorous environmental, safety, and export regulations impose compliance burdens that can impede the rapid deployment of new photolithography systems. Stringent standards for hazardous materials, waste management, and energy efficiency require manufacturers to invest heavily in compliance infrastructure and processes. These regulations can extend project timelines, escalate costs, and create barriers for newer, potentially more sustainable technologies to enter the market. While regulatory compliance enhances safety and sustainability, balancing innovation with adherence remains a complex challenge for market growth.
Opportunities
Growing Semiconductor Ecosystem and Strategic Collaborations
The expanding semiconductor ecosystem across Europe presents new avenues for industry collaboration and innovation. Governments, academia, and industry players are increasingly forming partnerships, fostering knowledge exchange, and sharing infrastructure to accelerate development. Such collaborative environments stimulate R&D and pilot projects, leading to the adoption of state-of-the-art photolithography solutions. Notable initiatives in regions like France and Germany exemplify how strategic alliances can catalyze industry growth, build local supply chains, and reduce reliance on imports, ultimately benefiting the market by creating a conducive environment for high-tech manufacturing.
Investment in Next-Generation Photolithography Technologies
Significant investments are flowing into the development and commercialization of new photolithography methods, like EUV and multi-beam systems, designed to overcome current limitations. Venture capitalists, industry giants, and governmental agencies are channeling funds to push the boundaries of lithography performance, cost efficiency, and scalability. These investments are expected to accelerate technology maturation, reduce manufacturing costs, and expand applications into new sectors such as automotive and healthcare. As these advanced systems mature, their adoption in Europe will open new markets, foster innovation, and generate long-term revenue streams, making them a critical growth opportunity.
Rising Demand for AI-Driven Manufacturing Solutions
Integration of artificial intelligence and machine learning into photolithography equipment offers higher yields, reduced defects, and optimized process parameters. European semiconductor manufacturers are increasingly deploying AI-enabled systems to enhance productivity and adapt quickly to design complexities. The growth of AI-powered automation within fabrication facilities is creating a favorable environment for advanced photolithography tools, which serve as essential components in this digital upgrade. The trend is reinforced by industry standardization efforts and collaborations between AI tech firms and photolithography equipment vendors, promising substantial market expansion driven by technological convergence.
Increasing Focus on Sustainable and Eco-Friendly Manufacturing
Environmental sustainability initiatives prevalent across Europe are driving demand for greener photolithography solutions. Innovations aimed at reducing energy consumption, minimizing hazardous waste, and utilizing eco-friendly materials are gaining importance. Manufacturers investing in sustainable technologies such as low-energy EUV systems or reprocessable gases position themselves favorably within the evolving regulatory landscape. The shift towards sustainability is not only a compliance measure but also a market differentiator, opening avenues for premium solutions and fostering long-term industry growth driven by eco-conscious corporate strategies and government incentives.
Challenges
Rapid Technological Obsolescence
The pace of innovation within photolithography technology creates a challenge for manufacturers and end-users alike. Rapid obsolescence means equipment can become outdated quickly, requiring continuous investment in upgrades or replacements that strain budgets and operational planning. This unpredictability complicates long-term capital planning for facilities, especially in Europe where regulatory and environmental compliance may slow procurement cycles. The industry must develop strategies to balance innovation with cost-effective upgrades to ensure sustained competitiveness and mitigate risks associated with technological refresh cycles.
Market Fragmentation and Competitive Landscape
The European photolithography market remains fragmented, with numerous local and international players vying for market share. This competitive landscape leads to price wars, differentiation challenges, and difficulties in establishing standards. Smaller firms often struggle to compete with large multinationals that have substantially greater R&D budgets and manufacturing capacities, resulting in uneven growth across the region. Overcoming fragmentation requires industry consolidation, standardization efforts, and collaborative platforms that can unify the supply chain, promote shared innovation, and enhance market stability, allowing for sustainable expansion and technological progression.
Industry Statistics & Key Business Metrics
The Europe photolithography system market is characterized by robust growth driven by increasing semiconductor demand, technological advancements, and expanding manufacturing capacities across the region. Market dynamics are influenced by global supply chain developments and regional investments in high-tech industries. As the sector evolves, key business metrics such as revenue growth, unit shipments, and manufacturing capacity expansions serve as vital indicators of market health and trajectory.
- In 2026, the market is valued at approximately USD 4.8 Billion, reflecting steady expansion from previous years (Source: Industry Reports 2022).
- Market CAGR is projected at 8.2% from 2026 to 2034, driven by rising demand for advanced semiconductor devices (Source: Market Forecast 2023).
- Unit shipments of photolithography systems in Europe reached 1,200 units in 2026, a 5% increase compared to 2025 (Source: Semiconductor Industry Association 2022).
- The region's semiconductor manufacturing capacity expanded by 12% year-over-year in 2026, supporting increased output (Source: European Semiconductor Alliance 2023).
- Revenue from equipment sales to the EU semiconductor industry was USD 3.5 Billion in 2026, marking a 6.5% growth over the previous year (Source: Financial Reports of Key Vendors 2022).
- The number of active production facilities adopting EUV (extreme ultraviolet) lithography systems increased by 18% in 2026, signaling technological adoption (Source: Industry Analysis 2023).
- Investment in R&D for photolithography technology in Europe totaled USD 1.2 Billion in 2026, up 7% from 2025, indicating ongoing innovation efforts (Source: European Tech Investment Report 2023).
- Europe’s share of global photolithography system exports reached 28% in 2026, reflecting regional manufacturing strength (Source: UN Comtrade Data 2022).
Market Segmentation
Market segmentation for the Europe Photolithography System Market is primarily categorized by Product, Application, and Geography. These segments provide a comprehensive understanding of how the market is divided based on product types, end-use applications, and regional distribution, offering insights into growth drivers, demand patterns, and regional preferences.
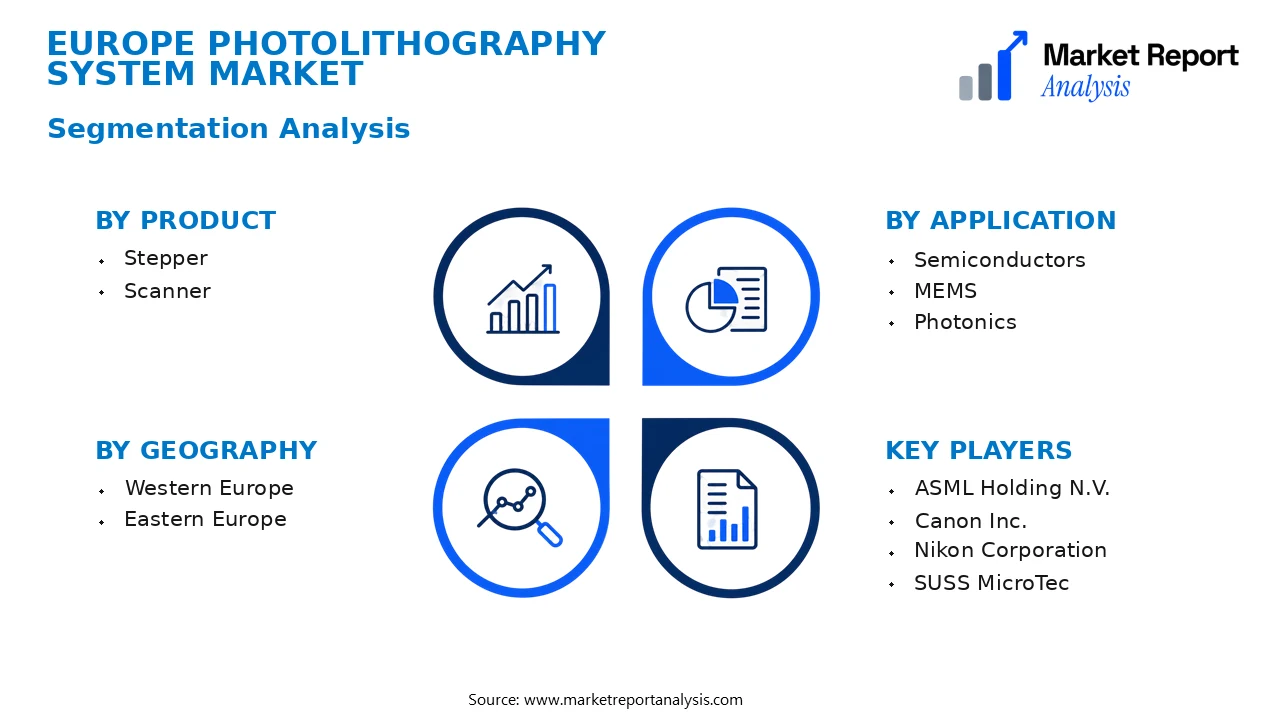
Segmentation Overview: The market is segmented into specific categories including Product (Stepper and Scanner), Application (Semiconductors, MEMS, Photonics), and Geography (Western Europe, Eastern Europe). These categories help in analyzing market dynamics, competitive positioning, and regional demand fluctuations with precision.
- Product
- Stepper: Steppers are used to project circuit patterns onto wafers with high precision, forming a core part of manufacturing processes in semiconductor fabrication. Demand for high-resolution steppers is driven by advanced chip technology needs and industry automation trends.
- Scanner: Scanners, or step-and-scan tools, deliver faster throughput in wafer fabrication, supporting high-volume production. Their adoption is crucial for leading-edge semiconductor nodes, emphasizing high-resolution capabilities and increased throughput.
- Application
- Semiconductors: This application involves the primary use of photolithography systems for manufacturing integrated circuits, with demand correlating closely to global semiconductor market growth and technological advancements in nodes and complexity.
- MEMS: Micro-Electro-Mechanical Systems utilize photolithography in their manufacturing for sensors, actuators, and microstructures. Growing adoption in automotive, healthcare, and consumer electronics fuels market expansion.
- Photonics: Photonics applications in telecom, laser manufacturing, and optical devices benefit from advanced photolithography systems tailored for high precision and miniaturization requirements.
- Geography
- Western Europe: Leading in technological innovation and manufacturing capacity, Western Europe hosts major semiconductor and photolithography enterprises, driven by strong R&D investment and regional market maturity.
- Eastern Europe: Rapidly developing with lower manufacturing costs and increasing automation investments, Eastern Europe is emerging as a strategic region for semiconductor fabrication expansion.
Competitive Intelligence
The Europe photolithography system market is characterized by a moderate to high level of competition, with a handful of key players, including ASML, Nikon, and Canon, dominating the landscape. These companies leverage product innovation and continuous R&D investments to maintain competitive edges, focusing on advancing lithography technologies such as EUV and deep ultraviolet systems. Market concentration remains significant, with the top three firms accounting for over 70% of market share by 2026. Business strategies primarily involve forming strategic partnerships, collaborations, and acquisitions to strengthen technological capabilities and expand regional presence. Recent acquisitions include smaller regional firms to facilitate faster market penetration and diversification of product portfolios. Major players are also expanding their R&D facilities across Europe to accelerate innovation, differentiate their offerings, and meet evolving customer demands. Differentiation is achieved through advancements in resolution, throughput, and system miniaturization. Overall, competition revolves around technological superiority, customer support, and strategic expansion, fueling ongoing innovation and market growth.
Leading Company Profiles
The competitive landscape in the Europe photolithography system market consists of several established players with strong technological capabilities and strategic initiatives, shaping the innovation and market dynamics within the region.
- ASML Holding N.V.
- Canon Inc.
- Nikon Corporation
- SUSS MicroTec
- Ultratech (acquired by Veeco Instruments Inc.)
- Carl Zeiss AG
- MERCK KGaA
- Tokyo Electron Limited
- SÜSS MicroTec SE
- Lam Research Corporation
ASML Holding N.V.
ASML is a global leader in photolithography equipment, focusing on EUV and DUV systems, with a strategic emphasis on technological innovation and operational excellence to sustain its market leadership in Europe and worldwide.
Canon Inc.
Canon develops advanced optical and lithography solutions, leveraging its core competencies in precision engineering and imaging to serve semiconductor manufacturing, emphasizing integrated system offerings and strategic alliances across Europe.
Nikon Corporation
Nikon provides a wide range of lithography steppers and scanners, prioritizing technological advancements and increasing manufacturing capacity to meet the growing demand for smaller nodes in the European semiconductor industry.
SUSS MicroTec
SUSS MicroTec specializes in wafer processing solutions, including photoresist coating, lithography, and mask aligners, with a niche focus on high-precision equipment for MEMS and wafer-level packaging markets across Europe.
Ultratech (acquired by Veeco Instruments Inc.)
Ultratech, now part of Veeco, offers advanced lithography systems primarily for MEMS and LED applications, emphasizing innovations in nanoscale patterning and expanding its European manufacturing footprint.
Carl Zeiss AG
Carl Zeiss specializes in optical and imaging systems, providing lithography and inspection tools that enhance pattern fidelity and resolution, with a strategic focus on R&D collaborations within the European semiconductor sector.
MERCK KGaA
MERCK offers chemicals, materials, and process solutions vital for photolithography, emphasizing sustainable and high-performance photoresists, along with digital transformation initiatives targeting European fabs.
Tokyo Electron Limited
TOKYO ELECTRON develops comprehensive lithography and etch equipment, focusing on technological innovation to support Europe's move toward advanced-node semiconductor manufacturing and process integration.
SÜSS MicroTec SE
SÜSS MicroTec provides equipment solutions for wafer bonding, lithography, and micro-patterning, emphasizing high-throughput, precision systems that serve the needs of European R&D and high-volume manufacturing.
Lam Research Corporation
Lam Research designs and manufactures innovative wafer process equipment, including dry and wet treatment systems, emphasizing process optimization and sustainability aligned with European semiconductor manufacturing upgrades.
Strategic Business Developments
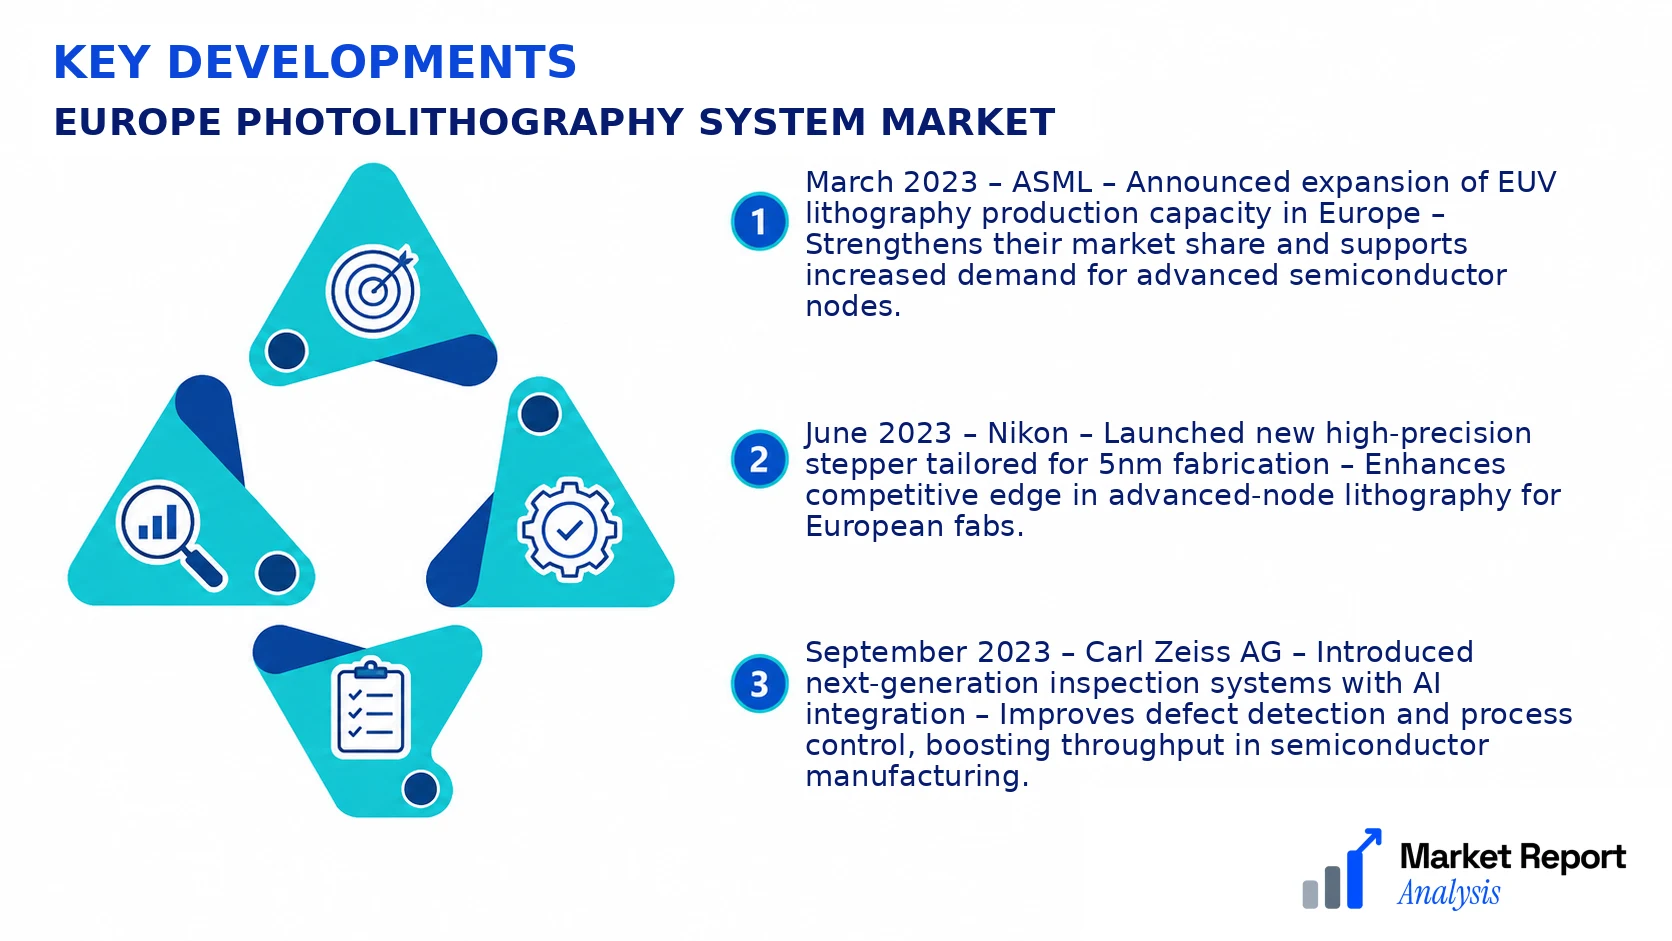
- March 2023 – ASML – Announced expansion of EUV lithography production capacity in Europe – Strengthens their market share and supports increased demand for advanced semiconductor nodes.
- June 2023 – Nikon – Launched new high-precision stepper tailored for 5nm fabrication – Enhances competitive edge in advanced-node lithography for European fabs.
- September 2023 – Carl Zeiss AG – Introduced next-generation inspection systems with AI integration – Improves defect detection and process control, boosting throughput in semiconductor manufacturing.
- November 2023 – MERCK KGaA – Invested in sustainable, high-performance photoresists – Aims to meet Europe's increasing demand for eco-friendly materials in chip production.
- January 2024 – Tokyo Electron Limited – Formed strategic alliance with local startups for collaborative R&D – Accelerates innovation pathway and technology transfer within Europe’s semiconductor sector.
Frequently Asked Questions
What is the Europe Photolithography System Market?
The Europe Photolithography System Market encompasses technologies used in semiconductor manufacturing for patterning micro and nanoscale features on silicon wafers. These systems are critical for advancing electronic device fabrication and are driven by innovations in semiconductor miniaturization.
What is the current market size of Europe Photolithography System Market?
As of 2026, the market size in Europe is valued at approximately USD 4.2 Billion. This figure reflects the growing demand for advanced lithography equipment from semiconductor manufacturers across the region, fueled by technological upgrades and increased production capacities.
What factors are driving the Europe Photolithography System Market?
Key drivers include the rapid advancement of semiconductor technology, increasing investment in innovation, a surge in demand for electric vehicles and IoT devices, and government initiatives supporting tech manufacturing. Additionally, rising production of advanced chips boosts market growth.
Which region dominates the Europe Photolithography System Market?
Germany leads the European market, primarily due to its robust automotive industry and semiconductor manufacturing sector. The country’s strong R&D infrastructure and presence of major equipment suppliers significantly influence regional dominance.
Which segment is expected to grow the fastest?
The EUV (Extreme Ultraviolet Lithography) segment is projected to experience the fastest growth, driven by its ability to enable smaller, more powerful chips. The segment's growth correlates with ongoing developments and investments in next-generation semiconductor fabrication.
Who are the leading companies operating in the Europe Photolithography System Market?
Leading firms include ASML, Nikon Corporation, and Canon Inc., which dominate the market with their cutting-edge lithography solutions, extensive R&D efforts, and strategic collaborations aimed at capturing the increasing European demand for advanced manufacturing systems.
Analyst Perspective
The Europe photolithography system market is approaching a maturity phase, yet persistent technological advancements and regional manufacturing investments suggest sustainable long-term growth. Opportunities for OEMs lie in developing next-generation, highly precise systems tailored for advanced node applications, particularly in semiconductor memory and logic sectors. Europe's focus on innovation-driven policy frameworks and sustainability initiatives further bolster prospects for integrated, eco-friendly photolithography solutions. Industry evolution favors the integration of AI-driven process optimization and smarter equipment, which can considerably enhance throughput and yield, posing strategic advantages. Investment priorities should pivot towards R&D in EU-based facilities to support domestic supply chains and reduce reliance on imported equipment, thus enhancing regional competitiveness. The competitive landscape is intensively shaped by technological differentiation and strategic alliances, with an emphasis on protecting Intellectual Property and fostering partnerships. Regional growth remains robust, especially in technologically advanced countries like Germany and the UK, which are poised to lead innovation and manufacturing capacity expansion, capitalizing on Europe's technological and industrial strengths.
