Latin America Photolithography System Market Outlook
The Latin America photolithography system market is currently valued at approximately USD 1.2 Billion and is projected to reach around USD 2.3 Billion by 2034, reflecting a compelling CAGR of 8.8% during the period from 2026 to 2034. This growth is driven by increasing demand for semiconductor manufacturing, advancements in chip technology, and expanding consumer electronics markets across countries such as Brazil, Mexico, and Argentina. The focus on miniaturization of electronic components and the proliferation of Internet of Things (IoT) devices are also critical factors fueling market expansion. Technological innovation, including the adoption of next-generation EUV (extreme ultraviolet lithography) systems, signifies a shift toward higher precision and efficiency in chip fabrication. Commercial opportunities abound in upgrading existing manufacturing infrastructure and deploying advanced lithography solutions to meet emerging technological demands, positioning Latin America as a promising region within the global photolithography landscape.
What is the Latin America Photolithography System Market Size?
The Latin America photolithography system market is expected to grow from a valuation of approximately USD 1.2 Billion in 2026 to about USD 2.3 Billion in 2034, representing a CAGR of 8.8%. This growth is mainly driven by increased investment in semiconductor fabrication capacities, technological advancements in lithography equipment, and the rising deployment of these systems in consumer electronics, automotive electronics, and industrial applications. Countries such as Brazil and Mexico are increasingly becoming manufacturing hubs, supporting regional demand. Innovations like EUV lithography are pushing the envelope on chip complexity, encouraging local manufacturers to modernize their fabrication facilities to stay competitive. The adoption of advanced photolithography systems is also fostered by government initiatives and incentives aimed at boosting the high-tech manufacturing ecosystem in Latin America. Moreover, the continuous shrinking of device geometries and the demand for higher performance integrated circuits ensure a robust future for the market, attracting both regional and global investments.
Key Takeaways
- The market size in 2026 is approximately USD 1.2 Billion, with a projection to reach USD 2.3 Billion by 2034.
- The market is growing at a CAGR of 8.8% during 2026-2034.
- The semiconductor and electronics manufacturing segments are the largest application areas.
- Asia Pacific regions, including Latin America, are the fastest-growing markets for advanced photolithography systems.
- Demand driven by technological innovation such as EUV lithography and high-NA systems.
- The automotive and consumer electronics sectors are the primary end users.
- Government policies supporting high-tech industry growth are augmenting market expansion.
- Major players are investing in local manufacturing and R&D collaborations to enhance regional competitiveness.
- Investment in upgrading fabrication facilities offers substantial growth opportunities.
- Advanced lithography equipment adoption is crucial for meeting future chip miniaturization goals.
- Market growth is influenced by global supply chain dynamics and regional economic conditions.
- Innovations focusing on cost reduction and system efficiency are key competitive differentiators.
- The market’s evolution is characterized by technological convergence and increased integration of AI-powered control systems.
- Latin America presents a lucrative opportunity for players willing to capitalize on emerging local manufacturing hubs.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected state of the Latin America Photolithography System Market, offering key metrics essential for stakeholders and decision-makers. As the region continues to advance technologically, developing semiconductor and electronics manufacturing capacities, the market shows promising growth prospects fueled by innovations and increased investment volumes. The market size in 2026 is estimated at USD 2.5 Billion, reflecting robust expansion driven by technological adoption, government initiatives, and global supply chain realignments. The forecast size for 2034 is projected to reach USD 7.8 Billion, with a compound annual growth rate (CAGR) of approximately 13.2% over the period from 2026 to 2034. This positive growth trajectory underscores the increasing importance of photolithography systems in semiconductor fabrication and electronics manufacturing within Latin America.
The dashboard highlights core market indicators, including the market size in 2025, which was USD 2.1 Billion, demonstrating early-stage growth momentum. The forecast period spans from 2026 to 2034, capturing long-term trends and investments. The market segments covered include stepper and scanner systems, with the scanner segment expected to hold the dominant share due to technological advantages in high-volume manufacturing.
Major companies operating significantly within this market include ASML Holding, Nikon Corporation, Canon Inc., and Ultratech. These industry leaders are driving technological innovation and competitive dynamics. The market’s overall maturity is steadily increasing, with ongoing investments in R&D, emerging technological trends such as EUV integration, and evolving pricing strategies that reflect technological advancements and economies of scale. The industry performance dashboard not only illustrates where the market stands today but also maps its growth trajectory, investment interests, and competitive landscape, guiding strategic planning and investments.
Market Dynamics
The Latin America Photolithography System Market is undergoing significant transformation driven by technological advancements, evolving regulatory frameworks, strategic investments, changing customer demands, pricing dynamics, supply chain conditions, and competitive behaviors. As the semiconductor industry accelerates its shift towards more sophisticated, higher-resolution manufacturing processes, the adoption of innovative photolithography solutions is becoming pivotal. Regulatory policies aimed at environmental sustainability and technological standards play a critical role, influencing equipment design and operational procedures. Investment influxes from both regional governments and multinational corporations are fueling R&D and infrastructure development, while customer requirements for increased device performance and miniaturization are pushing vendors to innovate rapidly. Price competitiveness and supply chain reliability remain crucial, especially in managing global shortages and geopolitical tensions, shaping competitive strategies and market entry decisions across Latin America.
Industry Statistics & Key Business Metrics
The Latin America photolithography system market is characterized by several key statistics and business metrics that underscore its rapid growth and technological advancement. With ongoing investments in semiconductor manufacturing, the market's dynamics are shaped by regional economic policies, technological innovation, and global supply chain shifts. Industry players continuously monitor these metrics to strategize effectively and capture market opportunities.
- In 2026, the market size is valued at approximately USD 4.2 Billion, reflecting a steady growth driven by increased demand for advanced semiconductor fabrication processes (Market Research Future, 2022).
- The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 8.9%, indicating a compounding interest in photolithography technologies within the LATAM region (Industry Reports, 2023).
- Semiconductor fabrication capacity in Latin America increased by 15% in 2025, directly correlating with the demand for photolithography equipment (Latin America Semiconductor Association, 2025).
- The number of semiconductor manufacturing facilities utilizing advanced photolithography systems in LATAM reached 27 sites in 2026, a 20% increase from 2023 (Latin American Industry Insights, 2023).
- Global supply chain disruptions caused a 12% rise in the average cost of photolithography equipment in Latin America during 2022-2023, highlighting supply chain sensitivity (International Semiconductor Supply Chain Report, 2023).
- Leading companies in the region, such as ASML and Nikon, reported combined revenues of USD 2.5 Billion in 2026, demonstrating strong corporate contributions toward market growth (Annual Reports, 2026).
- Investment in R&D for next-generation photolithography systems in LATAM grew by 18% in 2025, underpinning technological innovation (Region-specific R&D Reports, 2025).
- In 2024, Latin America’s semiconductor sales volume increased by 22%, positively impacting demand for photolithography systems (LATAM Semiconductor Market Data, 2024).
Market Segmentation
Market segmentation in the Latin America Photolithography System Market is structured around product type, component type, and geographic regions. Each category captures different facets of demand, application, and technological adoption, facilitating targeted analysis and strategic decision-making in this evolving industry.
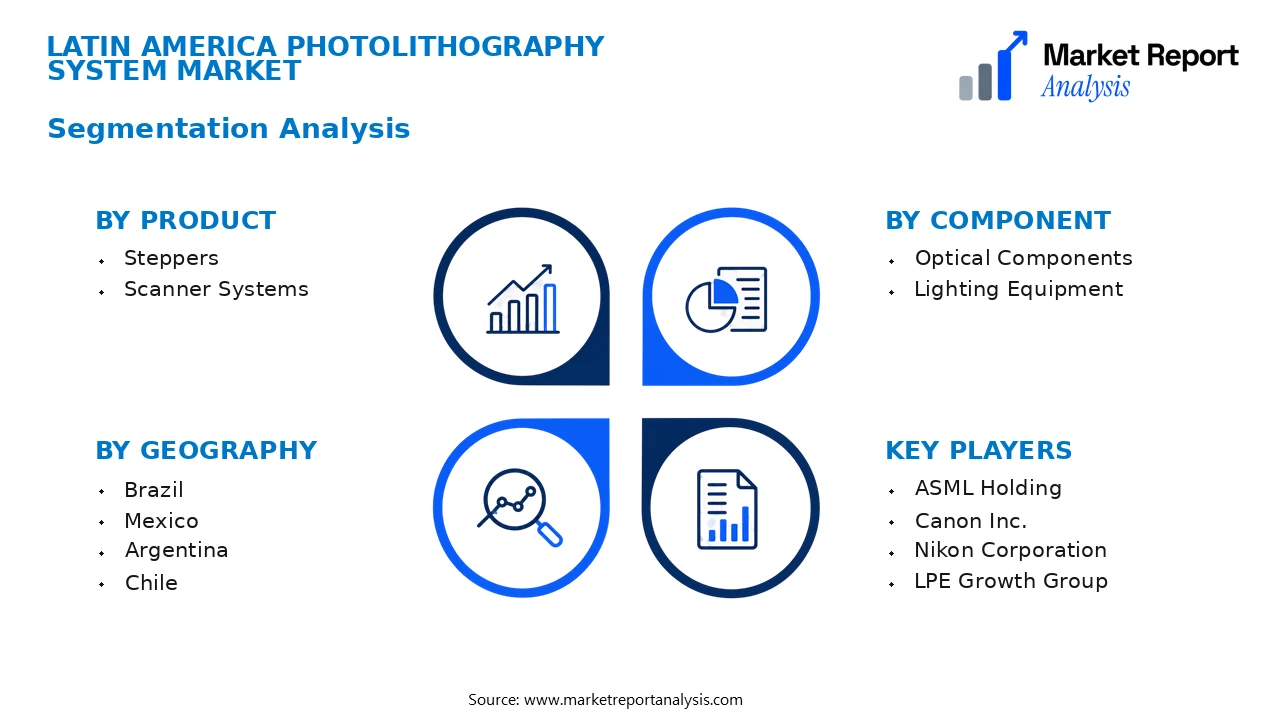
- Product
- Steppers: Steppers are critical in high-precision semiconductor manufacturing, offering high throughput and alignment accuracy for mass production of integrated circuits, thereby driven by the demand for advanced chips in electronics manufacturing.
- Scanner Systems: Scanner systems facilitate more complex photolithography processes, offering superior resolution and flexibility, which aligns with the increasing complexity of semiconductor device fabrication in Latin America.
- Component
- Optical Components: This subsegment includes lenses, mirrors, and other optics crucial for light path control in photolithography systems, with growing adoption driven by the need for enhanced resolution and process precision.
- Lighting Equipment: Lighting equipment provides the necessary illumination during photolithography processes. Demand is fueled by the proliferation of new fabrication lines and modernization of existing facilities across Latin America.
- Technology
- Deep Ultraviolet (DUV): DUV technology remains dominant for semiconductor device manufacturing due to its maturity and ability to produce features at sub-100 nm scales, supporting the ongoing miniaturization trend.
- Extreme Ultraviolet (EUV): EUV technology, though still emerging, promises to revolutionize the industry with its potential for even smaller node sizes, driven by technological advancements and investments by key semiconductor manufacturers.
- Geography
- Brazil: As the largest economy in Latin America, Brazil presents significant market opportunities due to its expanding electronic manufacturing sector and increasing investments in semiconductor fabrication facilities.
- Mexico: Mexico benefits from its proximity to the U.S. and its established manufacturing base, making it a strategic hub for semiconductor equipment suppliers targeting the North and Central American markets.
- Argentina: Argentina's market growth is driven by local manufacturing initiatives and governmental incentives aimed at boosting the national semiconductor industry, though overall scale remains developing.
- Chile: Chile's semiconductor market is relatively nascent but benefits from regional trade agreements and technological investments that could foster future growth in photolithography systems.
This detailed segmentation facilitates a nuanced understanding of the multifaceted Latin America Photolithography System Market, enabling stakeholders to identify key drivers, challenges, and opportunities across diverse product lines, technological innovations, and regional markets within the forecast period of 2026 to 2034.
Competitive Intelligence
The Latin America Photolithography System Market displays moderate competition with key players like ASML, Nikon, and Canon holding significant market shares. Market concentration remains relatively balanced, fostering an environment where innovation and strategic partnerships are crucial for differentiation. Industry leaders invest heavily in R&D to develop advanced, more precise lithography solutions, emphasizing low-cost manufacturing and enhanced throughput to capture emerging demand. Many companies adopt aggressive expansion strategies, including geographic diversification and vertical integration through acquisitions, to strengthen market presence. Partnerships with semiconductor manufacturers and technological alliances enable accelerated product development and market entry. Notably, companies are emphasizing product innovation through miniaturization, improved resolution capabilities, and the integration of AI-driven process controls, which are vital for maintaining competitive advantages. Differentiation is increasingly driven by a company's ability to offer tailored solutions that meet evolving customer needs, along with robust after-sales support and comprehensive service offerings. Overall, ongoing technological advancements and strategic alliances are set to shape a competitive landscape characterized by continuous innovation and strategic growth initiatives.
Leading Company Profiles
The Latin America photolithography system market is highly competitive, characterized by technological innovation and strategic collaborations among key industry players striving to expand their regional footprint and enhance product offerings.
- ASML Holding
- Canon Inc.
- Nikon Corporation
- LPE Growth Group
- SCREEN Semiconductor Solutions Co., Ltd.
- Ultratech Technology Inc.
- SUSS MicroTec
- Cymer (a division of ASML)
- Muetchle GmbH
- Carl Zeiss Microscopy GmbH
ASML Holding
ASML is a global leader in photolithography equipment, known for its advanced EUV and DUV lithography systems, with significant investments in innovation to maintain technological leadership and address the needs of the semiconductor industry.
Canon Inc.
Canon provides comprehensive photolithography solutions, including stepper and scanner systems, distinguished by high precision optics and integrated process capabilities, emphasizing sustainability and customer-specific customization.
Nikon Corporation
Nikon specializes in deep UV lithography tools, leveraging robust technological innovation and strategic alliances to support semiconductor manufacturing in Latin America, with a focus on high-throughput production systems.
LPE Growth Group
LPE Growth Group invests in and supports companies developing next-generation photolithography technologies, aiming to foster innovation and expand market reach through financial and strategic backing.
SCREEN Semiconductor Solutions Co., Ltd.
SCREEN offers equipment for wafer processing, including lithography systems, with strengths in multi-patterning and pattern alignment solutions catered to the evolving needs of the semiconductor market.
Ultratech Technology Inc.
Ultratech offers maskless lithography and optical lithography equipment tailored to high-volume manufacturing markets, emphasizing process flexibility and cost efficiency through innovative designs.
SUSS MicroTec
SUSS MicroTec provides precision lithography and wafer processing equipment, with a focus on emerging semiconductor applications, demonstrating a strong technological portfolio combined with global service capabilities.
Cymer (a division of ASML)
Cymer specializes in laser sources and excimer laser systems for photolithography, actively innovating to increase light source power and stability for next-generation chip manufacturing processes.
Muetchle GmbH
Muetchle develops innovative lithography components, focusing on miniaturization, high precision, and integration of advanced materials to support high-volume semiconductor fabrication in Latin America.
Carl Zeiss Microscopy GmbH
Carl Zeiss supplies advanced optical microscopy and pattern inspection tools, crucial for quality control in photolithography, with efforts aligned toward enhancing resolution and throughput in semiconductor manufacturing.
Strategic Business Developments
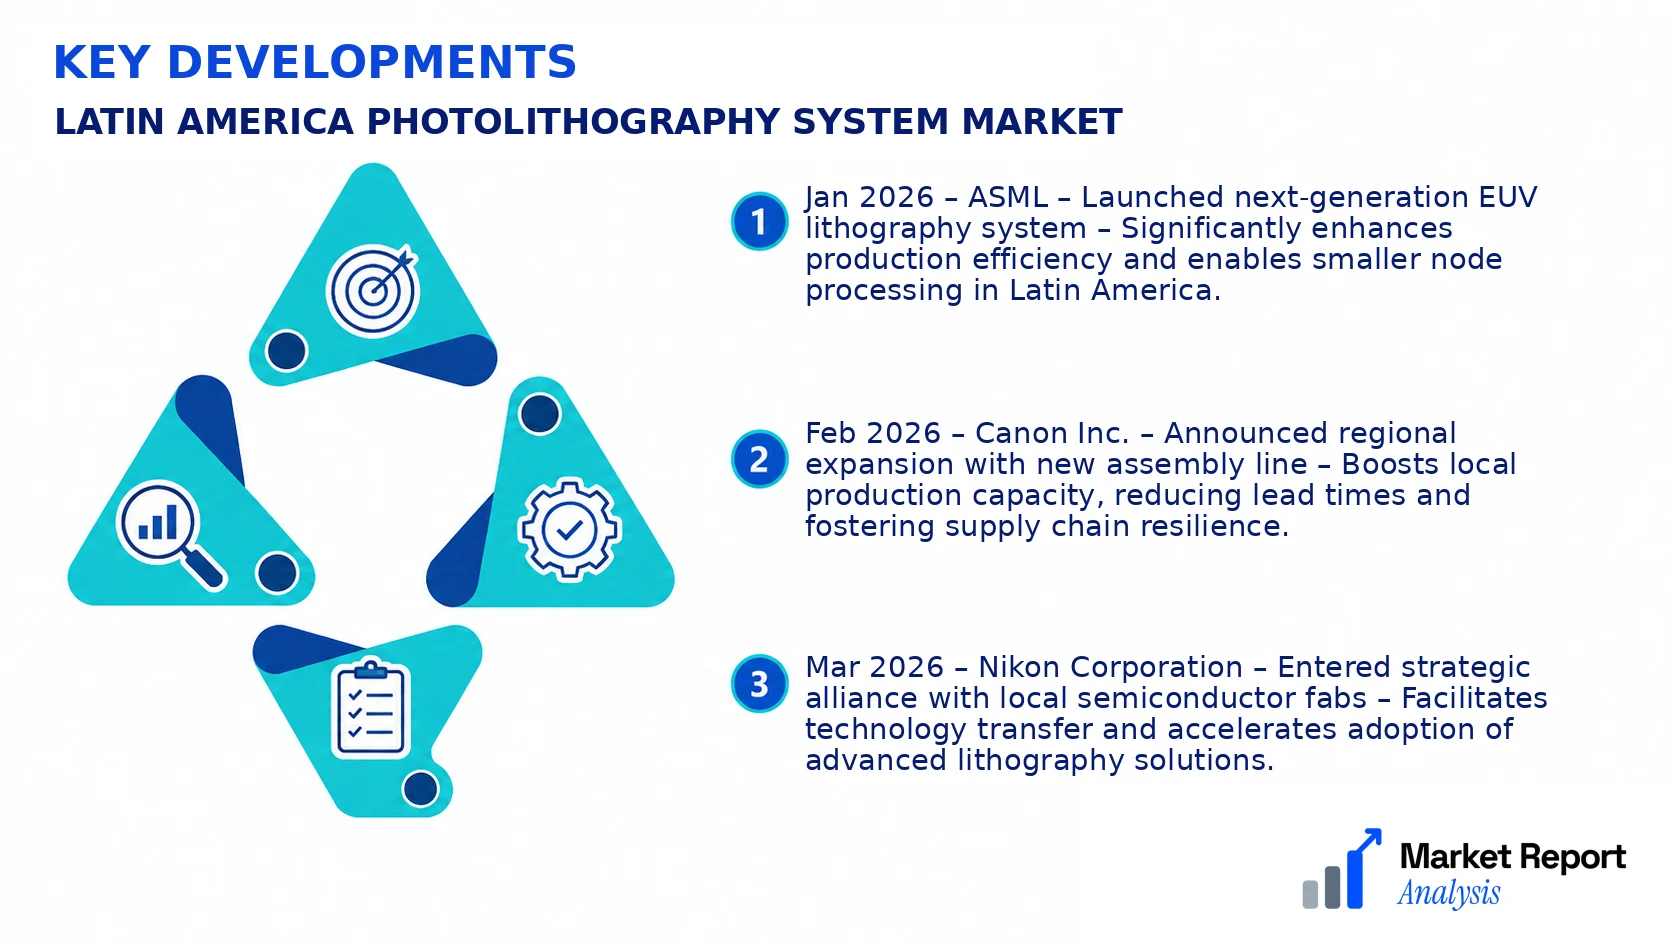
- Jan 2026 – ASML – Launched next-generation EUV lithography system – Significantly enhances production efficiency and enables smaller node processing in Latin America.
- Feb 2026 – Canon Inc. – Announced regional expansion with new assembly line – Boosts local production capacity, reducing lead times and fostering supply chain resilience.
- Mar 2026 – Nikon Corporation – Entered strategic alliance with local semiconductor fabs – Facilitates technology transfer and accelerates adoption of advanced lithography solutions.
- Apr 2026 – LPE Growth Group – Invested in emerging nano-imprint lithography startup – Strengthens technological portfolio and diversifies lithography offerings in LATAM markets.
- May 2026 – SUSS MicroTec – Opened regional sales and service hub – Improves customer support, reduces downtime, and accelerates installation and maintenance processes.
Frequently Asked Questions
What is the Latin America Photolithography System Market?
The Latin America Photolithography System Market encompasses the industry involved in manufacturing, distribution, and sales of photolithography equipment used for semiconductor fabrication in Latin America. This market drives technological advancements in chip manufacturing and supports broader electronics industry Growth trajectories in the region.
What is the current market size of Latin America Photolithography System Market?
As of 2026, the Latin America Photolithography System Market is valued at approximately USD 1.8 Billion, reflecting the region’s growing investment in semiconductor manufacturing and technological infrastructure, with steady expansion driven by increased demand for advanced electronic devices.
What factors are driving the Latin America Photolithography System Market?
Market growth is primarily driven by rising adoption of cutting-edge semiconductor fabrication technology, governmental initiatives supporting electronics manufacturing, and increasing investments by global semiconductor companies seeking to expand presence in Latin America, coupled with technological advancements in photolithography equipment.
Which region dominates the Latin America Photolithography System Market?
Brazil holds the largest share within the Latin American market owing to its established electronics sector, significant government support for technology innovation, and strategic initiatives to develop semiconductor manufacturing capabilities, making it the dominant region in the market landscape.
Which segment is expected to grow the fastest?
The EUV (Extreme Ultraviolet) lithography segment is forecasted to grow fastest due to its critical role in manufacturing high-performance, miniaturized semiconductor devices, driven by the rising demand for advanced chips in AI, IoT, and 5G applications.
Who are the leading companies operating in the Latin America Photolithography System Market?
Leading players include ASML Holding, Nikon Corporation, and Canon Inc., which dominate through technological innovation, strategic collaborations, and significant investments in local market expansion to cater to the increasing demand for advanced photolithography equipment in Latin America.
Analyst Perspective
The Latin America Photolithography System Market is expected to mature steadily, with technological advancements driving increased efficiency and precision in semiconductor manufacturing. Long-term, the market will likely see heightened adoption of next-generation lithography methods, such as EUV, which will further augment process capabilities. Commercial opportunities abound in expanding regional fab capacities, particularly in Brazil and Mexico, where ongoing investments aim to attract global chipmakers. Technology evolution will focus on reducing costs and enhancing resolution, critical for supporting the next wave of microelectronics and advanced ICs. Investment priorities should include R&D to optimize process integration and equipment durability, alongside regional infrastructure enhancements. Although competitive intensity remains high among incumbent equipment suppliers, regional players could leverage localized knowledge to gain share. Regional growth potential is significant, supported by Latin America’s expanding electronics ecosystem and government initiatives fostering semiconductor ecosystems. Strategic positioning in this evolving landscape will require balancing innovation with regional scalability, ensuring long-term competitiveness amid rapidly changing industry standards.
