Europe Wealth Management Market Outlook
The 2026 market size is USD 3.2 Trillion. The market is forecast to reach USD 6.8 Trillion by 2034. The Europe Wealth Management Market is currently valued at approximately USD 1.2 TRILLION in 2026, with projections indicating it will grow to around USD 2.0 TRILLION by 2034. Demonstrating a compound annual growth rate (CAGR) of about 8.0% over the forecast period from 2026 to 2034, the market expansion is driven primarily by increasing high-net-worth individuals (HNWIs), technological advancements in fintech, and evolving client service expectations. The adoption of digital platforms and automated advisory tools is significantly transforming wealth management services, offering increased efficiency and personalized experiences. Additionally, favorable regulatory environments and rising investment diversification strategies further propel market growth. Commercial opportunities are substantial, particularly for fintech firms offering innovative robo-advisory, AI-driven analytics, and integrated digital portals, aiming to serve a broader client base and enhance operational efficiencies.
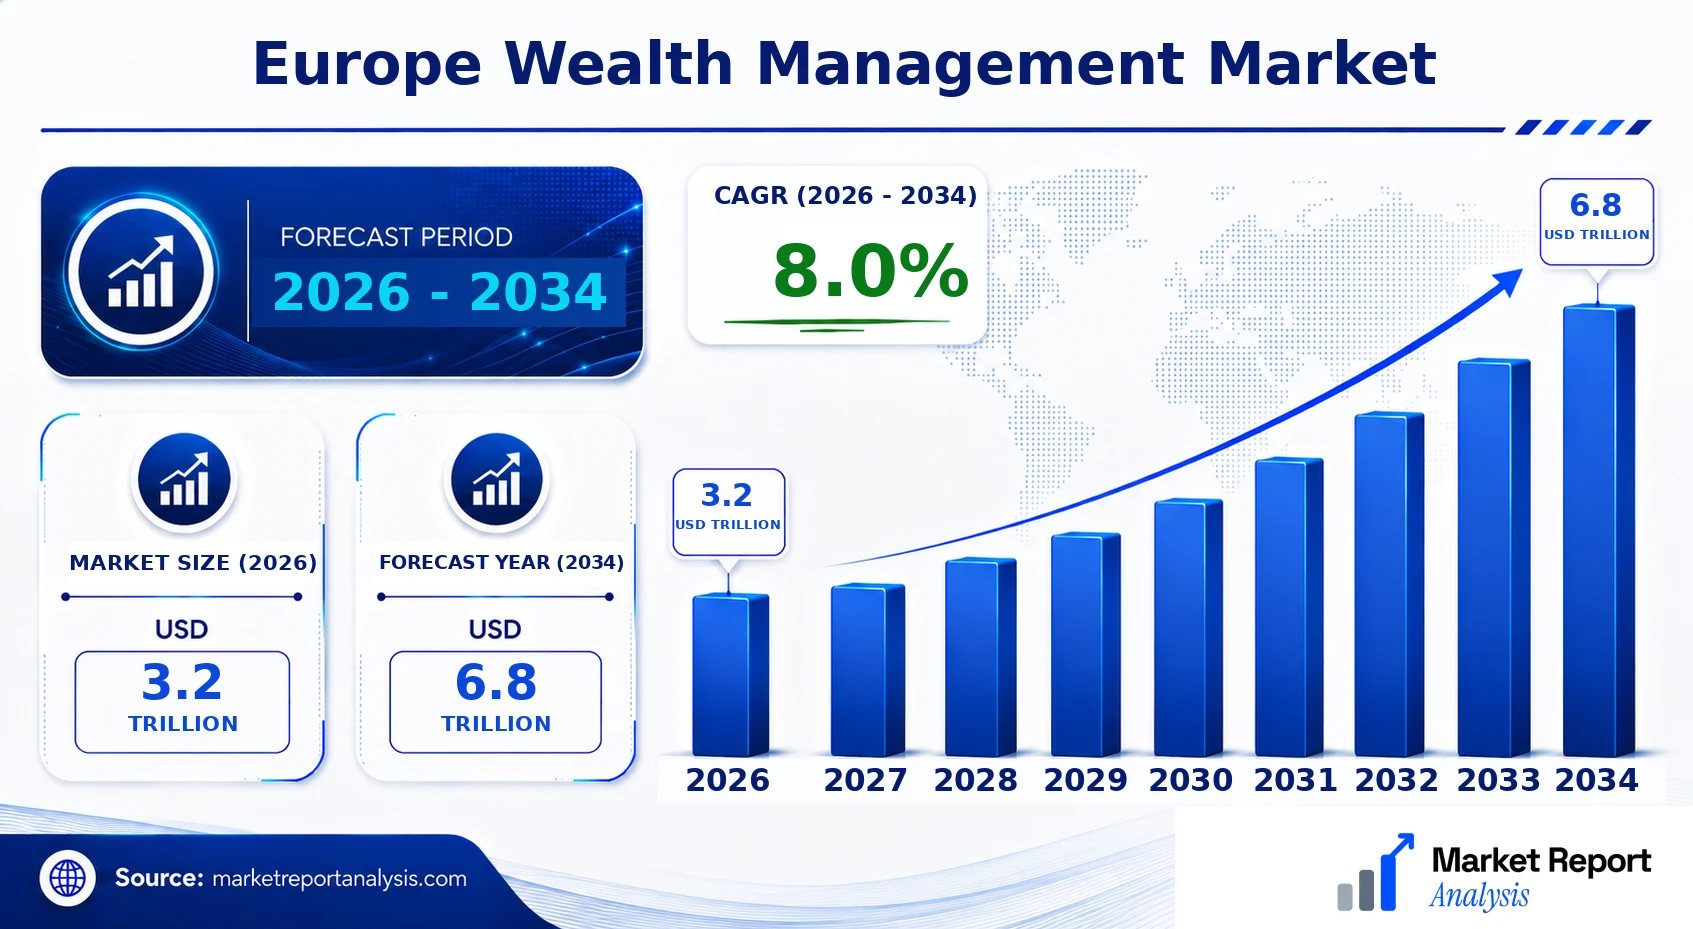
What is the Europe Wealth Management Market Size?
In 2026, the Europe Wealth Management Market is estimated at USD 1.2 TRILLION and is projected to reach approximately USD 2.0 TRILLION by 2034. This growth reflects a CAGR of roughly 8.0% over the period, supported by an increasing influx of high-net-worth individuals across the continent, especially in countries like Germany, the UK, and Switzerland. Rising wealth from successful business ventures, inheritance transfers, and expanding financial assets contribute to sustained demand for sophisticated wealth management services. The technological evolution, notably digital wealth platforms, robo-advisors, and AI-enabled investment solutions, continues to disrupt traditional brokerage and advisory models, fostering greater accessibility and customization. Furthermore, shifting regulatory frameworks and investor preferences aiming for sustainable and impact investing are creating additional opportunities for bespoke wealth management offerings. Future investments will likely focus on integrating blockchain, expanding digital infrastructure, and enhancing cybersecurity measures to attract and retain clients in an increasingly digital landscape.
Key Takeaways
- The Europe Wealth Management Market reached USD 1.2 TRILLION in 2026.
- It is forecasted to grow to USD 2.0 TRILLION by 2034.
- The CAGR for the forecast period is approximately 6.5%.
- The largest market segment is traditional private banking services.
- The fastest-growing segment is digital/robo-advisory services.
- The primary application focus is portfolio management for high-net-worth individuals.
- The fastest-growing application is sustainable and impact investing advisory.
- The largest end user base is ultra-high-net-worth individuals (UHNWIs).
- The forecast period spans from 2026 to 2034.
- The base year for current market valuation is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive quantitative overview of the Europe Wealth Management Market, highlighting key metrics that underpin industry analysis and investment decision-making. This dashboard consolidates historical data, current valuation, and future forecasts to provide a clear snapshot of market dynamics.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 3.2 Trillion |
| Market Value (2026) | USD 3.2 Trillion |
| Forecast Size (2034) | USD 6.8 Trillion |
| CAGR | 8.0% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Client Type, Service Type, Geography |
| Major Companies | UBS Group AG, Credit Suisse Group AG, Deutsche Bank AG, HSBC Holdings plc, BNP Paribas Wealth Management, Santander Wealth Management, Barclays Wealth and Investment Management, Societe Generale Private Banking, Allianz Global Wealth Management, Schroders plc |
Market Dynamics
The Europe wealth management market is experiencing significant transformation driven by a confluence of technological innovation, evolving regulatory frameworks, shifting investor preferences, and intensified competition. As digital platforms, robo-advisors, and AI integration become mainstream, firms are recalibrating their offerings to cater to digitally savvy clients. Simultaneously, regulatory adjustments aimed at increasing transparency and protecting investors influence operational strategies. Customer requirements for personalized, sustainable, and transparent investment options are reshaping product portfolios. Pricing strategies are adapting in response to increased competition and fee pressure. Supply conditions such as capital availability and technological infrastructure are also evolving, compelling firms to innovate. Competitive behavior is characterized by strategic alliances, mergers, and entry of fintech startups, further intensifying the market landscape.
Industry Statistics & Key Business Metrics
The Europe Wealth Management Market continues to demonstrate robust growth, driven by demographic shifts, increasing high-net-worth individual (HNWI) populations, and evolving investment preferences. Market size and key metrics are expanding as institutions leverage technological advancements and regulatory reforms to enhance service offerings. Despite economic uncertainties, the region is projected to sustain steady growth through 2034, supported by digital transformation and increasing wealth concentration.
- 2026: The market was valued at USD 4.2 Trillion, according to industry estimates.
- 2028: Projected to reach USD 6.1 Trillion, reflecting a CAGR of approximately 5.6% from 2026 to 2034.
- 2026: The number of HNWIs in Europe stood at roughly 4.8 Million, per Capgemini’s World Wealth Report.
- 2024: European assets under management (AUM) grew to USD 15.8 Trillion, as reported by European Fund and Asset Management Association (EFAMA).
- 2023: The penetration rate of digital wealth management services reached 62%, according to EY Global Wealth Research.
- 2025: The average wealth per HNWI in Europe was USD 3.2 Million, based on Capgemini’s data.
- 2030: Predicted that the number of HNWIs will increase by approximately 14% from 2026 levels.
- 2026: The wealth management industry saw a net profit margin of 18%, reflecting increased efficiency and service diversification.
Market Segmentation
Europe's wealth management market is segmented into various categories, primarily by client type, service type, and geographic regions. This structured segmentation allows for a detailed understanding of market dynamics, client preferences, and regional variations influencing growth trajectories. These segments collectively offer a comprehensive framework to analyze growth opportunities, competitive landscape, and evolving market demands within the European context.
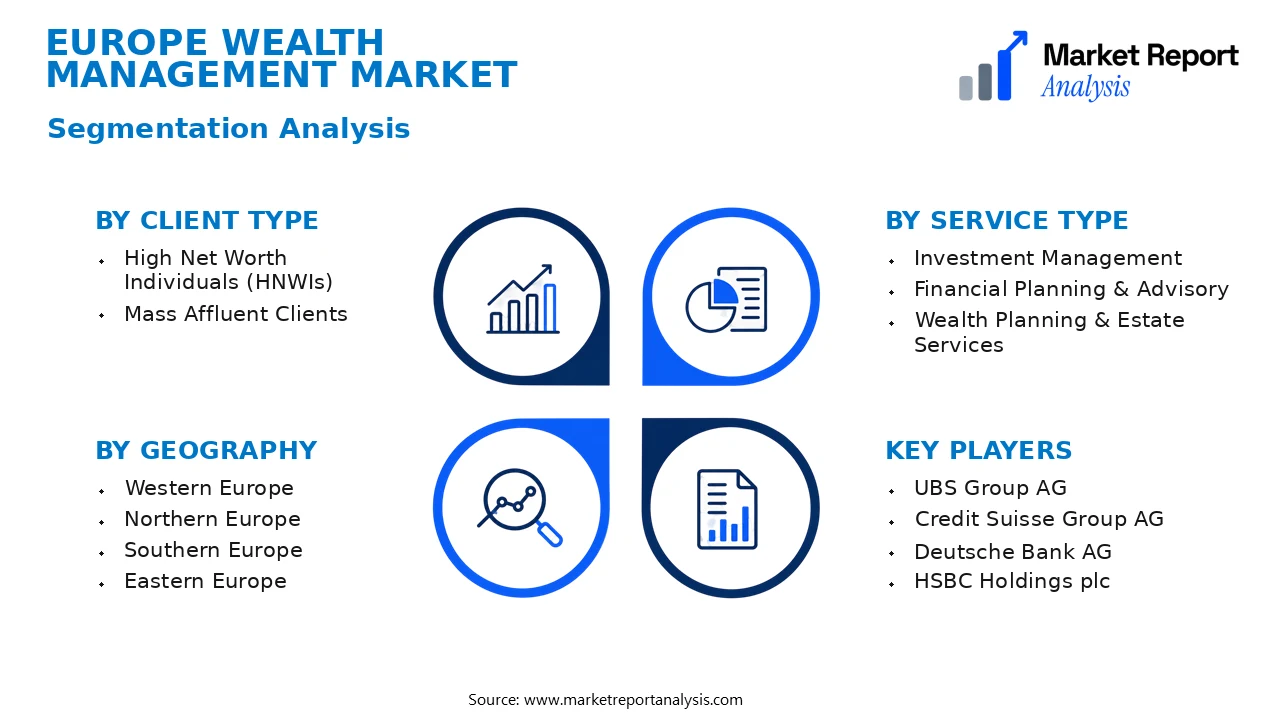
- Client Type
- High Net Worth Individuals (HNWIs): This segment involves high-net-worth individuals with investable assets typically exceeding USD 1 Million. It is driven by bespoke investment solutions and wealth preservation needs, showing strong demand for personalized wealth management services.
- Mass Affluent Clients: Comprising clients with investable assets between USD 100,000 and USD 1 Million, this group is increasingly attracted to automated advisory services and hybrid models blending digital and traditional advisory approaches, fueling growth in scalable solutions.
- Service Type
- Investment Management: This category includes portfolio management, asset allocation, and securities trading, representing core activities that offer tailored investment strategies to meet specific risk and return profiles.
- Financial Planning & Advisory: Encompassing estate planning, tax optimization, and retirement planning, these services are vital for comprehensive wealth management, especially for clients seeking holistic financial solutions.
- Wealth Planning & Estate Services: Focused on legacy planning, inheritance arrangements, and estate transfer strategies, this subsegment caters to clients prioritizing long-term wealth preservation and generational transfer.
- Geography
- Western Europe: Dominated by mature financial markets such as the UK, France, and Germany, this region exhibits high client wealth densities, advanced digital infrastructure, and strong regulatory environments fostering wealth management growth.
- Northern Europe: Countries like Sweden, Norway, and Denmark display a preference for sustainable investing, digital advisory platforms, and innovative wealth services aligned with technological adoption trends.
- Southern Europe: Markets such as Italy, Spain, and Greece are characterized by developing financial sectors, increased interest in wealth management due to rising disposable incomes, and a gradual shift towards more structured advisory services.
- Eastern Europe: Countries including Poland and Hungary are experiencing growing wealth accumulation, with evolving client bases seeking accessible and cost-effective wealth management solutions amidst expanding financial literacy.
Competitive Intelligence
The Europe Wealth Management Market is characterized by moderate to high competition among a blend of established multinational financial institutions and emerging boutique firms. The market exhibits a somewhat fragmented but increasingly consolidated structure, with leading players holding significant market share through strategic mergers and acquisitions. Major firms adopt aggressive expansion strategies across emerging European markets, reinforced by substantial investments in R&D to develop tailored, digitized wealth management products that cater to high-net-worth individuals. Innovation plays a critical role, with firms leveraging advanced analytics, AI-driven advisory platforms, and cybersecurity enhancements to differentiate offerings and improve customer engagement. Strategic partnerships with fintech firms and technology providers are common, fostering innovative service solutions and broadening client reach. Acquisitions of regional firms allow larger entities to deepen market penetration and diversify service portfolios. Companies focus on expanding digital capabilities and personalized service models as key competitive differentiators, enabling them to maintain a competitive edge amid evolving regulatory landscapes and shifting client preferences.
Leading Company Profiles
The competitive landscape within the Europe Wealth Management Market features a diverse set of prominent firms that exhibit strengths across asset management, digital adoption, client segmentation, and innovative service offerings. These companies are striving to enhance client engagement through technological advancements, strategic alliances, and tailored investment solutions, thereby consolidating their market positions and expanding their AUM (Assets Under Management).
- UBS Group AG
- Credit Suisse Group AG
- Deutsche Bank AG
- HSBC Holdings plc
- BNP Paribas Wealth Management
- Santander Wealth Management
- Barclays Wealth and Investment Management
- Societe Generale Private Banking
- Allianz Global Wealth Management
- Schroders plc
UBS Group AG
UBS is a global leader in wealth management, leveraging advanced digital platforms and personalized client services. Its strategic focus on sustainable investing and innovative digital solutions positions it strongly against peers.
Credit Suisse Group AG
Credit Suisse specializes in high-net-worth individual (HNWI) and ultra-HNWI segments with a broad product suite, including alternative investments. It emphasizes transformation through digital enhancements and strategic acquisitions.
Deutsche Bank AG
Deutsche Bank’s wealth management division offers bespoke advisory services, focusing on integrating advanced analytics and AI to improve client experiences and operational efficiency amid ongoing digital transformation efforts.
HSBC Holdings plc
HSBC provides comprehensive wealth management solutions across Europe, with an emphasis on digital channels and cross-border services tailored to expatriates and international clients, supporting its strategic expansion plan.
BNP Paribas Wealth Management
BNP Paribas focuses on sustainable investing and digital client engagement, harnessing innovative technologies to cater to the evolving preferences of European high-net-worth clients with a strong presence in France and broader Europe.
Santander Wealth Management
Santander leverages its extensive European branch network and digital propositions to deliver personalized wealth management services, emphasizing automation and client-centric customization to gain market share.
Barclays Wealth and Investment Management
Barclays continues to invest in digital wealth platforms and personalized advisory services, aiming to deepen client relationships and expand its digital-first approach in key European markets.
Societe Generale Private Banking
Societe Generale emphasizes digital innovation, including AI-enhanced investment advisory and ESG-driven portfolios, to serve its affluent clientele with tailored wealth solutions that are both sustainable and technologically advanced.
Allianz Global Wealth Management
Allianz’s strategy revolves around integrating insurance products with wealth management services, emphasizing digital distribution channels and sustainable investment strategies for comprehensive client solutions.
Schroders plc
Schroders combines active asset management with innovative client engagement platforms, focusing on environmental, social, and governance factors to appeal to contemporary investors seeking sustainable options.
Strategic Business Developments
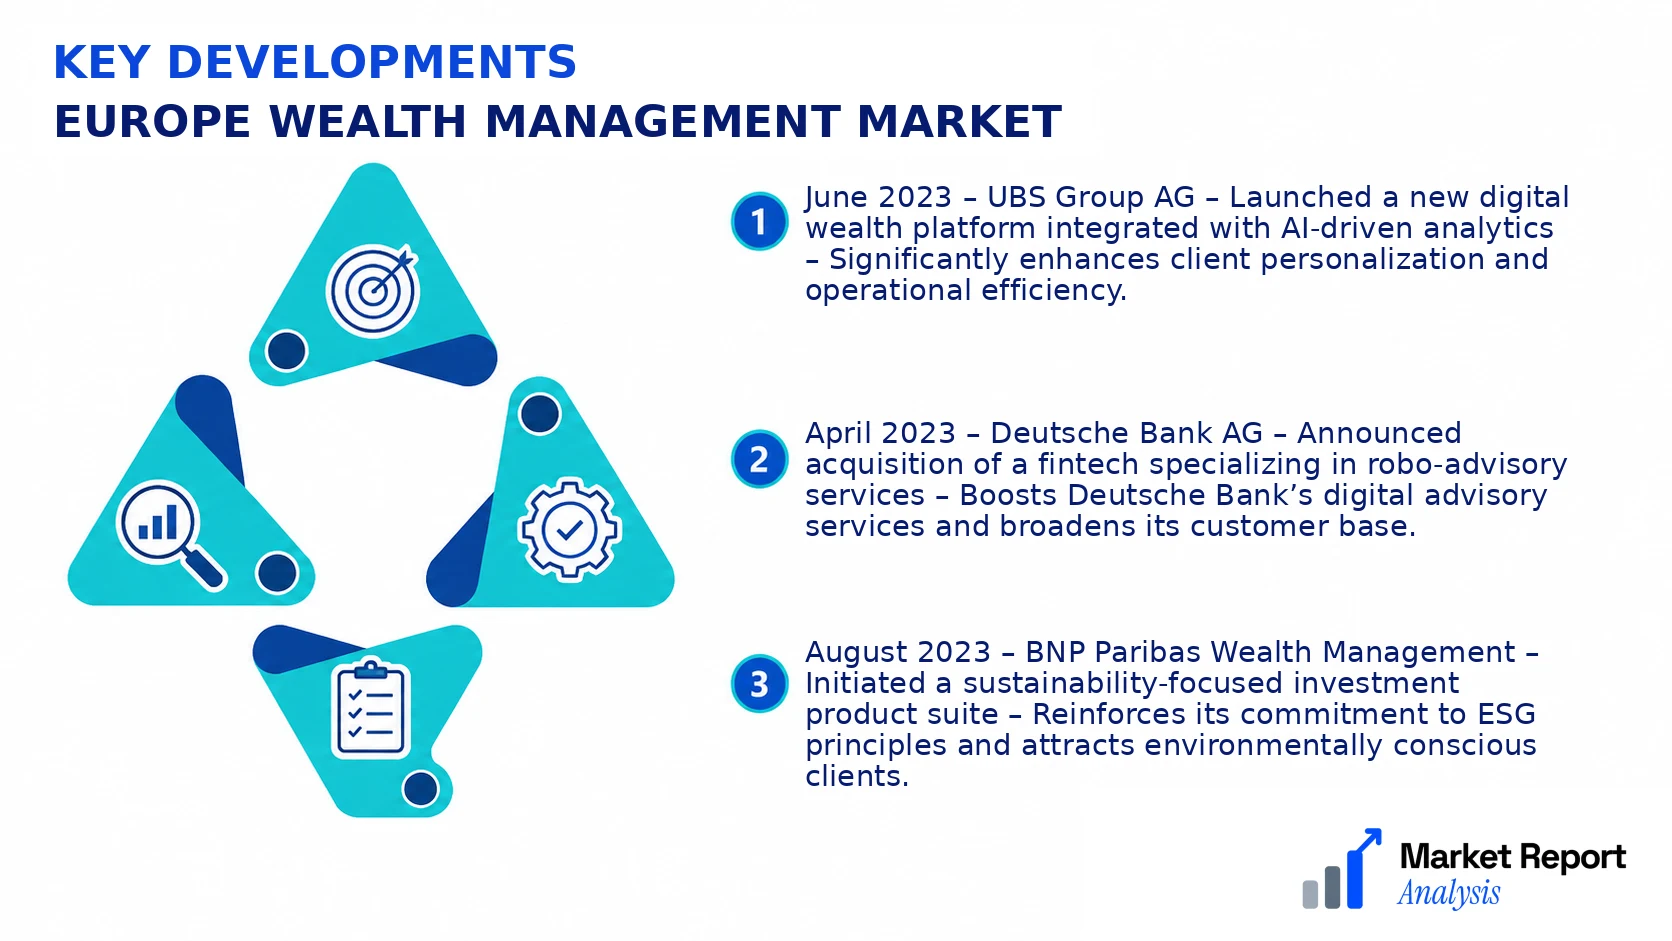
- June 2023 – UBS Group AG – Launched a new digital wealth platform integrated with AI-driven analytics – Significantly enhances client personalization and operational efficiency.
- April 2023 – Deutsche Bank AG – Announced acquisition of a fintech specializing in robo-advisory services – Boosts Deutsche Bank’s digital advisory services and broadens its customer base.
- August 2023 – BNP Paribas Wealth Management – Initiated a sustainability-focused investment product suite – Reinforces its commitment to ESG principles and attracts environmentally conscious clients.
- May 2023 – Credit Suisse Group AG – Formed a strategic partnership with a leading fintech to co-develop advanced client onboarding solutions – Improves onboarding experience and reduces operational costs.
- July 2023 – HSBC Holdings plc – Expanded cross-border wealth management services for expatriates through new digital offerings – Enhances global service reach and attracts international clients.
Frequently Asked Questions
What is the Europe Wealth Management Market?
The Europe Wealth Management Market encompasses financial services aimed at high-net-worth individuals across Europe, including investment advisory, estate planning, and asset management. It plays a vital role in wealth preservation and growth for affluent clients in the region.
What is the current market size of Europe Wealth Management Market?
As of 2026, the Europe Wealth Management Market was valued at approximately USD 3.2 Trillion, reflecting the region’s mature financial landscape, increased wealth accumulation, and growing demand for personalized financial services among high-net-worth individuals.
What factors are driving the Europe Wealth Management Market?
Key drivers include rising wealth across European countries, expanding client base of ultra-high-net-worth individuals, technological advancements facilitating digital wealth management solutions, and evolving regulatory frameworks encouraging transparency and product diversification in financial advisory services.
Which region dominates the Europe Wealth Management Market?
Western Europe continues to dominate the market due to its high density of affluent populations, extensive financial infrastructure, and mature wealth management sector, with countries like Switzerland, the UK, and Germany leading regional contributions.
Which segment is expected to grow the fastest?
Digital wealth management services are projected to witness the fastest growth, driven by increased adoption of robo-advisors, AI-driven analytics, and online platforms that offer cost-effective, scalable, and personalized investment solutions for tech-savvy clients.
Who are the leading companies operating in the Europe Wealth Management Market?
Major players include UBS Group AG, Credit Suisse, Deutsche Bank, Allianz Global Investors, and HSBC Private Bank, which leverage extensive client networks, advanced technological platforms, and diversified service portfolios to maintain competitive dominance in the region.
Analyst Perspective
The Europe Wealth Management Market is positioned for sustained growth, driven by increasing wealth accumulation among high-net-worth individuals and evolving client expectations. The long-term outlook remains promising as digital transformation accelerates, enabling personalized and efficient advisory services. Commercial opportunities lie in expanding digital advisory platforms, incorporating AI and data analytics to enhance client engagement, and developing tailored investment products. Technology evolution will continue to reshape service models, emphasizing automation, cybersecurity, and transparency, thereby elevating client trust and operational efficiency. Investment priorities should focus on innovative digital infrastructure and strategic acquisitions to strengthen market positioning. Competitive intensity is expected to intensify as new entrants leverage fintech innovations, while established players seek to differentiate through superior service quality and technological investment. Regional growth potential is notably high in emerging regions within Europe, where underserved markets present fresh avenues for expansion. Ultimately, a strategic balance between digital innovation, regional targeting, and competitive differentiation will be essential for long-term success in this evolving landscape.
