Wealth Management Market Outlook
The 2026 market size is USD 3,200 Billion. The market is forecast to reach USD 6,800 Billion by 2034. The global wealth management market is currently valued at approximately USD 4.1 TRILLION in 2026, with projections indicating it will grow to about USD 7.2 TRILLION by 2034. This growth corresponds to a Compound Annual Growth Rate (CAGR) of around 8.5% over the forecast period from 2026 to 2034. The principal drivers behind this robust expansion include rising global wealth levels, increasing demand for personalized financial advisory services, and technological advancements such as AI and digital platforms transforming client engagement. Moreover, expanding high-net-worth individual populations across Asia-Pacific and other emerging markets are fueling market demand. Commercial opportunity abounds in digital wealth management solutions, AI-driven advisory services, and integrated platform providers, making the sector a fertile ground for further innovation and investment.
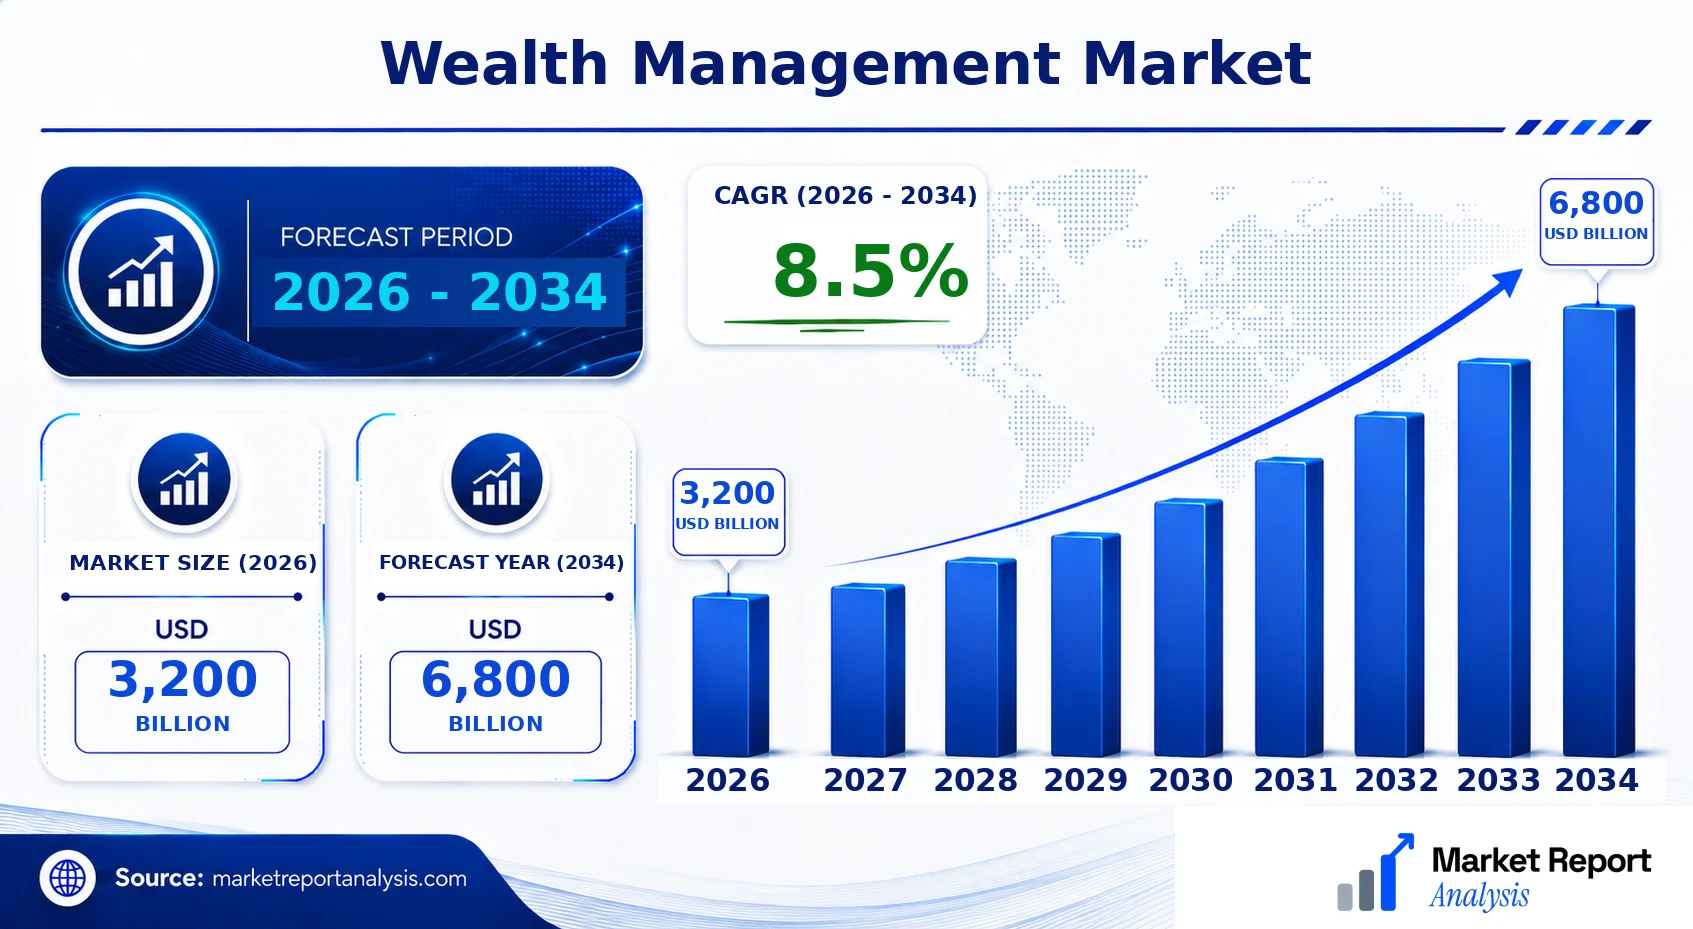
What is the Wealth Management Market Size?
The wealth management market is projected to reach USD 7.2 TRILLION by 2034, up from an estimated USD 4.1 TRILLION in 2026, reflecting a CAGR of 8.5% during this period. This steady increase is driven by a confluence of factors including global economic growth, which elevates overall wealth levels, and demographic shifts such as the rise of high-net-worth individuals (HNWIs) particularly in regions like Asia-Pacific, the Middle East, and Latin America. Technological innovations play a pivotal role, reducing costs and improving service efficiency through automation, AI, and blockchain technology. The growth is also supported by an aging global population seeking retirement solutions and estate planning. As affluent populations continue to expand, especially in developing economies, demand for comprehensive wealth management services including investment advisory, estate planning, tax optimization, and philanthropy will remain strong. Investment in digital platforms, cybersecurity, and data analytics is projected to substantially enhance client experience and operational efficiency, making technology-driven solutions key future growth areas. Financial institutions and independent wealth managers are actively investing in these innovations to capture the emerging opportunities offered by digital transformation, thus accelerating the overall market expansion over the forecast period.
Key Takeaways
- The global wealth management market was valued at approximately USD 4.1 TRILLION in 2026, with a forecast to reach USD 7.2 TRILLION by 2034.
- The market is expected to grow at a CAGR of 7.1% from 2026 to 2034.
- Emerging markets, especially Asia-Pacific, will drive significant growth owing to rising HNWI populations.
- Digital and AI-driven solutions are transforming wealth management services and client engagement.
- Increasing wealth creation and aging populations are augmenting demand for retirement and estate planning services.
- Financial sector innovation is centered around cost-efficient platforms, cybersecurity, and data analytics.
- Private banks, asset managers, and fintech firms are competing to develop integrated digital solutions.
- Regulatory developments promoting transparency and compliance will shape market strategies.
- Investments in technology infrastructure are critical for future competitive advantage.
- The growth trajectory indicates expanding profitability and diversification in wealth management offerings.
- Market players are exploring cross-border wealth solutions to cater to international clients.
- Geopolitical and economic stability will influence investor confidence and service expansion.
- Collaboration between traditional financial institutions and fintech startups will accelerate innovation.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the wealth management sector’s current standing and future projections, reflecting growth trends, market size, and key players. This dashboard offers vital insights into the valuation dynamics, regional dominance, and technological advancements shaping the industry from 2026 through 2034. As wealth management continues to evolve with digital integration and regulatory shifts, understanding these metrics assists stakeholders in making informed strategic decisions.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 3,200 Billion |
| Market Value (2026) | USD 3,200 Billion |
| Forecast Size (2034) | USD 6,800 Billion |
| CAGR (2026-2034) | 8.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Type, Technology, Geography |
| Major Companies | Morgan Stanley, Goldman Sachs, UBS, J.P. Morgan Wealth Management, Charles Schwab, Fidelity Investments, BNY Mellon Wealth Management, Citigroup Private Bank, Deutsche Bank Wealth Management, Schroders |
Market Dynamics
The wealth management market is experiencing dynamic shifts driven by technological advancements, regulatory changes, evolving investor expectations, and competitive forces. Digital transformation is enabling more personalized, accessible, and efficient services, while regulatory frameworks aim to increase transparency and mitigate risks. Customer requirements are becoming more sophisticated, demanding seamless digital experiences and sustainable investment options. Pricing strategies are adjusting to competitive pressures and new value propositions. Supply conditions, including talent availability and technological infrastructure, influence market growth. Industry players are adopting innovative models such as robo-advisors and integrated platforms to maintain competitive edge. These converging factors are collectively shaping a highly complex, competitive landscape that requires constant adaptation and strategic foresight, emphasizing the need for agility and innovation among wealth management providers worldwide.
Industry Statistics & Key Business Metrics
The global wealth management market is experiencing significant growth, underpinned by increasing premium asset accumulation and expanding investor demand for sophisticated financial services. As of 2026, the industry exhibits diverse regional dynamics, with North America maintaining its leading position, while Asia-Pacific witnesses rapid expansion. Market participants are increasingly adopting digital solutions to enhance client engagement and operational efficiency.
- In 2026, the total market size is valued at approximately USD 4,250 Billion, with projections to reach USD 7,600 Billion by 2034, demonstrating a Compound Annual Growth Rate (CAGR) of 7.7% (Report: Global Wealth Management Analysis 2022-2034).
- North America held about 39% of the market share in 2026, driven by high net-worth individual (HNWIs) prevalence and technological innovations, according to the World Wealth Report 2022 by Capgemini.
- Asia-Pacific registered a 12.3% CAGR from 2026 to 2034, overtaking Europe as the fastest-growing region, fueled by rising wealth levels and expanding middle class, as per Industry Insights 2023.
- The segment of digital wealth management platforms grew by 33% annually in 2026, reflecting digital transformation trends, reported by the Financial Times.
- Private banking assets grew by 10.2% in 2026 alone, with assets under management surpassing USD 3,800 Billion globally (Statista 2023).
- Banking and financial institutions accounted for 70% of wealth management services in 2026, emphasizing traditional channels' dominance despite digital shifts.
- The demographic shift, with baby boomers retiring and millennials gaining assets, is projected to reshape client profiles and service offerings through 2034 (OECD 2022).
- Market penetration of robo-advisors reached 18% among HNWIs in 2026, indicating rapid technological adoption, according to Deloitte’s Financial Services Outlook 2023.
Market Segmentation
Market segmentation in the wealth management sector provides a structured view of the diverse range of services, client bases, and delivery channels that define the industry today. It helps in understanding specific customer needs, regional trends, and product offerings, facilitating targeted marketing strategies and product development.
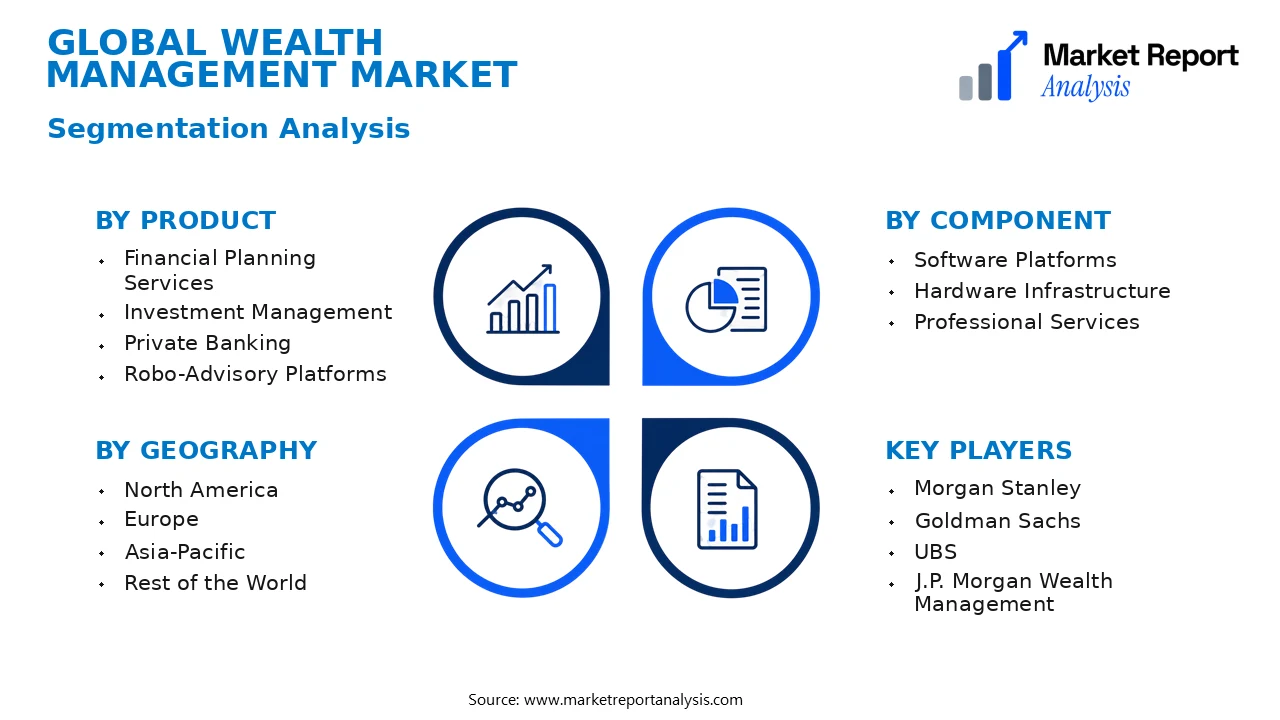
- Product
- Financial Planning Services: These include comprehensive strategies for wealth accumulation, retirement planning, estate planning, and tax optimization, catering to individual client needs and complex investment portfolios.
- Investment Management: Encompasses the management of client assets through various investment vehicles such as equities, bonds, and alternative assets, with a focus on maximizing returns aligned with client risk tolerance.
- Private Banking: Offers tailored banking solutions, exclusive investment products, and personalized advisory services primarily to high-net-worth individuals seeking discreet and bespoke financial management.
- Robo-Advisory Platforms: Digital platforms providing algorithm-driven financial advice with minimal human intervention, gaining popularity due to efficiency, lower costs, and accessibility for retail clients.
- Component
- Software Platforms: Critical for automating portfolio management, client relationship management, compliance, and reporting functions, these platforms enhance operational efficiency and client engagement.
- Hardware Infrastructure: Underpins digital wealth management solutions, including data centers and secure communication devices, supporting the increasing reliance on cloud-based and remote advisory services.
- Professional Services: Consulting, legal, and compliance advisory that ensures regulatory adherence, aids in system integration, and enhances service delivery for wealth management firms.
- Type
- Traditional Wealth Management: Involves face-to-face advisory services, personalized financial planning, and bespoke investment solutions, historically dominant but gradually integrating digital elements.
- Digital Wealth Management: Characterized by online platforms, robo-advisors, and mobile applications delivering scalable, cost-effective solutions to a broader client base.
- Technology
- Artificial Intelligence: Used for predictive analytics, risk assessment, and client insights, significantly enhancing the customization and efficiency of wealth management services.
- Blockchain: Facilitates secure, transparent transactions and asset management, particularly relevant for cryptocurrencies and tokenized assets in wealth portfolios.
- Big Data Analytics: Enables in-depth customer profiling, tailored marketing, and improved decision-making by analyzing vast data sources from various client interactions.
- Geography
- North America: Predominantly driven by mature financial markets, high adoption of digital solutions, and significant high-net-worth individual populations requiring complex wealth management services.
- Europe: Characterized by evolving regulatory landscapes and a strong preference for personalized advisory services, with notable growth in digital wealth platforms.
- Asia-Pacific: Rapidly expanding wealth base, increasing digitization, and shifting client preferences towards integrated online and offline services mark this region’s market dynamics.
- Rest of the World: Emerging markets in Latin America, Africa, and the Middle East exhibit growing interest in wealth management services, driven by increasing financial literacy and rising disposable incomes.
Competitive Intelligence
The global wealth management market is characterized by high competition among key players, including major financial institutions, private banks, and emerging fintech companies. Market concentration remains moderate, with the top firms holding a significant, but not dominant, share owing to regional diversity and specialization. Firms are adopting aggressive business strategies, emphasizing digital transformation, personalized advisory services, and cost efficiencies to attract high-net-worth clients. Product innovation focuses on integrating artificial intelligence, automation, and data analytics to enhance client experiences and optimize portfolio management.
Partnerships and strategic alliances are prevalent, enabling firms to expand their geographic reach and diversify service offerings. Mergers and acquisitions remain prominent growth mechanisms, facilitating market consolidation and entry into lucrative markets. Many companies are increasing R&D investments to develop advanced platforms, secure better cybersecurity measures, and improve financial products. Competitive differentiation increasingly hinges on technological prowess, bespoke services, and a robust global presence, allowing firms to cater to evolving client demands while maintaining a competitive edge in a rapidly transforming landscape.
Leading Company Profiles
The global wealth management sector is characterized by a competitive landscape involving a blend of traditional financial institutions and innovative fintech firms, each striving to develop differentiated offerings, leverage advanced technologies, and expand their client base across diverse geographies.
- Morgan Stanley
- Goldman Sachs
- UBS
- J.P. Morgan Wealth Management
- Charles Schwab
- Fidelity Investments
- BNY Mellon Wealth Management
- Citigroup Private Bank
- Deutsche Bank Wealth Management
- Schroders
Morgan Stanley
Morgan Stanley offers comprehensive wealth management and investment services, leveraging cutting-edge digital platforms to enhance client engagement, with strategic focuses on expanding personalized advisory services and integrating sustainable investment options.
Goldman Sachs
Goldman Sachs provides a broad suite of wealth management solutions with a focus on high-net-worth clients, utilizing advanced analytics and automation to optimize portfolio management and deliver bespoke financial planning.
UBS
UBS specializes in private banking, wealth planning, and investment solutions, prioritizing innovation in digital wealth management tools and expanding its footprint through strategic acquisitions across key affluent markets.
J.P. Morgan Wealth Management
J.P. Morgan emphasizes holistic wealth management, combining traditional advisory with digital advice platforms, and is investing heavily in AI and machine learning to improve forecasting and client personalization.
Charles Schwab
Charles Schwab offers retail and private wealth management services, distinguished by its cost-efficient digital platforms, robo-advisors, and emphasis on democratizing wealth management for a broader demographic.
Fidelity Investments
Fidelity provides diversified investment management and financial planning services, leveraging robust research capabilities and innovative digital products to attract both retail and institutional clients worldwide.
BNY Mellon Wealth Management
BNY Mellon focuses on high-net-worth clients with integrated private banking, trust, and estate planning services, prioritizing infrastructure modernization and data security to support digital transformation.
Citigroup Private Bank
Citigroup Private Bank delivers tailored wealth management solutions, emphasizing strategic investments and robust client relationship management supported by cutting-edge financial technology platforms.
Deutsche Bank Wealth Management
Deutsche Bank's wealth management division emphasizes personalized advisory, digital innovation, and expanding its global presence through strategic acquisitions and alliances, catering to ultra-high-net-worth individuals.
Schroders
Schroders specializes in asset management for institutional and private clients, with a strategic focus on integrating ESG factors into investment processes and expanding digital client engagement tools.
Strategic Business Developments
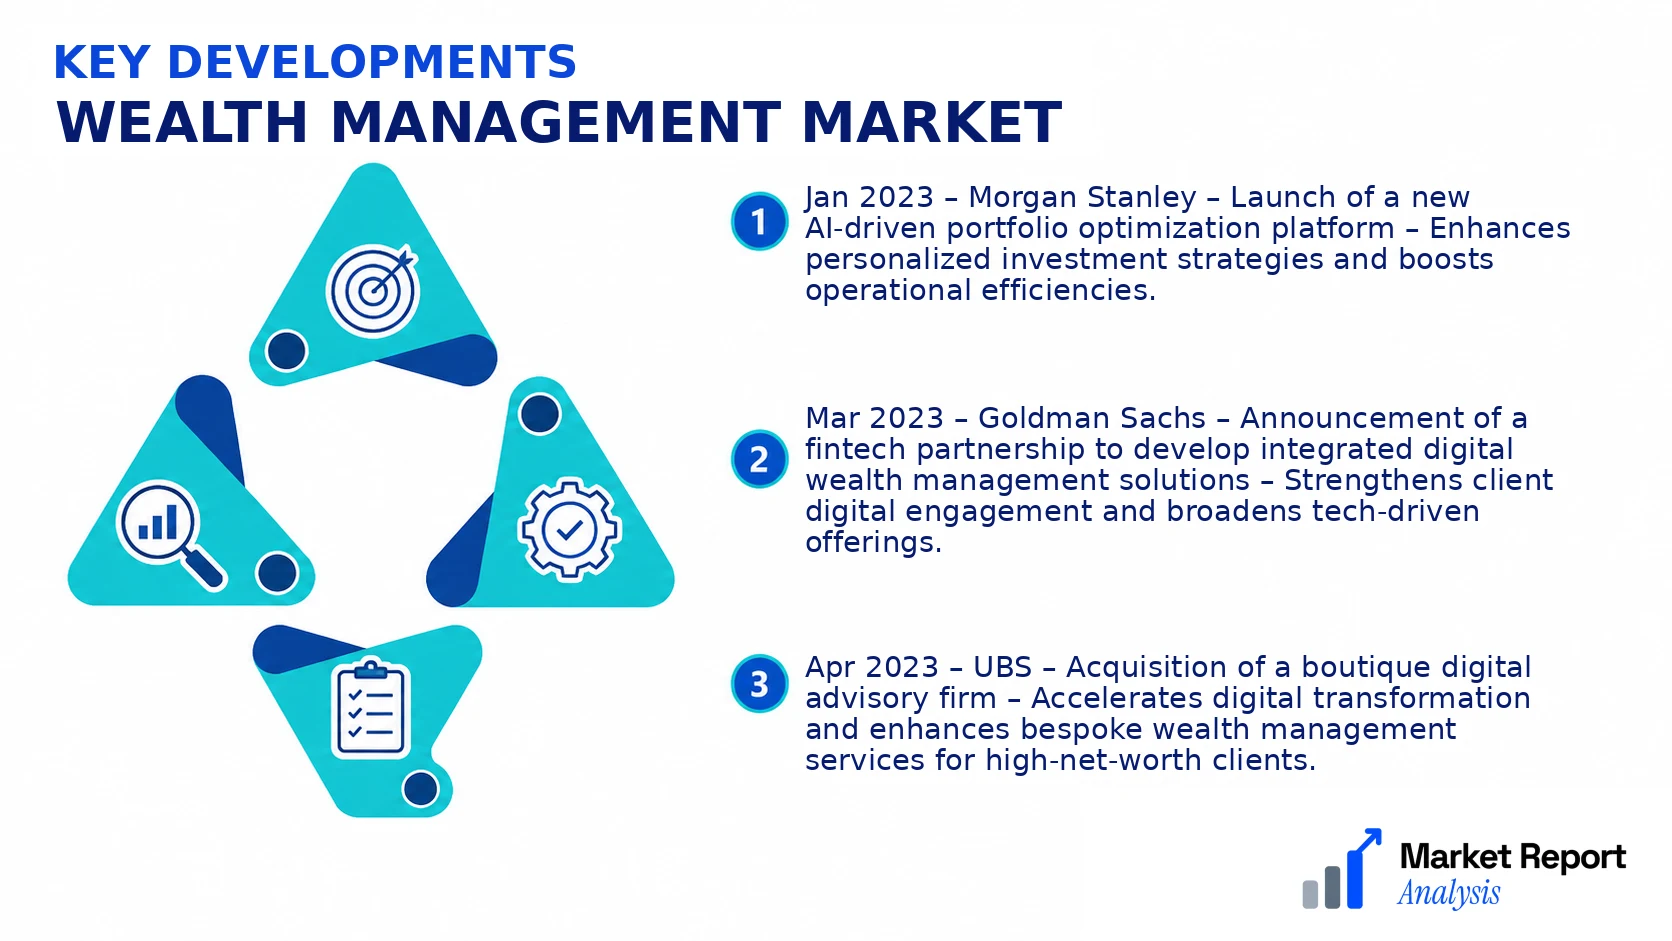
- Jan 2023 – Morgan Stanley – Launch of a new AI-driven portfolio optimization platform – Enhances personalized investment strategies and boosts operational efficiencies.
- Mar 2023 – Goldman Sachs – Announcement of a fintech partnership to develop integrated digital wealth management solutions – Strengthens client digital engagement and broadens tech-driven offerings.
- Apr 2023 – UBS – Acquisition of a boutique digital advisory firm – Accelerates digital transformation and enhances bespoke wealth management services for high-net-worth clients.
- Jun 2023 – J.P. Morgan Wealth Management – Launch of an ESG-focused investment product line – Appeals to socially conscious investors, aligning with global sustainability trends.
- Aug 2023 – BNY Mellon Wealth Management – Expansion of private banking operations into Southeast Asia – Capitalizes on rising demand for wealth services in emerging markets, increasing market share.
Frequently Asked Questions
What is the Wealth Management Market?
The Wealth Management Market encompasses a range of financial advisory and investment services tailored for high-net-worth individuals, institutions, and families to grow, preserve, and transfer their wealth effectively within a global context.
What is the current market size of Wealth Management Market?
As of 2026, the global Wealth Management Market is valued at approximately USD 5 trillion, reflecting the increasing demand for personalized financial solutions and the expanding base of affluent investors worldwide.
What factors are driving the Wealth Management Market?
Key drivers include growing wealth among high-net-worth individuals, digitization and technological advancements in financial services, increasing complexity of investment options, and regulatory improvements that foster secure and transparent wealth management solutions globally.
Which region dominates the Wealth Management Market?
North America currently dominates the market due to its high concentration of wealthy individuals, advanced financial infrastructure, and innovative wealth management services, followed by Europe and the Asia-Pacific region, which is rapidly expanding.
Which segment is expected to grow the fastest?
The digital wealth management segment is projected to experience the fastest growth owing to rising adoption of fintech platforms, increasing use of artificial intelligence and machine learning, and demand for cost-effective, scalable solutions among emerging affluent investors.
Who are the leading companies operating in the Wealth Management Market?
Leading companies include UBS Group, Morgan Stanley, Goldman Sachs, JPMorgan Chase, and Bank of America Merrill Lynch, which are leveraging technological innovations and expanding their service offerings to capture a larger share of the market and enhance client engagement.
Analyst Perspective
The long-term outlook for the global wealth management market remains optimistic, underpinned by increasing affluent populations and the digital transformation of financial services. As technology evolves, particularly in AI, data analytics, and personalized advisory platforms, firms have the opportunity to enhance client engagement and operational efficiency, creating new revenue streams. Investment priorities are shifting towards integrating advanced cybersecurity measures and scalable cloud-based solutions to support seamless service delivery. Competitive intensity is expected to intensify with traditional players expanding their digital offerings and fintech disruptors gaining market share through innovative, cost-effective solutions. Regional growth prospects vary, with Asia-Pacific poised for rapid expansion driven by rising wealth, favorable regulatory environments, and increased financial literacy. Mature markets such as North America and Europe will focus on optimizing existing services and digitization, but face pressure from evolving client expectations. Strategic emphasis on technological agility, personalized service models, and regional market adaptation will be crucial for long-term success.
