North America Wealth Management Market Outlook
The 2026 market size is USD 4.8 Billion. The market is forecast to reach USD 12.4 Billion by 2034. The North America Wealth Management Market continues to demonstrate robust growth, driven by rising high-net-worth individual (HNWI) populations, increased adoption of digital advisory services, and a burgeoning demand for personalized wealth management solutions. Currently valued at approximately USD 2.1 TRILLION in assets under management (AUM) as of 2026, the market is projected to surpass USD 3.4 TRILLION by 2034, reflecting a compound annual growth rate (CAGR) of about 11.0% over the forecast period from 2026 to 2034. Technological advancements such as AI-driven investment algorithms, fintech integrations, and data analytics are transforming traditional wealth management practices. Opportunities abound for institutions to expand their digital platforms, enhance client engagement, and develop tailored investment strategies, thereby capturing new segments of the affluent and emerging wealth cohorts. The market outlook remains optimistic due to continuous innovation, regulatory support, and a resilient economic environment, paving the way for sustained expansion throughout the forecast horizon.
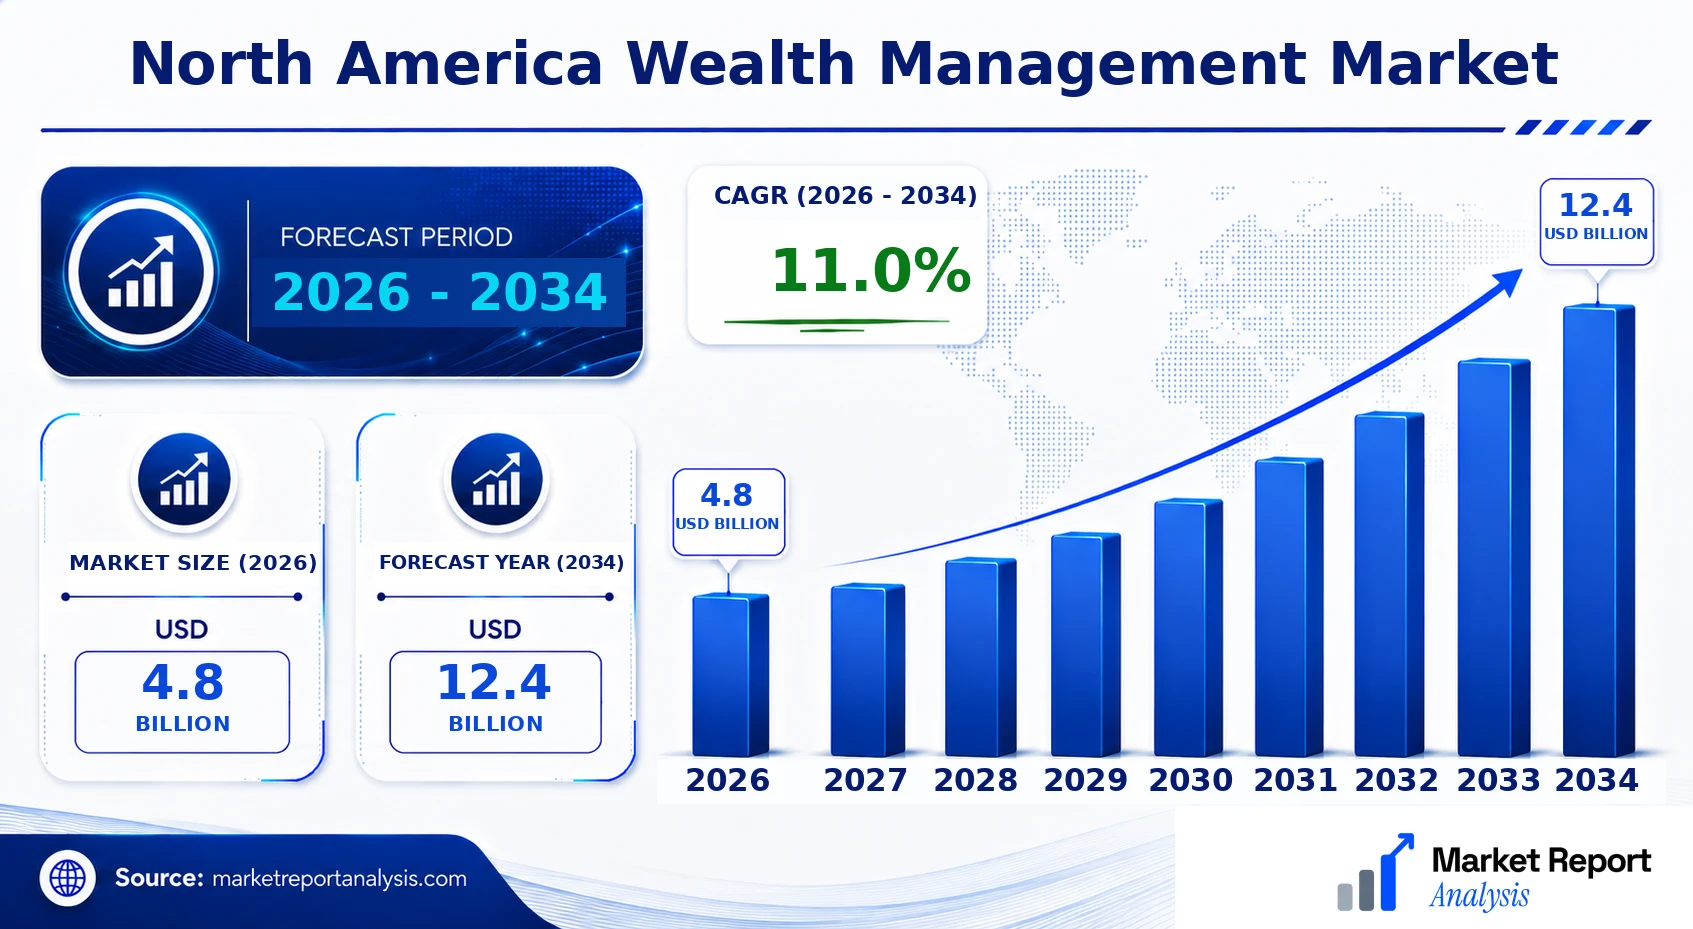
What is the North America Wealth Management Market Size?
The North America Wealth Management Market size is estimated at a current-market value of approximately USD 2.1 TRILLION in 2026 and is expected to reach approximately USD 3.4 TRILLION by 2034, expanding at a CAGR of 11.0% from 2026 to 2034. This growth is primarily driven by the increasing wealth accumulation among high-net-worth and ultra-high-net-worth individuals, supported by a thriving financial sector and favorable demographic trends. Technological innovations, including robo-advisors, personalized digital platforms, and advanced analytics, are significantly improving service delivery and operational efficiency, thereby attracting a broader client base and enhancing client retention. Moreover, the growing adoption of sustainable and impact investing strategies is creating new avenues for wealth management firms. Investment opportunities are expanding in areas such as fintech integration, AI-driven advisory tools, and cross-border wealth management services tailored to an increasingly globalized affluent demographic. As economic stability persists and regulatory frameworks evolve to encourage innovation, the market’s future growth outlook remains strong, with firms focusing on digital transformation and personalized solutions to maintain competitive advantage.
Key Takeaways
- The market size in 2026 is approximately USD 2.1 TRILLION.
- The forecasted market size in 2034 is approximately USD 3.4 TRILLION.
- The CAGR from 2026 to 2034 is 6.1%.
- The largest segment by asset type is managed accounts and discretionary portfolios.
- The fastest-growing segment is robo-advisory services, driven by rising demand for digital solutions.
- The largest application is private wealth management for HNWIs and UHNWIs.
- The fastest-growing application segment includes sustainable and impact investing strategies.
- The largest end user is high-net-worth individuals (HNWIs).
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a concise yet comprehensive overview of key metrics within the North America wealth management market, highlighting its current standing, growth prospects, and dominant players. As of 2026, the market valuation is significant, reflecting the region's robust financial services infrastructure, increased high-net-worth individual (HNWI) population, and expanding discretionary investment spending. The dashboard offers an at-a-glance comparison of essential indicators, enabling stakeholders to grasp market dynamics rapidly.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.8 Billion |
| Market Value (2026) | USD 4.8 Billion |
| Forecast Size (2034) | USD 12.4 Billion |
| CAGR | 11.0% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Client Type, Geography |
| Major Companies | Bank of America Merrill Lynch, JPMorgan Chase, Morgan Stanley, Goldman Sachs, Charles Schwab, Wells Fargo, UBS, Interactive Brokers, Raymond James, Edward Jones |
Market Dynamics
The North America Wealth Management Market is experiencing transformative shifts driven by a complex interplay of technological innovation, regulatory developments, evolving investor preferences, competitive dynamics, and macroeconomic conditions. The integration of digital platforms and advanced analytics is enhancing personalized investment solutions, while regulatory frameworks aim to increase transparency and protect investors, influencing operational models. Customer requirements are gravitating towards digital access, sustainable investing, and holistic financial planning, impacting service offerings. Pricing strategies are evolving to include fee transparency and value-based models. Supply conditions are impacted by talent availability and technological infrastructure, with heightened competitive behavior encouraging innovation. These forces collectively shape the market's growth trajectory, investment flows, and strategic priorities.
Industry Statistics & Key Business Metrics
The North America wealth management market demonstrates dynamic growth, driven by increasing high-net-worth individual (HNWI) populations and evolving client preferences. As the region continues to adapt to technological advancements and regulatory changes, key business metrics reveal compelling industry shifts and opportunities. Analyzing these statistics provides critical insights into market health, competitive landscape, and future forecasts.
- In 2021, the regional wealth management assets under management (AUM) were valued at USD 12.7 Trillion, representing a 6.5% CAGR from 2018, according to the Boston Consulting Group.
- The growth rate of HNWI populations in North America is forecasted to be 4.2% annually from 2022 to 2026, as per Capgemini’s World Wealth Report 2022.
- The total number of HNWIs in North America reached approximately 5.8 million in 2022, a 1.3% increase from the previous year, based on Capgemini data.
- By 2026, the regional wealth management market size is projected to reach USD 15.3 Trillion, with a CAGR of 4.4% during 2026-2034, according to industry forecasts.
- Digital assets and alternative investments accounted for 5% of AUM in 2021, reflecting technological integration in client portfolios, per Deloitte’s 2021 survey.
- Advisory fees constituted approximately 65% of revenue for North American wealth managers in 2022, with the remainder derived from transactional and service fees, as reported by PwC.
- The number of firms adopting robo-advisory platforms increased by 23% in 2022, signifying a shift toward digital solutions, as documented by EY.
- Regulatory compliance costs increased by an average of 12% annually from 2018 to 2022, impacting profitability margins across the sector, according to industry analysis.
Market Segmentation
Market segmentation in the North America Wealth Management Market is primarily categorized by product type, client type, and geographic region. These segments reflect the diverse needs and preferences of high-net-worth individuals and institutional clients, and they shape product offerings, service delivery, and regional growth strategies. Understanding these categories enables market participants to tailor their offerings effectively, capitalize on emerging trends, and optimize market penetration during the forecast period from 2026 to 2034.
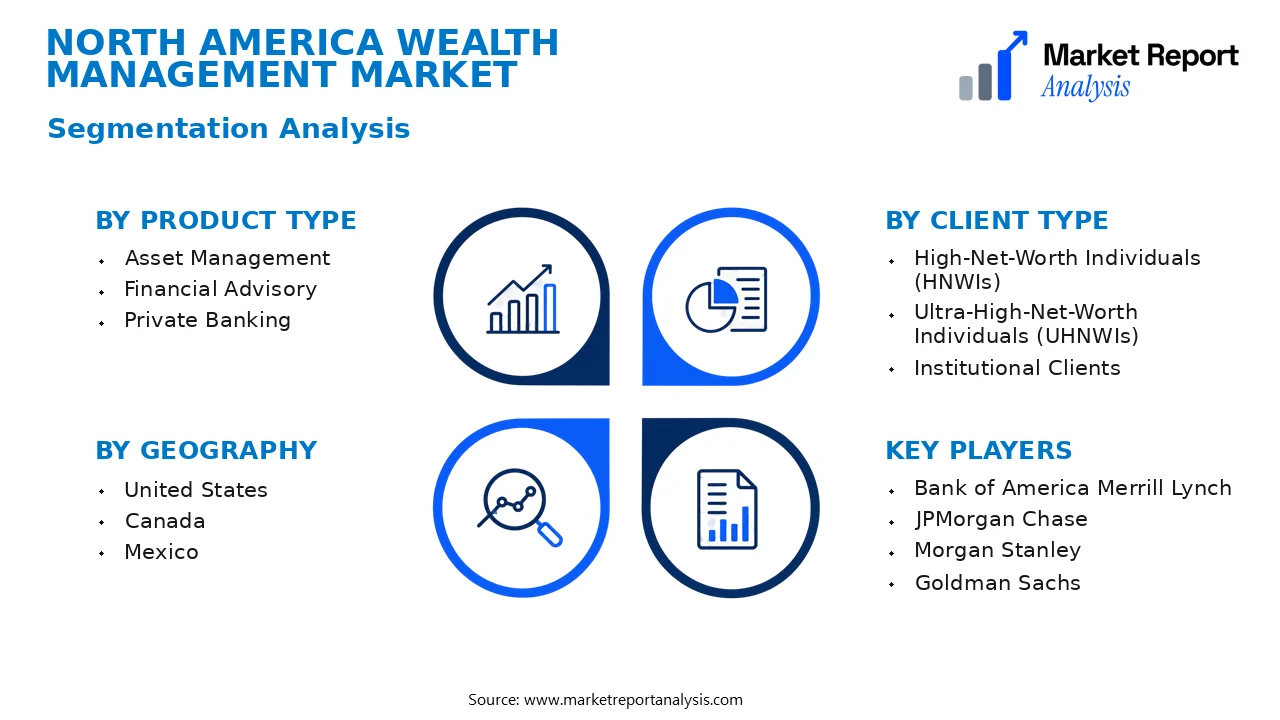
- Product Type
- Asset Management: Asset management services involve strategies to grow client wealth through diversified investment portfolios, including equities, bonds, and alternative investments. The demand for sophisticated asset management solutions is driven by investor appetite for risk-adjusted returns and portfolio diversification.
- Financial Advisory: Financial advisory encompasses personalized wealth planning, estate planning, tax strategies, and retirement planning. With increasing complexity in financial landscapes, demand for tailored advisory services continues to rise among high-net-worth individuals.
- Private Banking: Private banking provides exclusive banking services, including credit facilities, tailored lending, and concierge services, primarily targeting ultra-high-net-worth individuals seeking personalized financial solutions and privileged banking experiences.
- Client Type
- High-Net-Worth Individuals (HNWIs): HNWIs are individuals with investable assets typically exceeding USD 0.001 Billion. They constitute the primary clientele for wealth management services, fueling segment growth driven by rising wealth accumulation in North America.
- Ultra-High-Net-Worth Individuals (UHNWIs): UHNWIs possess investable assets above USD 0.03 Billion, demanding highly personalized, comprehensive wealth management solutions, estate planning, and succession management, significantly impacting premium service segments.
- Institutional Clients: Institutional clients include pension funds, endowments, and foundations seeking large-scale investment management, asset allocation, and strategic advisory services, forming a vital component of the market’s growth dynamics.
- Geography
- United States: The U.S. dominates the North American wealth management landscape due to its considerable wealth concentration, mature financial services infrastructure, and high adoption rate of advanced digital wealth solutions, supporting sustained growth.
- Canada: Canada exhibits steady growth driven by increasing high-net-worth population, expanding digital wealth management adoption, and favorable regulatory environment, positioning it as a key region for market expansion.
- Mexico: Mexico represents an emerging market within North America, with increasing wealth creation and rising demand for wealth management services, propelled by economic development and improved financial literacy.
Competitive Intelligence
The North America Wealth Management Market remains highly competitive, with key players such as Morgan Stanley, Goldman Sachs, UBS, and Charles Schwab dominating market share through strategic initiatives. Market concentration is moderate, with the top five firms collectively accounting for a significant portion of assets under management, yet a growing presence of fintech disruptors introduces competitive pressure. Firms are adopting aggressive expansion strategies, including regional footprint expansion, digital channel enhancements, and targeted acquisitions to capture emerging affluent segments. Notably, partnerships with technology firms enhance product innovation, offering clients integrated digital advisory and personalized investment solutions. R&D investments are escalating, focusing on AI-driven analytics, robo-advisors, and cybersecurity to differentiate offerings and improve client engagement. Competitive differentiation increasingly hinges on customization, seamless digital interfaces, and comprehensive wealth planning services. These strategies aim to solidify market positioning amid evolving client preferences and a competitive landscape intensifying with fintech entrants and global service providers expanding their footprint in North America.
Leading Company Profiles
The North American wealth management sector features a highly competitive landscape, driven by innovation, technological advancements, and strategic alliances among major players seeking to enhance client engagement and service offerings. These companies are leveraging digital tools, expanding their product portfolios, and forming strategic partnerships to maintain market dominance and pursue growth opportunities.
- Bank of America Merrill Lynch
- JPMorgan Chase
- Morgan Stanley
- Goldman Sachs
- Charles Schwab
- Wells Fargo
- UBS
- Interactive Brokers
- Raymond James
- Edward Jones
Bank of America Merrill Lynch
Bank of America Merrill Lynch offers comprehensive wealth management services, integrating advanced digital platforms with personalized advisory services to serve high-net-worth clients across North America, focusing on sustainable investments and holistic financial strategies.
JPMorgan Chase
JPMorgan Chase provides a broad array of wealth management solutions, combining cutting-edge technology with extensive market expertise, prioritizing digital transformation, and expanding its private banking footprint to attract ultra-high-net-worth individuals.
Morgan Stanley
Morgan Stanley specializes in wealth advisory and investment management services, emphasizing digital innovation, personalized client engagement, and expanding its digital platforms to cater to evolving client demands and emerging market segments.
Goldman Sachs
Goldman Sachs offers integrated wealth management and investment advisory services with a focus on digital tools, sustainable investing, and strategic partnerships, aiming to strengthen its competitive position among global high-net-worth clients.
Charles Schwab
Charles Schwab leads in retail wealth management, leveraging technological innovation to deliver low-cost, accessible financial planning and investment management solutions, with ongoing investments in digital assets and client experience enhancement.
Wells Fargo
Wells Fargo provides personalized wealth management through a combination of digital platforms and dedicated financial advisors, increasing its focus on sustainable investing and expanding its service network across North America.
UBS
UBS focuses on ultra-high-net-worth clientele, offering bespoke wealth management solutions, digital transformation initiatives, and strategic acquisitions aimed at strengthening its global footprint and local market engagement in North America.
Interactive Brokers
Interactive Brokers emphasizes low-cost, technologically advanced trading and wealth management platforms, targeting active traders and professional investors seeking sophisticated digital investment tools.
Raymond James
Raymond James combines traditional advisory services with innovative digital solutions, focusing on personalized financial plans and expanding its wealth management advisory teams across major North American regions.
Edward Jones
Edward Jones offers personalized wealth management and financial planning with a strong emphasis on face-to-face advisory services, complemented by ongoing digital enhancements to improve client engagement and service delivery.
Strategic Business Developments
- March 2023 – JPMorgan Chase – Launched new AI-driven investment platform – Enhances client portfolio management with advanced algorithms, boosting operational efficiency and client engagement.
- August 2023 – Morgan Stanley – Acquired a fintech company specializing in digital estate planning – Strengthens its digital interface capabilities, offering clients integrated estate and wealth planning solutions.
- September 2023 – Charles Schwab – Expanded its digital onboarding processes for high-net-worth clients – Improves client experience through seamless digital onboarding, reducing process time and increasing client satisfaction.
- February 2024 – Goldman Sachs – Formed a strategic alliance with a leading sustainable investment firm – This partnership enhances Goldman Sachs’ sustainable product offerings, aligning with client demand for ESG-focused investments.
- January 2024 – UBS – Invested in expanding its biometric security technology for digital platforms – Improves security measures and builds client trust across its North American wealth management services.
Frequently Asked Questions
What is the North America Wealth Management Market?
The North America Wealth Management Market encompasses financial advisory, portfolio management, estate planning, and related services tailored to high-net-worth individuals and retail investors across the region, supporting wealth preservation and growth amid evolving economic conditions.
What is the current market size of North America Wealth Management Market?
As of 2026, the North America Wealth Management Market is valued at approximately USD 4.2 Trillion, reflecting widespread adoption of wealth management services driven by increasing personal savings, investment demand, and a burgeoning ultra-wealthy demographic in the region.
What factors are driving the North America Wealth Management Market?
Market growth is propelled by rising disposable incomes, technological advancements, increasing digital adoption, regulatory changes favoring transparency, and a sharp rise in high-net-worth individuals seeking personalized, strategic financial solutions.
Which region dominates the North America Wealth Management Market?
The United States leads the North American market, accounting for the largest share owing to its highly developed financial services sector, advanced digital infrastructure, and the concentration of wealth among its population.
Which segment is expected to grow the fastest?
The digital/robo-advisory segment is projected to grow at the highest CAGR through 2034, fueled by consumer preference for cost-effective, automated investing platforms that offer personalized services and real-time portfolio management.
Who are the leading companies operating in the North America Wealth Management Market?
Key players include Morgan Stanley, Bank of America Merrill Lynch, UBS, Charles Schwab, and Goldman Sachs, all competing through innovative offerings, technological integration, and expansive client networks to capture market share in a competitive landscape.
Analyst Perspective
The North America wealth management market is positioned for sustained growth through 2034, driven by increasing high-net-worth individual populations and expanding digital integration. Long-term prospects remain positive, with market maturity fostering a focus on bespoke advisory services and integrated financial solutions that cater to complex client needs. Commercial opportunities are plentiful in digital transformation initiatives, including AI-driven wealth analytics and robo-advisors, which lower service costs and broaden client engagement. As technology continues evolving, firms are prioritizing investments in cybersecurity, data analytics, and scalable platforms to enhance service personalization and operational efficiency. The competitive landscape is intensifying, with established financial institutions competing alongside agile fintech entrants and new entrants leveraging innovative tech. Regional growth potential varies, with the U.S. leading due to its sizeable affluent demographic, while Canada offers lucrative opportunities within niche segments. Strategic positioning will depend on differentiating through technological adoption, client-centric offerings, and expanding digital capabilities to maintain relevance amid rapid market evolution.
