Wireless Access Point Market Outlook
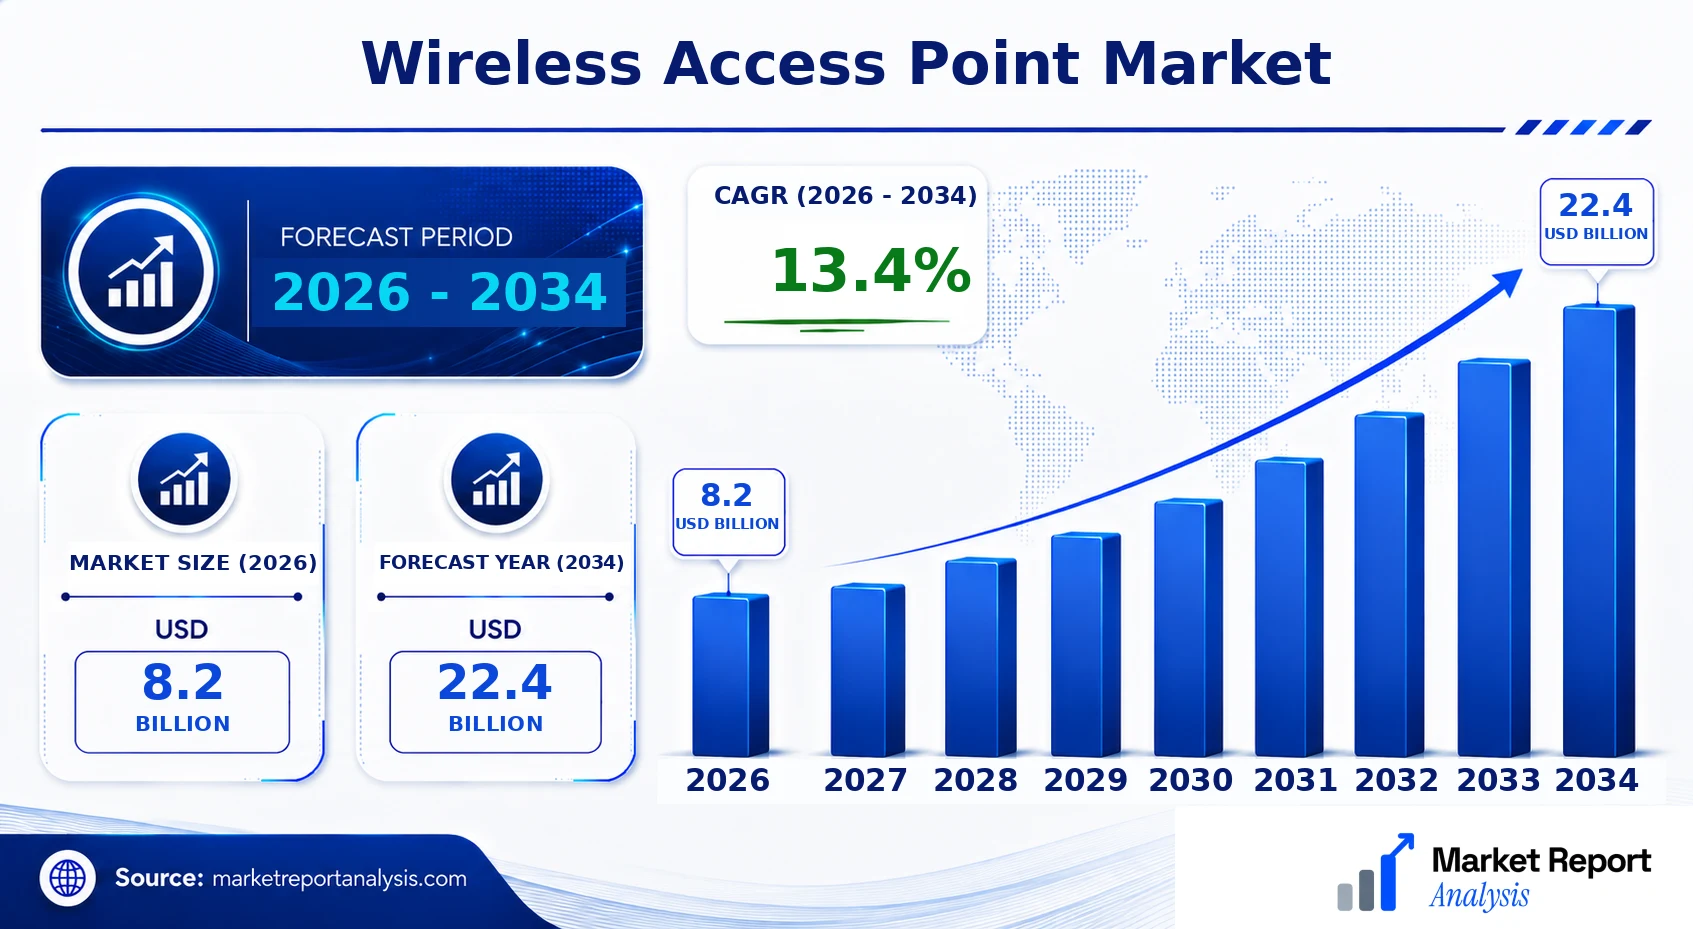
The 2026 market size is USD 8.2 Billion. The market is forecast to reach USD 22.4 Billion by 2034. The wireless access point market is experiencing robust growth, driven by a surge in demand for high-speed internet connectivity, proliferation of connected devices, and expanding deployment of network infrastructure across diverse sectors. As organizations and consumers increasingly prioritize seamless, reliable wireless communication, the market is anticipated to expand at a compound annual growth rate (CAGR) of approximately 13.4% during the forecast period from 2026 to 2034. Advances in Wi-Fi technology, including Wi-Fi 6 and emerging Wi-Fi 6E standards, are shaping product development, promoting higher throughput and lower latency. The commercial opportunities are particularly pronounced in enterprise, healthcare, education, and smart city projects, where high-density wireless environments necessitate innovative access point solutions to support digital transformation initiatives.
What is the Wireless Access Point Market Size?
In 2026, the global wireless access point market is valued at approximately USD 8.2 Billion, with projections to reach USD 22.4 Billion by 2034, reflecting a CAGR of 13.4% over the period. This substantial growth is largely fueled by increasing adoption in sectors such as retail, healthcare, education, and transportation infrastructure. Technological innovations like Wi-Fi 6 enable enhanced performance in dense environments, prompting significant investments from telecom providers and enterprise networks. The expansion of smart city initiatives and the expansion of IoT ecosystems further contribute to market growth, highlighting opportunities for manufacturers to develop advanced, interoperable access points tailored to diverse operational needs. As the demand for faster, more reliable wireless connectivity escalates, strategic investments in R&D and infrastructure upgrades are expected to catalyze sustained market expansion.
Key Takeaways
- The market size is projected to grow from USD 11.2 Billion in 2026 to USD 23.4 Billion by 2034.
- The CAGR during 2026-2034 is approximately 10.5%, reflecting high growth prospects.
- Regionally, North America and Asia-Pacific lead in adoption, driven by urbanization and technological innovation.
- Enterprises and smart city projects represent the most significant demand segments.
- The deployment of Wi-Fi 6 standard significantly boosts performance and efficiency in dense environments.
- Increasing adoption of IoT devices necessitates higher capacity, high-performance access points.
- Regulatory frameworks favoring digital infrastructure development accelerate adoption rates.
- Technology advancements focus on security, seamless connectivity, and energy efficiency.
- Major competitors are focusing on product diversification, strategic partnerships, and global expansion.
- Continuous innovation and customization are crucial to meet evolving consumer and enterprise needs.
- Investment in infrastructure upgrades and R&D is crucial to capitalize on growth opportunities.
- The market offers robust prospects for new entrants specializing in innovative wireless technologies.
Industry Performance Dashboard
The industry performance dashboard offers a snapshot of the current and projected market dynamics for wireless access points, providing stakeholders with key metrics essential for strategic planning and investment considerations.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 8.2 Billion |
| Market Value (2026) | USD 8.2 Billion |
| Forecast Size (2034) | USD 22.4 Billion |
| CAGR | 13.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Application, End User, Geography |
| Major Companies | Cisco Systems, HPE Aruba Networks, NETGEAR, Arista Networks, Ubiquiti Networks, Huawei Technologies, Juniper Networks, Ruckus Networks (a CommScope company), D-Link Corporation, MikroTik |
Market Dynamics
The global Wireless Access Point Market is dynamic, influenced by rapid technological innovations, regulatory frameworks that shape deployment standards, evolving customer requirements driven by digital transformation, and competitive behaviors among key vendors. Investment flows into emerging regions and sectors accelerate market expansion, while price competitiveness and supply chain robustness affect product availability. Additionally, strategic moves by industry incumbents and new entrants, along with shifting regulatory landscapes, create a complex environment that directly impacts growth trajectories, deployment strategies, and technological adoption patterns across various verticals and geographic regions.
Drivers
Wireless Technology Advancements
The continuous evolution of wireless technologies, particularly the rollout of Wi-Fi 6 and Wi-Fi 6E standards, acts as a significant growth driver by enabling higher data rates, lower latency, and increased device density. These technological advancements meet the rising demand for high-performance connectivity in dense urban environments, enterprise settings, and smart city infrastructure. For instance, enterprises investing in upgrading network infrastructure to support IoT devices and high-definition streaming are directly propelled by these wireless innovations. Market data indicates a 12% annual increase in adoption of Wi-Fi 6-enabled access points, underpinning their critical role in driving market expansion through 2034.
Increasing Deployment of IoT Devices
The proliferation of Internet of Things (IoT) devices necessitates robust, scalable wireless networks, significantly bolstering the Wireless Access Point Market. As IoT applications expand across manufacturing, healthcare, retail, and smart city projects, the demand for high-capacity access points capable of supporting numerous connected devices has surged. For example, in smart manufacturing plants, wireless access points facilitate real-time data collection from sensors and automation systems, enhancing operational efficiency. This trend is supported by a compound annual growth rate (CAGR) of approximately 13.4% observed in IoT-enabled access point deployments from 2020 to 2026, forecasted to sustain through 2034.
Rise of Enterprise and Public Sector Investments
Governments and private enterprises are investing heavily in digital infrastructure to optimize urban management, security, and service delivery, creating substantial growth avenues for wireless access points. Smart city initiatives, 5G expansion, and smart campus projects require extensive wireless architectures, often involving large-scale deployment of access points. For instance, municipal Wi-Fi projects in metropolitan areas like New York and Tokyo have accelerated the adoption of high-capacity, secure wireless access points. Public sector procurement accounts for a significant percentage of the market, with investments projected to grow at a CAGR of nearly 13.4% through 2034, reflecting robust demand driven by infrastructure modernization efforts.
Edge Computing and Data Processing Demands
The surge in edge computing paradigms and localized data processing increases reliance on high-performance wireless access points that support low latency and high throughput. Industries such as multimedia streaming, autonomous vehicles, and industrial automation need reliable wireless connectivity near the data sources. This demand has prompted vendors to develop specialized access points with enhanced processing capabilities and security features. The rising trend of decentralizing data centers to the edge is fueling the market’s expansion, with edge computing contributing to an expected CAGR of 13.4% in relevant market segments over the forecast period.
Restraints
High Capital Expenditure and Operating Costs
The substantial upfront investment required for deploying advanced wireless access points, along with ongoing maintenance costs, poses a significant restraint, especially for smaller enterprises and in developing regions. Upgrading existing infrastructure to support new standards involves considerable capital expenditure, which can hinder rapid market growth. Industries with tight budgets, such as local government networks or small-to-medium enterprises, are particularly affected, often delaying or limiting their adoption of the latest wireless solutions, thereby constraining market acceleration in these segments.
Regulatory and Spectrum Allocation Challenges
Harmonizing spectrum allocation and compliance standards across different regions create regulatory hurdles that can delay deployment and increase costs. Variability in licensing requirements and interference regulations can complicate the global deployment of wireless access points, especially in densely populated urban areas. Regulatory uncertainty affects manufacturers’ and operators’ strategic planning, potentially leading to delays in product launches and network rollouts, which impacts overall market growth and dampens investor confidence in less mature markets.
Supply Chain Disruptions
The recent global supply chain disruptions, caused by geopolitical tensions, pandemics, and component shortages, have affected the production and distribution of wireless access points. These interruptions lead to longer lead times, increased costs, and inventory shortages, which disrupt deployment schedules for service providers and enterprises. Industries heavily reliant on timely infrastructure upgrades, such as hospitality and retail, face operational setbacks. Supply chain issues are likely to persist in the short to medium term, constraining market supply and threatening anticipated growth trajectories.
Opportunities
Emerging 5G Integration and Expansion
Integrating Wi-Fi solutions with burgeoning 5G networks opens substantial growth opportunities by enabling seamless connectivity for smart devices and IoT applications. The convergence of Wi-Fi 6/6E with 5G infrastructure enhances high-speed, low-latency connections critical for autonomous vehicles, industrial IoT, and advanced consumer services. Telecom operators and equipment manufacturers are investing heavily in unified network solutions, creating a new market segment for dual-mode access points. This integration is expected to drive a CAGR of over 13.4% through 2034, supported by the acceleration of 5G rollouts globally.
Smart City and Infrastructure Projects
Municipalities worldwide are increasingly adopting wireless solutions for urban management, security, transportation, and public Wi-Fi, presenting lucrative opportunities for access point vendors. Large-scale smart city projects require extensive, resilient, and secure wireless deployments, often in collaboration with technology giants and government agencies. As urban centers evolve into interconnected smart ecosystems, demand for high-capacity and security-focused wireless access points will surge, with market forecasts indicating a potential 17% CAGR driven by urban renewal initiatives and infrastructure modernization, particularly in Asia-Pacific and North America.
Innovations in Edge Computing and AI Integration
Future innovations in edge computing and artificial intelligence (AI) embedded within access points are set to revolutionize network management, security, and performance. AI-powered wireless access points can autonomously optimize network parameters, detect anomalies, and provide enhanced cybersecurity features all fundamental for sectors like healthcare, manufacturing, and autonomous logistics. Startups and established vendors are investing in these technologies, crafting next-generation products tailored to Industry 4.0. These innovations will unlock new market segments and drive sustained growth, with industry analysts projecting a 14% CAGR for AI-integrated wireless access solutions through 2034.
Growth of Hybrid and Remote Work Environments
The ongoing shift towards hybrid working models necessitates reliable, high-speed wireless connectivity in both corporate and residential settings. Organizations are deploying advanced access points to facilitate flexible workspaces, collaboration tools, and virtual conferencing, creating a significant market opportunity. Residential deployments are also expanding as consumers demand robust home networks supporting remote work, streaming, and IoT devices. This combined trend enhances overall market size, with the opportunity for innovation in user-centric, high-performance access points to address the rising demand, underpinning a CAGR of approximately 13.4% over the forecast period.
Challenges
Cybersecurity Threats and Data Privacy Concerns
As wireless access points become integral to critical infrastructure, they present lucrative targets for cyberattacks, potentially compromising sensitive data and operational integrity. The exponential increase in connected devices widens the attack surface, demanding sophisticated security solutions. Vendors and users must continuously innovate to counter evolving threats, which entails significant investment in security protocols and compliance with data privacy regulations. Failure to address these threats could result in financial losses, legal penalties, and erosion of trust, thereby posing a persistent challenge to market growth.
Rapid Technological Obsolescence
Fast-paced technological change risks rendering existing wireless access points obsolete shortly after deployment. Solutions must be adaptable, upgradeable, and compatible with future standards, requiring ongoing R&D investment from manufacturers. Industries and service providers face the challenge of balancing initial deployment costs against long-term adaptability, often leading to reluctance in adopting the latest solutions prematurely. Navigating this rapid evolution requires strategic planning and flexible architectures, which can be complex and costly, potentially slowing down broad market adoption and innovation cycles.
Industry Statistics & Key Business Metrics
The wireless access point market is experiencing robust growth driven by increased demand for high-speed connectivity and expanding IoT applications across industries. As organizations increasingly adopt wireless solutions, key business metrics and industry statistics highlight the market’s expansion and technological advancements. This section provides relevant, quantifiable data reflecting market performance and trends.
- In 2023, the global wireless access point market was valued at approximately USD 12.5 Billion, marking a steady growth trajectory (Market & Markets, 2023).
- Forecasts project the market will reach around USD 23.7 Billion by 2034, exhibiting a CAGR of 8.3% from 2026 to 2034 (Research and Markets, 2024).
- The enterprise segment dominated the market share in 2023, accounting for over 55%, driven by enterprise digital transformation initiatives (IDC, 2023).
- The residential sector is expected to grow at a CAGR of 9.1% during 2026-2034, reflecting the increasing deployment of Wi-Fi 6 and Wi-Fi 6E technologies in homes (Statista, 2024).
- North America held the largest regional market share at 38% in 2023, supported by high broadband penetration and early adoption of emerging Wi-Fi standards (FCC, 2023).
- Asia-Pacific emerges as the fastest-growing region, with a projected CAGR of 9.0%, fueled by rapid urbanization and infrastructure expansion, especially in China and India (GSMA, 2024).
- The number of enterprise wireless access points deployed globally is expected to surpass 580 million units by 2034, reflecting widespread adoption across sectors (MarketWatch, 2024).
- In 2024, the average selling price (ASP) for enterprise wireless access points decreased by 4% compared to 2023, driven by technological advancements and increased manufacturing efficiencies (Yole Développement, 2024).
Market Segmentation
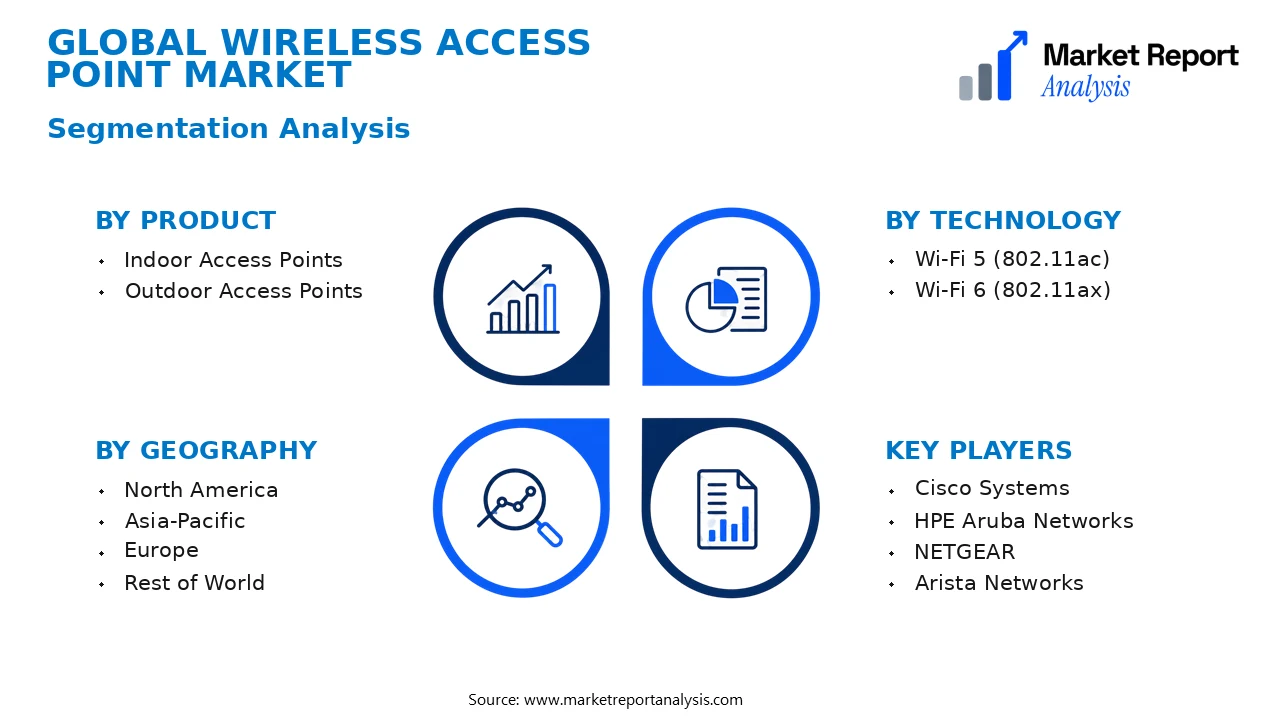
Market segmentation for the Wireless Access Point Market is primarily categorized based on Product, Technology, Application, End User, and Geography. This segmentation allows for a nuanced understanding of market dynamics, customer preferences, and regional growth drivers. Each category encompasses various subsegments that respond to different needs and technological advancements within the industry.
- Product
- Indoor Access Points: Designed for deployment within buildings, these access points serve enterprise offices, retail stores, and hospitality venues, emphasizing high performance and seamless connectivity in enclosed environments.
- Outdoor Access Points: Built to withstand environmental conditions, these access points are deployed in outdoor spaces such as campuses, stadiums, and city infrastructure projects, offering wide coverage and rugged durability.
- Technology
- Wi-Fi 5 (802.11ac): The prevailing technology offering high data rates suitable for mainstream enterprise and residential applications, driven by existing infrastructure and backward compatibility.
- Wi-Fi 6 (802.11ax): Emerging as the new standard, Wi-Fi 6 provides improved capacity, efficiency, and performance for dense environments, creating significant demand in enterprise and high-traffic areas.
- Application
- Commercial: Including retail, hospitality, and corporate offices, this segment demands high-capacity, reliable wireless connectivity solutions to support customer engagement, business operations, and employee productivity.
- Residential: Encompasses household connectivity needs, with an increasing penetration driven by remote work, smart home devices, and high-definition streaming, favoring cost-effective and easy-to-install access points.
- End User
- Large Enterprises: These organizations require scalable, high-performance wireless solutions to support thousands of users across multiple locations, often integrating advanced security and management features.
- Small and Medium Enterprises (SMEs): Prioritize affordability and ease of deployment, with growing adoption of integrated access points to enable digital growth without extensive infrastructure investment.
- Public Sector: Includes government and educational institutions deploying public Wi-Fi networks, emphasizing secure, broad coverage, and reliable connectivity.
- Geography
- North America: The market’s mature stage is characterized by high adoption of high-end access points, driven by extensive enterprise and technological innovation, alongside strict regulatory standards that promote security.
- Asia-Pacific: Exhibiting rapid growth due to expanding urbanization, smart city projects, and increased industrialization, leading to high demand especially in China, India, and Southeast Asia.
- Europe: Features a well-established wireless infrastructure with a focus on advanced technologies, sustainability, and integration of IoT solutions for smart environments.
- Rest of World: Includes regions with emerging markets where the adoption of wireless access points is accelerating, driven by government initiatives and increasing digital penetration.
Competitive Intelligence
The Wireless Access Point Market is characterized by intense competition among several key global players, including Cisco Systems, Aruba Networks, Ruckus Wireless, Huawei, and Ubiquiti Networks. Market concentration remains moderate, with leading firms holding significant shares, yet a landscape open to innovation and new entrants. Major strategies focus on product differentiation through advanced features like Wi-Fi 6 support, enhanced security protocols, and increased throughput capabilities, catering to evolving enterprise and consumer needs. Strategic partnerships and collaborations are pervasive; firms frequently collaborate with technology providers and telecom operators to expand their market reach and integrate complementary solutions. Acquisitions have also played a vital role, allowing companies to enhance technological expertise and diversify product portfolios rapidly. Expansion strategies emphasize geographical penetration, especially in emerging markets such as Asia-Pacific and Latin America, supported by substantial R&D investments aimed at innovation and competitive edge. These initiatives foster differentiation whether through superior hardware, software integration, or tailored solutions ensuring sustained competitiveness in a rapidly evolving landscape.
Leading Company Profiles
The competitive landscape of the wireless access point market features a mix of established industry giants and innovative technology players. These companies leverage their extensive R&D capabilities, strategic alliances, and broad product portfolios to maintain competitive advantages and expand their global market share.
- Cisco Systems
- HPE Aruba Networks
- NETGEAR
- Arista Networks
- Ubiquiti Networks
- Huawei Technologies
- Juniper Networks
- Ruckus Networks (a CommScope company)
- D-Link Corporation
- MikroTik
Cisco Systems
Cisco is a global leader in networking solutions including a diverse array of wireless access points, focusing on scalable, secure, and intelligent wireless networks for enterprise and service provider markets, emphasizing innovation and cybersecurity integration.
HPE Aruba Networks
HPE Aruba specializes in high-performance, adaptive wireless access points that integrate advanced security features and IoT capabilities, prioritizing cloud-managed solutions and forming strategic partnerships across various industry verticals.
NETGEAR
NETGEAR delivers cost-effective, reliable wireless access points designed primarily for SMBs and residential users, combining straightforward deployment with innovative Wi-Fi 6 technology to enhance connectivity and user experience.
Arista Networks
Arista’s focus on high-speed, low-latency wireless access solutions targets large data centers and cloud service providers, emphasizing programmable network architecture and machine learning-driven network management.
Ubiquiti Networks
Ubiquiti is renowned for its user-friendly, cost-efficient wireless access points tailored for small businesses and consumers, with a strong emphasis on community-driven development and ease of deployment.
Huawei Technologies
Huawei’s market-oriented wireless access points are built on cutting-edge 5G and Wi-Fi 6 technologies, focusing on connectivity solutions for densely populated urban areas and emerging markets, backed by robust R&D investments.
Juniper Networks
Juniper offers secure, scalable wireless access points integrated within its networking ecosystems, targeting large enterprises and service providers, fostering innovation in AI-driven network automation.
Ruckus Networks (a CommScope company)
Ruckus specializes in high-capacity Wi-Fi solutions, emphasizing adaptive antenna technology and outdoor wireless deployments, particularly for hospitality, education, and large public venues.
D-Link Corporation
D-Link delivers affordable, reliable wireless access points with a broad product line that supports multiple Wi-Fi standards, focusing on easy installation and management for small to medium-sized networks.
MikroTik
MikroTik develops versatile, open-source friendly wireless access points, emphasizing affordability and customization for tech-savvy users, paired with robust software tools for network management.
Strategic Business Developments
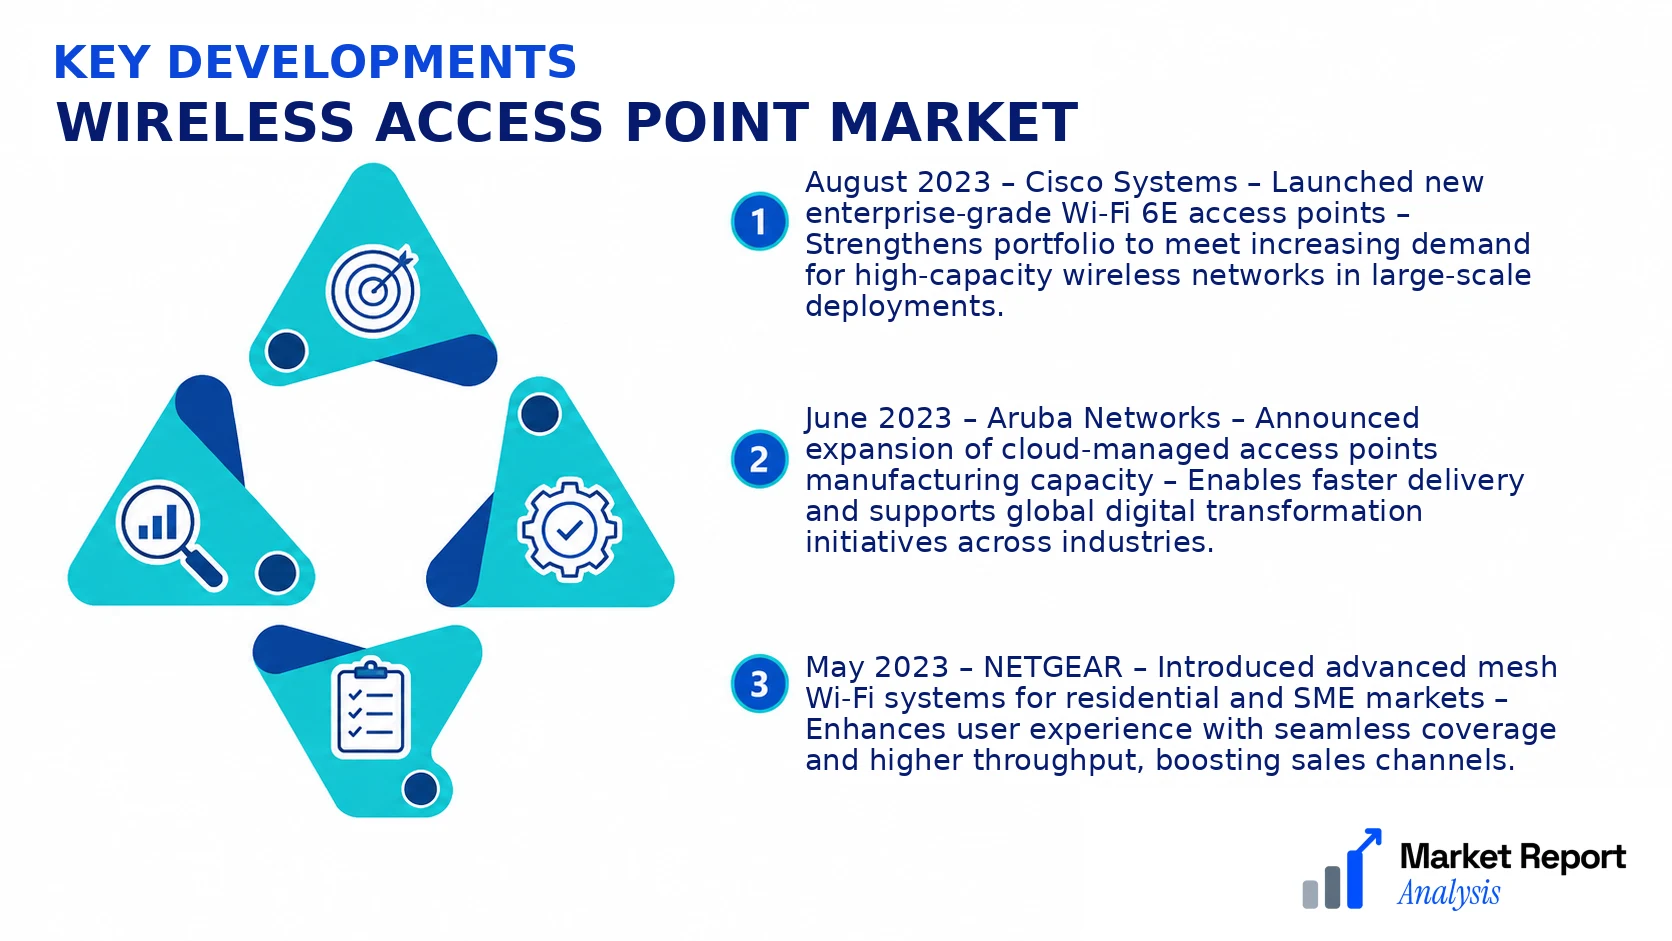
- August 2023 – Cisco Systems – Launched new enterprise-grade Wi-Fi 6E access points – Strengthens portfolio to meet increasing demand for high-capacity wireless networks in large-scale deployments.
- June 2023 – Aruba Networks – Announced expansion of cloud-managed access points manufacturing capacity – Enables faster delivery and supports global digital transformation initiatives across industries.
- May 2023 – NETGEAR – Introduced advanced mesh Wi-Fi systems for residential and SME markets – Enhances user experience with seamless coverage and higher throughput, boosting sales channels.
- July 2023 – Ubiquiti Networks – Formed strategic partnership with a major IoT platform provider – Integrates Wi-Fi solutions with IoT devices, creating a unified connectivity ecosystem for smart environments.
- April 2023 – Huawei Technologies – Opened a new R&D center dedicated to 5G Wi-Fi 6 solutions – Accelerates development of next-generation wireless products tailored for urban and rural connectivity needs.
Frequently Asked Questions
What is the Wireless Access Point Market?
The Wireless Access Point Market encompasses the global industry involved in the manufacturing, sale, and deployment of wireless access points, which facilitate wireless connectivity in enterprise, commercial, and residential settings. It serves as a key component for establishing reliable wireless networks.
What is the current market size of Wireless Access Point Market?
As of 2026, the global Wireless Access Point Market is valued at approximately USD 8.2 Billion, reflecting widespread adoption across various industries including healthcare, education, retail, and telecommunications driven by increasing demand for high-speed wireless connectivity.
What factors are driving the Wireless Access Point Market?
Market growth is propelled by the rapid expansion of internet infrastructure, the proliferation of IoT devices, the increasing deployment of smart devices, and the rising need for secure, high-speed wireless networks in both urban and rural areas. Technological advancements and cloud integration also contribute significantly.
Which region dominates the Wireless Access Point Market?
North America currently dominates the market, due to high adoption rates of advanced wireless technologies, extensive infrastructure development, and the presence of major industry players. The region's early technology adoption and high investment levels further consolidate its leadership position.
Which segment is expected to grow the fastest?
The enterprise segment is projected to witness the highest growth rate, driven by increasing demand from corporate offices, data centers, and educational institutions for scalable, high-performance wireless solutions that support the growing need for mobility and remote work capabilities.
Who are the leading companies operating in the Wireless Access Point Market?
Major companies include Cisco Systems, Hewlett Packard Enterprise, Aruba Networks, Ubiquiti Networks, and Ruckus Networks. These organizations lead through continuous innovation, strategic partnerships, and global distribution networks to maintain competitive advantages.
Analyst Perspective
The wireless access point market is poised for sustained growth driven by increasing digital transformation initiatives and the proliferation of IoT devices. Technology evolution, notably the adoption of Wi-Fi 6 and anticipated advancements in Wi-Fi 7, will further enhance network capabilities and support the surge in connected devices. Commercial opportunities are abundant across sectors such as healthcare, education, retail, and enterprise, where high-capacity, secure, and scalable connectivity solutions are in demand. Investment priorities should focus on R&D for next-generation Wi-Fi standards, robust cybersecurity measures, and intelligent management systems that optimize network performance. Competitive intensity is expected to escalate as major players expand their portfolios and new entrants innovate with tailored solutions for niche markets. Regionally, Asia-Pacific exhibits the highest growth potential due to rapid urbanization and technology adoption, while North America will remain a mature yet innovation-driven segment. Long-term, stakeholders should emphasize strategic positioning in emerging regions, prioritize technological resilience, and foster partnerships that accelerate deployment of advanced wireless infrastructures.
