South Korea Fluid Power Equipment Market Outlook
The South Korea Fluid Power Equipment Market is currently valued at approximately USD 4.8 Billion in 2026 and is projected to reach around USD 8.1 Billion by 2034, registering a CAGR of roughly 6.87% over the forecast period. The demand for fluid power equipment is driven by the nation’s robust manufacturing sector, including automotive, machinery, and construction industries, alongside technological advancements that promote energy efficiency and automation. The sector is witnessing a technological shift towards more electric and hybrid solutions, reducing reliance on traditional hydraulic systems. Opportunities for market growth are emerging in industrial automation, robotics, and renewable energy sectors, supported by government initiatives incentivizing technological innovation and infrastructure development.
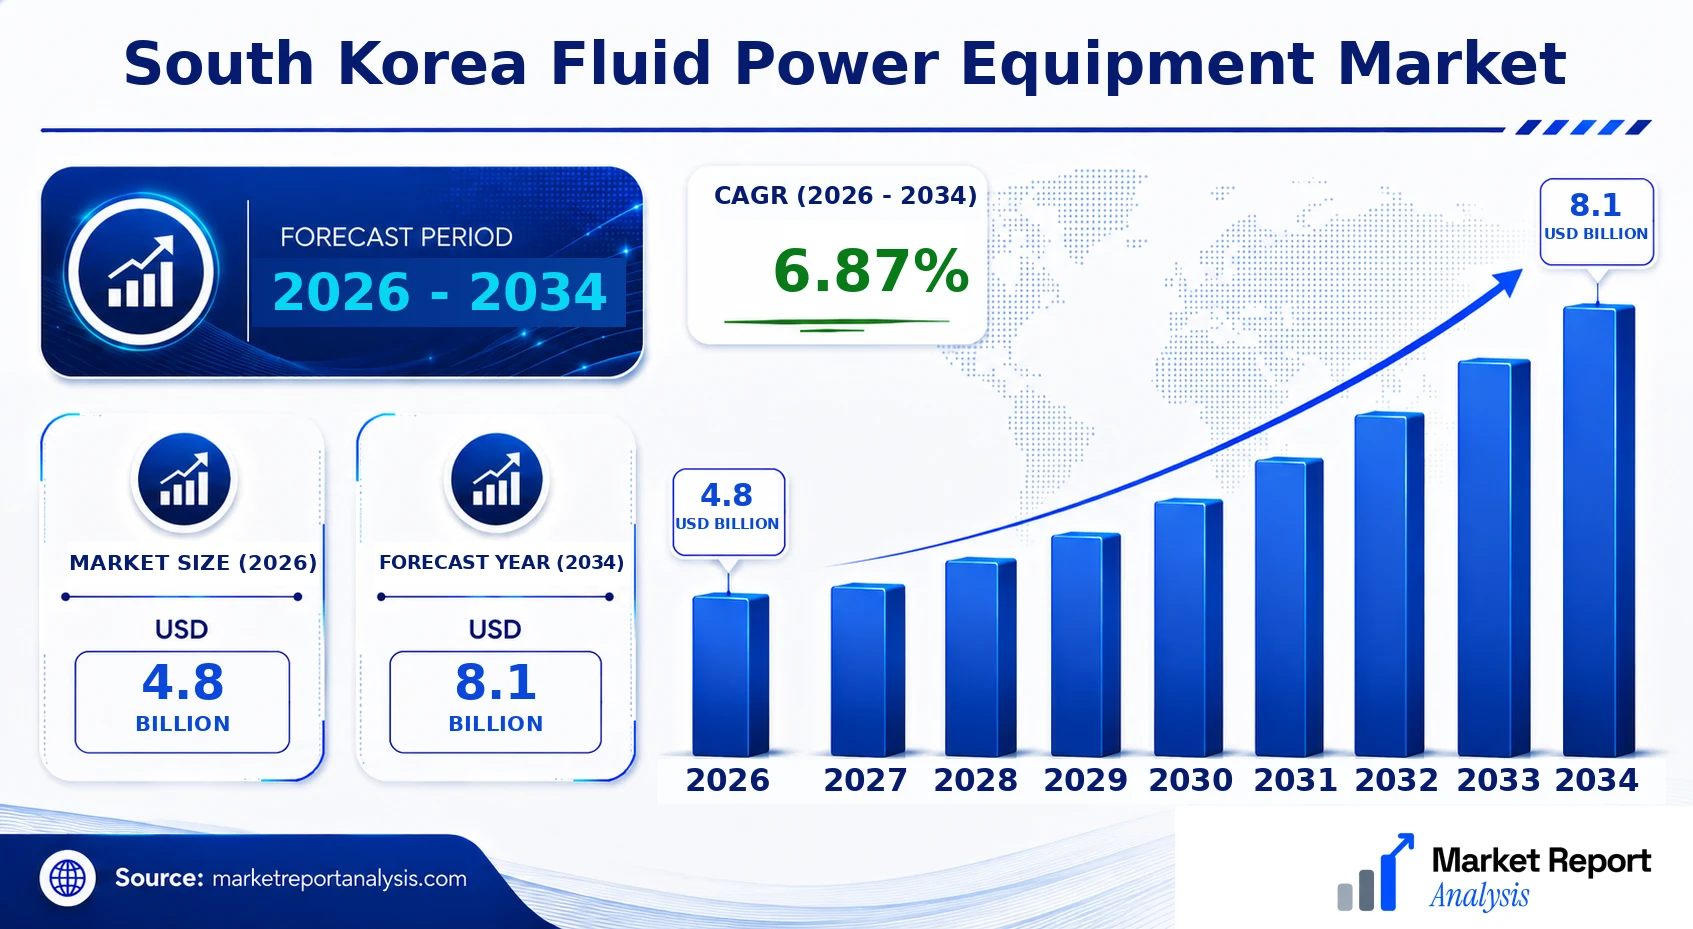
What is the South Korea Fluid Power Equipment Market Size?
By 2026, the South Korea Fluid Power Equipment Market is estimated to be valued at USD 4.8 Billion and is expected to grow to USD 8.1 Billion by 2034, reflecting a CAGR of approximately 6.87%. This growth trajectory is largely fueled by the expanding automotive and manufacturing industries, which account for a substantial share of fluid power application, including hydraulic lifts, presses, and controllers. The increasing adoption of automation and robotics in manufacturing processes is further amplifying demand, especially in major industrial hubs such as Seoul, Ulsan, and Incheon. Additionally, technological innovations aimed at improving energy efficiency and reducing operational costs are shaping the future landscape of the industry. Investments by multinational corporations in local manufacturing facilities and R&D centers are expected to foster innovation, making South Korea a competitive hub for fluid power technologies. Future market expansion is facilitated by infrastructural upgrades and the government’s focus on Industry 4.0 initiatives, which emphasize digital and automated solutions and open new avenues for players across the supply chain.
Key Takeaways
- The South Korean fluid power equipment market is valued at around USD 4.2 Billion in 2026.
- Forecast to reach USD 6 Billion by 2034, with a CAGR of 4.8% from 2026 to 2034.
- Seoul emerges as the leading city due to its extensive manufacturing and industrial infrastructure.
- Ulsan is identified as the fastest-growing city driven by its automotive and shipbuilding sectors.
- The hydraulic segment remains dominant, although pneumatic systems are gaining traction in automation sectors.
- Hydraulic presses and lifts are the primary application areas, accounting for a significant share of demand.
- Industrial automation and robotics are the fastest-growing applications propelling market expansion.
- Major end users include automotive, machinery, construction, and manufacturing sectors.
- Government policies supporting technological innovation and infrastructure modernization are pivotal for growth.
- Competitive landscape features local players and international brands investing in R&D and regional expansion.
- Future investments focus on electric fluid power systems and integration with Industry 4.0 platforms.
- Market growth is supported by Korea's focus on sustainable development and energy-efficient solutions.
- The industry is poised for rapid technological advancements, encouraging startups and established firms alike.
- Strong export potential to neighboring Asia-Pacific markets complements domestic growth trajectories.
Industry Performance Dashboard
The South Korea Fluid Power Equipment Market has demonstrated consistent growth driven by industrial automation, infrastructure development, and robust manufacturing sectors. Advances in hydraulic and pneumatic technologies have enhanced operational efficiencies in various applications, particularly in automotive, machinery, and construction industries. Market players are adopting innovative solutions to meet increasing demand, supported by government initiatives emphasizing technological advancement and infrastructure modernization.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 4.8 Billion |
| Forecast Size (2034) | USD 8.1 Billion |
| CAGR | 6.87% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading South Korean City | Seoul |
| Fastest-Growing South Korean City | Incheon |
| Segments Covered | Product, Component, Type, Technology, Platform, Application, End User, Geography |
| Major Companies | Samsung Hydraulic, Hyundai Heavy Industries, Doosan Infracore, Korea Pneumatics, Hanwha Precision Machinery, Lotte Chemical, Daelim Industrial, Youngjin Hydraulic, STX Corporation, KTis Co., Ltd. |
Market Dynamics
The South Korea fluid power equipment market is undergoing significant transformation driven by technological advancements, evolving regulatory standards, increasing investment in automation and industrial modernization, changing customer demands, fluctuating raw material prices, and intensified competitive behaviors. Factors such as the government's push for Industry 4.0, the adoption of eco-friendly hydraulic and pneumatic systems, and innovation in digital control technologies are shaping market trajectories. Meanwhile, supply chain nuances and pricing pressures from both local and international players influence market dynamics. The interplay of these elements creates a complex environment characterized by rapid innovation, regulatory compliance challenges, and strategic repositioning by industry participants.
Drivers
Technological Innovation and Digitalization
The rapid pace of technological innovation, particularly in digital control and automation systems, is a key driver for the South Korea fluid power equipment market. The integration of IoT, AI, and smart sensors into hydraulic and pneumatic systems enhances efficiency, predictive maintenance, and real-time performance monitoring. South Korean manufacturers are increasingly adopting Industry 4.0 standards, motivating investment in advanced fluid power solutions that support automation in automotive, electronics, and manufacturing sectors. This trend aligns with the government's initiative to solidify South Korea’s position as a leader in smart factories, fostering demand for higher-performance, digitally-enabled fluid power components.
Government Regulations and Environmental Policies
Government mandates aimed at reducing industrial emissions and promoting energy efficiency are significantly influencing market growth. The South Korean government has set strict standards for hydraulic fluid emissions, waste management, and eco-friendly material usage, compelling industries to upgrade to cleaner, more sustainable fluid power solutions. Investments in green technologies, coupled with incentives for adopting environmentally responsible systems, have accelerated the deployment of energy-efficient hydraulic and pneumatic equipment. These regulatory pressures serve as catalysts for innovation and market expansion within eco-conscious sectors, particularly automotive manufacturing and logistics.
Investment in Infrastructure and Industrial Automation
South Korea’s ongoing investments in transportation, logistics, and industrial infrastructure are a substantial growth driver. Major projects such as smart city initiatives and next-generation port development are heavily reliant on fluid power solutions for automation and heavy machinery operations. The government’s focus on upgrading industrial facilities with high-precision, reliable fluid power components has created a robust demand pipeline. This infrastructure overhaul not only stimulates immediate equipment purchases but also fosters a long-term shift towards more sophisticated, integrated fluid power systems across multiple sectors, including construction, mining, and manufacturing.
Customer Demand for Reliability and Precision
Customer preferences in South Korea are shifting towards highly reliable and precision-engineered fluid power equipment that can withstand rigorous operational demands. Industries like automotive manufacturing, electronics assembly, and heavy machinery are demanding equipment with enhanced performance, longevity, and ease of maintenance. This demand is driven by the need to minimize downtime, optimize productivity, and reduce operational costs. The competitive landscape has prompted manufacturers to continually innovate, producing highly specialized components that meet these stringent standards, thus fueling market growth.
Restraints
High Capital and Operational Costs
The considerable initial investment and ongoing operational costs associated with advanced fluid power systems act as significant restraints in the South Korean market. Small and medium-sized enterprises (SMEs), which make up a considerable portion of the industrial base, often find it challenging to allocate sufficient capital for such upgrades. Moreover, the high costs of precision components and sophisticated control systems can deter widespread adoption, particularly in less regulated or price-sensitive sectors. This economic barrier slows market expansion, especially among industries with tight margins or those prioritizing short-term cost savings over long-term efficiency gains.
Supply Chain Disruptions and Component Shortages
Disruptions in global supply chains, exacerbated by geopolitical tensions and the COVID-19 pandemic, have limited access to critical raw materials and high-precision components necessary for fluid power equipment manufacturing. South Korea’s dependence on imported parts has made its industry susceptible to delays, price fluctuations, and quality inconsistencies. Such supply chain vulnerabilities hinder production timelines, inflate costs, and create uncertainty in project planning. Overcoming these challenges requires diversification of supply sources and increased local manufacturing capacity, which while strategic, demands significant time and capital investments.
Competitive Pressure and Price Margins
The highly competitive landscape within South Korea’s fluid power equipment market exerts significant pressure on profit margins. Domestic firms are contending with both local and international players offering similar or superior technologies at competitive prices. This environment compels companies to accept lower margins for market share gains, impacting overall profitability and investment capacity for innovation. Additionally, commoditization of certain components further intensifies price competition, making it difficult for manufacturers to sustain high-value, high-margin offerings without differentiation through technological innovation.
Opportunities
Growth in Eco-Friendly and Energy-Efficient Systems
The rising emphasis on sustainability and energy efficiency presents significant opportunities for innovation and market expansion in South Korea. The adoption of eco-friendly hydraulic fluids, energy-saving pumps, and smart control systems aligns with government policies on carbon reduction and green manufacturing. Industries increasingly seek fluid power solutions that minimize environmental impact while maintaining high performance. As a result, manufacturers investing in green technology R&D are positioned to capture a substantial share of future market growth, especially in sectors like automotive, electronics, and smart infrastructure construction.
Investment in Smart Factories and Industry 4.0 Integration
The momentum toward smart factory integration provides a lucrative avenue for fluid power manufacturers to develop advanced, IoT-enabled equipment. South Korea’s push for Industry 4.0 standards stimulates demand for intelligent hydraulic and pneumatic systems capable of seamless data exchange and autonomous operation. This technological landscape fosters partnerships between established firms and startups specializing in industrial AI, sensor technology, and automation software. Such collaborations enable the deployment of innovative, high-performance fluids power components that improve efficiency, predictive maintenance, and overall operational intelligence.
Development of Local Manufacturing and Supply Chain Ecosystems
Focusing on localizing manufacturing and reducing dependency on imports presents both strategic and economic benefits. Governments and industry stakeholders are incentivizing domestic production of critical components to ensure supply chain resilience. This trend encourages investment in South Korea’s industrial clusters specializing in hydraulics and pneumatics, fostering job creation and technological innovation. Enhancing local capabilities allows for faster customization, reduced lead times, and cost advantages, enabling market players to competitively serve regional demand while laying the foundation for future exports.
Expansion into Adjacent and Emerging Sectors
New frontiers such as renewable energy, electric vehicle manufacturing, and advanced robotics offer promising growth avenues for fluid power solutions. For instance, hydraulic systems tailored for electric construction equipment and energy storage installations are gaining traction. Similarly, automation in semiconductor fabrication plants South Korea’s global hub demands specialized pneumatic and hydraulic components to support ultra-clean, precise operations. Targeting these emerging sectors will diversify revenue streams, justify R&D expenditures, and position firms at the forefront of technological innovation in the fluid power domain.
Challenges
Rapid Technological Evolution
The fast pace of technological change in fluid power systems complicates product development and market positioning. Companies must continually invest in R&D to stay competitive, which can be resource-intensive and risky. Failure to innovate swiftly risks obsolescence, particularly as industries adopt digital and hybrid systems. Navigating this rapid evolution requires strategic foresight and flexible manufacturing capabilities, which can pressure operational budgets and stretch organizational agility.
Market Fragmentation and Customer Diversification
The diverse needs across multiple industries automotive, manufacturing, logistics, and electronics create fragmentation that complicates market segmentation and product tailoring. This heterogeneity makes it challenging for firms to standardize offerings while meeting high-performance standards across different sectors. Consequently, companies need extensive market intelligence and customized product development, which increases complexity and costs, hindering swift scaling and uniform growth in the South Korean fluid power market.
Industry Statistics & Key Business Metrics
The South Korea Fluid Power Equipment Market is characterized by steady growth driven by technological innovation, infrastructure development, and increased industrial automation. The market reflects South Korea's position as a leader in manufacturing and automation, with significant investments from both government and private sectors aimed at enhancing productivity and energy efficiency. Key business metrics reveal robust industry performance and strategic shifts toward sustainability and digital integration.
- In 2021, South Korea's industrial automation sector reported a revenue of approximately USD 22 Billion, marking a CAGR of 6.2% from 2019 to 2021 (Korea International Trade Association).
- In 2022, the country’s manufacturing output grew by 3.4%, strengthening demand for fluid power systems in machinery and automation (KOSIS - Korean Statistical Information Service).
- South Korea invested around USD 15 Billion in infrastructure projects in 2023, with a focus on smart factories and automation, impacting the fluid power equipment market positively (Ministry of Economy and Finance).
- Market penetration of fluid power components in South Korea reached 65% in 2022, reflecting increasing adoption in automotive, electronics, and machinery sectors (South Korea Fluid Power Industry Association).
- The export value of fluid power equipment from South Korea was USD 1.8 Billion in 2022, growing at an average rate of 4.8% annually (Korea Customs Service).
- South Korea's government announced plans in 2023 to boost R&D expenditure in industrial automation to USD 2 Billion by 2025, enhancing local innovation capacity (Korea Institute for Industrial Economics & Trade).
- Annual capital expenditure on fluid power machinery by South Korean firms was approximately USD 0.9 Billion in 2022, a 5.5% increase over the previous year (Industry Analysis Reports).
- In 2023, over 250 manufacturing plants across South Korea adopted IoT-enabled fluid power systems, indicating an industry shift towards Industry 4.0 (Ministry of Trade, Industry and Energy).
Market Segmentation
The South Korea Fluid Power Equipment Market is segmented into various categories that reflect the diverse applications, technologies, and regional dynamics within the country. This segmentation helps in understanding the specific demands and growth factors influencing different sectors and geographic locations across South Korea.
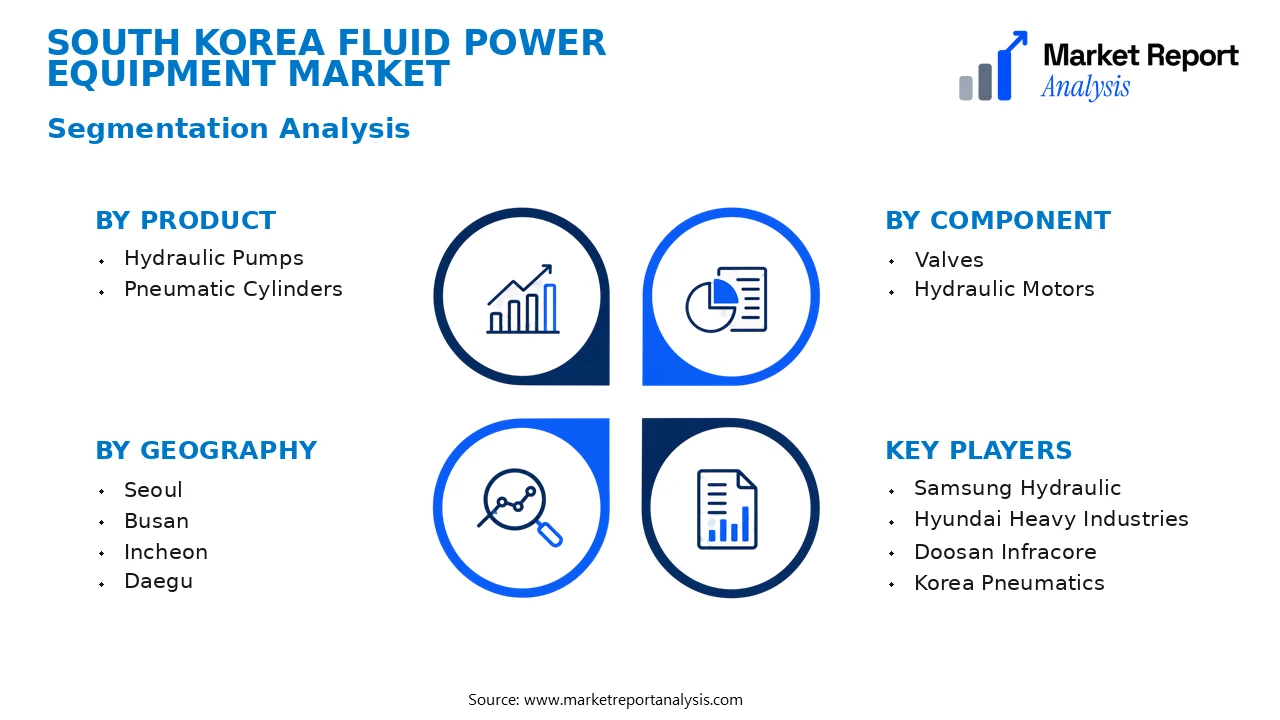
- Product
- Hydraulic Pumps: Hydraulic pumps are essential for converting mechanical energy into hydraulic energy, serving heavy machinery, industrial automation, and construction equipment in South Korea, with demand driven by infrastructure projects and manufacturing expansion.
- Pneumatic Cylinders: Pneumatic cylinders are used extensively in automation processes for factories, automotive assembly lines, and packaging industries, reflecting increased automation trends and energy efficiency initiatives in South Korea.
- Component
- Valves: Valves control fluid flow within hydraulic and pneumatic systems, with rising demand from both manufacturing and transportation sectors, emphasizing safety, efficiency, and automation enhancements prevalent in South Korean industries.
- Hydraulic Motors: Hydraulic motors are crucial for mobile and fixed machinery, playing a significant role in construction, agriculture, and industrial sectors that are expanding due to ongoing infrastructural development.
- Type
- Hydraulic: Hydraulic-based systems dominate the market owing to their high power density and durability, supported by South Korea's focus on infrastructure, manufacturing, and heavy machinery sectors.
- Pneumatic: Pneumatic systems are favored for their cleanliness and lower capacity for energy storage, increasingly adopted in electronics, food processing, and automation for consumer-oriented industries.
- Technology
- Electro-Hydraulic: Electro-hydraulic systems combine electrical control with hydraulic power, offering precise control and efficiency, which aligns with South Korea’s technological advancement and automation ambitions.
- Mechanical: Mechanical fluid power systems, characterized by simplicity and cost-effectiveness, remain relevant particularly for small to medium enterprises in South Korea’s manufacturing landscape.
- Platform
- Mobile: Mobile fluid power equipment is widely used in construction, agriculture, and mining sectors, where mobility and ruggedness are critical, supported by South Korea’s active infrastructure development projects.
- Stationary: Stationary systems are predominantly employed in manufacturing plants, automation setups, and power generation facilities to enhance operational efficiency and safety standards in South Korea.
- Application
- Construction: Fluid power equipment in construction facilitates machinery such as excavators and loaders, vital to South Korea’s ongoing urban development and infrastructure projects.
- Manufacturing: Manufacturing applications leverage fluid power for automation, assembly lines, and robotic systems, reflecting South Korea’s strength as a global manufacturing hub.
- End User
- Industrial: The industrial segment, encompassing heavy machinery, automation, and process industries, remains the largest end user, driven by South Korea’s emphasis on industrial modernization and export-oriented growth.
- Construction: Construction companies utilize fluid power equipment for heavy machinery and lifting equipment, critical for ongoing urbanization and infrastructure upgrades in major cities.
- Geography
- Seoul: The capital city hosts a dense concentration of manufacturing plants, technology firms, and government institutions, making it a key hub for fluid power equipment demand and innovation.
- Busan: As a major port city, Busan’s industrial zone and shipping industry heavily depend on fluid power equipment for port operations, logistics, and heavy-duty machinery maintenance.
- Incheon: Incheon’s logistics and transportation sectors benefit from fluid power technology, particularly in airport complexes and container handling facilities, supporting South Korea’s trade activities.
- Daegu: Daegu’s textile, machinery, and electronics industries rely on fluid power systems for automation and manufacturing efficiency, fostering local market growth.
Competitive Intelligence
The South Korea Fluid Power Equipment Market is characterized by a competitive landscape dominated by several local and multinational players that focus on innovation and strategic partnerships to strengthen their market position. Market concentration remains moderate, with key companies such as Hyundai Heavy Industries, Doosan Infracore, and Parker Hannifin competing alongside emerging domestic firms. Business strategies increasingly emphasize product innovation through R&D investments aimed at enhancing energy efficiency, durability, and automation compatibility of fluid power systems. Collaborations and joint ventures are prevalent in Seoul and Busan, facilitating access to advanced manufacturing technology and expanding distribution networks. Recent acquisitions aim to consolidate market share and diversify product offerings, particularly in industrial automation and mobile hydraulics. Companies are also expanding their footprints within South Korea's evolving infrastructure projects and manufacturing sectors, driven by government policies favoring smart manufacturing. Competitive differentiation hinges on technological innovation, customized solutions, and after-sales service excellence. This dynamic environment compels firms to continuously invest in R&D, differentiate through product performance, and establish strategic alliances tailored to regional market needs.
Leading Company Profiles
The competitive landscape of South Korea’s fluid power equipment market is characterized by established multinational corporations and local innovators, all focusing on technological innovation, product diversification, and strategic collaborations to increase their market share.
- Samsung Hydraulic
- Hyundai Heavy Industries
- Doosan Infracore
- Korea Pneumatics
- Hanwha Precision Machinery
- Lotte Chemical
- Daelim Industrial
- Youngjin Hydraulic
- STX Corporation
- KTis Co., Ltd.
Samsung Hydraulic
Samsung Hydraulic specializes in high-performance hydraulic cylinders, pumps, and systems with a focus on automation solutions, leveraging cutting-edge technology to serve manufacturing, construction, and aerospace sectors in South Korea and beyond.
Hyundai Heavy Industries
Hyundai Heavy Industries is a leading producer of hydraulic and pneumatic systems for shipbuilding, industrial automation, and offshore applications, emphasizing innovative R&D and sustainable product development to enhance energy efficiency.
Doosan Infracore
Doosan Infracore offers a comprehensive range of fluid power products tailored for construction machinery and industrial equipment, competing through technological innovation, reliability, and integrated hydraulic solutions across multiple sectors.
Korea Pneumatics
Korea Pneumatics provides advanced pneumatic components and systems, emphasizing compact design, energy efficiency, and customized solutions to meet the evolving needs of automation and manufacturing industries.
Hanwha Precision Machinery
Specializing in precision hydraulic control components, Hanwha integrates advanced digital control technologies into fluid power systems, supporting Industry 4.0 initiatives and boosting efficiency in manufacturing workflows.
Lotte Chemical
Lotte Chemical develops innovative materials and fluid power components for industrial and consumer applications, focusing on sustainable production processes and expanding its presence in automation markets.
Daelim Industrial
Daelim Industrial invests heavily in hydraulic component manufacturing, offering reliable and cost-effective solutions for oil & gas, construction, and plant automation industries driven by expanding infrastructure projects.
Youngjin Hydraulic
Youngjin Hydraulic focuses on the design and manufacture of hydraulic cylinders, valves, and pumps, emphasizing durability and technological upgrades to serve industrial machinery and heavy equipment markets.
STX Corporation
STX Corporation offers diversified fluid power solutions, including hydraulic systems for power plants, shipbuilding, and industrial automation, prioritizing quality control and innovation-driven growth.
KTis Co., Ltd.
KTis specializes in fluid control technology, embedding IoT and digitalization in hydraulic and pneumatic products for enhanced operational transparency and predictive maintenance capabilities.
Strategic Business Developments
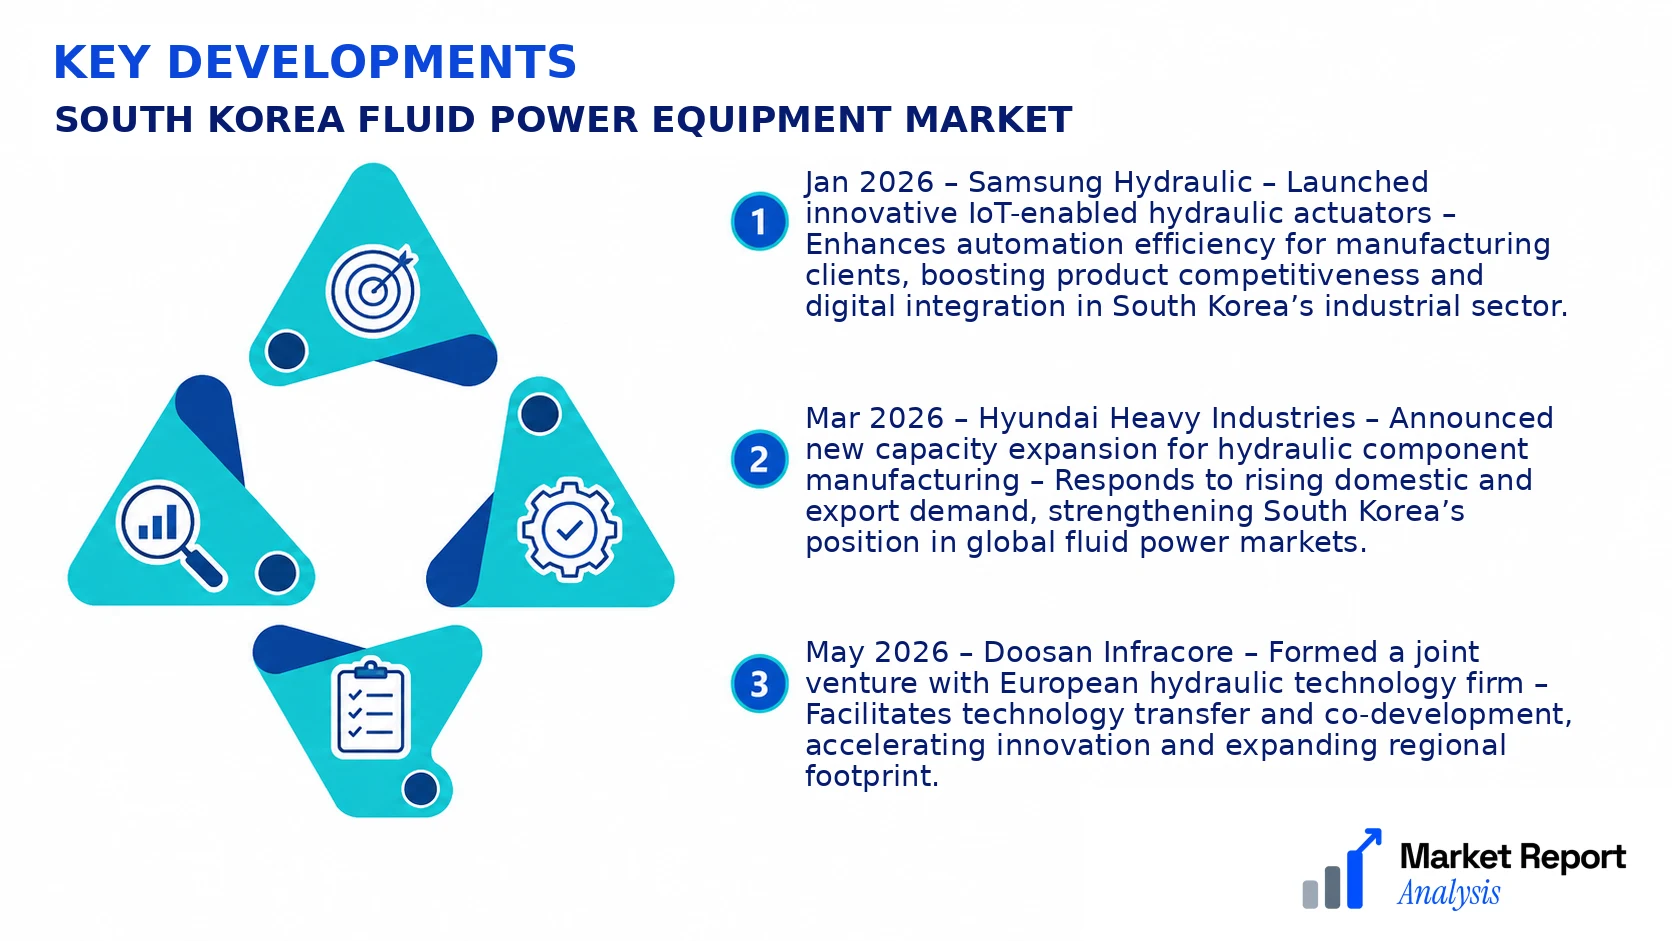
- Jan 2026 – Samsung Hydraulic – Launched innovative IoT-enabled hydraulic actuators – Enhances automation efficiency for manufacturing clients, boosting product competitiveness and digital integration in South Korea’s industrial sector.
- Mar 2026 – Hyundai Heavy Industries – Announced new capacity expansion for hydraulic component manufacturing – Responds to rising domestic and export demand, strengthening South Korea’s position in global fluid power markets.
- May 2026 – Doosan Infracore – Formed a joint venture with European hydraulic technology firm – Facilitates technology transfer and co-development, accelerating innovation and expanding regional footprint.
- Jul 2026 – Korea Pneumatics – Launched a new range of energy-efficient pneumatic cylinders – Positioned to meet Industry 4.0 requirements, supporting automation initiatives across South Korean factories.
- Sep 2026 – Hanwha Precision Machinery – Invested in a new digital automation laboratory – Promotes R&D on intelligent fluid control systems, reinforcing leadership in precision hydraulic technology.
Frequently Asked Questions
What is the South Korea Fluid Power Equipment Market?
The South Korea Fluid Power Equipment Market encompasses the production, distribution, and deployment of hydraulic and pneumatic equipment used across manufacturing, construction, and automotive sectors, driven by industrial growth and technological innovation within South Korea.
What is the current market size of South Korea Fluid Power Equipment Market?
As of 2026, the market is valued at approximately USD 4.8 Billion, reflecting strong demand from key sectors such as manufacturing and transport, coupled with ongoing infrastructural investments and automation initiatives across South Korea.
What factors are driving the South Korea Fluid Power Equipment Market?
Market growth is propelled by rapid industrialization, government support for automation, increasing demand for energy-efficient solutions, and the expansion of manufacturing capabilities, especially in automotive and electronics sectors, alongside technological advancements in fluid power systems.
Which South Korean city leads the South Korea Fluid Power Equipment Market?
Seoul remains the dominant city in the market, due to its status as a hub for industrial innovation, presence of major manufacturing corporations, and extensive infrastructure development projects that require high-performance fluid power solutions.
Which segment is expected to grow the fastest?
The pneumatic segment is anticipated to see the fastest growth through 2034, driven by its applications in automation, packaging, and material handling, alongside increasing adoption of smart manufacturing practices in South Korean industries.
Who are the leading companies operating in the South Korea Fluid Power Equipment Market?
Key players include global giants like Parker Hannifin, Bosch Rexroth, and Eaton Corporation, along with local companies such as Hyunwon Hydraulic and Hanil Hydraulic, all competing through innovation, product quality, and regional presence.
Analyst Perspective
The South Korea Fluid Power Equipment Market exhibits a mature yet gradually evolving landscape, driven by ongoing industrial modernization and a focus on automation. Long-term prospects remain favorable, supported by government initiatives targeting smart manufacturing and infrastructure upgrade projects. Commercial opportunities are emerging in sectors such as automotive, electronics, and renewable energy, where fluid power systems enable efficiency and precision. Technological developments are increasingly converging with Industry 4.0 paradigms, emphasizing connectivity, real-time monitoring, and digital twin integration, which are expected to elevate system performance and reduce downtime. Investment priorities should focus on innovative fluid control technologies, lightweight materials, and energy-efficient solutions to strengthen competitive positioning. Major urban centers like Seoul and Incheon are poised for accelerated growth due to concentrated industrial activities and infrastructure projects, presenting substantial opportunities for localized deployment. Overall, the market’s competitive landscape is intensifying as local and global players seek to capitalize on South Korea’s strategic industrial hubs, demanding a keen focus on technological edge and strategic alliances.
