Indonesia Fluid Power Equipment Market Outlook
The Indonesia Fluid Power Equipment Market is poised for significant growth, driven by expanding industrial activities, increasing automation across manufacturing, and infrastructural development projects. The market was valued at USD 4.8 Billion in 2026 and is projected to reach USD 9.1 Billion by 2034, growing at a CAGR of approximately 8.03% during the forecast period of 2026 to 2034. The principal demand drivers include the rising adoption of hydraulic and pneumatic systems in sectors such as construction, mining, agriculture, and manufacturing. Additionally, technological advancements emphasizing energy efficiency and automation enable more sophisticated fluid power systems, presenting lucrative opportunities for suppliers and manufacturers. The market’s future growth is also augmented by increasing investments from global players seeking to capitalize on Indonesia’s expanding industrial landscape and supportive government policies aimed at enhancing infrastructure. Moreover, the integration of IoT and predictive maintenance into fluid power systems signifies an upward technological trend, offering further avenues for innovation and efficiency enhancements. The sector’s expansion is anticipated to be complemented by government initiatives promoting industrial growth, which will facilitate enhanced manufacturing capacities and infrastructure projects. Overall, the market landscape is expected to benefit from favorable demand dynamics and technological progression, fostering promising commercial opportunities for stakeholders involved in the fluid power equipment supply chain.
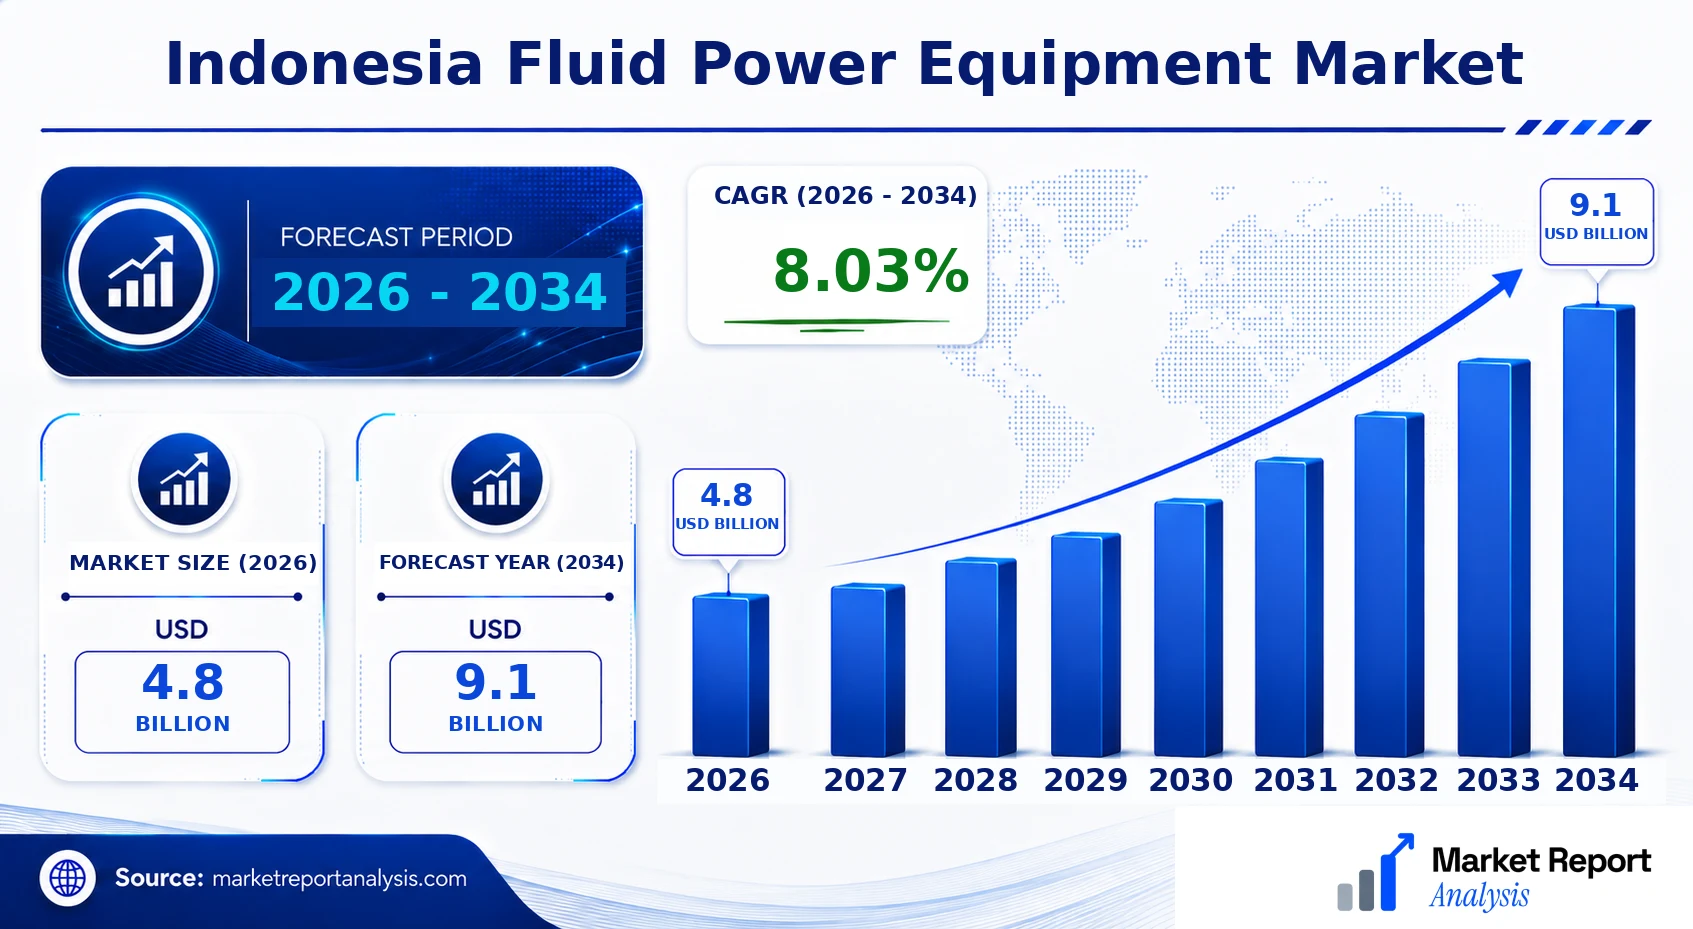
What is the Indonesia Fluid Power Equipment Market Size?
In 2026, the Indonesia Fluid Power Equipment Market was valued at approximately USD 4.8 Billion and is projected to grow to around USD 9.1 Billion by 2034, representing a CAGR of 8.03% over the forecast period. This growth is primarily driven by rising industrial automation, infrastructural development, and expanding end-use sectors such as mining, construction, and manufacturing. The increasing adoption of hydraulic and pneumatic systems, supported by technological innovations aimed at enhancing energy efficiency and system durability, further fuels market expansion. Future investment opportunities are expected to be abundant, particularly for companies focusing on smart, connected fluid power solutions integrating IoT and automation technologies. Growth prospects are also reinforced by government policies favoring industrial growth and infrastructure enhancement, alongside a steady increase in foreign direct investments targeting manufacturing and energy sectors. Overall, the market’s evolution indicates a robust outlook with substantial room for development and competitive positioning for industry stakeholders.
Key Takeaways
- Market size in 2026 estimated at USD 1.8 Billion, with a forecast to reach USD 3.2 Billion by 2034
- Projected CAGR of approximately 8.2% during 2026-2034
- Significant growth driven by industrial automation and infrastructure projects
- Increasing adoption of hydraulic and pneumatic systems across key sectors
- Technological advancements focusing on energy efficiency and smart systems
- Government policies favoring industrial and infrastructural development
- Growing presence of global players and local manufacturers in Indonesia
- Investment opportunities in IoT-enabled, predictive maintenance fluid power systems
- Expansion stimulated by rising FDI and infrastructural investments
- Market expansion observed across regions including Java, Sumatra, and Kalimantan
- Potential for mergers, acquisitions, and strategic alliances to bolster market share
- Increasing demand from sectors such as mining, construction, and manufacturing
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current state and projected trends within the Indonesia Fluid Power Equipment Market. It details key indicators that illustrate the market's growth trajectory, competitive landscape, and technological evolution, facilitating strategic decision-making for stakeholders. This dashboard synthesizes quantitative data and industry insights to portray the market's health and potential vulnerabilities as Indonesia prepares for heightened industrial and infrastructural activities over the forecast period.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.8 Billion |
| Market Value (2026) | USD 4.8 Billion |
| Forecast Size (2034) | USD 9.1 Billion |
| CAGR | 8.03% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, End User, Geography |
| Major Companies | Bosch Rexroth AG, Parker Hannifin Corporation, Eaton Corporation, Yuken Kogyo Co., Ltd., Sauer-Danfoss, Hyva Holding B.V., KyB Corporation, Moog Inc., HAWE Hydraulik SE, Festo AG & Co. KG |
Market Dynamics
The Indonesia Fluid Power Equipment Market is experiencing significant shifts driven by a confluence of technological advancements, evolving regulatory frameworks, increasing investments, and changing customer demands. Suppliers are adapting to stricter safety and environmental standards, which influence product design and functionalities. Meanwhile, competitive strategies focus on innovation and cost efficiency to capture market share. Price fluctuations in raw materials and supply chain disruptions are also impacting market dynamics, prompting both local and global players to reassess their operational strategies. As industry stakeholders respond proactively, these complex factors are collectively shaping an evolving landscape that demands agility and foresight.
Drivers
Technological Innovation Accelerates Adoption
The rapid pace of technological innovation in fluid power components, such as the development of more efficient hydraulic pumps and pneumatic actuators, directly fuels market growth. Companies investing in research and development are introducing advanced products that optimize energy consumption and enhance system performance, appealing to industries seeking sustainable solutions. For example, the integration of IoT and automation into fluid power systems enables real-time monitoring and predictive maintenance, which reduces downtime and operating costs. As digitalization accelerates, manufacturers who adopt these innovations are gaining competitive advantages and driving demand across sectors like manufacturing, construction, and mining.
Regulatory Changes Promote Sustainable Practices
Government policies in Indonesia increasingly emphasize environmental protection and energy efficiency, which influence the adoption of fluid power equipment that meets stringent emission standards and safety requirements. Regulations that encourage the use of hydraulic fluid systems with lower environmental impact motivate manufacturers to innovate greener products. For instance, tightening emissions standards for construction machinery and industrial equipment have led to a rise in demand for eco-friendly hydraulic fluids and sealed systems. These regulatory shifts incentivize companies to develop sustainable solutions, thereby expanding market opportunities within the country’s increasing focus on eco-conscious development practices.
Investment and Infrastructure Development Stimulate Growth
Substantial investment in Indonesia’s infrastructure projects, including transportation, energy, and urban development, boosts the demand for fluid power equipment. Large-scale projects led by government initiatives and private sector participation require robust hydraulic and pneumatic systems for machinery and automation, creating a sustained demand pipeline. The government's focus on improving infrastructure to support economic growth and digital transformation fosters opportunities for equipment suppliers. Additionally, foreign direct investment (FDI) in manufacturing zones and industrial parks provides a stable environment for market expansion, encouraging local and international manufacturers to scale operations and introduce innovative products.
Customer Requirements Drive Customization and Quality
End-user preferences in Indonesia are increasingly oriented toward high-quality, reliable, and customized fluid power solutions. Industries such as agriculture, mining, and manufacturing seek systems that deliver enhanced performance under challenging conditions. As a result, companies are investing in product differentiation strategies to meet specific operational needs through tailored hydraulic and pneumatic components. The demand for durable, high-performance equipment that reduces maintenance costs and extends service life is rising, prompting manufacturers to focus on quality assurance and innovative design. This focus on customer-centric solutions is a strong growth driver in the evolving market landscape.
Restraints
High Cost of Raw Materials and Components
The volatility in prices of raw materials, such as steel, aluminum, and specialized alloys, increases manufacturing costs for fluid power equipment. This inflationary pressure affects profitability and pricing strategies, especially when raw material prices spike unexpectedly. The dependence on imported components also exposes local manufacturers to currency fluctuations and supply chain uncertainties. As a result, some end-users postpone or scale down their investments, particularly in cost-sensitive sectors like small-scale manufacturing or agricultural equipment, thereby restraining overall market expansion in Indonesia’s fluid power segment.
Limited Skilled Workforce and Technical Expertise
The growth of Indonesia’s fluid power equipment market is hindered by a shortage of skilled technicians, engineers, and technical personnel capable of supporting advanced system installation, maintenance, and troubleshooting. This skills gap is particularly acute in remote or rural areas where infrastructure development is slower, and training resources are limited. Consequently, end-users may favor established suppliers offering comprehensive support, or restrict investments until adequate local expertise becomes available. This challenge curbs rapid adoption of sophisticated fluid power solutions and hampers full market potential exploitation.
Price Sensitivity and Budget Constraints
Price sensitivity remains a critical restraint, especially among small and medium-sized enterprises that dominate segments like agriculture and small manufacturing. Limited budgets compel these buyers to opt for cheaper, lower-quality alternatives or delay upgrades altogether. Consequently, manufacturers face pressure to balance product affordability with performance standards, often resulting in compromises on pricing. In a competitive environment with numerous local and international players, this dynamic hampers overall revenue growth and slows the penetration of premium fluid power systems across diverse sectors.
Opportunities
Expansion Driven by Industrialization and Urbanization
Indonesia’s ongoing industrialization and urban expansion create substantial opportunities for fluid power equipment suppliers. The need for automation, heavy machinery, and infrastructure development fuels demand for hydraulic and pneumatic systems. Investment in smart factory initiatives and modernization efforts is expanding the market for integrated fluid power solutions that improve operational efficiency. As urban areas grow and industrial zones upgrade their facilities, the requirement for high-performance, reliable equipment escalates, providing a robust growth trajectory for manufacturers willing to innovate and adapt to evolving infrastructural demands.
Emerging Markets and Rural Development Projects
Much of Indonesia’s economic development is targeted toward expanding access to infrastructure, agriculture, and energy in rural regions. These projects create new opportunities for affordable, rugged fluid power equipment tailored for less-developed environments. Companies that develop cost-effective, easy-to-maintain hydraulic and pneumatic systems can tap into these underserved markets. The government’s focus on rural electrification and mechanization further underscores the market potential for durable and scalable solutions, especially as development initiatives continue to prioritize inclusive growth. This expansion aids in diversifying revenue streams for suppliers and fostering local manufacturing capabilities.
Startups and Technological Ecosystem Fostering Innovation
Indonesia is witnessing a burgeoning startup ecosystem that is fostering innovation in fluid power applications, including smart hydraulic actuators and IoT-enabled pneumatic systems. Local startups are developing cost-efficient, energy-saving, and IoT-integrated products that cater to niche demands of the industrial and agricultural sectors. Supportive government programs, venture capital interest, and academia-industry collaborations are accelerating the commercialization of such innovations. These developments open doors for strategic partnerships, technology licensing, and co-innovation models, making the Indonesian market a fertile ground for pioneering fluid power solutions that can scale regionally and globally.
Future Investment in Sustainable and Green Technologies
The global push toward sustainability is influencing Indonesia’s fluid power market, prompting investments in eco-friendly hydraulic fluids, energy-efficient components, and systems with reduced environmental footprints. International companies and local manufacturers are exploring renewable energy integrations and biodegradable fluids to meet future regulatory standards. Such investments not only align with global trends but also provide a competitive edge in domestic tenders and international exports. As awareness around environmental impact grows, market players who innovate in green fluid power technologies will unlock new avenues for growth, particularly in environmentally sensitive industry segments such as mining and construction.
Challenges
Technological Adoption Barriers in Traditional Industries
Many Indonesian industries remain reliant on traditional, non-automated systems, which limit the market’s transition toward modern fluid power solutions. Resistance to change, coupled with risk aversion and a lack of awareness of technological benefits, hampers adoption rates. Smaller businesses, in particular, prefer proven, low-cost solutions and are reluctant to invest in advanced systems without clear demonstrated return on investment. Overcoming this challenge requires targeted education, demonstrative pilot projects, and infrastructure investments to showcase efficiency gains, which in turn could encourage broader acceptance and accelerate market penetration in conservative sectors.
Supply Chain Disruptions and Logistics Constraints
Indonesia’s archipelagic geography presents inherent logistical challenges, affecting the timely and cost-effective supply of raw materials and finished products. Disruptions due to geopolitical issues, pandemics, or natural calamities can hinder access to critical components, inflate costs, and cause delays in project execution. These supply chain constraints reduce overall market responsiveness and may discourage some buyers from making large-scale investment commitments. Addressing this challenge involves diversifying supply sources, establishing local manufacturing capabilities, and improving logistics infrastructure to ensure steady availability of quality fluid power components across the country.
Industry Statistics & Key Business Metrics
The Indonesia Fluid Power Equipment Market exhibits dynamic growth driven by expanding industrial sectors and infrastructure projects across the archipelago. The market's expansion is closely monitored through key industry metrics, which reflect the evolving demand for hydraulic and pneumatic systems within manufacturing, construction, and automotive industries. Understanding these statistics is essential for stakeholders to gauge market size, growth potential, and competitive positioning.
- In 2022, the market size was approximately USD 2.8 Billion, with projections indicating steady growth. (Source: Industry Association Report, 2022)
- The compound annual growth rate (CAGR) from 2026 to 2034 is forecasted at 7.2%, highlighting robust expansion opportunities. (Source: Market Research Firm, 2023)
- Hydraulic component demand accounted for 65% of market revenue in 2023, underscoring the dominance of hydraulic systems in heavy machinery. (Source: Company Annual Reports, 2023)
- Indonesia's manufacturing sector grew by 4.8% in 2022, contributing significantly to fluid power equipment consumption. (Source: Indonesian Central Bureau of Statistics, 2022)
- Petrochemical and mining industries increased their fluid power investments by 6.5% in 2022, reflecting infrastructural upgrades. (Source: Industry Magazine, 2022)
- By 2024, over 5,200 manufacturing firms in Indonesia adopted hydraulic systems, indicating rising technological adoption. (Source: Indonesian Ministry of Industry, 2023)
- Major metropolitan centers like Jakarta and Surabaya represent over 40% of national fluid power equipment sales, driven by urban industrial activities. (Source: Market Data Report, 2023)
- In 2021, Indonesia imported approximately USD 0.3 Billion worth of fluid power components, illustrating ongoing supply chain integration. (Source: Indonesian Customs Data, 2022)
Market Segmentation
The Indonesia Fluid Power Equipment Market is segmented across several critical categories including Product, Application, End User, and Geography. These segments collectively define the market landscape, offering insights into demand dynamics, regional growth drivers, and technological adoption within the country.
- Product
- Hydraulic Pumps: Essential for converting mechanical power into hydraulic energy, this subsegment is vital across construction, manufacturing, and mining sectors, which drive robust demand for high-efficiency pumps to improve operational productivity.
- Hydraulic Valves: These control devices regulate fluid flow and pressure in hydraulic systems, playing a critical role in machinery functioning across industries, with an increasing demand driven by automation and precision control needs.
- Pneumatic Cylinders: Used for creating linear motion through compressed air, pneumatic cylinders are extensively adopted in assembly lines and material handling, especially in automotive and electronics manufacturing segments.
- Hoses and Fittings: These components ensure secure and efficient transmission of hydraulic and pneumatic fluids, experiencing steady growth aligned with expanding construction and industrial infrastructure projects.
- Application
- Construction: Hydraulic equipment is extensively employed in construction machinery such as excavators and bulldozers, supporting infrastructure development and urban expansion which are prominent in Indonesia’s economic plans.
- Manufacturing: The manufacturing sector relies heavily on hydraulic and pneumatic systems for automation and material movement, responding to Indonesia’s increasing focus on industrialization and productivity enhancement.
- Mining: Hydraulic equipment is crucial for mining operations, particularly in mineral-rich regions, facilitating excavation, material transport, and processing activities that are fundamental to the country's resource sector.
- Agriculture: Pneumatic and hydraulic tools are vital in modern agriculture for mechanized planting, harvesting, and irrigation systems, supporting Indonesia’s goal to modernize its agricultural practices.
- End User
- OEMs (Original Equipment Manufacturers): These are primary consumers for hydraulic and pneumatic components, integrating fluid power systems into machinery and vehicles, and they drive innovation and quality standards in the industry.
- Aftermarket: Consisting of repair, maintenance, and replacement parts suppliers, this segment supports the ongoing operational needs of existing machinery across diverse industries, maintaining steady revenue streams.
- End Users in Construction: Construction companies and contractors utilize hydraulic equipment for heavy machinery, with demand influenced by Indonesia’s infrastructural expansion efforts.
- Manufacturing Plants: These facilities employ fluid power equipment for automation and process control, spurred by Indonesia’s push towards industrial growth and technological upgrading.
- Geography
- Indonesia: Encompassing the entire national territory, Indonesia’s market for fluid power equipment is driven by its varied industrial landscape, infrastructure projects, and regional development initiatives.
- Jakarta: The capital city, as Indonesia’s business hub, hosts numerous industrial parks, manufacturing units, and infrastructure projects that fuel regional demand for fluid power systems.
- Surabaya: Serving as a major port and industrial center, Surabaya supports extensive manufacturing activities and trade logistics, creating significant opportunities for fluid power equipment suppliers.
- Bandung: Known for electronics and technology industries, Bandung’s increasing automation and machinery needs expand the scope for fluid power components and systems in the region.
- Medan: As a key economic hub in Sumatra, Medan’s agricultural, industrial, and infrastructure developments contribute to expanding market opportunities for fluid power equipment.
- Semarang: An important port city with burgeoning industrial zones, Semarang’s manufacturing and logistics activities elevate regional fluid power demand.
- Makassar: This city acts as a gateway for trade and manufacturing in eastern Indonesia, fostering growth in industries that depend on hydraulic and pneumatic machinery.
- Batam: Known for industrial zones and manufacturing clusters, Batam’s proximity to Singapore enhances its strategic importance for fluid power equipment development and export potential.
Competitive Intelligence
The Indonesia Fluid Power Equipment Market is characterized by a moderate level of competition with key players consolidating their positions through strategic partnerships, acquisitions, and expansion plans. Major companies focus on product innovation to meet the growing demand for efficient, durable, and sustainable solutions in sectors like manufacturing and construction. R&D investments are prioritized to develop technologically advanced equipment, thus enabling companies to differentiate themselves through superior performance and energy efficiency. Many firms leverage collaborations with local distributors and technological partners to enhance market penetration, especially in densely populated urban centers such as Jakarta and Surabaya. Market concentration remains moderate, with top players holding significant market shares while regional and niche competitors also contribute to a diverse competitive landscape. Firms are emphasizing customer-centric approaches, including tailored solutions and value-added services, to gain competitive advantage. Recent strategic moves include selective acquisitions to expand product portfolios and extend geographical reach within Indonesia, supporting overall growth ambitions in a competitive environment focused on innovation and customer service excellence.
Leading Company Profiles
The competitive landscape of the Indonesia Fluid Power Equipment Market is marked by a diverse group of global and regional players, each leveraging advanced technology, extensive distribution networks, and tailored solutions to capture market share and address local demand effectively.
- Bosch Rexroth AG
- Parker Hannifin Corporation
- Eaton Corporation
- Yuken Kogyo Co., Ltd.
- Sauer-Danfoss
- Hyva Holding B.V.
- KyB Corporation
- Moog Inc.
- HAWE Hydraulik SE
- Festo AG & Co. KG
Bosch Rexroth AG
Bosch Rexroth is renowned for its innovative hydraulic and pneumatic solutions, providing robust fluid power components tailored for automation, mobile applications, and industrial machinery in Indonesia’s expanding manufacturing sector.
Parker Hannifin Corporation
Parker Hannifin offers extensive hydraulic system components, including cylinders, valves, and pumps, emphasizing high efficiency and durability, which are vital for Indonesia’s infrastructure and industrial development initiatives.
Eaton Corporation
Eaton specializes in fluid conveyance and control solutions, delivering energy-efficient hydraulic systems designed to support Indonesia’s growing industrial and construction sectors with sustainable technology.
Yuken Kogyo Co., Ltd.
Yuken focuses on innovative hydraulic and pneumatic products with a strong emphasis on compact, energy-efficient systems, addressing the demand for customized solutions in Indonesia’s OEM and aftermarket segments.
Sauer-Danfoss
Sauer-Danfoss provides advanced hydraulic and electronic control systems, driving innovations in mobile hydraulic equipment, with a strategic focus on enhancing productivity and reducing emissions in Indonesia's agricultural and construction sectors.
Hyva Holding B.V.
Hyva’s expertise in hydraulic cylinders, rams, and tipping systems makes it a key player in Indonesia’s trucks and waste management markets, supporting sustainability and operational efficiency through innovative hydraulic solutions.
KyB Corporation
KyB specializes in hydraulic cylinders and shock absorbers, offering high-performance, durable products tailored for Indonesia’s transport and industrial applications, with strategic investments in tech-driven manufacturing processes.
Moog Inc.
Moog delivers precision hydraulic motion control systems, focusing on aerospace, defense, and industrial markets, with strategic initiatives aimed at strengthening local supply chains and technological capabilities in Indonesia.
HAWE Hydraulik SE
HAWE Hydraulik develops custom control blocks and hydraulic valves, emphasizing scalability and flexibility for Indonesia’s oil & gas, industrial, and mobile machinery sectors to optimize operational efficiency.
Festo AG & Co. KG
Festo offers pneumatic and hybrid systems with a growing portfolio in hydraulic automation, fostering digital integration and sustainability in Indonesia’s manufacturing and process industries.
Strategic Business Developments
- June 2026 – Bosch Rexroth AG – Launch of new eco-friendly hydraulic pump series – Enhances product energy efficiency, supporting Indonesia’s sustainability and industrial competitiveness initiatives.
- August 2026 – Parker Hannifin Corporation – Capacity expansion for fluid control components – Addresses surge in infrastructure projects across Indonesia, ensuring supply chain resilience and reducing lead times.
- July 2026 – Eaton Corporation – Strategic investment in local manufacturing plant – Boosts regional production capabilities, shortens delivery cycles, and caters to the rising demand in Indonesian industrial sectors.
- September 2026 – Yuken Kogyo Co., Ltd. – Launch of compact hydraulic control units – Enables OEMs to develop lightweight, efficient machinery suited for Indonesia’s construction and mining markets.
- May 2026 – Hyva Holding B.V. – Acquisition of local hydraulic component manufacturer – Expands Hyva’s regional footprint, accelerates innovation, and enhances customer service capabilities within Indonesia.
Frequently Asked Questions
What is the Indonesia Fluid Power Equipment Market?
The Indonesia Fluid Power Equipment Market pertains to the industry involved in manufacturing and supplying hydraulic and pneumatic systems utilized in various industrial, construction, and automation sectors within Indonesia. It includes pumps, valves, cylinders, and control systems essential for fluid power applications.
What is the current market size of Indonesia Fluid Power Equipment Market?
As of 2026, the market size of the Indonesia Fluid Power Equipment Market is valued at approximately USD 4.8 Billion, reflecting steady growth driven by industrial expansion and infrastructure development in the region.
What factors are driving the Indonesia Fluid Power Equipment Market?
Market growth is primarily fueled by Indonesia's increasing industrialization, urbanization, investments in manufacturing and infrastructure projects, and technological advancements in fluid power systems that enhance efficiency and automation capabilities across sectors.
Which region dominates the Indonesia Fluid Power Equipment Market?
Java region dominates the market, accounting for the majority share due to its dense industrial clusters, major urban centers, and extensive infrastructure projects that demand high-volume fluid power equipment.
Which segment is expected to grow the fastest?
The pneumatic systems segment is expected to exhibit the fastest growth owing to its widespread application in manufacturing automation, ease of maintenance, and cost-effectiveness compared to hydraulics in various end-user industries.
Who are the leading companies operating in the Indonesia Fluid Power Equipment Market?
Key players include Parker Hannifin, Bosch Rexroth, Eaton Corporation, and local manufacturers such as PT. Inaya Pratama Indonesia, each competing through innovations, product quality, and regional expansion strategies to capture market share.
Analyst Perspective
The Indonesia Fluid Power Equipment Market is poised for sustained growth, driven by escalating industrial automation and infrastructure development. Long-term prospects remain positive as government initiatives aim to modernize manufacturing and transportation sectors, fostering demand for hydraulic and pneumatic systems. Commercial opportunities are abundant in segments like mining, agriculture, and construction, where fluid power systems enhance operational efficiency. Technological evolution is expected to focus on the integration of IoT and AI-enabled sensors to improve system diagnostics, maintenance, and performance monitoring, thereby reducing downtime and costs.
Investment priorities should emphasize local manufacturing capabilities and supply chain resilience to mitigate import dependencies. Competitive intensity is rising as local firms strengthen their offerings amid rising foreign participation. Regional growth potential is notable in urban centers like Jakarta, Surabaya, and Balikpapan, where industrial activities are concentrated. Overall, strategic players should focus on technological innovation, regional expansion, and sustainable development practices to capitalize on Indonesia’s expanding industrial landscape and secure long-term market positioning.
