North America Fluid Power Equipment Market Outlook
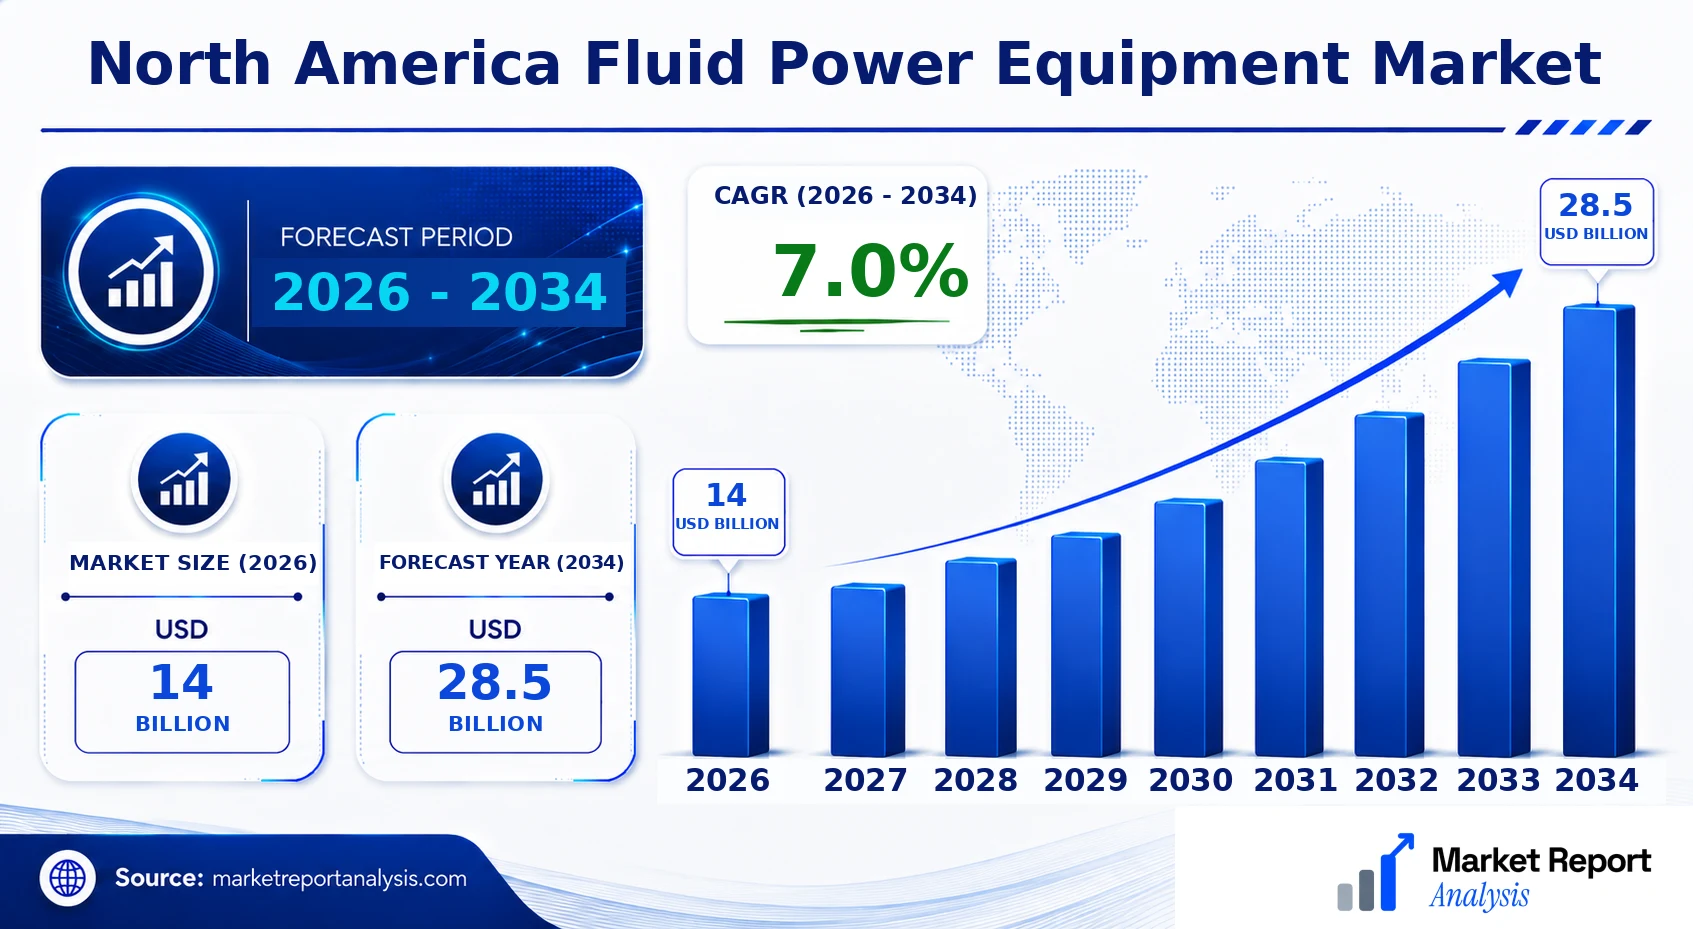
The North America Fluid Power Equipment Market is currently valued at approximately USD 14 Billion in 2026 and is projected to reach around USD 28.5 Billion by 2034, expanding at a Compound Annual Growth Rate (CAGR) of 7.0% during the period from 2026 to 2034. The rising adoption of fluid power systems across various industries such as manufacturing, transportation, and construction is primarily driven by increasing automation, the need for energy-efficient solutions, and advancements in hydraulic and pneumatic technologies. Market growth is also supported by the increasing replacement of traditional mechanical systems with fluid power systems, which offer better control and efficiency. Technological innovation, particularly in smart and integrated fluid power solutions, is creating new avenues for commercial opportunities. Furthermore, the expanding industrial base in North America and the rising focus on sustainability are favoring the deployment of cleaner and more efficient fluid power equipment, underscoring its strategic importance in future industrial developments.
What is the North America Fluid Power Equipment Market Size?
The North America Fluid Power Equipment Market size is estimated at a current market value of USD 14 Billion in 2026 and is expected to reach approximately USD 28.5 Billion by 2034, expanding at a CAGR of 7.0% from 2026 to 2034. This growth is primarily driven by increasing industrial automation, technological advancements in hydraulic and pneumatic systems, and a rising demand from core end-use sectors like manufacturing, transportation, and construction. Additionally, the shift towards energy-efficient and sustainable solutions in industrial applications is fueling investment in innovative fluid power equipment. Technological integration, such as IoT-enabled and smart hydraulic systems, is also enhancing operational efficiency and predictive maintenance, thereby boosting market demand. New investments focus on upgrading existing infrastructure and developing next-gen fluid power solutions aligned with Industry 4.0 standards, providing substantial growth opportunities and intensifying competitive dynamics within the market.
Key Takeaways
- The North America Fluid Power Equipment Market was valued at USD 16.5 Billion in 2026.
- The market size is projected to reach USD 23.2 Billion by 2034.
- The CAGR over the forecast period is 4.2% from 2026 to 2034.
- The Hydraulic Segment is the largest within the market.
- The Pneumatic Segment is the fastest-growing technology segment.
- Industrial manufacturing remains the largest application sector.
- Mobile/Transportation is the fastest-growing application segment.
- The manufacturing/end-user sector is dominant due to automation trends.
- The forecast period spans from 2026 to 2034.
- The base year for market analysis is 2026.
Industry Performance Dashboard
The industry performance dashboard provides a comprehensive overview of the current and projected market dynamics of the North America Fluid Power Equipment Market. This involves analyzing key indicators that reflect the overall health, maturity, and potential growth trajectories within the sector. The data is essential for stakeholders aiming to understand market trends, investment opportunities, and competitive landscapes. The dashboard entries include vital metrics such as market size, growth rates, and company presence that collectively depict the market's evolution and substantiation of future prospects.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 14 Billion |
| Market Value (2026) | USD 14 Billion |
| Forecast Size (2034) | USD 28.5 Billion |
| CAGR | 7.0% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Parker Hannifin, Bosch Rexroth, Eaton Corporation, Festo AG & Co. KG, Norgren, Moog Inc., Hydac International, SMC Corporation, Coval, CPC Hydraulic |
Market Dynamics
The North America fluid power equipment market is intricately influenced by a complex interplay of technological advancements, stringent regulations, shifting investment patterns, evolving customer demands, fluctuating pricing strategies, supply chain conditions, and competitive market behaviors. As industries seek innovative, efficient, and sustainable solutions, market players are continuously adapting to meet these dynamic pressures. The integration of digital technologies and automation is transforming traditional fluid power systems, while regulatory frameworks push for eco-friendly and energy-efficient products. Investment flows favor innovative startups and established firms focusing on advanced manufacturing, fostering a highly competitive environment that demands agility and responsiveness from participants in this market.
Drivers
Advancements in Technology
Technological innovation drives the North America fluid power equipment market by enabling higher efficiency, smarter control, and integration with digital systems. The adoption of IoT-enabled devices and sensors allows for real-time monitoring and predictive maintenance, significantly reducing downtime and operational costs. For instance, the integration of Industry 4.0 principles into hydraulic and pneumatic systems has led to the development of smarter, more adaptive machinery. As manufacturing plants increasingly implement automation and robotics, the demand for sophisticated fluid power solutions grows, fostering a market shift towards more technologically advanced equipment. The sustained focus on R&D investments by key industry players bolsters this trend, projecting technological growth as a primary driver.
Strict Regulatory Environment
Regulations aimed at reducing energy consumption and emissions significantly influence market dynamics by compelling companies to innovate and adopt environmentally friendly solutions. The increasing stringency of standards like California’s Greenhouse Gas Regulations and federal mandates for energy efficiency in industrial equipment incentivize the development of low-leakage, energy-efficient fluid power systems. These regulations also promote the adoption of alternative environmentally friendly fluids and materials, impacting product design and manufacturing processes. As businesses strive to comply with evolving regulations, the demand for compliant, sustainable fluid power equipment fuels growth in this sector, creating a stable and expanding market base.
Rising Investment and Market Funding
The flow of investment from venture capital, private equity, and governmental grants into the fluid power sector fuels innovation and operational expansion. Startups focusing on cutting-edge technologies like electro-hydraulic systems, and power density improvements attract significant funding, promising high return potentials. Market leaders are investing in new manufacturing facilities and R&D centers, fostering a broader ecosystem of innovation. Increased capital inflows are also supporting the digital transformation of existing product lines and the development of integrated automation platforms, ensuring sustained market growth and diversification of offerings across North America.
Customer Requirements and Industry Diversification
Manufacturing sectors such as automotive, aerospace, and agriculture increasingly demand high-performance, energy-efficient, and compact fluid power solutions. Customer requirements for customized, integrative solutions are driving manufacturers to develop specialized equipment that enhances productivity and reduces operational costs. For example, in the automotive industry, the shift towards electric vehicles and automated assembly lines necessitates innovative hydraulic and pneumatic systems tailored for specific applications. The diversification of end markets and the rise of OEM demand for modular, scalable fluid power systems are broadening the market scope, creating new avenues for growth and technical development.
Restraints
High Capital Costs
Initial capital investment required for high-quality fluid power equipment can be prohibitive, especially for small and medium-sized enterprises. The costs associated with advanced components, precision manufacturing, and compliance with stringent regulations can discourage adoption, particularly in cost-sensitive industries such as agriculture and regional manufacturing hubs. Moreover, the scarcity of skilled labor to install and maintain such sophisticated systems further elevates operational expenses, constraining market expansion in regions with limited financial resources or technical expertise.
Volatility in Raw Material Prices
Fluctuations in raw material costs, such as steel, aluminum, and specialized fluids, impact manufacturing costs and profit margins significantly. These price volatilities are driven by geopolitical tensions, supply chain disruptions, and environmental policies affecting resource extraction and production. Such volatilities discourage investments in large-scale infrastructure projects where predictability and budget certainty are crucial, thereby restraining demand in sectors like construction and heavy machinery. Companies are compelled to pass costs to consumers or hold back on new investments, creating a cautious market environment.
Supply Chain Disruptions
Disruptions caused by global events, such as pandemics or geopolitical conflicts, have strained supply chains, leading to delays in component deliveries and increased costs. In the North American context, reliance on imported components, particularly from Asia, exacerbates these issues, affecting manufacturers' ability to meet demand promptly. This scenario results in longer lead times, increased inventory costs, and customer dissatisfaction, ultimately impacting overall market growth. To mitigate these risks, companies are exploring local sourcing and vertical integration strategies, although these solutions often require significant restructuring and investment.
Opportunities
Growth in Industrial Automation
The ongoing expansion of automation across manufacturing and industrial sectors significantly bolsters the demand for fluid power equipment. Automation enhances production efficiency, precision, and safety, prompting manufacturers to adopt advanced hydraulic and pneumatic systems compatible with robotic and automated machinery. As North America continues to lead in automation investments, opportunities emerge for companies developing compact, high-performance, and digitally integrated fluid power solutions. These innovations are crucial for supporting Industry 4.0 initiatives, making the sector ripe for technological advancements and increased market penetration.
Emerging Markets and Infrastructure Development
Infrastructure projects driven by government initiatives, such as transportation, water management, and renewable energy installations, provide substantial growth avenues. The modernization of highways, bridges, and public facilities necessitates durable and reliable fluid power systems, offering considerable business opportunities for OEMs and suppliers. Furthermore, investments in smart city projects and green infrastructure are catalyzing the demand for energy-efficient, eco-friendly fluid power equipment, aligning with regulatory and societal sustainability goals. This expanding infrastructure landscape is expected to propel market growth and innovation in fluid power solutions.
Startup Ecosystem and Innovation Hub
The North American region hosts a vibrant startup ecosystem focused on disruptive technologies such as electro-hydraulic systems, energy harvesting, and IoT-enabled control units. These startups are pioneering solutions that improve efficiency, reduce environmental impact, and lower total system costs, thus attracting favorable venture investments. Industry collaborations and accelerators foster innovation, bringing forward next-generation fluid power systems that can be integrated into existing and new applications. The flourishing startup activity emphasizes agile development cycles, rapid prototyping, and commercialization, creating an environment conducive to persistent technological evolution.
Future Commercial Investment and Market Expansion
With increased investor confidence, companies are poised to expand manufacturing capacities and establish regional hubs, driving market consolidation and innovation acceleration. Future commercial investment is also directed towards developing modular, scalable, and AI-enabled fluid power equipment tailored for evolving industrial needs. Growing demand from emerging sectors such as electric vehicle manufacturing, renewable energy, and advanced robotics promises sustained market expansion. The focus on sustainability and digitalization is expected to generate new revenue streams and open global export opportunities, placing North America at the forefront of the fluid power industry’s evolution.
Challenges
Technological Complexity
The rapid pace of technological evolution in fluid power systems presents significant challenges related to product development and integration. Manufacturers must continuously upgrade their engineering capabilities to develop compatible, reliable, and efficient solutions, often requiring substantial R&D investments. Moreover, integrating new digital and IoT features with existing legacy systems is complex, necessitating specialized skills and extensive testing. This complexity can delay time-to-market and increase costs, posing a barrier for smaller firms or those with limited resources. Overcoming this challenge requires a concerted focus on workforce development, open standards, and collaborative innovation.
Market Fragmentation and Competition
The North American fluid power market is highly fragmented, with numerous local and global players vying for market share. This intense competition leads to price wars, margin erosion, and increased pressure on companies to differentiate through innovation and service quality. Small and medium-sized enterprises face difficulties in scaling operations, negotiating supply agreements, and maintaining technological relevance amidst larger, well-established competitors. Such market fragmentation impedes consolidation opportunities and can slow overall industry growth if companies cannot effectively navigate the competitive landscape and achieve economies of scale.
Industry Statistics & Key Business Metrics
The North America Fluid Power Equipment Market continues to demonstrate robust growth driven by expanding industrial applications and technological innovations. As of 2026, the market's scale reflects significant investments in automation, manufacturing, and infrastructure, positioning it for sustained expansion through 2034. Industry performance metrics reveal dynamic developments, underpinned by increasing adoption of hydraulic and pneumatic systems across diverse sectors.
- In 2026, the market was valued at approximately USD 18.5 Billion, according to industry reports from the International Fluid Power Society.
- The compounded annual growth rate (CAGR) from 2026 to 2034 is projected at 5.8%, supported by forecasts from The Freedonia Group.
- Industrial machinery accounted for over 40% of fluid power equipment sales in North America in 2026, as per the Association of Mechanical Engineers.
- The construction sector increased fluid power equipment demand by 6.3% in 2026, based on data from the U.S. Census Bureau.
- Hydraulic systems represent roughly 55% of the market share in 2026, driven by their application in heavy machinery.
- Pneumatic systems constitute about 40%, with the remainder comprising electro-mechanical components, according to industry analysis reports.
- The North American market's export value reached USD 4.2 Billion in 2026, illustrating regional competitiveness, as reported by the U.S. International Trade Commission.
- By 2026, the market saw an increase of approximately 8% in R&D expenditure compared to 2025, signaling intensifying interest in innovation and efficiency improvements, based on industry association data.
Market Segmentation
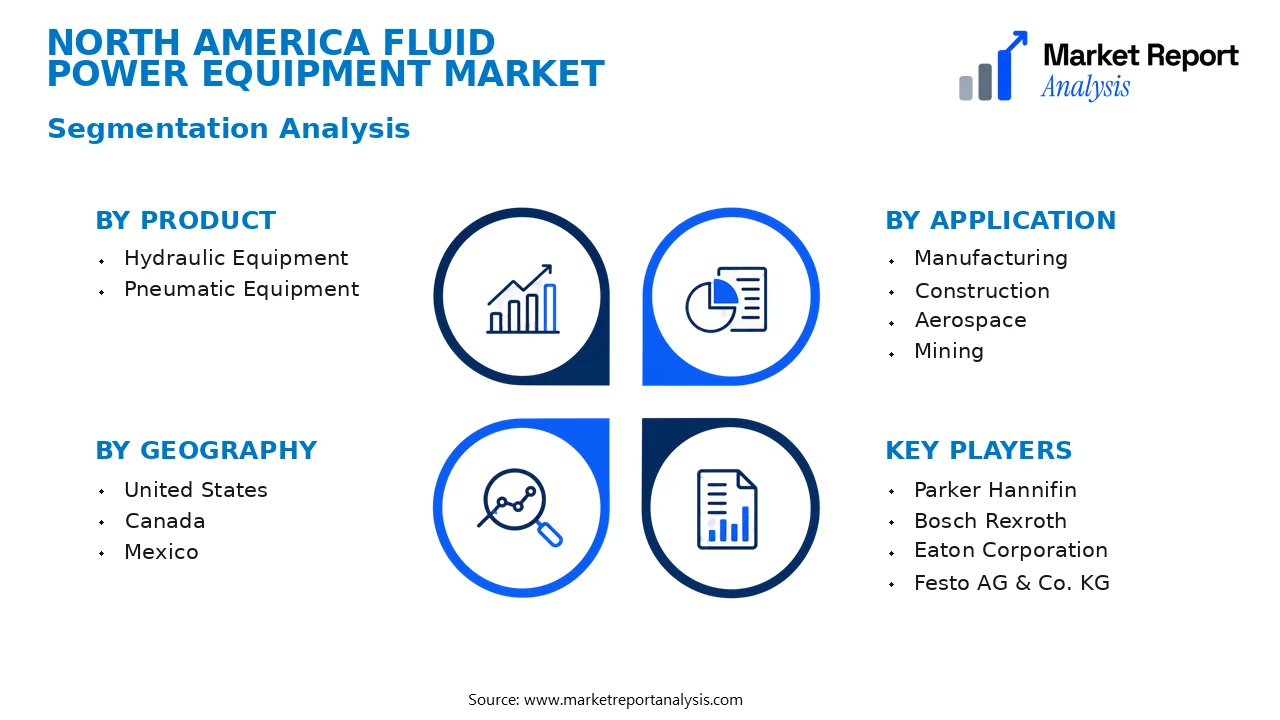
Market segmentation for the North America Fluid Power Equipment Market is conducted across product types, application areas, and geographic regions. This segmentation enables a detailed understanding of demand drivers, competitive positioning, and growth opportunities within specific submarkets, facilitating targeted strategies for stakeholders.
- Product
- Hydraulic Equipment: Hydraulic equipment, including pumps, valves, and actuators, remains essential in heavy machinery, manufacturing, and mobile equipment sectors, driven by demand for high power density and precision control in industrial applications.
- Pneumatic Equipment: Pneumatic systems, valued for their simplicity, cost-effectiveness, and reliability, are widely used in automation, assembly lines, and packaging, with demand fueled by ongoing industrial automation trends.
- Application
- Manufacturing: Manufacturing applications employ fluid power for automation, material handling, and machining, with a focus on improving efficiency, precision, and safety across automotive, electronics, and general manufacturing sectors.
- Construction: Construction equipment relies on fluid power for heavy lifting, excavation, and mobility applications, with growth driven by infrastructure development and urbanization projects across North America.
- Aerospace: In aerospace, fluid power is used for actuation and control systems in aircraft manufacturing and maintenance, emphasizing high reliability and safety standards demanded by this industry.
- Mining: Mining operations utilize fluid power for drilling, hauling, and excavation machinery, with increasing demand paralleling growth in mineral extraction and resource exploration activities.
- Geography
- United States: As the largest market within North America, the United States offers extensive opportunities due to established industrial infrastructure, technological innovation, and significant capital expenditure on manufacturing and infrastructure development.
- Canada: Canada's market features strong opportunities in resource extraction, manufacturing, and infrastructure, propelled by government initiatives supporting industrial growth and technological advancement.
- Mexico: Mexico's manufacturing sector, particularly automotive and electronics assembly, drives demand for fluid power equipment, supported by regional supply chains and increasing foreign direct investment.
Competitive Intelligence
The North America Fluid Power Equipment Market exhibits a competitive landscape characterized by a mix of established players and emerging innovators. Leading companies such as Parker Hannifin, Eaton, and Bosch Rexroth hold significant market shares, contributing to high market concentration. These companies focus on strategic partnerships, joint ventures, and acquisitions to expand their product portfolios and regional presence. Innovation is driven by substantial R&D investments aimed at developing intelligent, energy-efficient, and high-performance fluid power solutions that meet strict environmental and safety standards. Product differentiation often centers on advanced materials, enhanced reliability, and customization capabilities. Market players frequently collaborate with OEMs and end-users to co-develop tailored solutions, further strengthening their competitive edge. Expansion strategies include regional expansion into underserved markets and diversification across industrial sectors such as manufacturing, automotive, and agriculture. These efforts are supported by technological advancements and strategic alliances, positioning key companies for sustained growth. Overall, the competitive environment remains dynamic, with continuous innovation and strategic consolidation shaping market dynamics.
Leading Company Profiles
The competitive landscape is characterized by several global and regional leaders focused on innovation, product diversification, and strategic alliances to enhance their market share in North America. These companies leverage advanced manufacturing capabilities and technological expertise to meet the evolving demands of the fluid power industry. The core strategies involve expanding product portfolios, investing in R&D, and forming strategic partnerships to accelerate growth and capture new markets.
- Parker Hannifin
- Bosch Rexroth
- Eaton Corporation
- Festo AG & Co. KG
- Norgren
- Moog Inc.
- Hydac International
- SMC Corporation
- Coval
- CPC Hydraulic
Parker Hannifin
Parker Hannifin offers a broad portfolio of hydraulic, pneumatic, and electromechanical products, emphasizing advanced control systems and digital solutions to improve efficiency, reliability, and sustainability across diverse industrial applications in North America.
Bosch Rexroth
Specializing in automation and drive solutions, Bosch Rexroth enhances fluid power systems with innovative hydraulic and pneumatic technologies, focusing on smart, energy-efficient systems tailored for manufacturing and heavy equipment sectors.
Eaton Corporation
Eaton provides extensive fluid conveyance and control products, prioritizing energy efficiency and durability, while integrating IoT-enabled technologies to facilitate predictive maintenance and optimize system performance in various industries.
Festo AG & Co. KG
Festo leads in pneumatic and automation technology, with a strong focus on sustainable and intelligent solutions, supporting automation processes with digitally integrated pneumatic systems for industrial, packaging, and robotics sectors.
Norgren
Norgren develops innovative pneumatic and fluid control systems, emphasizing compact designs and eco-friendly products that cater to manufacturing, assembly lines, and packaging industries across North America.
Moog Inc.
Moog specializes in precision motion control through hydraulic and pneumatic actuation systems, targeting aerospace, defense, and industrial sectors with high-reliability products and integrated control solutions.
Hydac International
Hydac provides hydraulic filters, accumulators, and electronic controls, emphasizing technological innovation and sustainable product development to meet the stringent efficiency and environmental standards.
SMC Corporation
SMC offers diverse pneumatic components and systems with a strategic focus on compact, lightweight designs, and smart automation solutions tailored for factory automation and process industries.
Coval
Coval specializes in hydraulic and pneumatic cylinders, valves, and control systems, with a focus on custom-engineered solutions and efficient manufacturing to serve North American manufacturing users.
CPC Hydraulic
CPC Hydraulic provides hydraulic equipment, including pumps, valves, and complete systems, leveraging innovative technology to improve operational efficiency and energy savings across industrial and mobile applications.
Strategic Business Developments
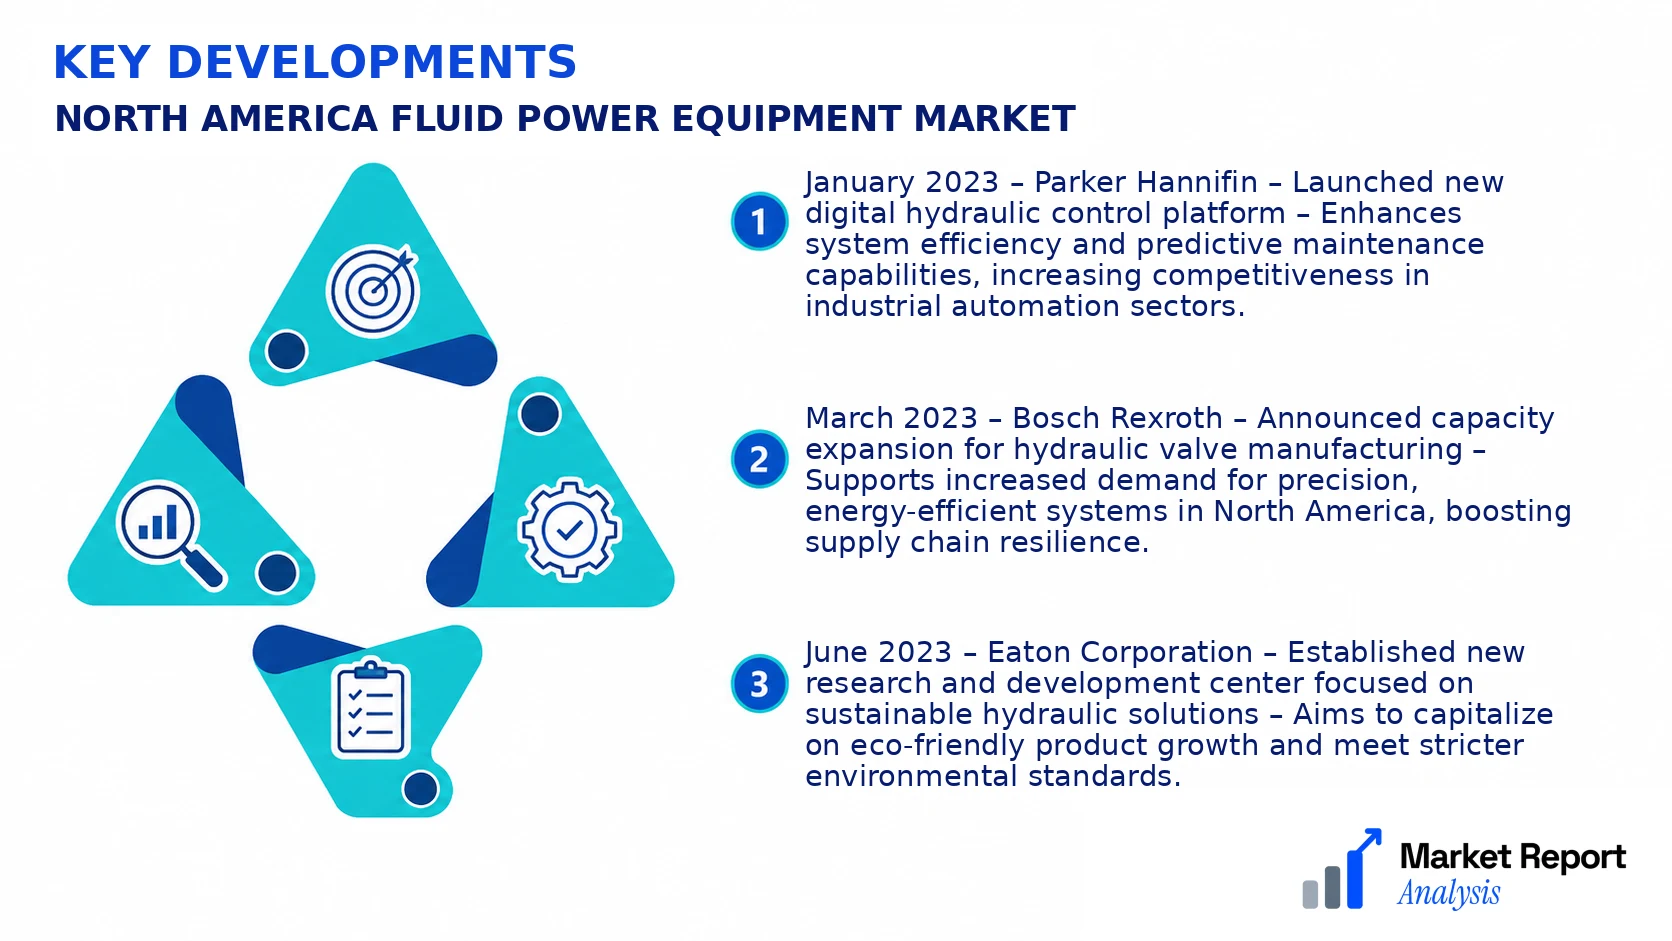
- January 2023 – Parker Hannifin – Launched new digital hydraulic control platform – Enhances system efficiency and predictive maintenance capabilities, increasing competitiveness in industrial automation sectors.
- March 2023 – Bosch Rexroth – Announced capacity expansion for hydraulic valve manufacturing – Supports increased demand for precision, energy-efficient systems in North America, boosting supply chain resilience.
- June 2023 – Eaton Corporation – Established new research and development center focused on sustainable hydraulic solutions – Aims to capitalize on eco-friendly product growth and meet stricter environmental standards.
- September 2023 – Festo AG & Co. KG – Formed strategic alliance with robotics integrators to advance smart pneumatic systems – Strengthens position in industrial automation and robotics sectors.
- December 2023 – Norgren – Completed acquisition of tech startup specializing in IoT-enabled pneumatic controls – Expands product offerings with innovative, connected systems for manufacturing sectors.
Frequently Asked Questions
What is the North America Fluid Power Equipment Market?
The North America Fluid Power Equipment Market encompasses the production and sales of hydraulic and pneumatic systems used in various industrial applications across the region, including manufacturing, construction, and transportation, driven by technological innovation and infrastructure development.
What is the current market size of North America Fluid Power Equipment Market?
As of 2026, the market valuation for North America Fluid Power Equipment stands at approximately USD 15 Billion, reflecting steady growth driven by increased demand for automation and machinery upgrades across key sectors.
What factors are driving the North America Fluid Power Equipment Market?
Market growth is propelled by technological advancements, increased industrial automation, rising investments in infrastructure, and the ongoing shift from traditional mechanical systems to fluid power solutions for efficiency and sustainability.
Which region dominates the North America Fluid Power Equipment Market?
The United States leads the North American market due to its advanced manufacturing base, technological innovation, and significant infrastructure projects, accounting for a major share of the region’s market value.
Which segment is expected to grow the fastest?
The hydraulic segment is projected to witness the fastest growth, driven by its widespread application in heavy machinery, aerospace, and mobile equipment sectors, supported by innovations in energy-efficient and high-performance hydraulic systems.
Who are the leading companies operating in the North America Fluid Power Equipment Market?
Key market players include Parker Hannifin, Bosch Rexroth, Eaton Corporation, and Caterpillar Inc., all competing through technological innovation, strategic acquisitions, and expanding their regional footprint to strengthen market positions.
Analyst Perspective
The North America Fluid Power Equipment Market is positioned for steady long-term growth driven by ongoing industrial automation, infrastructure development, and manufacturing modernization. The region's technological evolution favors smarter, more energy-efficient fluid power solutions, opening avenues for innovations in IoT-enabled and integrated systems. Major players are expected to enhance R&D investments to maintain a competitive edge amid rising industry consolidation, which is likely to intensify market rivalry. Opportunities lie in industrial automation sectors, such as automotive manufacturing and aerospace, where fluid power technology remains vital. Regionally, the U.S. will continue to be the primary growth engine, supported by robust infrastructure projects and technological adoption, while Canada and Mexico offer emerging opportunities in mining, agriculture, and energy. Strategic investment should prioritize advanced, sustainable solutions addressing energy efficiency and environmental impact, with a focus on digital transformation. Overall, the market will remain dynamic, with technological innovation and regional growth potential serving as key drivers amidst increasing competition and evolving industry standards.
