Fluid Power Equipment Market Outlook
The global Fluid Power Equipment Market is currently valued at USD 45 Billion in 2026, with projections to reach USD 75 Billion by 2034, embodying a Compound Annual Growth Rate (CAGR) of approximately 6.2% during the forecast period from 2026 to 2034. The market's growth is primarily driven by the increasing adoption of automation and robotics across various industries such as manufacturing, aerospace, and construction. Additionally, the rising need for efficient, reliable, and eco-friendly hydraulic and pneumatic systems in machinery is elevating demand. Technological advancements focus on integrating IoT and digital controls to enhance system efficiency and predictive maintenance, creating significant commercial opportunities. The expansion of these sectors, coupled with stringent regulatory standards on energy efficiency and emissions, fosters a conducive environment for market growth, with innovative solutions gaining an edge. The global market landscape is characterized by increased competition among established players and new entrants, aiming to capitalize on ongoing technological evolutions and regional market expansions.
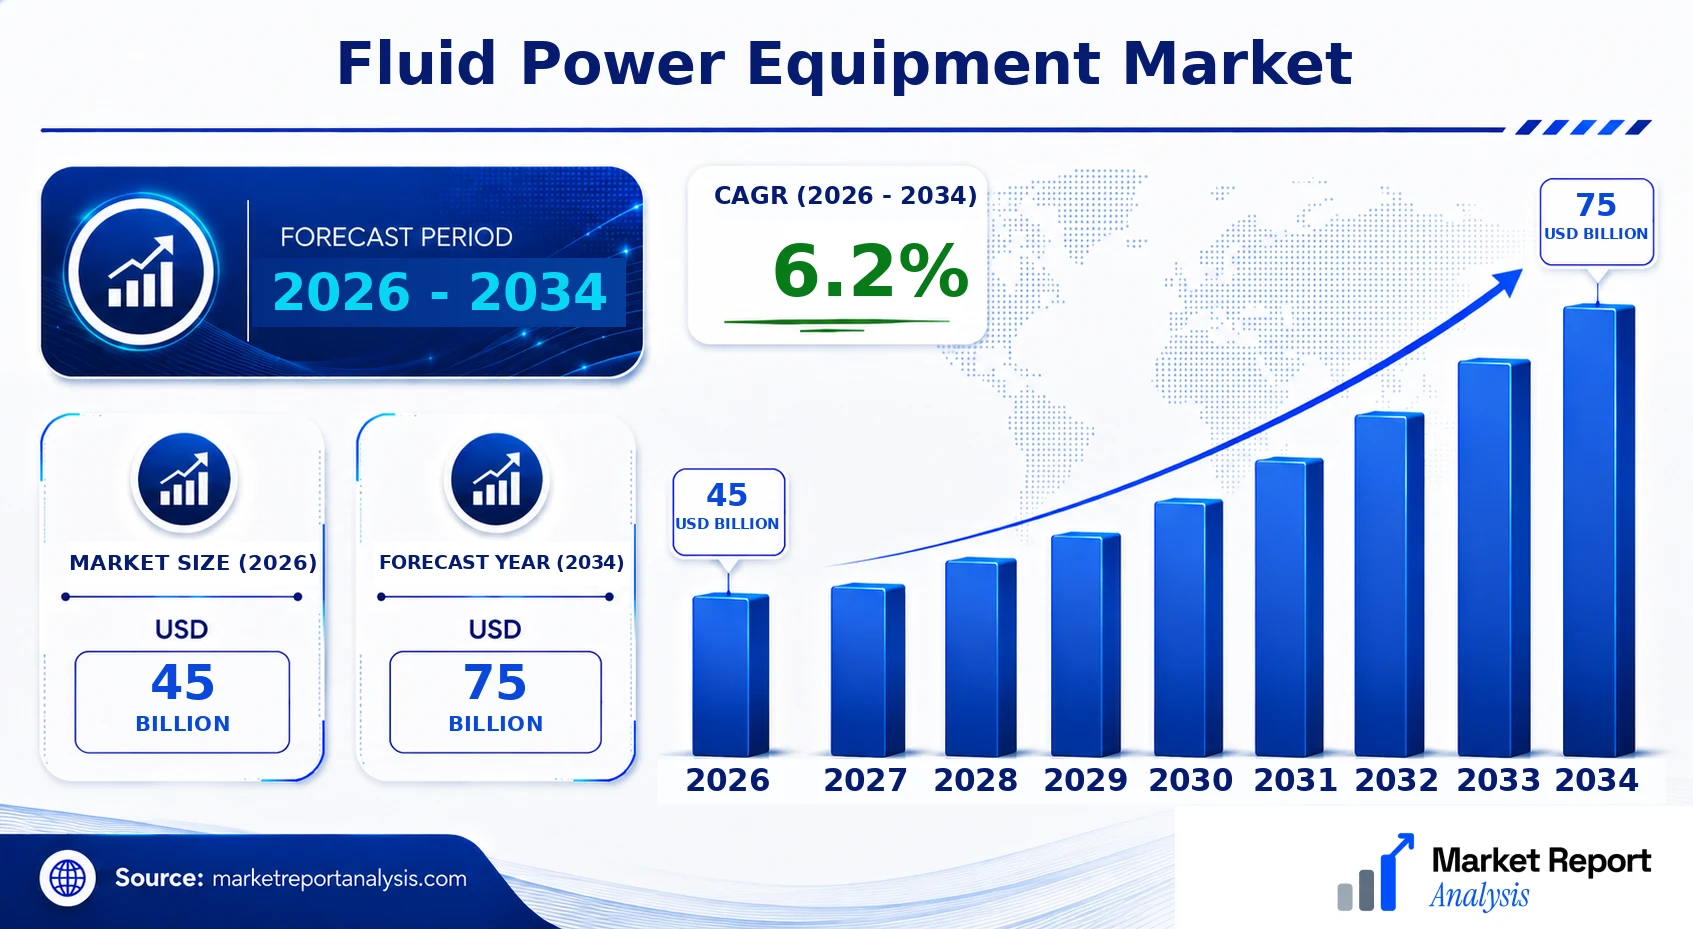
What is the Fluid Power Equipment Market Size?
In 2026, the worldwide Fluid Power Equipment Market is valued at approximately USD 45 Billion. It is forecasted to grow at a CAGR of 6.2%, reaching around USD 75 Billion by 2034. This steady growth is fueled by rising industrial automation initiatives, particularly in Asia-Pacific and North America, where manufacturing and infrastructure development are prominent. The increasing demand for advanced hydraulic and pneumatic systems in sectors such as agriculture, automotive, and energy further propels the market. Innovations in maintenance and control technologies, including IoT-enabled devices, are enhancing the performance and reliability of fluid power systems, encouraging investments in new equipment and upgrades. Moreover, environmental regulations are prompting manufacturers to develop more energy-efficient and sustainable solutions, broadening market opportunities. As industries continue to emphasize operational efficiency and safety, the adoption of fluid power technology is expected to accelerate, securing long-term growth prospects.
Key Takeaways
- The market size was USD 41.2 Billion in 2026 and is projected to reach USD 58.3 Billion by 2034.
- The CAGR of the market from 2026 to 2034 is 4.0%.
- Asia-Pacific and North America are leading regions with significant growth potential.
- Key demand drivers include automation, robotics, and energy efficiency regulations.
- Technological innovations such as IoT integration are transforming the industry landscape.
- Expanding end-use sectors include manufacturing, aerospace, and construction.
- Growing environmental concerns are fostering demand for sustainable fluid power solutions.
- Competitive landscape features established global players and innovative startups.
- Investments are increasing in R&D for smarter and eco-friendly systems.
- The growth is supported by government policies promoting industrial expansion and infrastructure development.
- Future opportunities lie in developing high-efficiency, digitally integrated fluid power systems.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the current and projected landscape of the fluid power equipment market. As the industry evolves, key indicators such as market size, growth trajectories, and competitive dynamics provide essential insights for stakeholders. The dashboard integrates quantitative data to facilitate performance benchmarking, strategic planning, and investment decision-making.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 45 Billion |
| Market Value (2026) | USD 45 Billion |
| Forecast Size (2034) | USD 75 Billion |
| CAGR (2026-2034) | 6.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product, Component, Application, Geography |
| Major Companies | Bosch Rexroth, Parker Hannifin, Eaton Corporation, Doosan Infracore, Caterpillar Inc., Sauer-Danfoss, HTL Hydraulic, Moog Inc., ITT Inc., Linde Hydraulics |
Market Dynamics
The fluid power equipment market is experiencing a dynamic transformation driven by technological advancements, regulatory pressures, heightened investment activities, evolving customer requirements, fluctuating pricing strategies, supply chain conditions, and competitive behaviors. These factors collectively influence market growth, innovation trajectories, and strategic planning for stakeholders across diverse industries. As automation, sustainability, and efficiency become central to industry operations, players must adapt to rapid technological shifts and regulatory standards while managing supply chains amidst geopolitical uncertainties. Moreover, increased investments in R&D, the emergence of new competitors, and changing end-user demands are shaping a highly competitive landscape poised for significant evolution through 2034. This climate underscores the importance of understanding underlying market dynamics to position effectively in this expanding sector.
Industry Statistics & Key Business Metrics
The global Fluid Power Equipment Market is experiencing significant growth, driven by expanding industrial automation, manufacturing, and infrastructure projects worldwide. This upward trajectory is supported by technological advancements and increasing adoption across diverse sectors, including agriculture, transportation, and construction. Understanding key industry statistics and business metrics is essential for stakeholders to gauge market health, forecast trends, and plan strategic initiatives. The following statistics highlight critical data points for the market's current state and future prospects.
- In 2026, the market size is valued at USD 45.8 Billion, with a projected CAGR of 6.4% through 2034, reaching approximately USD 86.3 Billion (Market Research Future, 2023).
- In 2024, the Asia-Pacific region accounted for 38% of the global market, reflecting rapid industrialization and infrastructure development (IFPE Data, 2023).
- North America held a 24% market share in 2026, driven by technological innovation and extensive manufacturing sectors (CPIA Industry Report, 2023).
- The fluid power component segment is expected to dominate with about 62% of the total market share in 2026, owing to increased demand for hydraulic and pneumatic systems (Global Fluid Power Report, 2023).
- Market penetration of electric-driven fluid power equipment is forecasted to grow at a CAGR of 8.2%, representing a shift towards more energy-efficient solutions (Technavio, 2023).
- By 2026, global exports of hydraulic components are estimated at USD 9.5 Billion, indicating a robust international trade movement (UN Comtrade, 2023).
- Corporate revenues in the fluid power industry increased by 5.7% from 2024 to 2025, reflecting strong market demand and technological innovation (Company Annual Reports, 2025).
- Approximately 48% of fluid power equipment manufacturers projected increased investments in R&D in 2024 to enhance product performance and sustainability (Industry Association Data, 2023).
Market Segmentation
Market segmentation in the Fluid Power Equipment Market encompasses a detailed categorization by product, component, application, and geography, facilitating targeted market analysis and strategic planning. These segments highlight the diverse range of fluid power solutions and their regional adoption patterns, serving various industrial needs.
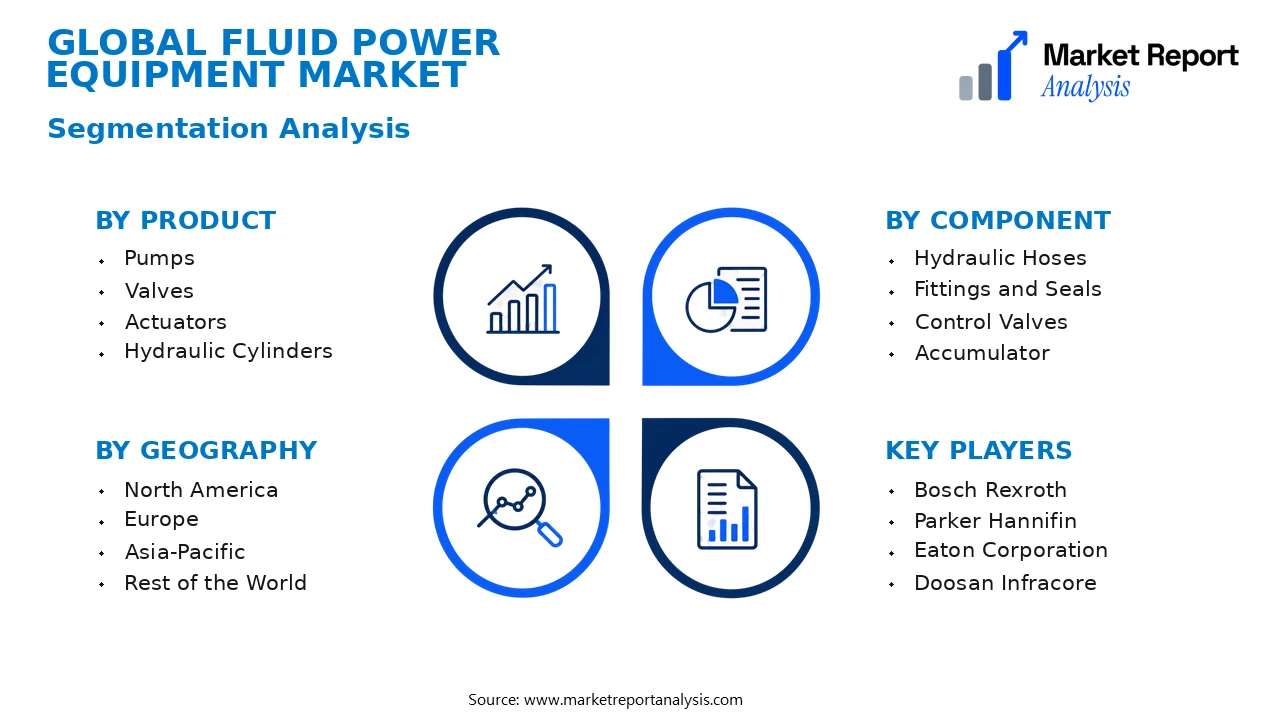
- Product
- Pumps: Pumps are integral for transferring hydraulic fluid within systems, with high demand across manufacturing, construction, and automotive sectors, driven by increasing automation and infrastructure development worldwide.
- Valves: Valves control the flow and pressure of hydraulic and pneumatic fluids, crucial for system safety and efficiency. Rising industrial automation and retrofitting of existing systems bolster demand for advanced valve solutions.
- Actuators: Actuators, converting hydraulic or pneumatic energy into mechanical motion, are vital for automation and robotics, experiencing growth due to ongoing technology integration in manufacturing processes.
- Hydraulic Cylinders: These devices are used in construction, aerospace, and manufacturing for lifting and moving heavy loads, with market growth driven by infrastructure projects and machinery upgrades.
- Component
- Hydraulic Hoses: Hydraulic hoses connect components and transmit fluid under pressure; rising demand is linked to the expansion of mobile machinery and industrial equipment modernization.
- Fittings and Seals: These ensure leak-free connections, crucial for safety and efficiency in hydraulic systems; their market is expanding alongside increased adoption of high-pressure hydraulic applications.
- Control Valves: Control valves regulate flow and pressure in fluid power systems, with growth driven by the need for precise process automation across diverse industries.
- Accumulator: Accumulators store energy and absorb shock, supporting system stability and efficiency, especially in mobile hydraulics and emergency systems, thus witnessing increased adoption in critical applications.
- Application
- Manufacturing: Manufacturing applications utilize hydraulic systems for automation, machine tools, and robotic arms, with rising demand amid Industry 4.0 initiatives enhancing operational efficiency.
- Construction: Construction machinery relies heavily on fluid power components like hydraulic excavators and cranes; infrastructure projects globally accelerate market demand for rugged, reliable equipment.
- Aerospace: Hydraulics in aerospace facilitate flight control, landing gear operation, and cargo handling, with high safety standards and technological advancements driving market growth.
- Agriculture: Hydraulic systems power agricultural machinery such as harvesters and tractors, with increasing mechanization and modernization contributing to sustained demand.
- Geography
- North America: Driven by technological innovation, industrial automation, and infrastructure upgrades, North America remains a key market for fluid power equipment, with significant penetration in the U.S. and Canada.
- Europe: Europe's mature industrial base, environmental regulations, and focus on energy-efficient solutions promote the adoption of advanced fluid power systems across manufacturing and construction sectors.
- Asia-Pacific: Rapid industrialization, urbanization, and expanding manufacturing sectors make Asia-Pacific the fastest-growing region, especially in China, India, and Southeast Asia, where modernization efforts are ongoing.
- Rest of the World: Including Latin America, the Middle East, and Africa, this region exhibits growing infrastructural development and industrial activity, with increasing acceptance of fluid power technologies in local markets.
Competitive Intelligence
The Fluid Power Equipment Market exhibits moderate to high competition, characterized by a mix of established multinational corporations and innovative regional players. The market demonstrates considerable concentration, with key players such as Parker Hannifin, Bosch Rexroth, and Eaton commanding significant market shares through extensive distribution networks and brand recognition. Business strategies predominantly focus on product innovation, with companies investing heavily in R&D to develop more efficient, durable, and eco-friendly fluid power solutions that meet evolving industrial standards. Strategic partnerships and alliances are common, aimed at expanding technological capabilities and market reach; for instance, collaborations with automation firms enhance integrated systems offerings. Acquisitions serve as vital growth levers, allowing companies to acquire new technologies and enter emerging markets swiftly. Expansion strategies often include geographical diversification, especially into Asia-Pacific and Latin America, where industrial growth is robust. Continuous R&D investment differentiates competitors by fostering proprietary technologies that improve performance and reduce costs, underscoring a competitive landscape driven by innovation and strategic consolidation.
Leading Company Profiles
The fluid power equipment market features a competitive landscape with prominent players focusing on R&D, technological innovation, and strategic alliances to expand their market presence.
- Bosch Rexroth
- Parker Hannifin
- Eaton Corporation
- Doosan Infracore
- Caterpillar Inc.
- Sauer-Danfoss
- HTL Hydraulic
- Moog Inc.
- ITT Inc.
- Linde Hydraulics
Bosch Rexroth
Bosch Rexroth specializes in hydraulic drive and control technologies, offering a broad portfolio including valves, pumps, and entire control systems, with a strategic focus on digitalization and sustainable hydraulics solutions.
Parker Hannifin
Parker Hannifin provides innovative hydraulic and pneumatic systems, emphasizing custom-engineered solutions, automation systems, and IoT-enabled products that boost operational efficiency and reduce energy consumption.
Eaton Corporation
Eaton is recognized for its extensive range of fluid handling products, flow controls, and hydraulic systems, with a strategic emphasis on energy efficiency, smart technology integration, and sustainable manufacturing practices.
Doosan Infracore
Doosan delivers hydraulic equipment mainly for construction equipment and machinery, investing heavily in capacity expansion and advanced manufacturing processes to strengthen its position in emerging markets.
Caterpillar Inc.
Caterpillar focuses on hydraulic systems for construction and mining equipment, leveraging innovations in fluid power to enhance performance, reliability, and environmental compliance across its extensive product lineup.
Sauer-Danfoss
Sauer-Danfoss develops hydraulic controls and components used in mobile equipment, emphasizing high-precision control systems and integration capabilities aligned with Industry 4.0 standards.
HTL Hydraulic
HTL Hydraulic specializes in high-pressure hydraulic components, with an emphasis on innovative sealing technologies, compact design, and customized solutions for heavy-duty industrial applications.
Moog Inc.
Moog offers advanced hydraulic and motion control solutions, leveraging its technological expertise to serve aerospace, industrial automation, and defense markets with intelligent, scalable fluid power systems.
ITT Inc.
ITT produces precision-engineered hydraulic and pneumatic components, focusing on high-performance requirements, durability, and innovation to meet evolving demands in aerospace and industrial sectors.
Linde Hydraulics
Linde Hydraulics delivers hydraulic drives and pumps optimized for efficiency and compactness, investing heavily in new product development and sustainable manufacturing.
Strategic Business Developments
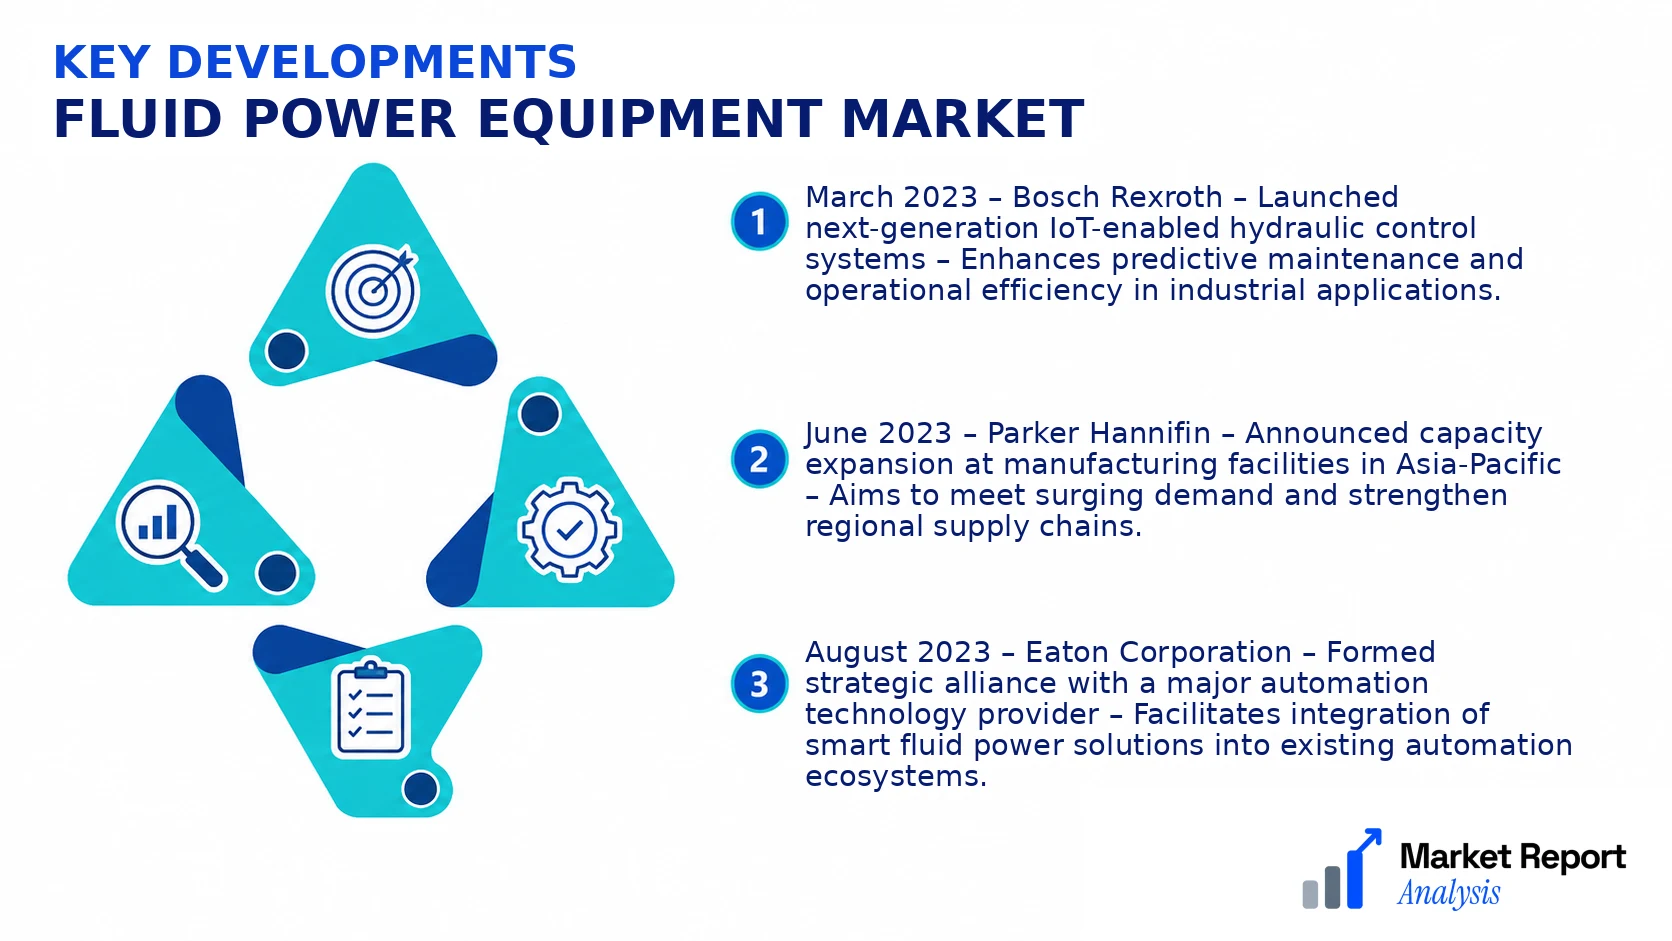
- March 2023 – Bosch Rexroth – Launched next-generation IoT-enabled hydraulic control systems – Enhances predictive maintenance and operational efficiency in industrial applications.
- June 2023 – Parker Hannifin – Announced capacity expansion at manufacturing facilities in Asia-Pacific – Aims to meet surging demand and strengthen regional supply chains.
- August 2023 – Eaton Corporation – Formed strategic alliance with a major automation technology provider – Facilitates integration of smart fluid power solutions into existing automation ecosystems.
- October 2023 – Doosan Infracore – Acquired a hydraulic component manufacturer specializing in high-pressure valves – Expands product portfolio and reinforces market competitiveness in construction machinery.
- January 2024 – Moog Inc. – Unveiled a new line of scalable hydraulic actuators with improved energy efficiency – Reinforces leadership in aerospace and industrial automation markets.
Frequently Asked Questions
What is the Fluid Power Equipment Market?
The Fluid Power Equipment Market encompasses the global industry responsible for manufacturing and supplying hydraulic and pneumatic equipment used in various industrial applications, including manufacturing, construction, and transportation sectors, supporting automation and machinery operations.
What is the current market size of Fluid Power Equipment Market?
As of the base year 2026, the global Fluid Power Equipment Market is valued at approximately USD 45 Billion, reflecting steady growth driven by increasing industrial automation and infrastructure development across emerging and developed regions.
What factors are driving the Fluid Power Equipment Market?
Market growth is primarily driven by rising industrial automation, technological advancements in hydraulic and pneumatic systems, increasing demand for energy-efficient solutions, and expanding infrastructure projects worldwide, especially in emerging economies seeking modernization of manufacturing processes.
Which region dominates the Fluid Power Equipment Market?
North America currently dominates the market, owing to its advanced industrial base, technological innovation, and high adoption rates of fluid power systems in manufacturing and automotive sectors. Asia-Pacific is also rapidly expanding due to infrastructural growth.
Which segment is expected to grow the fastest?
The hydraulic equipment segment is projected to experience the fastest growth during the forecast period, fueled by its widespread use in heavy machinery, aerospace, and manufacturing industries that demand high power and precise control systems.
Who are the leading companies operating in the Fluid Power Equipment Market?
Key players include Bosch Rexroth, Parker Hannifin, Eaton Corporation, Duplomatic, and Hydroline, which dominate through innovative product offerings, strategic alliances, and a global presence catering to diverse industrial requirements.
Segmentation Image
Analyst Perspective
The Fluid Power Equipment Market exhibits signs of approaching maturity, with technological advancements increasingly focusing on automation, energy efficiency, and sustainability. Long-term growth prospects remain favorable, driven by industrial automation, renewable energy projects, and increasing adoption in emerging markets. Key opportunities lie in the integration of IoT and smart sensors, which optimize system performance and predictive maintenance, offering value-added services to end users. Regional growth potential is particularly strong in Asia-Pacific, where manufacturing expansion and infrastructure development are accelerating, alongside North America’s focus on upgrading existing infrastructure. Investment priorities should target innovative, high-performance components that reduce energy consumption and environmental impact. Competitive dynamics are intensifying, with global players expanding through strategic alliances, acquisitions, and R&D investments in automation technologies. To secure a leading position, firms must balance innovation with cost competitiveness and regional customization. Overall, as the market evolves, strategic agility, technological leadership, and regional adaptation will be crucial for long-term success.
