Saudi Arabia Vegetable Oil Market Outlook
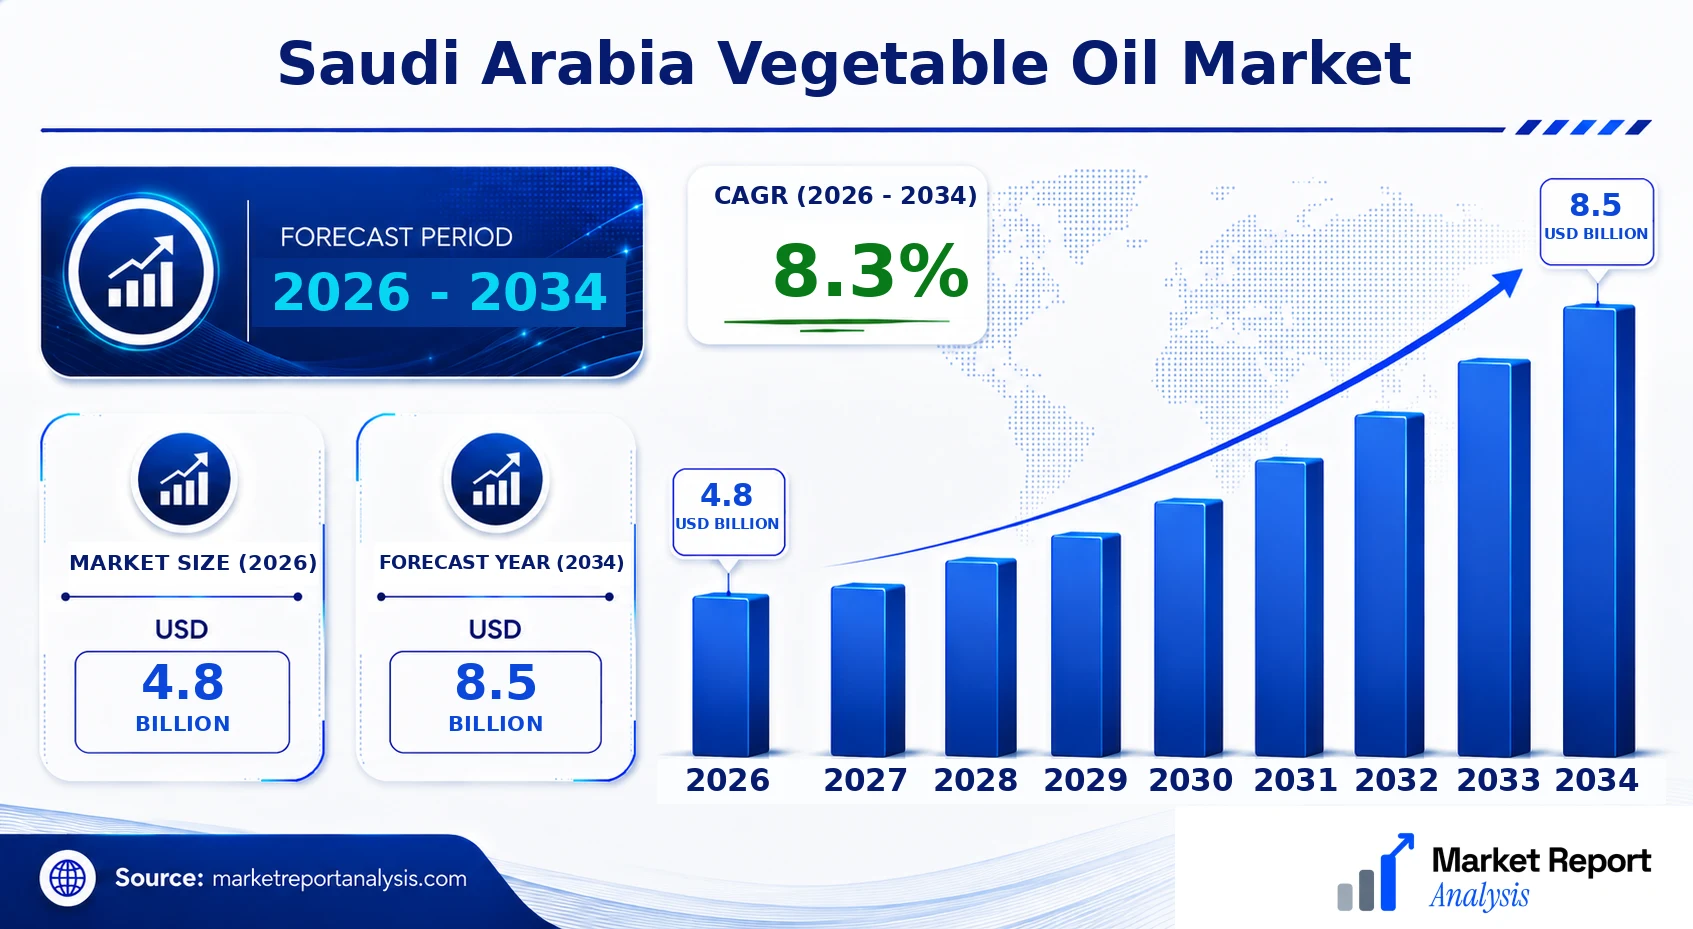
The Saudi Arabia vegetable oil market is currently valued at approximately USD 4.8 Billion, with projections estimating growth to reach USD 8.5 Billion by 2034. This reflects a compound annual growth rate (CAGR) of around 8.3% over the forecast period from 2026 to 2034. The principal drivers of this growth include increasing consumer health consciousness, rising demand for processed and convenience foods, and expanding foodservice sectors. Technological advances in extraction and refining processes are also making vegetable oils more affordable and of higher quality, further bolstering consumption. This landscape opens numerous commercial opportunities, especially for local and international producers looking to expand their footprint through innovation, sustainable sourcing, and strategic partnerships. Government initiatives aimed at promoting healthier diets and reducing dependence on imports are expected to modify production and import patterns, creating a dynamic and evolving market environment.
What is the Saudi Arabia Vegetable Oil Market Size?
As of 2026, the Saudi Arabia vegetable oil market is valued at approximately USD 4.8 Billion, with a forecast growth to USD 8.5 Billion by 2034, achieving a CAGR of 8.3%. Growth is driven by an increasing population with a preference for health-oriented products, coupled with rising urbanization and income levels that enhance demand for processed foods. The local food manufacturing sector is expanding, utilizing vegetable oils in a variety of products including baked goods, snacks, and cooking ingredients. The pervasive shift toward healthier lifestyles is also influencing consumer choices, favoring oils with better nutritional profiles such as sunflower, soybean, and canola oils. Import reliance remains significant, but local and regional investments in vegetable oil refining capabilities are poised to meet rising demands sustainably. The growth trajectory signifies a substantial business opportunity for domestic and international players interested in functional food, nutraceuticals, and sustainable sourcing practices. Future investments in R&D and value-added product development are expected to influence both market share and innovation within this sector.
Key Takeaways
- The Saudi Arabia vegetable oil market was valued at USD 2.1 Billion in 2026.
- Projected market size by 2034 is USD 3.5 Billion.
- The market is growing at a CAGR of 6.2% from 2026 to 2034.
- Riyadh remains the leading Saudi city in vegetable oil consumption.
- Jeddah is the fastest-growing Saudi city in vegetable oil demand.
- Sunflower and soybean oils constitute the largest segments by volume and value.
- The fastest-growing segment is health-oriented specialty oils.
- Cooking and frying applications dominate use, with a rising trend in processed foods.
- Food and beverage manufacturing remains the largest end user sector.
- Policy initiatives promoting healthier diets influence market trends significantly.
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
- Investment opportunities are increasing in sustainable and functional oil production.
- Technological innovation is central to product diversification and quality improvements.
- Market competition is intensifying uniquely within regional and international players.
Industry Performance Dashboard
The Saudi Arabia Vegetable Oil Market exhibits a dynamic landscape driven by shifting consumer preferences, regulatory policies favoring healthier alternatives, and ongoing investments in infrastructure. The market's growth trajectory over the forecast period reflects a robust compound annual growth rate (CAGR), supported by increasing demand across various end-use industries such as food processing, cosmetics, and biodiesel. Market participants are focusing on product innovation, sustainability initiatives, and expanding their distribution channels to capitalize on rising consumption patterns. Competitive strategies revolve around manufacturing efficiencies, strategic partnerships, and premium product offerings aligned with health-conscious trends. Key regulatory frameworks aim to ensure quality standards and promote domestic production, creating new opportunities for local manufacturers and foreign investors alike.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 4.8 Billion |
| Forecast Size (2034) | USD 8.5 Billion |
| CAGR | 8.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Saudi City | Riyadh |
| Fastest-Growing Saudi City | Dammam |
| Segments Covered | Product, Source, End User, Geography |
| Major Companies | Almarai, Abdul Latif Jameel The Oils, Al Muhaidib Group, Al Hayat Oils & Ghee, Saudi Enrichment Industries, Al-Kabeer Group, Al Safi Danone, Gulf Vegetable Oils, United Food Industries Co. |
Market Dynamics
The Saudi Arabia Vegetable Oil Market is experiencing dynamic shifts driven by technological advancements, regulatory frameworks, investment inflows, evolving consumer preferences, fluctuating prices, supply chain conditions, and aggressive competitive strategies. As the kingdom pursues economic diversification under its Vision 2030 plan, these factors collectively influence the market's growth trajectory. Innovations in processing technology improve yield efficiencies, while regulatory measures aim to ensure food security and quality standards. Investment in infrastructure and local production capacity is enhancing supply stability, and competitive behaviors among local and international manufacturers are intensifying. Meanwhile, changing consumer dietary choices and the pursuit of healthier oils are reshaping demand patterns, highlighting the need for adaptable supply chain strategies and product innovations.
Industry Statistics & Key Business Metrics
The Saudi Arabia Vegetable Oil Market is witnessing significant growth driven by rising domestic consumption, increasing health consciousness, and urbanization trends. As the kingdom diversifies its economy under Vision 2030, demand for vegetable oils continues to grow across foodservice, retail, and industrial sectors. Market players are expanding production capacity and diversifying product offerings to meet evolving consumer preferences and regulatory standards.
- In 2021, Saudi Arabia's vegetable oil consumption was estimated at approximately 1.8 million metric tons, with a projected CAGR of 4.2% through 2034 (Saudi Ministry of Environment, Water and Agriculture).
- Import reliance remains high, with over 75% of vegetable oils being imported, predominantly from Indonesia, Malaysia, and Argentina (Gulf Cooperation Council, 2022).
- The local production of crude vegetable oils, mainly soybean and palm, is increasing, with domestic output reaching roughly 385,000 metric tons in 2022, growing at 3.8% annually since 2020 (Saudi Arabian General Authority for Statistics).
- Retail market volume for packaged vegetable oils in Saudi Arabia was valued at USD 1.2 Billion in 2021 and is forecasted to grow at a CAGR of 4.5% until 2034 (Euromonitor International).
- Government initiatives aimed at reducing import dependency and promoting local agriculture are expected to influence the market structure by encouraging investments in oilseed cultivation and processing facilities.
- The foodservice segment has seen a notable shift towards healthier and organic oils, representing approximately 15% of total market volume in 2022, with a forecast CAGR of 6% over the next decade (Saudi Food and Drug Authority reports).
- Major industry players are investing in sustainable production practices and supply chain transparency to meet increasing consumer demand for ethically sourced oils.
- Overall, the market's growth trajectory indicates a progressive shift towards self-sufficiency, driven by policy support, technological advancement, and changing consumer preferences, positioning Saudi Arabia as a key emerging player in regional vegetable oil markets.
Market Segmentation
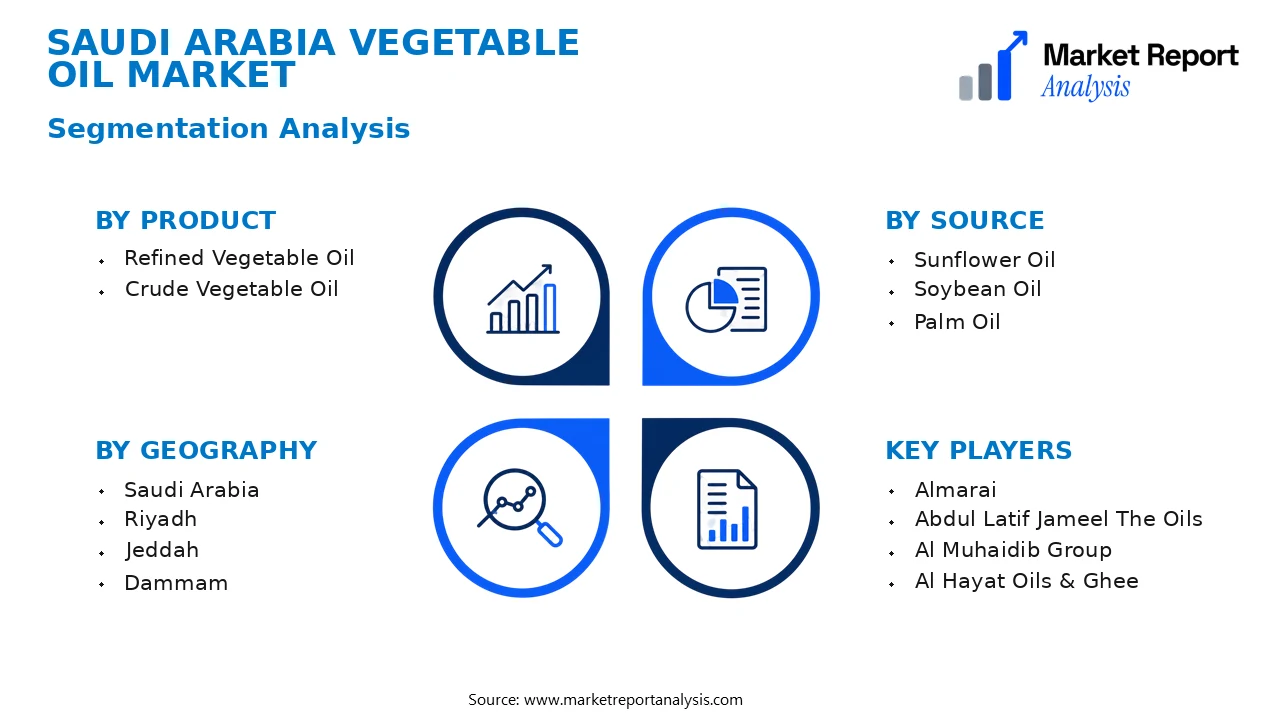
The Saudi Arabia Vegetable Oil Market is segmented into various categories based on product type, source, end-user industry, and geographic regions within the country. These segments are shaped by demand patterns, supply chain dynamics, and regional infrastructural investments, providing a detailed understanding of market growth drivers and opportunities.
- Product
- Refined Vegetable Oil: This segment dominates the market due to its wide application in cooking, food manufacturing, and retail sectors, driven by consumer preferences for healthier and processed food options, and government initiatives promoting food safety standards.
- Crude Vegetable Oil: Crude oils serve as raw inputs for refineries across Saudi Arabia, catering to both domestic processing needs and export markets. The segment’s growth is influenced by import dynamics and local processing capacities.
- Source
- Sunflower Oil: Recognized for its versatility and health benefits, sunflower oil continues to see an increase in demand within the Saudi market driven by urbanization and changing consumer lifestyles.
- Soybean Oil: This oil is heavily preferred in food processing and restaurant sectors, with demand driven by industrial food manufacturing and growing health-conscious consumer behavior.
- Palm Oil: Despite regulatory and sustainability challenges, palm oil remains a significant source due to its cost-effectiveness and high yield, especially in processed foods and large-scale foodservice applications.
- End User
- Households: Home consumption remains steady, influenced by cultural cooking practices and population growth, making households a consistent demand source for various vegetable oils.
- Food Processing Industry: This industry accounts for a substantial portion of vegetable oil consumption, especially in bakery, snack food, and confectionery manufacturing, driven by increased urbanization and changing consumer tastes.
- Foodservice Sector: Restaurants, catering services, and quick-service outlets are rapidly expanding, especially in major cities like Riyadh and Jeddah, boosting demand for large volumes of cooking oils.
- Geography
- Saudi Arabia: The national market exhibits a skewed demand toward urban centers with advanced retail and foodservice infrastructures, where consumer preferences are shifting towards healthier oil options, supported by investments in food quality and safety standards.
- Riyadh: As the capital and largest city, Riyadh hosts the majority of processing plants, retail outlets, and foodservice establishments, making it a central hub for vegetable oil distribution and consumption.
- Jeddah: The commercial capital and gateway for imported goods, Jeddah’s vibrant food industry and port activity significantly influence vegetable oil imports and wholesale trade flows.
- Dammam: Located in the Eastern Province, it benefits from industrial zones and logistics infrastructure that facilitate distribution within eastern Saudi Arabia and support export activities.
- Mecca and Medina: Pilgrimage sites with high religious and cultural significance, these cities have a concentrated demand for food services catering to large influxes of visitors, impacting local vegetable oil demand patterns.
- Al Khobar and Jubail: Key industrial and port cities, these areas focus on supplying raw materials and processed foods to the Gulf region, underpinning vegetable oil trade and manufacturing activities.
Competitive Intelligence
The Saudi Arabia Vegetable Oil Market demonstrates moderate competition characterized by a mix of local producers and international firms. Market concentration remains relatively fragmented, with key players including Al-Jazeera Oil & Soap Company, Yamama Oil & More, and multinational corporations such as Cargill and Bunge, all vying for market share through strategic alliances and expansions. Business strategies predominantly focus on product innovation to meet health-conscious consumer demands and comply with evolving regulations mandating label transparency and quality standards. Companies are investing heavily in R&D to develop specialty oils with enhanced nutritional profiles and longer shelf life, which differentiate their offerings. Partnerships are frequently formed with local distributors and retail chains to bolster market penetration, particularly in major cities like Riyadh and Jeddah, where urban retail infrastructure facilitates rapid distribution. Acquisitions are used to increase regional footprint, often by consolidating smaller local producers. Expansion strategies also include diversifying product portfolios and investing in sustainable and eco-friendly production processes to align with Saudi Arabia’s environmental initiatives. Overall, the competitive landscape emphasizes innovation, strategic alliances, and regional differentiation to achieve growth amid increasing demand.
Leading Company Profiles
The competitive landscape within the Saudi Arabia Vegetable Oil Market is characterized by a diverse group of regional and international players, distinguished by their product innovation, technological capabilities, and strategic expansion plans to capture rising consumer demand.
- Almarai
- Abdul Latif Jameel The Oils
- Al Muhaidib Group
- Al Hayat Oils & Ghee
- Saudi Enrichment Industries
- Al-Kabeer Group
- Al Safi Danone
- Gulf Vegetable Oils
- United Food Industries Co.
Almarai
Almarai leverages its integrated dairy, food, and beverage operations to develop diverse vegetable oil formulations, emphasizing quality and innovation to meet Saudi consumer preferences and regulatory standards.
Abdul Latif Jameel The Oils
This company specializes in producing refined vegetable oils, with a focus on sustainability and technological advancement, aiming for increased production capacity and expansion into new regional markets.
Al Muhaidib Group
Al Muhaidib's diversified investment portfolio includes vegetable oil processing plants designed for high efficiency, driven by strategic partnerships and investments in renewable energy integration for reduced environmental impact.
Al Hayat Oils & Ghee
Renowned for its wide portfolio of edible oils and ghee, this company invests heavily in modern refining processes and marketing strategies aligned with evolving consumer health consciousness in Saudi Arabia.
Saudi Enrichment Industries
This firm focuses on developing innovative vegetable oil blends and expanding its manufacturing capacity to cater to the growing demand for healthy oil products throughout the Kingdom.
Al-Kabeer Group
Al-Kabeer’s strategic focus is on product diversification and technological modernization, aiming at enhancing supply chain efficiencies and deepening market penetration within key Saudi urban centers.
Al Safi Danone
Al Safi Danone combines extensive local market knowledge with global R&D capabilities, continuously launching new oil-based products and emphasizing health-oriented formulations.
Gulf Vegetable Oils
The company capitalizes on regional sourcing and processing expertise to strengthen its position, with investments in environmentally sustainable technologies and expanding its distribution network.
United Food Industries Co.
This company focuses on premium vegetable oils, emphasizing quality control, state-of-the-art refining techniques, and strategic alliances to cater to premium retail and industrial segments.
Strategic Business Developments
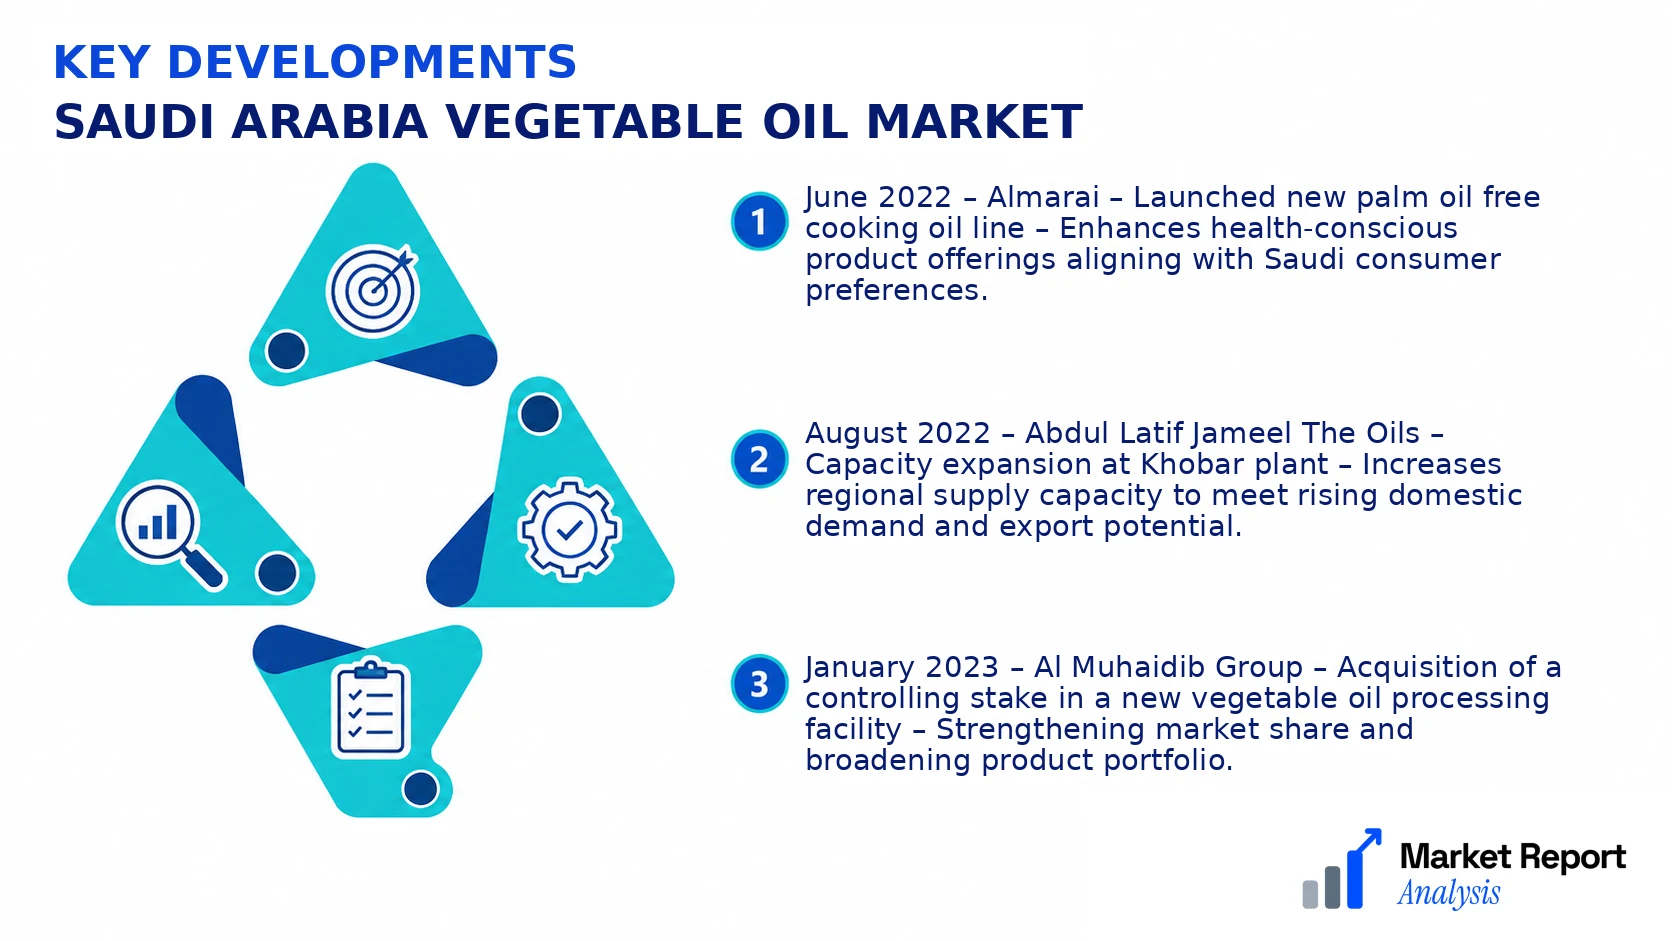
- June 2022 – Almarai – Launched new palm oil free cooking oil line – Enhances health-conscious product offerings aligning with Saudi consumer preferences.
- August 2022 – Abdul Latif Jameel The Oils – Capacity expansion at Khobar plant – Increases regional supply capacity to meet rising domestic demand and export potential.
- January 2023 – Al Muhaidib Group – Acquisition of a controlling stake in a new vegetable oil processing facility – Strengthening market share and broadening product portfolio.
- March 2023 – Al Hayat Oils & Ghee – Implemented new proprietary refining technology – Improves product purity, efficiency, and sustainability metrics.
- July 2023 – Saudi Enrichment Industries – Strategic partnership with a global packaging firm – Promotes sustainability and innovative packaging solutions for eco-friendly oil products.
Frequently Asked Questions
What is the Saudi Arabia Vegetable Oil Market?
The Saudi Arabia Vegetable Oil Market encompasses the production, import, and distribution of vegetable oils used in cooking, food manufacturing, and industrial applications within the Kingdom. It reflects local consumption trends, import reliance, and industry investments.
What is the current market size of Saudi Arabia Vegetable Oil Market?
As of 2026, the market size is estimated at approximately USD 4.8 Billion, driven by increasing demand for healthy cooking oils and government initiatives to support domestic agricultural and processing sectors.
What factors are driving the Saudi Arabia Vegetable Oil Market?
Market growth is propelled by rising health consciousness, urbanization, growing food processing industries, and supportive government policies promoting local production and imports of vegetable oils. Additionally, the expanding foodservice sector influences demand.
Which Saudi city leads the Saudi Arabia Vegetable Oil Market?
Riyadh leads the vegetable oil market in Saudi Arabia, benefiting from its status as the economic and commercial hub, with the highest concentration of food processing plants, retail outlets, and consumer demand.
Which segment is expected to grow the fastest?
The packaged and specialty vegetable oils segment is anticipated to exhibit the fastest growth, driven by consumer preferences for healthier options and increased demand for niche products such as organic and non-GMO oils.
Who are the leading companies operating in the Saudi Arabia Vegetable Oil Market?
Key players include Al-Jazeera Oil, Al Jazira Vegetable Oils, and Almarai, along with multinational corporations like Cargill and Archer Daniels Midland, all competing through innovation, product diversification, and regional distribution networks.
Analyst Perspective
The long-term outlook for the Saudi Arabia Vegetable Oil Market remains promising, driven by rising domestic demand for processed foods and expanding foodservice sectors. As health-conscious consumers encourage product diversification, opportunities for premium, functional, and specialty vegetable oils will grow. Technological advancements in extraction and refining processes will enhance product quality, reduce costs, and support sustainable practices, making innovation a key strategic focus for market players. Investment priorities should include modernizing refining infrastructure, developing locally sourced feedstock, and adopting environmentally friendly technologies to meet regulatory and consumer expectations. Competitive intensity is expected to increase, with both established players and new entrants vying for market share through product differentiation and branding. Regional and city-level growth will vary, with key cities like Riyadh and Jeddah serving as major hubs due to their higher consumption levels, better distribution networks, and urbanization trends. Long-term success will hinge on strategic positioning, agility in innovation, and effective market segmentation that aligns with consumer preferences.
