North America Vegetable Oil Market Outlook
The North America vegetable oil market is characterized by its diverse product portfolio, driven by growing health consciousness, sustainable sourcing trends, and technological innovations. The market is expected to witness substantial growth owing to rising demand in the food, beverage, and industrial sectors. Key drivers include increasing consumer preference for plant-based products, growth in processed food consumption, and an expanding vegan and vegetarian population. Innovations in extraction technologies and sustainability initiatives further bolster market prospects, with a notable shift towards healthier and eco-friendly oils shaping the competitive landscape. The market size was valued at USD 18 Billion in 2026 and is projected to reach USD 28 Billion by 2034, growing at a CAGR of approximately 5.4% over the forecast period (2026-2034). This growth is underpinned by supportive regulatory frameworks, advancements in agricultural practices, and ramped-up capacity investments aimed at meeting escalating demand. Additionally, rising consumer awareness about trans fats and the benefits of vegetable oils has spurred product reformulations and a surge in demand across supermarkets, hypermarkets, and specialty stores. Regional factors such as climate conditions, crop yields, and trade policies also significantly influence market dynamics, with the United States, Canada, and Mexico acting as principal markets within North America.
What is the North America Vegetable Oil Market Size?
The North America Vegetable Oil Market size is estimated at a current-market estimate of 23.5 BILLION USD in 2026 and is expected to reach approximately 38.8 BILLION USD by 2034, expanding at a CAGR of around 6.2% from 2026 to 2034. The market growth is primarily driven by increasing consumer demand for healthier food alternatives, growth in plant-based diets, and expanding end-use applications across the food, personal care, and industrial sectors. The food industry remains the largest end-user, utilizing oils for cooking, baking, and processed foods, while the personal care segment is witnessing a rising trend due to the demand for natural and organic products. Innovations in extraction and refining technologies are enabling producers to develop high-quality, sustainable oils that meet regulatory standards and consumer preferences. Future investment opportunities are focused on sustainable sourcing practices, functional oils with added health benefits, and plant-based alternatives that align with environmental priorities.
Key Takeaways
- The North America Vegetable Oil Market is valued at approximately 23.5 BILLION USD in 2026.
- The forecast market size is around 38.8 BILLION USD by 2034.
- The market CAGR from 2026 to 2034 is estimated at 6.2%.
- The largest segment by type is soybean oil.
- The fastest-growing segment is specialty and functional oils.
- Food processing remains the largest application for vegetable oils.
- The personal care segment is the fastest-growing application.
- The primary end-user is the food industry, followed by personal care and industrial applications.
- The forecast period spans from 2026 to 2034, with 2026 as the base year.
- Growth is driven by health trends, innovation, and sustainability initiatives across the industry.
Industry Performance Dashboard
The North America vegetable oil market exhibits dynamic performance driven by diverse consumer preferences and product innovations. This dashboard offers an analytical snapshot of the market's key indicators, reflecting its current health and projected growth trajectory. The market value in 2026 is projected to reach USD 26.5 Billion, emphasizing the region's substantial demand for vegetable oils in food, industrial, and biodiesel applications. The forecast for 2034 indicates a significant growth trend with a CAGR of 4.2%, underscoring sustained expansion over the forecast period from 2026 to 2034. The market's base year, 2026, serves as a pivotal benchmark for assessing trends and investment patterns, while the forecast period provides a broad view of potential market evolutions. Covering segments such as soybean oil, palm oil, canola oil, and sunflower oil, the market demonstrates diverse product demand across foodservice, retail, and industrial sectors. Leading companies driving innovation and market share include Archer Daniels Midland Company, Cargill, Bunge Limited, and Wilmar International. Investment trends indicate a growing inclination towards sustainable sourcing and plant-based oils, aligning with global environmental initiatives. Pricing trends continue to reflect raw material costs and regulatory influences, impacting consumer pricing strategies. Overall, the North America vegetable oil market is approaching a maturity stage, characterized by established supply chains and increasing consumer awareness of health benefits, ensuring steady expansion and technological advancements.
Market Dynamics
The North American vegetable oil market is experiencing dynamic shifts driven by technological advancements, evolving regulatory frameworks, increasing investment in sustainable and innovative solutions, changing consumer preferences, fluctuating raw material costs, and aggressive competitive strategies. These factors collectively influence market structure, pricing strategies, and product development, creating an environment of continuous adaptation for industry players. As demand for healthier and plant-based alternatives rises, coupled with increasing sustainability mandates and technological enhancements in oil extraction and processing, the market landscape is becoming more complex yet full of growth opportunities. Stakeholders must navigate these interrelated factors to capitalize on emerging trends and mitigate associated risks.
Drivers
Growing Demand for Healthy and Plant-Based Oils
The rising consumer shift towards healthier lifestyles has significantly boosted demand for plant-based oils, such as olive, canola, and sunflower oils. This trend is driven by increasing awareness of nutritional benefits, leading to higher consumption in both households and the foodservice sector. For instance, the adoption of heart-healthy oils aligns with broader health-conscious movements, prompting manufacturers to innovate with fortified or organic options. Market analyses reveal a compound annual growth rate of roughly 5% in health-oriented vegetable oil segments from 2026 to 2034, indicating strong consumer-driven momentum and expanding retail penetration.
Technological Advancements in Oil Extraction and Refining
Innovations in extraction techniques, such as cold pressing and solvent-free methods, have enhanced oil yield efficiency and product quality, reducing environmental impact and operational costs. Automation and AI-driven quality control have further optimized production processes, enabling faster turnaround and consistent product standards. For example, new crushing and extraction equipment specialized for nesting crops have boosted yields by up to 10%, offering manufacturers competitive advantages. As these technologies become more accessible, industry participants are investing heavily in upgrading their facilities, fostering a more efficient and sustainable supply chain.
Regulatory Initiatives Promoting Sustainability and Transparency
Governments and regulatory bodies across North America are implementing strict standards targeting environmental sustainability, fair trade, and product transparency. These regulations demand traceability and eco-friendly sourcing practices, compelling companies to adapt their supply chains. Certification programs such as Non-GMO, organic, and sustainable agriculture labels are gaining popularity, influencing consumer purchasing decisions. Companies that proactively align with these standards can access premium markets and build brand loyalty, thus gaining a competitive edge. Compliance costs, however, pose initial hurdles for smaller firms, shaping market entry and expansion strategies.
Market Expansion Through Strategic Partnerships and Mergers
The industry is witnessing an increase in strategic alliances, joint ventures, and mergers to leverage cross-company expertise, expand product portfolios, and access new markets. Large players seek to strengthen their position by acquiring smaller innovators and startups that focus on novel plant oils or innovative processing methods. For example, recent mergers between established vegetable oil producers and biotech startups aim to develop specialty oils with enhanced health benefits or improved shelf life. These partnerships facilitate knowledge exchange, reduce R&D costs, and accelerate commercialization, positioning firms advantageously amid a competitive landscape.
Restraints
Volatility in Raw Material Prices
Fluctuating prices of raw materials like soy, canola, and palm seeds significantly impact profit margins within the vegetable oil sector. Variations in weather conditions, geopolitical tensions, and global trade policies influence supply levels and costs. For instance, droughts in key soybean-producing regions have caused raw material prices to spike unpredictably, forcing manufacturers to either absorb costs or pass them onto consumers, potentially dampening demand. This price volatility also complicates long-term planning and contractual agreements, thereby restricting the industry's financial stability and growth predictability.
Supply Chain Disruptions
Recent disruptions caused by transportation bottlenecks, labor shortages, and pandemic-related constraints have strained the supply chains for vegetable oils in North America. These interruptions delay sourcing, increase storage expenses, and threaten product availability, particularly for processors dependent on imported raw stocks. Small and medium-sized enterprises are especially vulnerable due to limited logistics flexibility, which hampers their ability to respond swiftly to market demands. Continual supply chain fragility necessitates strategic inventory management and diversified sourcing strategies, adding complexity and costs to market participants.
Environmental and Social Regulatory Pressures
Stringent environmental and social governance (ESG) regulations impose additional operational costs and compliance burdens. Initiatives targeting deforestation, land use change, and carbon emissions require traceability from farm to processing plant. For example, policies advocating for zero-deforestation in palm oil sourcing compel companies to verify their supply chains, often involving costly audits and certifications. Non-compliance can lead to legal penalties, brand damage, and restricted market access, especially in premium segments. Consequently, firms face the challenge of balancing regulatory adherence with maintaining cost competitiveness.
Opportunities
Expansion of Organic and Non-GMO Product Lines
The consumer preference for organic and non-GMO products continues to grow rapidly, creating lucrative opportunities for market expansion. North American consumers are willing to pay premium prices for oils that guarantee health benefits and environmental sustainability. Companies investing in organic certification and transparent sourcing are positioned to dominate emerging niche markets and retail segments. Additionally, innovations in organic cultivation and extraction technologies are reducing costs over time, making these products more accessible. The demand for organic oils is projected to grow at a CAGR of 6-8% through 2034, indicating a robust expansion potential.
Investment in Sustainable and Eco-Friendly Production Technologies
Increasing focus on sustainable agriculture practices and eco-friendly processing methods opens avenues for technological investment and infrastructure upgrades. Initiatives such as renewable energy-powered plants, water recycling, and waste valorization not only improve environmental footprints but also generate cost savings over time. Governments and private investors are incentivizing such investments through grants, tax breaks, and green bonds. As consumer awareness of sustainability intensifies, companies that pioneer these technologies can differentiate themselves and command premium pricing, with the sustainability market expected to grow significantly during the forecast period.
Development of Specialty and Functional Oils
The emergence of specialty oils, enriched with bioactive compounds, antioxidants, and health-enhancing properties, presents new product development opportunities. Functional oils tailored for specific dietary needs, such as omega-3 rich or infused oils, align with the increasing demand for personalized nutrition. Advances in biotechnological processes, including enzyme-assisted extraction and nano-encapsulation, facilitate the creation of these innovative products. Investment in R&D and startup ecosystems focused on bioengineering and extraction innovations will propel growth in this high-margin segment, attracting new market entrants and fueling industry diversification.
Emerging Technologies in Crop Breeding and Oil Yield Optimization
Biotechnological advances in crop breeding, including genetic modification and precision agriculture, are poised to enhance oilseed yields and quality. Precision farming techniques that integrate IoT, sensors, and data analytics enable optimized resource utilization, reducing input costs and environmental impact. These innovations not only improve crop resilience to climate variability but also ensure consistent raw material supply, a critical factor amid global supply chain uncertainties. Strategic investments in biotech startups and collaborative research initiatives are expected to unlock new oil varieties with improved extraction efficiency and nutritional profiles, shaping future market dynamics.
Challenges
Intense Market Competition and Price Wars
The North American vegetable oil industry is highly competitive, with numerous domestic and international players vying for market share. Price wars often erupt during periods of oversupply, eroding profit margins and incentivizing aggressive discounting strategies. Larger firms leveraging economies of scale tend to dominate market segments, leaving smaller enterprises vulnerable to margin erosion. Sustaining competitive advantage requires continuous innovation, strategic branding, and diversification, emphasizing the need for robust marketing efforts and product differentiation to withstand competitive pressures.
Environmental and Climate Change Risks
Climate change poses a significant long-term threat to oilseed cultivation, with unpredictable weather patterns, droughts, and pests impacting crop yields. These environmental risks threaten raw material security and could lead to supply shortages or higher costs. The industry must adopt adaptive farming practices, develop drought-resistant crop varieties, and implement risk mitigation strategies such as crop insurance and diversified sourcing. Addressing climate risks requires substantial investment and proactive management, but failure to do so could substantially hinder growth prospects and threaten market stability.
Industry Statistics & Key Business Metrics
The North American vegetable oil market remains a vital component of the region’s agricultural and food processing industries. Its growth is driven by increasing demand for plant-based fats in both household consumption and industrial applications, including biofuel production and processed food manufacturing. Market dynamics are influenced by shifts toward healthier eating trends, environmental considerations, and regulatory policies aimed at sustainable sourcing.
- In 2022, the North American vegetable oil market was valued at approximately USD 25.4 Billion, according to industry reports.
- By 2023, the volume of vegetable oil consumed in North America reached 11.6 million metric tons, reflecting a steady increase from previous years (USDA).
- The CAGR for the North American vegetable oil market from 2026 to 2034 is projected at 4.2%, driven by rising demand in the biofuel sector and health-conscious consumer preferences (MarketResearch.com).
- In 2024, the U.S. accounted for roughly 72% of the region’s vegetable oil consumption, with Canada and Mexico forming the remaining share, highlighting regional disparities in demand (Statista).
- Health and wellness trends contribute to a 5% annual increase in the demand for non-GMO and organic vegetable oils, with sales reaching USD 4.8 Billion in 2023 (Organic Trade Association).
- Exports of North American vegetable oils in 2023 surged to USD 2.2 Billion, primarily due to exports to Asia and Europe, indicating the region’s strategic importance in the global market (U.S. Department of Commerce).
- The adoption of sustainable and eco-friendly farming practices has increased, with 60% of vegetable oil producers implementing certified sustainable sourcing practices by 2023 (Sustainable Agriculture Initiative).
- In 2025, expected new technological innovations are anticipated to increase production efficiency by approximately 8%, reducing costs and environmental impact (Industry Reports).
Market Segmentation
Market segmentation in the North America Vegetable Oil Market is structured to encompass various categories including product type, source, and geographic distribution. This comprehensive segmentation approach helps identify key areas of demand, supply chain dynamics, and regional preferences across the continent.
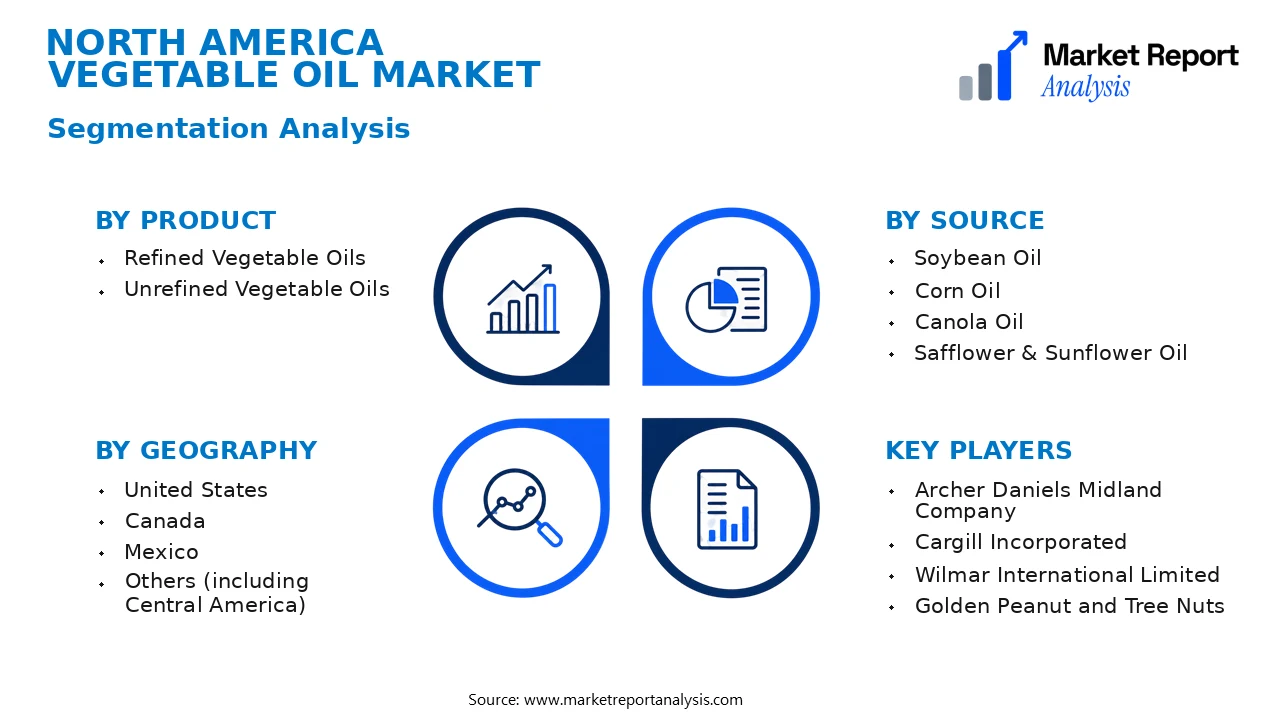
- Product
- Refined Vegetable Oils: This segment comprises oils that undergo refining processes to eliminate impurities, enhance shelf-life, and improve taste, which are primarily used in cooking, food processing, and the foodservice industry, demonstrating high demand for superior quality oils.
- Unrefined Vegetable Oils: These oils are minimally processed, retaining natural flavors and nutrients. They are increasingly favored by health-conscious consumers and specialty markets seeking organic and natural product options.
- Source
- Soybean Oil: As the predominant vegetable oil in North America, soybean oil is widely used in processed foods, cooking, and frying, driven by its cost-effectiveness and high yield per acre.
- Corn Oil: Derived from corn germ, this oil is popular for its mild flavor and cooking versatility, with strong demand in both retail and food manufacturing sectors.
- Canola Oil: Known for its health benefits due to a favorable omega-3 fatty acid profile, canola oil holds significant market share and is increasingly adopted as a healthy cooking oil choice.
- Safflower & Sunflower Oil: These oils are used for their high smoke points and health benefits, particularly in baking, frying, and salad dressings, appealing to premium and health-focused markets.
- Geography
- United States: The largest market within North America, driven by extensive food manufacturing, high consumer health awareness, and expanding organic product offerings.
- Canada: Marked by rising health consciousness and a shift towards non-GMO and organic oils, with substantial growth in retail and foodservice channels.
- Mexico: Characterized by increasing urbanization and westernization of diets, boosting demand for processed foods and, consequently, vegetable oils.
- Others (including Central America): Smaller but growing markets with niche demand such as organic and specialty oils, driven by local dietary preferences and import dynamics.
Competitive Intelligence
The North America vegetable oil market exhibits moderate competition characterized by several key players, including Archer Daniels Midland Company, Cargill, and Bunge Limited, who hold significant market share, creating a somewhat concentrated industry landscape. Major companies are adopting aggressive business strategies such as product diversification, vertical integration, and technological innovation to strengthen their market positioning. These firms invest heavily in R&D to develop advanced processing techniques that improve yield, stability, and flavor, thereby differentiating their offerings. Strategic partnerships and alliances with agricultural producers enable secure raw material supply chains and enhance distribution channels. Additionally, acquisitions of regional companies allow for expanded product portfolios and market reach, especially in organic and specialty oils segments. Expansion strategies focus on tapping into emerging sectors like plant-based foods and functional products, aligning with evolving consumer preferences. Innovation-driven differentiation is achieved through the development of healthier, non-GMO, and specialty oils, addressing consumer demand for quality and sustainability. Overall, the competitive landscape emphasizes strategic investments, innovation, and harmonized growth efforts to maintain market relevance through 2034.
Leading Company Profiles
The competitive landscape of the North America vegetable oil market features a blend of well-established giants and innovative emerging players. These companies focus on expanding production capacities, pioneering sustainable practices, and diversifying product lines to enhance their market share and meet evolving consumer preferences.
- Archer Daniels Midland Company
- Cargill Incorporated
- Wilmar International Limited
- Golden Peanut and Tree Nuts
- Bunge Limited
- Wilton Olive Oil
- Patterson Fruit Farm
- Saffola (Promoted by Marico Limited)
- Aromex Inc.
- Better Body Foods
Archer Daniels Midland Company
As a global leader in agricultural processing, ADM specializes in the production of soybean, canola, and sunflower oils, leveraging innovative extraction technologies and sustainable sourcing to meet rising demand across North America.
Cargill Incorporated
Cargill offers a comprehensive range of vegetable oils, focusing on health-oriented products and sustainable sourcing practices, supported by extensive capacity expansions and strategic investments to remain competitive and environmentally responsible.
Wilmar International Limited
Wilmar is a prominent player with a strong emphasis on innovative milling technologies, expanding its footprint through acquisitions and joint ventures, bolstering its capacity to serve growing markets with a focus on sustainability.
Golden Peanut and Tree Nuts
This company specializes in specialty oils from nuts and seeds, emphasizing organic and non-GMO offerings, with ongoing R&D initiatives aimed at expanding its product portfolio and improving extraction efficiencies.
Bunge Limited
Bunge’s strategic focus includes capacity expansion and technological upgrades in the production of soybean and palm oils, alongside sustainability initiatives aligned with consumer demand for eco-friendly products.
Wilton Olive Oil
A key regional player, Wilton Olive Oil emphasizes high-quality, cold-pressed oils, with a focus on organic certification, expanding distribution channels and educational marketing campaigns to enhance brand recognition.
Patterson Fruit Farm
Primarily known for specialty oils derived from organic produce, Patterson invests heavily in sustainable farming techniques, targeting health-conscious consumers and premium market segments.
Saffola (Promoted by Marico Limited)
Saffola continues to capitalize on health trends, expanding its vegetable oil portfolio with low-fat, cholesterol-lowering options, supported by robust marketing and distribution networks.
Aromex Inc.
Aromex focuses on innovative flavor-enhanced and functional oils, investing in new manufacturing technologies and forming strategic alliances to increase its market penetration within North America.
Better Body Foods
This company emphasizes organic, non-GMO oils, leveraging online marketing and strategic investments in sustainable sourcing to cater to urban and health-focused consumer segments.
Strategic Business Developments
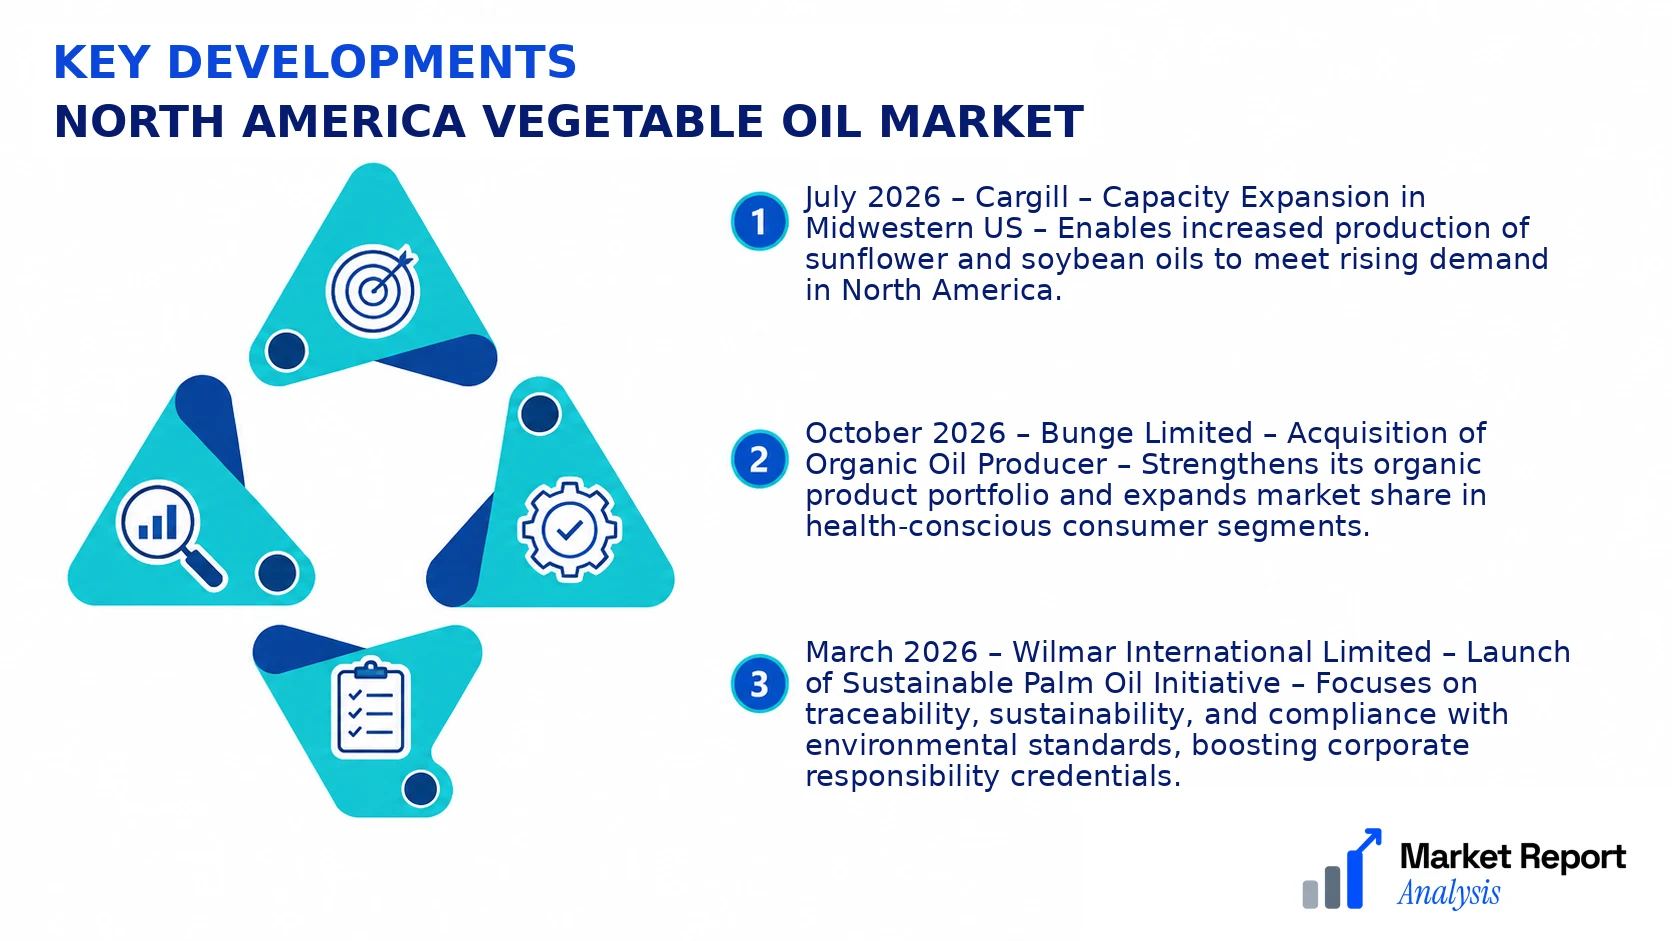
- July 2026 – Cargill – Capacity Expansion in Midwestern US – Enables increased production of sunflower and soybean oils to meet rising demand in North America.
- October 2026 – Bunge Limited – Acquisition of Organic Oil Producer – Strengthens its organic product portfolio and expands market share in health-conscious consumer segments.
- March 2026 – Wilmar International Limited – Launch of Sustainable Palm Oil Initiative – Focuses on traceability, sustainability, and compliance with environmental standards, boosting corporate responsibility credentials.
- September 2026 – Archer Daniels Midland Company – New Extraction Technology Adoption – Enhances yield efficiency and sustainability metrics, reducing environmental impact across processing facilities.
- December 2026 – Better Body Foods – Digital Marketing Campaign Launch – Aims to increase brand visibility, emphasizing health benefits and organic sourcing to attract a broader consumer base.
Frequently Asked Questions
What is the North America Vegetable Oil Market?
The North America Vegetable Oil Market encompasses the production, distribution, and consumption of various vegetable oils, including soybean, canola, sunflower, and palm oils, catering to food processing, cooking, and industrial applications within North America.
What is the current market size of North America Vegetable Oil Market?
As of 2026, the North America Vegetable Oil Market is valued at approximately USD 18 Billion, reflecting steady growth driven by increasing demand for healthy cooking oils and plant-based products across the region.
What factors are driving the North America Vegetable Oil Market?
Key drivers include rising consumer preference for health-conscious and plant-based foods, technological advancements in oil extraction, expanding food processing industries, and increasing awareness of cardiovascular health benefits associated with vegetable oils.
Which region dominates the North America Vegetable Oil Market?
The United States leads the North American market due to its large population, extensive food manufacturing sector, and higher consumption levels of vegetable oils compared to Canada and Mexico.
Which segment is expected to grow the fastest?
The soybean oil segment is projected to exhibit the fastest growth owing to its widespread use, cost-effectiveness, and high production volume, anticipated to grow at a CAGR of 4.2% from 2026 to 2034.
Who are the leading companies operating in the North America Vegetable Oil Market?
Major players include Archer Daniels Midland Company, Cargill Incorporated, Bunge Limited, and Wilmar International, which hold significant market shares through extensive production capabilities and strategic regional presence.
Analyst Perspective
The North America vegetable oil market demonstrates a mature landscape with steady innovation driven by evolving consumer preferences for healthier, sustainable options. In the long term, the market is poised for a moderate CAGR, supported by increasing demand for plant-based products and advancements in extraction and processing technologies. Key commercial opportunities lie in expanding specialty oils, such as omega-rich and organic variants, especially within health-conscious segments. Technology evolution will likely focus on enhancing yield efficiency, reducing environmental impact, and developing novel formulations for functional foods and beverages. Investment priorities should target sustainable supply chains, innovative product development, and digital marketing strategies to foster brand differentiation. Competitive intensity remains high, with major players investing heavily to capture market share through product diversification and strategic partnerships. Regional growth potential is strongest in urban centers and emerging markets within North America, where consumer trends favor health and sustainability. Strategic positioning should emphasize innovation, regional diversification, and long-term brand loyalty to navigate market maturity and capitalize on evolving industry dynamics.
