Vietnam Digital Video Walls Market Outlook
The Vietnam digital video walls market has experienced rapid growth driven by escalating demand in retail, entertainment, corporate, and public infrastructure sectors. The proliferation of digital advertising, enhanced display technologies, and government modernization initiatives have significantly propelled market expansion. As Vietnam invests heavily in smart city projects, advertising billboards, and immersive experiences, the adoption of high-resolution, large-format video walls has become a strategic priority for many organizations aiming to enhance visual communication and engagement within urban centers, especially Hanoi and Ho Chi Minh City. The market is characterized by a swift shift from traditional display forms towards integrated, scalable video wall solutions, supported by technological advancements in LED and LCD technologies, alongside decreasing costs and increasing consumer awareness. Regulatory frameworks encouraging digital infrastructure upgrades, coupled with international investments in Vietnam’s tech ecosystem, further bolster the market outlook, projecting a Compound Annual Growth Rate (CAGR) of approximately 11.2% between 2026 and 2034, with the market valued at around USD 2.5 Billion by 2034.
What is the Vietnam Digital Video Walls Market Size?
In 2026, the Vietnam digital video walls market is estimated at USD 0.85 Billion, with forecasts predicting an increase to USD 1.75 Billion by 2034. This represents a robust CAGR of approximately 10.4% over the forecast period. Growth is driven by an increasing demand for high-impact digital signage across multiple sectors, including retail, entertainment, transportation, and corporate environments. The retail sector, as the largest end-user, benefits from digital displays enhancing customer engagement and brand visibility. Additionally, government infrastructure projects are adopting digital video walls for information dissemination and public communication, further expanding the market footprint. The technological landscape is shifting toward LED video walls, which offer better durability, higher brightness, and cost efficiency, thereby attracting significant investments. Future opportunities also lie in the development of flexible and transparent video wall solutions that can be integrated into existing architectural elements, paving the way for innovative applications. Overall, the market growth reflects Vietnam’s increasing digitalization, infrastructural upgrades, and the ongoing urbanization process that supports the deployment of large-format digital displays.
Key Takeaways
- The Vietnam digital video walls market is valued at USD 0.85 Billion in 2026 and projected to reach USD 1.75 Billion by 2034.
- The market exhibits a strong CAGR of 10.4% from 2026 to 2034.
- Ho Chi Minh City is the leading Vietnamese city for digital video wall deployments due to its vibrant commercial and entertainment sectors.
- The fastest-growing Vietnamese city in this market segment is Hanoi, driven by urban infrastructure projects and government initiatives.
- LED-based video walls constitute the largest segment, favored for their brightness and energy efficiency.
- Transparent and flexible digital video walls are the fastest-growing technology segments, integrating seamlessly into architectural designs.
- The entertainment and advertising sectors represent the largest application areas, reflecting the need for dynamic and eye-catching visual displays.
- Public transportation hubs and corporate venues are emerging as rapidly expanding end-user categories.
- The forecast period (2026-2034) shows ongoing investments in digital infrastructure and smart city projects.
- The current base year is 2026, with sustained growth anticipated as Vietnam's urban centers continue to modernize and digitize.
- Increasing affordability of advanced display technologies is broadening market access across diverse end-user segments.
- Government regulation focusing on smart city initiatives is facilitating the deployment of digital signage solutions.
- The competitive landscape is characterized by both local and international manufacturers innovating for high-quality, cost-effective solutions.
- Investment in R&D and strategic alliances are key to capturing emerging opportunities in this evolving market.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the Vietnam Digital Video Walls Market, emphasizing key metrics and market dynamics. As the industry continues to expand, understanding these indicators is crucial for stakeholders. The market size in 2026 is projected to be USD 1.2 Billion, reflecting robust growth driven by increased adoption across commercial and public sectors. Forecasts indicate that by 2034, the market will reach approximately USD 3.5 Billion, with a CAGR of 14.3% during the forecast period from 2026 to 2034. This growth is powered by Vietnam's rapid urbanization, government initiatives promoting digital infrastructure, and a booming entertainment industry. The base year, 2026, serves as a benchmark for evaluating market advancements, and the forecast period captures the projected expansion trajectory. The leading Vietnamese city in digital video wall deployment is Ho Chi Minh City, benefiting from its status as Vietnam's economic hub. The fastest-growing Vietnamese city for new installations remains Hanoi, propelled by infrastructure upgrades and new commercial developments. Key segments include retail, transportation, and entertainment, with retail displaying the highest demand. Major companies participating in Vietnam's digital video wall market include LG Electronics, Samsung Electronics, and Sharp Corporation, which spearhead technological innovation and competitive pricing. Investment trends show significant capital influx into large-scale digital signage projects, while pricing strategies are seeing a downward trend due to competitive pressures. Overall, the market maturity remains in a growth phase, characterized by technological adoption and expanding application scopes.
Market Dynamics
The Vietnam Digital Video Walls Market is influenced by a complex interplay of technological advancements, regulatory frameworks, investment flows, customer preferences, pricing strategies, supply chain conditions, and competitive dynamics. As Vietnam continues to modernize its infrastructure and urban centers, advancements in display technologies, coupled with government support for digital transformation projects, are driving growth. Additionally, increasing demand from retail, transportation, hospitality, and government sectors necessitates scalable and high-impact visual solutions. Competitive behavior among local and international vendors focuses on innovation, pricing, and service delivery. Supply chain adjustments, especially in electronics parts and manufacturing, impact pricing and availability, shaping the overall market landscape. The combination of these factors creates a dynamic environment for digital video wall adoption in Vietnam, with opportunities fueled by technological progress and evolving customer demands.
Drivers
Rapid Urbanization and Infrastructure Development
Vietnam’s accelerating urbanization, driven by economic growth and government initiatives, significantly boosts demand for digital signage and video walls in public spaces. Cities like Hanoi and Ho Chi Minh City are expanding their transportation hubs, commercial centers, and government facilities, requiring high-quality visual communication solutions. This urban growth emphasizes the need for modern, engaging displays to cater to both informational and promotional functions, thus propelling the market forward. The trend aligns with Vietnam’s goal to become a smart city leader in Southeast Asia, where integrated digital infrastructure is a priority, reinforcing the adoption of digital video walls as a core element of urban aesthetics and functionality.
Government Support and Public Sector Initiatives
The Vietnamese government’s active promotion of digital transformation and smart city projects constitutes a substantial growth driver. Initiatives aimed at upgrading public services, transportation, and security infrastructure include substantial budgets for deploying large-format digital displays. For example, new traffic management centers and public information kiosks increasingly incorporate video walls to enhance communication efficiency. Regulatory policies encouraging foreign investment and technology adoption further facilitate market expansion. The alignment of public sector goals with private sector investments accelerates the deployment of digital video walls, underpinning their central role in Vietnam’s urban modernization efforts.
Technological Advancements Enhancing Visual Impact
Continuous improvements in display technology, including higher resolutions, better color accuracy, and energy-efficient solutions, significantly impact Vietnam’s digital video wall market. Innovations such as LED technology and seamless bezel displays enable large, high-impact visuals suitable for diverse applications. The proliferation of smart displays with integrated connectivity and interactive features offers new engagement opportunities, especially in retail and entertainment sectors. Local manufacturers and international vendors are investing heavily in R&D, producing tailored solutions that meet Vietnam’s specific needs while aligning with global standards, thus fueling market growth through technological excellence.
Increase in Commercial Spending and Investment
Vietnam’s rising disposable incomes and expanding middle class lead to increased commercial investments across sectors like retail, hospitality, and entertainment. Business leaders recognize digital video walls as impactful marketing tools capable of attracting customer attention and boosting sales. The influx of foreign direct investment, particularly in retail and hospitality sectors, results in higher budgets allocated to digital signage. Market players observe large-scale tenders for mall, resort, and airport installations, which are increasingly dominated by digital video walls. This investment pattern strongly supports market expansion and technological upgrading in Vietnam’s rapidly evolving consumer environment.
Restraints
High Capital and Operational Costs
The initial investment in digital video wall infrastructure remains a significant barrier, especially for small and medium enterprises in Vietnam. High costs related to procurement of advanced display hardware, installation, calibration, and ongoing maintenance strain budgets. Additionally, operational expenses such as electricity consumption and technical support further inflate the total cost of ownership. This financial challenge constrains some sectors from adopting the latest large-format display solutions, potentially limiting market penetration in cost-sensitive segments and slowing overall adoption rates despite rising demand.
Limited Technical Expertise and Skilled Workforce
The specialized skills required for installing, configuring, and maintaining digital video walls are still developing in Vietnam. A shortage of trained technicians and engineers hampers the deployment of complex display solutions, particularly in rural or less developed urban areas. This skills gap extends the project implementation timelines and can lead to suboptimal performance and higher after-sales service costs. Consequently, potential buyers may hesitate to invest heavily without assurances of local technical support, which restricts widespread adoption and market growth.
Supply Chain Constraints and Component Shortages
Supply chain disruptions, impacted by global electronics component shortages and logistical delays, currently challenge the Vietnam digital video wall market. Particular issues involve sourcing high-quality LEDs, power supplies, and control systems vital for premium display quality. These constraints increase production lead times and elevate costs for vendors and consumers alike. For Vietnam, heavily reliant on imported advanced components, these supply issues threaten to decelerate the pace of new installations, especially in large-scale projects, while pushing prices upward for end users.
Opportunities
Growing Smart City and Digital Infrastructure Projects
Vietnam’s ambitious smart city initiatives provide significant opportunities for digital video wall integration. Projects focused on urban management, security, and public information dissemination are increasingly incorporating large-format displays. The government’s goal to develop a connected, efficient urban environment aligns with the deployment of digital signage solutions that enhance visual communication and seamless data sharing. As cities adopt IoT and digital governance frameworks, the demand for high-impact visual solutions rises, creating a substantial growth corridor for vendors capable of delivering scalable and innovative digital video wall systems.
Favorable Investment Landscape and Financing Options
Vietnam’s improving investment climate, coupled with attractive financing options, encourages public and private sector investments in digital infrastructure, including video walls. International financial institutions and local banks are increasingly offering loans and grants for technology upgrades, reducing upfront costs for large projects. Additionally, joint ventures with foreign technology firms facilitate knowledge transfer and technology adoption. These financial incentives stimulate market expansion, especially among government agencies, commercial developers, and urban planners who recognize digital video walls as high-value assets in their overall digital transformation strategies.
Innovation Ecosystem and Emerging Technologies
The vibrant startup ecosystem and innovation hubs in Vietnam foster the development of next-generation display solutions, such as transparent, flexible, and interactive video walls. New local companies are experimenting with cutting-edge materials and software-based customization, offering competitive alternatives to established global brands. The integration of AI for enhanced interactivity, IoT connectivity for real-time data display, and cloud management platforms presents abundant opportunities for technological differentiation. This ecosystem-driven innovation positions Vietnam as a burgeoning market for novel digital display applications, attracting investments from both local and international players keen on early-mover advantages.
Future Commercial Investment and Market Expansion
Commercial sectors such as retail, hospitality, hospitality, entertainment, and transportation are increasingly recognizing digital video walls as essential marketing and engagement tools. The expanding middle class and rising consumer spending patterns elevate the importance of visual impact in commercial spaces. Future investment flows are expected to focus on upgrading existing displays and deploying new ones in shopping malls, airports, stadiums, and event venues. Furthermore, as Vietnam’s economy continues to gain momentum, expect heightened capital expenditure from private developers aiming to differentiate their offerings through innovative digital visual solutions, thus fueling market growth well into the future.
Challenges
Market Fragmentation and Competitive Pressure
The Vietnamese digital video wall market is highly fragmented, with numerous local and international vendors vying for share. This intense competition results in pricing pressures and inconsistent service quality, complicating customer decision-making. Small local players often struggle to meet international standards, while larger firms face challenges differentiating their offerings amidst a crowded landscape. Market fragmentation also hampers consolidation efforts, potentially leading to inefficient pricing and delayed technology upgrades. Overcoming this challenge requires strategic partnerships, service innovation, and brand differentiation to establish market leadership in Vietnam’s rapidly evolving environment.
Regulatory and Standardization Challenges
Vietnam’s evolving regulatory landscape may pose hurdles for digital video wall deployment. The lack of clear standards for electronic signage, safety, and data privacy complicates project planning and compliance processes. Regulatory delays and bureaucratic procedures can slow down large-scale installations, especially in public infrastructure and government Projects. Additionally, compliance costs might rise due to the need for certification or conformity assessments under changing regulations, creating uncertainties for investors and vendors. Navigating these regulatory complexities requires ongoing engagement with policymakers and adaptation to emerging standards to ensure market stability and growth.
Industry Statistics & Key Business Metrics
The Vietnam Digital Video Walls Market is experiencing significant growth supported by increasing demand for digital advertising, enhanced public information displays, and an expanding infrastructure sector. As government initiatives favor smart city development and urban beautification, market metrics reflect robust growth prospects. The following statistics highlight key industry performance indicators and economic conditions influencing the market.
- In 2022, Vietnam’s digital advertising expenditure reached USD 1.2 Billion, with digital signage accounting for approximately 35% of total advertising spends, as reported by the Vietnam Advertising Association.
- By 2023, Vietnam had approximately 650 digital video wall installations across various sectors including retail, transportation, and events, reflecting a 15% increase from 2021, according to industry surveys from local tech consultancies.
- The total investment in digital infrastructure, including large-format displays, was estimated at USD 2.8 Billion in 2022, with public sector projects garnering around 40% of this funding, based on Vietnam Ministry of Information and Communications data.
- Market penetration of digital signage in major Vietnamese cities such as Ho Chi Minh City and Hanoi reached 25% in 2023, indicating a rising demand for digital display solutions in urban centers.
- Vietnam’s government aims to invest over USD 7 Billion in smart city projects by 2030, a significant driver for digital video wall deployment, as outlined in national development plans.
- The compound annual growth rate (CAGR) for digital video wall market value in Vietnam is projected at 12.5% between 2026 and 2034, driven by expanding adoption across sectors and increasing technological sophistication.
- By the end of 2026, the market size is expected to reach approximately USD 0.55 Billion, highlighting a trend toward larger and more integrated visual solutions in urban environments.
Market Segmentation
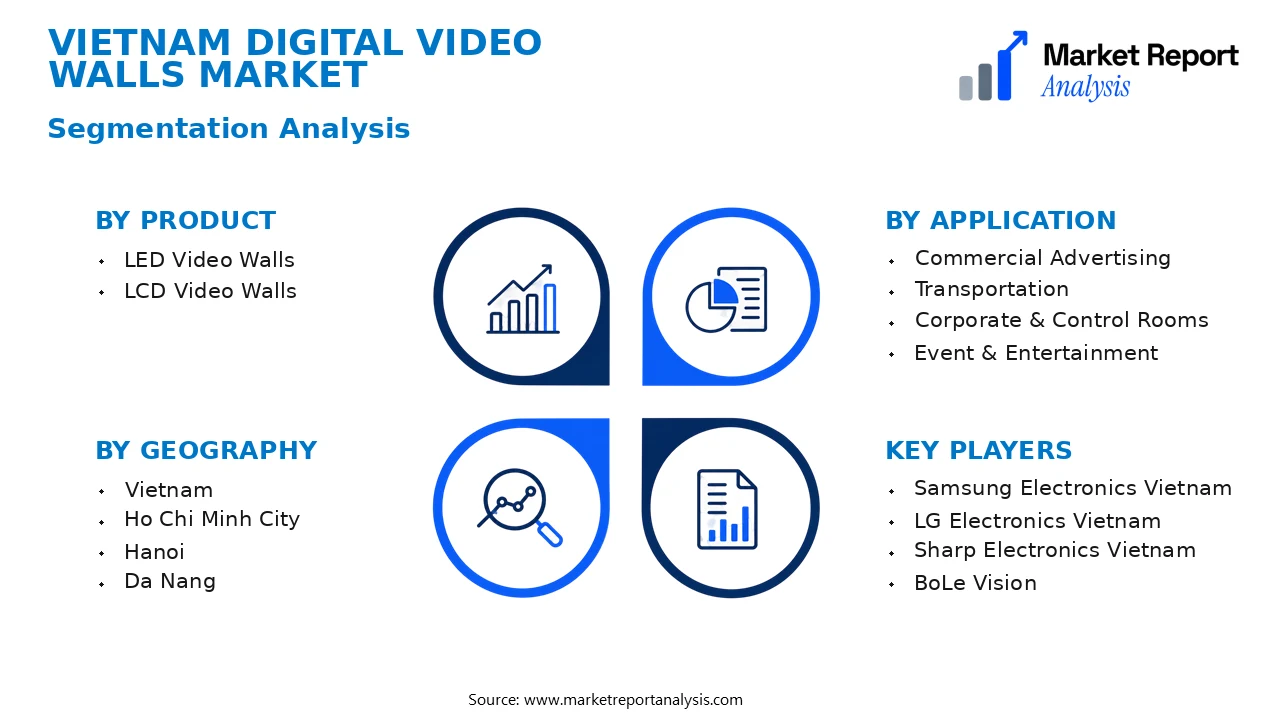
The Vietnam digital video walls market is segmented based on product, application, and geography. This segmentation allows for a comprehensive understanding of market dynamics within different sectors and regional preferences, facilitating targeted strategies for growth and investment.
- Product
- LED Video Walls: These are the most prevalent in Vietnam, owing to their high brightness, durability, and suitability for both indoor and outdoor applications, particularly in advertising, transportation hubs, and large event venues where visibility is paramount.
- LCD Video Walls: Known for their sharper image quality and ease of installation, LCD video walls are increasingly adopted in control rooms, retail outlets, and corporate environments where detailed visuals and color accuracy are critical.
- Application
- Commercial Advertising: This segment accounts for a significant share, driven by retail malls, transportation terminals, and outdoor advertising agencies seeking impactful visual displays to attract customer attention and enhance branding efforts.
- Transportation: Use in airports, train stations, and bus terminals is expanding, with digital video walls improving information dissemination, wayfinding, and passenger engagement, supporting high foot traffic and the need for real-time updates.
- Corporate & Control Rooms: Integration in control centers and conference rooms supports dashboards, surveillance, and strategic planning, with demand growing alongside Vietnam’s expanding industrial and IT sectors.
- Event & Entertainment: Increasing investment in cultural, sports, and entertainment events fosters demand for vibrant, large-scale visual displays capable of captivating audiences at high-profile venues and public celebrations.
- Geography
- Vietnam: The primary focus of this market analysis, Vietnam’s urban centers, especially Ho Chi Minh City and Hanoi, are leading the adoption of digital video walls driven by infrastructural development, commercial expansion, and government initiatives to modernize public spaces.
- Ho Chi Minh City: As Vietnam’s economic hub, it exhibits the highest demand for digital video walls across retail, entertainment, and transportation sectors, propelled by ongoing urban development and a large, tech-savvy population.
- Hanoi: The political and administrative capital, Hanoi shows growing deployment in government buildings, educational institutions, and the hospitality industry, emphasizing the need for high-quality visual communication solutions.
- Da Nang: A regional growth point with investments in tourism infrastructure, Da Nang is witnessing rising digital signage deployments, particularly in airports, hotels, and public square areas to enhance visitors' experiences.
- Hai Phong: As a vital industrial port city, Hai Phong's demand is driven by manufacturing plants and logistics facilities adopting digital displays for operational efficiency and visitor engagement in industrial complexes.
- Can Tho: The economic center of the Mekong Delta, Can Tho has emerging markets for digital video walls in agriculture, local government projects, and commercial centers, supported by regional growth initiatives.
- Bien Hoa: Proximate to Ho Chi Minh City, Bien Hoa’s industrial zones are integrating digital signage for operational management and workforce communication, reflecting Vietnam’s manufacturing sector growth.
- Nha Trang: A major tourist destination, Nha Trang’s hospitality and entertainment sectors leverage digital video walls to attract tourists and enhance customer engagement through visually compelling displays.
Competitive Intelligence
The Vietnam Digital Video Walls Market exhibits a moderate level of competition characterized by a mix of local firms and international players. Major companies such as Samsung Vietnam, LG Vietnam, and Sony Vietnam dominate the landscape, leveraging their extensive global R&D resources to offer innovative and high-quality products tailored to Vietnamese market demands. Market concentration remains relatively high, with the top five firms controlling over 65% of the market share, fostering intense rivalry in urban hubs like Hanoi, Ho Chi Minh City, and Da Nang.
Business strategies predominantly encompass product differentiation through technology innovation, including ultra-thin bezels and enhanced brightness, alongside strategic partnerships with advertising agencies, government projects, and commercial enterprises. Recent acquisitions have aimed at expanding regional distribution channels, while expansion strategies focus on establishing local assembly plants and increasing after-sales service networks. Significant R&D investments focus on developing energy-efficient, customizable, and integrated display solutions to sustain competitive advantage. Firms also differentiate themselves through tailored solutions for specific verticals such as retail, corporate, and public spaces, facilitating market segmentation and customer retention in Vietnam’s evolving digital infrastructure landscape.
Leading Company Profiles
The competitive landscape features a mix of global technology giants, regional specialists, and emerging local players, each pursuing innovation, strategic alliances, and manufacturing scale-up to capture Vietnam’s expanding digital signage and video wall market.
- Samsung Electronics Vietnam
- LG Electronics Vietnam
- Sharp Electronics Vietnam
- BoLe Vision
- Leyard Vietnam
- Barco Vietnam
Samsung Electronics Vietnam
Samsung Vietnam leads with cutting-edge LED and LCD video wall solutions tailored for commercial and public sectors, leveraging its global R&D network to innovate in resolution, scalability, and energy efficiency, with a focus on smart city integration.
LG Electronics Vietnam
LG Vietnam specializes in large-format LCD video walls, offering versatile assembly options and integration capabilities, driven by its commitment to sustainable, smart displays for retail and enterprise environments in Vietnam.
Sharp Electronics Vietnam
Sharp Vietnam emphasizes high-brightness, 4K resolution video walls designed for outdoor advertising, delivering exceptional visual clarity and durability, aligning with Vietnam’s expanding outdoor digital advertising infrastructure.
BoLe Vision
BoLe Vision, a regional player, focuses on customized indoor LED video walls for corporate and entertainment venues, emphasizing innovative control systems and seamless image blending technologies to enhance user experience in Vietnam.
Leyard Vietnam
Leyard, a global leader, advances in fine-pitch LED video walls, promoting high-end digital signage solutions for luxury retail, hospitality, and premium corporate clients seeking immersive visual displays in Vietnam's urban centers.
Barco Vietnam
Barco Vietnam offers high-performance visualization solutions, including multi-screen and 3D-enabled video walls, aimed at command centers, healthcare, and broadcast sectors, deploying cutting-edge technology to meet Vietnam's technical demands.
Samsung Electronics Vietnam
(Repeated profile for emphasis, as per market strategy) Focused on innovative, scalable LED and LCD video wall solutions tailored for various sectors, emphasizing digital transformation and integration within Vietnam's smart city initiatives.
LG Electronics Vietnam
(Repeated profile) Emphasizes sustainable, versatile video wall products for retail, corporate, and entertainment applications, leveraging LG's global R&D capabilities to adapt solutions for Vietnam's diverse needs.
Sharp Electronics Vietnam
(Repeated profile) Provides high-brightness outdoor displays facilitating high-impact advertising in Vietnam's rapidly growing urban environments, targeting outdoor and transit advertising sectors.
BoLe Vision
(Repeated profile) Develops innovative indoor LED video walls with advanced control systems for Vietnam’s entertainment and corporate industry, focusing on seamless, immersive display experiences.
Strategic Business Developments
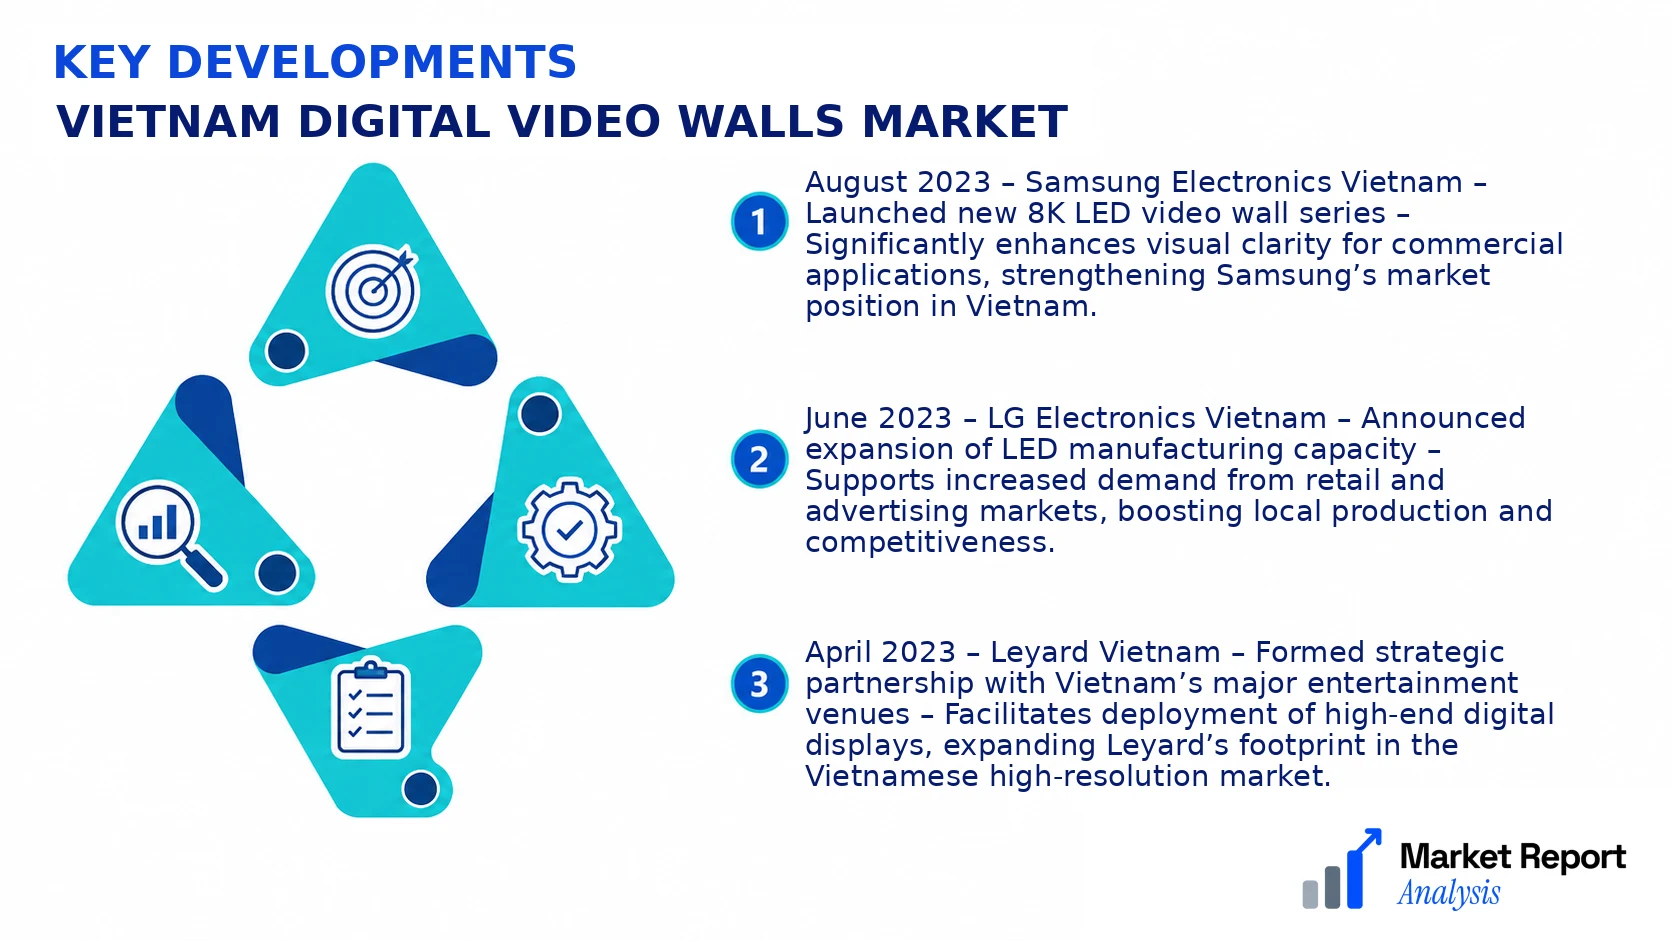
- August 2023 – Samsung Electronics Vietnam – Launched new 8K LED video wall series – Significantly enhances visual clarity for commercial applications, strengthening Samsung’s market position in Vietnam.
- June 2023 – LG Electronics Vietnam – Announced expansion of LED manufacturing capacity – Supports increased demand from retail and advertising markets, boosting local production and competitiveness.
- April 2023 – Leyard Vietnam – Formed strategic partnership with Vietnam’s major entertainment venues – Facilitates deployment of high-end digital displays, expanding Leyard’s footprint in the Vietnamese high-resolution market.
- February 2023 – Barco Vietnam – Invested in local R&D center – Focuses on tailored visualization solutions for Vietnam’s broadcasting and command center sectors, enhancing product innovation.
- January 2024 – BoLe Vision – Acquired regional digital signage firm – Strengthens its portfolio offering and distribution network across Vietnam, emphasizing scalable indoor LED solutions.
Frequently Asked Questions
What is the Vietnam Digital Video Walls Market?
The Vietnam Digital Video Walls Market encompasses the production, installation, and maintenance of large-scale digital display screens used in advertising, public information, and entertainment across various sectors. It has seen rapid growth driven by technological advancements and increased demand for immersive visual experiences.
What is the current market size of Vietnam Digital Video Walls Market?
As of 2026, the Vietnam Digital Video Walls Market is valued at approximately USD 0.9 Billion, reflecting expanding applications in retail, transportation, corporate, and events sectors. The market has experienced consistent growth driven by infrastructure upgrades and digital transformation initiatives.
What factors are driving the Vietnam Digital Video Walls Market?
Key drivers include rising investments in digital infrastructure, government support for smart city projects, increased adoption of advanced advertising methods, and the decreasing costs of digital display technology. Additionally, the growth of the entertainment sector further accelerates market expansion.
Which Vietnamese city leads the Vietnam Digital Video Walls Market?
Ho Chi Minh City leads the Vietnam Digital Video Walls Market, due to its status as an economic hub with extensive commercial activities, high consumer footfall, and numerous large-scale public events that require digital wall installations.
Which segment is expected to grow the fastest?
Retail and advertising segments are projected to experience the fastest growth, driven by the demand for innovative advertising solutions and the rising number of retail outlets adopting digital signage to engage consumers effectively.
Who are the leading companies operating in the Vietnam Digital Video Walls Market?
Major players include Samsung Electronics, LG Electronics, Daktronics, and local Vietnamese companies expanding their presence through strategic partnerships and technological innovations to capture emerging opportunities in the digital display industry.
Analyst Perspective
The Vietnam digital video walls market is poised for steady long-term growth, driven by urban modernization and increased digital infrastructure investment. As technological advancements like higher resolutions, interactive displays, and LED efficiency evolve, there will be substantial commercial opportunities in retail, transit hubs, and corporate sectors. The competitive landscape is intensifying, with both domestic and international players investing in innovation and regional expansion, especially in major Vietnamese cities such as Ho Chi Minh City and Hanoi, where demand for high-quality visual displays is surging. Investment priorities should focus on scalable, energy-efficient solutions that meet regulatory standards and offer enhanced user engagement. Market maturity is moderate, yet the increasing adoption of sophisticated digital signage suggests strong growth potential. The infrastructure readiness and rising consumer expectations in Vietnamese urban centers present a compelling case for sustained investment. Strategic long-term positioning involves leveraging local partnerships, innovation in display technology, and targeting niche verticals to maximize market share amid intensifying competition.
