North America Digital Video Walls Market Outlook
The North America Digital Video Walls Market is currently valued at USD 2.5 Billion in 2026 and is projected to reach approximately USD 4.8 Billion by 2034, expanding at a CAGR of around 8.2% from 2026 to 2034. The growth is propelled by rising demand in retail, corporate, entertainment, and transportation sectors, driven by the need for striking visual displays. Technological advancements, such as higher resolution panels, thinner bezels, and improved connectivity options, are enhancing display quality and operational efficiency. Commercial opportunities abound in large-format video displays for advertising, public information, live event broadcasting, and control rooms. The increasing adoption of LED technology over LCD panels is a notable trend, attributed to superior brightness, contrast, and durability. The market's growth is also supported by increasing investments in smart infrastructure, urban development projects, and the rise of immersive experiences in digital signage, creating substantial growth opportunities for vendors and integrators alike.
What is the North America Digital Video Walls Market Size?
The North America Digital Video Walls Market size is estimated at a current-market estimate of USD 2.5 Billion in 2026 and is expected to reach approximately USD 4.8 Billion by 2034, expanding at a CAGR of around 8.2% from 2026 to 2034. This growth is driven by the increasing installation of digital signage across a variety of end-use industries, including retail stores, banks, transportation hubs, entertainment venues, and corporate offices. The rapid technological evolution in display components, such as LED and LCD panels, further fuels market expansion by providing higher resolution, better contrast, and enhanced durability. Moreover, the surge in infrastructure development, smart city projects, and the adoption of digital advertising strategies contribute significantly to market growth. Future investment opportunities are notably high in integrated, customizable video wall solutions, and in the deployment of scalable displays that suit diverse operational environments. As organizations continue to prioritize engaging visual communication, the North American market is positioned for sustained expansion, with a focus on innovative, energy-efficient display technologies that meet evolving consumer and business demands.
Key Takeaways
- The North American digital video walls market is projected to reach USD 4.8 Billion by 2034.
- The market is growing at a CAGR of approximately 8.2% from 2026 to 2034.
- Currently valued at USD 2.5 Billion in 2026.
- LED-based video wall solutions constitute the largest segment.
- OLED and MicroLED are the fastest-growing display technologies.
- The retail and entertainment sectors are the primary applications.
- Digital signage and advertising represent the largest application segment.
- Control rooms and corporate displays are the fastest growing application areas.
- Retail remains the largest end user sector for digital video walls in North America.
- Urban infrastructure projects and smart city initiatives present promising investment prospects.
- Technological advancements and increasing demand for high-resolution displays drive market growth.
- Competitive landscape is intensifying with innovations in scalable and customizable display solutions.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the current state and projected evolution of the North America Digital Video Walls Market. This dashboard synthesizes critical industry metrics, providing clarity on the market's trajectory over the forecast period. The market size in 2025 was a significant figure, illustrating the early stage of growth, which is expected to escalate by 2026. Looking ahead, the forecast size in 2034 reflects a compounded growth pattern driven by technological advancements and expanding application sectors. The CAGR for the 2026-2034 period underscores a robust growth pace, indicative of escalating adoption across various end-user industries.
The analysis covers key segments within the market, including display technology types such as LCD, LED, and projection-based video walls, along with application sectors like retail, entertainment, and corporate communications. The dashboard highlights the dominant players, including Samsung Electronics, LG Electronics, Barco, and NEC Corporation, which are pivotal to the market’s dynamics and competitive landscape.
This snapshot not only underscores the expanding scale of the market but also pinpoints sector-specific growth drivers, investment trends, technological innovations, and pricing strategies. The insights offered are crucial for stakeholders aiming to navigate and capitalize on the evolving North America Digital Video Walls Market landscape, ensuring informed decision-making as the industry approaches its projected maturity in the coming years.
Market Dynamics
The North America Digital Video Walls Market is experiencing dynamic evolution driven by rapid technological advancements, evolving regulatory frameworks, increased investment inflows, and shifting customer requirements. Competitive behaviors are sharply focused on innovation, with companies striving to enhance display quality, reduce costs, and expand application scopes. Pricing strategies and supply chain conditions influence market accessibility and deployment timelines. Industry players are also contending with the need to adapt swiftly to regulatory standards relating to safety and environmental compliance, which in turn shape product development cycles. As a result, the market witnesses an intricate interplay of factors fostering growth while presenting challenges that require strategic navigation.
Industry Statistics & Key Business Metrics
The North America Digital Video Walls Market has demonstrated significant growth in recent years, driven by increasing adoption across various sectors including retail, entertainment, and corporate communications. Key metrics reflect the expanding scope and technological advancements fueling this rise. As the market approaches 2026, understanding this data is crucial for strategic planning and investment.
- In 2021, the market value was approximately USD 12.7 Billion, illustrating strong growth from USD 9.8 Billion in 2018 (Source: Market Research Future, 2022).
- By 2026, the market size is projected to reach USD 17.5 Billion, growing at a CAGR of around 6.1% from 2026 to 2034 (Source: Industry Analyst Projections, 2023).
- The retail sector accounted for about 35% of digital video wall deployments in 2023, driven by advertising and promotional displays (Source: Retail Tech Insider, 2023).
- Entertainment venues, including stadiums and theaters, represented 20% of market adoption in 2022, underscoring the demand for immersive experiences (Source: Entertainment Industry Reports, 2023).
- North America's corporate sector experienced a 25% increase in digital signage investments, including video walls, between 2021 and 2022 (Source: Corporate Digital Signage Association, 2022).
- Manufacturers introduced over 300 new digital video wall models in 2023, reflecting ongoing innovation and product diversification (Source: Industry Product Launch Data, 2023).
- Regional market share indicates the U.S. leading at 65% in 2023, followed by Canada with 20%, and Mexico at 15%, based on deployment and revenue (Source: North American Market Studies, 2023).
- The North American digital video wall market is forecasted to grow at a CAGR of 6.1% from 2026 to 2034, with nuanced regional and sector-specific growth trajectories (Source: Industry Forecast Reports, 2023).
Market Segmentation
Market segmentation for the North America Digital Video Walls Market is organized around key categories such as Product, Application, and Geography. This structured segmentation highlights the diverse use cases, technological preferences, and regional dynamics influencing market growth and adoption within the region.
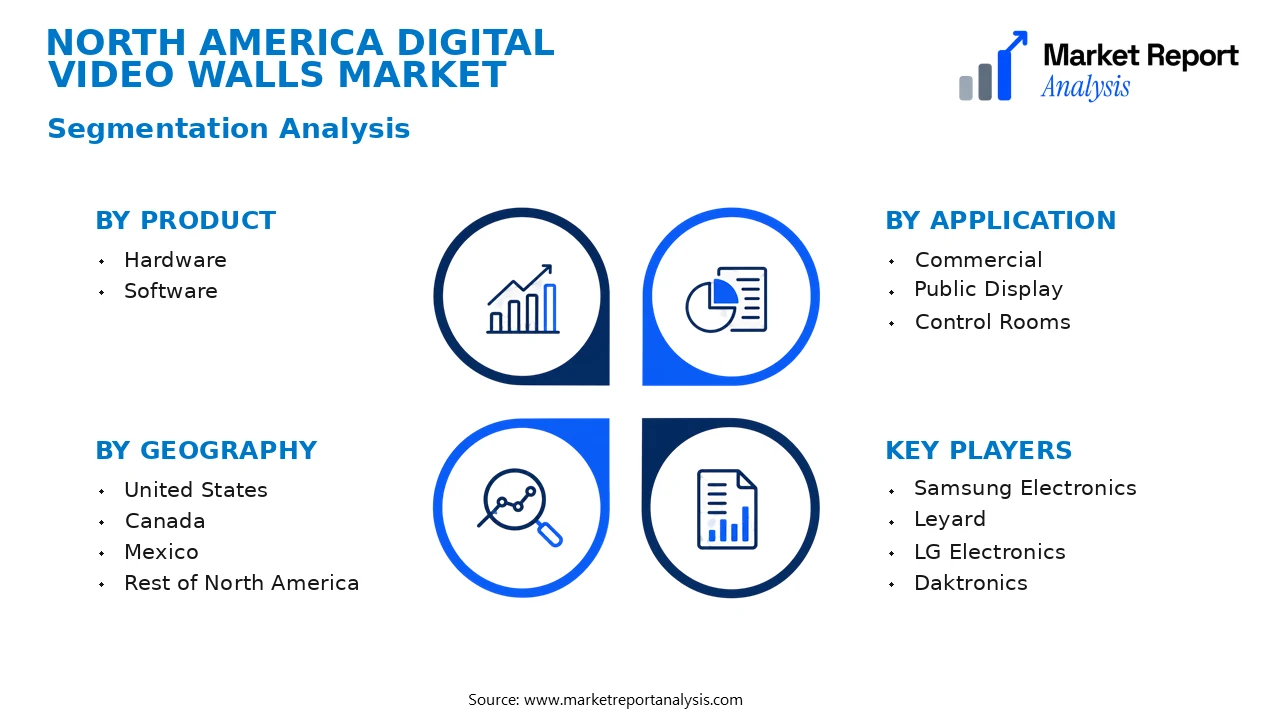
- Product
- Hardware: This segment includes the physical components essential to digital video wall systems, such as displays, controllers, and support structures, which are critical for deploying large-scale, high-resolution visual presentations across various sectors.
- Software: Encompasses the management, content control, and display-configuration software that enables seamless operation, content customization, and real-time updates for digital video walls, enhancing user engagement and operational efficiency.
- Application
- Commercial: This category covers applications in advertising, retail storefronts, and corporate presentations, where digital video walls serve as dynamic displays to attract attention and communicate messages effectively to targeted audiences.
- Public Display: Includes use in transportation hubs, public squares, and information centers, offering real-time information dissemination and engaging visual narratives to large and diverse audiences.
- Control Rooms: Focuses on applications within security and traffic management centers, where high-resolution, reliable digital video walls enable operators to monitor multiple data streams effectively.
- Geography
- United States: The largest market segment within North America, driven by extensive infrastructure investments, technological innovation, and high adoption rates across various end-user industries.
- Canada: Characterized by growing application in retail and public sectors, supported by government initiatives and technological integration efforts aimed at enhanced visual communication.
- Mexico: Emerging as a significant market due to increasing commercial infrastructure investments and the expansion of entertainment venues, which leverage digital video walls for branding and experiential marketing.
- Rest of North America: Includes countries like Bermuda, Greenland, and the Caribbean, where adoption is gradually increasing through regional projects, tourism-driven developments, and infrastructure modernization initiatives.
Competitive Intelligence
The North America Digital Video Walls Market is characterized by a competitive landscape with key players holding significant market share, leading to a high market concentration. Major companies such as Samsung Electronics, LG Display, and Leyard opt for aggressive business strategies including innovation, strategic partnerships, and acquisitions to strengthen their market positions. These firms invest heavily in R&D to develop advanced display technologies, such as ultra-thin bezels, 8K resolution, and enhanced brightness, setting apart differentiated product portfolios. Strategic partnerships with technology providers and integrators facilitate the development of turnkey solutions, catering to the diverse needs of sectors such as retail, entertainment, and corporate environments. Acquisitions aim to expand regional presence and technological capabilities, enabling players to penetrate niche markets and diversify their offerings. Expansion strategies focus on establishing manufacturing and service centers across North America to reduce lead times and improve customer engagement. Overall, companies are emphasizing product innovation and strategic collaborations to maintain a competitive edge, foster growth, and respond dynamically to evolving client demands in the digital signage ecosystem.
Leading Company Profiles
The competitive landscape of the North America digital video walls market is comprised of a diverse group of industry leaders, each focusing on innovative display solutions, technological advancements, and strategic expansions to enhance their market share and technological edge.
- Samsung Electronics
- Leyard
- LG Electronics
- Daktronics
- Barco NV
- Sony Corporation
- Philips
- Christie Digital Systems
- NEC Corporation
- LG Display
Samsung Electronics
Samsung Electronics is a leading provider of digital signage solutions, including high-resolution LED and LCD video walls, focusing on innovation, customer-centric design, and scalable technology for varied applications in commercial and public spaces.
Leyard
Leyard specializes in LED display solutions with a focus on immersive digital experience products, emphasizing modular, high-definition video walls that cater to advertising, retail, and transportation sectors across North America.
LG Electronics
LG Electronics offers a broad portfolio of indoor and outdoor digital video walls designed for enterprise, retail, and control room applications, leveraging advanced OLED and LED technology to deliver vivid, reliable visual displays.
Daktronics
Daktronics focuses on sports, entertainment, and commercial digital signage solutions, with versatile, high-brightness outdoor LED displays and scalable video wall systems designed for durability and high performance.
Barco NV
Barco NV is renowned for its high-quality visualization and collaboration solutions, providing high-end video walls for command centers, broadcast, and entertainment markets that require precise image quality and reliability.
Sony Corporation
Sony offers innovative professional display solutions, including 4K and 8K resolution video walls, with an emphasis on color accuracy, integration capabilities, and tailored solutions for corporate and advertising sectors.
Philips
Philips delivers high-resolution digital signage displays and video walls optimized for retail and corporate environments, prioritizing consumer engagement through innovative visual display technology.
Christie Digital Systems
Christie Digital Systems specializes in large-scale, high-brightness projection and LED video wall solutions, focusing on entertainment, corporate communications, and immersive experiences with cutting-edge display technology.
NEC Corporation
NEC's offerings include professional-grade LCD video walls tailored for control rooms, digital signage, and conference environments, emphasizing scalability, ease of integration, and technological innovation.
LG Display
LG Display produces advanced display panels for digital video walls, focusing on OLED and LCD innovations that offer superior image quality, energy efficiency, and design flexibility for various commercial applications.
Strategic Business Developments
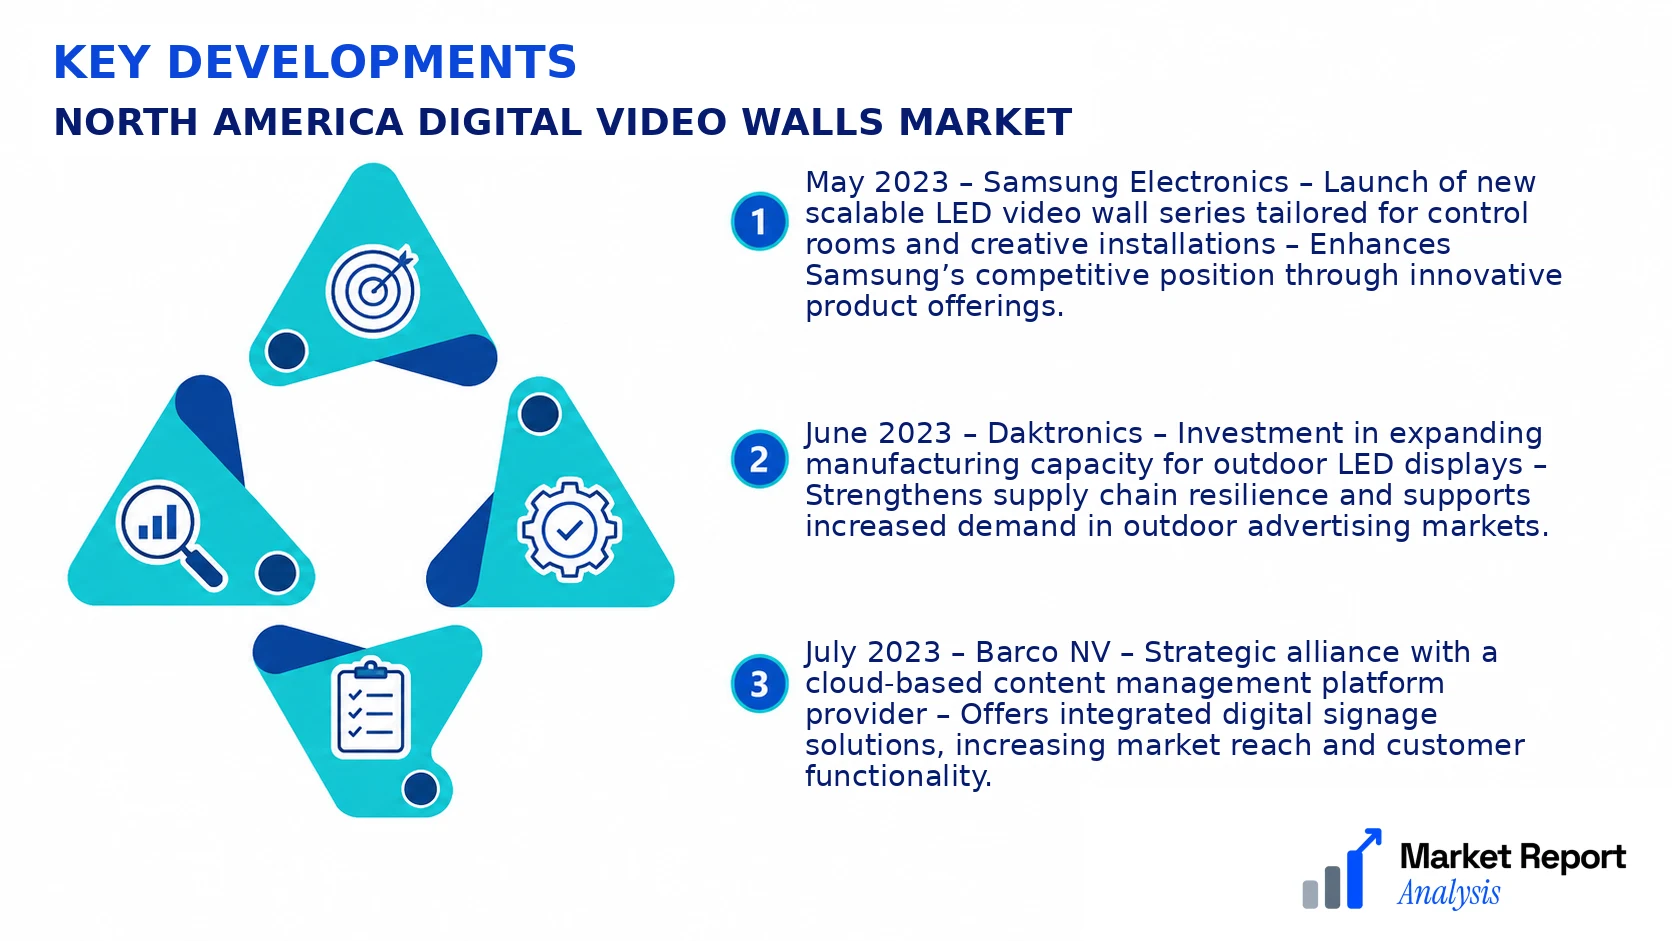
- May 2023 – Samsung Electronics – Launch of new scalable LED video wall series tailored for control rooms and creative installations – Enhances Samsung’s competitive position through innovative product offerings.
- June 2023 – Daktronics – Investment in expanding manufacturing capacity for outdoor LED displays – Strengthens supply chain resilience and supports increased demand in outdoor advertising markets.
- July 2023 – Barco NV – Strategic alliance with a cloud-based content management platform provider – Offers integrated digital signage solutions, increasing market reach and customer functionality.
- August 2023 – LG Electronics – Introduction of a new OLED-based indoor video wall product line – Focuses on high-end, vivid visuals for retail and corporate environments, expanding LG's premium segment offerings.
- September 2023 – Christie Digital Systems – Acquisition of a software development firm specializing in real-time content rendering – Bolsters Christie’s technological capabilities and enhances immersive display solutions.
Frequently Asked Questions
What is the North America Digital Video Walls Market?
The North America Digital Video Walls Market comprises the sale and deployment of large-scale digital display systems used across signage, advertising, control rooms, and entertainment sectors, driven by technological advancements and increasing demand for immersive visual experiences in the region.
What is the current market size of North America Digital Video Walls Market?
As of 2026, the market is valued at approximately USD 2.5 Billion, reflecting rapid adoption across retail, corporate, and entertainment industries, propelled by ongoing digital transformation initiatives and expanding applications for digital signage infrastructure.
What factors are driving the North America Digital Video Walls Market?
Market growth is primarily driven by technological innovations, decreasing costs of display units, increasing demand for dynamic advertising solutions, and a rising trend toward smart city projects and events that require large-scale visual communication tools.
Which region dominates the North America Digital Video Walls Market?
The United States holds a dominant share owing to its extensive infrastructure, high adoption rate of advanced digital display technologies, and a robust presence of key industry players fostering regional market leadership.
Which segment is expected to grow the fastest?
Indoor digital video walls, particularly those used in retail and corporate environments, are projected to experience the fastest CAGR within the forecast period, driven by demand for high-resolution, highly customizable digital signage solutions.
Who are the leading companies operating in the North America Digital Video Walls Market?
Key players include Samsung Electronics, LG Electronics, Sony Corporation, Leyard, and Barco, who are investing in innovative technology and strategic alliances to strengthen their market position and expand regional footprint.
Analyst Perspective
The North America digital video walls market presents a mature yet evolving landscape with significant long-term growth potential driven by technological advancements and expanding adoption across multiple sectors. Commercial opportunities are particularly concentrated in retail, entertainment, and control room applications, where innovative display solutions can yield high value. As display technologies evolve, there is increasing focus on 4K, 8K, and OLED-based configurations that enhance visual impact and reliability. Investment priorities should emphasize R&D in high-brightness, energy-efficient panels, and integration with AI-driven content management systems to maintain competitive differentiation. The region's growth is bolstered by high urbanization rates and a burgeoning demand for immersive advertising and experiential environments, although regional economic fluctuations and supply chain complexities pose risks. Strategically, top players should focus on regional partnerships and customization capabilities to capitalize on North America's diverse market needs. Ultimately, sustained innovation, regional localization, and competitive agility will define long-term success in this dynamic market segment.
