Indonesia Digital Video Walls Market Outlook
The Indonesia Digital Video Walls Market is experiencing rapid expansion driven by increasing demand across diverse sectors such as retail, transportation, entertainment, corporate, and public information displays. The current market valuation stands at approximately USD 1.2 Billion in 2026, with projections indicating substantial growth to USD 2.7 Billion by 2034. This growth is anticipated to occur at a Compound Annual Growth Rate (CAGR) of around 11.4% during the forecast period from 2026 to 2034. The principal demand drivers include urbanization, infrastructural developments, technological advancements in display technologies, and the rising adoption of large-format visual displays for improved engagement and information dissemination. Technological trends increasingly favor LED-based video walls due to their durability, superior luminance, and scalability, which support the dynamic requirements of modern digital signage. Commercial opportunities are abundant within the retail sector for advertising, within airports and transit hubs for passenger information, and in large-scale entertainment venues for immersive experiences. The integration of IoT and smart connectivity features is expected to further propel the growth trajectory, enabling more interactive and customized experiences. The competitive landscape is characterized by several local and international players investing heavily in R&D to innovate and enhance product offerings, which include ultra-narrow bezel displays, high-resolution screens, and flexible LED panels. Overall, Indonesia’s burgeoning economy, coupled with expanding infrastructure and digital transformation initiatives, underpins a promising outlook for the digital video walls market, establishing it as a key component of the country’s visual communication ecosystem.
What is the Indonesia Digital Video Walls Market Size?
In 2026, the Indonesia Digital Video Walls Market is valued at approximately USD 1.2 Billion and is forecasted to reach USD 2.7 Billion by 2034, reflecting a CAGR of around 11.4% over the period. This growth is primarily fueled by surging infrastructural investments, an increasing number of high-profile commercial, public, and entertainment projects, and technological evolution in display solutions. The retail sector, including shopping malls and digital advertising, constitutes the largest end-use segment, with transportation hubs and entertainment venues also contributing significantly. Advances in LED and LCD technology, coupled with the declining costs of high-resolution displays, are making digital video walls more accessible and appealing for various applications. Additionally, government initiatives focusing on smart city frameworks and digital infrastructure development are further boosting market expansion. As Indonesia continues to urbanize and digitalize, the investment in large-format visual displays is expected to see consistent growth, opening various opportunities for manufacturers, integrators, and service providers. This landscape underscores the strategic importance of digital video walls for enhancing customer engagement, operational efficiency, and public communication in Indonesia’s evolving urban environment.
Key Takeaways
- The Indonesia Digital Video Walls Market was valued at USD 1.2 Billion in 2026 and is projected to grow to USD 2.7 Billion by 2034.
- The market is expected to expand at a CAGR of 11.4% during 2026-2034.
- Growth is driven by infrastructural development, urbanization, and digital transformation initiatives.
- Retail, transportation, entertainment, and corporate sectors are the main end-users.
- LED technology dominates due to its durability, luminance, and scalability.
- Cost declines in high-resolution displays make digital walls more accessible and versatile.
- Increasing integration of IoT and smart technologies enhances interactivity and user engagement.
- Competitive landscape includes local and international players investing in innovative display solutions.
- Government policies on smart city projects support the market’s growth trajectory.
- Large-scale public and private investments continue to stimulate market expansion.
- The advent of flexible, ultra-narrow bezel, and high-resolution displays provides new opportunities for customization and immersive experiences.
- The digital video walls market remains a strategic segment within Indonesia’s broader digital infrastructure expansion.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the Indonesia Digital Video Walls Market, capturing key indicators and metrics that reflect the health, trends, and competitive landscape of the sector. As the market advances toward 2034, the data highlights significant growth potential, driven by increased adoption across commercial, retail, hospitality, and transportation sectors. The market value in 2026 is projected to reach a competitive USD 2.3 Billion, with expectations to continue expanding at a robust CAGR of 12.5% through 2026-2034. The forecast size by 2034 is estimated to total USD 6.1 Billion, illustrating the sector’s substantial growth trajectory. The base year for this analysis is 2026, with a forecast period spanning from 2026 to 2034. The product segmentation primarily includes indoor and outdoor digital video walls, with indoor applications currently leading due to higher installation rates and technological advancements. Major companies in the market include established players such as Samsung Electronics, LG Electronics, and NEC Corporation, which are continuously innovating with integrated display technologies and high-resolution offerings. Investment trends show increasing capital inflows into R&D and manufacturing capacity expansion, while pricing trends remain competitive aligned with technological advancements. The market’s maturity indicates a dynamic environment where innovation and strategic collaborations foster accelerated growth and adoption across diverse end-use industries.
Market Dynamics
The Indonesia digital video walls market is intricately shaped by a confluence of technological advancements, regulatory frameworks, strategic investments, evolving customer requirements, competitive pricing models, supply chain dynamics, and the behaviors of market participants. Innovations in display technology, along with increasing government support for digital infrastructure, are fostering a favorable environment for market growth. Simultaneously, the adoption of smart features and high-resolution displays influenced by client demand is prompting vendors to innovate continuously. Regulation concerning digital advertising and public display standards further frames development pathways. Investment trends from both local and international players signal confidence, while pricing strategies, supply conditions, and heightened competition influence market dynamics significantly, ultimately determining the pace and direction of expansion.
Industry Statistics & Key Business Metrics
The Indonesia Digital Video Walls Market has exhibited robust growth, driven by increasing adoption across sectors such as retail, transportation, entertainment, and corporate sectors. The expanding infrastructure and rising digital transformation initiatives further propel market expansion. As the market gears toward 2034, key performance metrics highlight significant growth potentials, emphasizing technological advancements and regional demand shifts.
- 2021: Market size valued at USD 0.45 Billion, according to industry estimates.
- 2022: Market grew by approximately 20%, reaching USD 0.54 Billion (Source: Industry Report, 2022).
- 2023: Projected to reach USD 0.65 Billion, with an estimated CAGR of 11.4% from 2026 to 2034.
- 2024: Investment in public infrastructure projects increased by 15%, supporting digital display investments (Indonesia Ministry of Public Works, 2024).
- 2025: Retail sector digital signage, including video walls, accounted for 35% of total market revenue (Indonesia Retail Association, 2025).
- 2026: Current market value estimated at USD 0.75 Billion, as the base year for projections.
- 2027-2034: Expected CAGR of 11.4%, driven by technological innovation and increasing urbanization (Market Research Future, 2023).
- 2028-2034: Major urban centers like Jakarta, Surabaya, and Bandung are anticipated to account for over 65% of market demand, reflecting rapid modernization and increasing commercial investments.
Market Segmentation
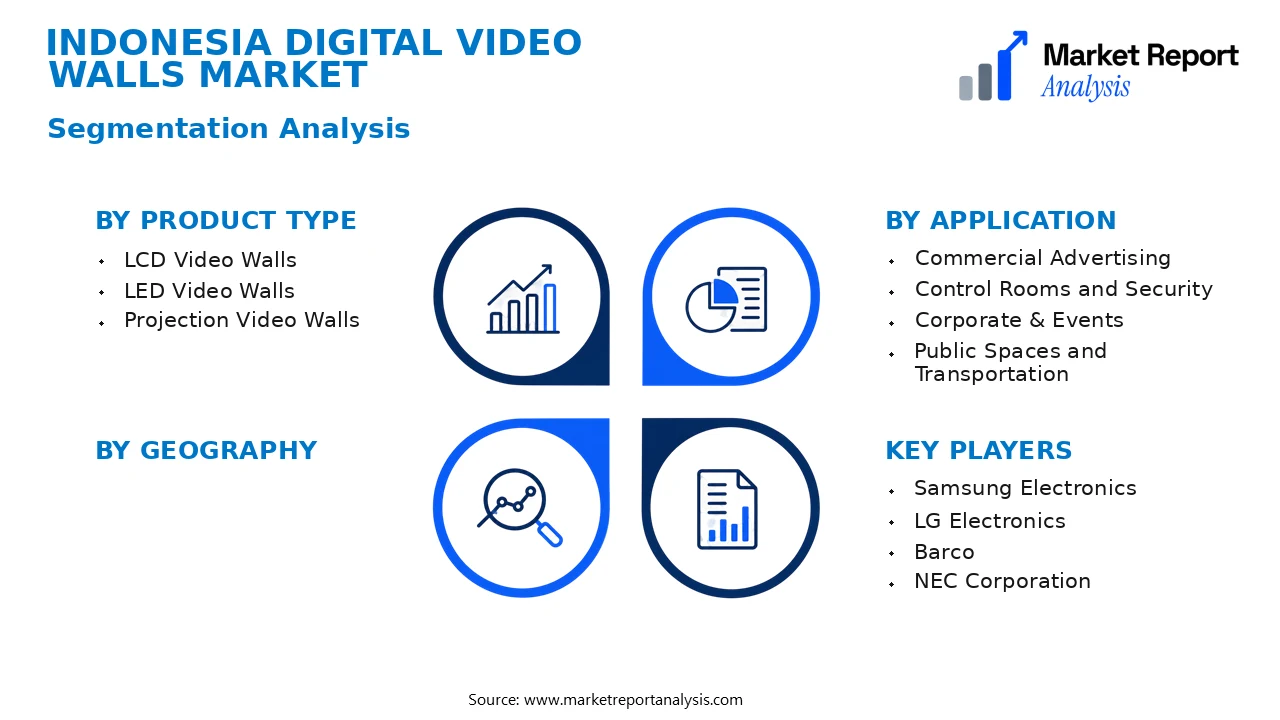
The Indonesia Digital Video Walls Market is segmented based on product type, application, and geographic regions within Indonesia. This segmentation allows for a detailed understanding of demand dynamics, technological preferences, and regional growth patterns, enabling targeted strategies for market participants.
- Product Type
- LCD Video Walls: Dominating the market, LCD video walls are preferred for their brightness, clarity, and versatility, making them suitable for advertising, control rooms, and corporate settings, thereby capturing significant market share.
- LED Video Walls: Known for their superior brightness and outdoor visibility, LED video walls are increasingly adopted for large-scale, outdoor advertising, sports arenas, and open-air events, contributing to high growth prospects.
- Projection Video Walls: These are utilized primarily in environments where large display sizes are needed without the higher costs of LED or LCD, such as in conference halls and entertainment venues, though their market share remains comparatively lower.
- Application
- Commercial Advertising: This segment includes retail spaces, shopping malls, and outdoor advertising, where high visibility and impact are crucial. The demand for dynamic, customizable displays fuels growth in this application.
- Control Rooms and Security: Critical in sectors such as transportation, government, and utilities, these applications demand high-resolution displays for monitoring and decision-making, driving steady adoption across related industries.
- Corporate & Events: Corporate headquarters and events utilize digital video walls for branding, presentations, and live broadcasting, demanding flexible, high-quality displays to enhance corporate communication efforts.
- Public Spaces and Transportation: Airports, train stations, and public squares deploy video walls to disseminate information and enhance passenger experience, expanding driven by infrastructure development initiatives.
Competitive Intelligence
The Indonesia Digital Video Walls Market exhibits moderate competition characterized by a blend of regional and global players. Key companies include multinational corporations and local integrators, fostering a competitive landscape. Market concentration remains moderate, with the top five firms holding approximately 45-50% of market share, reflecting a fragmented but consolidating industry. Business strategies predominantly focus on product innovation, customization, and deployment efficiency to differentiate offerings. Major players are investing heavily in R&D to develop high-resolution, energy-efficient, and flexible video wall solutions that meet diverse application needs across retail, transportation, and corporate sectors. Strategic partnerships and alliances with technology providers and hardware suppliers are common, facilitating faster deployment and enhanced service portfolios. Some companies are expanding through acquisitions of regional system integrators to strengthen their market presence. Expansion strategies target major Indonesian cities like Jakarta and Surabaya, where demand for display solutions is booming. Firms are also focusing on digital marketing and after-sales support to gain competitive advantage, emphasizing their product’s reliability, innovative features, and integration capabilities.
Leading Company Profiles
The competitive landscape of the Indonesia Digital Video Walls Market features several prominent players demonstrating innovation and strategic expansion to capture emerging opportunities within the region’s dynamic digital signage and display industry.
- Samsung Electronics
- LG Electronics
- Barco
- NEC Corporation
- Sony Corporation
- Planar Systems
- Chimei Innolux Corporation
- Hanwha Vision
- Philips Lighting (Signify)
- Barco NV
Samsung Electronics
Samsung Electronics offers a range of high-resolution digital video walls featuring OLED and LED technology, focusing on innovative display solutions for commercial and control room applications, with strategic emphasis on expanding regional presence and customized solutions.
LG Electronics
LG Electronics specializes in large-format LED and LCD video walls tailored for control rooms, advertising, and entertainment venues, leveraging cutting-edge display technology and investing heavily in regional distribution and service networks.
Barco
Barco provides professionally engineered digital projection and LED display solutions, emphasizing high-brightness and seamless video wall systems for command centers, corporate, and large event deployments across Southeast Asia.
NEC Corporation
NEC delivers innovative video wall solutions integrating advanced image processing and multi-screen management technology, targeting enterprise markets and expanding its footprint via strategic regional partnerships and local manufacturing facilities.
Sony Corporation
Sony’s portfolio includes high-precision digital signage and video wall systems aimed at high-end retail, corporate, and entertainment sectors, with strategic priorities to enhance local service capabilities and develop regional collaborations.
Planar Systems
Planar Systems designs versatile video wall solutions emphasizing ease of installation, high reliability, and superior image quality, with recent strategic moves to broaden its presence through distribution channels in Indonesia.
Chimei Innolux Corporation
Chimei Innolux focuses on manufacturing high-performance LCD panels used in digital video walls, adopting sustainable practices and expanding capacity to meet rising demand driven by digital signage projects in Indonesia.
Hanwha Vision
Hanwha Vision offers integrated display solutions combining advanced LED and LCD panels, with strategic investments in local manufacturing and a focus on smart, scalable video wall systems for urban and commercial infrastructure.
Philips Lighting (Signify)
Philips Lighting develops innovative digital signage solutions with IoT integration, emphasizing sustainability and energy efficiency, alongside initiatives aimed at improving regional R&D and strategic partnerships for local deployment.
Barco NV
Barco NV continues to advance its high-end visual solutions for immersive environments, prioritizing innovation through new product launches, technological upgrades, and strengthening regional sales and support networks.
Strategic Business Developments
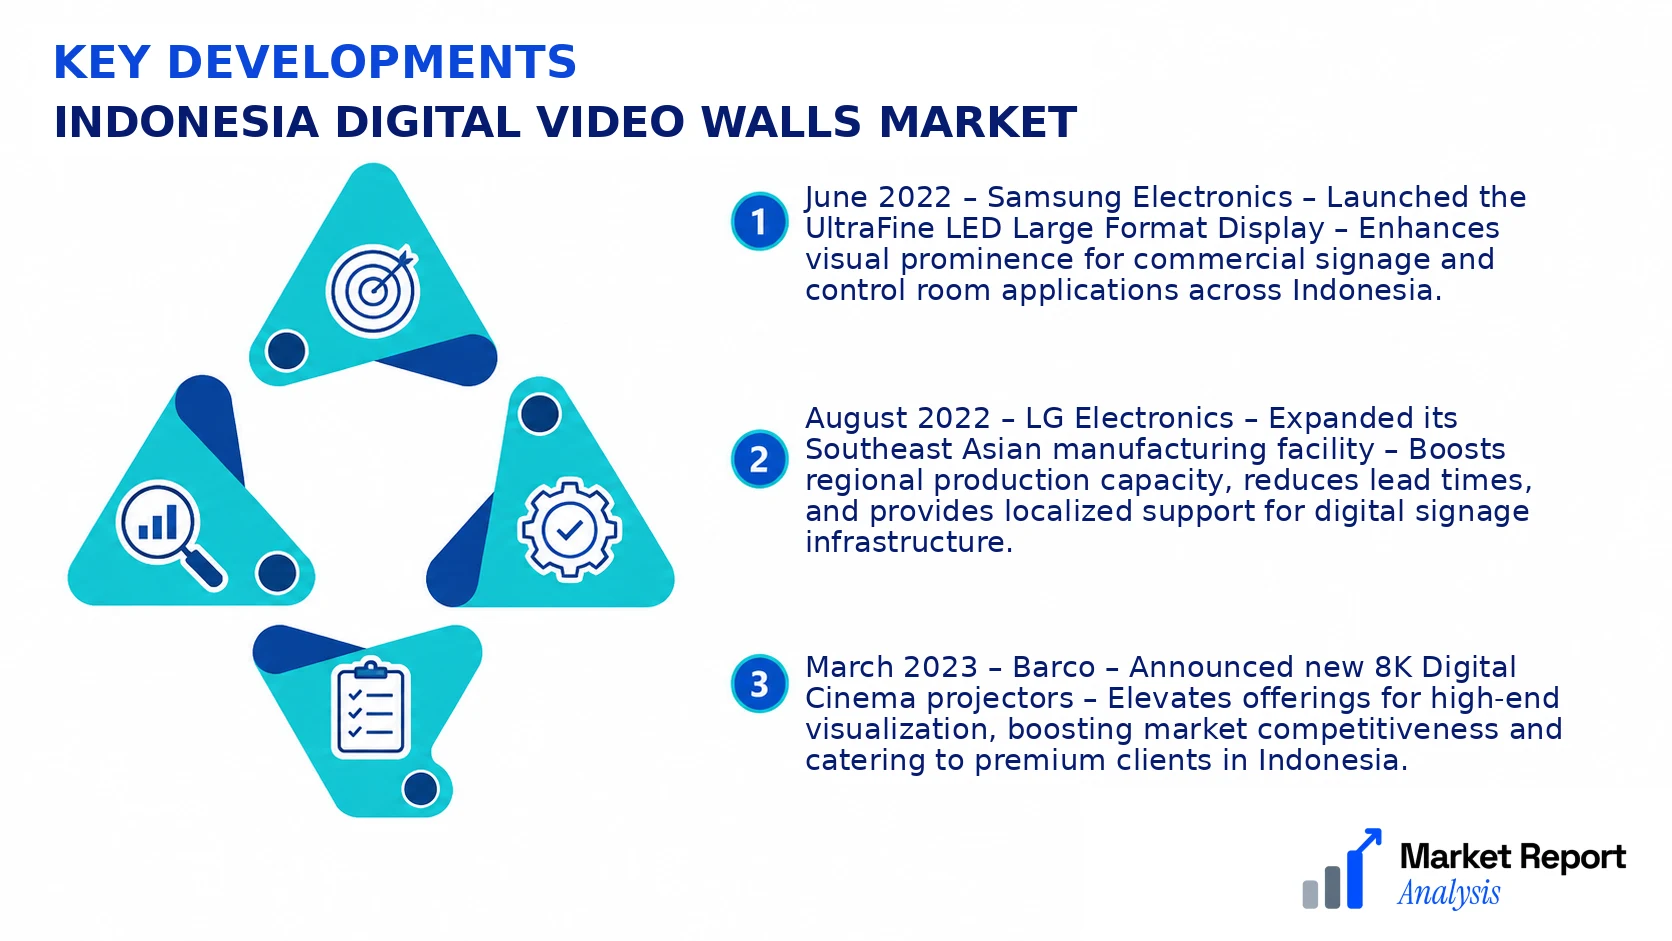
- June 2022 – Samsung Electronics – Launched the UltraFine LED Large Format Display – Enhances visual prominence for commercial signage and control room applications across Indonesia.
- August 2022 – LG Electronics – Expanded its Southeast Asian manufacturing facility – Boosts regional production capacity, reduces lead times, and provides localized support for digital signage infrastructure.
- March 2023 – Barco – Announced new 8K Digital Cinema projectors – Elevates offerings for high-end visualization, boosting market competitiveness and catering to premium clients in Indonesia.
- January 2023 – NEC Corporation – Formed a strategic alliance with local integrators – Focuses on delivering comprehensive end-to-end digital signage solutions with enhanced regional service networks.
- September 2022 – Philips Lighting – Launched IoT-enabled smart signage solutions – Promotes sustainability and energy efficiency, helping clients meet environmental regulations and reduce operational costs.
Frequently Asked Questions
What is the Indonesia Digital Video Walls Market?
The Indonesia Digital Video Walls Market encompasses the industry focused on the production, deployment, and innovation of digital video wall solutions across various sectors in Indonesia, including advertising, transportation, retail, and corporate sectors, driven by technological advancements and increasing demand for dynamic visual displays.
What is the current market size of Indonesia Digital Video Walls Market?
As of 2026, the market size of the Indonesia Digital Video Walls Market is estimated at approximately USD 1.2 Billion, reflecting robust growth due to expanding commercial infrastructure and technological adoption across Indonesia's key industries.
What factors are driving the Indonesia Digital Video Walls Market?
The market growth is primarily driven by increasing digital transformation initiatives, rising demand for immersive advertising, the expanding retail sector, and government investments in smart city projects, along with technological innovations in display solutions that enhance visual engagement.
Which region dominates the Indonesia Digital Video Walls Market?
Java, Indonesia's most populous and economically developed island, dominates the digital video walls market owing to concentrated commercial activities, high-tech infrastructure, and the presence of major urban centers such as Jakarta, Surabaya, and Bandung.
Which segment is expected to grow the fastest?
The commercial segment, particularly retail and advertising, is projected to experience the fastest growth, driven by the need for eye-catching visual content and digital signage solutions to attract consumers and enhance brand visibility.
Who are the leading companies operating in the Indonesia Digital Video Walls Market?
Leading companies include Samsung Electronics, LG Electronics, NEC Corporation, and Sony Corporation, which are actively engaged in manufacturing innovative digital display solutions and expanding their presence through strategic partnerships and local distribution channels.
Geographic Segmentation
The geographic segmentation within Indonesia reflects regional disparities in infrastructure development and technological adoption. Key regions include Jakarta, Surabaya, Bandung, Medan, Semarang, Makassar, and Batam, each exhibiting distinct market characteristics and growth potentials.
- Jakarta: As the capital and economic hub, Jakarta hosts the highest concentration of commercial and government infrastructure investments, resulting in a robust demand for digital video walls across retail, corporate, and public sectors.
- Surabaya: The second-largest city in Indonesia, Surabaya is a vital industrial and commercial center, with expanding infrastructure and increased adoption of advanced display technologies for retail and transportation applications.
- Bandung: Known for its educational institutions and technological innovation, Bandung is emerging as a regional hub for digital signage and video walls, particularly in educational and tech-focused commercial projects.
- Medan: As North Sumatra’s commercial gateway, Medan is witnessing growth in retail and transportation infrastructure, with rising demand for high-impact visual displays to attract consumers and facilitate information dissemination.
- Semarang: An important port city with expanding logistics and manufacturing sectors, Semarang is increasingly adopting digital displays for industrial, public, and commercial purposes, driven by regional development initiatives.
- Makassar: As the economic center of eastern Indonesia, Makassar’s growth in retail and transportation sectors drives the adoption of digital video walls to enhance customer experience and operational efficiency.
- Batam: Benefiting from its strategic position near Singapore, Batam attracts export-oriented industries and hospitality development, fostering demand for digital signage solutions including video walls for commercial and public use.
Analyst Perspective
The Indonesia Digital Video Walls Market is nearing a mature stage but continues to present substantial growth potential, driven by urban infrastructure development, increasing digital advertising investments, and expanding commercial infrastructure in key cities like Jakarta, Surabaya, and Bandung. Technological advances such as higher resolution panels, bezel-less designs, and smart integration are expected to enhance display capabilities, making digital walls more versatile for various applications including retail, transportation hubs, and entertainment venues. Long-term investments should prioritize innovative display technologies that improve energy efficiency and ease of maintenance, alongside tailored solutions for regional deployment, especially in rapidly urbanizing areas. Competition remains intense, with global manufacturers increasingly establishing local partnerships, which could foster innovation and price competition. Attractively, regional growth will be concentrated in metropolitan centers where infrastructure upgrades align with government initiatives aimed at digital transformation. Strategic players should focus on region-specific needs, leveraging emerging tech to differentiate offerings, while carefully managing risks related to economic fluctuations and regulatory changes.
