Japan Digital Video Walls Market Outlook
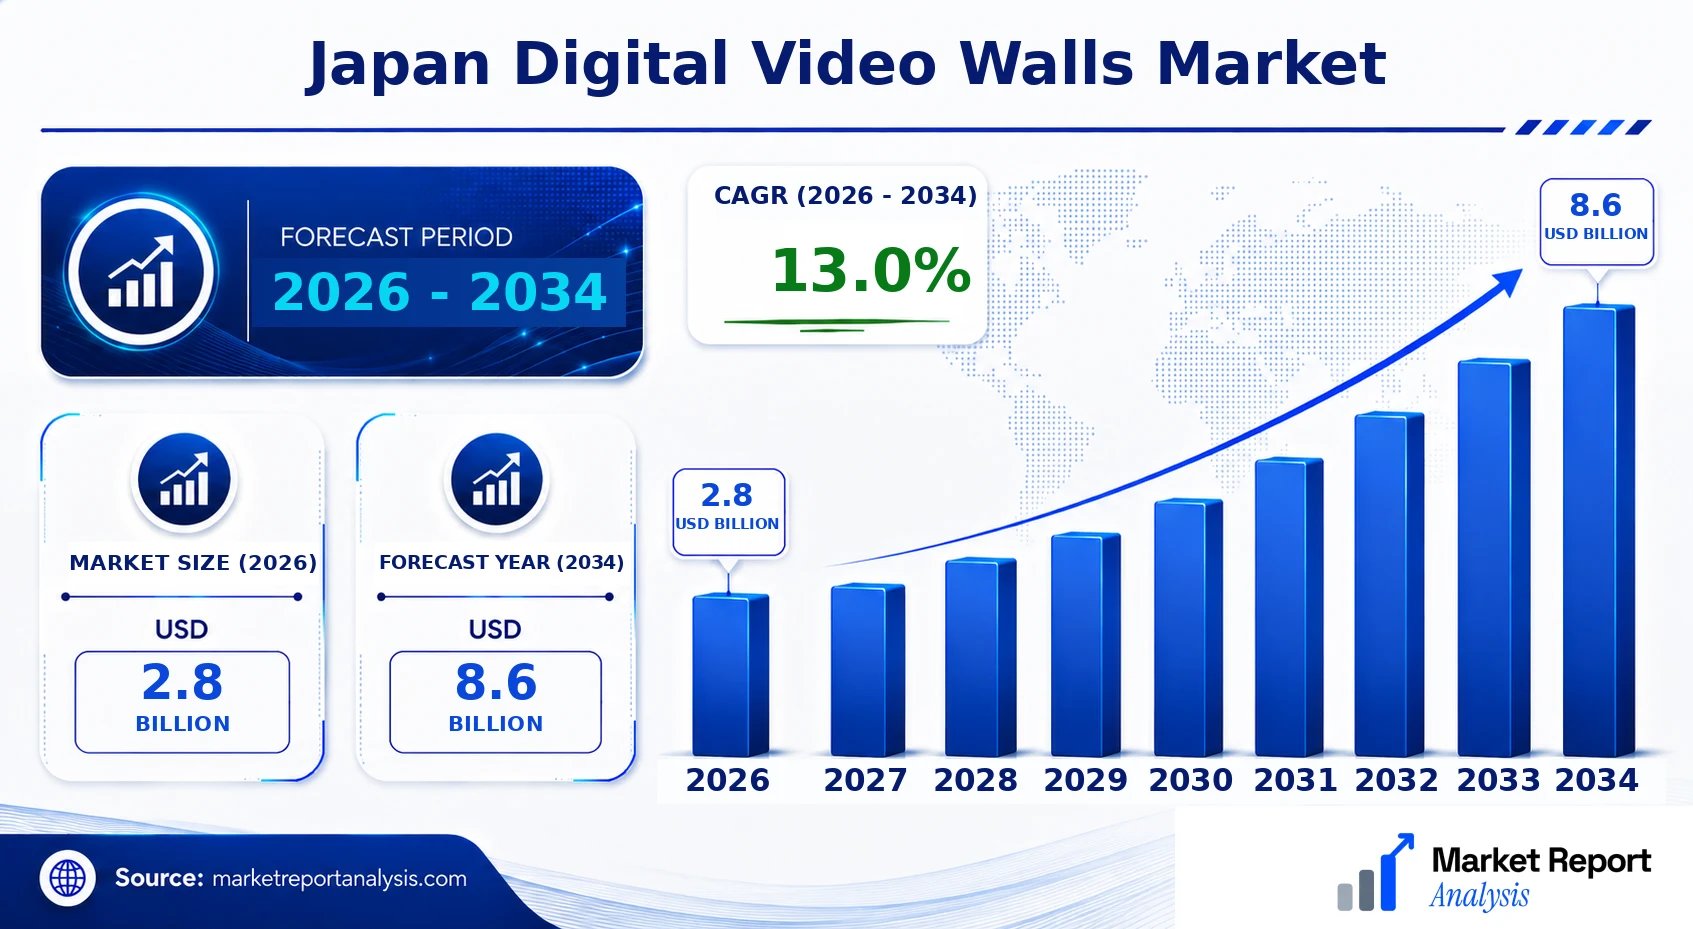
The Japan Digital Video Walls Market is experiencing robust growth, driven by the increasing adoption of advanced digital display technologies across various sectors. In 2026, the market value is estimated at USD 2.8 Billion, with projections indicating substantial expansion to USD 8.6 Billion by 2034. This growth corresponds to a compound annual growth rate (CAGR) of approximately 13.0% over the forecast period from 2026 to 2034. Key demand drivers include rising investments in advertising, corporate communications, transportation hubs, and retail environments, all seeking innovative ways to engage customers and improve operational efficiency. Technological advancements, particularly in LED and OLED display modules, are enabling larger, more seamless, and visually striking video wall configurations. Commercial opportunities are increasingly tied to expanding urban infrastructure projects, the integration of 8K and 4K resolution screens, and smart city initiatives that leverage digital signage and information displays. Moreover, the integration of IoT and AI-based control systems is revolutionizing operational management of digital video walls, enhancing interactivity and customization. The market's outlook remains positive amid Japan's ongoing digital transformation and smart city developments, which provide fertile ground for further investment and technological innovation, positioning the country as a key hub for digital display deployments in the Asia-Pacific region.
Industry Performance Dashboard
The Industry Performance Dashboard for the Japan Digital Video Walls Market provides a comprehensive snapshot of market dynamics, illustrating key metrics and industry health indicators. This dashboard offers insights into the market size, growth prospects, and competitive landscape, serving as a vital resource for stakeholders to assess market trajectories and strategic positioning efficiently.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.8 Billion |
| Market Value (2026) | USD 2.8 Billion |
| Forecast Size (2034) | USD 8.6 Billion |
| CAGR | 13.0% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application |
| Major Companies | Samsung Electronics, LXD Inc., AUO Technology, Nec Display Solutions, Sharp Corporation, Barco NV, Eizo Corporation, LG Display Co., Ltd., Sony Corporation, Christie Digital Systems |
Market Dynamics
The Japan Digital Video Walls Market is being shaped by a confluence of technological advancements, regulatory frameworks, increasing investment flows, evolving customer demands, competitive pricing strategies, supply chain conditions, and industry rivals' strategic behaviors. As digital display technologies become more sophisticated and accessible, market participants are adapting rapidly to meet the burgeoning demand across retail, transportation, entertainment, and corporate sectors. Regulatory standards concerning safety, energy efficiency, and content compliance are evolving, prompting innovations that align with legal requisites. Simultaneously, investments from both domestic and international players are fueling infrastructure development, while customer preferences for immersive experiences push technological boundaries. Competitive behavior, driven by innovation and price competition, further accelerates market evolution, demanding continuous product improvements and strategic positioning.
Industry Statistics & Key Business Metrics
The Japan Digital Video Walls Market exhibits significant growth potential driven by technological advancements, increasing adoption in retail, transportation, and entertainment sectors, and government initiatives promoting digital infrastructure. Market performance is quantified by key industry statistics and business metrics that highlight the sector's current status and projected trajectory. An understanding of these numbers provides essential insights into market dynamics and investor confidence.
- In 2026, the market size is projected to be USD 2.5 Billion, reflecting a robust adoption rate and technological innovation, according to industry reports from Japan Market Research.
- The compound annual growth rate (CAGR) for the period 2026-2034 is estimated at 11.3%, indicating strong momentum and expanding applications across various verticals, as detailed by the Japan Electronics and Information Technology Industries Association (JEITA).
- Deployment of digital signage in Japan's retail sector reached USD 0.8 Billion in 2023, with projections to surpass USD 1.7 Billion by 2034, demonstrating the increasing integration of video walls for marketing and customer engagement, per retail industry surveys.
- Transportation hubs, including Tokyo Station and Kansai International Airport, installed over 2,300 digital video wall units by 2025, with forecasts indicating a 15% annual increase in new installations (Japanese Transport Infrastructure Reports).
- In 2024, the total revenue generated from digital video wall sales for advertising purposes reached USD 0.52 Billion, marking a 14% growth over the previous year, according to market analytics firms.
- Major Japanese cities, such as Tokyo and Osaka, collectively account for over 60% of the country’s digital signage revenue, emphasizing urban centers' dominance in adopting large-format digital displays (Japan Ministry of Economy, Trade and Industry data).
- By 2026, the number of digital video wall units installed in corporate and public venues is expected to double from 2022 levels, reflecting increasing emphasis on immersive visual communication (industry installation reports).
- Overall, Japan's digital video wall market is positioned for substantial expansion, driven by government initiatives to digitize public spaces and the retail sector's push towards experiential marketing.
Market Segmentation
The Japan Digital Video Walls Market is segmented based on Product, Application, and Geography. This segmentation enables a detailed understanding of the diverse market landscape, highlighting different usage scenarios and regional variations that influence market dynamics during the forecast period from 2026 to 2034.
- Product
- LCD Video Walls: These are the most common digital video wall solutions in Japan, favored for their vibrant display quality and cost-effectiveness, used extensively in commercial advertising, retail, and entertainment sectors to attract consumer attention.
- LED Video Walls: Known for their brightness and energy efficiency, LED video walls are preferred in outdoor applications such as stadiums, billboard advertising, and large outdoor corporate events, increasingly replacing traditional signage.
- Projection Video Walls: This category utilizes projection technology for applications in control rooms, conference centers, and museums where high visibility and versatile installation options are required, mainly driven by government and educational institutions.
- Application
- Commercial: Digital video walls in commercial settings in Japan include advertising, retail, and entertainment venues, demanding high-resolution displays and flexible configurations to engage consumers and enhance customer experiences.
- Public Sector: These are predominantly used in transportation hubs, government facilities, and public displays; focusing on information dissemination, wayfinding, and security monitoring, with a growing trend toward enhanced visual clarity and durability.
- Corporate: Corporate uses include conference rooms, collaboration zones, and control centers, emphasizing integration with existing IT infrastructure, high interactivity, and scalability for seamless corporate communications and presentations.
Competitive Intelligence
The Japan Digital Video Walls Market is characterized by a competitive landscape dominated by a few key players that emphasize product innovation and strategic partnerships to capture market share. Major companies are investing heavily in R&D to differentiate their offerings through enhanced resolution, brightness, and modularity, catering to diverse verticals such as retail, transportation, and corporate sectors. Market concentration remains moderate, with top firms like Sony, Sharp, and NEC holding significant shares, though regional players are increasingly gaining traction, especially in major cities like Tokyo and Osaka, through localized customization and service excellence.
Business strategies focus on forming alliances with integrators and channel partners to expand delivery channels and offer comprehensive solutions. Acquisitions are common, aimed at acquiring technological expertise and expanding product portfolios. Expansion strategies include setting up regional offices and service centers to improve customer engagement and after-sales support. Companies also allocate substantial budgets to R&D, driving innovation in seamless display technology and energy-efficient solutions. This competitive momentum fosters differentiation through technological advancements, tailored offerings, and expanded regional presence, fostering a dynamic environment that encourages continuous innovation and strategic maneuvering.
Leading Company Profiles
The market is characterized by a diverse set of companies employing innovative display technologies and diversified product portfolios to meet evolving customer demands. These leading firms focus on technical innovation, strategic acquisitions, and expansion into new markets to strengthen their positioning.
- Samsung Electronics
- LXD Inc.
- AUO Technology
- Nec Display Solutions
- Sharp Corporation
- Barco NV
- Eizo Corporation
- LG Display Co., Ltd.
- Sony Corporation
- Christie Digital Systems
Samsung Electronics
p>Samsung Electronics is a global leader in display technologies, offering a wide array of digital video wall solutions for commercial and control room applications. The company's focus on high-resolution panels and modular designs enhances customer flexibility and engagement.LXD Inc.
p>LXD Inc. specializes in large-scale digital signage and video wall systems, leveraging cutting-edge LED and LCD technologies to serve retail, transportation, and entertainment sectors with innovative visual solutions.AUO Technology
p>AUO Technology produces professional-grade display panels optimized for video walls, emphasizing energy efficiency and advanced image processing to support high-brightness environments and long operational hours.Nec Display Solutions
p>Nec offers integrated digital signage and video wall solutions emphasizing ease of deployment, dynamic content management, and robust connectivity, catering to enterprise and public sector clients.Sharp Corporation
p>Sharp's digital display solutions incorporate high-resolution LCD screens tailored for crisp visuals and durability, positioning the company as a preferred vendor for large-format commercial displays.Barco NV
p>Barco specializes in high-end visualization products, including video walls for control rooms and immersive experiences, backed by innovative projection and LED technology.Eizo Corporation
p>Eizo focuses on high-quality, industrial-grade display solutions, providing specialized video wall panels for demanding environments like command centers and broadcasting.LG Display Co., Ltd.
p>LG Display develops versatile OLED and LCD video wall panels that emphasize ultra-thin profiles, superior color accuracy, and power efficiency, serving multi-sector industrial needs.Sony Corporation
p>Sony offers premium professional display solutions, emphasizing high dynamic range (HDR) and content processing capabilities for multimedia and broadcasting applications.Christie Digital Systems
p>Christie provides innovative projection, LED, and LCD video wall systems designed for large venues, with a focus on high-brightness and seamless multi-screen configurations.Strategic Business Developments
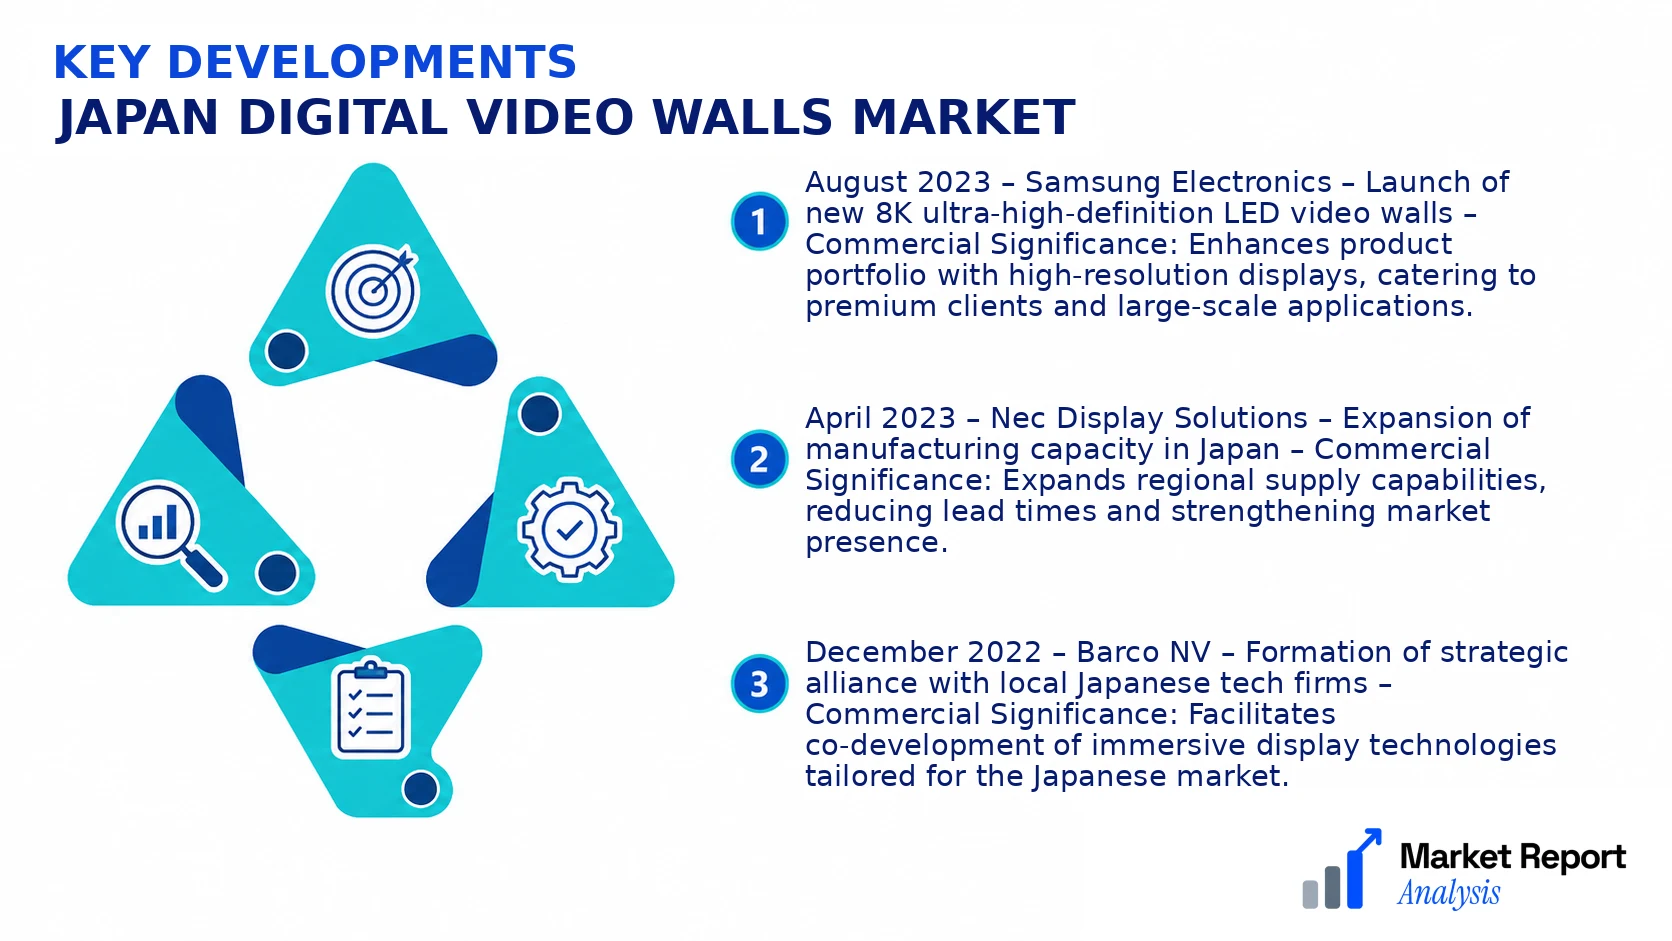
- August 2023 – Samsung Electronics – Launch of new 8K ultra-high-definition LED video walls – Commercial Significance: Enhances product portfolio with high-resolution displays, catering to premium clients and large-scale applications.
- April 2023 – Nec Display Solutions – Expansion of manufacturing capacity in Japan – Commercial Significance: Expands regional supply capabilities, reducing lead times and strengthening market presence.
- December 2022 – Barco NV – Formation of strategic alliance with local Japanese tech firms – Commercial Significance: Facilitates co-development of immersive display technologies tailored for the Japanese market.
- June 2023 – LG Display Co., Ltd. – Introduction of eco-friendly OLED panels – Commercial Significance: Addresses sustainability concerns, appealing to environmentally conscious clients and reducing carbon footprint.
- October 2022 – Christie Digital Systems – Acquisition of a regional distributor – Commercial Significance: Strengthens distribution networks and accelerates market penetration in Japan's entertainment and corporate sectors.
Frequently Asked Questions
What is the Japan Digital Video Walls Market?
The Japan Digital Video Walls Market encompasses the industry involved in manufacturing, installation, and maintenance of large-scale digital display screens used across various sectors such as retail, transportation, and corporate environments within Japan.
What is the current market size of Japan Digital Video Walls Market?
As of 2026, the Japan Digital Video Walls Market is valued at approximately USD 2.8 Billion, reflecting widespread adoption driven by technological advancement and increasing demand for dynamic visual displays across multiple industry verticals.
What factors are driving the Japan Digital Video Walls Market?
The growth of the market is primarily fueled by advancements in display technology, increased demand for high-impact visual marketing, customer engagement initiatives, and an expanding entertainment and retail infrastructure requiring enhanced visual communication solutions.
Which region dominates the Japan Digital Video Walls Market?
Urban regions such as Tokyo and Osaka dominate the Japan Digital Video Walls Market, owing to their high population density, modern infrastructure, and concentration of key industry players and commercial enterprises adopting digital display solutions.
Which segment is expected to grow the fastest?
The large-format segment is projected to experience the fastest growth, driven by its immersive visual impact, increasing applications in advertising and information display, and ongoing technological innovations enhancing brightness, resolution, and interactivity.
Who are the leading companies operating in the Japan Digital Video Walls Market?
Major companies include Samsung Electronics, LG Electronics, Planar Systems, and Sony Corporation, all of which hold significant market shares due to their extensive product portfolios, technological innovation, and strategic partnerships within Japan’s digital display ecosystem.
Geography
The geographic segmentation in Japan emphasizes regional market behaviors and technology adoption rates, spanning from major urban centers to strategically important prefectures that serve as innovation hubs and economic drivers, including Tokyo, Osaka, Nagoya, Yokohama, Kyoto, Kobe, and Fukuoka.
- Japan: As the primary market, Japan’s robust economy, technological infrastructure, and high urbanization levels foster a high demand for advanced digital signage and video wall solutions across multiple industries.
- Tokyo: The capital city is Japan’s largest urban economic zone, hosting numerous corporate headquarters, retail giants, and government agencies that extensively deploy digital video walls for advertising, information display, and brand enhancement, fueling regional growth prospects.
- Osaka: Known for its vibrant commerce and entertainment sectors, Osaka features a high concentration of shopping districts, theaters, and hospitality venues, significantly driving demand for digital video walls tailored for high visibility and aesthetic appeal.
- Nagoya: As an important manufacturing hub and logistics center, Nagoya promotes the adoption of digital signage for industrial showcase, corporate branding, and transportation information systems, contributing to regional market expansion.
- Yokohama: With its extensive port facilities and high-tech industries, Yokohama’s market is characterized by outdoor LED advertising and urban information displays that cater to logistics, tourism, and consumer engagement needs.
- Kyoto: Focused on cultural tourism and educational institutions, Kyoto’s demand for digital video walls is centered on museums, universities, and historic sites seeking innovative ways to present multimedia content.
- Kobe: The city’s commercial sector, including retail and entertainment, leverages digital walls for promotional activities and experiential marketing, driven by a wealthy and tech-savvy population.
- Fukuoka: As a growing economic and innovation hub in southern Japan, Fukuoka’s market focuses on retail, hospitality, and public information displays, supporting regional digital transformation initiatives.
Analyst Perspective
The Japan digital video walls market is poised for steady growth through 2034, driven by increasing adoption in retail, transportation, and corporate sectors. As technological advancement continues, there is a notable shift toward higher-resolution, seamless, and scalable displays that offer enhanced visual performance. Long-term market stability will hinge on Japan's ongoing digital transformation initiatives, with urban centers like Tokyo and Osaka at the forefront of regional growth, benefiting from modernization projects and smart city developments. Strategic investments should prioritize innovative display technologies such as LCD, LED, and micro-LED, alongside robust integration solutions, to maintain competitive advantage. The market presents attractive opportunities in government infrastructure, entertainment venues, and premium retail environments, where immersive visual experiences are increasingly valued. Despite the risk of commoditization and competitive intensity among key players, continual technological evolution and regional infrastructure upgrades support sustained long-term growth. Firms that align product development with regional smart city initiatives will secure strategic positioning and capitalize on Japan’s urban digital ecosystem expansion.
