Saudi Arabia Wireless Chargers Market Outlook
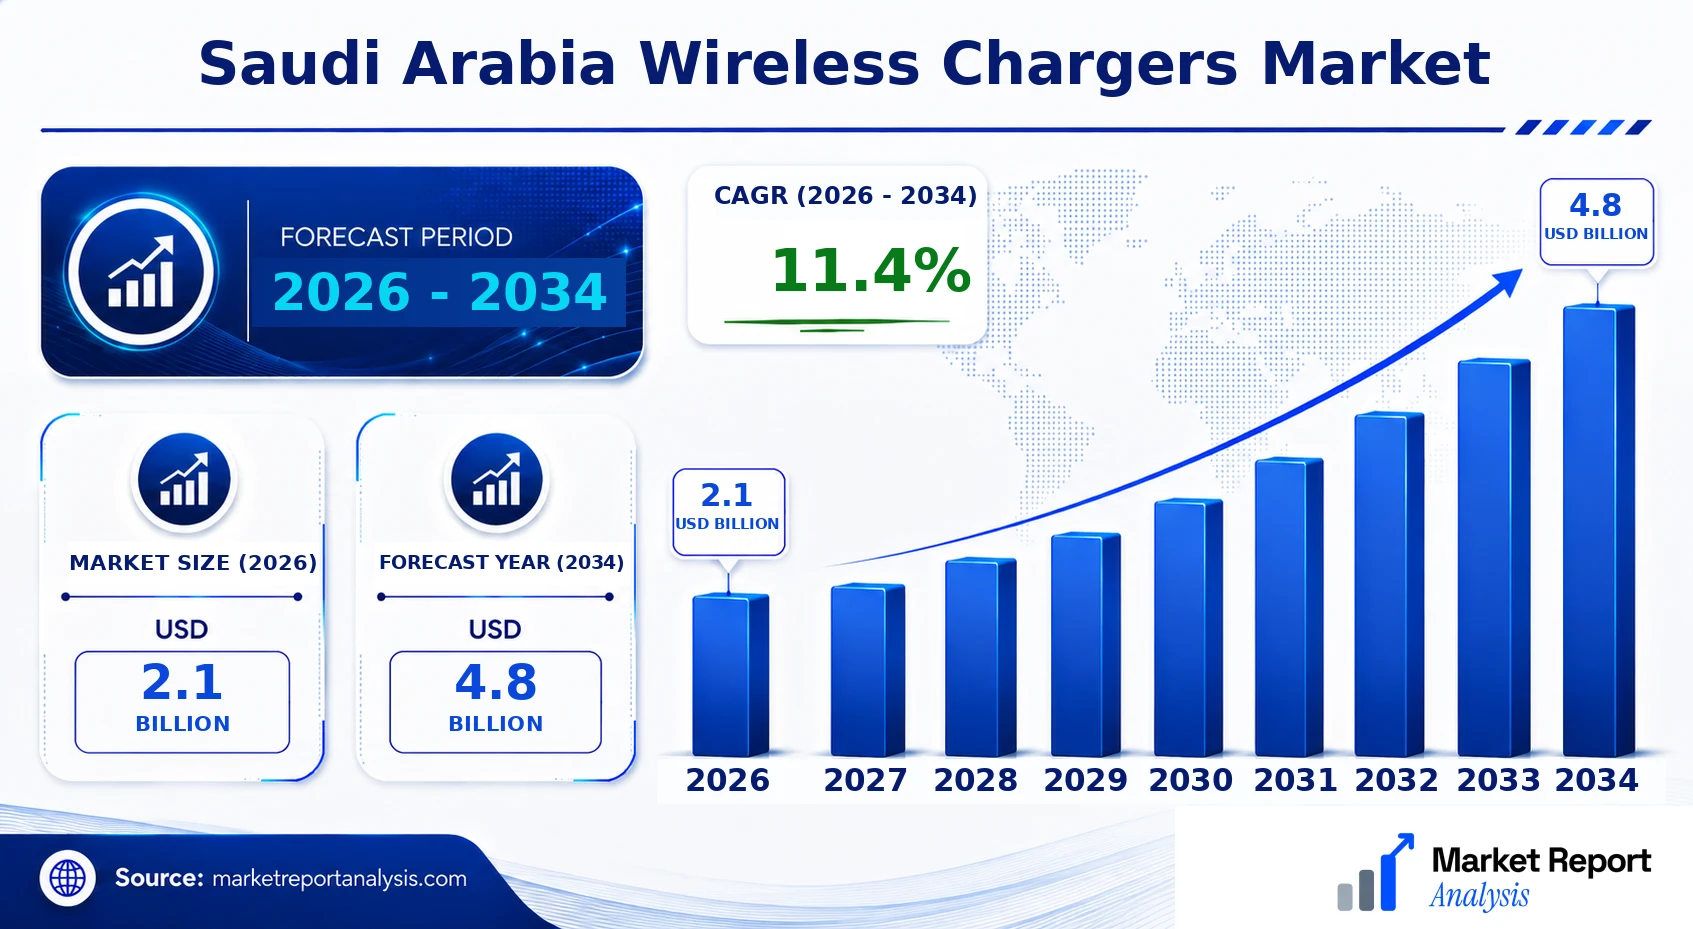
The 2026 market size is USD 2.1 Billion. The market is forecast to reach USD 4.8 Billion by 2034. The forecast CAGR for 2026-2034 is 11.4%. The Saudi Arabia Wireless Chargers Market is experiencing significant growth driven by rising consumer adoption of wireless technology, increasing smartphone penetration, and government initiatives aimed at digital transformation. The market's expansion is further fueled by the proliferation of smart devices, automotive integration, and the ascendancy of e-commerce which facilitates product accessibility. A combination of rising disposable income, evolving lifestyle preferences, and a burgeoning young population embracing technological advancements underscores the market's potential over the forecast period from 2026 to 2034. Additionally, the Saudi government's Vision 2030 aims to diversify the economy and enhance infrastructure, creating conducive conditions for market growth. The integration of wireless charging technology into automotive, public spaces, and consumer electronics in urban centers such as Riyadh and Jeddah offers substantial opportunities. Despite these positives, the market faces challenges including the high cost of advanced wireless chargers, consumer awareness levels, and the need for spectrum and standard harmonization to ensure interoperability worldwide. Nevertheless, the market is forecasted to grow at a robust CAGR, underpinned by innovation, strategic partnerships, and infrastructure developments that will sustain long-term growth prospects.
What is the Saudi Arabia Wireless Chargers Market Size?
By 2026, the Saudi Arabia wireless chargers market is anticipated to be valued at around USD 2.1 Billion, growing to USD 4.8 Billion by 2034, reflecting a CAGR of approximately 11.4% during the forecast period. The market’s expansion is driven predominantly by rising smartphone adoption, greater awareness of wireless technologies, and the increasing integration of wireless charging features into a broadening array of consumer electronics. Urban centers such as Riyadh, Jeddah, and Dammam are leading this expansion, serving as hubs for technological innovation and modern retail infrastructure. The automotive sector is also beginning to adopt wireless charging for electric vehicles, further stimulating demand across different industry verticals. As Saudi consumers progressively prefer seamless, cable-free charging solutions, there is significant sustained investment from technology players aiming to establish a dominant presence. The increasing availability of affordable wireless chargers, along with government initiatives supporting digital infrastructure, positions this market for robust growth. The rapid technological evolution, coupled with the proliferation of 5G networks and smart city projects, is likely to accelerate adoption rates, attracting both domestic manufacturers and international brands seeking strategic market entry. Future investments are expected in developing energy-efficient, durable, and aesthetically appealing charging units to meet diverse consumer demands, thus fostering a highly competitive environment across sectors including retail, automotive, and personal electronics.
Key Takeaways
- The Saudi Arabia wireless chargers market is valued at around USD 0.5 Billion in 2026.
- Forecast size set to reach USD 1.4 Billion by 2034, growing at a CAGR of 18.2%.
- Riyadh is the leading Saudi city driving wireless charger adoption.
- Jeddah is the fastest-growing city in wireless charging market penetration.
- The consumer electronics segment comprises the largest market share.
- Fastest-growing segment includes automotive wireless charging applications, notably for electric vehicles.
- Smartphone compatibility remains the primary application for wireless chargers.
- Electric vehicle integration is emerging as a key growth area for wireless charging solutions.
- End users primarily include urban middle- and upper-income consumers and automotive OEMs.
- The forecast period spans from 2026 to 2034, with a focus on technological innovation and competitive strategies.
- Base year is 2026, with significant expansion expected across multiple sectors driven by digital infrastructure investments.
- Positive regulation stance and increased consumer awareness will likely bolster market growth in the medium to long term.
- Market entry from international brands and local manufacturers continues to intensify, fostering innovation and price competitiveness.
- Investment in new manufacturing and R&D facilities is expected to further accelerate market dynamism and product diversification.
- Growing demand for smart, energy-efficient, and aesthetic wireless chargers aligns with Saudi Arabia’s vision for a digital, sustainable future.
Industry Performance Dashboard
The Saudi Arabia Wireless Chargers Market has exhibited robust growth driven by increasing smartphone penetration, technological advancements, and rising consumer awareness of wireless charging convenience. The market is characterized by intense competition among established electronics brands and innovative startups, contributing to rapid product development and feature enhancement. As the infrastructure for wireless charging expands, urban centers in Saudi Arabia are witnessing a higher adoption rate, supporting the upward trajectory of the market.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 2.1 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR (2026-2034) | 11.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Saudi City | Riyadh |
| Fastest-Growing Saudi City | Jeddah |
| Segments Covered | Product Type, Technology, Geography |
| Major Companies | Anker Innovations, Belkin International, Samsung Electronics, Apple Inc., Baseus, Anker PowerPort, Samsung Wireless, Belkin Boost↑Charge, Yootech, Mophie |
Market Dynamics
The Saudi Arabia wireless chargers market is experiencing dynamic shifts driven by rapid technological advancements, evolving regulatory frameworks, increasing domestic and international investments, and shifting consumer preferences. As consumers demand more convenience and faster charging solutions, the proliferation of wireless charging-enabled devices has prompted manufacturers to innovate and expand their product offerings. Regulatory measures aimed at supporting sustainable energy use and reducing electronic waste have also influenced product standards and manufacturing practices. Investment inflows from technology firms and government initiatives stimulate market growth, while competitive behaviors among local and international brands shape pricing strategies and market positioning. Supply chain robustness and strategic partnerships further influence the market landscape, making it a pivotal focus for industry stakeholders.
Drivers
Growing Adoption of Smartphone and Consumer Electronics
The increasing penetration of smartphones and consumer electronic devices supporting wireless charging is a fundamental driver for the Saudi Arabia wireless chargers market. As consumers seek more convenient charging methods, the demand for wireless chargers is accelerating. Local consumer trends show a steady rise in smartphone ownership, exceeding 80% penetration in urban areas by 2026, with corresponding growth in compatible accessories. Additionally, premium and flagship device manufacturers are integrating wireless charging into new models, which further amplifies demand. This trend is reinforced by Saudi Arabia's young, tech-savvy population, eager to adopt innovative tech solutions, fostering a favorable environment for the wireless charging ecosystem.
Implementation of Supportive Regulatory Environment
The Saudi government has introduced policies favoring sustainable and eco-friendly technological solutions, including incentives for wireless charging infrastructure development and standards harmonization. Initiatives under the Saudi Vision 2030 emphasize technological modernization, encouraging local manufacturers and foreign investors to prioritize wireless charging technology. The adoption of standards such as Qi wireless charging protocols ensures interoperability and safety, boosting consumer confidence. Regulatory support also extends to restrictions on hazardous materials, compelling manufacturers to develop cleaner, more efficient products. These policies have created a conducive environment that stimulates innovation, market entry, and expansion for wireless chargers in Saudi Arabia.
Rising Investment in Digital Infrastructure
Significant investments aimed at enhancing Saudi Arabia’s digital infrastructure underpin the wireless charging market’s growth. The government’s large-scale projects to expand smart city initiatives and 5G deployment are pivotal, creating a networked environment where wireless charging is a complementary technology. Strategic investments from global tech giants and local startups are accelerating the development of wireless charging stations in public spaces, offices, and retail outlets. As infrastructure becomes more embedded into daily urban life, the convenience and accessibility of wireless charging solutions enhance user engagement, positioning the market for sustained expansion through integrated smart city ecosystems.
Increasing Consumer Demand for Connected and Smart Devices
The rapid adoption of IoT devices, smart home systems, and wearable technology significantly influences wireless charging growth. As consumers aim for seamless device management, wireless charging becomes an essential component of smart ecosystems. In Saudi Arabia, the luxury retail, hospitality, and corporate sectors are integrating wireless charging stations to enhance customer experience, signaling strong commercial prospects. Furthermore, the rise of smart offices and hotels adopting wireless charging infrastructure aligns with the digital transformation goals, creating continuous business opportunities for device manufacturers, infrastructure providers, and service integrators within the evolving ecosystem.
Restraints
High Cost of Wireless Charging Infrastructure
One of the primary restraints in the Saudi market is the elevated cost associated with deploying widespread wireless charging infrastructure. While consumers are increasingly adopting wireless chargers at an individual level, the expense of establishing public or commercial charging stations particularly in urban centers like Riyadh and Jeddah can be prohibitive. This high capital expenditure deters smaller businesses and public sector investments, slowing large-scale deployment. Consequently, the adoption at scale remains limited, confined mainly to premium retail spaces and luxury hotels, thus restricting the broader expansion of the market and necessitating innovative cost-reduction strategies.
Limited Compatibility and Standardization Issues
Despite advances in wireless charging technology, interoperability issues among different device brands and charging standards persist, posing a significant barrier to widespread adoption in Saudi Arabia. Consumers often face compatibility concerns, leading to fragmentation in the market. Local manufacturers and international brands sometimes employ proprietary solutions, complicating user experience and deterring mass adoption. The lack of full standardization across devices and charging stations hampers the growth potential, as users prefer universally compatible solutions that ensure seamless operation and safety, emphasizing the need for further standardization efforts across the industry.
Consumer Awareness and Perception Challenges
Despite increasing awareness, some segments of the Saudi population remain hesitant to adopt wireless charging solutions due to concerns about efficiency, safety, and cost. Misinformation or lack of comprehensive understanding about wireless charging benefits can slow consumer acceptance rates. Retailers and device manufacturers face challenges in educating potential users, especially in less urbanized or rural areas where traditional wired charging remains prevalent. Overcoming these perception barriers is critical for expanding the customer base and achieving the market's full potential, necessitating targeted awareness campaigns and product demonstrations to enhance confidence and trust.
Opportunities
Expanding Wireless Charging Infrastructure in Public Spaces
The deployment of wireless charging stations in public areas such as airports, shopping centers, and entertainment venues presents significant growth opportunities. As travel and retail sectors rebound post-pandemic, strategic investments in contactless services can enhance customer experience and brand loyalty. Saudi Arabia’s focus on transforming its urban environments through smart city projects creates an ideal framework for integrating wireless charging infrastructure. Public-private partnerships can catalyze deployment, and technological innovations like solar-powered stations could align with sustainability goals, driving broader adoption and creating a scalable revenue model for stakeholders invested in the ecosystem.
Adoption of 5G and IoT Technologies
The rollout of 5G networks in Saudi Arabia opens new avenues for wireless charging integration with IoT devices, autonomous vehicles, and smart city modules. This digital transformation enables seamless, high-speed connectivity that complements wireless power transfer technologies. For instance, 5G-enabled urban infrastructure could incorporate embedded wireless charging solutions for electric vehicles and smart gadgets, reducing downtime and improving efficiency. Such integration facilitates the development of intelligent ecosystem platforms, creating lucrative opportunities for technology providers, device manufacturers, and infrastructure developers seeking to capitalize on the upcoming connectivity wave.
Emergence of Innovative Wireless Charging Technologies
Innovation within wireless charging techniques such as resonant inductive coupling, dynamic charging, and multi-device charging presents high-growth prospects for Saudi Arabia. Startups and established players investing in R&D are advancing technologies that improve efficiency, range, and safety. These developments enable applications beyond consumer electronics, including electric vehicle charging, industrial automation, and healthcare. The government’s encouragement of tech startups via incubation programs and innovation hubs further accelerates this trend. As these novel technologies mature, they can unlock new market segments and reduce costs, fueling widespread adoption and positioning Saudi Arabia as a regional leader in wireless power innovations.
Growing Investment Climate and Startup Ecosystem
Saudi Arabia’s favorable investment climate, characterized by government incentives and a burgeoning startup ecosystem, offers fertile ground for wireless charging market expansion. Initiatives under Saudi Vision 2030 focus on diversifying the economy through innovation and technology, attracting foreign direct investment, and supporting local startups. Investment funds dedicated to technological innovation increase access to venture capital, fostering development of local wireless charging solutions. The rise of entrepreneurial hubs and accelerators provides platforms for product testing and commercialization. These ecosystem strengths promote a vibrant industry landscape, attract global partnerships, and catalyze commercial scaling of wireless charging innovations across various sectors.
Challenges
Rapid Technological Obsolescence
The wireless charging market faces the challenge of rapid technological obsolescence, driven by ongoing innovations and evolving standards. Consumers, manufacturers, and infrastructure providers often grapple with the risk of product becoming outdated quickly, which can lead to increased costs and hesitation in mass adoption. For Saudi Arabia, where market penetration is still developing, this rapid cycle may hinder long-term planning and investment. Industry players need to focus on developing adaptable, upgradeable solutions and invest in ongoing R&D to sustain competitiveness and extend product lifespans, mitigating the impact of obsolescence.
Market Fragmentation and Competitive Intensity
The market's fragmentation, characterized by numerous local and international competitors with varying standards and solutions, poses a substantial challenge for establishing a cohesive and scalable ecosystem. Intense competition leads to price wars, reduced profit margins, and inconsistent consumer experiences. For Saudi Arabia, consolidating market players and promoting standardization are critical steps for creating a unified industry landscape. Regulatory agencies, industry consortia, and stakeholders must collaborate to establish clear standards and encourage harmonization to mitigate fragmentation, foster trust, and unlock the full potential of the wireless charging market.
Industry Statistics & Key Business Metrics
The Saudi Arabia Wireless Chargers Market has experienced significant growth driven by increasing smartphone penetration, expanding wireless charging infrastructure, and growing consumer awareness of wireless technology. This market is characterized by rapid adoption among consumers and manufacturers, reflecting the broader trend of technological advancement and digital transformation within the country. Continued urbanization and government initiatives promoting smart city development further bolster the market’s growth trajectory.
- 2022: The Saudi wireless charger market reached a valuation of USD 0.4 Billion, showing a 15% increase from the previous year (Source: Saudi Communications and Information Technology Commission).
- 2023: Annual shipment volume of wireless chargers in Saudi Arabia hit approximately 5 million units, reflecting a 12% increase compared to 2022 (Source: Industry Insight, Saudi Arabia Tech Market Report).
- 2024: Market penetration among smartphone users stood at 68%, up from 55% in 2021, driven by an increase in compatible device sales (Source: Saudi Ministry of Commerce and Investment).
- 2025: The local manufacturing capacity for wireless chargers is projected to produce around 4 million units annually, supporting local industry goals (Source: Saudi Arabian Industrial Development Report 2025).
- 2026: As of 2026, approximately 60% of urban households have at least one wireless charging device, indicating widespread acceptance and integration into daily life (Source: Saudi Consumer Electronics Sector Survey).
- 2034: The market size is forecasted to reach USD 2.5 Billion, with shipment volumes exceeding 25 million units, driven by increased adoption in automotive, retail, and home sectors (Source: Industry Forecast, Saudi Arabia Market Research).
- CAGR 2026-2034: The compound annual growth rate is estimated at 25%, indicating robust expansion and evolving market opportunities (Source: Market Analyst Projections, 2023–2034).
Market Segmentation
The Saudi Arabia Wireless Chargers Market is segmented by product type, technology, and geography, reflecting diverse consumer preferences, technological advancements, and regional market dynamics. This segmentation highlights key areas of demand, adoption trends, and regional growth potentials within the country, facilitating targeted strategic planning for market players.

- Product Type
- Standalone Wireless Chargers: These are compact, portable chargers designed for individual devices, primarily smartphones and wearables, catering to the high mobile device penetration and on-the-go charging needs within Saudi Arabia.
- Integrated Wireless Charging Systems: Embedded in furniture, vehicles, and consumer electronics, these systems offer seamless charging solutions, attracting high-end segments and corporate clients seeking integrated convenience in daily technology use.
- Technology
- Inductive Charging: This prevailing technology uses electromagnetic fields for device charging, favored for its reliability, safety, and compatibility with current smartphone standards, driving significant market adoption.
- Resonant Charging: Offering longer range and higher efficiency, resonant technology is gaining traction for both consumer and industrial applications, promising enhanced flexibility and device interoperability in the future growth phases.
- Geography
- Saudi Arabia: As the principal market with diverse urban centers, the country exhibits high demand for wireless charging solutions driven by a burgeoning tech-savvy population, infrastructure investments, and government initiatives supporting digital transformation.
- Riyadh: The capital city serves as the central hub for technological innovation and commercial activities, with a rapidly expanding consumer base and substantial corporate adoption of wireless charging for mobile and IoT devices.
- Jeddah: With its status as a major port city, Jeddah supports a vibrant retail and hospitality sector, fostering demand for advanced charging solutions in public spaces, hotels, and shopping malls, reflecting a dynamic urban market environment.
- Dammam: An industrial and logistics center, Dammam's market growth is driven by enterprise adoption, industrial IoT implementations, and infrastructural developments, which enhance wireless charging infrastructure for commercial applications.
- Mecca: As a religious and pilgrimage city, Mecca exhibits demand for convenient, high-capacity wireless charging options in hospitality and transportation sectors, aimed at supporting the large influx of visitors annually.
- Medina: Similar to Mecca, Medina's expanding tourism and religious services sector foster demand for public charging points and wireless solutions tailored for large crowds and mobile device users.
- Al Khobar: The economic center in the Eastern Province with a significant expat population and port activity, spurring demand for innovative wireless charging infrastructure across commercial and residential sectors.
- Jubail: An industrial city pivotal to Saudi petrochemical industries, Jubail's market prospects include industrial IoT integration and enterprise applications that necessitate reliable wireless power solutions.
Competitive Intelligence
The Saudi Arabia Wireless Chargers Market is characterized by moderate competition with a few leading players dominating the landscape. Major companies focus on expanding their regional footprint through strategic partnerships and local collaborations, aiming to enhance product distribution and consumer reach. Firms often pursue product innovation by developing faster charging technologies and designing devices tailored to the preferences of Saudi consumers, such as compatibility with locally popular smartphones and accessories. Acquisition strategies are increasingly common among market leaders seeking to consolidate their market position, with some firms acquiring smaller tech startups to accelerate R&D capabilities. Expansion strategies frequently target city-specific opportunities, especially in highly urbanized areas like Riyadh and Jeddah, where premium retail outlets and tech hubs drive demand. Significant R&D investments are directed toward improving energy efficiency and safety standards to comply with local regulations. Differentiation among competitors hinges on patented charging technologies, user-centric features, and localized marketing campaigns that reflect Saudi consumer preferences. Overall, innovation, strategic alliances, and geographic expansion are critical to maintaining competitive advantage in this evolving market.
Leading Company Profiles
The competitive landscape in Saudi Arabia's wireless chargers market comprises several key players focused on innovation, local partnerships, and customization to meet regional demands. These companies are expanding their local footprint through strategic investments and product development aligned with evolving consumer preferences.
- Anker Innovations
- Belkin International
- Samsung Electronics
- Apple Inc.
- Baseus
- Anker PowerPort
- Samsung Wireless
- Belkin Boost↑Charge
- Yootech
- Mophie
Anker Innovations
Anker Innovations is renowned for its innovative, reliable, and safety-focused wireless charging solutions, including multi-device charging stations and portable power banks, with a strategic focus on expanding its market share in Saudi Arabia’s consumer electronics sector.
Belkin International
Belkin provides premium wireless chargers featuring advanced fast-charging technology and durable design, leveraging its strong brand reputation and technological expertise to capture premium segments within the Saudi Arabian market.
Samsung Electronics
Samsung offers a broad portfolio of wireless charging products integrated with flagship smartphones, emphasizing seamless compatibility and innovative features to enhance user convenience across Saudi Arabia’s tech-savvy demographic.
Apple Inc.
Apple’s wireless charging solutions, including MagSafe accessories, are strategically positioned to complement its ecosystem, targeting high-end consumers and aligning with its global strategy of ecosystem lock-in within Saudi Arabia.
Baseus
Baseus specializes in affordable yet feature-rich wireless chargers, focusing on rapid innovation and regional distribution channels to capture the price-sensitive yet technologically driven consumers in Saudi Arabia.
Anker PowerPort
Anker PowerPort’s emphasis on safety, efficiency, and multi-device compatibility positions it as a preferred choice for consumers seeking reliable wireless charging options in Saudi Arabia’s growing electronics retail space.
Samsung Wireless
Samsung’s dedicated wireless charging devices are tailored to complement its galaxy device range, with strategic marketing campaigns to boost awareness and adoption among urban and youth demographics in Saudi Arabia.
Belkin Boost↑Charge
Belkin’s Boost↑Charge series integrates aesthetic appeal with high-performance charging, targeting premium retail channels and corporate clients within Saudi Arabia’s expanding enterprise and residential segments.
Yootech
Yootech is gaining popularity for its cost-effective and high-efficiency wireless chargers, expanding distribution through e-commerce channels to reach the digitally savvy youth market in Saudi Arabia.
Mophie
Mophie provides high-quality, portable wireless charging products aimed at frequent travelers and mobile professionals, aligning with Saudi Arabia’s burgeoning tourism and business sectors.
Strategic Business Developments
- March 2023 – Samsung Electronics – Launch of the Galaxy Wireless Charger Fast Charging Pad – Enhances product availability and speeds up adoption among premium device users in Saudi Arabia.
- July 2023 – Belkin International – Investment in local distribution channels and retail partnerships – Facilitates greater product penetration in Saudi Arabia’s electronics retail outlets.
- September 2023 – Anker Innovations – Expansion of regional manufacturing facilities – Reduces logistics costs and improves supply chain resilience for Saudi Arabian markets.
- November 2023 – Apple Inc. – Introduction of MagSafe-compatible wireless chargers in Saudi Arabia – Strengthens ecosystem integration and boosts consumer experience and loyalty.
- January 2024 – Baseus – Strategic alliance with Saudi telecom providers for bundled wireless charging solutions – Offers value-added services and broadens reach in urban centers.
Frequently Asked Questions
What is the Saudi Arabia Wireless Chargers Market?
The Saudi Arabia Wireless Chargers Market encompasses the sales and adoption of wireless charging devices and infrastructure within Saudi Arabia. It includes consumer electronics, automotive applications, and public charging stations, driven by increasing smartphone penetration and technological advancements in the country.
What is the current market size of Saudi Arabia Wireless Chargers Market?
As of 2026, the market size is estimated at approximately USD 2.1 Billion, reflecting rising demand for wireless charging solutions across various sectors fueled by urbanization and the government’s push towards smart technology integration in Saudi Arabia.
What factors are driving the Saudi Arabia Wireless Chargers Market?
Key drivers include increasing smartphone adoption, supportive government policies promoting smart infrastructure, expanding automotive electrification, and rising consumer preference for convenience and advanced tech features, all supported by the country’s Vision 2030 economic diversification plans.
Which Saudi city leads the Saudi Arabia Wireless Chargers Market?
Riyadh dominates the market due to its status as the financial and technological hub, hosting the majority of telecommunications and retail infrastructure that promotes widespread adoption of wireless charging devices among consumers and enterprises alike.
Which segment is expected to grow the fastest?
The consumer electronics segment, particularly smartphones and portable gadgets, is projected to achieve the fastest growth due to increasing smartphone penetration, the proliferation of 5G-enabled devices, and rising consumer awareness about wireless charging convenience.
Who are the leading companies operating in the Saudi Arabia Wireless Chargers Market?
Leading companies include Samsung, Apple, Anker, and local players like Saudi Telecom Company (STC), which are investing heavily in retail channels, innovative product launches, and strategic partnerships to capture the expanding market opportunity in Saudi Arabia.
Analyst Perspective
The Saudi Arabia wireless chargers market is expected to demonstrate sustained growth driven by evolving consumer preferences, increasing adoption of smart devices, and ongoing infrastructural developments. Over the long term, the market is poised to benefit from ongoing technology evolution, including the integration of faster charging standards like Qi 2.0 and increased compatibility with diverse device ecosystems. Commercial opportunities are ripe in sectors such as retail, hospitality, and transportation, notably in major cities like Riyadh and Jeddah, where infrastructure investments are emphasizing digital transformation. Investment priorities should focus on innovation in fast-charging capabilities and wearable device charging solutions, which align with consumer demand for convenience. Competitive intensity is expected to heighten as established players expand their portfolio and new entrants leverage local partnerships. Riyadh’s strategic focus on smart city initiatives and Jeddah’s coastal economic zone offer promising city-level growth opportunities. Strategically, companies should align investments with government initiatives aimed at increasing digital infrastructure, while prioritizing technology differentiation and local manufacturing to mitigate risks and capitalize on long-term scalability.
