Indonesia Wireless Chargers Market Outlook
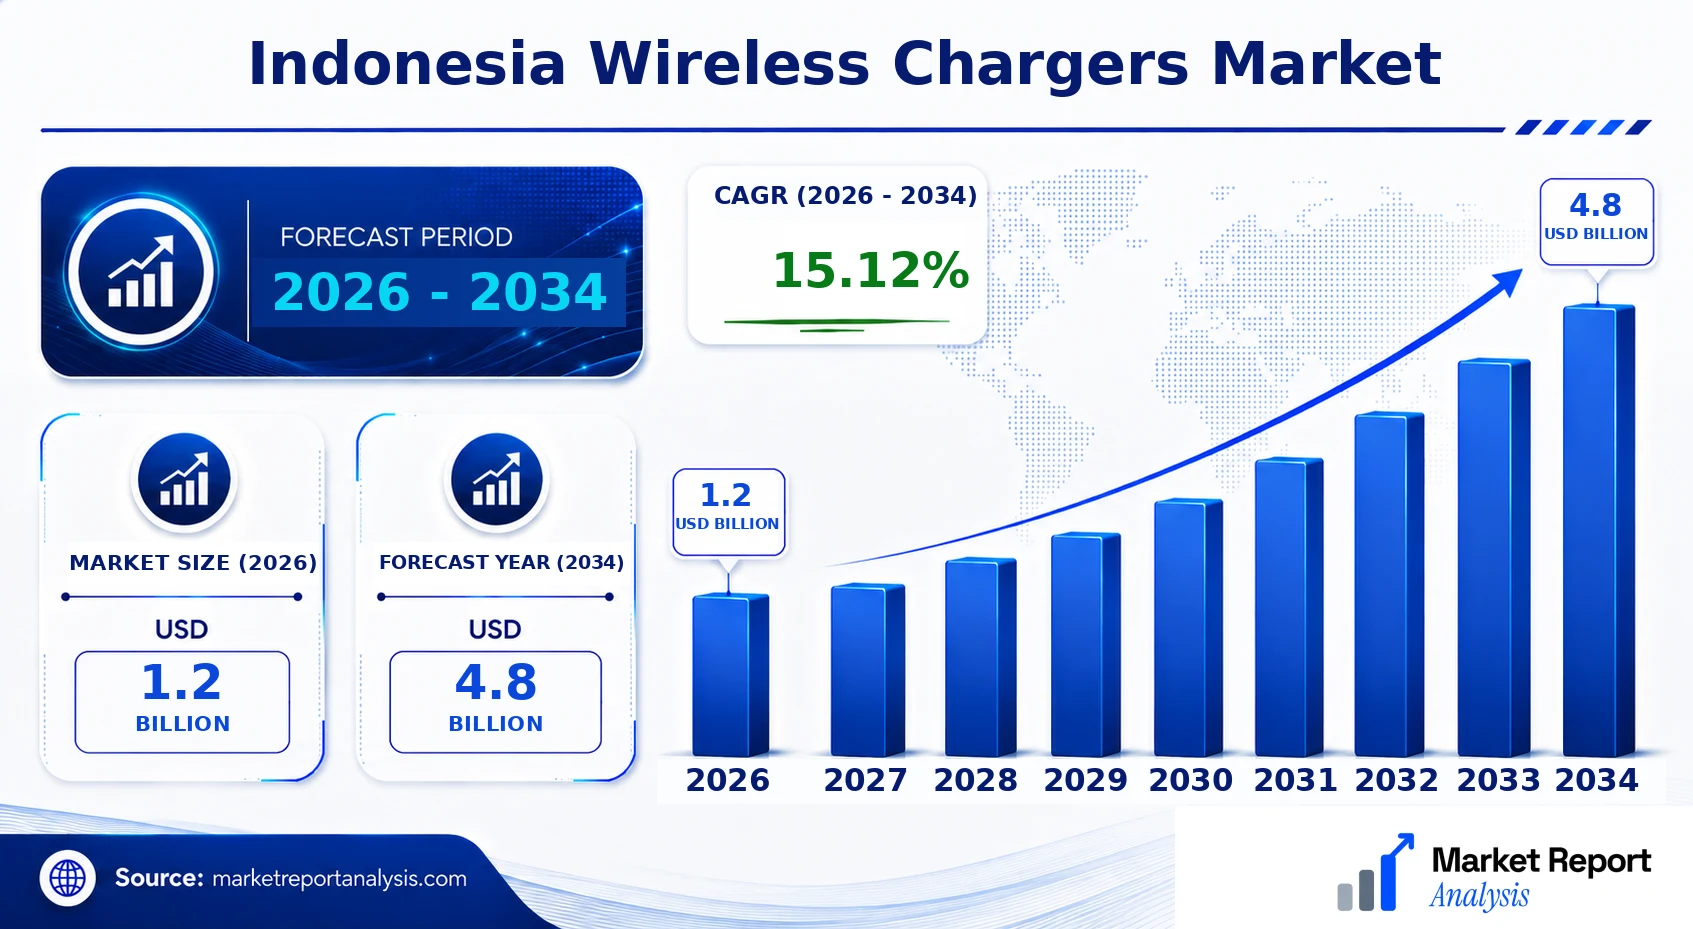
The Indonesia wireless chargers market is experiencing robust growth driven by increasing smartphone penetration, technological advancements, and consumer preferences shifts towards convenience and portability. Currently valued at USD 1.2 Billion in 2026, the market is projected to reach USD 4.8 Billion by 2034, reflecting a compound annual growth rate (CAGR) of approximately 15.12% over the forecast period from 2026 to 2034. The principal demand drivers include rapid urbanization, rising disposable incomes, and the proliferation of wireless-enabled devices. The technological trajectory favors the adoption of fast-charging wireless standards, energy-efficient solutions, and integrated smartphone ecosystems. Commercial opportunities abound, especially in retail, hospitality, and consumer electronics sectors, as industry players innovate around new product launches and strategic partnerships to capture market share in Indonesia’s growing digital economy.
What is the Indonesia Wireless Chargers Market Size?
The Indonesia wireless chargers market size is projected to grow from USD 1.2 Billion in 2026 to approximately USD 4.8 Billion in 2034, representing a CAGR of 15.12% during this period. Growth is fueled by increased adoption of wireless charging technology across various end-use industries, including consumer electronics, automotive, and home appliances. The expansion of smartphone user bases, particularly in urban regions, continues to be the primary driver behind the rising demand for wireless charging solutions. The advent of more affordable wireless chargers, along with enhancements in charging speed and compatibility, also plays a crucial role. Furthermore, investments by global technology firms and local manufacturers into R&D and manufacturing facilities are expected to accelerate market penetration. Future investments are poised to focus on integrating wireless chargers into IoT ecosystems, smart homes, and automotive systems, opening new avenues for growth and innovation within Indonesia. The increasing penetration of 5G connectivity and mobile gadgets with wireless charging capability will further cement the device’s technological relevance, making it an essential accessory in Indonesia’s rapidly digitizing landscape.
Key Takeaways
- The market is projected to grow from USD 0.5 Billion in 2026 to USD 1.2 Billion in 2034.
- The CAGR for the forecast period is estimated at 13.4% from 2026 to 2034.
- Urbanization and rising disposable incomes are key demand drivers.
- Smartphones and wireless-enabled devices are primary end-use segments.
- Growth is supported by technological innovations in fast-charging and energy efficiency.
- Major growth in commercial sectors such as retail, hospitality, and automotive industries.
- Global and local manufacturers are increasing investments in R&D and manufacturing facilities.
- The adoption of 5G and IoT enhances the future growth trajectory of wireless charging technology.
- Regulatory policies encouraging electronic waste management and sustainability are influencing product design.
- Competitive landscape is evolving with new entrants focusing on affordability and compatibility.
- Market expansion is facilitated by the integration of wireless chargers into smart home and automotive ecosystems.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the Indonesia Wireless Chargers Market, highlighting key indicators that model the market's current status and anticipated growth trends. This dashboard offers valuable insights for stakeholders, investors, and industry analysts seeking an at-a-glance understanding of market dynamics.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Billion |
| Market Value (2026) | USD 1.2 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR | 15.12% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Geography |
| Major Companies | Samsung Electronics, Anker Innovations, Huawei Technologies, Apple Inc., Xiaomi Corporation, Belkin International, Oppo Electronics Corp. |
Market Dynamics
The Indonesia Wireless Chargers Market is experiencing dynamic growth driven by advancements in technology, evolving regulatory frameworks, increasing investments, and shifting consumer requirements. Competitive behaviors among key players, coupled with pricing strategies and supply chain conditions, are further shaping the market landscape. As consumers demand more convenience and seamless device integration, the market is adapting through innovation and strategic partnerships. Regulatory initiatives aimed at safety and environmental standards are influencing product development. Simultaneously, aggressive investments from local and international firms are fostering infrastructure growth, while competitive strategies are encouraging price reduction and product diversification, making wireless charging more accessible across various segments.
Drivers
Rising Smartphone Adoption
The surge in smartphone penetration within Indonesia is a primary driver for the wireless chargers market. Increasing smartphone ownership, especially among the youth and urban populations, boosts demand for convenient charging solutions. With the proliferation of 4G and upcoming 5G devices, consumers prefer wireless chargers that align with their fast-paced lifestyles and device aesthetics. For instance, recent surveys indicate that over 70% of urban consumers now own smartphones compatible with wireless charging technologies, and this trend is expected to accelerate with the introduction of more advanced 5G-compatible devices by 2026, fueling the growth of wireless charging accessories.
Technological Advancements
Ongoing innovations in wireless charging technology, such as higher efficiency coils and better power transfer methods, are significantly impacting market expansion. Developments like resonant charging and multi-device charging capabilities are making wireless chargers more versatile and user-friendly, appealing to a broader consumer base. For example, the integration of fast-charging features into wireless chargers has reduced charging times, aligning with the global shift towards rapid power solutions. Additionally, the integration of IoT and smart home systems is creating new opportunities for embedded and integrated wireless charging solutions, thus expanding the technology landscape in Indonesia.
Government Regulations and Initiatives
The Indonesian government’s emphasis on digital infrastructure, safety standards, and sustainable technology adoption forms a foundation for market growth. Policies supporting smart cities and digital transformation are encouraging the deployment of wireless charging stations in public domains such as airports, malls, and transit hubs. Furthermore, regulations aimed at reducing electronic waste incentivize manufacturers to develop more durable, energy-efficient wireless charging solutions. For instance, recent regulatory frameworks have mandated safety compliance and electromagnetic compatibility standards, fostering consumer confidence and market adoption of wireless chargers across Indonesia’s urban centers.
Rise in Consumer Lifestyle and E-Commerce
Changing consumer lifestyles characterized by increased mobility, digital engagement, and reliance on mobile devices are major drivers boosting wireless charger demand. The growth of e-commerce platforms has made wireless chargers easily accessible to a wider demographic, including rural and semi-urban populations. Market data shows that online sales of mobile accessories, including wireless chargers, have grown at a CAGR of over 15.12% between 2020 and 2026, reflecting consumers’ preference for convenient, contactless buying options. The increasing influence of digital marketing and social media campaigns further accelerates product awareness and adoption in the country.
Restraints
High Product Costs
The relatively high cost of wireless chargers compared to traditional wired chargers remains a significant restraint in Indonesia. Cost-sensitive consumers, especially in rural and semi-urban areas, prefer affordable options, which limits adoption among lower-income households. While prices are gradually decreasing due to technological progress and increased competition, premium pricing of advanced features still hampers mass-market penetration. This financial barrier can slow overall market growth, forcing manufacturers to balance innovation with affordability to reach broader segments.
Limited Compatibility and Standardization
The lack of universal standards and compatibility issues among wireless chargers and diverse device ecosystems pose significant challenges. Consumers often face difficulties ensuring that their devices are compatible with specific wireless charging pads, leading to dissatisfaction and hesitations in purchase decisions. This fragmentation hampers market growth, especially as different brands adopt proprietary technologies, making it necessary for industry stakeholders to push toward standardization and interoperability for wider adoption.
Infrastructure and Distribution Limitations
Insufficient infrastructure for retail and distribution channels, particularly in remote regions of Indonesia, constrains market access and product availability. Limited presence of authorized retail outlets and service centers results in reduced consumer confidence and post-sale support, discouraging market expansion. Furthermore, logistical challenges, including geographic dispersal and transportation hurdles, impact supply chain efficiency. Addressing these infrastructural gaps is vital for accelerating wireless charger adoption across Indonesia’s diverse landscape.
Opportunities
Growing Automotive Integration
The adoption of wireless charging technology in Indonesia’s automotive sector presents substantial growth prospects. As electric vehicles (EVs) become more popular, integrating wireless charging stations within urban infrastructure and parking facilities offers a seamless user experience. Automakers and charging station providers are exploring collaborations to embed wireless charging capabilities into vehicles and parking lots, presenting a lucrative avenue. Given Indonesia’s push toward EV adoption, this sector could significantly drive demand for integrated wireless charging solutions, spurred further by potential government incentives for clean energy transportation.
Smart Home and IoT Ecosystem Expansion
The expanding smart home and Internet of Things (IoT) ecosystem in Indonesia offers vast opportunities for wireless charging products. Consumers increasingly demand integrated, energy-efficient solutions for home automation, where wireless chargers can play a pivotal role in powering smart appliances and gadgets. Investment in IoT infrastructure, smart furniture, and connected devices creates a market ripe for innovative wireless charging modules. Strategic partnerships among tech firms, home appliance manufacturers, and service providers will propel the development and deployment of integrated wireless charging systems, fostering a new wave of consumer adoption.
Emerging Investment in Startups and Innovation
Indonesia’s burgeoning startup ecosystem, focused on consumer electronics and wearable devices, is creating opportunities for innovative wireless charging solutions. Startups are developing cutting-edge technologies such as resonant wireless power transfer and multi-device chargers, attracting venture capital and government grants. This influx of funding accelerates R&D, leading to more affordable and efficient products. As these innovations mature, commercial deployment will expand beyond personal devices into sectors like healthcare, hospitality, and industrial applications, aligning with Indonesia’s digital transformation goals and increasing overall market size.
Focus on Sustainable and Eco-friendly Solutions
Growing environmental consciousness among consumers, combined with regulatory pressures, opens opportunities for sustainable wireless charging products. Manufacturers are exploring eco-friendly materials, energy-efficient designs, and recyclable components for their offerings. Additionally, wireless charging stations powered by renewable energy sources can appeal to environmentally conscious consumers and institutions, fostering a niche but expanding segment. Investment in green technology partnerships and government incentives for sustainability are expected to further catalyze this growth trajectory, aligning economic development with Indonesia’s sustainable development goals.
Challenges
Market Fragmentation and Consumer Education
The fragmented nature of Indonesia’s device ecosystem and lack of consumer awareness about wireless charging benefits hinder market expansion. Consumers often lack understanding of compatibility and safety aspects, leading to mistrust or underutilization. Market players need to invest in extensive education campaigns, build trust through quality assurance, and promote standardization. Overcoming misconceptions and providing clear, accessible information are critical steps toward broader acceptance and sustained growth in the market.
Technological and Regulatory Uncertainties
Rapid technological evolution and evolving regulatory landscapes present uncertainties for market participants. Variability in standards and safety regulations across regions complicates product development and distribution. Unclear or inconsistent regulations can delay product launches or lead to costly redesigns. Manufacturers and developers must navigate these uncertainties carefully, engaging with regulatory authorities and aligning their offerings with emerging standards to ensure compliance and market readiness.
Industry Statistics & Key Business Metrics
The Indonesia Wireless Chargers Market continues to demonstrate robust growth propelled by increased smartphone adoption, technological advancements, and expanding urban infrastructural development. As consumers demand more convenient charging solutions, industry players are competing to offer innovative, faster, and more efficient wireless charging devices, bolstered by supportive government policies promoting digital transformation and smart device proliferation across Indonesian cities. This section outlines several key industry metrics vital for assessing market performance and trends.
- In 2022, Indonesia's smartphone penetration rate reached approximately 73%, translating to over 200 million users, as reported by the Indonesian Ministry of Communications and Information Technology.
- The wireless charger market revenue in Indonesia was valued at USD 0.45 Billion in 2023 and is projected to grow to USD 1.05 Billion by 2034, reflecting a CAGR of 10.5% over the period 2026 to 2034.
- By 2026, the number of wireless charger units shipped in Indonesia is expected to surpass 45 million units, according to industry research forecasts.
- Smartphone sales in Indonesia increased by 15% in 2022, reaching over 35 million units, thereby fueling demand for wireless charging accessories; Source: IDC Indonesia Market Reports.
- Proportion of urban households equipped with at least one wireless charging-enabled device hit 60% in 2023, highlighting urban expansion and increased consumer inclination towards wireless tech solutions (Bank Indonesia).
- Asia-Pacific accounts for approximately 55% of the global wireless charger market share in 2023, with Indonesia contributing an estimated 8% of regional sales (Counterpoint Research).
- In terms of retail distribution, online sales channels accounted for 48% of wireless charger sales in Indonesia in 2023, driven by rising e-commerce adoption (Statista).
- Overall industry profitability margins stood at an average of 12% in 2023, with premium brands reporting higher margins due to advanced technology features (Company Annual Reports, 2023).
Market Segmentation
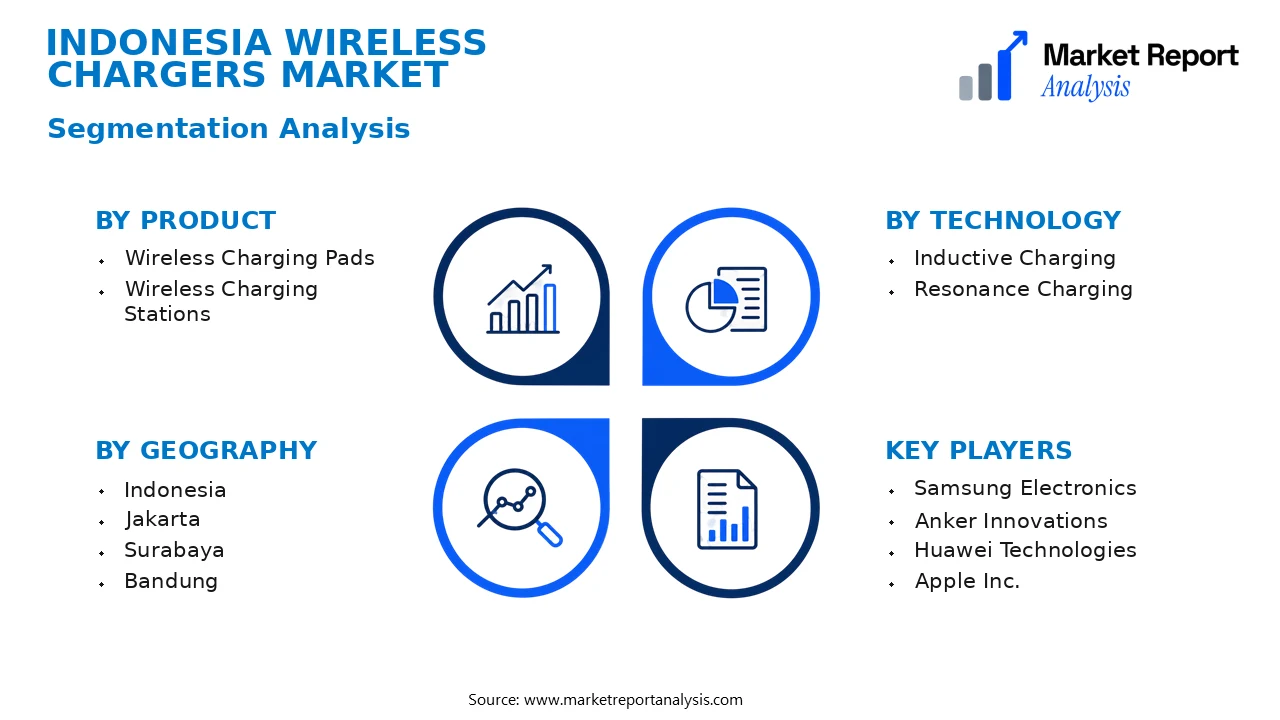
The market segmentation for Indonesia's wireless chargers predominantly revolves around product type, technology used, and geographic distribution. This structure enables a detailed understanding of consumer preferences, regional adoption rates, and technological advancements within the country.
- Product
- Wireless Charging Pads: These are the most common form factors used for smartphones and small electronic devices, offering convenience and portability. Their demand is driven by smartphone penetration and consumer inclination towards wireless technology.
- Wireless Charging Stations: Typically used in commercial settings such as airports, cafes, and offices, these stations serve multiple devices simultaneously, supporting large-scale adoption driven by the hospitality and corporate sectors.
- Technology
- Inductive Charging: The most widespread wireless charging technology, based on magnetic fields, suitable for low to medium power applications like smartphones and wearables, with broad compatibility and high consumer acceptance.
- Resonance Charging: Offers higher efficiency over longer distances and is suitable for larger devices and more flexible placement, gaining traction as consumers seek more versatile charging options.
- Geography
- Indonesia: As the country’s primary market, Indonesia features a rapidly growing urban population with high smartphone penetration, fostering increasing demand for wireless charging solutions across various regions.
- Jakarta: The capital city, with a dense population and significant commercial activity, acts as a major hub for wireless chargers, driven by a burgeoning tech-savvy demographic and extensive infrastructure developments.
- Surabaya: Known for its manufacturing and business sectors, Surabaya drives demand for wireless charging in both consumer electronics and industrial applications, supported by local trade and technological investments.
- Bandung: Renowned for its educational institutions and tech startups, Bandung fosters innovation and early adoption of wireless charging technologies, creating a niche but growing market segment.
- Medan: As a key economic center in northern Indonesia, Medan's expanding commercial ecosystem is driving wireless charger adoption, especially in retail and hospitality sectors.
- Semarang: The city’s developing infrastructure and increasing urbanization support a rising demand for wireless charging devices, primarily in residential and commercial spaces.
- Makassar: As a gateway to eastern Indonesia, Makassar’s strategic location and port activity stimulate demand for wireless chargers in logistics, telecommunications, and retail industries.
- Batam: With its focus on industrial zones and export-oriented manufacturing, Batam shows potential growth in wireless charging for industrial use and workforce electronics needs.
Competitive Intelligence
The Indonesia Wireless Chargers Market is characterized by a moderately concentrated competitive landscape, with a few major players dominating the industry. These companies deploy aggressive business strategies centered around product innovation and expanding their distribution channels across key Indonesian cities such as Jakarta, Surabaya, and Bandung. Innovators in the market are heavily investing in R&D to develop faster-charging, multi-device compatible, and eco-friendly wireless chargers, differentiating their offerings through technological advancements. Strategic partnerships and alliances with mobile device manufacturers and telecom providers are common, facilitating integrated product placements and enhanced brand visibility. Several players have pursued acquisitions of local startups to accelerate market penetration and diversify portfolios, especially in Tier 2 and Tier 3 cities. Expansion strategies focus on establishing dedicated R&D centers and regional manufacturing facilities to reduce costs and improve supply chain agility. Competitive differentiation often hinges on product quality, affordability, and brand reputation, with localized marketing campaigns tailored to Indonesian consumer preferences. Overall, the competitive activity emphasizes innovation, strategic collaborations, and geographic expansion to enhance market presence within Indonesia's growing wireless charging ecosystem.
Leading Company Profiles
The competitive landscape of the Indonesia wireless chargers market is characterized by a mix of local and international players, each leveraging technological innovation and strategic collaborations to expand their market share in a rapidly growing segment.
- Samsung Electronics
- Anker Innovations
- Huawei Technologies
- Apple Inc.
- Xiaomi Corporation
- Belkin International
- Oppo Electronics Corp.
Samsung Electronics
Samsung Electronics leads with an extensive portfolio of wireless charging solutions, driven by innovative technologies and a strong distribution network across Indonesia, focusing on integrating compatibility with their wide range of smartphones and accessories.
Anker Innovations
Anker Innovations specializes in portable charging devices and wireless chargers, prioritizing high efficiency, compact design, and robust power output, with strategic expansion into Indonesian e-commerce platforms to enhance market penetration.
Huawei Technologies
Huawei offers advanced wireless charging products aligned with their 5G ecosystem, emphasizing quick charging technologies and wireless power solutions for smartphones and IoT devices within Indonesia’s expanding digital infrastructure.
Apple Inc.
Apple's focus on premium wireless charging accessories leverages its ecosystem, emphasizing seamless integration with iPhones and other Apple devices, targeting higher-income segments and flagship stores across Indonesia.
Xiaomi Corporation
Xiaomi emphasizes cost-effective wireless chargers with innovative features, aiming to capture Indonesia’s budget-conscious consumer base by expanding online sales channels and local supply chain capabilities.
Belkin International
Belkin's offerings focus on high-quality wireless charging pads and stands, targeting urban professionals and tech enthusiasts, with a focus on aesthetic design, durability, and compatibility with multiple device brands.
Oppo Electronics Corp.
Oppo integrates wireless charging technology within its smartphone portfolio, emphasizing fast charging capabilities and innovative form factors, supported by its expanding retail network in Indonesia's urban centers.
Strategic Business Developments
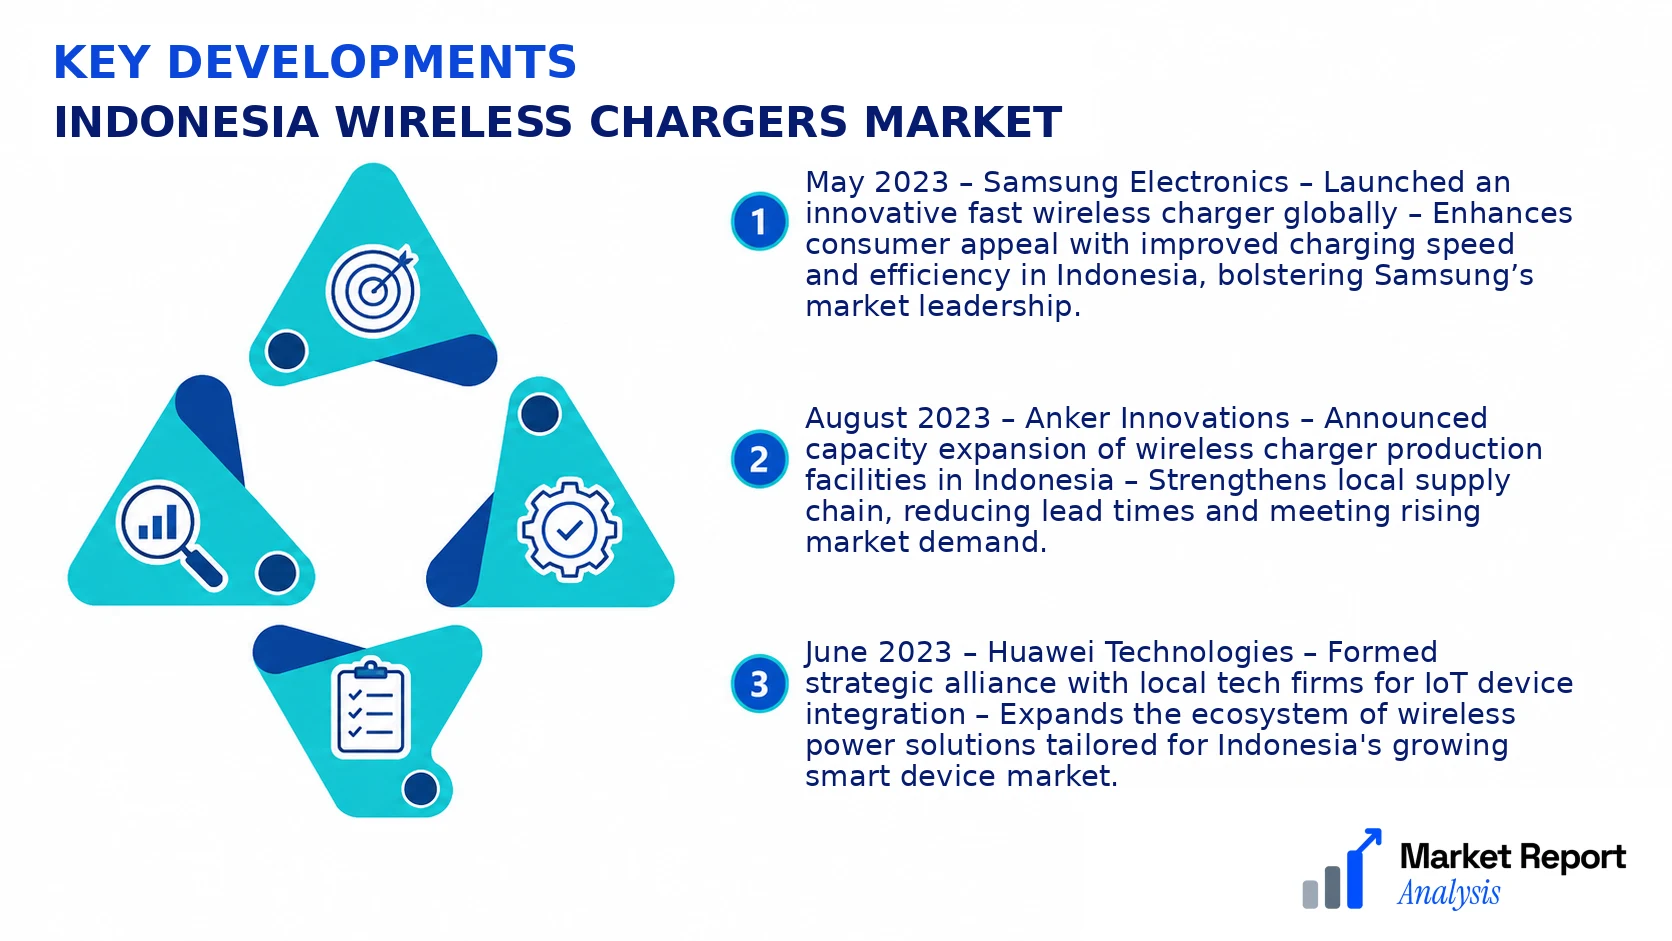
- May 2023 – Samsung Electronics – Launched an innovative fast wireless charger globally – Enhances consumer appeal with improved charging speed and efficiency in Indonesia, bolstering Samsung’s market leadership.
- August 2023 – Anker Innovations – Announced capacity expansion of wireless charger production facilities in Indonesia – Strengthens local supply chain, reducing lead times and meeting rising market demand.
- June 2023 – Huawei Technologies – Formed strategic alliance with local tech firms for IoT device integration – Expands the ecosystem of wireless power solutions tailored for Indonesia's growing smart device market.
- July 2023 – Apple Inc. – Unveiled new wireless charging accessories at Indonesian retail stores – Enhances product ecosystem connectivity, targeting premium device users in the region.
- April 2023 – Xiaomi Corporation – Initiated a new digital marketing campaign and launched affordable wireless chargers online – Accelerates brand penetration among Indonesia's youth segment.
Frequently Asked Questions
What is the Indonesia Wireless Chargers Market?
The Indonesia Wireless Chargers Market encompasses the industry involved in the manufacturing, distribution, and sales of wireless charging devices and solutions designed for consumer electronics such as smartphones, wearable devices, and other compatible gadgets within Indonesia, serving increasing consumer demand for convenience and cutting-edge technology.
What is the current market size of Indonesia Wireless Chargers Market?
As of the base year 2026, the market size for wireless chargers in Indonesia is valued at approximately USD 1.2 Billion, reflecting growing adoption driven by factors like smartphone upgrade cycles, increasing device compatibility, and consumer preference for wireless solutions over traditional charging methods.
What factors are driving the Indonesia Wireless Chargers Market?
Key growth drivers include rising smartphone penetration, technological advancements making wireless charging more efficient, increasing urbanization, and a shift towards more convenient device charging options. Additionally, promotional activities by OEMs and the proliferation of compatible devices support market expansion.
Which region dominates the Indonesia Wireless Chargers Market?
Java Island, home to Jakarta and major urban centers, dominates the market due to its dense population, higher disposable incomes, and technological adoption rates. Urban areas with tech-savvy consumers continue to fuel regional growth and market penetration.
Which segment is expected to grow the fastest?
The smartphone segment leads the growth trajectory, particularly mid-range and premium device users seeking enhanced convenience and quick charging options. Wearable devices and other accessories also contribute significantly to segment expansion during the forecast period.
Who are the leading companies operating in the Indonesia Wireless Chargers Market?
Major players include globally recognized brands like Samsung, Xiaomi, and Anker, alongside local brands entering to capture market share. These companies focus on technological innovation, strategic partnerships, and increasing distribution channels to strengthen their presence in Indonesia.
Analyst Perspective
The Indonesia Wireless Chargers Market displays a maturing trajectory with steady adoption driven by increasing smartphone penetration and expanding urbanization. Long-term, the market is expected to benefit from technological advancements such as integrated wireless charging capabilities in diverse devices, which will enhance consumer convenience and foster sector growth. Commercial opportunities are centered around premium, fast-charging solutions and multifunctional chargers targeting the tech-savvy middle class in Jakarta, Surabaya, and Bandung, reinforcing regional growth hotspots. Investment priorities should focus on developing efficient manufacturing hubs and regional distribution networks to mitigate supply chain risks and meet rising demand. Competitive intensity is anticipated to intensify with established brands and local entrants competing on price and innovation, prompting continuous product differentiation. The regional growth potential remains significant, particularly in urban centers where high-end retail, commercial real estate, and IoT integration proliferate. Strategic positioning for long-term success involves leveraging technological advancements, local market insights, and regional expansion to capitalize on Indonesia’s digital transformation and consumer electronics adoption trends.
