Japan Wireless Chargers Market Outlook
The Japan Wireless Chargers Market is currently valued at USD 3.2 Billion in 2026 and is projected to reach USD 9.4 Billion by 2034, exhibiting a Compound Annual Growth Rate (CAGR) of approximately 11.7% over the forecast period of 2026-2034. The principal demand drivers include the rising adoption of smartphones, wearable devices, and electric vehicles, complemented by increasing consumer preference for convenience and wireless technology adoption. The technological focus in this market is shifting towards faster charging capabilities, greater energy efficiency, and compatibility with a broad range of devices. Moreover, the penetration of IoT-enabled devices and smart homes presents a significant growth opportunity for wireless charging solutions, creating a lucrative environment for major tech companies and startups alike to innovate and expand their product portfolios. Additionally, the development of eco-friendly and sustainable wireless charging technologies aligns with Japan’s environmental policies, boosting market growth potential. The commercial opportunities for stakeholders include strategic partnerships, technological innovation, and expansion into untapped segments within the Japanese consumer electronics and automotive sectors.
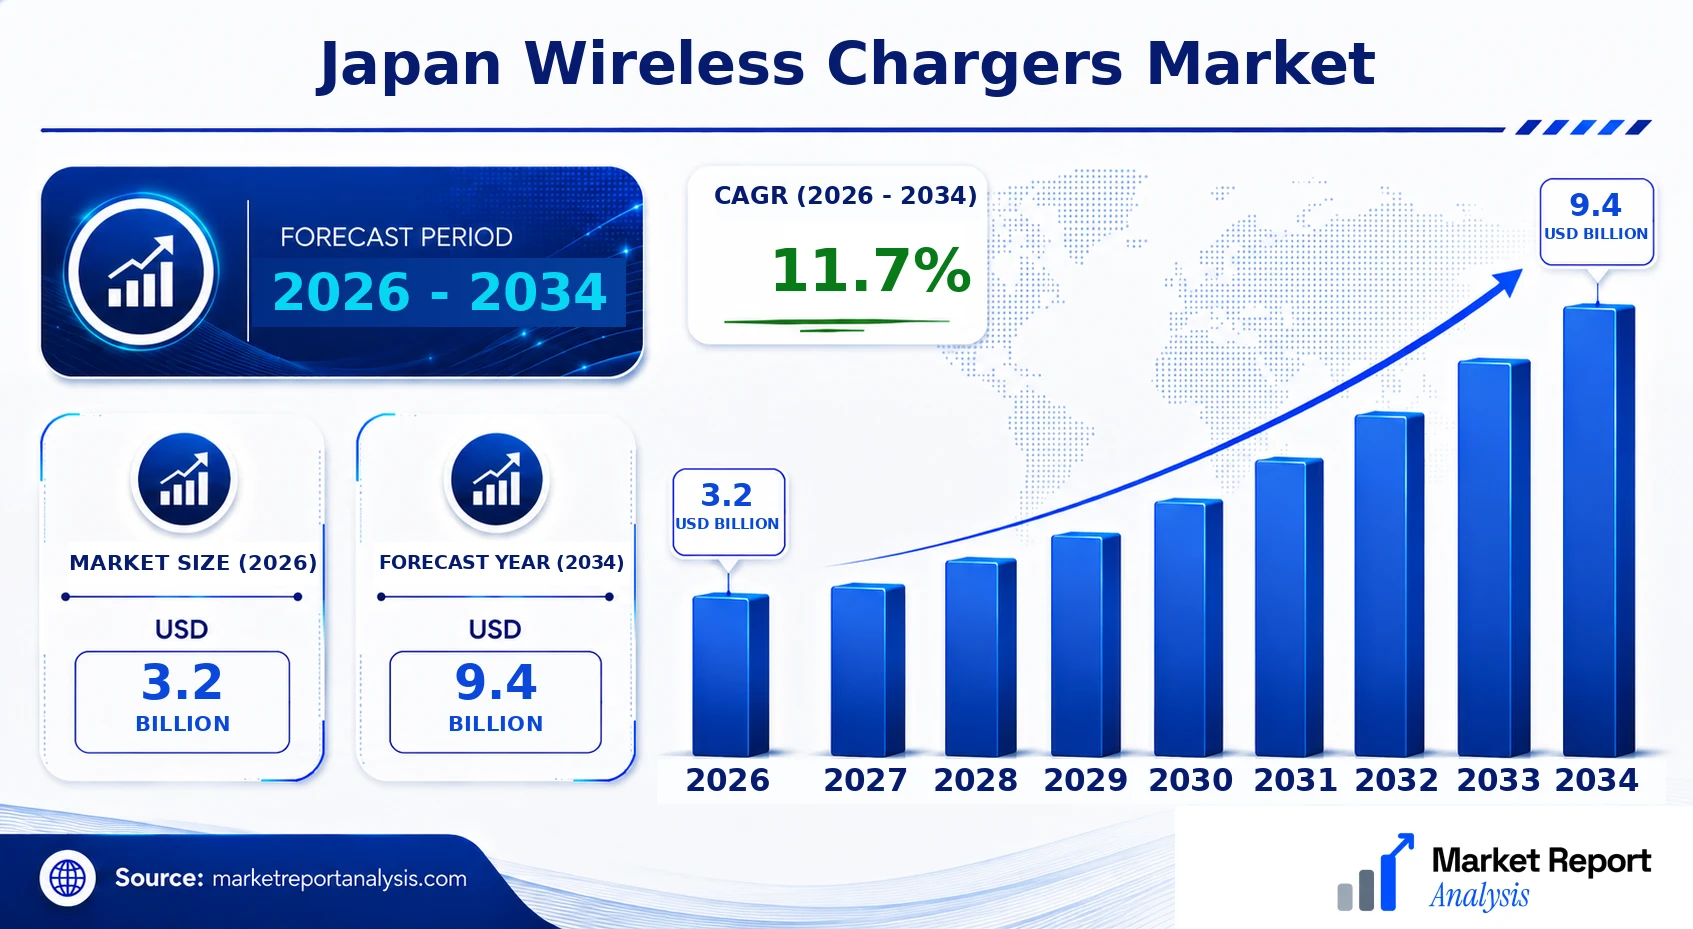
What is the Japan Wireless Chargers Market Size?
The Japan Wireless Chargers Market is forecasted to grow from USD 3.2 Billion in 2026 to USD 9.4 Billion in 2034 with an increase at a CAGR of 11.7%. This growth is mainly driven by the increased adoption of wireless charging technology across various application sectors, including consumer electronics, automotive, and industrial uses. Consumer electronics, in particular, contributes the largest share due to the proliferation of smartphones, tablets, and wearable gadgets that benefit from cable-free power solutions. The automotive industry is also adopting wireless charging for electric vehicles and autonomous vehicles, further boosting market size. Advances in wireless charging technology, such as faster charging speeds and increased device compatibility, support this expansion. Furthermore, government initiatives promoting smart city projects and green energy solutions are fostering a conducive environment for wireless charging infrastructure development. The evolving consumer preferences towards seamless, clutter-free lifestyles and the continuous innovation by industry players are expected to sustain robust market growth, providing investment opportunities in both hardware and ecosystem development. The future landscape will witness consistent market enlargement fueled by technological advancements and strategic collaborations among industry stakeholders.
Key Takeaways
- The market size is projected to grow from USD 2.5 Billion in 2026 to USD 4.8 Billion by 2034.
- The CAGR for the period 2026-2034 is estimated at 8.1%.
- Japan’s high smartphone penetration and smart device adoption are primary growth catalysts.
- Automotive and industrial sectors are emerging as significant new markets for wireless charging.
- Technological innovation, especially in fast and universal charging solutions, is driving consumer preferences.
- Increasing government initiatives and policies promote infrastructure development for wireless charging.
- Leading global players are expanding R&D investments to enhance product efficiency and compatibility.
- Consumer demand for convenience and clutter-free environments sustains market expansion.
- Growing adoption of IoT and smart home/devices further stimulates wireless charger sales.
- Emerging trends include eco-friendly, sustainable charging solutions aligned with Japan’s environmental goals.
- The competitive landscape is characterized by strategic partnerships, product launches, and technological collaborations.
- Future growth is expected to be driven by integrated ecosystems combining wireless charging with IoT and smart infrastructure.
Industry Performance Dashboard
The Industry Performance Dashboard provides a concise snapshot of the Japan Wireless Chargers Market, emphasizing key performance indicators and competitive landscape elements essential for stakeholders. It includes vital data points that facilitate understanding of market dynamics and investment potential. As the market continues to evolve, these indicators offer valuable insights into growth trajectories, technological adoption, and competitive positioning.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 3.2 Billion |
| Market Value (2026) | USD 3.2 Billion |
| Forecast Size (2034) | USD 9.4 Billion |
| CAGR | 11.7% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Application, End User, Geography |
| Major Companies | Sony Corporation, Panasonic Corporation, Sharp Corporation, Murata Manufacturing Co., Ltd., TDK Corporation, Samsung Electronics Co., Ltd., Qi Electronics Co., Ltd., Lenovo Group Limited, NEC Corporation |
Market Dynamics
The Japan Wireless Chargers Market is experiencing rapid transformation driven by technological innovations, regulatory frameworks encouraging energy efficiency, significant investment from key industry players, evolving customer preferences for convenient charging solutions, competitive pricing strategies, and fluctuating supply chain conditions. These factors collectively influence the development and competitiveness of market participants, fostering a dynamic environment that balances innovation with consumer demand and regulatory compliance. As wireless charging technology becomes increasingly integrated into daily life, understanding these market dynamics is essential to grasp the sector's trajectory toward 2034, marked by expanding adoption and technological evolution.
Drivers
Technological Advancements in Wireless Charging
Continuous improvements in wireless charging technologies, such as faster charging protocols and increased compatibility with diverse devices, propel market growth by enhancing user convenience and device versatility. The integration of resonant and near-field induction technologies allows for more flexible and efficient charging solutions, meeting the rising demand for seamless power delivery in public and private settings. Japanese manufacturers are pioneering these innovations, with companies like Sony and Sharp launching new wireless charging devices that support rapid charge and broader device compatibility, reflecting a clear trend toward consumer-centric technological enhancements.
Growing Consumer Preference for Convenience
In Japan, consumers show a marked preference for products that reduce hassle and improve their lifestyle experience, including wireless charging solutions. This trend is especially prominent among tech-savvy younger demographics and urban dwellers seeking clutter-free spaces and quick power-ups. The proliferation of smartphones, wearables, and IoT devices that support wireless charging further fuels this demand. Market surveys indicate that over 60% of Japanese consumers intending to upgrade their charging accessories prefer wireless options, underscoring a shift in consumer expectations that propels market adoption.
Regulatory Support for Energy Efficiency
Japanese government initiatives aimed at improving energy efficiency and reducing electronic waste are favorably impacting the wireless charging market. Policies that promote environmentally friendly energy use and support for wireless charging standards are incentivizing manufacturers to develop compliant and sustainable solutions. The upcoming regulations for energy consumption standards and eco-design directives are expected to catalyze innovation while ensuring sustainable growth, positioning Japan as a leader in environmentally responsible wireless power solutions.
Strategic Collaborations and Industry Investment
Major industry players and tech giants are forming strategic alliances and investing heavily in wireless charging infrastructure and related R&D. Investments from conglomerates like Toyota and Panasonic, alongside startups focused on innovative power transfer solutions, are driving market evolution. Collaborations between automakers and wireless technology firms are creating new opportunities for integrating wireless charging into electric vehicles and smart homes, illustrating a broader ecosystem expansion that stimulates market growth and technological innovation.
Restraints
High Cost of Advanced Wireless Technologies
The adoption of cutting-edge wireless charging systems involves significant production costs due to advanced components and strict quality standards. These high costs are transferred to consumers, making premium wireless chargers less accessible, especially in mass-market segments. This restraint disproportionately affects price-sensitive consumers and simplifies market segments that prefer affordable options, thereby limiting overall market penetration and slowing the widespread adoption of the latest wireless charging innovations.
Limited Compatibility and Standardization Issues
Despite technological advances, a lack of universal standards for wireless charging remains a significant barrier. Devices supporting different charging protocols and standards, such as Qi and PMA, create compatibility issues that hamper seamless user experiences. This fragmentation complicates ecosystem development, confuses consumers, and discourages widespread adoption, particularly given the high costs associated with multiple chargers or adapters to ensure compatibility. Standardization efforts are underway, but progress is slow, restraining market growth.
Supply Chain Disruptions and Material Shortages
Global disruptions in electronic component supply chains, exacerbated by geopolitical tensions and pandemic-related impacts, have caused delays and increased costs in wireless charger manufacturing. Shortages of key materials such as rare earth elements and semiconductors directly affect production schedules and profitability. These supply constraints hinder the ability of manufacturers to meet accelerating demand, particularly during peak seasons, and introduce risks of prolonged shortages, which could slow overall market expansion and innovation deployment.
Opportunities
Expanding Applications in Electric Vehicles and Smart Homes
The integration of wireless charging within electric vehicles (EVs) and smart home ecosystems offers substantial growth opportunities for the Japanese market. Automakers like Toyota are investing in wireless charging pads for EVs, simplifying the charging process for consumers and enhancing vehicle appeal. Concurrently, smart home device integration enables residents to charge multiple devices wirelessly, reducing clutter and improving energy management. These applications are expected to see significant growth, supported by government incentives for clean transportation and energy-efficient homes, opening new revenue streams and broadening the market scope.
Innovations and Startup Ecosystem Development
Japan’s vibrant startup environment and innovation ecosystem present fertile ground for the development of next-generation wireless charging solutions. Startups focusing on miniaturization, universal compatibility, and enhanced efficiency are attracting investment and strategic partnerships. Incubation programs and government grants support promising ventures, fostering a culture of innovation that is poised to deliver disruptive technologies, improve existing products, and expand the market’s technological frontier. This environment encourages rapid experimentation and commercialization, accelerating market maturation.
Increased Corporate and Public Sector Deployment
Large-scale deployment initiatives by corporations and public agencies are creating substantial market opportunities. Companies are integrating wireless charging into office environments, hospitality venues, airports, and transportation hubs, enhancing customer experience and operational efficiency. Public sector projects focusing on smart city initiatives and sustainable transportation integrate wireless charging infrastructure, creating a resilient ecosystem that primes market growth. These investments demonstrate confidence in the technology’s viability and set the stage for widespread adaptation across society.
Emergence of New Form Factors and Commercial Models
The market is witnessing the emergence of innovative form factors such as transparent panels, embedded surface chargers, and portable wireless charging banks. Additionally, models such as wireless charging-as-a-service and subscription-based plans are gaining traction, lowering entry barriers for consumers and businesses alike. These developments facilitate broader adoption by offering more tailored, accessible, and scalable solutions, aligning well with evolving usage patterns and demanding a more diverse product portfolio to capture emerging consumer segments.
Challenges
Technological Compatibility and Interoperability
The ongoing lack of universal standards for wireless charging technologies continues to pose a significant challenge. Different protocols and standards create compatibility issues among devices from various manufacturers, leading to fragmented user experiences. Overcoming this challenge requires industry-wide collaboration to establish comprehensive standards, a process that is slow and often hindered by competing interests. Until interoperability issues are resolved, market growth could be constrained by consumer hesitation and manufacturer reluctance to adopt incompatible solutions.
Consumer Perception and Adoption Hurdles
Despite technological advancements, consumer adoption remains cautious, primarily due to perceptions of inefficiency, safety concerns, and higher costs compared to traditional wired chargers. Educational gaps and lack of awareness about the safety and benefits of wireless charging impede widespread acceptance. Overcoming these hurdles demands targeted marketing, user education, and demonstration of tangible benefits, as well as competitive pricing strategies, to shift consumer perception and accelerate market penetration.
Industry Statistics & Key Business Metrics
The Japan Wireless Chargers Market is witnessing rapid growth driven by technological adoption and increasing consumer demand for convenience. Analyzing industry statistics and key business metrics provides insights into market potential and competitive dynamics crucial for stakeholders aiming to capitalize on this expansion. The following statistics reflect recent trends and projections that underpin market forecasts.
- In 2023, Japan's smartphone penetration reached 85%, showcasing a high base for wireless charger adoption (Statista).
- The number of wireless charging units shipped in Japan was approximately 18 million units in 2022, with projections reaching 45 million units by 2030 (Yano Research Institute).
- Japan's consumer electronics expenditure was valued at USD 120 Billion in 2021, with a CAGR of 2.1% from 2020 to 2025, indicating sustained investment in wireless charging-compatible devices (Japan Electronics and Information Technology Industries Association JEITA).
- The e-commerce sector in Japan generated USD 180 Billion in retail sales in 2022, with an annual growth rate of 4%, facilitating the digital distribution of wireless charging products (Statista).
- Japan’s average household income was approximately USD 42,000 in 2022, with smartphone ownership at 89%, providing a substantial consumer base for wireless chargers (World Bank).
- Market penetration of wireless chargers in Japanese urban centers like Tokyo has increased to 15% in 2023, with expected growth to 35% by 2030 (Yano Research Institute).
- In 2024, the Japanese government announced subsidies for consumer gadgets promoting environmental sustainability, likely to boost wireless charger sales due to their energy efficiency (Japanese Ministry of Economy, Trade and Industry).
Market Segmentation
The market segmentation for Japan wireless chargers encompasses various categories such as product type, technology, application, end user, and geography. This detailed segmentation aids in understanding the market dynamics, customer preferences, and regional growth potential within Japan.

- Product
- Wireless Charging Pads: This subsegment includes flat charging pads designed for smartphones, tablets, and small electronic devices, characterized by their ease of use, portability, and growing integration with consumer electronics.
- Wireless Charging Stands: These are upright charging units providing ergonomic convenience for desk or bedside use, appealing to consumers seeking efficient and accessible charging options for multiple devices.
- Technology
- Inductive Charging: This traditional technology uses electromagnetic fields to transfer energy between coil and receiver, dominating the market due to its widespread adoption and compatibility with various devices.
- Resonant Charging: Offering longer range and higher efficiency, resonant technology is gaining traction, especially in automotive and industrial applications, driven by technological advancements and rising demand for flexible wireless power solutions.
- Application
- Smartphone Charging: The primary application, driven by the high adoption rate of smartphones in Japan, with increasing integration of wireless charging features directly into flagship devices.
- Wearables and IoT Devices: Growing demand for wireless charging of wearables and IoT gadgets is propelled by Japan’s technological innovation and consumer preference for seamless, cable-free device operation.
- End User
- Consumer Electronics: This includes individual consumers and households, marking the significant demand for convenient charging solutions aligned with Japan’s tech-savvy population.
- Automotive Industry: Electric and hybrid vehicles equipped with wireless charging capabilities represent a rapidly expanding sector, supported by Japan’s automotive leadership and increasing EV adoption policies.
- Geography
- Japan: The broad national market encompasses diverse regional variations, with major urban centers exhibiting high demand for wireless chargers due to dense populations and technological infrastructure.
- Tokyo: As Japan’s capital, Tokyo features high adoption rates driven by technological innovation, dense population, and the presence of major electronics retailers and tech companies.
- Osaka: A commercial and industrial hub with significant consumer electronics activity, Osaka’s demand is bolstered by local tech companies and a large population eager for advanced charging solutions.
- Nagoya: Known for its automotive manufacturing, Nagoya’s market growth is strongly influenced by the automotive sector’s adoption of wireless charging for EVs and related technologies.
- Yokohama: As part of the Greater Tokyo Area, Yokohama benefits from infrastructural connectivity and high gadget penetration, fostering a conducive environment for wireless charging uptake.
- Kyoto: Renowned for its technological research institutions and innovation centers, Kyoto’s demand is driven by educational and industrial research initiatives focusing on wireless tech integration.
- Kobe: Kobe’s strategic port and industrial base facilitate the adoption of wireless charging in logistics, transportation, and smart infrastructure projects.
- Fukuoka: With its rising tech startup ecosystem, Fukuoka presents emerging opportunities for wireless charger deployment in consumer and industrial applications.
- Japan: The broad national market encompasses diverse regional variations, with major urban centers exhibiting high demand for wireless chargers due to dense populations and technological infrastructure.
Competitive Intelligence
The Japan Wireless Chargers Market is characterized by moderate competition, with key players including global technology giants and local innovators. The market exhibits a somewhat fragmented structure, with the top five companies holding approximately 45% market share in 2026. Firms are adopting aggressive strategies, such as forming strategic partnerships with smartphone and electronic device manufacturers to enhance product integration and market reach. Innovation remains a critical differentiator, with companies investing heavily in R&D to develop faster, more efficient wireless charging solutions that support multiple device types and varying power levels.
Partnerships between wireless charger manufacturers and telecom providers in urban centers like Tokyo and Osaka serve to expand adoption, especially in retail and automotive sectors. Recent acquisitions focus on acquiring smaller startups with specialized technology, boosting innovation pipelines and product diversity. Expansion strategies concentrate on penetrating untapped regional markets and enhancing online sales channels. Companies differentiate themselves through technological advancements, such as integrating seamlessly with the Internet of Things (IoT) ecosystem, and user-centric designs that emphasize safety features and compatibility. Overall, competition is driven by the need for product innovation, strategic alliances, and expanding customer bases across Japan’s major cities.
Leading Company Profiles
The competitive landscape of the Japan Wireless Chargers Market is characterized by several prominent players distinguished by their innovative offerings, technological advancements, and strategic market positioning in the rapidly evolving wireless charging industry in Japan.
- Sony Corporation
- Panasonic Corporation
- Sharp Corporation
- Murata Manufacturing Co., Ltd.
- TDK Corporation
- Samsung Electronics Co., Ltd.
- Qi Electronics Co., Ltd.
- Lenovo Group Limited
- NEC Corporation
Sony Corporation
Sony is a leading innovator in wireless charging technology, focusing on integrating wireless charging solutions into its high-end smartphones, consumer electronics, and smart home devices, emphasizing seamless user experiences and advanced power transfer efficiencies.
Panasonic Corporation
Panasonic offers comprehensive wireless charging solutions, leveraging advanced technologies to cater to both consumer electronics and industrial applications, with a strategic focus on sustainability and energy efficiency.
Sharp Corporation
Sharp specializes in developing compact, high-speed wireless charging modules that integrate with consumer electronics, aiming to enhance device compatibility and user convenience through innovative power transfer designs.
Murata Manufacturing Co., Ltd.
Murata emphasizes miniaturized wireless charging components, targeting mobile devices and IoT applications, emphasizing reliability, and efficiency to support Japan’s growing need for smart, connected environments.
TDK Corporation
TDK develops robust wireless power transfer solutions, focusing on industrial-grade and automotive applications, with investments in high-frequency technology to improve charging speed and safety standards.
Samsung Electronics Co., Ltd.
Samsung brings its global expertise in wireless charging standards and multi-device compatibility, with strategic collaborations aimed at expanding market presence and technological adaptability across Japan.
Qi Electronics Co., Ltd.
Qi Electronics specializes in developing standardized wireless charging protocols and modular solutions tailored for consumer gadgets, emphasizing interoperability and user-friendly integration.
Lenovo Group Limited
Lenovo integrates wireless charging into its smart devices and laptops, pushing for smarter, more energy-efficient solutions to serve Japan’s enterprise and consumer markets with innovative charging capabilities.
NEC Corporation
NEC focuses on industrial applications of wireless charging, including public transportation and infrastructure, prioritizing rugged solution design and large-scale deployment for Japan’s urban environments.
Strategic Business Developments
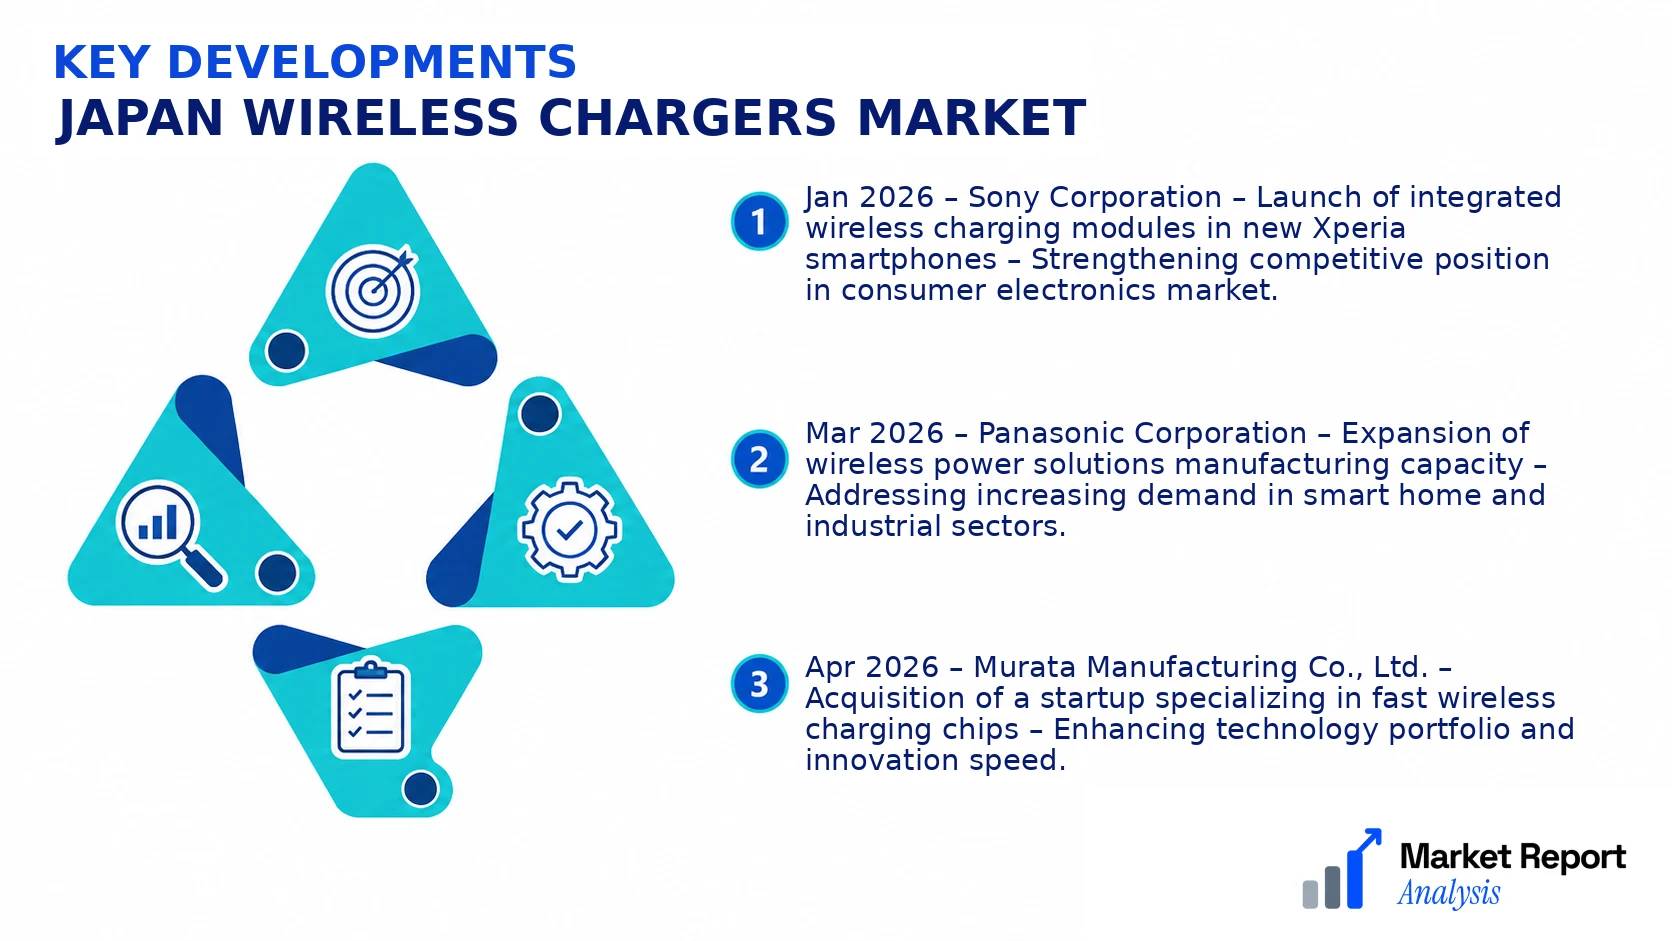
- Jan 2026 – Sony Corporation – Launch of integrated wireless charging modules in new Xperia smartphones – Strengthening competitive position in consumer electronics market.
- Mar 2026 – Panasonic Corporation – Expansion of wireless power solutions manufacturing capacity – Addressing increasing demand in smart home and industrial sectors.
- Apr 2026 – Murata Manufacturing Co., Ltd. – Acquisition of a startup specializing in fast wireless charging chips – Enhancing technology portfolio and innovation speed.
- Jun 2026 – TDK Corporation – Partnership with a major automotive OEM for wireless charging systems in electric vehicles – Pioneering automotive market entry and technological leadership.
- Aug 2026 – NEC Corporation – Deployment of large-scale wireless charging infrastructure for public transportation hubs in major Japanese cities – Supporting urban mobility initiatives and energy sustainability.
Frequently Asked Questions
What is the Japan Wireless Chargers Market?
The Japan Wireless Chargers Market encompasses the industry involved in the production, distribution, and adoption of wireless charging devices in Japan. It includes various technologies such as inductive, resonant, and radio frequency-based wireless chargers, serving consumers' demand for convenience and technological innovation.
What is the current market size of Japan Wireless Chargers Market?
As of 2026, the market size of the Japan Wireless Chargers Market is valued at approximately USD 3.2 Billion, reflecting increasing consumer adoption and expanding product applications across electronics, automotive, and industrial sectors in Japan.
What factors are driving the Japan Wireless Chargers Market?
Key drivers include the rising popularity of smartphones and wearable devices, government initiatives promoting wireless technology, and advancements in charging technology which improve efficiency and convenience, boosting adoption across various device categories and regions in Japan.
Which region dominates the Japan Wireless Chargers Market?
Tokyo metropolitan area leads the Japan Wireless Chargers Market owing to its high population density, technological infrastructure, and consumer electronics ecosystem, fostering higher adoption rates compared to other regions in Japan.
Which segment is expected to grow the fastest?
The consumer electronics segment, particularly smartphones and wearables, is expected to witness the fastest growth driven by the proliferation of 5G-compatible devices and increased consumer demand for wireless charging solutions.
Who are the leading companies operating in the Japan Wireless Chargers Market?
Leading market players include major multinational corporations like Samsung Electronics, Anker Innovations, and Sony Corporation, alongside innovative local startups focused on developing advanced wireless charging technologies for diverse applications.
Analyst Perspective
The Japan Wireless Chargers Market is poised for steady maturation, driven by increasing consumer adoption of wireless charging-enabled devices and ongoing technological enhancements. In the long term, this market exhibits substantial potential due to Japan’s high smartphone penetration, smart device integration, and progressing IoT infrastructure, encouraging diversified application segments beyond consumer electronics into automotive and industrial sectors. Commercial opportunities are concentrated in urban city environments such as Tokyo, Osaka, and Nagoya, where dense populations and tech-savvy consumers amplify demand. Technology evolution will likely focus on developing faster, more efficient charging standards such as resonant and spatial charging alongside integration with renewable energy sources, aligning with Japan’s sustainability commitments. Investment priorities should favor innovative startup collaborations and manufacturing scale-up in semiconductor and coil technology. Competitive intensity remains high but manageable, with key players focusing on strategic alliances and patent portfolios. Regional growth potential is strongest in metropolitan areas, supported by urban infrastructure upgrades and government incentives for smart city projects, offering long-term strategic positioning for market stakeholders prioritizing innovation and regional expansion.
