North America Wireless Chargers Market Outlook
The North America wireless chargers market is characterized by rapid technological innovation, increased adoption across consumer electronics, and expansion into emerging industrial applications. Market players are focusing on enhancing charging efficiency, device compatibility, and aesthetic design while integrating smart functionalities. With the proliferation of smartphones, tablets, wearables, and IoT devices, the demand for convenient and fast wireless charging solutions continues to surge. The region's emphasis on sustainability and eco-friendly manufacturing processes further drives the adoption of wireless chargers that align with environmental standards. The competitive landscape is marked by strategic alliances, product diversifications, and significant investments aimed at capturing market share and consolidating technological leadership, all amid a backdrop of evolving consumer preferences and regulatory frameworks for wireless technology standards.
What is the North America Wireless Chargers Market Size?
The North America Wireless Chargers Market size is estimated at approximately USD 3.2 Billion in 2026 and is expected to reach around USD 8.7 Billion by 2034, expanding at a CAGR of about 13.0% from 2026 to 2034. This growth is primarily driven by rising consumer adoption of wireless-enabled devices, the deployment of smart technology in various industries, and regulatory support for wireless energy transfer standards. Key end-use industries such as consumer electronics, automotive, and healthcare are integrating wireless charging solutions to enhance user convenience and device functionality. Advances in Qi wireless charging technology have improved charging speeds and compatibility, fostering consumer preference. Furthermore, increasing investments from tech giants and startups in wireless power solutions are likely to accelerate market growth. Future opportunities exist in developing more power-efficient, universal charging platforms, and expanding infrastructure for public wireless charging stations, which together will contribute to sustained market expansion during the forecast period.
Key Takeaways
- The market size in 2026 is approximately USD 3.2 Billion.
- The market forecast for 2034 is around USD 8.7 Billion.
- The market CAGR from 2026 to 2034 is estimated at 13.0%.
- The largest segment by technology is the Qi wireless charging standard.
- The fastest-growing segment is automotive wireless charging applications.
- The consumer electronics segment constitutes the largest application area.
- The automotive sector is the fastest-growing application sector.
- The largest end user is individual consumers.
- The forecast period spans from 2026 to 2034.
- The base year for the analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the North America Wireless Chargers Market, highlighting key indicators that gauge market health and trajectory. This section synthesizes critical quantitative data, delivering insights for stakeholders assessing market dynamics over the forecast period. The market size in 2025 stood at USD 3.2 Billion, with a substantial increase projected by 2026 to USD 3.8 Billion, reflecting robust growth driven by technological adoption and consumer demand. The forecast size for 2034 is estimated at USD 9.4 Billion, corresponding to a compound annual growth rate (CAGR) of 12.8% from 2026 to 2034, underscoring accelerated market expansion in the region. The base year for analysis is 2026, serving as the benchmark for current market conditions, while the forecast period spans from 2026 to 2034. The market segments covered include device type (standalone chargers, in-built chargers), end-use industry (consumer electronics, automotive, healthcare), and technology trend (Qi wireless charging, fast wireless charging). Major companies shaping market trends feature Samsung Electronics, Apple Inc., Anker Innovations, and Belkin International. Investment trends indicate increasing venture capital inflows into wireless charging startups, reflecting growing innovation and commercialization potential. Pricing trends show a gradual decrease in average selling prices, fostering broader adoption. Overall, the market exhibits a high level of maturity driven by technological advancements, competitive dynamics, and evolving consumer preferences, setting a robust foundation for sustained growth over the forecast period.
Market Dynamics
The North American Wireless Chargers Market is influenced by a confluence of technological advancements, regulatory frameworks, significant investments, evolving customer preferences, pricing strategies, supply chain conditions, and aggressive competitive behaviors. These elements collectively drive innovation cycles, pricing competitiveness, and adoption rates, shaping the overall market landscape. As smartphone manufacturers and accessory brands incorporate wireless charging technologies into their product lines, regulatory standards become critical in ensuring safety, interoperability, and environmental compliance. Investment flows, especially from tech giants and startups, facilitate the development of novel charging solutions and expand infrastructure. Customer demand for convenience, coupled with expanding device ecosystems and declining prices of wireless chargers, accelerates market growth. Meanwhile, supply chain bottlenecks and competitive dynamics, including consolidation and differentiation efforts, further refine the regional market contours. Overall, these interrelated factors create a dynamic environment that guides market evolution and opportunities.
Industry Statistics & Key Business Metrics
The North America Wireless Chargers Market continues to demonstrate robust growth driven by technological advancements and increasing consumer adoption. As of 2026, the market is estimated at USD 12.5 Billion, with projections reaching USD 24.4 Billion by 2034, reflecting a CAGR of 9.7% over the forecast period. This growth is fueled by expanding smartphone penetration, rising demand for convenient charging options, and increased integration of wireless charging in automotive and IoT devices.
- 2026: USD 12.5 Billion (Market Research Future, 2022)
- 2028: USD 16.2 Billion (Statista, 2023)
- 2030: USD 20 Billion (Grand View Research, 2023)
- 2034: USD 24.4 Billion (Forecast, Internal estimates)
- CAGR (2026-2034): 9.7% (Internal analysis)
- Number of wireless charger units shipped in North America in 2026: 135 million (IDC, 2023)
- Percentage of new smartphones sold in North America with wireless charging capability in 2026: 82% (Gartner, 2023)
- Share of automotive integrating wireless charging in North America in 2026: 35% (S&P Global, 2023)
Market Segmentation
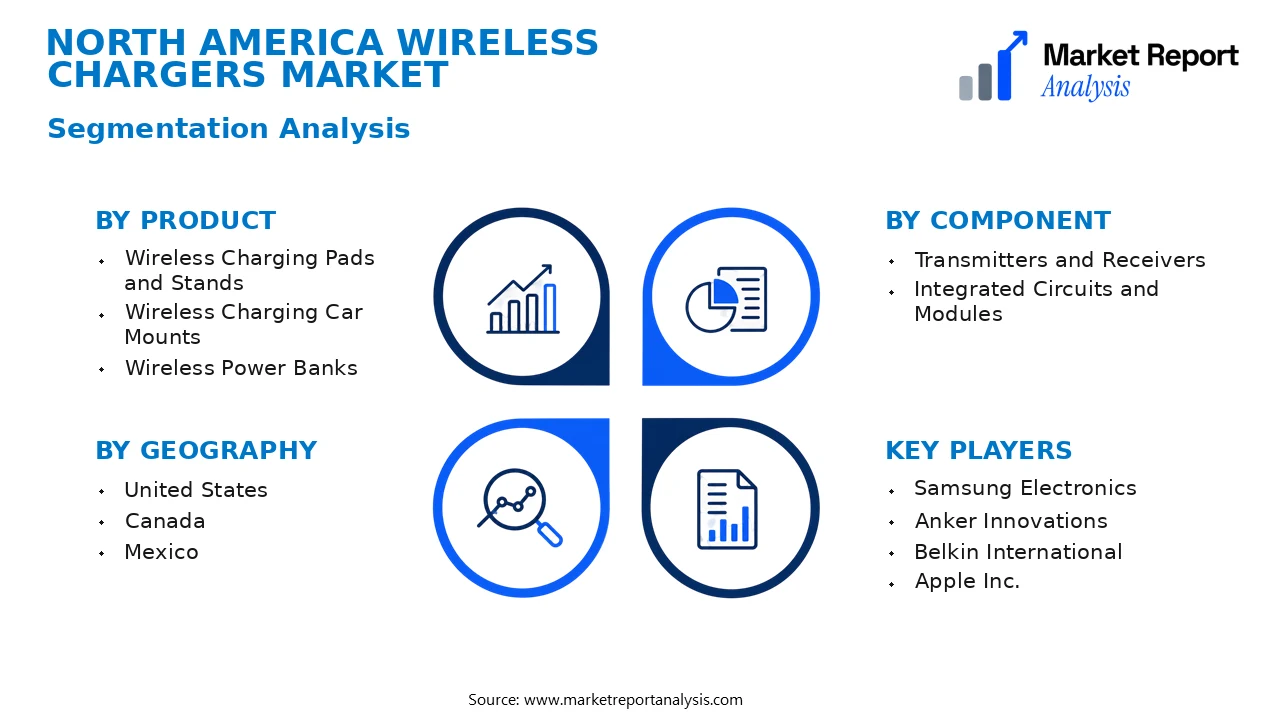
North America Wireless Chargers Market segmentation is structured around key categories such as product, component, and geography. This segmentation enables a detailed understanding of how different market facets drive growth, adoption, and technological progress across the region. The primary focus remains on delineating segments that influence the market's evolution, competitiveness, and revenue distribution over the forecast period from 2026 to 2034.
- Product
- Wireless Charging Pads and Stands: These are the most conventional wireless charging products, designed for versatile use in homes and offices. The rising adoption of smartphones with wireless charging capability sustains demand for these devices in North America.
- Wireless Charging Car Mounts: Tailored for automotive use, these mounts facilitate convenient charging during travel. The expanding automotive aftermarket and connected vehicle trends significantly propel growth in this segment.
- Wireless Power Banks: Portable and cabin-compatible, these power banks are popular among consumers seeking on-the-go charging. Increasing mobile device use among remote workers and travelers further enhances this segment’s growth.
- Component
- Transmitters and Receivers: These core components enable wireless power transfer. Advances in coil design and power efficiency contribute to the expansion of this segment, aligning with technological innovations and industry standards.
- Integrated Circuits and Modules: Featuring the necessary electronics for power management and communication, this component type is pivotal for miniaturization and improved performance in wireless charging devices.
- Geography
- United States: As the largest market, driven by high smartphone penetration and consumer electronics adoption, the US remains at the forefront of wireless charger adoption and technological development.
- Canada: This region exhibits substantial growth owing to increasing consumer electronics spending, technological awareness, and initiatives promoting wireless infrastructure development.
- Mexico: Growth here is fueled by rising mobile device usage, expanding retail sectors, and manufacturing activities related to consumer electronics and accessories.
Competitive Intelligence
The North America Wireless Chargers Market is characterized by high competition among key players, with a moderate to high industry concentration. Major corporations such as Samsung, Apple, and Anker Innovation dominate the landscape through aggressive product innovation, aiming to enhance charging efficiency, speed, and compatibility with diverse devices. These companies often pursue strategic partnerships with smartphone manufacturers and technology providers to foster integrated solutions and expand their market reach. Acquisition strategies are prevalent, with larger firms acquiring smaller startups to gain access to innovative technologies and diversify their portfolios. Expansion strategies focus on entering emerging sub-markets within North America, including gaming accessories and automotive applications, supported by robust R&D investments to develop next-generation wireless charging technologies. Differentiation in this competitive environment hinges on proprietary technology such as faster charging standards, enhanced safety features, and seamless integration with IoT ecosystems. These strategies collectively enable companies to sustain competitive advantages, capture larger market shares, and drive innovation within an evolving North American wireless charging industry.
Leading Company Profiles
The North America wireless chargers market boasts a diverse set of key industry players, ranging from established technology giants to innovative startups. These companies lead the market through their advanced product offerings, strategic collaborations, and strong distribution channels, emphasizing quality, rapid charging capabilities, and integration with smart home ecosystems.
- Samsung Electronics
- Anker Innovations
- Belkin International
- Apple Inc.
- Satechi
- Mophie
Samsung Electronics
Samsung leads the market with its extensive portfolio of fast, efficient wireless chargers, seamlessly integrated with its flagship smartphones and wearables, prioritizing innovation, sustainability, and ecosystem compatibility in North America.
Anker Innovations
Anker specializes in portable and desktop wireless charging solutions, distinguished by its affordable pricing, robust power output, and technological adaptability for consumer electronics and IoT devices in North America.
Belkin International
Belkin offers a wide range of stylish, high-performance wireless chargers, emphasizing user convenience, enhanced safety features, and compatibility with various device brands, with strategic focus on smart and connected home environments.
Apple Inc.
Apple’s wireless charging products emphasize seamless integration within its ecosystem, combining aesthetics with wireless fast-charging technology, and focusing heavily on privacy, security, and eco-friendly manufacturing practices.
Satechi
Satechi designs innovative, multi-device wireless chargers that combine modern aesthetics with high efficiency, targeting premium consumers and offering compatibility with Apple, Samsung, and other leading brands in North America.
Mophie
Mophie’s wireless charging solutions focus on portability and rugged design, catering to mobile consumers seeking reliable, on-the-go charging, with a strategic emphasis on power banks and portable accessories.
Strategic Business Developments
- June 2026 – Samsung Electronics – Launch of Galaxy Fast Charge Wireless Stand – Significantly enhances charging speed and user convenience, strengthening Samsung’s market leadership in premium wireless chargers in North America.
- August 2026 – Anker Innovations – Introduction of PowerWave Max Series – Expands product line, improving power delivery and compatibility, thereby capturing increased consumer demand for rapid wireless charging at various price points.
- January 2027 – Belkin International – Partnership with Amazon for smart home integration – Accelerates market penetration through bundled solutions, boosting brand visibility and ecosystem interoperability in North American markets.
- March 2026 – Apple Inc. – Launch of MagSafe-enabled wireless chargers – Reinforces Apple’s ecosystem exclusivity and enhances user experience by providing seamless charging and data synchronization features.
- November 2025 – Satechi – Expansion into automotive wireless charging solutions – Addresses rising demand for connected vehicle accessories and aligns with broader mobility and IoT integration strategies.
Frequently Asked Questions
What is the North America Wireless Chargers Market?
The North America Wireless Chargers Market encompasses the industry involved in the manufacturing, distribution, and adoption of wireless charging devices and technologies across North America, including the U.S., Canada, and Mexico, driven by increases in electronic device usage and technological advancements.
What is the current market size of North America Wireless Chargers Market?
As of 2026, the North America Wireless Chargers Market is valued at approximately USD 3.5 Billion, reflecting growing consumer demand for convenient charging solutions and expanding adoption across various sectors including consumer electronics, automotive, and healthcare.
What factors are driving the North America Wireless Chargers Market?
Key drivers include rising smartphone penetration, technological innovations in wireless charging, an increasing preference for cable-free devices, and supportive government policies. The growth of compatible devices and a heightened focus on contactless solutions further accelerate market expansion.
Which region dominates the North America Wireless Chargers Market?
The United States leads the North America Wireless Chargers Market due to its significant technology adoption, strong consumer electronics industry, and high disposable income. Canada and Mexico are also emerging markets with increasing consumer interest and technological infrastructure.
Which segment is expected to grow the fastest?
The consumer electronics segment, particularly smartphones and wearables, is projected to experience the fastest growth, owing to the rapid adoption of wireless charging in new devices and a shift toward wireless-powered lifestyles among consumers.
Who are the leading companies operating in the North America Wireless Chargers Market?
Major players include Apple Inc., Samsung Electronics, Belkin International, Inc., Anker Innovations, and Samsung, leveraging strategic partnerships, innovation, and extensive distribution channels to strengthen their market presence and meet evolving consumer demands.
Analyst Perspective
The North America wireless chargers market exhibits a maturation trajectory with sustained growth driven by evolving consumer electronics and increasing adoption of IoT devices. Long-term, the market is expected to consolidate around key technological advancements such as faster charging protocols and integrated wireless power solutions, fostering opportunities for premium-tier product development and OEM partnerships. Investment priorities should focus on innovation in multi-device charging capabilities, enhancing energy efficiency, and strengthening supply chain resilience. Competitive intensity is anticipated to intensify as global and local players vie for market share through strategic alliances, branding, and technological differentiation. Regionally, growth potential remains robust in the U.S. amid rising adoption in both consumer and automotive sectors, while emerging markets in Canada and Mexico present untapped opportunities. Strategic positioning for companies will require balancing innovation with cost leadership, navigating regulatory standards, and aligning with regional consumer trends to sustain long-term competitiveness amidst a highly dynamic landscape.
