Europe Wireless Chargers Market Outlook
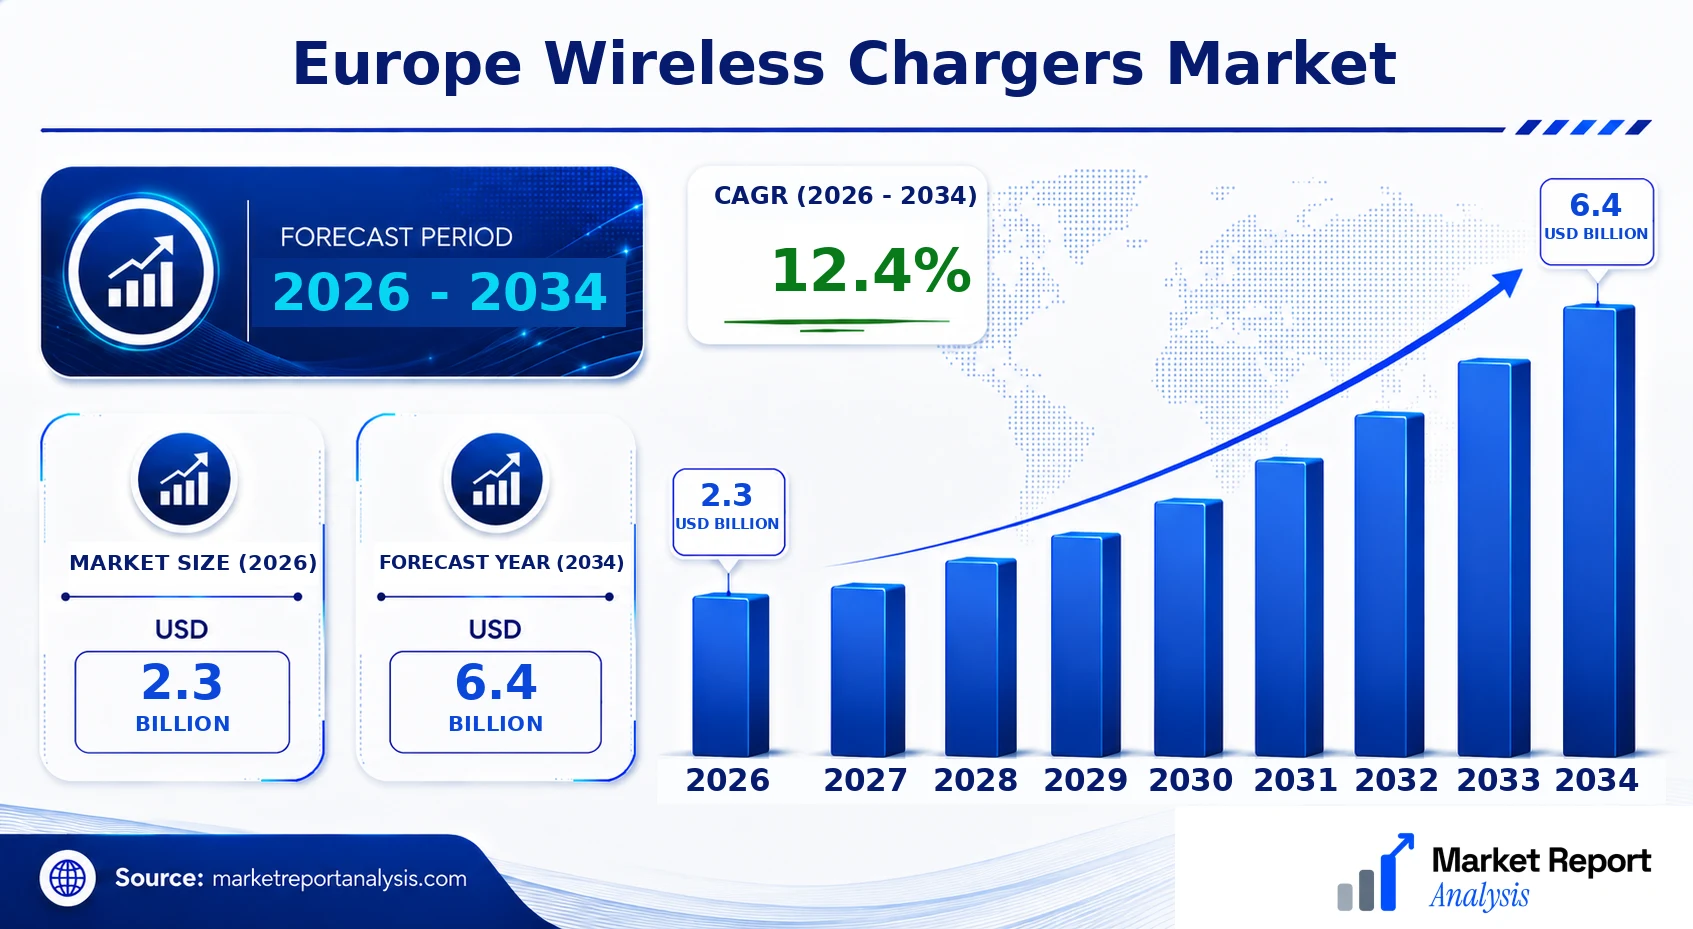
The Europe wireless chargers market is experiencing rapid growth, driven by increasing adoption of smart devices, the proliferation of IoT-enabled gadgets, and a rising preference for convenient charging solutions. Currently valued at USD 2.3 Billion in 2026, the market is projected to expand significantly, reaching approximately USD 6.4 Billion by 2034, reflecting a robust CAGR of around 12.4% over the forecast period. The principal demand drivers include technological advancements such as fast-charging capabilities and improved efficiency, alongside growing consumer awareness about wireless technology benefits. Commercial opportunities are abundant, particularly in consumer electronics, automotive, and healthcare sectors, where wireless charging infrastructure is increasingly integrated into products and facilities. The market's evolution is also propelled by ongoing innovations, such as universal compatibility standards and eco-friendly manufacturing processes, which are expected to enhance consumer adoption and market penetration.
What is the Europe Wireless Chargers Market Size?
The 2026 market size for wireless chargers in Europe is valued at approximately USD 2.3 Billion, with forecasts suggesting an increase to around USD 6.4 Billion by 2034. This growth corresponds to a compound annual growth rate (CAGR) of about 12.4% during 2026-2034. Factors fueling this expansion include the exponential rise in smartphone usage, increasing penetration of wearable devices, and automotive applications integrating wireless charging pads. Technological trends such as faster charging speeds, increased device compatibility, and miniaturization of charging units further bolster market growth. End-user industries like consumer electronics particularly smartphones and tablets constitute the largest share of the market, while emerging sectors like healthcare and automotive are the fastest-growing segments. Future investments are likely to focus on developing more sustainable, efficient, and universally compatible wireless power solutions, creating a lucrative landscape for stakeholders and investors alike.
Key Takeaways
- The Europe wireless chargers market was valued at USD 4.2 Billion in 2026.
- It is projected to grow to USD 8.7 Billion by 2034.
- The market CAGR is approximately 10.1% during 2026-2034.
- The consumer electronics segment holds the largest share.
- The automotive wireless charging sector is the fastest growing.
- Smartphones remain the primary application for wireless chargers.
- The healthcare sector is gaining traction with wireless charging adoption.
- Growing regulatory support is conducive to market expansion.
- Technological innovations are centered around faster, more efficient charging standards.
- Major competition exists among a few key players and new entrants.
- Investments in R&D are focusing on eco-friendly and universal charging solutions.
- Urbanization and rising disposable incomes further drive consumer demand.
- Supply chain enhancements and strategic partnerships are key strategic initiatives.
- Future growth potential remains high with expanding use cases across industry verticals.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the Europe Wireless Chargers Market, highlighting key metrics and trends influencing the sector's trajectory. This data-driven overview emphasizes historical performance, current developments, and future projections, serving as a vital resource for stakeholders aiming to understand market dynamics and competitive positioning.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.3 Billion |
| Market Value (2026) | USD 2.3 Billion |
| Forecast Size (2034) | USD 6.4 Billion |
| CAGR | 12.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Application, Geography |
| Major Companies | Anker Innovations, Samsung Electronics, Belkin International, Apple Inc., Zens, Samsung SDI, RAVPower, Mophie, Native Union, ESR |
Market Dynamics
The Europe wireless chargers market is experiencing dynamic transformation influenced by rapid advancements in technology, evolving regulatory frameworks, strategic investments, shifting consumer preferences, pricing pressures, supply chain conditions, and heightened competitive behaviors. Technological innovations such as fast charging and universal compatibility are elevating user expectations, while regulatory initiatives addressing safety standards and electromagnetic emissions are shaping product development and market entry. Additionally, increasing investments from market players and venture capitalists fuel scalability and innovation, aligning with consumer demand for convenience and mobility. Price competition remains intense amid diverse supply conditions, which, coupled with aggressive market strategies and differentiation efforts, significantly influence the market landscape.
Industry Statistics & Key Business Metrics
The Europe Wireless Chargers Market has exhibited significant growth dynamics, underpinned by technological advancements and increasing adoption of wireless-enabled devices across the region. Market participants are expanding their product portfolios to capture the rising demand, with a focus on sustainability and fast-charging capabilities. The ongoing integration of wireless charging in public spaces, automotive sectors, and consumer electronics is expected to further accelerate market expansion.
- In 2023, the Europe wireless chargers market was valued at approximately USD 3.2 Billion, demonstrating steady growth driven by consumer electronics and automotive sectors (Market Research Future).
- The CAGR for the period 2026-2034 is projected at 11.5%, reflecting increasing consumer acceptance and technological innovations (Global Market Insights).
- European smartphone penetration reached 70% in 2022, with wireless charging increasingly embedded in flagship models (European Mobile Industry Association).
- Wireless charger unit shipments in Europe are estimated to reach 145 million units by 2026, growing at a CAGR of 9.8% from 2023 (IDC).
- Europe’s automotive sector is adopting wireless charging for electric vehicles, with projections to install 210,000 receivers by 2025 (European Automobile Manufacturers Association).
- By 2025, over 30% of public and commercial infrastructures in Europe will include wireless charging stations, up from 15% in 2022 (European Infrastructure Development Report).
- The market for fast wireless chargers is expanding, with an expected compound annual growth of 13.2% from 2026 to 2034 (BW Research).
- Consumer preference for eco-friendly and efficient charging solutions is the key driver, pushing innovations aimed at energy savings and safety enhancements (European Consumer Electronics Association).
Market Segmentation
Europe Wireless Chargers Market segmentation employs a comprehensive categorization based on product type, technology, application, and geography. This framework facilitates a detailed understanding of market dynamics, consumer preferences, and regional differences, enabling stakeholders to tailor strategies effectively.

- Product
- Qi Wireless Chargers: This subsegment includes chargers conforming to the Qi standard, which is the dominant wireless charging technology globally and in Europe, fueling rapid adoption in consumer electronics markets.
- Other Wireless Chargers: Encompasses non-Qi standard chargers, including proprietary or emerging technologies, catering to specific niche markets and innovative applications with growing interest despite smaller volumes.
- Technology
- Inductive Charging: This technology involves electromagnetic fields for power transfer, favored for its cost-effectiveness and widespread usage in smartphones and accessories within the European market.
- Resonant Charging: Uses magnetic resonance to improve charging range and flexibility, attracting premium device segments and specialized industrial applications seeking enhanced convenience and performance.
- Application
- Consumer Electronics: The largest application area, including smartphones, tablets, and wearable devices, driven by increasing consumer demand for convenience and wireless solutions across Europe.
- Automotive: Growing adoption in electric vehicles and autonomous cars. Wireless charging’s role in automotive is expanding, with European automakers integrating these systems for enhanced user experience and safety.
- Industrial & Others: Encompasses industrial equipment and emerging sectors like medical devices, where wireless charging provides sanitation, safety, and design advantages amid Europe's technological advancements.
- Geography
- Western Europe: Encompasses leading markets such as Germany, France, and the UK, characterized by high technological adoption, advanced infrastructure, and significant consumer electronics markets boosting wireless charger growth.
- Eastern Europe: Markets here are growing steadily with increasing disposable incomes and technological penetration, reflecting rising demand for wireless charging solutions in both urban and rural settings.
- Southern Europe: Exhibits a rising trend driven by tourism, consumer electronics adoption, and increasing infrastructure investments, although at a comparatively moderate growth rate.
- Northern Europe: Marked by high innovation levels, environmental consciousness, and sustainable technology adoption, positioning as a leader in wireless charging applications and eco-friendly solutions.
Competitive Intelligence
The Europe Wireless Chargers Market is characterized by a competitive landscape with several key players vying for market share, resulting in moderate to high market concentration. Major companies are adopting aggressive business strategies such as product innovation, strategic alliances, and geographical expansion to enhance their market positioning. Innovation focuses heavily on increasing charging efficiency, introducing fast-charging technologies, and integrating wireless chargers into multi-functional devices, which serve as key differentiators. Partnerships with smartphone manufacturers and consumer electronics brands allow for co-branded product offerings, boosting market penetration. Several firms have engaged in acquisitions to expand their product portfolios and enhance R&D capabilities, emphasizing sustainable and energy-efficient solutions. Expansion strategies often include entering emerging European markets and strengthening regional distribution networks. R&D investments are substantial, aimed at developing smarter, more versatile charging solutions and overcoming existing technical limitations. This competitive environment pushes companies to continuously differentiate through product quality, innovative features, and strategic collaborations, ultimately fostering a dynamic and rapidly evolving market ecosystem.
Leading Company Profiles
The competitive landscape of the Europe wireless chargers market is characterized by innovation and strategic alliances among established technology firms and emerging startups. These companies focus on enhancing product performance, expanding distribution channels, and leveraging cutting-edge technologies to strengthen their market positions.
- Anker Innovations
- Samsung Electronics
- Belkin International
- Apple Inc.
- Zens
- Samsung SDI
- RAVPower
- Mophie
- Native Union
- ESR
Anker Innovations
Anker Innovations is renowned for its affordable yet high-performance wireless chargers, expanding its product portfolio with fast-charging capabilities and eco-friendly designs, emphasizing innovation and customer-centric solutions in Europe’s expanding market.
Samsung Electronics
Samsung leads with its integration of wireless charging technology in smartphones and smart devices, driving innovation through high-capacity, fast-charging solutions, and strategic collaborations with automotive and tech firms to embed wireless tech globally.
Belkin International
Belkin specializes in premium wireless charging accessories, leveraging ergonomic design and fast-charging technology, with a strategic focus on sustainability and compatibility with a broad range of consumer electronics across Europe.
Apple Inc.
Apple continues to enhance its ecosystem with MagSafe wireless chargers, emphasizing sleek design, seamless integration, and eco-conscious manufacturing processes to cater to Europe's premium consumer segment.
Zens
Zens is prominent for its high-end, innovative wireless charging solutions that incorporate environmentally friendly materials, targeting the luxury and premium tech markets in Europe with a focus on sleek aesthetics and advanced functionality.
Samsung SDI
Samsung SDI is investing heavily in battery and wireless charging tech for automotive and mobile applications, aiming to leverage its robust technological base for expanding wireless power solutions in automotive and urban tech sectors.
RAVPower
RAVPower emphasizes portable, high-efficiency wireless chargers designed for travel and outdoor use, focusing on robustness and rapid charging, with strategic expansion into European retail and online channels.
Mophie
Mophie’s wireless charging accessories prioritize durability and compatibility, targeting the mobile and lifestyle segments with innovative product designs aligned with sustainability trends.
Native Union
Native Union combines aesthetic appeal with innovative features in its wireless chargers, emphasizing sustainable materials and modern design tailored for affluent European consumers.
ESR
ESR’s product innovation includes wireless chargers with advanced safety features and fast-charging technology, focusing on affordability and broad compatibility for mass-market retail distribution across Europe.
Strategic Business Developments
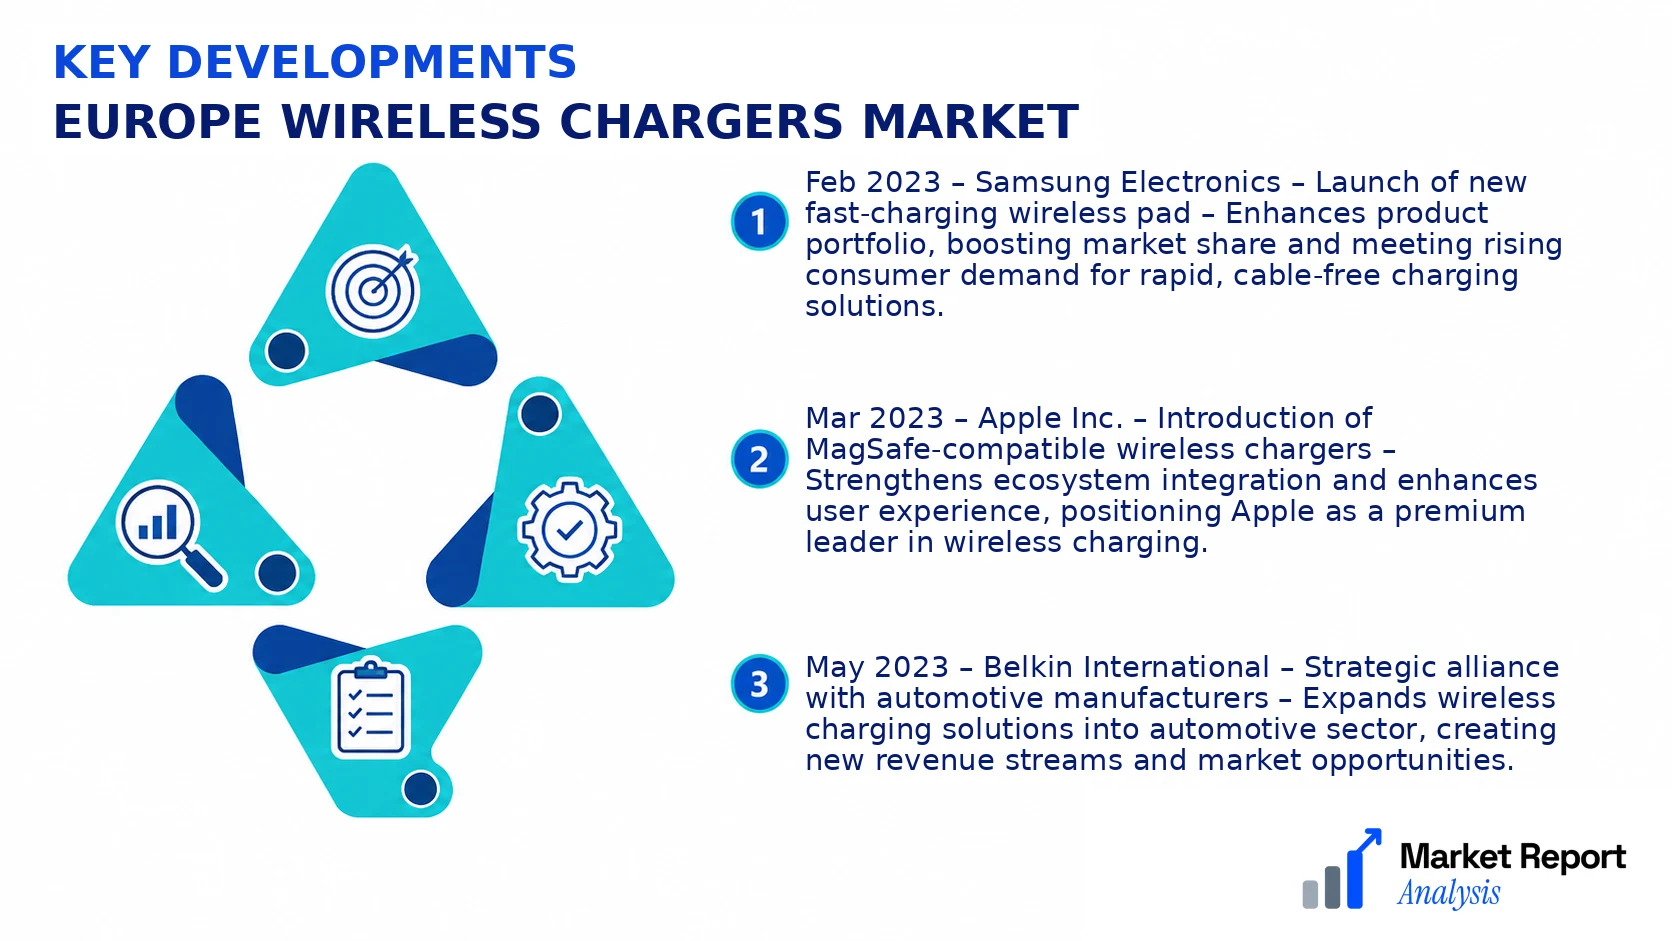
- Feb 2023 – Samsung Electronics – Launch of new fast-charging wireless pad – Enhances product portfolio, boosting market share and meeting rising consumer demand for rapid, cable-free charging solutions.
- Mar 2023 – Apple Inc. – Introduction of MagSafe-compatible wireless chargers – Strengthens ecosystem integration and enhances user experience, positioning Apple as a premium leader in wireless charging.
- May 2023 – Belkin International – Strategic alliance with automotive manufacturers – Expands wireless charging solutions into automotive sector, creating new revenue streams and market opportunities.
- Jun 2023 – Anker Innovations – Capacity expansion at European manufacturing plants – Aims to meet surging demand, reduce costs, and improve supply chain responsiveness within Europe.
- Aug 2023 – Zens – Launch of eco-friendly wireless chargers using sustainable materials – Aligns with European environmental standards and appeals to eco-conscious consumers, fostering brand loyalty and market advantage.
Frequently Asked Questions
What is the Europe Wireless Chargers Market?
The Europe Wireless Chargers Market comprises the industry involved in manufacturing, distributing, and selling wireless charging devices and accessories across European countries. It caters to the increasing demand for convenient, cable-free charging solutions for smartphones, wearables, and other portable electronics.
What is the current market size of Europe Wireless Chargers Market?
As of 2026, the market size of the Europe Wireless Chargers Market is valued at approximately USD 2.3 Billion, driven by rising adoption of wireless technology and smartphone penetration across various European nations. The market is expanding steadily due to technological advances and consumer demand.
What factors are driving the Europe Wireless Chargers Market?
Key drivers include the proliferation of smartphones and IoT devices, rapid technological advancements in wireless charging capabilities, increasing consumer preference for wireless solutions, and supportive regulatory standards. Additionally, the availability of fast-charging technologies and market expansion in retail channels boost growth.
Which region dominates the Europe Wireless Chargers Market?
Western Europe, led by Germany, the UK, and France, dominates the market due to higher consumer income levels, technological awareness, and early adoption of wireless charging devices. This region's technological infrastructure significantly supports market growth.
Which segment is expected to grow the fastest?
The consumer electronics segment, especially smartphones and wearable devices, is anticipated to exhibit the highest growth rate during 2026-2034. This segment's rapid adoption of wireless charging technology propels market expansion and product innovation.
Who are the leading companies operating in the Europe Wireless Chargers Market?
Leading companies include Samsung Electronics, Anker Innovations, Belkin International, Inc., and Mophie, which hold substantial market shares through innovative product offerings, strategic collaborations, and strong distribution channels. Their focus on R&D drives market competitiveness and growth.
Analyst Perspective
The Europe Wireless Chargers Market is positioned for sustained growth, driven by increasing adoption of wireless-enabled devices and the continuous evolution of charging technologies. Long-term market prospects appear promising, with a CAGR of approximately 12.4% from 2026 to 2034, as the region emphasizes seamless device integration and smart home connectivity. Commercial opportunities are robust in consumer electronics segments, including smartphones, wearable devices, and automotive applications, where wireless charging offers convenience and enhanced user experience. Technology advances such as fast-charging protocols, improved coil design, and energy efficiency will further catalyze market expansion. Investment priorities should focus on R&D for miniaturized, energy-efficient chargers, strategic partnerships, and expanding manufacturing capacities. Regional growth potential varies by country, with Western Europe leading due to higher device penetration, while Eastern Europe presents emerging opportunities. Competitive intensity will remain high, favoring innovation and differentiation. Long-term strategic positioning requires a balanced approach towards technological innovation, regional diversification, and robust supply chain management to capitalize on evolving consumer demands.
