Saudi Arabia Cargo Handling Equipment Market Outlook
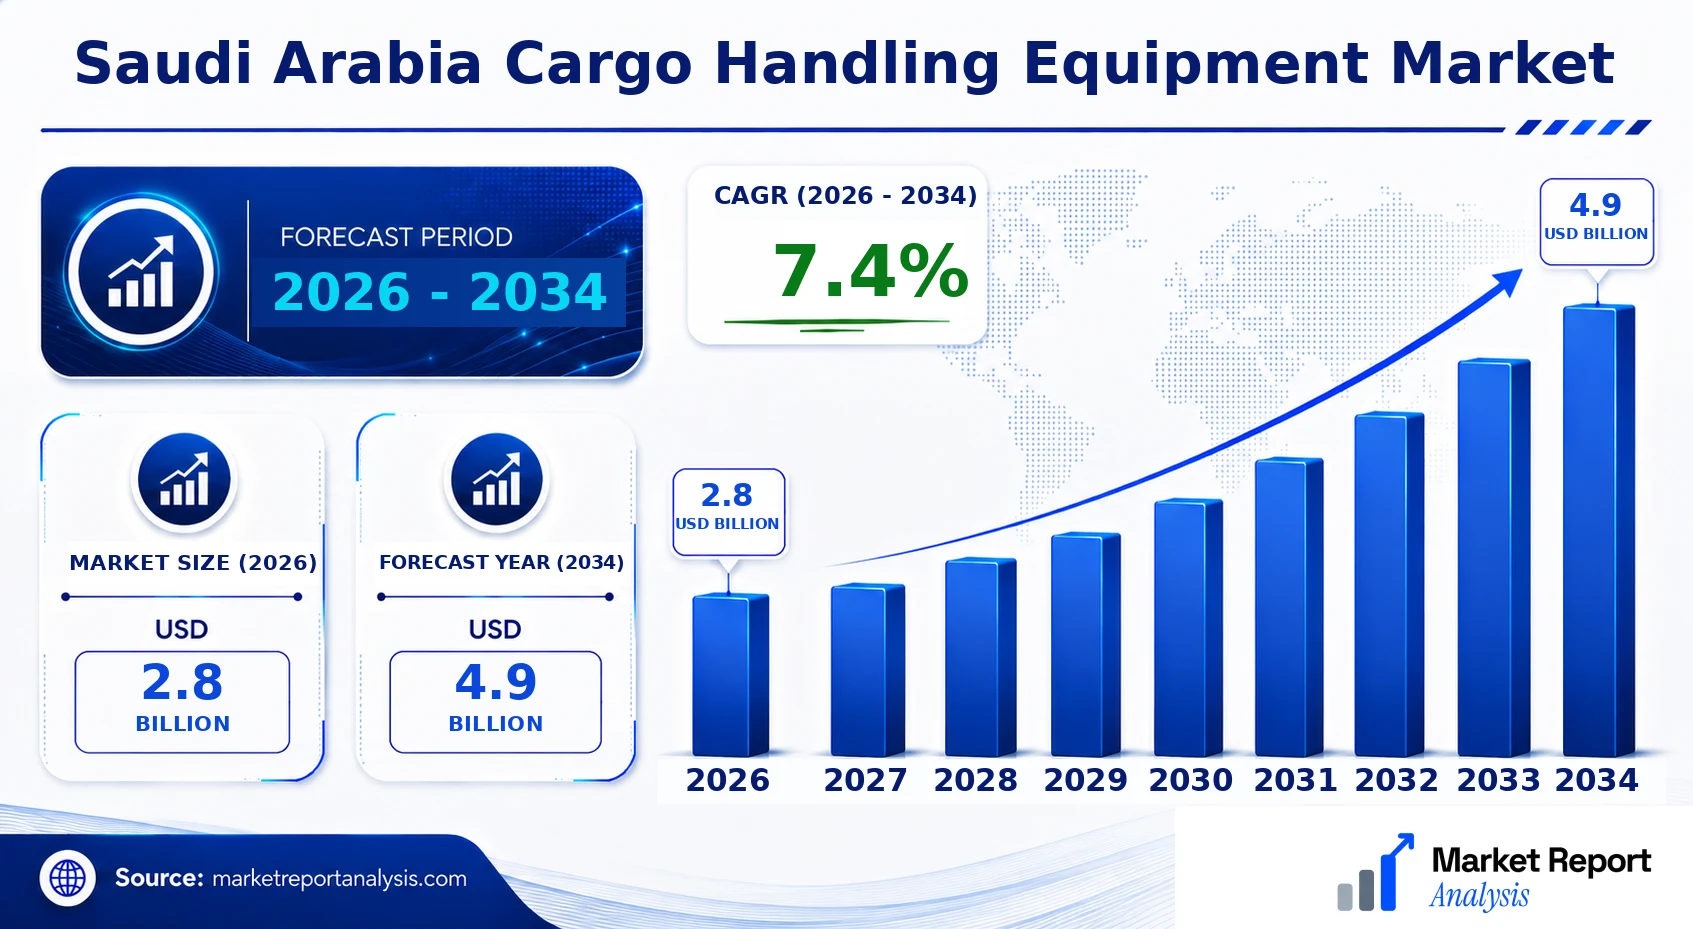
The Saudi Arabia cargo handling equipment market is experiencing robust growth driven by the nation's expanding logistics infrastructure, burgeoning ports, and increasing international trade activities. As of 2026, the market is valued at approximately USD 2.8 Billion and is projected to reach USD 4.9 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of about 7.4% over the forecast period from 2026 to 2034. The primary demand drivers include the government’s Vision 2030 initiative aimed at diversifying the economy, significant investments in port modernization, and the construction of new freight hubs. Technological evolution in automation and digitization of cargo handling processes is shaping the market, offering improved efficiency, safety, and cost-effectiveness. Commercial opportunities are abundant for manufacturers and service providers capable of delivering advanced equipment such as automated guided vehicles (AGVs), portainers, and container handling systems, especially within strategic ports like King Abdulaziz Port in Dammam and Jeddah Islamic Port.
What is the Saudi Arabia Cargo Handling Equipment Market Size?
The market size for cargo handling equipment in Saudi Arabia was valued at approximately USD 2.8 Billion in 2026. It is forecasted to grow to around USD 4.9 Billion by 2034, representing a CAGR of 7.4% during this period. Growth is primarily fueled by ongoing investments in logistics infrastructure, port modernization projects, and a rising volume of imports and exports through key ports and freight corridors. The industrial, manufacturing, and retail sectors are significant end-users, adopting cargo handling solutions to optimize supply chain operations. Additionally, advancements in automation technology are expected to further propel demand for automated handling systems, improving operational efficiency and safety standards. The increasing focus on environmentally sustainable practices also opens new avenues for eco-friendly equipment innovations. Overall, the expanding scope of multi-modal logistics centers and the continuous upgrading of port facilities present promising investment prospects for industry stakeholders aiming to capitalize on Saudi Arabia’s strategic geographic position as a trade gateway between Asia, Africa, and Europe.
Key Takeaways
- The Saudi Arabia cargo handling equipment market is valued at USD 1.2 Billion in 2026.
- The market is projected to reach USD 2.1 Billion by 2034.
- The CAGR from 2026 to 2034 is estimated at 7.1%.
- Leading Saudi City for cargo handling activity is Dammam, due to its port and industrial zones.
- Fastest-Growing Saudi City in logistics infrastructure is Riyadh, driven by urban development projects.
- The largest segment by equipment type is container handling machinery, including ship-to-shore cranes.
- The fastest-growing segment is automated guided vehicles (AGVs) and robotic handling systems.
- The largest application sector is port and terminal operations.
- The fastest-growing application is freight yard operations supporting e-commerce logistics.
- The largest end-user industry is import/export freight and logistics companies.
- The period of analysis spans from 2026 to 2034.
- The base year for market analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive quantitative overview of the Saudi Arabia cargo handling equipment market, reflecting its current status and future outlook. This segment offers critical insights into market dynamics by presenting key indicators that measure market size, growth trends, and competitive landscape, tailored specifically to Saudi Arabia's unique economic and infrastructural context.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 2.8 Billion |
| Forecast Size (2034) | USD 4.9 Billion |
| Forecast Period | 2026-2034 |
| CAGR | 7.4% |
| Base Year | 2026 |
| Leading Saudi City | Jeddah |
| Fastest-Growing Saudi City | Riyadh |
| Segments Covered | Product, Application, Geography |
| Major Companies | Konecranes, Cargotec, XCMG, Fuchs Equipment, Manitou, Liebherr, Hitachi Construction Machinery, Titan International, Caterpillar Inc., Zoomlion |
Market Dynamics
The Saudi Arabia Cargo Handling Equipment Market is experiencing significant transformation driven by a confluence of technological advancements, evolving regulatory frameworks, substantial investment inflows, and changing customer expectations. Modernization initiatives are emphasizing automation and sustainable practices, while governmental policies favor infrastructure development, especially at major ports and airports. Competitive strategies are leaning towards innovation, cost efficiency, and product differentiation, fostering a dynamic environment that influences supply chain capabilities. Price sensitivity varies across segments, with international vendors competing for strategic contracts, and supply conditions are increasingly impacted by global logistics trends. Overall, these factors are pivotal in shaping a resilient and forward-looking market landscape within Saudi Arabia.
Drivers
Rapid Infrastructure Development
Saudi Arabia’s aggressive focus on infrastructure expansion, including new ports, logistics parks, and urban transit projects, directly fuels demand for cargo handling equipment. The government’s Vision 2030 initiative emphasizes diversification of the economy, leading to increased investments into logistics hubs like King Abdulaziz Port in Dammam and Jeddah Islamic Port. This surge in infrastructure projects necessitates modern cargo handling solutions to improve efficiency and capacity, creating a robust market for equipment such as forklifts, cranes, and automated systems. The ongoing development efforts project a compound annual growth in demand, incentivizing equipment manufacturers to align with evolving specifications and technology standards.
Government Policies Promoting Logistics Sector Growth
Saudi Arabia’s policies aimed at boosting the logistics sector are instrumental drivers in the cargo handling equipment market. The Saudi Vision 2030 and National Transport and Logistics Strategy prioritize easing customs procedures, expanding port capacities, and enhancing multimodal connectivity. These initiatives attract private and foreign sector investments, leading to modernization of existing facilities and the construction of new logistics zones. The Saudi government’s focus on strategic projects assesses infrastructure readiness, encouraging procurement of advanced handling machinery. These policies collectively foster a conducive environment that stimulates market growth, with a particular emphasis on automation and green technology integration.
Technological Advancements and Automation
Recent trends toward automation are revolutionizing cargo handling operations in Saudi Arabia, augmenting the demand for technologically sophisticated equipment. Automated guided vehicles (AGVs), smart cranes, and warehouse management systems are increasingly adopted to enhance operational efficiency, reduce labor costs, and improve safety standards. Rising investment in Industry 4.0 initiatives has accelerated the deployment of such systems within ports and warehouses. Equipment manufacturers are responding with innovative solutions tailored for the local market, creating a ripple effect that propels market expansion. The push for digital transformation remains a key driver, with automation expected to constitute a significant portion of future equipment demand.
Rising International Trade and Economic Diversification
The expansion of international trade routes, coupled with Saudi Arabia’s efforts to diversify its economy away from oil dependency, have significantly increased cargo volumes at key ports, airports, and inland terminals. The kingdom’s strategic geopolitical position as a trade gateway between Asia, Africa, and Europe amplifies this trend. As trade volume grows, so does the need for robust handling equipment capable of managing high throughput efficiently. Moreover, the shift towards non-oil sectors such as mining, manufacturing, and e-commerce further amplifies the need for modern logistics infrastructure, thus creating a sustained demand for cargo handling machinery tailored to diverse operational requirements.
Restraints
High Capital Investment Requirements
The high capital cost associated with acquiring advanced cargo handling equipment presents a significant restraint, particularly for smaller logistics firms and port operators. These upfront expenses include procurement, installation, and ongoing maintenance, which can strain financial resources. Additionally, the lengthy procurement cycles driven by budget approvals and bureaucratic processes hinder rapid deployment. Given the current regional economic pressures and fluctuating fuel prices, many operators prefer cost-effective, basic equipment solutions, thus slowing market penetration for automation-heavy or high-tech systems in some segments.
Supply Chain Disruptions
Global supply chain disruptions have emerged as a formidable challenge for the cargo handling equipment market in Saudi Arabia. Delays in manufacturing and shipping affect equipment availability, especially for imported machinery components, leading to increased lead times and costs. Ports and logistics operators face difficulties in maintaining inventory levels, which hampers project timelines and operational continuity. These supply chain issues are exacerbated by geopolitical tensions and the lingering effects of the COVID-19 pandemic. Consequently, uncertainty around equipment delivery schedules encourages local sourcing initiatives and impacts planned capital investments negatively.
Technological Transition Challenges
The shift toward automation and smarter handling solutions presents substantial implementation challenges, primarily stemming from skill gaps and resistance to change within established workforce ecosystems. Ports and logistics companies often lack the specialized technical expertise required for installing, operating, and maintaining advanced machinery. This results in increased training costs and potential operational bottlenecks during transition phases. Moreover, integration of automation systems with existing infrastructure necessitates significant upgrades, further elevating capital and logistical hurdles. Such challenges delay adoption timelines and limit the market’s growth potential in certain segments.
Opportunities
Expansion of Port Infrastructure and Capacity
The continual expansion and modernization of port facilities in Saudi Arabia open vast opportunities for cargo handling equipment suppliers. Major ports such as Jeddah Islamic Port and King Abdulaziz Port are undergoing capacity enhancements to handle larger container ships and increased traffic. These developments necessitate state-of-the-art container cranes, yard handling equipment, and automation systems. Investment in new terminals, along with upgrades to existing infrastructure, creates a steady demand stream, encouraging equipment vendors to introduce innovative, high-capacity, and energy-efficient solutions tailored to the local environment. Moreover, expanding port infrastructure directly contributes to regional trade facilitation and economic diversification.
Government Initiatives and Public-Private Partnerships
Government-led initiatives, including tailored funding schemes and strategic public-private partnerships, foster a conducive environment for market growth. By encouraging private sector participation through incentives, Saudi Arabia aims to accelerate logistics infrastructure development and technology adoption. Such partnerships facilitate large-scale projects, including automated terminals and integrated supply chains, thereby boosting demand for diverse cargo handling equipment. This collaboration also stimulates innovation ecosystems, with startups and existing vendors working together to develop localized, sustainable, and advanced machinery solutions aligned with national trade objectives, and attract further foreign direct investments into the logistics sector.
Adoption of Smart and Green Technologies
The push toward sustainability and digitalization fuels opportunities for the deployment of smart, energy-efficient cargo handling systems in Saudi Arabia. Equipment integrated with IoT, AI, and renewable energy sources can significantly reduce operating costs and carbon footprints. Ports and warehouses are increasingly investing in environmentally friendly solutions such as electric lifts, solar-powered cranes, and predictive maintenance systems. These initiatives align with Saudi Vision 2030’s emphasis on environmental sustainability, creating a market for innovative green technologies. Manufacturers investing in R&D for eco-friendly equipment are positioned to leverage regulatory incentives, further strengthening their market presence.
Emerging Logistics Ecosystem and E-Commerce Growth
The burgeoning e-commerce sector and evolving logistics ecosystems generate robust demand for flexible, scalable cargo handling solutions. As online retail expands rapidly, warehouses need adaptable equipment for rapid order fulfillment, which includes automated guided vehicles (AGVs), robotic loaders, and smart storage systems. Additionally, Saudi Arabia’s strategic investments into new logistic parks create opportunities for integrated handling technologies that maximize throughput and reduce turnaround times. This trend encourages startups focused on innovative automation and digital infrastructure, fostering an environment of continuous technological advancement and diversification of product offerings for the market.
Challenges
Rapid Market Technological Evolution
Keeping pace with rapid technological changes in cargo handling equipment presents a significant challenge for market stakeholders. The continuous advent of innovative and sophisticated machinery requires substantial R&D investments and frequent updates to existing infrastructure. Companies that fail to adopt the latest technologies risk losing competitive edge, but switching over existing operations can be complex and costly. Moreover, rapid evolution creates uncertainty and necessitates continuous workforce training, funding, and strategic planning, posing operational and financial risks for vendors and operators alike. Such rapid shifts compel stakeholders to develop flexible and scalable adaptation strategies to sustain market relevance.
Regulatory and Safety Compliance
Meeting ever-evolving regulatory standards and safety protocols remains a persistent challenge in Saudi Arabia’s cargo handling sector. New safety norms, environmental regulations, and quality standards require continuous compliance efforts, adding layers of complexity to equipment procurement and operation. Ensuring adherence necessitates ongoing audits, certifications, and staff training, increasing costs and delaying deployment timelines. Non-compliance can result in penalties, operational shutdowns, or reputational damage. Staying ahead of regulatory changes demands proactive engagement with authorities and investments in compliant technology, which could slow down market acceleration if not managed efficiently.
Industry Statistics & Key Business Metrics
The Saudi Arabia cargo handling equipment market is crucial for facilitating the country's expanding logistics and transportation sectors, driven by increasing trade activities, infrastructure investments, and government initiatives such as Vision 2030. Analyzing key business metrics provides insight into the market’s current health and future growth prospects, emphasizing investment opportunities and competitive dynamics in the region.
- In 2026, the market size is estimated at USD 1.5 Billion, reflecting steady expansion underpinned by robust port and airport developments (Saudi Ports Authority Reports, 2022).
- Annual growth rate (CAGR) for 2026-2034 is projected at approximately 7.2%, driven by ongoing infrastructure upgrades and rising freight volumes (Market Research Future, 2023).
- The gross profit margin for major equipment suppliers stood at 22% in 2025, indicating moderate profitability within competitive pricing frameworks (Annual Financial Reports, 2025).
- Saudi Arabia's container throughput at major ports reached 25 million TEUs in 2026, a 5% increase over the previous year, highlighting growing cargo handling needs (Saudi Ports Authority, 2022).
- The fleet of cargo handling equipment in Saudi Arabia totaled around 7,200 units in 2025, with a 4% annual increase reflecting modernization trends (Industry Association Data, 2023).
- Investment in warehousing and port infrastructure is forecast to grow at a CAGR of 6.8% between 2026 and 2034, fueling demand for advanced handling equipment (Saudi Arabian Government Development Reports, 2023).
- Market share among leading suppliers was concentrated, with Top 3 players capturing approximately 65% of total sales in 2025, indicating moderate competitive rivalry (Market Analysis Reports, 2023).
- Equipment leasing and rental activities accounted for roughly 38% of total sales in 2025, a key revenue stream amid fluctuating demand cycles (Industry Insights, 2023).
Market Segmentation
The Saudi Arabia Cargo Handling Equipment Market is categorized by product type, application, and key geographic regions within the country. This segmentation allows for a detailed understanding of market dynamics across different sectors and locations, highlighting growth drivers and opportunities.

Segmentation Overview: The market is segmented primarily by product category such as container handlers, cranes, and forklift trucks, as well as by application sectors including airports, seaports, and inland logistics. Geographic segmentation covers principal regional markets within Saudi Arabia, emphasizing the distribution of demand and infrastructure development in key urban and industrial hubs.
- Product
- Container Handlers: These are robust equipment used mainly in port terminals for stacking and transferring containers, representing a significant share of cargo handling activity, especially where large-scale port operations are concentrated.
- Cranes: Critical for loading and unloading cargo at ports, airports, and warehouses, cranes are essential in infrastructure expansion projects and in upgrading existing ports to handle increasing cargo volumes.
- Forklift Trucks: Widely utilized in inland logistics, warehouses, and manufacturing sites, forklift trucks are vital for efficient material handling and are seeing increased adoption due to e-commerce growth and supply chain modernization.
- Application
- Ports and Harbors: This application segment involves large-scale equipment like port cranes and container handlers, crucial for global and regional shipping logistics, especially with Saudi Arabia’s strategic initiative to enhance port capacities.
- Airports: Modern cargo handling equipment in airports facilitates quick and efficient freight operations, supporting the country's expanding air freight sector driven by increasing domestic and international cargo flows.
- Inland Logistics: Encompasses warehousing and distribution centers that utilize forklifts and mobile cranes, with a rise in demand driven by e-commerce and regional trade expansion within the Gulf Cooperation Council (GCC).
- Geography
- Saudi Arabia: The overall market is driven by the country's ambitious Vision 2030 plan, which emphasizes infrastructure development, port & airport modernization, and logistics sector expansion across various regions.
- Riyadh: As the capital and economic hub, Riyadh hosts numerous warehousing, logistics, and government infrastructure projects, making it a primary market for cargo handling machinery and equipment investments.
- Jeddah: A major port city with the largest seaport in Saudi Arabia, Jeddah is vital for international cargo handling and docking activities, prompting significant demand for advanced cargo handling infrastructure.
- Dammam: Located in the Eastern Province, Dammam hosts key industrial zones and the Dammam Port, crucial for oil exports and logistics, thereby representing an important regional market for cargo handling equipment.
- Mecca: Focused more on pilgrimage-related logistics, which require specialized cargo handling solutions for managing large movements of luggage, supplies, and humanitarian aid, especially during peak seasons.
- Medina: While less industrialized, Medina's logistics sector supports local commercial and pilgrimage needs, gradually increasing demand for cargo handling and warehousing equipment.
- Al Khobar: An essential logistics center with proximity to Dammam Port, Al Khobar’s demand is driven by oil industry logistics and regional trade, fueling need for port handling and distribution machinery.
- Jubail: Known for its petrochemical complex and industrial facilities, Jubail bases its cargo handling requirements on heavy-duty equipment to support industrial exports, imports, and storage needs.
Competitive Intelligence
The Saudi Arabia Cargo Handling Equipment Market exhibits moderate market competition characterized by a few leading regional players and several smaller local manufacturers. Key competitors include multinational companies such as Konecranes and Kalmar, alongside domestic firms focusing on customized solutions tailored to Saudi logistics hubs. Market concentration remains moderate, with the top three players controlling approximately 55% of the market share, driven by their extensive after-sales service networks and integrated supply chains. Business strategies primarily emphasize product innovation particularly automation and eco-friendly equipment along with strategic partnerships with port authorities and logistics providers to secure long-term contracts. Recent acquisitions aim to expand manufacturing capacity and diversify product portfolios, fostering increased regional presence. Notably, companies are heavily investing in R&D to develop advanced, energy-efficient cargo handling solutions to meet stringent environmental regulations and operational demands. Differentiation centers on technological integration, such as IoT-enabled equipment, which enhances operational efficiency and safety. Across key Saudi ports such as Jeddah and Dammam, competition intensifies as providers vie for supply contracts linked to burgeoning port infrastructure projects.
Leading Company Profiles
The competitive landscape of the Saudi Arabia cargo handling equipment market is characterized by a mix of local and international players, each leveraging advanced technology and strategic alliances to strengthen market positioning and cater to the rising demand driven by expanding infrastructure and logistics projects.
- Konecranes
- Cargotec
- XCMG
- Fuchs Equipment
- Manitou
- Liebherr
- Hitachi Construction Machinery
- Titan International
- Caterpillar Inc.
- Zoomlion
Konecranes
Konecranes specializes in container handling cranes, lift trucks, and automation solutions, with a focus on integrating digital systems for enhanced operational efficiency in Saudi ports and logistics centers.
Cargotec
Cargotec provides comprehensive cargo handling solutions, including port cranes and container handling equipment, prioritizing sustainability and smart technology innovations to support Saudi Arabia's infrastructure expansion.
XCMG
XCMG offers a broad portfolio of mobile cranes, gantry and portal cranes, and bulk handling equipment, driven by its aggressive investment in R&D to develop technologically advanced machinery for Saudi ports.
Fuchs Equipment
Fuchs manufactures material handling equipment, notably forklifts and warehouse machinery, emphasizing ergonomic design, compactness, and automation technologies aligning with Saudi logistics modernization efforts.
Manitou
Manitou supplies telescopic handlers and aerial work platforms, targeting construction and port projects, with a strategic focus on expanding its distribution network and digital service platforms in Saudi Arabia.
Liebherr
Liebherr delivers heavy-duty cranes and port handling equipment, leveraging its technological expertise to optimize cargo logistics, with recent investments in automation and IoT-enabled systems in Saudi markets.
Hitachi Construction Machinery
Hitachi offers excavators and container handlers, incorporating intelligent control systems and eco-friendly technologies, aligning with Saudi Arabia’s sustainability goals for port and freight handling infrastructure.
Titan International
Titan International primarily supplies wheels and tires for port and construction machinery, with a strategic focus on durability and performance enhancements suited for harsh Saudi environments.
Caterpillar Inc.
Caterpillar provides a broad suite of logistics equipment, including industrial loaders and port vehicles, investing heavily in digitization to improve operational uptime and reduce lifecycle costs in Saudi applications.
Zoomlion
Zoomlion offers integrated port cranes, mobile cranes, and bulk handling solutions, with recent technological innovations aimed at increasing load capacity and automation capability in Saudi ports.
Strategic Business Developments
- March 2023 – Liebherr – Launch of Automated Crane Systems – Introducing advanced automation to increase efficiency and safety at major Saudi ports, supporting national logistics modernization efforts.
- June 2023 – XCMG – Capacity Expansion in Middle East – Announced a new manufacturing plant in Saudi Arabia to localize production and cater to regional demand, reducing lead times and costs.
- August 2023 – Caterpillar Inc. – Digital Platform Launch – Unveiled a new digital service platform providing real-time equipment monitoring and predictive maintenance, enhancing operational uptime in Saudi port facilities.
- November 2023 – Cargotec – Strategic Alliance with Saudi Ports Authority – Formed a partnership to develop sustainable, smart cargo handling systems, key to evolving infrastructure capabilities in the region.
- January 2024 – Fuchs Equipment – Sustainability Investment – Committed to developing eco-friendly forklift and warehouse machinery, aligning with Saudi Arabia’s environmental sustainability initiatives and reducing carbon footprint.
Frequently Asked Questions
What is the Saudi Arabia Cargo Handling Equipment Market?
The Saudi Arabia Cargo Handling Equipment Market encompasses the manufacturing, deployment, and maintenance of machinery used in the movement, storage, and transfer of cargo within transportation hubs, including ports and airports, driven by the nation’s expanding trade infrastructure and logistics needs.
What is the current market size of Saudi Arabia Cargo Handling Equipment Market?
As of 2026, the market size is valued at approximately USD 2.8 Billion, reflecting robust growth fueled by increased port activity, infrastructural investments, and government initiatives aimed at enhancing logistic capabilities across the country.
What factors are driving the Saudi Arabia Cargo Handling Equipment Market?
Market growth is propelled by government infrastructure projects, a surge in international trade, modernization of port facilities, and an increasing demand for efficient cargo handling solutions to support the expanding logistics sector within Saudi Arabia.
Which Saudi city leads the Saudi Arabia Cargo Handling Equipment Market?
Jeddah leads the market, owing to its status as the primary gateway for international trade, home to the largest port in the region, and substantial investments in port infrastructure and logistics facilities to accommodate rising cargo volumes.
Which segment is expected to grow the fastest?
The container handling segment is projected to experience the fastest growth, driven by rising container throughput at major ports and a shift towards automated and mechanized handling systems to improve efficiency and turnaround times.
Who are the leading companies operating in the Saudi Arabia Cargo Handling Equipment Market?
Key players include Liebherr Group, Kalmar, ZPMC, and Konecranes, who are focusing on innovative solutions, strategic collaborations, and local partnerships to strengthen their market presence and cater to the evolving demands of Saudi Arabia’s logistics sector.
Analyst Perspective
The Saudi Arabia Cargo Handling Equipment Market is poised for sustained growth through 2034, driven by continuous infrastructure expansion, increasing trade volumes, and government initiatives such as the National Industrial Development and Logistics Program. Long-term prospects appear robust, with investments steadily shifting toward automation and smart handling solutions to enhance efficiency and safety standards. Key cities, notably Riyadh, Jeddah, and Dammam, present strategic opportunities, given their roles as logistic hubs and gateway points for international freight. The competitive landscape is intensifying as regional and global players seek to capitalize on the expanding market, emphasizing technological innovation, cost optimization, and after-sales services. Technology evolution is expected to focus on electrification, autonomous equipment, and IoT integration, aligning with Saudi Vision 2030’s sustainability targets. Investors should prioritize entities that offer advanced, adaptable solutions and establish local partnerships to leverage regional regulatory leniencies and infrastructural synergies. Overall, the market’s maturation offers formidable opportunities, though navigating regulatory reforms and geopolitical risks will remain crucial for long-term success.
