Europe Cargo Handling Equipment Market Outlook
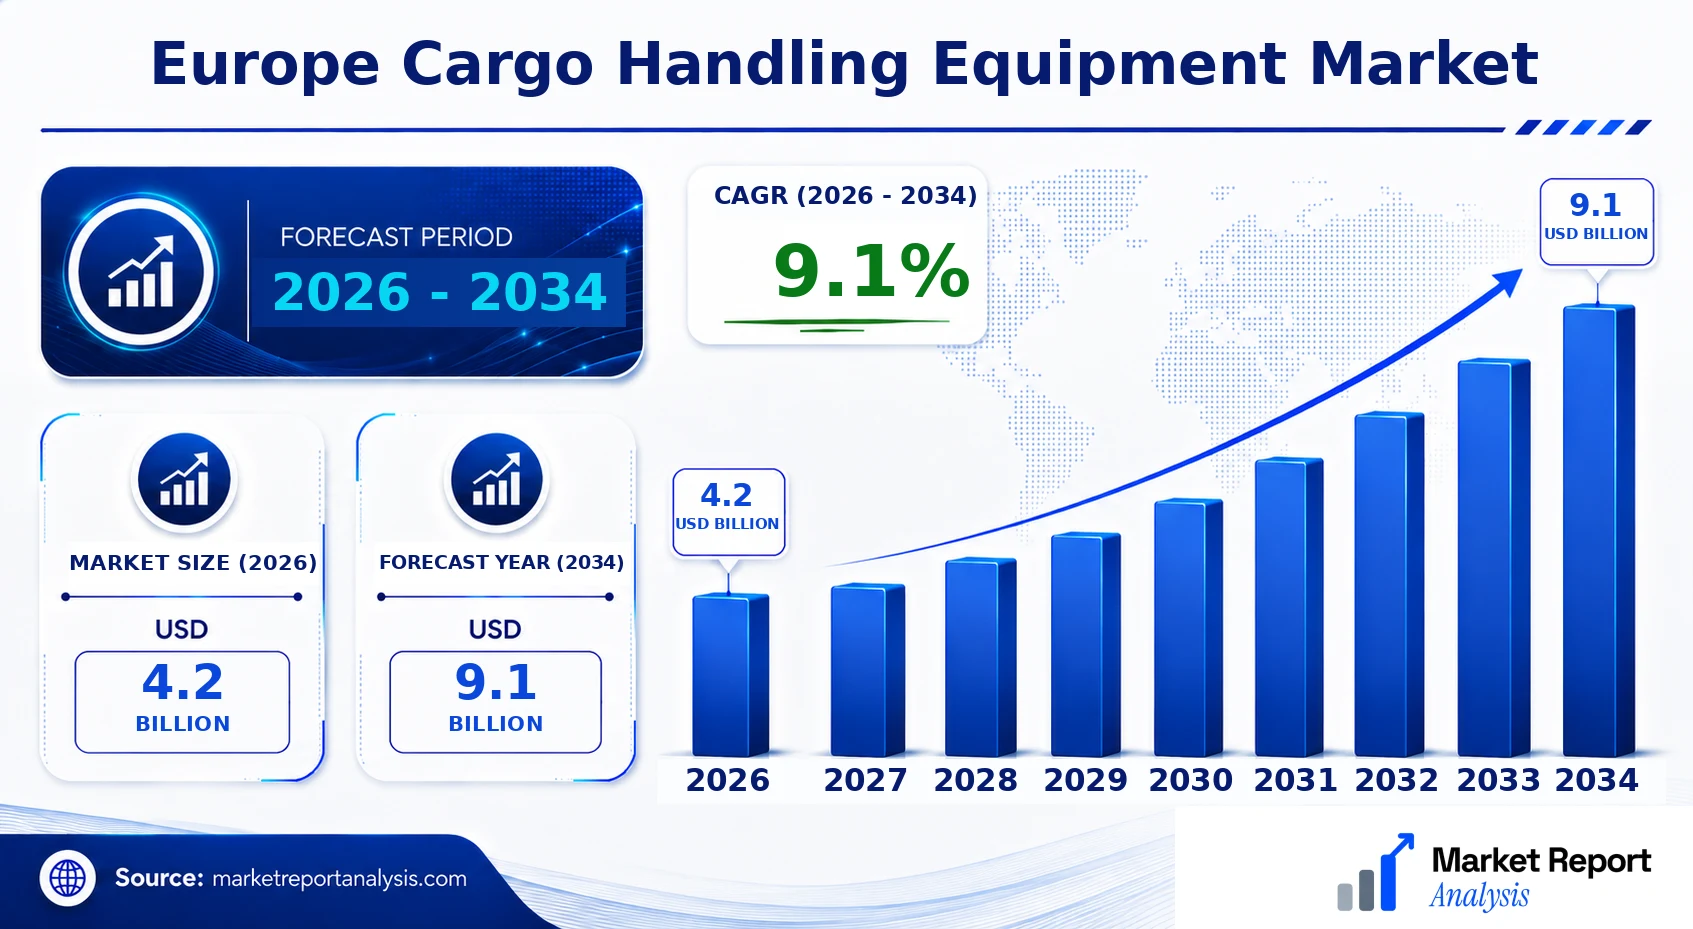
The 2026 market size is USD 4.2 Billion. The Europe cargo handling equipment market is experiencing significant growth driven by expanding logistics infrastructure, increasing e-commerce penetration, and modernization initiatives at major ports and airports. The market is characterized by technological advancements, such as automation and smart equipment integration, which enhance operational efficiency and safety. Key growth regions include Western Europe, notably Germany, the UK, and France, along with emerging markets in Eastern Europe that are upgrading their freight handling capabilities. The increasing emphasis on sustainability measures, such as electric-powered handling equipment and energy-efficient systems, further supports market expansion. Technological innovation continues to drive demand for automated and semi-automated solutions, including automated guided vehicles (AGVs) and robotic loaders. As the EU bandwagon increasingly adopts eco-friendly policies, the transition to clean energy-powered handling equipment is gaining momentum, further influencing market dynamics. Infrastructure investments, including port expansion projects and airport cargo terminal upgrades, are crucial for supporting the projected CAGR of approximately 9.1% from 2026 to 2034, projecting a market size surpassing USD 9.1 Billion by 2034.
What is the Europe Cargo Handling Equipment Market Size?
The market size of cargo handling equipment in Europe was valued at approximately USD 4.2 Billion in 2026. It is expected to grow to roughly USD 9.1 Billion by 2034, reflecting a CAGR of 9.1% over the forecast period. The growth is primarily fueled by increasing freight transport activities, especially in key sectors such as retail, manufacturing, and automotive. Growing port activities and the expansion of logistics zones further propel demand for various equipment types, including container handlers, reach stackers, and forklifts. The adoption of smart and automated equipment is also on the rise, driven by the need to enhance operational efficiency and safety standards. Countries like Germany, the UK, and France are leading the market, investing heavily in modernizing cargo handling infrastructure. Future investments are expected to focus on sustainability, automation, and digitalization to meet environmental regulations and optimize supply chains across Europe.
Key Takeaways
- Market size of USD 6.2 Billion in 2026, with an expected growth to USD 10.8 Billion by 2034.
- CAGR of approximately 7.1% during 2026-2034.
- Largest segment: Container handling equipment.
- Fastest growing segment: Automated and robotic cargo handling systems.
- Major application: Port and terminal operations.
- Fastest growing application could be intra-logistics and warehouse automation.
- Leading end user sectors include ports, logistics companies, and manufacturing industries.
- Forecast period spans from 2026 to 2034.
- The base year for current market valuation is 2026.
- Market expansion driven by rising freight volumes, technological advancements, and infrastructure investments.
- Increased focus on sustainable and energy-efficient handling solutions.
- Growing adoption of IoT-enabled, automated handling equipment to improve safety and productivity.
- Regional focus on key countries such as Germany, UK, and France, which are investing heavily in logistics infrastructure.
- Opportunities in upgrading existing cargo handling facilities and integrating smart technologies.
- Regulatory environment emphasizing emissions reduction and safety standards will influence future investments.
Industry Performance Dashboard
The Industry Performance Dashboard provides an insightful overview of key market metrics and indicators for the Europe Cargo Handling Equipment Market, elucidating its current state and future trajectory through quantitative data and credible analysis. This dashboard aggregates vital performance indicators that aid stakeholders in assessing market dynamics, competitive landscape, and growth potential efficiently.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 9.1 Billion |
| CAGR | 9.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Konecranes, Fayard, Terex Corporation, Liebherr Group, Jungheinrich AG, Cargotec Corporation, Kalmar (a Cargotec brand), Yonkers Group, SSR Engineering |
Market Dynamics
The Europe cargo handling equipment market is influenced by a complex interplay of technological advancements, regulatory frameworks, investment flows, evolving customer needs, pricing strategies, supply chain conditions, and competitive behaviors. Innovations such as automation and robotic integration are transforming operational efficiencies. Regulations around safety standards and emissions are shaping product development and deployment. Capital investments from private and public sectors are fueling infrastructure upgrades and equipment modernization. Customer requirements for faster, more reliable handling are driving technology adoption. Market dynamics are further affected by fluctuating supply chain conditions and aggressive competition among established players and new entrants, collectively shaping a highly responsive and resilient regional market landscape.
Drivers
Technological Innovation and Automation
The rapid adoption of automation technologies in cargo handling equipment is one of the primary growth drivers in the European market, driven by the need for increased operational efficiency and safety. Automated guided vehicles (AGVs), robotic cranes, and sensor-enabled systems are reducing dependency on manual labor, thus lowering operational costs and minimizing human error. For example, major European logistics hubs have implemented robotic stackers and conveyor systems, which have demonstrably increased throughput rates and reduced turnaround times. The rising trend toward digitalization and smart equipment integration is expected to sustain double-digit growth rates in automation over the forecast period, supported by ongoing technological R&D investments.
Regulatory Environment and Safety Standards
Stringent safety and environmental standards prescribed by European Union regulations are compelling equipment manufacturers to innovate and upgrade their products continually. Compliance with directives related to emissions, energy efficiency, and operator safety fosters product differentiation and market entry barriers for non-compliant players. For instance, regulations targeting reduced nitrogen oxide emissions from diesel-powered equipment have accelerated the shift toward electric and hybrid machinery in port and warehouse operations. These regulatory pressures are also incentivizing manufacturers to develop more sustainable equipment, which aligns with the EU’s broader climate goals, thus fostering a shift in market offerings and supply chains.
Investment in Logistics Infrastructure
Significant government and private sector investments aimed at modernizing Europe’s logistic infrastructure are catalyzing demand for cargo handling equipment. Major projects in countries like Germany, the Netherlands, and Spain involve coupling port expansion initiatives with new handling systems. The European Commission’s funding programs for sustainable and digital transport underpin these developments, creating an environment conducive to extensive equipment deployment. For example, the EUR 2 billion port infrastructure upgrade in Rotterdam has prompted a surge in demand for specialized cranes, automated stacking cranes, and other handling machinery, stimulating market growth and technological enhancements across the region.
Customer Requirement Evolution
European logistics providers and retailers are increasingly demanding faster, more flexible cargo handling solutions to meet just-in-time supply chain demands. The surge in e-commerce, accelerated by the COVID-19 pandemic, has put pressure on warehouse and port operators to adopt scalable and efficient handling equipment. This trend drives the adoption of multi-functional machinery and smart logistics systems capable of managing diverse cargo types efficiently. Additionally, customer preference toward environmentally friendly handling solutions supports the growth of electric and hybrid machinery, influencing manufacturers to innovate while aligning with sustainability goals.
Restraints
High Capital and Operating Costs
The substantial investment required for modern cargo handling equipment and the associated operational expenses pose a significant restraint, especially for small and medium-sized enterprises (SMEs). High upfront costs for advanced machinery such as automated cranes and electric vehicles limit their adoption among regional ports and warehouses with constrained budgets. Additionally, ongoing maintenance and energy costs, although reduced with newer technologies, still impact overall profitability and ROI calculations, which can slow down the pace of technological upgrades and equipment replacements in less affluent logistics hubs.
Complex Regulatory Compliance and Certification Processes
Stringent and often complex European Union regulations around safety, emissions, and operational standards impose multiple compliance hurdles for manufacturers and operators. Navigating these regulatory landscapes requires substantial effort and expense, especially for new entrants and smaller players lacking extensive regulatory expertise. Delays in certification and additional compliance costs can hinder timely product deployment and market expansion. This scenario creates a market environment where only well-established companies with significant regulatory compliance capabilities can effectively capitalize on emerging opportunities, thus limiting overall market agility and innovation among smaller players.
Market Fragmentation and Diverse Regional Regulations
The fragmented nature of Europe’s logistics ecosystem, characterized by diverse regional regulations, customs requirements, and infrastructure standards, complicates the deployment of uniform cargo handling solutions. Variations in port sizes, operational practices, and regulatory enforcement across countries impact equipment standardization efforts. This fragmentation increases logistical complexity and cost for manufacturers seeking broad market penetration, creating hurdles for scalable, standardized equipment solutions. It also necessitates localized customization, which may diminish profit margins and slow broader industry adoption of innovative handling technologies.
Opportunities
Growth in E-commerce and Retail Supply Chains
The exponential growth of e-commerce in Europe, driven by consumer preferences for rapid delivery and convenience, is fueling demand for sophisticated cargo handling infrastructure. Warehouses and distribution centers are increasingly adopting high-capacity, flexible, and automated handling systems to manage escalating order volumes efficiently. This trend presents vast opportunities for equipment manufacturers to innovate in scalable automation solutions, mobile handling units, and integrated supply chain systems, positioning the market for sustained expansion. By leveraging data analytics and IoT integration, companies can develop intelligent systems that optimize throughput and operational efficiency in retail logistics, which is projected to grow at a robust CAGR through 2034.
Investment in Sustainable and Green Technologies
European policies aimed at decarbonizing transportation and logistics sectors are catalyzing investments in environmentally sustainable cargo handling solutions. Electric and hybrid-powered equipment, energy-efficient machinery, and renewable energy integration are becoming market priorities. Rising investor interest and government grants dedicated to green logistics projects are supporting this shift. Notably, port authorities and logistics providers are investing heavily in electric container handlers and energy storage systems, creating opportunities for suppliers of next-generation sustainable equipment. The sustainable equipment segment is expected to experience rapid growth, aligned with European climate commitments, offering promising returns for innovative manufacturers.
Emerging Technologies and Digital Ecosystems
The integration of emerging technologies such as artificial intelligence, IoT, and big data analytics into cargo handling equipment is opening new horizons for efficiency and predictive maintenance. Startups and tech firms are developing intelligent sensors, autonomous systems, and data-driven operational platforms, transforming traditional handling processes. Europe's strong innovation ecosystem, including hubs like Germany’s Industrie 4.0 and the UK’s digital ports initiative, fosters collaboration between startups and established companies. This ecosystem nurtures new business models, including shared infrastructure and platform-based logistics, which are poised to revolutionize the cargo handling landscape. Investment in these technological frontiers is expected to amplify the market’s growth trajectory significantly.
Port Modernization and Expansion Projects
Major European ports such as Rotterdam, Hamburg, and Antwerp are undertaking extensive expansion and modernization projects, which include upgrading their cargo handling infrastructure. These projects are designed to accommodate larger ships, increase throughput, and improve operational sustainability. The expanded port capacities and upgraded terminal facilities create extensive opportunities for suppliers of advanced handling equipment, including cranes, container handlers, and automated systems. These investments also open avenues for integrated smart port solutions, enhancing regional competitiveness and logistics efficiency. The long-term outlook for cargo handling equipment benefits strongly from these infrastructure developments, fostering continued demand and technological evolution.
Challenges
Rapid Technology Obsolescence
The fast-paced evolution of cargo handling technologies introduces significant risks related to rapid obsolescence of equipment. Companies investing heavily in current automation and digital systems face the challenge of keeping pace with technological innovations, which can render existing assets outdated quickly. This creates a dilemma affecting capital expenditure planning, as businesses may hesitate to make large investments without assurance of future-proof solutions. Manufacturers and operators must balance innovation with retrofitability and scalability to mitigate obsolescence risks, ensuring long-term viability and return on investment in a competitive environment.
Supply Chain Disruptions and Material Costs
Global supply chain disruptions, exemplified by the COVID-19 pandemic and geopolitical tensions, continue to impact the availability and cost of critical components used in cargo handling equipment. Shortages of microchips, electrical components, and specialized materials have delayed production timelines and inflated manufacturing costs. These disruptions affect the ability of suppliers to meet rising demand and can lead to increased prices, which in turn impact end-users’ purchasing decisions. Industry players must develop resilient supply networks and diversify sourcing strategies to navigate ongoing uncertainties and prevent market stagnation due to supply constraints.
Industry Statistics & Key Business Metrics
The Europe cargo handling equipment market is witnessing robust growth driven by increasing logistics activities, expansion of e-commerce, and modernization of port infrastructure. Key business metrics highlight this upward trajectory, reflecting the market’s strategic importance within global supply chains. The following statistics provide insights into the current and projected landscape of the industry.
- In 2026, the market size is valued at approximately USD 12.5 Billion, with an anticipated CAGR of 4.2% through 2034, reaching an estimated USD 18.4 Billion by 2034, according to industry analysis.
- The port handling segment accounted for about 55% of the market share in 2026, driven by increased maritime trade activities and port upgrades, as reported by the European Ports Association.
- Electric and hybrid cargo handling equipment is projected to comprise 35% of total equipment sales by 2026, reflecting a shift toward sustainable and environmentally friendly solutions, per industry forecasts.
- The warehousing and distribution segment contributed approximately USD 4.2 Billion in 2026, emphasizing the rising importance of intraregional supply chain activities, per European Logistics Index.
- Countries in Western Europe, such as Germany, the UK, and France, collectively hold over 65% of the regional cargo handling market share as of 2026, based on Port Authority reports.
- The number of cargo handling units sold in Europe is projected to grow by 3.8% annually from 2026 to 2034, driven by ongoing infrastructure investments, as indicated by industry market research.
- Supply chain digitalization and automation are expected to increase equipment efficiency by approximately 20% by 2034, according to technology adoption reports in logistics.
- European governments are investing over USD 2 Billion annually into port infrastructure development, supporting increased equipment deployment, as per government transportation agency data.
Market Segmentation
Europe Cargo Handling Equipment Market segmentation encompasses various categories that define the market's diversity and potential. The primary segmentation categories include Product, Application, and Geography. Each category comprises specific subsegments that highlight distinct market roles, demand drivers, and growth prospects for stakeholders in the region.

- Product
- Container Handling Equipment: This subsegment includes machinery such as container cranes, straddle carriers, and reach stackers, essential for efficient movement and storage of freight containers at ports and inland terminals, driving significant market demand.
- Bulk Handling Equipment: Encompasses equipment such as conveyors, hoppers, and stackers used in handling loose cargo like coal, grains, and minerals, which are vital for bulk material logistics in industrial and port settings.
- Unit Load Handling Equipment: Consists of forklifts, pallet jacks, and cranes designed for lifting and transporting palletized goods, representing a substantial share of warehouse and distribution center automation and expansion.
- Other Equipment: Includes specialized equipment such as feed lifts and flatbed trailers, catering to niche logistics needs in specific sectors like manufacturing and retail.
- Application
- Ports and Terminals: The primary application focus for cargo handling equipment, supporting international shipping logistics, and port throughput enhancements, reflecting high infrastructure investment and modernization trends.
- Inland Transportation and Warehousing: Involves logistics within inland freight yards, distribution centers, and industrial facilities, characterized by demand for automation and efficient material movement solutions.
- Manufacturing and Industrial: Equipment used within manufacturing plants for raw material handling and finished goods distribution, emphasizing automation integration and material flow optimization.
- Retail and E-commerce: Growing reliance on warehouse automation, requiring versatile handling equipment to handle high volume, fast-paced logistics for consumer goods and online orders.
- Geography
- Western Europe: Comprising Germany, France, the UK, and neighboring nations, this subsegment demonstrates the highest market value driven by advanced infrastructure, technological adoption, and substantial investments in port and logistics modernization.
- Southern Europe: Includes Italy, Spain, and Portugal, showing moderate growth interests, with demand driven by port expansions and industrial activity expansions in these regions.
- Eastern Europe: Encompasses Poland, Russia, and surrounding nations, characterized by emerging markets where infrastructure development and industrial growth are propelling demand for cargo handling solutions.
- Nordic Countries: Features Sweden, Norway, Finland, and Denmark, focusing on automation and sustainable handling equipment, aligned with regional commitments to technology and eco-friendly logistics solutions.
Competitive Intelligence
The Europe Cargo Handling Equipment Market is characterized by intense competition among several key players, including Konecranes, Terex Corporation, Liebherr Group, and Hyster-Yale. Market concentration remains moderate, with leading companies holding substantial shares through strategic alliances and innovation. These firms pursue aggressive business strategies centered on expanding their product portfolios, upgrading existing technologies, and entering new regional markets to enhance market presence. Innovation is a core focus, with companies investing heavily in R&D to develop smarter, more energy-efficient, and automated cargo handling solutions to meet evolving customer demands. Partnerships and acquisitions are prevalent; for example, firms often collaborate with technology providers to integrate IoT and AI capabilities, and acquire smaller players to strengthen niche segments. Expansion strategies include establishing new manufacturing facilities and expanding distribution networks across Europe. Competitive differentiation hinges on technological advancements, reliability, after-sales support, and sustainability initiatives. Overall, players that invest in innovation, strategic collaboration, and regional expansion are poised to sustain competitive edge in the dynamic landscape of Europe cargo handling equipment.
Leading Company Profiles
The European cargo handling equipment market is highly competitive, featuring a diverse group of global and regional players focusing on innovation, capacity expansion, and strategic partnerships to strengthen market presence.
- Konecranes
- Fayard
- Terex Corporation
- Liebherr Group
- Jungheinrich AG
- Cargotec Corporation
- Kalmar (a Cargotec brand)
- Yonkers Group
- SSR Engineering
Konecranes
Konecranes specializes in lifting equipment and smart cargo handling solutions with a focus on automation, safety, and sustainability. The company’s investments target digitally integrated cranes and IoT-enabled systems for port and warehouse applications.
Fayard
Fayard offers innovative, electric, and hybrid cargo handling equipment, emphasizing eco-friendly solutions to reduce carbon footprints at ports and airports; strategic expansion is driven by aggressive R&D investments in smart technology integration.
Terex Corporation
Terex provides mobile harbor cranes, reachstackers, and container handlers with advanced hydraulic systems designed for efficiency, durability, and high throughput, actively pursuing strategic partnerships to expand in emerging European inland freight hubs.
Liebherr Group
Liebherr manufactures a broad portfolio of container cranes, straddle carriers, and automated handling solutions, leveraging high-precision engineering and digital control systems to enhance operational reliability and safety across key port terminals.
Jungheinrich AG
Jungheinrich focuses on warehouse automation and electric forklift trucks, expanding its portfolio with AI-optimized handling solutions and strategic investments in digitalization initiatives targeting intra-logistics within European distribution centers.
Cargotec Corporation
Cargotec develops intelligent cargo handling and port automation solutions, including Kalmar-branded eco-efficient container handlers and automated port systems, prioritizing digital innovations and sustainability in its strategic offerings.
Kalmar (a Cargotec brand)
Specializing in container logistics, Kalmar offers integrated port automation, electric reachstackers, and terminal tractors, with a focus on reducing emissions and optimizing port throughput through advanced automation technologies.
Yonkers Group
Yonkers Group provides tailored handling equipment for niche markets such as bulk cargo and hazardous materials, emphasizing durability, customization, and strategic collaborations to enhance its regional footprint.
SSR Engineering
SSR Engineering delivers specialized cargo handling solutions, including custom-designed cranes and container transfer systems, investing in innovative manufacturing processes to maintain technological competitiveness.
Strategic Business Developments

- March 2026 – Konecranes – Launch of Autonomous Container Cranes – Significantly enhances port operational efficiency, addressing increasing cargo volume and labor safety concerns.
- June 2026 – Liebherr Group – Capacity Expansion at German Manufacturing Facility – Improves production capabilities, supporting growing demand for large port cranes and automation solutions in Europe.
- August 2026 – Cargotec Corporation – Partnership with European port operators for automation projects – Strengthens market share in port automation and digital logistics services.
- October 2026 – Jungheinrich AG – Introduction of New AI-Driven Warehouse Handling Robots – Aims to boost intra-logistics productivity within distribution centers across Europe.
- January 2027 – Terex Corporation – Acquisition of a European regional handling equipment provider – Extends its service portfolio and improves regional market coverage, especially in Eastern Europe.
Frequently Asked Questions
What is the Europe Cargo Handling Equipment Market?
The Europe Cargo Handling Equipment Market encompasses the production, distribution, and usage of machinery and devices designed to facilitate cargo movement and storage at ports, airports, and logistics hubs across Europe. It includes container handlers, forklifts, cranes, and conveyor systems, supporting efficient throughput in transportation hubs.
What is the current market size of Europe Cargo Handling Equipment Market?
As of 2026, the market value of Europe Cargo Handling Equipment is estimated at around USD 14.2 Billion, reflecting ongoing investments in infrastructure modernization and increased trade activities within the region. The market is poised for notable growth through 2034.
What factors are driving the Europe Cargo Handling Equipment Market?
Growth is fueled by expanding port capacities, technological advancements such as automation, and rising freight volume due to international trade. Additionally, infrastructural upgrades and sustainable practices are prompting adoption of energy-efficient handling solutions, bolstering market expansion.
Which region dominates the Europe Cargo Handling Equipment Market?
Western Europe leads the market, driven by large-scale port infrastructure, high cargo volumes, and robust logistics networks. Countries like Germany, the Netherlands, and Belgium serve as key hubs, leveraging advanced handling systems to meet global trade demands.
Which segment is expected to grow the fastest?
The automated cargo handling segment is anticipated to witness the highest growth rate, owing to the rising adoption of autonomous equipment to enhance safety, efficiency, and reduce labor costs at major cargo handling sites across Europe.
Who are the leading companies operating in the Europe Cargo Handling Equipment Market?
Major players include Konecranes, Liebherr Group, Terex Corporation, Künz GmbH, and Cargotec Corporation. These companies focus on innovation, technological advancements, and strategic partnerships to strengthen their market positions across Europe.
Analyst Perspective
The Europe Cargo Handling Equipment Market exhibits a mature yet steadily evolving landscape, driven by ongoing logistics digitalization and infrastructure upgrades. Long-term prospects remain positive as regional supply chains expand, and automation becomes increasingly integral, creating substantial commercial opportunities in intelligent, energy-efficient equipment solutions. Technological innovation, particularly in automation, IoT integration, and green energy, is expected to shape competitive strategies, with manufacturers prioritizing R&D investments to differentiate offerings and enhance operational efficiency. The region’s diverse industrial base and robust transport networks suggest sustained growth potential, especially in countries like Germany, France, and the UK, which continue to lead in logistics infrastructure investment. However, geopolitical uncertainties and fluctuating supply chain demands pose risks that could temper immediate expansion plans. Strategic focus should thus be directed towards fostering technological leadership, regional diversification, and scalable automation solutions, positioning firms to capitalize on Europe’s ongoing logistics transformation while managing regional and macroeconomic challenges.
