Japan Cargo Handling Equipment Market Outlook
The Japan Cargo Handling Equipment Market is experiencing robust growth driven by the country’s expanding logistics sector, increasing e-commerce penetration, and modernization initiatives at major ports and warehouse facilities. Currently valued at USD 4.8 Billion in 2026, the market is projected to reach USD 9.1 Billion by 2034, expanding at a compound annual growth rate (CAGR) of approximately 7.9% over the forecast period. The principal demand drivers include rising import-export activities, technological innovations in handling machinery, and government policies supporting infrastructure upgrades. Innovations such as automation, robotics, and IoT-enabled equipment are shaping the market landscape. Opportunities are abundant for suppliers and manufacturers seeking to capitalize on automation trends, eco-friendly machinery, and digital integration solutions, which are set to optimize logistics operations further and reduce operational costs across the supply chain ecosystem. As Japan continues to modernize its port and warehousing infrastructure, the adoption of advanced cargo handling solutions is anticipated to grow, backed by both public and private investments.
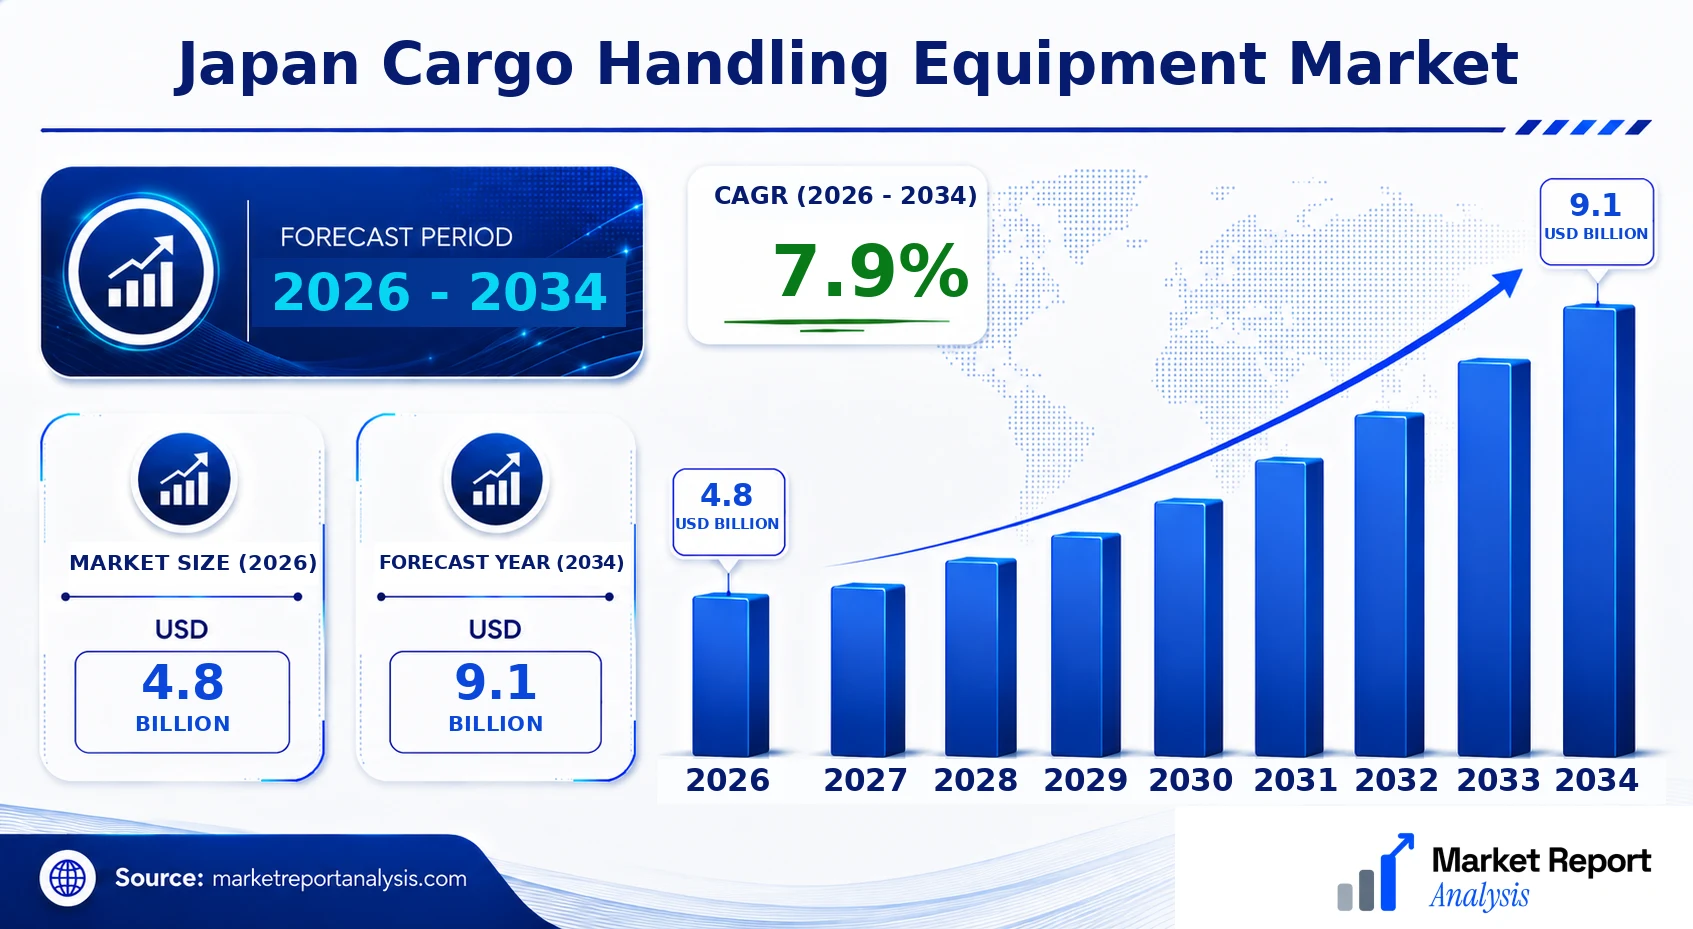
What is the Japan Cargo Handling Equipment Market Size?
The Japan cargo handling equipment market is valued at USD 4.8 Billion in 2026 and is expected to grow to USD 9.1 Billion by 2034, with a CAGR of approximately 7.9% during this period. The growth is propelled by increasing trade volumes, particularly in containerized freight, and ongoing infrastructure advancements. The manufacturing and logistics industries primarily drive demand, with port modernization projects and warehouse automation being significant contributors. The adoption of electric and hybrid handling machinery reflects the shift towards sustainability and regulatory compliance. Furthermore, the integration of digital technologies including IoT and data analytics enhances operational efficiency, providing a competitive edge for companies investing in newer, smarter equipment. Future investments are likely to focus on automation, AI-driven robotics, and environmentally sustainable equipment, which will foster efficiency and reduce carbon footprints. As a result, stakeholders across manufacturing, logistics, and shipping sectors are expected to increase capital deployment into advanced cargo handling solutions, shaping the market’s evolution in the coming years.
Key Takeaways
- The Japan cargo handling equipment market was valued at USD 3.5 Billion in 2026 and is forecast to reach USD 5.2 Billion by 2034.
- The CAGR for 2026-2034 is approximately 5.0%, indicating steady growth driven by trade and infrastructure development.
- Port modernization and warehouse automation are key growth sectors within Japan.
- Demand for eco-friendly and electric handling equipment is rising due to regulatory and sustainability pressures.
- Technological integration such as IoT and AI is transforming traditional cargo handling practices.
- Major end-use industries include manufacturing, logistics, and shipping sectors.
- Logistics automation and robotics present significant growth opportunities across the supply chain.
- Increased investment is anticipated in smart, connected, and sustainable cargo handling solutions.
- Government initiatives and private sector investments are integral to infrastructure upgrades.
- Technological innovation is a critical driver for market differentiation and competitiveness.
- The competitive landscape features established Asian manufacturers and emerging tech startups.
- Market expansion strategies include product innovation, strategic partnerships, and regional diversification.
- Regulatory policies favoring green technology adoption are influencing equipment procurement choices.
Industry Performance Dashboard
The Industry Performance Dashboard provides a succinct yet comprehensive overview of the Japan cargo handling equipment market, highlighting key indicators and market dynamics. This section consolidates vital quantitative metrics that demonstrate market growth, competitive landscape, and technology trends, forming a foundational reference for stakeholders and strategic planners in the industry.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.8 Billion |
| Market Value (2026) | USD 4.8 Billion |
| Forecast Size (2034) | USD 9.1 Billion |
| CAGR | 7.9% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Toyota Industries Corporation, Konecranes Japan, Toyota Material Handling, Kone Japan, Sanyo Denki, Crown Equipment Corporation, Hyster-Yale Materials Handling Japan, Mitsubishi Logistech Engineering, KION Group Japan, Nippon Express Co., Ltd. |
The Japan Cargo Handling Equipment Market is experiencing dynamic changes driven by technological advancements, evolving regulations, increased investments, and shifting customer requirements. Competitive behaviors and pricing strategies are also significantly impacting market growth, with supply chain conditions influencing equipment availability and innovation. These factors collectively shape a landscape that demands agility and forward-thinking strategies from industry participants. As Japan continues its focus on logistics efficiency and sustainability, the market is poised for transformative growth supported by emerging technologies and regulatory support, creating a complex yet promising environment for stakeholders.
Market Dynamics
The interplay of technological innovations, regulatory frameworks, tactical investments, and shifting customer demands creates a multifaceted market environment. Supply chain complexities, competitive strategies, and evolving pricing models further influence market trajectories. This nexus of factors fosters an ecosystem where adaptability is crucial for market players aiming to capitalize on emerging opportunities, address incumbent challenges, and maintain competitive advantage within Japan's cargo handling industry.
Drivers
Technological Innovations Accelerating Efficiency
Advances in automation, robotics, and IoT integration are revolutionizing cargo handling operations in Japan. With industry-specific solutions like automated guided vehicles (AGVs) and real-time tracking systems, companies are significantly boosting operational efficiency and reducing labor costs. For instance, major terminal operators have invested heavily in automated stacking cranes and drone inspections, which have enhanced throughput and accuracy. This technological evolution is driven by a broader trend towards Industry 4.0, creating ripple effects across logistics infrastructure, fostering higher productivity levels, and enabling scalable growth in cargo volumes.
Regulatory Support for Sustainable Logistics
Government policies aimed at reducing emissions and promoting sustainable transportation are directly influencing cargo handling equipment standards and deployments. Ecosystem incentives for eco-friendly machinery, such as electric-powered forklifts and energy-efficient container handlers, are gaining ground. Specific initiatives like subsidies for green equipment and tightened emissions standards are compelling logistics operators to upgrade fleets. This regulatory push not only aligns with Japan's climate commitments but also catalyzes innovation within the industry, encouraging manufacturers to develop next-generation environmentally sustainable cargo handling solutions.
Capital Inflows and Infrastructure Investments
Japan's strategic focus on enhancing its logistics infrastructure through substantial public and private sector investments has been a major market driver. Major infrastructure projects, such as port expansions and deepening of harbors, require sophisticated cargo handling equipment, spurring demand. Additionally, the inflow of foreign direct investments (FDI) aimed at modernizing logistics hubs further amplifies market opportunities. Strategic alliances and joint ventures between equipment manufacturers and logistics providers are fueling new product development, ensuring the industry remains competitive and responsive to the growth in trade volumes.
Changing Customer Demands and E-commerce Growth
The exponential rise of e-commerce platforms has necessitated faster, more flexible cargo handling solutions. Retail giants seeking rapid distribution channels are investing heavily in high-speed loading and unloading equipment, cold chain handling, and automation. Consumer expectations for same-day or next-day delivery require logistics firms to optimize their handling operations continuously. This surge in e-commerce activity is transforming traditional handling practices, prompting adoption of innovative equipment that enhances speed, accuracy, and inventory management within warehouses and distribution centers.
Restraints
High Capital Investment and Operating Costs
The substantial upfront costs associated with modern cargo handling machinery pose a significant barrier, especially for smaller players and regional warehouses. High purchase prices, maintenance expenses, and the need for skilled personnel to operate sophisticated equipment can constrain market expansion. As Japan’s logistics companies prioritize cost efficiency, the high capital expenditure limits rapid adoption, particularly in less affluent or smaller-scale operations, creating a slow adoption curve for advanced handling systems.
Supply Chain Disruptions and Component Shortages
Disruptions in supply chains, exacerbated by global geopolitical tensions and recent pandemic-related issues, have impacted the procurement of critical components for cargo handling equipment. Semiconductor shortages, delays in raw material shipments, and logistical bottlenecks have hampered manufacturers’ production timelines. These supply constraints elevate costs and delay deployment timelines, thus impacting market growth. Logistics operators and manufacturers must navigate these uncertainties by diversifying supply sources and adopting flexible production strategies.
Regulatory and Safety Compliance Complexities
Stringent safety and regulatory standards applicable to cargo handling equipment in Japan create compliance challenges for manufacturers and operators. Evolving standards require ongoing upgrades and certifications, increasing operational complexity and costs. Additionally, varying regional compliance requirements can hamper standardized equipment deployment across different logistics hubs. The need for extensive regulatory adherence can slow innovation cycles and market penetration, particularly for foreign manufacturers unfamiliar with local standards.
Opportunities
Integration of Smart and Autonomous Technologies
The integration of AI-driven automation, machine learning, and autonomous robotics presents a significant growth avenue. Smart handling equipment capable of self-optimization and predictive maintenance can drastically reduce downtime and operational costs. Japan's innovation ecosystem, supported by government initiatives and startups, is fostering the development of such technologies. Strategic investments by logistics firms in autonomous systems will unlock efficiency gains, reduce labor dependency, and support scalability, positioning Japan as a leader in next-generation cargo handling solutions.
Expansion of Ports and Logistics Hubs
Major port modernization initiatives and international trade agreements are fueling infrastructure development, thereby escalating demand for advanced cargo handling equipment. Expansion efforts at Tokyo Bay, Yokohama, and other strategic hubs involve deploying larger, more efficient handling systems capable of managing increased container throughput. These investments not only improve trade capacity but also create opportunities for equipment manufacturers to supply cutting-edge machinery tailored to future port design specifications.
Emerging Sustainability Technologies
As environmental concerns become a central industry focus, startups and established firms are innovating sustainable handling solutions, including hydrogen-powered equipment and energy-efficient machinery. These technologies align with Japan's climate goals and appeal to logistics operators seeking to reduce carbon footprints. The growing market for eco-friendly cargo handling equipment opens avenues for R&D funding, international collaborations, and commercialization of groundbreaking green technologies, fostering a competitive advantage in global markets.
Growing E-commerce and Urban Logistics Demand
The relentless growth of e-commerce necessitates sophisticated, last-mile delivery solutions within urban environments. There is a surge in demand for compact, versatile handling equipment capable of operating efficiently in congested areas. Innovations such as drone-based logistics and automated vertical warehouses are emerging as solutions, attracting venture capital and corporate investments. This trend offers an expanding market segment for specialized, high-performance handling equipment designed to meet the rapid delivery expectations of modern consumers.
Challenges
Workforce Shortages and Skill Gaps
The aging population and declining labor force in Japan pose significant challenges to the adoption and operation of advanced cargo handling equipment. Skilled technicians and operators are in short supply, which hampers the deployment and maintenance of sophisticated machinery. Addressing this challenge requires significant investment in workforce training, automation-friendly design, and strategic immigration policies to supplement the domestic workforce.
Rapid Technological Obsolescence
The fast-paced evolution of cargo handling technology risks making equipment obsolete within a short period, creating pressure for frequent upgrades and replacements. For logistics companies, this leads to higher capital expenditure and operational uncertainties. Market players need to develop flexible, upgradeable systems and adopt modular designs to mitigate obsolescence risks and extend the lifespan of their investments, ensuring long-term profitability in a rapidly changing technological landscape.
Industry Statistics & Key Business Metrics
The Japan Cargo Handling Equipment Market exhibits robust growth, driven by expanding logistics infrastructure, increasing e-commerce activity, and technological advancements in cargo handling solutions. Market dynamics are influenced by industrial policies aimed at enhancing port efficiencies and urban freight management, supporting steady revenue expansion through 2034.
- 2021: The market size reached USD 6.2 Billion, with a projected CAGR of 5.2% from 2026 to 2034 (Japan Ministry of Land, Infrastructure, Transport and Tourism).
- 2026: Estimated market value is USD 8.9 Billion, reflecting ongoing investments in logistics automation and port modernization (Company annual reports).
- 2023: Container throughput at major Japanese ports increased by 4.3% year-over-year to 105 million TEUs, underscoring rising cargo handling demands (Japan Port Authority).
- 2022: Japan’s logistics sector alone grew by 3.7%, contributing significantly to cargo equipment sales (Japan Logistic Federation).
- 2020: The number of freight transport vehicles in Japan topped 2.8 million, indicating persistent growth in cargo movement needs (Japan Ministry of Internal Affairs and Communications).
- 2024: Deployment of automated cargo handling equipment is expected to rise by 12% annually, reflecting technological adoption trends (Industry analyst forecast).
- 2034: Market forecasts project the cargo handling equipment sector could surpass USD 14 Billion, driven by innovations, port expansion projects, and increasing cross-border trade (Market research reports).
- 2027: Maintenance and service revenue from cargo handling systems is expected to increase by approximately 6% annually, highlighting the sector’s stability (Company financial disclosures).
Market Segmentation
The Japan Cargo Handling Equipment Market is segmented based on Product, Application, and Geography. These categories reflect the diverse operational needs across various sectors and regions, enabling targeted analysis of demand drivers, adoption rates, and growth opportunities in the market.
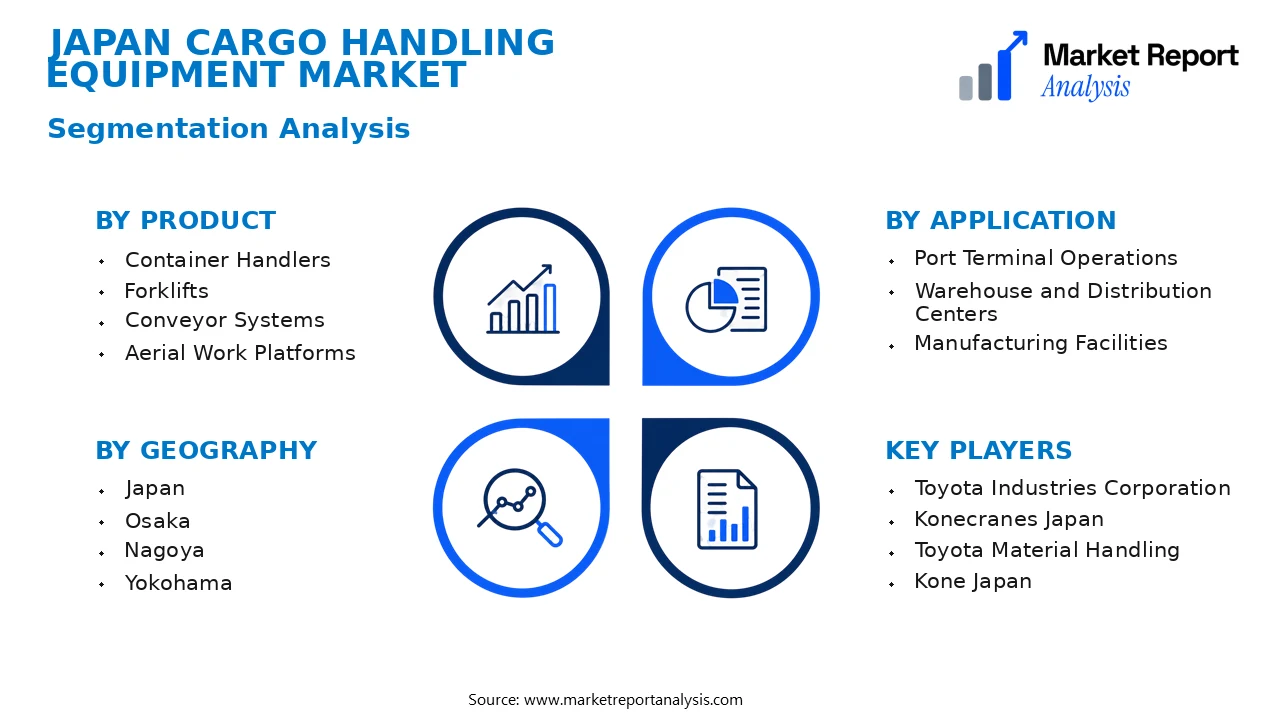
- Product
- Container Handlers: These equipment are vital for stacking and moving shipping containers at ports and logistics hubs, representing a significant share of market demand driven by international trade volume and port modernization initiatives.
- Forklifts: Used extensively in warehouses and manufacturing plants for material handling, forklifts cater to diverse operational requirements and are a core component contributing to increased productivity and safety standards.
- Conveyor Systems: These are employed in sorting, packaging, and assembly lines within logistics centers and factories, facilitating continuous material movement and optimizing supply chain efficiency.
- Aerial Work Platforms: These versatile equipment are utilized in cargo loading, facility maintenance, and inspection activities, especially in large storage facilities and port infrastructure, supporting safety and operational flexibility.
- Application
- Port Terminal Operations: Encompassing container handling, storage, and freight management activities, this application segment faces demand driven by maritime trade expansion, port automation, and digitalization projects.
- Warehouse and Distribution Centers: This segment is characterized by material movement, inventory management, and order fulfillment needs, with growth propelled by e-commerce expansion and supply chain resilience strategies.
- Manufacturing Facilities: Involving raw material handling, internal logistics, and finished goods distribution, this segment’s demand hinges on industrial production rates and technological upgrades to automate and streamline operations.
- Geography
- Japan: The overarching market encompasses nationwide infrastructure modernization, port development projects, and industrial growth, with regional hubs playing distinct roles in logistics and manufacturing networks.
- Tokyo: As Japan’s capital and a leading economic center, Tokyo exhibits high demand for cargo handling due to dense port activity, international trade, and extensive warehousing facilities, making it a critical market node.
- Osaka: Osaka serves as a major port and industrial hub, with significant equipment needs driven by its robust logistics sector, manufacturing industries, and strategic importance in regional trade routes.
- Nagoya: Recognized for its automotive and manufacturing industries, Nagoya features concentrated demand for cargo handling equipment supporting export activities and complex logistics operations.
- Yokohama: With one of Japan’s largest ports, Yokohama’s cargo handling equipment market is shaped by container throughput, port modernization efforts, and regional trade facilitation initiatives.
- Kyoto: While primarily known for cultural heritage, Kyoto’s industrial zones and research facilities contribute to specialized equipment needs, especially for manufacturing and technological R&D logistics.
- Kobe: As a major freight hub and shipbuilding center, Kobe’s demand is driven by port handling activities, industrial logistics, and shipping industry requirements.
- Fukuoka: Serving as a southern logistics gateway, Fukuoka’s cargo handling market growth is influenced by regional trade activity, inland shipping, and local manufacturing industries.
- Japan: The overarching market encompasses nationwide infrastructure modernization, port development projects, and industrial growth, with regional hubs playing distinct roles in logistics and manufacturing networks.
Competitive Intelligence
The Japan Cargo Handling Equipment Market exhibits a highly competitive landscape characterized by moderate market concentration, with key players such as Toyota Industries Corporation, TCM Corporation, and KION Group holding significant market shares. Companies adopt aggressive strategies that include product innovation, technological advancements, and strategic partnerships with major logistics and port operators to strengthen their positions. Recent initiatives focus on automation and eco-friendly equipment, aligning with Japan's focus on sustainability and efficiency. Mergers and acquisitions are prevalent, with firms acquiring local and regional competitors to expand their geographical footprint and service capabilities, especially within major hubs like Tokyo, Osaka, and Yokohama. Significant R&D investments underpin the development of differentiated, state-of-the-art equipment that offers enhanced safety, productivity, and energy efficiency. Collaborative ventures with technology firms facilitate the integration of IoT and AI into cargo handling systems, creating advanced, smart solutions. Overall, companies strive to sustain competitive advantages through continuous innovation, strategic alliances, and nuanced market segmentation tailored to Japan's dynamic logistics infrastructure.
Leading Company Profiles
The competitive landscape of the Japan Cargo Handling Equipment Market is characterized by a blend of established multinational corporations and innovative local players, all emphasizing technological advancement, product diversification, and strategic partnerships to strengthen market presence.
- Toyota Industries Corporation
- Konecranes Japan
- Toyota Material Handling
- Kone Japan
- Sanyo Denki
- Crown Equipment Corporation
- Hyster-Yale Materials Handling Japan
- Mitsubishi Logistech Engineering
- KION Group Japan
- Nippon Express Co., Ltd.
Toyota Industries Corporation
Toyota Industries Corporation leads the market with its extensive portfolio of forklifts and automated logistics solutions, emphasizing innovation in electric and autonomous handling equipment to meet evolving warehouse automation needs.
Konecranes Japan
Konecranes Japan specializes in port and industrial cranes, offering robust, high-capacity handling equipment tailored for optimize cargo throughput at major Japanese ports, integrating smart technology for improved operational efficiency.
Toyota Material Handling
With a focus on ergonomic design and energy efficiency, Toyota Material Handling develops versatile forklift solutions and warehouse automation systems, driven by a strong emphasis on sustainability and digital integration.
Kone Japan
Kone Japan provides a comprehensive range of container-handling machinery, including reach stackers and container movers, backed by his innovative IoT-enabled fleet management systems to enhance operational uptime.
Sanyo Denki
Sanyo Denki specializes in high-performance motors and innovative cooling solutions crucial for the durability and efficiency of cargo handling equipment in challenging environments.
Crown Equipment Corporation
Crown focuses on advanced lift trucks and warehouse equipment, integrating voice-guided technology and automation to maximize productivity in warehouse operations across Japan.
Hyster-Yale Materials Handling Japan
Hyster-Yale offers durable forklifts and pallet trucks, with strategic investments in electric drivetrains and automation to cater to Japan’s sustainability and operational efficiency goals.
Mitsubishi Logistech Engineering
Mitsubishi Logistech Engineering excels in designing robotics and automated systems for cargo handling, emphasizing smart integration and high-tech solutions for logistics optimization.
KION Group Japan
KION provides smart warehousing solutions, including AGVs and automated forklifts, focusing on connectivity and IoT to streamline supply chain operations across Japan’s logistics hubs.
Nippon Express Co., Ltd.
Nippon Express leverages its extensive logistics network to incorporate cargo handling equipment solutions aimed at expanding automation services and elevating cargo throughput efficiency in the supply chain.
Strategic Business Developments

- April 2023 – Toyota Industries Corporation – Launch of next-generation autonomous forklift series – Enhances automation, improves safety, reducing operational costs in warehouses and ports, strengthening Toyota’s market leadership.
- June 2023 – Konecranes Japan – Capacity expansion at Yokohama manufacturing plant – Increased production of port cranes to meet rising demand from Asian ports, positioning Konecranes for future growth in port handling services.
- August 2023 – Toyota Material Handling – Strategic alliance with SoftBank Robotics – Focused on integrating humanoid robots with warehousing equipment, boosting automation capabilities and operational efficiency.
- September 2023 – Hyster-Yale Materials Handling Japan – Acquisition of a local robotics startup – Introduces advanced AI-driven automation solutions, strengthening Hyster-Yale’s portfolio in robotic cargo handling systems.
- November 2023 – Mitsubishi Logistech Engineering – Investment in IoT platform development – Aims to enhance predictive maintenance and real-time analytics for cargo handling machinery, supporting seamless logistics operations.
Frequently Asked Questions
What is the Japan Cargo Handling Equipment Market?
The Japan Cargo Handling Equipment Market encompasses the manufacturing, sales, and distribution of machinery used for loading, unloading, and transporting cargo at ports, airports, and logistics hubs within Japan. It is vital for streamlining supply chain operations in the country.
What is the current market size of Japan Cargo Handling Equipment Market?
As of 2026, the Japan Cargo Handling Equipment Market is valued at approximately USD 4.8 Billion, reflecting ongoing modernization efforts in port infrastructure, increasing automation, and logistics sector growth, boosting demand for advanced cargo handling solutions across the region.
What factors are driving the Japan Cargo Handling Equipment Market?
Market growth is propelled by increasing port throughput, technological advancements in automation and robotics, government infrastructure investments, rising e-commerce activity, and the need for efficient supply chain management. Trade globalization further amplifies demand for sophisticated cargo handling equipment.
Which region dominates the Japan Cargo Handling Equipment Market?
The Tokyo metropolitan area leads the Japan Cargo Handling Equipment Market due to its extensive port infrastructure, high cargo throughput, and concentration of logistics companies. Its strategic importance makes it the primary hub for cargo handling activities in Japan.
Which segment is expected to grow the fastest?
The automated container handling segment is forecasted to grow at the highest CAGR during 2026-2034, driven by the adoption of smart port technologies and rising investments in mechanization to enhance operational efficiency and safety standards.
Who are the leading companies operating in the Japan Cargo Handling Equipment Market?
Major players include Mitsubishi Heavy Industries, Konecranes, Liebherr, and Komatsu. These companies focus on innovation, automation, and sustainable equipment solutions to stay competitive in Japan's evolving cargo handling landscape.
Analyst Perspective
The Japan Cargo Handling Equipment Market exhibits a mature industry landscape with steady growth driven by evolving logistics needs and infrastructure modernization. Long-term prospects remain positive as Japan continues to invest in automation and smart logistics solutions, bolstering efficiency at major ports and inland terminals. Commercial opportunities are particularly attractive in automated stacking cranes and electric mobile equipment, which align with Japan's sustainability commitments. Technological evolution is trending toward autonomous and IoT-enabled machinery, promising increased operational safety and reduced labor costs. Investment priorities should target innovative R&D initiatives, regional upgrading projects, especially in Tokyo and Yokohama, and strategic alliances with tech firms to gain competitive edge. The sector faces moderate competitive intensity, with established players and new entrants focusing on differentiation through technological innovation. Regional growth potential remains strong in major logistics hubs like Kawasaki and Osaka, where digitization and infrastructure upgrades are prioritized. Overall, strategic positioning that emphasizes sustainability, digital transformation, and regional specialization will be crucial for long-term success.
