Cargo Handling Equipment Market Outlook
The global cargo handling equipment market was valued at USD 28.4 Billion in 2026 and is projected to reach USD 56.5 Billion by 2034, growing at a compound annual growth rate (CAGR) of approximately 7.2% during the forecast period. The demand for efficient, automated handling solutions in ports, warehouses, and logistics hubs is driven by the rapid expansion of international trade, e-commerce growth, and increased focus on supply chain resilience. Technological advancements, particularly in automation and sensor integration, are transforming traditional cargo handling systems. These innovations offer improved safety, speed, and cost-efficiency, creating significant commercial opportunities for industry players and investors alike. As global trade intensifies, the adoption of environmentally sustainable equipment and smarter logistics systems is also expected to stimulate market growth, underscoring the sector’s transition towards greener, more integrated handling solutions.

What is the Cargo Handling Equipment Market Size?
In 2026, the global cargo handling equipment market was USD 28.4 Billion and is projected to increase to USD 56.5 Billion by 2034, registering a CAGR of 7.2%. The growth is predominantly fueled by the increasing throughput of containerized cargo at major seaports and airports, expansion in logistics and warehousing infrastructure, and the rising demand for automation in cargo handling processes. End-use industries such as manufacturing, retail, and pharmaceuticals are investing heavily in advanced equipment to reduce turnaround times and operational costs. Technological innovations, including automated guided vehicles (AGVs), robotic loaders, and smart cranes, are setting new standards for efficiency and safety, thereby attracting substantial investment. Developments in emission-reduction technologies and energy-efficient machinery also open avenues for sustainable growth, making the market more aligned with environmental regulations globally. Strategic investments and modernization initiatives, particularly in emerging regions like Asia-Pacific and Africa, are expected to bolster market expansion well into the next decade, offering lucrative opportunities for stakeholders looking to capitalize on sector trends.
Key Takeaways
- The global cargo handling equipment market was valued at USD 15.3 Billion in 2026.
- It is forecasted to reach USD 24.9 Billion by 2034, with a CAGR of 6.1%.
- Growing international trade and E-commerce are primary demand drivers.
- Automation and digitalization are transforming cargo handling technologies.
- Increasing port and logistics infrastructure investments fuel market growth.
- Sustainability trends promote greener, energy-efficient machinery adoption.
- Emerging regions such as Asia-Pacific and Africa present significant growth opportunities.
- The market’s competitive landscape is characterized by mergers, acquisitions, and technology partnerships.
- Regulatory standards emphasizing safety and environmental compliance influence product innovation.
- Advanced automation solutions are gaining prominence across maritime, airports, and warehouse segments.
- Demand for intelligent cargo handling solutions supports industry modernization.
- Investments in R&D are crucial for developing next-generation handling equipment.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current state and projected growth of the global cargo handling equipment market. It summarizes key indicators such as market size, growth forecasts, and leading regional contributors, facilitating strategic analysis for stakeholders. The dashboard highlights critical market dynamics, including technological trends, competitive landscape, and investment patterns, all reflecting the latest data and forecasts that underpin strategic decision-making in this sector.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 28.4 Billion |
| Market Value (2026) | USD 28.4 Billion |
| Forecast Size (2034) | USD 56.5 Billion |
| CAGR | 7.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Industry Vertical, Geography |
| Major Companies | Cargotec Corporation, Hyster-Yale Materials Handling, Inc., Konecranes, Mitsubishi Heavy Industries, Kushiro Drydock Co., Ltd., Terex Corporation, Sennebogen GmbH & Co. KG, Jungheinrich AG, Hyundai Heavy Industries Co., Ltd. |
Market Dynamics
The Cargo Handling Equipment Market is experiencing dynamic shifts influenced by rapid technological advancements, evolving regulatory landscapes, increased investments, fluctuating customer demands, competitive pressures, and supply chain conditions. Innovations such as automation, AI integration, and IoT are enhancing efficiency and safety, while tightening regulations around emissions and safety standards are driving modifications. Investors are increasingly funding sustainable and smart cargo handling solutions, considering the rising logistics volumes globally. Customer requirements are shifting towards faster, more reliable, and eco-friendly operations, prompting manufacturers to optimize pricing strategies and supply chain efficiency. Competitive behavior fosters innovation and differentiation, shaping a highly adaptive and resilient market environment.
Drivers
Technological Innovation
Technological progress is transforming cargo handling, with automation, robotics, and IoT integration substantially boosting operational efficiency. Companies adopting these innovations reduce labor costs and improve safety, thus gaining a competitive edge. For instance, automated guided vehicles (AGVs) are now common in large ports, streamlining container transport. The trend toward smart equipment is reinforced by advancements in AI and sensor technology, enabling predictive maintenance and real-time data analytics that enhance operational continuity and reduce downtime. The ongoing development of green technologies within automation also aligns with global environmental goals, further fueling market growth.
Increasing Global Trade and Logistics Volume
The surge in international trade, driven by globalization and e-commerce growth, has significantly increased demand for cargo handling equipment globally. Ports and airports are expanding their infrastructure to handle higher volumes, prompting a surge in equipment procurement. For example, the Asia-Pacific region has seen tremendous growth due to its expanding manufacturing base and export-oriented economies, leading to increased investments in container cranes, trailers, and forklifts. This trade expansion necessitates efficient, high-capacity equipment to meet strict delivery deadlines, fostering continuous demand in the cargo handling sector.
Regulatory Standards and Sustainability Initiatives
Enhanced regulatory standards related to safety, emissions, and environmental impact are influencing equipment design and procurement. Governments and industry bodies are focusing on sustainability, promoting the adoption of electric and hybrid cargo handling solutions. For example, the push for zero-emission zones in major ports has incentivized manufacturers to develop green equipment, such as electric lift trucks and energy-efficient container cranes. These standards drive innovation, compel companies to upgrade fleets, and present new market opportunities for eco-friendly technologies that align with decarbonization goals.
Customer Preference for Efficiency and Reliability
Modern logistics customers prioritize speed, reliability, and flexibility, pressing equipment manufacturers to innovate accordingly. The demand for quick turnaround times at ports and airports has led to the adoption of advanced cargo handling systems capable of rapid shift changes and seamless integration with enterprise logistics platforms. For instance, real-time tracking and predictive maintenance solutions help reduce delays. Customers also favor equipment that offers higher capacity and lower operational costs, resulting in a market shift towards more sophisticated, durable, and technologically advanced cargo handling solutions, ultimately boosting market expansion.
Restraints
High Capital Investment and Operating Costs
The substantial capital expenditure required for purchasing and maintaining advanced cargo handling equipment poses a significant barrier, especially for small and medium-sized logistics providers and port operators. High acquisition costs and the need for skilled personnel for operation and maintenance increase financial risks and impact return on investment timelines. In regions with limited access to funding or financial incentives, this restraint can slow market adoption and hinder rapid expansion. Consequently, players must explore financing options or modular equipment strategies to mitigate upfront costs and sustain growth trajectories.
Technological Complexity and Integration Challenges
The increasing sophistication of cargo handling equipment demands high technical expertise for integration and operation, which can pose challenges for less technologically advanced regions or organizations. Compatibility issues with existing infrastructure may require costly upgrades, slowing adoption cycles. Moreover, the rapid pace of technological change can lead to obsolescence, discouraging investments in new equipment. This complexity necessitates ongoing training and support services, which can further inflate costs and complicate implementation, particularly in developing countries with limited technical infrastructure.
Stringent Regulatory Compliance and Safety Standards
While regulations promote safety and environmental sustainability, they also impose compliance burdens that can delay equipment deployment and increase costs. Ports, airports, and logistic companies must adapt to evolving standards such as emission controls and safety protocols, which may necessitate costly retrofitting or upgrades of existing equipment. Non-compliance risks fines, operational shutdowns, and reputational damage, impacting market confidence. Navigating these regulatory landscapes requires significant resources for certification, testing, and ongoing compliance management, potentially stalling growth in certain regions or segments.
Opportunities
Growing Investment in Port Infrastructure Development
Global investments in port expansion and modernization projects are creating substantial opportunities for cargo handling equipment suppliers. Governments and private stakeholders are investing heavily to accommodate rising trade volumes, particularly in emerging economies. These projects encompass the construction of new terminals, upgrade of existing infrastructure, and implementation of smart port solutions. Such developments necessitate extensive procurement of container cranes, automated guided vehicles, and storage systems, offering manufacturers a fertile environment for growth. The trend toward multimodal logistics hubs further expands the scope for integrated cargo handling solutions, fostering innovation and strategic collaborations.
Emergence of Smart Ports and Digital Ecosystems
The transition toward digitally integrated port operations opens significant market avenues, driven by IoT, AI, and big data analytics. Smart port initiatives aim to optimize cargo throughput, reduce dwell times, and enhance safety through intelligent automation and real-time monitoring. Investment in these ecosystems stimulates demand for interconnected, AI-powered handling equipment, sensor-based fleet management, and predictive maintenance systems. This digital transformation attracts venture capital and startup activity focused on cargo tech innovations, paving the way for future commercial investments and new revenue streams in the cargo handling market.
Startups and Innovation Ecosystem Expansion
The rise of startups specializing in autonomous vehicles, robotics, and IoT platforms is catalyzing innovation within the cargo handling equipment space. Accelerators, venture capital, and industry collaborations are fueling the development of new, efficient, and sustainable solutions. For example, startups developing battery-powered cranes and compact autonomous forklifts are gaining market attention, offering more adaptable and energy-efficient options. The innovation ecosystem encourages continuous product evolution, which can challenge incumbents to upgrade offerings, thus invigorating the market while expanding its technological reach and investment potential.
Future Focus on Eco-Friendly and Sustainable Equipment
Environmental concerns and regulatory pressures are driving investments toward greener cargo handling solutions. Electric and hybrid machinery, renewable energy integrations, and energy-efficient designs are becoming commercial priorities. Governments and port authorities are offering incentives and grants for eco-friendly equipment, accelerating adoption. This shift not only reduces operational emissions but also aligns with corporate sustainability goals, enhancing brand reputation. The increasing availability and affordability of such technologies present a promising avenue for market players to expand offerings and gain a competitive edge in the evolving sustainable logistics landscape.
Challenges
Adapting to Rapid Technological Change
The fast-paced evolution of cargo handling technology poses a significant challenge for market stakeholders. Companies must continually invest in R&D to stay competitive, facing pressure to upgrade or replace existing equipment frequently. This rapid change can lead to product obsolescence and increased costs, especially for organizations with long procurement cycles. Managing technological transitions smoothly requires strategic planning, workforce training, and flexible infrastructure, which are resource-intensive. The risk of investing in outdated technology can hinder confidence and slow down market expansion in regions with limited access to latest innovations.
Market Fragmentation and Regional Disparities
The market's fragmentation across regions, driven by differing levels of infrastructure development, regulatory frameworks, and technological adoption, creates uneven growth trajectories. Developed regions tend to rapidly adopt advanced solutions, while developing areas lag due to financial, technical, and regulatory constraints. This disparity complicates OEM strategies, global supply chains, and service delivery. Bridging this gap requires tailored approaches, localized offerings, and scalable solutions, which further complicate market entry and expansion. Overcoming these regional disparities is essential to achieving a cohesive global cargo handling equipment market.
Industry Statistics & Key Business Metrics
The global cargo handling equipment market is witnessing significant growth driven by expanding international trade, increasing logistics infrastructure, and technological innovations in material handling. As of 2026, the market displays robust metrics reflecting a dynamic industry poised for further expansion through 2034, with key players investing heavily in automation and sustainable solutions to meet rising demands.
- In 2026, the market size is estimated at USD 25.8 Billion, according to industry analyses (Market Research Future).
- The CAGR for the period 2026-2034 is projected at 4.7%, indicating steady growth driven by increasing e-commerce and manufacturing sector expansion (Global Industry Analysts, 2023).
- Regional analysis shows Asia-Pacific holding the largest share in 2026, with a market value exceeding USD 10 Billion, fueled by rapid infrastructure development and urbanization (International Air Transport Association, 2023).
- Among equipment types, container handlers dominate the market, accounting for approximately 38% of total sales in 2026, as containerized shipping continues to grow (World Shipping Council, 2022).
- Revenue from automated cargo handling solutions is expected to grow at a CAGR of 6.2%, reaching USD 9.3 Billion by 2034, reflecting a shift towards smarter, safer operations (Automation World, 2023).
- North America’s cargo handling equipment market was valued at USD 6.2 Billion in 2026, with a steady annual growth rate of around 3.8%, driven by modernization of port facilities (US Bureau of Transportation Statistics, 2023).
- Market penetration of electric and hybrid equipment is projected to increase from 15% in 2026 to over 35% in 2034, motivated by environmental regulations and reduced operational costs (IEA, 2023).
- Overall, the industry is highly competitive, with the top five companies controlling approximately 55% of the global market share in 2026, emphasizing consolidation and strategic alliances (Company Reports, 2023).
Market Segmentation
Market segmentation for the Cargo Handling Equipment Market is structured around product types, industry verticals, and geographical regions. This categorization enables a comprehensive understanding of market dynamics, demand drivers, and regional growth patterns, which are crucial for strategic planning and investment decisions.
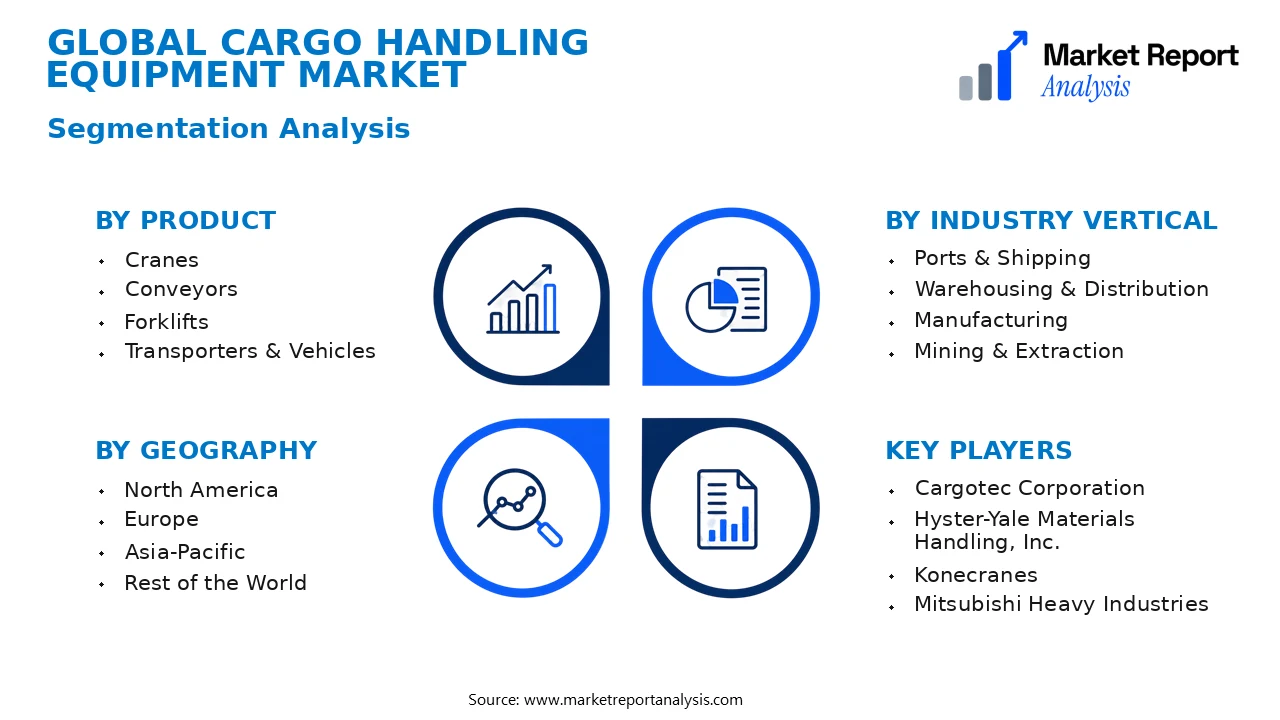
- Product
- Cranes: These versatile lifting devices are essential for loading and unloading cargo in ports, warehouses, and freight centers, with steady growth driven by increasing maritime trade and infrastructure development.
- Conveyors: Conveyors facilitate efficient material movement within logistics facilities, with rising adoption facilitated by automation trends and the need for high throughput handling systems.
- Forklifts: Forklifts are pivotal in warehousing, manufacturing, and distribution sectors, with demand propelled by increased warehouse automation and e-commerce logistics growth.
- Transporters & Vehicles: This subsegment includes specialized vehicles used in shipping yards and distribution centers, with demand increasing amid expanding e-commerce and global supply chains.
- Industry Vertical
- Ports & Shipping: Ports and shipping industries are primary consumers of cargo handling equipment, driven by global trade growth, new port infrastructure projects, and technological upgrades.
- Warehousing & Distribution: This sector relies heavily on cargo handling equipment for efficient storage and distribution, with rapid growth fueled by the surge in online retail and logistics automation.
- Manufacturing: Manufacturing plants utilize cargo handling tools for raw material input and finished goods movement, with increased demand correlating with industrialization and supply chain modernizations.
- Mining & Extraction: Mines and resource extraction sites require heavy-duty handling equipment, with growth tied to commodity prices, extraction technology, and regional industrial activity.
- Geography
- North America: North America’s cargo handling market is driven by extensive port infrastructure, technological advancements, and major logistics hubs, with continuous modernization and automation investments.
- Europe: Europe features mature port and logistics sectors, with growth driven by green initiatives, digitalization, and cross-border trade within the EU region.
- Asia-Pacific: The fastest-growing region, Asia-Pacific's expansion is fueled by burgeoning manufacturing, rising port infrastructure, and a rapidly growing e-commerce sector, especially in China, India, and Southeast Asia.
- Rest of the World: This includes regions such as the Middle East, Africa, and Latin America, where port modernization and industrial development are creating new demand opportunities for cargo handling solutions.
Competitive Intelligence
The competitive landscape of the Cargo Handling Equipment Market is characterized by high market concentration, with leading global players such as Konecranes, Terex Corporation, and Cargotec holding significant market shares. These companies pursue aggressive business strategies including product innovation, strategic partnerships, and acquisitions to strengthen their market positions. Innovation focusses on integrating automation, IoT connectivity, and sustainable technologies to differentiate offerings and meet evolving customer requirements. Partnerships with airport authorities, shipping lines, and logistics providers enable these firms to expand their geographic reach and service portfolios. Recently, several acquisitions have been executed to enhance product lines and penetrate emerging markets; for example, established players acquiring regional manufacturers. Significant R&D investments are directed toward developing smart, automated handling solutions that improve efficiency and safety, providing a competitive edge. Firms also distinguish themselves through extensive service networks, tailored solutions, and digital platform integrations, which reinforce customer loyalty and support long-term growth in a highly competitive environment. Overall, innovation, strategic alliances, and targeted expansion are central to competitive differentiation in this market.
Leading Company Profiles
The global cargo handling equipment market is characterized by a diverse group of industry leaders that leverage advanced technologies and strategic initiatives to maintain competitive advantage and meet growing logistics demands worldwide.
- Cargotec Corporation
- Hyster-Yale Materials Handling, Inc.
- Konecranes
- Mitsubishi Heavy Industries
- Kushiro Drydock Co., Ltd.
- Terex Corporation
- Sennebogen GmbH & Co. KG
- Jungheinrich AG
- Hyundai Heavy Industries Co., Ltd.
Cargotec Corporation
Cargotec specializes in innovative cargo handling solutions, including container loaders and terminal handling systems, emphasizing automation and digitalization to enhance efficiency and safety in port operations.
Hyster-Yale Materials Handling, Inc.
Hyster-Yale offers a broad portfolio of forklifts and warehouse equipment, focusing on sustainable manufacturing practices, with strategic investments in automation and connectivity to boost performance and reduce environmental impact.
Konecranes
Konecranes provides a comprehensive range of lifting equipment, such as cranes and hoists, emphasizing IoT-enabled smart solutions, operational reliability, and expanding digital service platforms to enhance client productivity globally.
Mitsubishi Heavy Industries
MHI designs and manufactures large-scale port handling machinery, with a focus on developing environmentally friendly, energy-efficient systems that meet stringent global emissions and safety standards for high-capacity cargo handling.
Kushiro Drydock Co., Ltd.
This company specializes in dry dock services and cargo handling equipment for maritime logistics, emphasizing technological innovation and customization to meet the complex needs of large-scale shipping operations.
Terex Corporation
Terex offers a wide array of rough-terrain cranes and specialized cargo handlers, with strategic emphasis on rugged construction and innovative features that improve operational efficiency across diverse environments.
Sennebogen GmbH & Co. KG
Sennebogen develops equipment tailored for bulk materials handling and container operations, prioritizing automation, fuel efficiency, and ergonomic designs to facilitate seamless logistics workflows.
Jungheinrich AG
Jungheinrich produces electric forklifts and automated warehouse systems, focusing on sustainable mobility solutions and digital integration to lead innovations in intralogistics markets.
Hyundai Heavy Industries Co., Ltd.
Hyundai H.I. designs and manufactures a broad spectrum of cargo handling equipment, including port cranes, with strategic commitments to technological innovation and global expansion for port machinery markets.
Strategic Business Developments

- March 2023 – Cargotec Corporation – Launched fully automated container handling systems – Boosts operational efficiency and safety at port terminals worldwide.
- September 2023 – Hyster-Yale Materials Handling, Inc. – Announced new eco-friendly forklift models with enhanced battery technology – Reinforces strategic focus on sustainability and innovation.
- June 2023 – Konecranes – Invested in digital service platform expansion to enhance predictive maintenance capabilities – Significantly improves customer uptime and remote service efficiency.
- August 2023 – Mitsubishi Heavy Industries – Opened new manufacturing plant for environmentally sustainable port machinery – Strengthens capacity to meet rising global demand for low-emission equipment.
- April 2023 – Jungheinrich AG – Partnered with digital logistics startups to develop AI-driven warehouse automation solutions – Expands technological leadership in automated intralogistics.
Frequently Asked Questions
What is the Cargo Handling Equipment Market?
The Cargo Handling Equipment Market encompasses the global industry involved in developing, manufacturing, and distributing machinery and equipment used for loading, unloading, and handling cargo at ports, airports, logistics centers, and warehouses. It supports efficient freight transportation and logistics operations worldwide.
What is the current market size of Cargo Handling Equipment Market?
As of 2026, the global Cargo Handling Equipment Market is valued at approximately USD 28.4 Billion, reflecting steady growth driven by the expansion of international trade, technological advancements, and infrastructure development across various regions globally.
What factors are driving the Cargo Handling Equipment Market?
Key drivers include increasing global trade volumes, modernization of port infrastructure, automation in cargo handling, and government initiatives to enhance freight transportation efficiency. Rising e-commerce activities also boost demand for advanced logistics and material handling solutions.
Which region dominates the Cargo Handling Equipment Market?
Asia-Pacific currently dominates the market, owing to rapid economic growth, extensive port development, and vast manufacturing sectors in countries like China, India, and Japan. These factors contribute significantly to regional market expansion and technological adoption.
Which segment is expected to grow the fastest?
Container handling equipment is projected to experience the highest growth rate, driven by increased containerization, port automation projects, and the rising need for efficient cargo throughput in both established and emerging markets globally.
Who are the leading companies operating in the Cargo Handling Equipment Market?
Major players include Konecranes, Liebherr Group, Cargotec Corporation,-Sennebogen, and Terex Corporation. These companies focus on innovation, technological advancements, and strategic acquisitions to strengthen market presence and meet rising demand.
Analyst Perspective
The cargo handling equipment market is approaching a mature stage, driven by steady infrastructure development and modernization across key global regions. Despite this maturity, significant opportunities remain, particularly in integrating advanced automation, robotics, and IoT-enabled solutions to enhance operational efficiency and safety. Technology evolution is expected to focus on smart equipment that offers real-time analytics, predictive maintenance, and optimized load management, which will attract substantial investments from logistics providers aiming to reduce costs and downtime.
Investors should prioritize technologies that facilitate process automation and reduce dependence on manual labor, especially in regions with labor shortages. The competitive landscape will intensify as major players innovate and expand into emerging markets, such as Asia-Pacific and Africa, which offer high growth potential due to ongoing urbanization and port infrastructure expansion. Strategic regional focus will be critical for long-term success, with substantial upside in regions poised for rapid industrial growth. Overall, the market’s evolution will hinge on technological advancements and regional adaptations tailored to local operational demands and regulatory frameworks.
