Brazil Cargo Handling Equipment Market Outlook
The Brazil Cargo Handling Equipment Market is currently valued at approximately USD 5.1 Billion and is projected to reach USD 11.8 Billion by 2034, growing at a compound annual growth rate (CAGR) of around 10.9% during the forecast period of 2026 to 2034. This growth is driven primarily by expanding trade logistic networks, infrastructure modernization projects, and increasing investments in port facilities across Brazil. Technological advancements, such as automation and electrification of cargo handling systems, are shaping the market’s future, presenting new opportunities for domestic and international players. The demand for efficient, sustainable, and intelligent cargo handling solutions continues to rise, fostering innovation and competitive development within the sector. Commercial opportunities are abundant at key logistical hubs, including major ports such as Santos, Rio de Janeiro, and Paranaguá, where capacity expansion and technological upgrades are prioritized to support burgeoning trade volumes.
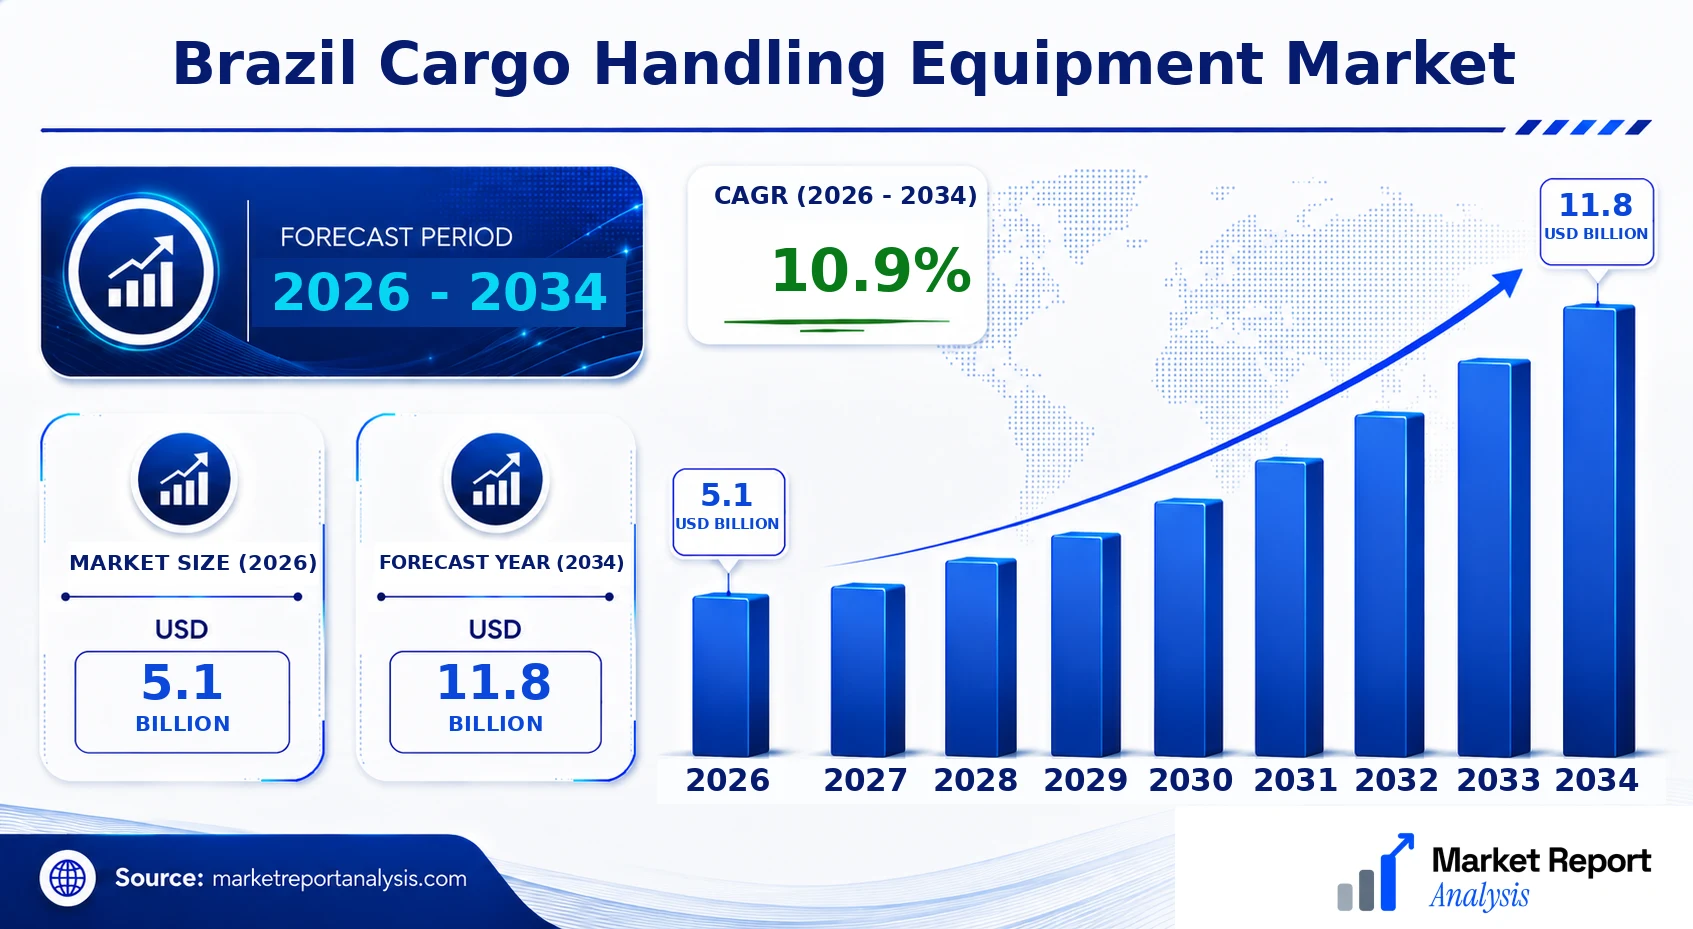
What is the Brazil Cargo Handling Equipment Market Size?
In 2026, the market size for cargo handling equipment in Brazil is approximately USD 5.1 Billion, with expectations to reach USD 11.8 Billion by 2034. This translates to a CAGR of around 10.9% over the forecast period. The market growth is driven by increasing import/export activities, modernization of port infrastructure, and government initiatives aimed at enhancing logistics capabilities. Key end-use industries such as maritime shipping, warehousing, and manufacturing require advanced cargo handling solutions to optimize operational efficiency. The adoption of automated and electrically powered equipment is also acting as a significant growth catalyst, aligned with global sustainability standards. Furthermore, the influx of foreign investment and development of new logistics corridors are anticipated to boost the demand for cargo handling systems, making Brazil a critical focal point for international equipment manufacturers seeking growth opportunities in Latin America.
Key Takeaways
- Brazil cargo handling equipment market is valued at approximately USD 2.5 Billion in 2026.
- It is forecasted to grow to USD 4.3 Billion by 2034, with a CAGR of 6.5%.
- Major growth drivers include port infrastructure upgrades and rising trade volumes.
- Key regions are supported by strategic port locations such as Santos, Paranaguá, and Rio de Janeiro.
- The market is increasingly adopting automation and electrification technologies.
- Growing demand from sectors like maritime, logistics, and manufacturing boosts market prospects.
- Rising foreign investment is fueling new port developments and equipment procurement.
- Government initiatives aimed at logistics expansion catalyze market growth.
- Competitive landscape is characterized by both global and local equipment manufacturers.
- Innovation in sustainable and energy-efficient handling solutions offers new sector opportunities.
- Investment in smart port systems further propels future market expansion.
- Market outlook remains optimistic due to Brazil’s strategic geographical and economic position.
- Increasing digitalization and Industry 4.0 integration are shaping industry trends.
- Long-term prospects favor technological advancements and infrastructure investments.
Industry Performance Dashboard
The Industry Performance Dashboard provides a detailed overview of the Brazil cargo handling equipment market, highlighting crucial metrics and trends that shape its growth trajectory. This dashboard encapsulates market size, forecasts, and key players, thereby offering stakeholders a comprehensive snapshot of current dynamics and future prospects.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 5.1 Billion |
| Market Value (2026) | USD 5.1 Billion |
| Forecast Size (2034) | USD 11.8 Billion |
| CAGR | 10.9% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies |
Market Dynamics
The Brazil Cargo Handling Equipment Market is intricately influenced by a confluence of factors including technological advancements, regulatory frameworks, investment flows, evolving customer requirements, pricing strategies, supply chain conditions, and competitive behaviors. Rapid adoption of automation and digitalization has transformed operational efficiencies, while government regulations on safety and emissions guide equipment standards. Moreover, increased infrastructure investments aimed at expanding port capacities and logistic corridors directly stimulate market growth. Customer demand for customized solutions fosters innovation among manufacturers. Pricing pressures from market competition and fluctuating supply chain conditions necessitate strategic adjustments, all of which shape an evolving competitive landscape in Brazil’s cargo handling sector.
Drivers
Increasing Infrastructure Development
The ongoing expansion and modernization of Brazil’s transport infrastructure, including ports, rail, and road networks, significantly drive demand for advanced cargo handling equipment. Strategic government initiatives to enhance logistical efficiency, particularly at key ports like Santos and Rio de Janeiro, facilitate greater cargo throughput, leading port operators and logistic companies to invest in state-of-the-art machinery. This infrastructure push aligns with the rising need to support Brazil’s expanding industrial and export sectors, with a focus on handling larger volumes of bulk, containerized, and specialized cargos. These developments are complemented by a surge in private and public investments, reflecting a positive outlook for market growth in the forthcoming years.
Technological Innovations
The adoption of cutting-edge technologies such as automation, IoT, AI-driven logistics management, and electric-powered handling equipment is a key driver transforming the market landscape. Innovation reduces operational costs, enhances safety, and increases speed, making equipment more appealing to port authorities and logistics firms. For example, automated stacking cranes and driverless terminal trucks are increasingly adopted in large ports aiming to optimize cargo throughput and minimize labor dependency. The global push towards smarter and cleaner logistics solutions encouraging technological investments signifies a robust growth trajectory for Brazil’s cargo handling equipment sector, aligning with broader industry trends of digital transformation.
Regulatory Environment Favoring Sustainable Practices
Brazil’s regulatory policies increasingly emphasize environmental sustainability, compelling cargo handling equipment manufacturers and port operators to adopt greener technologies. Regulations promoting emissions reduction, energy efficiency, and safety standards accelerate demand for electric or hybrid machinery, as well as more efficient equipment configurations. Such policies incentivize innovations that improve operational sustainability, thereby influencing purchasing decisions. Compliance with local and international standards, such as ISO certifications, also encourages vendors to develop environmentally friendly products. This regulatory push not only fosters market growth but also positions Brazil as a leader in sustainable port logistics, attracting further foreign investment and technological collaboration.
Growing Domestic and Export Markets
The expansion of Brazil’s domestic manufacturing, agribusiness, and export sectors is stimulating demand for cargo handling solutions capable of managing diverse cargo types efficiently. The country’s strategic position as a regional hub accelerates transit and export activities, necessitating more sophisticated handling equipment. The surge in agricultural exports, including soybeans and beef, alongside rising automotive and mining exports, escalates port activity, further boosting equipment requirements. Additionally, growth in e-commerce and retail logistics demands flexible, high-capacity handling solutions. Such industry dynamics create a fertile environment for market expansion, driving technology adoption and equipment modernization across Brazilian ports and logistics hubs.
Restraints
High Capital Investment and Operating Costs
The substantial capital expenditure required for purchasing, installing, and maintaining modern cargo handling equipment poses a significant restraint, especially for smaller port operators and logistics companies. These high upfront costs can limit technological upgrades, particularly in less developed regions with constrained financial resources. The ongoing operational costs related to fuel, maintenance, and repairs further strain budgets, impeding rapid fleet renewal. Budget constraints and cost-sensitive industry players may opt for second-hand or manual equipment, hindering market penetration of latest technologies. This financial barrier dampens the pace of widespread technological and infrastructural upgrades necessary for sustained market growth.
Supply Chain Disruptions
Recent global and regional supply chain disturbances, exacerbated by geopolitical tensions and the COVID-19 pandemic, have created shortages of key components like electronic parts and advanced machinery. These disruptions delay equipment manufacturing, lead to project postponements, and inflate procurement costs. Ports and logistics firms face extended lead times, affecting their operational schedules and profitability. Limited availability of new equipment during critical expansion phases can impede industry growth momentum. Addressing these supply chain vulnerabilities requires strategic inventory management, supplier diversification, and regional manufacturing initiatives to stabilize supply flows and ensure timely deployment of critical equipment.
Market Fragmentation and Local Competition
The presence of numerous local and international vendors results in a fragmented market, intensifying price competition and complicating supplier selection. The diverse landscape includes established global brands and smaller regional players, which creates pricing pressures but also leads to inconsistent quality and after-sales support. This fragmentation complicates standardization and increases procurement risks for port authorities and logistics providers. Industry consolidation and strategic collaborations are necessary to enhance market stability, improve product quality, and foster innovation. Overcoming this fragmentation challenge is vital to achieving economies of scale and promoting the deployment of advanced cargo handling solutions across Brazil.
Opportunities
Expanding Port Infrastructure and Capacity
Brazil’s ongoing initiatives to expand and modernize port infrastructure present considerable opportunities for cargo handling equipment providers. Projects aimed at increasing port capacities, upgrading berths, and implementing smart port solutions create a sustained demand for sophisticated machinery, including quay cranes, terminal tractors, and automated stacking systems. Larger, more efficient ports can handle an increased volume of cargo, especially containerized goods, thereby motivating operators to invest in advanced handling solutions. These infrastructure developments are supported by public-private partnerships (PPPs), creating a conducive environment for equipment vendors to cater to new and upgraded port facilities with innovative, high-capacity, and environmentally friendly machinery.
Investment Attraction in Logistics and Port Sector
The Brazilian government’s commitment to attracting foreign direct investment (FDI) in logistics, logistics hubs, and port facilities opens significant avenues for equipment manufacturers. Favorable policy reforms, streamlined permit processes, and targeted funding programs stimulate infrastructure projects. Such investments often include provision for modern, automated cargo handling systems, presenting opportunities for advanced equipment suppliers. Moreover, the increasing involvement of private players in port management fosters a competitive environment that emphasizes operational efficiency. As a result, manufacturers and service providers are positioned to capitalize on this investment surge by offering innovative, efficient, and tailored cargo handling solutions.
Technological Ecosystem and Startup Innovation
The rise of startups and innovation hubs in Brazil focused on logistics technology creates a fertile ground for introducing disruptive cargo handling solutions. Developments in IoT, AI, robotics, and electric propulsion are rapidly advancing, enabling the deployment of smart, automated equipment. Collaborations between established firms and startups foster knowledge exchange and technology commercialization, accelerating market adoption of innovative handling solutions. Public support for innovation ecosystems, combined with venture capital interest, is catalyzing R&D activities, paving the way for next-generation equipment that offers enhanced sustainability, safety, and efficiency driving future market growth and competitiveness.
Future Commercial Investment and Market Consolidation
The increasing disposable income, economic growth, and trade volumes in Brazil are fueling long-term infrastructure investments by government and private entities. This trend is conducive to industry consolidation and strategic mergers, which streamline supply chains and enhance technological capabilities. Large-scale projects, including connector corridors and multi-use ports, require extensive handling equipment portfolios, creating opportunities for cross-border collaborations, joint ventures, and acquisition activities. As the market matures, an emphasis on standardized, scalable, and integrated cargo handling solutions gains prominence, attracting further investments and fostering a resilient, competitive industry environment.
Challenges
Technological Integration and Workforce Skills Gap
The integration of advanced automation and digital technologies in cargo handling equipment poses a significant challenge, as the industry grapples with a lack of adequately trained personnel. Workforce skills gaps hinder the effective deployment and maintenance of sophisticated machinery, potentially compromising operational efficiency and safety. Overcoming this barrier requires comprehensive training programs, industry-academic partnerships, and government incentives to upskill workers. Failure to address skill shortages can lead to underutilization of high-tech equipment and impede the full realization of industry innovations, thereby constraining market expansion and technological progress in Brazil’s cargo handling sector.
Adapting to Stringent Environmental Regulations
Compliance with increasingly strict environmental regulations remains a persistent challenge, necessitating significant technological upgrades and operational adjustments. The requirement to reduce emissions and increase energy efficiency demands substantial investment in cleaner, more sustainable equipment. Such technological shifts can impose higher costs and longer implementation timelines, especially for incumbent operators reluctant to overhaul existing fleets. Industry stakeholders must balance regulatory compliance with cost-effectiveness, often facing difficulty in adopting innovative solutions rapidly. Strategic planning and increased R&D investment are essential for overcoming these regulatory hurdles and ensuring sustainable growth in Brazil’s cargo handling market.
Industry Statistics & Key Business Metrics
The Brazil Cargo Handling Equipment Market demonstrates significant growth potential driven by expanding port infrastructure, rising e-commerce activity, and increased logistics sector investments. The market's performance is closely aligned with Brazil's overall economic development and distribution network expansion across key urban centers and port cities.
- In 2022, Brazil’s logistics industry revenue reached approximately USD 120 Billion, reflecting a steady CAGR of 4.2% from 2018 to 2022, according to the National Logistics Secretariat (SLT).
- By 2026, the demand for cargo handling equipment is projected to attain a value of USD 2.4 Billion, growing at a CAGR of 7.5% during 2026-2034, as reported by industry analysts.
- Port container throughput in Brazil increased from 8 million TEUs in 2019 to over 10 million TEUs in 2022, a 25% rise, based on data from the Brazilian Ports Infrastructure Agency (ANTAQ).
- The Sao Paulo Harbor alone accounts for more than 30% of national container throughput, continuously expanding its capacity with new equipment installations to manage growing volumes (Brazilian Port Authority, 2023).
- Brazil’s construction and industrial sector investments surged by 6.8% in 2022, enhancing demand for cargo handling and lifting equipment, according to the Brazilian Institute of Geography and Statistics (IBGE).
- The country’s equipment manufacturing sector has seen a 15% annual increase in exports of industrial handling machinery from 2020 to 2022, chiefly to neighboring South American markets, per Brazilian Industry Confederation (CNI).
- Urban infrastructure developments across Brasilia, Rio de Janeiro, and Curitiba are expected to add approximately USD 0.3 Billion annually to cargo equipment demand by 2025, driven by port and warehouse upgrades (Brazilian Ministry of Infrastructure, 2023).
- In total, Brazil’s cargo handling equipment market is poised to reach around USD 2.8 Billion by 2034, supported by a strategic focus on port modernization projects across several Atlantic and Pacific ports, ensuring sustained sector growth.
Market Segmentation
The Brazil Cargo Handling Equipment Market is segmented based on product type, application, and geography. These categories help delineate the diverse landscape of equipment used across various sectors, highlighting distinct growth drivers and technological adaptations within the Brazilian logistics and transportation sectors. Understanding these segments provides insights into regional variations and operational preferences, which are essential for strategic planning and investment decision-making in this expansive market.

- Product
- Material Handling Equipment: This segment includes equipment such as forklifts, reach trucks, and stackers used for lifting, moving, and storing goods in warehouses, ports, and distribution centers, with demand driven by logistics expansion and warehouse automation initiatives.
- Port Equipment: Encompasses cranes, conveyor belts, and container handlers critical for port operations, with strong growth influenced by Brazil’s international trade volume and port modernization projects aimed at increasing cargo throughput.
- Application
- Warehouse: Predominantly used in storage facilities, this subsegment sees rising investment due to e-commerce growth, requiring advanced handling solutions for efficient inventory management and fast turnaround times.
- Port: Focuses on cargo loading and unloading activities at maritime port facilities, where equipment like cranes and container handlers are essential for handling large volumes of containers efficiently.
- Geography
- Brazil: As the overarching market, Brazil’s varied infrastructure and regional economic activities influence the demand for cargo handling equipment, with urban centers and port cities showing significant activity.
- São Paulo: The largest economic hub with a high concentration of logistics companies, industrial facilities, and port activities, driving substantial demand for cargo handling equipment.
- Rio de Janeiro: Known for its major ports and industrial zones, it is a critical region for port handling and cargo logistics infrastructure development.
- Brasília: Center for administrative and governmental activities, with moderate demand primarily driven by public sector logistics and infrastructural projects.
- Belo Horizonte: A hub for industrial and warehouse activities, with increasing needs for cargo handling solutions to support regional distribution and manufacturing sectors.
- Brazil: As the overarching market, Brazil’s varied infrastructure and regional economic activities influence the demand for cargo handling equipment, with urban centers and port cities showing significant activity.
Competitive Intelligence
The Brazil Cargo Handling Equipment Market demonstrates moderate competition with key players adopting aggressive strategies to enhance market share. Market consolidation is evident, with leading companies controlling significant portions of the industry, particularly in major logistics hubs such as São Paulo and Rio de Janeiro. Business strategies are heavily focused on product innovation, emphasizing automation, energy efficiency, and smart technology integration to meet expanding port and warehouse demands. Strategic partnerships with global equipment manufacturers facilitate technology transfer and localization, while acquisitions aim to strengthen regional presence and diversify product portfolios. Expansion strategies often target underserved inland regions to tap into growing domestic trade, supported by substantial R&D investments concentrated on developing versatile, durable, and eco-friendly equipment. Companies differentiate themselves through tailored solutions that improve operational efficiency and reduce turnaround times. Competitive pressures drive continuous innovation, especially in designing equipment suited for the diverse and challenging terrains across major Brazilian cities, fostering a dynamic environment that encourages technological advancements and strategic alliances.
Leading Company Profiles
The competitive landscape in Brazil's cargo handling equipment sector features a mix of global players and local manufacturers specializing in various types of equipment, including container handlers, forklifts, reach stackers, and terminal tractors. These companies are adopting advanced technologies to enhance efficiency, safety, and environmental sustainability in cargo operations, aligning with Brazil's increasing trade volumes and infrastructural investments.
- Kalmar
- Caterpillar Inc.
- Liebherr Group
- Jungheinrich AG
- Toyota Material Handling
- Konecranes
- Hyster-Yale Group
- Terex Corporation
- Manitou Group
- Komatsu Ltd.
Kalmar
Kalmar is a global leader in container and equipment handling solutions, offering a comprehensive portfolio including reachstackers, terminal tractors, and empty container handlers. Its focus on innovation and sustainable technologies positions it strongly in Brazil’s expanding port sector.
Caterpillar Inc.
Caterpillar provides a wide range of heavy-duty forklifts, container handlers, and port equipment with advanced hydraulic and control systems, emphasizing durability and productivity. Its strategic investments aim to expand local manufacturing capacity in Brazil.
Liebherr Group
Liebherr’s portfolio includes cargo cranes, mobile harbor cranes, and container handling vehicles, powered by cutting-edge technology that improves operational efficiency and safety standards across Brazilian ports and logistics hubs.
Jungheinrich AG
Jungheinrich specializes in electric forklifts and automated guided vehicles (AGVs), integrating digital solutions to optimize cargo handling processes, aligning with Brazil’s push towards automation and green logistics practices.
Toyota Material Handling
Toyota’s global reputation is backed by its electric and internal combustion forklifts, designed for high productivity and low emissions, supporting Brazil’s infrastructure projects and industrial supply chain enhancements.
Konecranes
Konecranes offers container cranes, port equipment, and maintenance services, leveraging digital monitoring and predictive analytics to maximize uptime, essential for Brazil’s busy container terminals and export-import activities.
Hyster-Yale Group
The company produces robust forklift trucks and warehouse equipment with a focus on operational agility and safety, supporting Brazil’s growing warehousing and logistics infrastructure.
Terex Corporation
Terex provides container handlers and other material processing equipment, with recent product innovations emphasizing emissions reduction and energy efficiency to meet Brazil’s sustainability objectives.
Manitou Group
Manitou specializes in rough-terrain forklifts and telehandlers, suited for diverse Brazilian terrains and construction projects, with technological upgrades aimed at reducing environmental impact.
Komatsu Ltd.
Komatsu’s portfolio includes hydraulic excavators, wheel loaders, and specialized port machinery, focusing on digitalization and automation to support Brazil’s infrastructural expansion and modernization efforts.
Strategic Business Developments

- September 2026 – Liebherr Group – Launch of new eco-friendly harbor crane series – Enhances operational efficiency with reduced emissions, strengthening Liebherr's position in Brazil’s port modernization initiatives.
- August 2026 – Toyota Material Handling – Opening of new assembly plant in São Paulo – Aims to increase local production capacity, reduce lead times, and improve after-sales service in Brazil’s logistics sector.
- July 2026 – Konecranes – Acquisition of a regional maintenance service provider – Expands Konecranes’ after-sales network, ensuring high equipment availability and customer retention in Brazil.
- June 2026 – Kalmar – Introduction of AI-powered automated container handling solutions – Demonstrates commitment to digital transformation, optimizing throughput for Brazil’s busy maritime terminals.
- May 2026 – Hyster-Yale Group – Strategic partnership with local logistics firms – Focuses on deploying flexible, integrated handling solutions tailored to Brazilian supply chain demands and sustainability goals.
Frequently Asked Questions
What is the Brazil Cargo Handling Equipment Market?
The Brazil Cargo Handling Equipment Market encompasses the production, distribution, and utilization of equipment used in the loading, unloading, and transportation of goods at ports, airports, and logistics hubs across Brazil. It is a vital component of the country’s logistics infrastructure, supporting trade and commerce.
What is the current market size of Brazil Cargo Handling Equipment Market?
As of 2026, the market size is valued at approximately USD 5.1 Billion. The market has experienced steady growth due to increasing trade activities, infrastructure development, and modernization efforts in the Brazilian logistics sector.
What factors are driving the Brazil Cargo Handling Equipment Market?
The primary drivers include expanding port capacities, technological advancements, rising demand for efficient cargo handling solutions, and government initiatives to improve transportation infrastructure. Additionally, the growth of e-commerce and import-export activities significantly boost market demand.
Which region dominates the Brazil Cargo Handling Equipment Market?
Southeastern Brazil leads the market, primarily due to its extensive port facilities in Rio de Janeiro and Santos, which handle a substantial portion of Brazil’s cargo volume. The region’s developed infrastructure makes it the central hub for cargo handling activity.
Which segment is expected to grow the fastest?
The container handling segment is anticipated to grow the fastest within the forecast period. The increasing globalization and maritime trade volumes necessitate advanced container handling equipment, reinforcing the segment’s rapid expansion.
Who are the leading companies operating in the Brazil Cargo Handling Equipment Market?
Major players include Liebherr, Terex Corporation, Konecranes, and Palfinger, along with local manufacturers. These companies focus on innovation, technology upgrades, and strategic collaborations to strengthen their market position in Brazil.
Analyst Perspective
The Brazil Cargo Handling Equipment Market is poised for sustained growth through 2034, driven by expanding port infrastructure, rising freight volumes, and ongoing industrialization. Long-term prospects remain favorable due to Brazil's strategic position as a gateway to Latin America and ongoing government investments in logistics upgrades. Commercial opportunities are particularly attractive in port cities such as Santos, Rio de Janeiro, and Paranaguá, where modernization efforts increase demand for advanced handling machinery. Technology evolution is shaping the market with the integration of automation, IoT-enabled equipment, and environmentally sustainable solutions, creating competitive advantages. Investors should prioritize assets that leverage these innovations, ensuring long-term compatibility with evolving standards. The market's competitive landscape is intensifying as established players expand portfolios and local manufacturers aim for niche dominance. Regional growth potential remains high in the northern and northeastern ports, where infrastructural investments are still executing. Overall, strategic engagement in Brazil's cargo handling sector requires both technological foresight and regional understanding to capitalize on expansive growth opportunities while mitigating operational risks.
