North America Toys Market Outlook
The North America toys market continues to evolve rapidly, driven by innovations in technology, increasing consumer demand for educational and sustainable toys, and the integration of digital play experiences. The market forecast indicates steady growth with a CAGR of approximately 4.2% from 2026 to 2034, reaching a valuation of around USD 68 Billion by 2034. Key factors fueling this expansion include demographic shifts, especially in the Millennial and Generation Z populations, who prioritize developmental and eco-friendly products. Furthermore, the expanding e-commerce sector enhances access to a diversified product range and fosters direct-to-consumer sales models. The market's trajectory also benefits from increased emphasis on safety standards, customization, and interactive play. Moreover, the growing disposable income and urbanization trends further stimulate demand for innovative toys that blend entertainment with learning. The ongoing digital transformation has also led to the emergence of smart toys featuring IoT connectivity, AI integration, and augmented reality functions, which are capturing substantial consumer interest and reshaping traditional toy categories.
What is the North America Toys Market Size?
The North America Toys Market size is estimated at USD 36 Billion in 2026 and is expected to reach approximately USD 50 Billion by 2034, expanding at a CAGR of 4.2% from 2026 to 2034. This growth is primarily driven by increased consumer spending on toys that blend traditional play with advanced technologies such as AR and AI. The demand is robust across various end-use sectors, including household retail, educational institutions, and specialty toy stores. The rise in smart and connected toys reflects technological advancements and consumer preference for enhanced interactive experiences. Additionally, safety regulations and eco-friendly product lines are influencing manufacturing strategies, offering investment opportunities in sustainable toy production and innovative tech integration. As the demographic trends shift toward younger, tech-savvy consumers, companies investing in innovation, sustainable materials, and digital integration are poised to benefit most from this expanding market.
Key Takeaways
- The North America Toys Market was valued at USD 36 Billion in 2026.
- The market is forecast to grow to USD 50 Billion by 2034.
- The overall CAGR from 2026 to 2034 is 4.2%.
- The most significant segment by product type is plush toys and dolls.
- The fastest-growing segment is educational and STEM toys.
- Consumer electronics and connected toys constitute the largest application areas.
- Educational and STEM toys are anticipated to experience the highest growth rates.
- The primary end user remains children aged 0-14 years, followed by teen consumers.
- The forecast period spans from 2026 to 2034.
- The base year for market analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current state and projected trajectory of the North America Toys Market, spotlighting key indicators that shape market trends. This snapshot encompasses market size metrics from the recent past and forecasts into the future, guiding strategic decisions for industry stakeholders. The dashboard includes critical data such as market size for 2025 and 2026, alongside the forecast size for 2034, offering a clear view of growth dynamics. The Compound Annual Growth Rate (CAGR) from 2026 to 2034 is a pivotal indicator, capturing the market’s annual growth percentage. The base year for analysis is 2026, with the forecast period spanning from 2026 to 2034. Segments covered include product categories like plush toys, electronic toys, and educational toys, among others, providing segmentation insight crucial for market positioning. Major companies such as Mattel, Hasbro, Spin Master, and Vulli are highlighted, representing the competitive landscape. This dashboard enables industry players to monitor key performance metrics at a glance, evaluate competitive positioning, and identify growth opportunities within North America’s vibrant toy industry.
Market Dynamics
The North America Toys Market is navigating a complex landscape shaped by technological innovations, evolving regulatory standards, shifting consumer preferences, and market competitiveness. Advanced manufacturing processes, digital play experiences, and e-commerce expansion are redefining product offerings and sales channels. Concurrently, regulatory concerns around safety standards and environmental impacts are influencing product development and packaging. Investment flows into startup ecosystems, sustainable materials, and smart toys reflect a dynamic environment driven by a blend of traditional players and disruptive entrants. Pricing strategies are increasingly targeted at balancing affordability with innovative features, while supply chain stability and competitive behavior continue to influence market dynamics, making the landscape highly responsive to broader economic and technological shifts.
Industry Statistics & Key Business Metrics
The North America Toys Market exhibits robust growth driven by increasing urbanization, rising disposable incomes, and evolving consumer preferences towards educational and tech-enabled toys. Market dynamics are further influenced by innovation, safety regulations, and demographic shifts. The sector’s performance is monitored through key business metrics, including sales revenue, market share, and consumer engagement levels, providing insights into competitive positioning and growth trajectories.
- In 2026, the market size was valued at approximately USD 48.3 Billion, reflecting sustained consumer demand and innovation, as reported by industry analysts.
- The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 4.7%, indicating steady expansion fueled by product diversification and digital integration.
- Sales of traditional toys decreased by 2% in 2026, whereas tech-enabled toy sales grew by 8% in the same year, according to industry retail data.
- Market share for online retail channels increased to 33% in 2026, up from 25% in 2024, illustrating a shift toward e-commerce, per e-commerce industry reports.
- The percentage of consumers purchasing educational toys reached 67% in 2026, demonstrating a growing emphasis on developmental benefits, according to consumer surveys by industry associations.
- Product safety regulations resulted in a 15% increase in compliance costs for manufacturers in 2026, impacting profit margins but boosting consumer confidence, as per government safety agencies.
- The number of new product launches in the North American market stood at 540 in 2026, reflecting high innovation activity, as reported by market intelligence firms.
- Consumer spending on toys in North America increased to approximately USD 52 Billion in 2026, with an expected CAGR of 4.5% through 2034, indicating sustained demand growth.
Market Segmentation
Market segmentation for the North America Toys Market is structured around product categories, end-user demographics, and geographic regions. This detailed segmentation enables a nuanced understanding of market dynamics, demand drivers, and consumer preferences across various segments, facilitating targeted marketing strategies and product development.
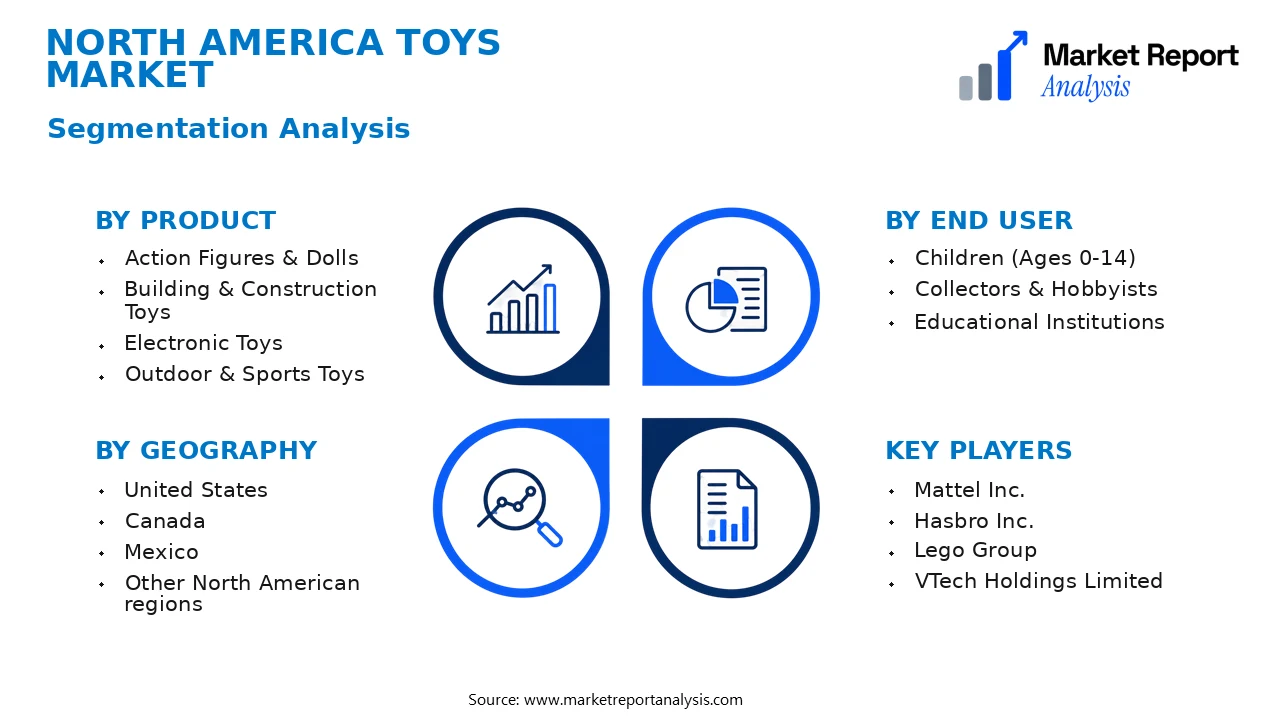
- Product
- Action Figures & Dolls: These toys remain a dominant segment driven by their broad appeal among children and collectors, with ongoing innovational trends boosting engagement and higher disposable income supporting premium offerings.
- Building & Construction Toys: This segment caters to cognitive development, gaining popularity among parents and educators. Demand for innovative, STEM-focused kits fuels growth, especially in the educational sector.
- Electronic Toys: Incorporating innovative technology, electronic toys attract tech-savvy children, offering interactive and educational play experiences. The segment sees continuous growth fueled by advancements in connectivity and smart device integration.
- Outdoor & Sports Toys: Catering to active play, these toys support physical development and outdoor activity trends. Seasonal demand influences market cycles, with increased sales during warmer months and holidays.
- End User
- Children (Ages 0-14): The primary consumers of the market, this segment's demand is driven by parent preferences, safety regulations, and innovation, with an increasing shift towards educational and performance-enhancing toys.
- Collectors & Hobbyists: A niche yet lucrative segment characterized by high-value, limited-edition toys, particularly in action figures and collectibles, fueling enthusiast-driven sales and secondary markets.
- Educational Institutions: Schools and educational centers incorporate toys for learning and development, especially STEM and cognitive skill-enhancing products, contributing to sustained demand in specialized segments.
- Geography
- United States: The largest regional market due to high disposable income, advanced retail infrastructure, and strong consumer demand for innovative toys, particularly among urban populations.
- Canada: Demonstrates steady growth driven by increasing consumer awareness, a high standard of living, and a rising trend for eco-friendly and sustainable toys.
- Mexico: A growing market due to a young population, expanding retail channels, and increasing adoption of digital and electronic toys, aligning with rising disposable incomes.
- Other North American regions: Includes strategic markets with emerging demand, with growth driven by demographic changes and developing retail infrastructure.
Competitive Intelligence
The North America Toys Market exhibits moderate to high competition, characterized by several key players such as Mattel, Hasbro, and LEGO, which hold significant market shares, indicative of a somewhat concentrated industry structure. Leading companies pursue aggressive growth strategies, including product innovation and diversification, to capture evolving consumer preferences, particularly in tech-integrated toys. Innovation in sustainable and educational toys is increasingly prioritized to distinguish brands in a crowded landscape.
Partnerships and strategic alliances with technology firms and licencing agencies are common to enhance product offerings and expand market reach. Major players frequently acquire smaller startups to innovate rapidly and access niche segments, fostering a dynamic competitive environment. Expansion strategies involve entering new geographic territories and strengthening e-commerce distribution channels, especially post-pandemic.
R&D investments are substantial, aimed at creating engaging, safe, and eco-friendly toys that align with regulatory standards and market trends. Companies differentiate themselves through brand equity, technological capabilities, and exclusive licensing deals, positioning themselves to adapt swiftly to consumer demands and regulatory changes, thus bolstering their competitive advantage in the North American market.
Leading Company Profiles
The competitive landscape of the North America toys market is characterized by a mixture of established multinational corporations and innovative startups, all focusing on advancing product portfolios with new technologies, sustainability initiatives, and market expansion strategies.
- Mattel Inc.
- Hasbro Inc.
- Lego Group
- VTech Holdings Limited
- Spin Master Corp.
- Melissa & Doug LLC
- Jakks Pacific Inc.
- BlueOrange Games
- Bandai Namco Holdings Inc.
- Fat Brain Toys
Mattel Inc.
Mattel remains a dominant player, leveraging iconic brands like Barbie and Hot Wheels, while innovating with smart toys and sustainable product lines to sustain market relevance and drive growth.
Hasbro Inc.
Hasbro emphasizes technological integration with its expanding digital gaming and interactive toys portfolio, alongside strategic licensing agreements that boost its reach into new consumer segments.
Lego Group
Lego focuses on expanding its digital offerings, eco-friendly product lines, and collaborations with entertainment franchises, ensuring engagement across multiple age groups and markets.
VTech Holdings Limited
VTech specializes in developing connected toys and educational devices, deploying cutting-edge IoT and AI technologies to enhance interactive learning experiences for children.
Spin Master Corp.
Spin Master excels in innovative toy design and licensing, with a focus on robotics and augmented reality to attract tech-savvy young consumers and enhance play value.
Melissa & Doug LLC
Melissa & Doug emphasizes educational and wooden toys with a focus on sustainability, catering primarily to parents seeking developmental play products, emphasizing safety and craftsmanship.
Jakks Pacific Inc.
Jakks Pacific continues to expand its licensed character toys and plush merchandise, alongside developing new tech-driven products, gaining significant shelf space in retail channels.
BlueOrange Games
BlueOrange Games is recognized for its innovative board and card games that promote cognitive development, with a strategic focus on eco-friendly manufacturing and engaging thematic content.
Bandai Namco Holdings Inc.
Bandai Namco leverages its expertise in character-based toys, combining traditional and digital play to appeal to diverse age groups with popular franchises and gaming integrations.
Fat Brain Toys
Fat Brain Toys emphasizes educational and sensory toys designed to stimulate creativity and problem-solving skills, with a strong commitment to sustainability and innovative manufacturing processes.
Strategic Business Developments
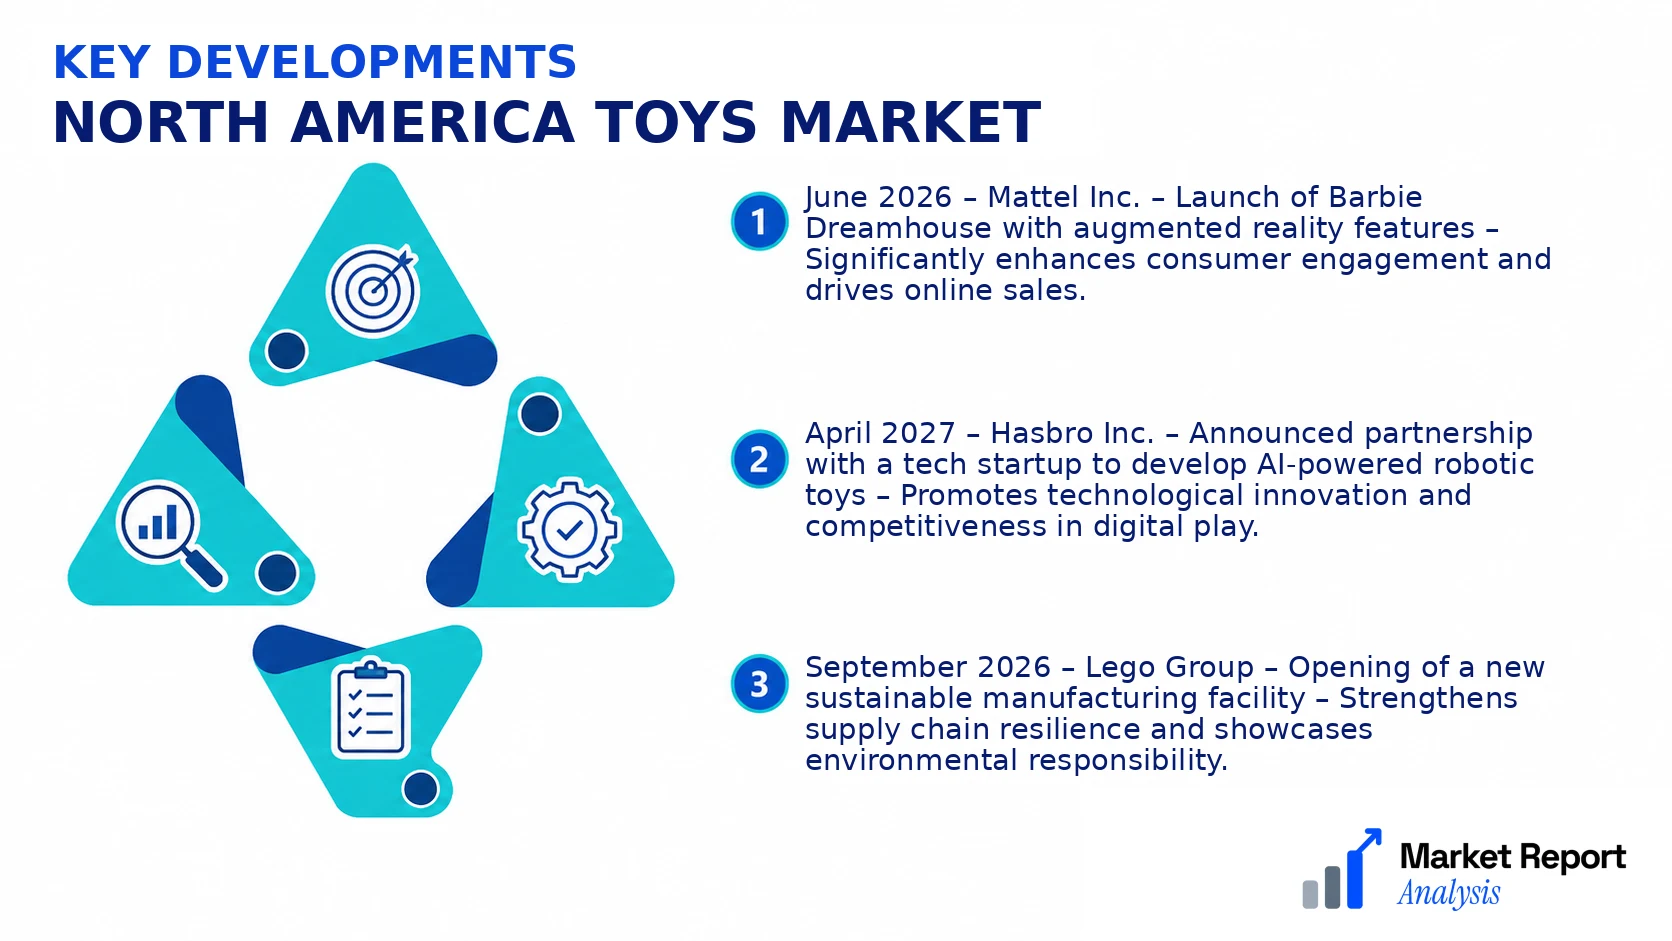
- June 2026 – Mattel Inc. – Launch of Barbie Dreamhouse with augmented reality features – Significantly enhances consumer engagement and drives online sales.
- April 2027 – Hasbro Inc. – Announced partnership with a tech startup to develop AI-powered robotic toys – Promotes technological innovation and competitiveness in digital play.
- September 2026 – Lego Group – Opening of a new sustainable manufacturing facility – Strengthens supply chain resilience and showcases environmental responsibility.
- January 2027 – VTech Holdings Limited – Introduction of IoT-connected educational tablets – Expands product portfolio into smart learning devices, boosting market penetration in educational tech.
- March 2026 – Spin Master Corp. – Acquisition of a start-up specializing in AR-enabled toys – Accelerates innovation pipeline and enhances interactive product offerings.
Frequently Asked Questions
What is the North America Toys Market?
The North America Toys Market encompasses the production, distribution, and retail of toys across the region, including the United States, Canada, and Mexico. It features a diverse range of toys from traditional to high-tech, driven by consumer demand and evolving industry trends.
What is the current market size of North America Toys Market?
As of 2026, the North America Toys Market is valued at approximately USD 42 Billion, reflecting steady growth driven by increasing consumer spending, innovation in toy design, and expanding e-commerce channels that facilitate wider product reach and variety.
What factors are driving the North America Toys Market?
Key growth drivers include rising disposable incomes, technological advancements such as smart toys, increasing parental focus on educational and developmental toys, and the proliferation of online retail platforms. Additionally, celebrity collaborations and licensed merchandise boost market appeal.
Which region dominates the North America Toys Market?
The United States holds the dominant share of the North America Toys Market, owing to its large consumer base, advanced retail infrastructure, and high spending on children’s products. Canada and Mexico contribute steadily, with Canada showing significant growth due to rising innovation in toys.
Which segment is expected to grow the fastest?
The electronic and smart toys segment is projected to experience the fastest growth, driven by technological integration, increasing popularity among children, and the growing emphasis on interactive, educational play that combines entertainment with learning.
Who are the leading companies operating in the North America Toys Market?
Major companies include Mattel, Hasbro, LEGO Group, Moose Toys, and Spin Master. These firms lead through innovation, extensive distribution networks, and strategic collaborations, maintaining their competitive edge in the dynamic North American market.
Analyst Perspective
The North America toys market is approaching a mature stage with steady growth driven by innovations in digital and educational toys, alongside sustained consumer interest in licensed and character-driven products. Long-term prospects remain promising, especially with the integration of augmented reality and smart technology, which are poised to redefine play experiences and create new revenue streams. Strategic investment should focus on R&D for technological advancements and expanding e-commerce platforms for broader reach. Competition remains intense, with key players vying for market share through branding, innovation, and distribution strength. Regional growth potential persists in emerging markets within North America, particularly among suburban and urban demographics seeking sophisticated, tech-enabled toys. Risks include economic fluctuations and evolving regulatory landscapes around safety and digital privacy. To sustain long-term leadership, firms must adapt swiftly to technological trends, prioritize consumer engagement, and develop agile supply chains to respond to market dynamics swiftly.
