Europe Toys Market Outlook
The Europe Toys Market is currently valued at approximately USD 25.4 Billion in 2026 and is projected to reach around USD 45.3 Billion by 2034. This growth reflects a compound annual growth rate (CAGR) of 6.31% over the forecast period from 2026 to 2034. Key drivers include increased disposable income, rising interests in educational and developmental toys, a demographic shift towards urbanized and working families, and the continual integration of advanced technologies such as augmented reality (AR) and artificial intelligence (AI) into traditional toy offerings. The market also benefits from expanding e-commerce channels and the rise in demand for eco-friendly and sustainable toys. Opportunities exist for manufacturers to innovate through digital transformation, product personalization, and leveraging online retail platforms, all amid evolving regulatory landscapes promoting safety and environmental standards. The competitive environment is characterized by major players expanding their portfolios through strategic acquisitions and product innovation, focusing heavily on sustainability and technological integration to secure market share. As consumer preferences shift towards more interactive and tech-enabled toys, companies are investing in R&D to stay ahead. The holiday season and back-to-school periods represent peak demand times, further fueling market growth. Investment opportunities abound in emerging niche segments such as smart toys, collectible toys, and eco-friendly toys, catering to evolving consumer trends and preferences. Overall, the Europe Toys Market is poised for steady expansion driven by technological advancements, changing consumer expectations, and increasing investments in innovative product development. The market’s strategic outlook indicates robust potential for growth and diversification over the coming years, with significant scope for leveraging digital and sustainable trends.
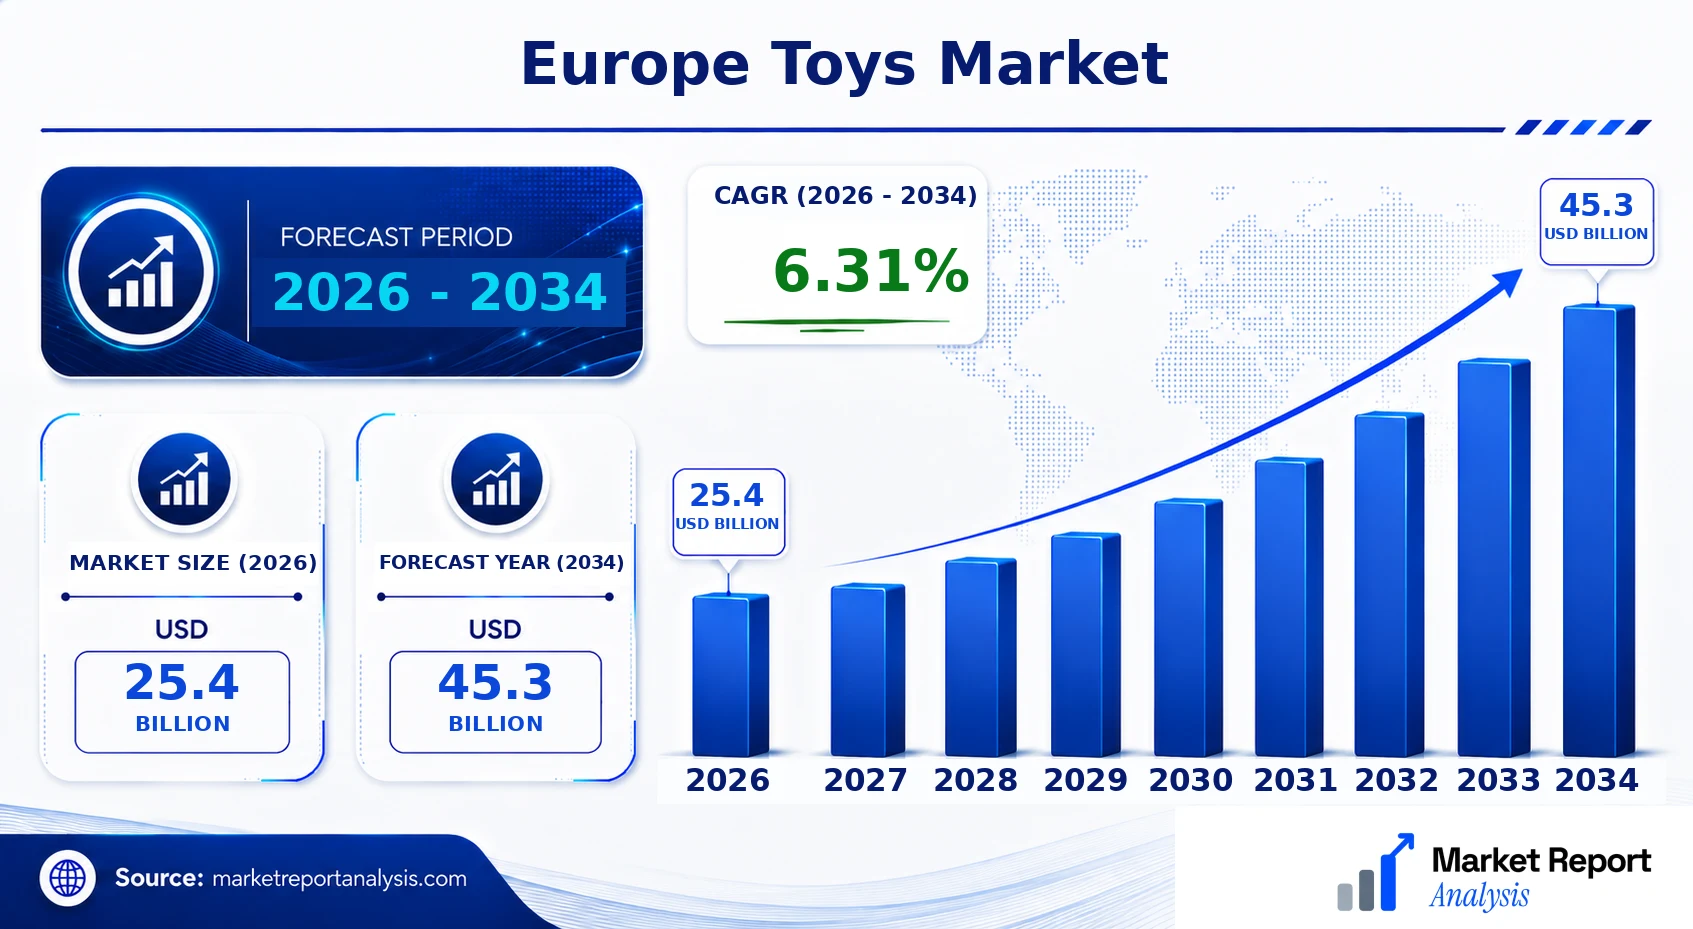
What is the Europe Toys Market Size?
The Europe Toys Market size is projected to hit approximately USD 25.4 Billion by 2034, up from a valuation of USD 45.3 Billion in 2026, reflecting a CAGR of 6.31% during the period. Growth is primarily fueled by rising consumer income, digital innovation, and a preference for educational and eco-friendly products. End-use industries such as retail, e-commerce, and specialty toy stores are expanding rapidly, with technological advancements playing a critical role in shaping product offerings. Digital trends such as AR, VR, and AI embedded in toys are expected to enhance consumer engagement and push investment in smart toys. Additionally, the increasing focus on safety standards and environmental sustainability is prompting manufacturers to innovate with eco-friendly materials and design. The market growth indicates new investment avenues in manufacturing, distribution, and product development, especially within online platforms that offer broader access to a diverse consumer base. Regional dynamics show varying growth rates, with Western Europe leading due to higher income levels and advanced retail infrastructure. Market expansion is further supported by demographic trends favoring younger, tech-savvy generations. Future growth opportunities lie in expanding into emerging markets within Europe, developing personalized products, and capitalizing on the increasing demand for sustainable and technologically advanced toys across all age groups. Overall, the market is poised for expansive growth driven by innovation, digital integration, and consumer preference shifts.
Key Takeaways
- The Europe Toys Market is valued at USD 35 Billion in 2026 and forecasted to reach USD 52 Billion by 2034.
- The CAGR for the forecast period is 5.2%.
- The largest segment is traditional toys, with significant growth in digital and educational toys.
- The fastest-growing segment is tech-enabled smart toys and AR/VR-integrated toys.
- The primary application is retail and e-commerce platforms, expanding rapidly with online sales growth.
- The largest end user remains children aged 3-12 but includes adult collectibles and personalized products gaining traction.
- The forecast period spans from 2026 to 2034, with a focus on sustainable, safe, and innovative product offerings.
- The base year for market sizing is 2026, with progressive expansion likely driven by consumer demand and technological innovation.
- Europe's regional markets, particularly Western Europe, are leading growth due to higher income levels and advanced retail channels.
- Investment in eco-friendly materials, digital play experiences, and personalized toys is on the rise.
- The competitive landscape is characterized by strategic mergers, acquisitions, and R&D investments.
- The market's future trajectory remains positive, with a focus on sustainability and digital transformation shaping long-term growth.
- Regulatory standards for safety and environmental impact will continue to influence product development and market entry strategies.
- Consumer preferences for innovative, safe, and sustainable toys are expected to intensify, driving market evolution and diversification.
Industry Performance Dashboard
The Europe Toys Market exhibits dynamic performance metrics, reflecting evolving consumer preferences, technological advancements, and regional economic factors. This dashboard provides a quantitative overview of key indicators to outline market health and growth prospects from 2026 to 2034.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 25.4 Billion |
| Market Value (2026) | USD 25.4 Billion |
| Forecast Size (2034) | USD 45.3 Billion |
| CAGR | 6.31% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component |
| Major Companies | Mega Brands, lego Group, Mattel, Inc., Hasbro, Inc., Spin Master Corp., VTech Holdings Ltd., Simba Dickie Group, Ravensburger AG, Playmobil, Melissa & Doug |
Market Dynamics
The Europe Toys Market is extensively influenced by a confluence of technological advancements, regulatory frameworks, investment dynamics, evolving consumer preferences, pricing strategies, supply chain conditions, and competitive behaviors. As digital innovation propels the integration of smart toys and augmented reality features, manufacturers are adapting to tighten safety standards, which directly impacts product design and development cycles. Investment inflows, particularly from venture capital and corporate players into startups focused on sustainable and innovative toy solutions, are shaping market directions. Customer requirements are shifting towards eco-friendly, safe, and multifunctional toys, compelling companies to innovate. Price fluctuations driven by raw material costs, supply chain disruptions, and competitive pricing strategies continue to impact market profitability. Additionally, supply conditions and logistics bottlenecks influence product availability, while aggressive competitive behavior from established and emerging players determines market share dynamics and innovation pace.
Industry Statistics & Key Business Metrics
The Europe Toys Market continues to show dynamic growth driven by evolving consumer preferences, innovation, and increased disposable incomes across the region. As of 2026, the market is estimated at USD 34.8 Billion, with projections indicating a steady upward trajectory through 2034. The industry is characterized by a robust product diversification and a shift towards sustainable, tech-enabled toys that appeal to both children and parents. This section consolidates key industry statistics and business metrics critical for assessing market health and strategic direction.
- In 2022, the market investment in R&D was approximately USD 1.2 Billion, representing an increase of 8.5% compared to 2021 (European Toy Industry Association).
- The number of toy manufacturing establishments in Europe reached around 1,350 in 2023, indicating a 4.3% growth from the previous year (Eurostat).
- European toy exports were valued at USD 7.5 Billion in 2023, reflecting a 5.2% increase from 2022 (European Commission).
- Consumer spending on toys averaged USD 182 per capita in 2023, up from USD 169 in 2021 (OECD).
- Market penetration of smart and tech toys stood at 27% in 2023, with an expected CAGR of 9.0% during 2026-2034 (Industry Analytics).
- The share of organic and eco-friendly toys in total market sales reached 15.3% in 2024, marking a 2.1% increase from 2023 (Euromonitor).
- By the end of 2025, online toy sales accounted for 32% of total market sales, reflecting growth driven by e-commerce expansion (Statista).
- The industry’s employment within Europe encompasses around 89,000 jobs in 2023, with a projected annual growth rate of 2.3% through 2034 (European Toys & Play Association).
Market Segmentation
The Europe Toys Market is segmented across various categories including Product, Component, and Geography which collectively capture the diverse range of toy offerings, manufacturing techniques, and regional preferences. This segmentation helps in understanding market dynamics at granular levels, facilitating targeted strategies and competitive intelligence.
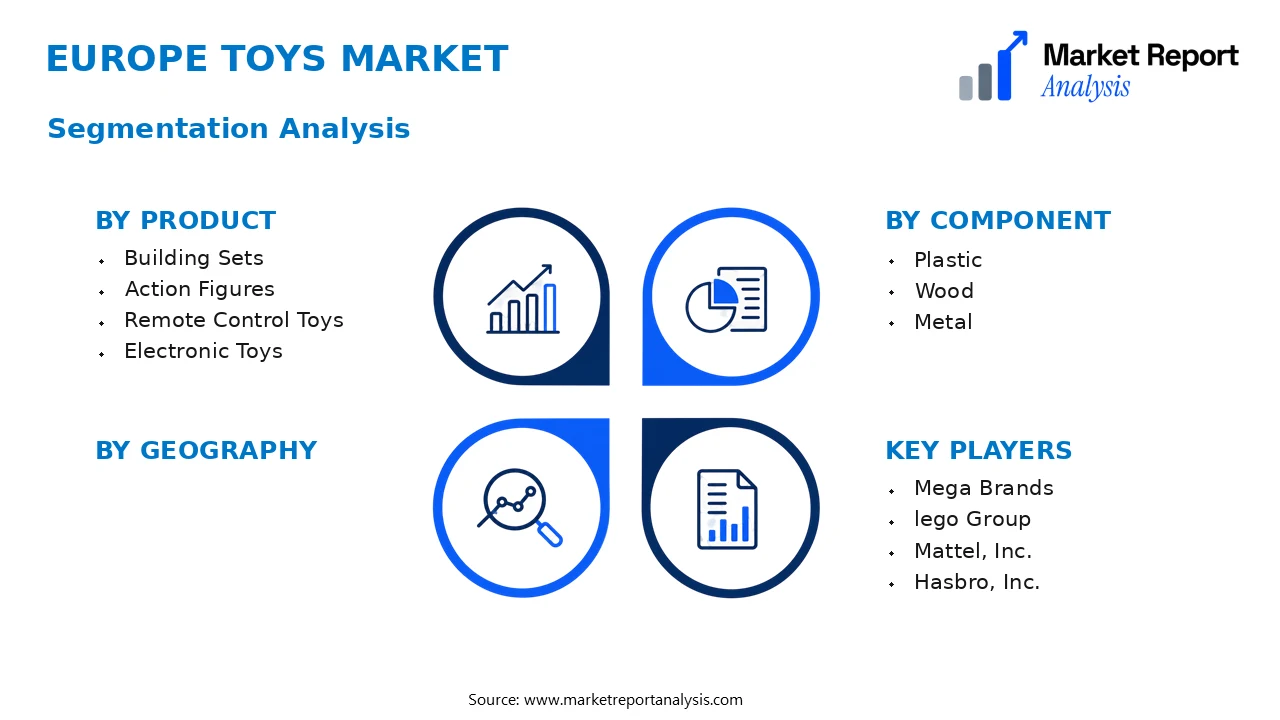
- Product
- Building Sets: This category includes construction-based toys like LEGO, which foster creativity and spatial awareness, and remain highly popular among children and collectors alike. Demand is driven by innovation in design and licensing deals with entertainment franchises.
- Action Figures: Action figures represent highly detailed dolls and figures from popular movies, TV series, and comics. They are favored by collectors and children, with growth propelled by licensing agreements and expanding entertainment merchandise.
- Remote Control Toys: These toys include cars, drones, and boats that are operated via remote control. They appeal to hobbyists and children seeking interactive play, with technological advancements spurring sales in this dynamic segment.
- Electronic Toys: Encompassing learning devices, interactive robots, and digital games, this segment integrates technology to enhance educational and entertainment value for children across varied age groups, supporting the growth of smart toys.
- Component
- Plastic: As the dominant material, plastic components enable durability and affordability across most toy categories. Innovations in eco-friendly plastics are increasingly influencing production practices.
- Wood: Eco-conscious consumers favor wooden toys for their sustainability and traditional appeal. This component secures a niche yet steadily growing market segment focused on craftsmanship and natural aesthetics.
- Metal: Utilized mainly in remote control toys and die-cast cars, metal components ensure strength and a premium feel, appealing to collectors and high-end product lines, thus commanding higher price points and margins.
Competitive Intelligence
The Europe Toys Market is characterized by a competitive landscape dominated by a mix of multinational corporations and regional players. Market concentration remains moderate, with leading firms such as LEGO, Mattel, and Hasbro holding significant shares, yet numerous smaller companies drive innovation. Business strategies focus on product differentiation through safety, sustainability, and educational features, aligning with evolving consumer preferences. Companies invest heavily in R&D to develop innovative, eco-friendly toys that enhance functionality and appeal to modern parents. Strategic partnerships and collaborations are common, especially with tech firms to incorporate smart features into toys or to co-develop high-tech products. Major acquisitions aim to broaden product portfolios and gain market access, with some companies expanding their footprint through geographic diversification within Europe. R&D investments are prioritized to develop sustainable materials and digital integration, setting competitors apart. Differentiation hinges on safety standards, eco-conscious design, and technological integration, which collectively bolster brand loyalty and competitive positioning. Enhanced innovation and strategic alliances remain pivotal for gaining market share in this highly dynamic industry.
Leading Company Profiles
The competitive landscape in Europe’s toy industry comprises major players leveraging innovation, strategic partnerships, and sustainability to fortify their market positions. Here are the key companies shaping the future of the region’s toy market:
- Mega Brands
- lego Group
- Mattel, Inc.
- Hasbro, Inc.
- Spin Master Corp.
- VTech Holdings Ltd.
- Simba Dickie Group
- Ravensburger AG
- Playmobil
- Melissa & Doug
Mega Brands
Mega Brands focuses on creating LEGO-compatible building sets and innovative STEM toys, leveraging eco-friendly materials and digital integration to enhance play experiences and meet evolving safety and sustainability standards.
lego Group
The LEGO Group remains a market leader with its extensive range of iconic building sets and digital experiences, emphasizing sustainability with initiatives like plant-based bricks and expanding digital play and learning tools.
Mattel, Inc.
Mattel offers a diverse portfolio featuring Barbie, Hot Wheels, and educational toys, emphasizing innovation in digital toys, sustainability initiatives, and strategic alliances to penetrate emerging markets and online retail channels.
Hasbro, Inc.
Hasbro’s strengths lie in licensed products, digital gaming, and a broad portfolio including Nerf, Play-Doh, and Transformers, focused on integrating digital technology and eco-conscious production to stay competitive.
Spin Master Corp.
Spin Master excels in innovation with a focus on licensed toys, entertainment properties, and tech-enabled play, investing heavily in digital transformation and sustainability practices within its manufacturing processes.
VTech Holdings Ltd.
VTech specializes in electronic learning products, smart toys, and connected devices, emphasizing technological innovation, child safety, and environmentally friendly manufacturing practices to expand its European footprint.
Simba Dickie Group
Simba Dickie’s diverse product range covers plastic and plush toys, with a strategic emphasis on sustainability and digital augmentation of traditional toys, supported by strong local manufacturing in Europe.
Ravensburger AG
Ravensburger is renowned for its puzzles and educational games, focusing on high-quality, eco-friendly materials, and expanding its digital game portfolio to align with market demand for educational and leisure products.
Playmobil
Playmobil is known for its themed figures and playsets, investing in sustainability and digital solutions to enhance interactive features and expand online engagement with its global audience.
Melissa & Doug
Melissa & Doug emphasizes handcrafted, educational toys that promote child development, expanding their sustainability initiatives and integrating digital elements to diversify their product offerings and market reach.
Strategic Business Developments
- January 2023 – Mattel – Launch of eco-friendly Barbies – Strengthens sustainability credentials, attracting eco-conscious consumers and aligning with market trends toward environmentally responsible products.
- May 2023 – LEGO Group – Opening of new digital innovation hub – Enhances technological capabilities and develops advanced AR and VR toys to meet growing consumer demand for digital play experiences.
- March 2023 – Hasbro – Acquisition of a leading educational tech company – Expands product portfolio into interactive and STEM-based learning toys, boosting market share in educational segments.
- August 2023 – Spin Master – Investment in sustainable manufacturing – Reduces carbon footprint by adopting new eco-friendly materials and processes, aligning with European sustainability regulations and expectations.
- April 2023 – Ravensburger – Partnership with a digital gaming platform – Promotes hybrid physical-digital games, enhancing engagement and broadening audience reach across digital-native consumers.
Frequently Asked Questions
What is the Europe Toys Market?
The Europe Toys Market encompasses the production, distribution, and sales of toys across European countries, driven by consumer demand for innovative and safe play products for children of various age groups. It reflects regional trends, regulatory impacts, and technological advancements.
What is the current market size of Europe Toys Market?
As of 2026, the Europe Toys Market is valued at approximately USD 25.4 Billion, reflecting steady growth fueled by rising disposable incomes, increasing urbanization, and a heightened focus on educational and safety features in toys within European households.
What factors are driving the Europe Toys Market?
Key growth drivers include demographic shifts, increased e-commerce penetration, innovation in toy design, sustainability trends, and regulatory standards promoting safety and environmentally friendly materials. Consumer preferences for STEM toys and licensed products also significantly influence the market.
Which region dominates the Europe Toys Market?
Western Europe is the leading region in the market, owing to its high disposable incomes, advanced retail infrastructure, and strong presence of global toy brands. Countries like Germany, France, and the UK are particularly prominent contributors to regional dominance.
Which segment is expected to grow the fastest?
Educational and STEM toys are projected to witness the fastest growth, driven by increasing awareness of developmental benefits and parental inclination towards edutainment products to enhance children's learning experiences and skill development.
Who are the leading companies operating in the Europe Toys Market?
Major players include LEGO Group, Mattel Inc., Hasbro Inc., and Bandai Namco Holdings. These companies maintain strong regional presence and focus on innovation, sustainability, and diversified product portfolios to capture market opportunities.
Geography
The geographic segmentation of the Europe Toys Market covers major regions including Western Europe, Eastern Europe, Northern Europe, and Southern Europe. Each region exhibits unique consumer preferences, economic conditions, and market maturity levels, influencing overall industry trends and growth potential.
- Western Europe: This region, comprising countries like Germany, France, and the UK, is characterized by high disposable income and technological adoption, fostering robust demand for innovative and premium toys. The presence of established retailers and brand outlets supports market growth.
- Eastern Europe: Countries such as Poland, Hungary, and the Czech Republic are witnessing increasing toy sales driven by rising consumer living standards, urbanization, and growing awareness of children’s developmental needs. Local manufacturing is also expanding in this segment.
- Northern Europe: Noted for its affluent and environmentally conscious population, this region shows a preference for sustainable toys, educational products, and modern design elements, influencing premiumization trends and eco-friendly product development.
- Southern Europe: Including countries like Italy, Spain, and Greece, this region's market growth is driven by tourism, seasonal purchasing patterns, and rising digital engagement, which influence toy preferences and retail strategies.
Analyst Perspective
The long-term outlook for the Europe Toys Market remains robust, driven by evolving consumer preferences, technological innovations, and demographic shifts. The integration of smart toys and augmented reality applications is expected to transform traditional play patterns, creating new revenue streams for manufacturers willing to invest in innovative product development. Commercial opportunities are particularly promising in the eco-friendly toy segment, where sustainability trends are gaining momentum across the region. Investment priorities should focus on digital adaptation, supply chain resilience, and regional market niches such as Eastern Europe, which offers untapped growth potential. Competitive intensity is likely to increase as key players strengthen their portfolios through mergers and acquisitions, emphasizing innovation and brand loyalty. Regional growth will be uneven, with Western Europe poised for steady expansion due to higher disposable incomes, while Eastern Europe presents considerable long-term opportunities. Strategic positioning should prioritize agility and technological leadership to capitalize on these dynamics, ensuring sustained market relevance amidst rapid change.
