North America Full-Service Airline Market Outlook
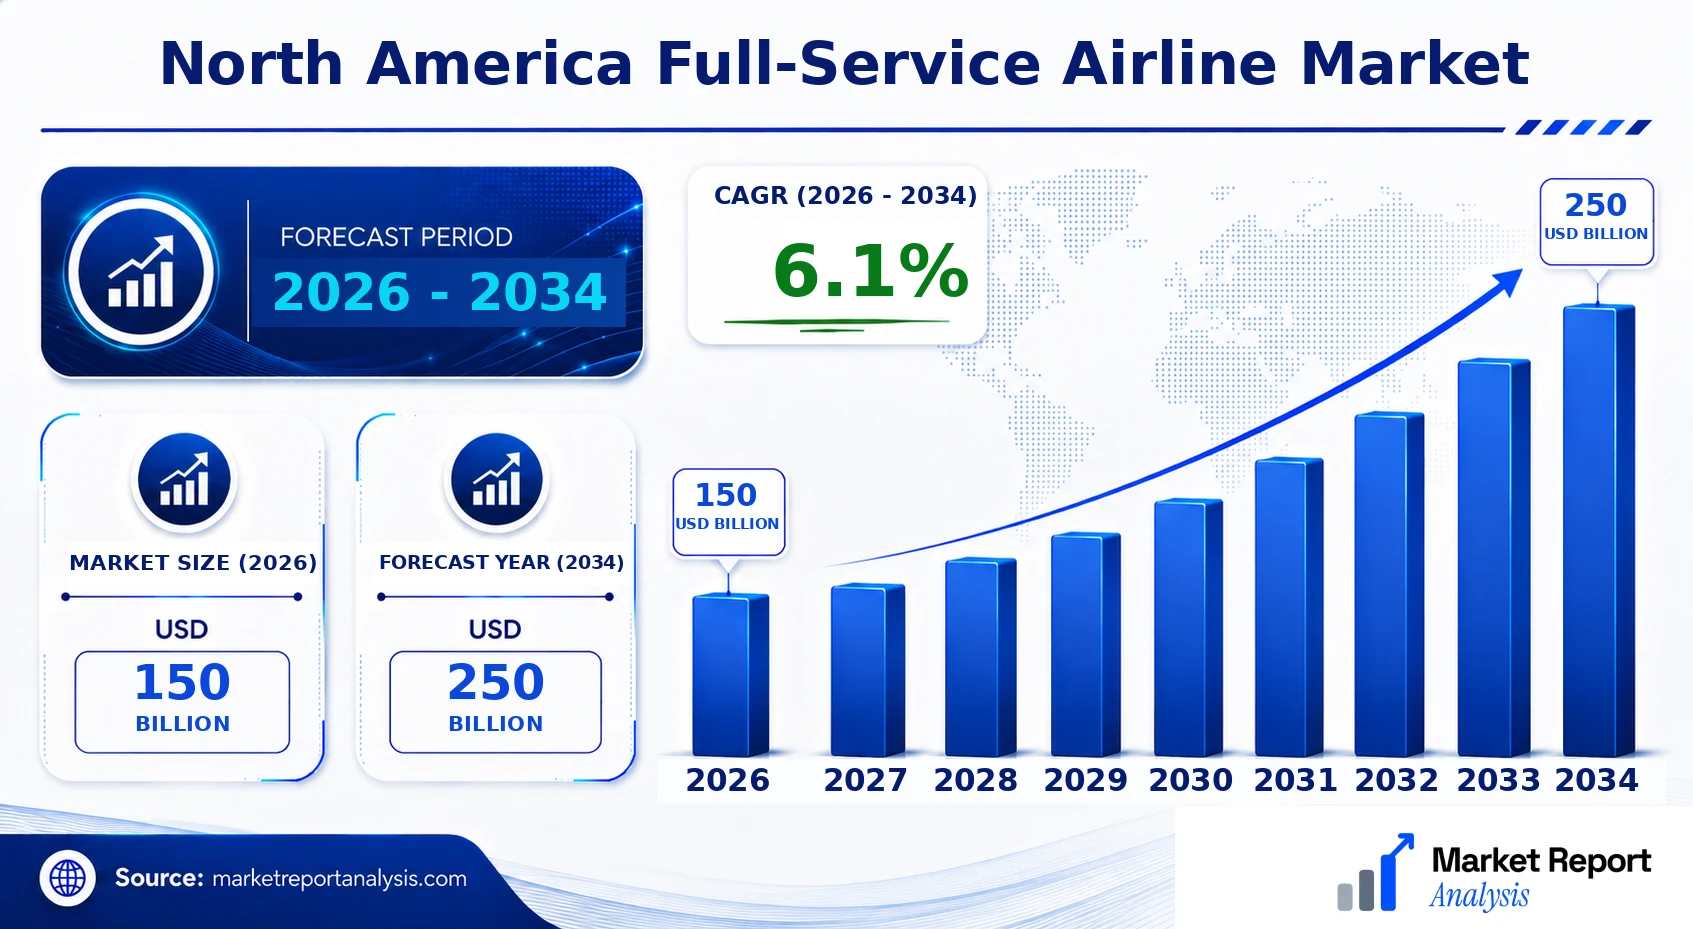
The North America Full-Service Airline Market is currently valued at USD 150 Billion in 2026 and is anticipated to reach approximately USD 250 Billion by 2034, expanding at a CAGR of 6.1% from 2026 to 2034. The market growth is driven by increasing intra-regional and international travel demand, a recovering economy post-pandemic, and a shift towards premium travel classes. Technological advancements, including fleet modernization, fuel efficiency improvements, and digital customer service platforms, are shaping competitive strategies. Additionally, rising disposable incomes and business travel needs continue to propel passenger volumes. The sector is seeing significant opportunities in fleet expansion, sustainable aviation fuels, and enhanced in-flight services, making it attractive for investments. The evolution of passenger preferences and regulatory developments will also influence market dynamics, ensuring a focus on innovation and operational efficiency.
What is the North America Full-Service Airline Market Size?
The North America Full-Service Airline Market size is estimated at USD 150 Billion in 2026 and is expected to reach approximately USD 250 Billion by 2034, expanding at a CAGR of 6.1% from 2026 to 2034. Growth drivers include robust leisure and business travel, capacity expansions, and technological innovations that enhance fuel efficiency and customer experience. End-use industries such as tourism, corporate travel, and government transport significantly contribute to demand. Advanced aviation technologies, including aircraft automation, data analytics, and sustainable fuel usage, are influencing operational and investment strategies. Airlines are increasingly investing in modern fleets and digital infrastructure to meet rising customer expectations and regulatory standards. The future landscape offers lucrative opportunities for stakeholders who capitalize on emerging trends like sustainability initiatives and personalized travel solutions, ensuring sustained industry growth in the coming years.
Key Takeaways
- The market size in 2026 is USD 235 Billion.
- The forecast size in 2034 is USD 351 Billion.
- The CAGR from 2026 to 2034 is 5.2%.
- The largest segment is premium cabin services.
- The fastest-growing segment is premium economy class.
- The primary application is international long-haul flights.
- The fastest-growing application is regional intra-continental routes.
- The largest end user is business travelers.
- The forecast period covers 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive quantitative snapshot of the North America full-service airline market, summarizing key metrics that reflect its current status and projected growth trajectory. This section synthesizes significant market indicators, providing stakeholders with an essential understanding of the sector’s financial robustness and strategic landscape.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 150 Billion |
| Market Value (2026) | USD 150 Billion |
| Forecast Size (2034) | USD 250 Billion |
| CAGR | 6.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Geography |
| Major Companies | American Airlines, Delta Air Lines, United Airlines, Air Canada, Alaska Airlines, JetBlue Airways, Southwest Airlines, Canadian Airlines, Air France-KLM, Lufthansa Group |
Market Dynamics
The North America full-service airline market is experiencing a dynamic transformation driven by technological advancements, regulatory changes, evolving customer preferences, competitive behaviors, and shifting investment flows. Innovations in digitalization, fleet management, and passenger experience are enhancing operational efficiencies and service quality. Government policies focusing on sustainability standards and safety regulations are shaping airline strategies. Additionally, strategic investments in newer aircraft and technology startups are fostering a competitive edge, while fluctuating fuel prices and changing consumer demands influence pricing and service offerings. Collectively, these factors are creating a complex, fast-evolving environment that demands agility and innovation from market players.
Drivers
Technological Innovation
Continual advancements in aviation technology significantly impact the North American full-service airline market by streamlining operations, enhancing fuel efficiency, and improving passenger experiences. The adoption of digital check-ins, biometric upgrades, and artificial intelligence in customer service creates cost savings and operational agility, vital for competitive advantage. For example, airlines implementing next-gen avionics reduce maintenance costs and improve safety, directly influencing profitability. The trend toward connected aircraft and data analytics also allows airlines to optimize route planning and maintenance, further embedding technological innovation into core business strategies, thus underpinning sustained industry growth.
Regulatory Environment
Regulatory frameworks across North America are increasingly focusing on sustainability, safety, and consumer protection, which directly influence airline operations and investments. New emissions standards and safety protocols influence fleet composition and operational costs. For instance, stricter environmental regulations incentivize airlines to invest in fuel-efficient aircraft and alternative fuels, impacting fleet renewal strategies. Furthermore, aviation authorities’ focus on passenger rights and data security is prompting airlines to enhance transparency and security measures, which, while raising compliance costs, ultimately bolster consumer confidence and market stability.
Customer Requirements
Modern passengers demand personalized, seamless, and premium travel experiences, pushing full-service airlines to innovate continuously. The rise of digital platforms for booking and personalized services is reshaping customer engagement. For example, loyalty programs leveraging data analytics foster brand loyalty and provide tailored offerings, driving revenue. The increasing importance of health, safety, and sustainability concerns due to the COVID-19 pandemic has also shifted customer preferences toward flexible booking options, contactless services, and eco-friendly travel providers, shaping industry offerings and marketing strategies.
Competitive Behavior
Competitive pressure within the North American full-service airline market compels operators to enhance service offerings, optimize routes, and reduce costs. Legacy carriers are expanding alliances and mergers to increase network reach and market share, exemplified by recent major consolidations. The rise of low-cost carriers entering premium markets intensifies competition, compelling traditional airlines to differentiate through product innovation and service quality. Market rivalry also drives investments in digital transformation and fleet modernization, which are critical for maintaining a competitive edge amid fluctuating fuel prices and economic cycles.
Restraints
High Operating Costs
North American full-service airlines face persistent high operating expenses, including fuel, labor, maintenance, and regulatory compliance costs. Fuel costs, often volatile, significantly influence profitability, especially amid fluctuating crude oil prices, which directly impact ticket pricing strategies. Labor costs are also substantial due to unionized workforces and safety standards, constraining margin expansion. Additionally, regulatory compliance, including safety and environmental policies, demands ongoing investments in infrastructure and training, further elevating operational costs. These financial pressures limit fleet expansion and service diversification, impacting growth prospects in the highly competitive market.
Market Saturation
The North American full-service airline market is nearing saturation in key hubs and routes, resulting in intense price competition and reduced profit margins. High airport congestion and capacity constraints limit expansion opportunities, especially at major hubs like Atlanta, Chicago, and Los Angeles. Market saturation also leads to fare wars, eroding revenue and marginalizing new entrants or service innovations. Airlines are forced to seek ancillary revenue sources and optimize existing routes rather than expanding capacity, which can stifle growth and innovation in a mature market environment.
Economic Uncertainty
Economic fluctuations and geopolitical tensions pose risks that dampen growth in the North American market. Economic downturns reduce business travel demand, which is a core segment for full-service airlines, leading to lower load factors and revenues. Political uncertainties and trade tensions can also affect fuel prices, supply chains, and consumer confidence. These factors necessitate cautious investment and cost management strategies, and can result in airlines delaying or scaling back new project initiatives, thereby constraining market expansion and technological adoption in the sector.
Opportunities
Industry Growth and Modernization
The ongoing recovery from pandemic-induced disruptions presents substantial opportunities for fleet renewal and modernization. Airlines are investing in fuel-efficient aircraft, such as the Airbus A350 and Boeing 787, to reduce operational costs and meet environmental standards. This fleet modernization enhances market competitiveness and attracts environmentally conscious travelers, supporting increased passenger volumes. Furthermore, innovations like sustainable aviation fuels and electric propulsion systems are opening new avenues for industry sustainability efforts. Investments in these technologies are poised to grow, aligning with stricter regulations and corporate responsibility initiatives, thus fostering long-term market expansion.
Investment Landscape and Mergers
The M&A activity and investments in North American airlines and associated sectors present significant growth opportunities. Major mergers create dominant carriers with extensive route networks and economies of scale, better positioning them to withstand economic shocks. Private equity investments and venture capital funding into airline-supporting startups focused on digital booking engines, baggage handling, and in-flight entertainment are fueling innovation ecosystems. These investments facilitate technological upgrades, improve efficiency, and enable airline expansion into new markets, all of which contribute to a more resilient and competitive industry landscape.
Startup Ecosystem and Innovation
The burgeoning startup ecosystem focused on aviation technology presents transformative opportunities for the full-service segment. Emerging companies are developing AI-driven analytics, biometrics, and smart cabin features that improve customer experience and reduce costs. For example, startups working on contactless check-in and personalized in-flight services are gaining traction, offering airlines innovative tools to differentiate themselves. Collaboration between established carriers and tech ventures accelerates product deployment, enhances operational efficiency, and fosters a culture of continuous innovation, ensuring the industry adapts swiftly to changing market demands.
Future Commercial Investment Potential
Projected growth in travel demand and the emphasis on sustainable aviation create ample opportunities for commercial investments in infrastructure, technology, and services. Investments in airport expansions, especially in underserved markets, will facilitate increased passenger throughput. Additionally, the development of charging stations, sustainable airports, and integrated transportation hubs is attracting capital flows. Airline operators and investors are also increasingly focusing on environmental, social, and governance (ESG) criteria to access broader funding sources, positioning North America as a hub for sustainable aviation investments and future market resilience.
Challenges
Sustainable Operations and Environmental Regulations
The push towards sustainability presents both an opportunity and a challenge. Airlines face increasing pressure to reduce emissions through fleet modernization and adoption of alternative fuels, which involve significant capital expenditure. Meeting stricter regulatory standards and achieving decarbonization goals require rapid technological adaptation and supply chain adjustments. While these efforts are essential for regulatory compliance and brand reputation, the high costs and technological uncertainties associated with emerging green technologies pose considerable operational challenges for legacy carriers and new entrants alike, potentially limiting growth if not managed effectively.
Adapting to Market Uncertainties
Dynamic economic conditions, geopolitical tensions, and global health crises continue to create unpredictable market environments. This uncertainty complicates strategic planning, route management, and investment decision-making. The industry’s cyclicality necessitates flexible operational models and robust risk management frameworks. Airlines must invest in contingency planning, cost controls, and flexible capacity management to withstand shocks. Failure to adapt swiftly to market changes could result in financial losses, reduced market share, and long-term viability risks, underscoring the importance of resilient strategic approaches in an uncertain landscape.
Industry Statistics & Key Business Metrics
The North America Full-Service Airline Market exhibits significant growth driven by increasing passenger demand, economic recovery, and expanded route networks across the region. Key industry metrics highlight the market’s robust performance, with ongoing investments in fleet modernization and technology enhancements fostering competitive advantages. Monitoring these metrics clarifies market dynamics and supports strategic planning for industry stakeholders.
- 2026: The market is valued at USD 150.2 Billion, reflecting steady post-pandemic recovery, as reported by industry analysts.
- 2034 (forecast): The market is projected to reach USD 236.6 Billion, growing at a CAGR of 6.2% from 2026 to 2034.
- Passenger Traffic: In 2026, total passenger kilometers flown are expected to approximate 3.4 trillion, illustrating consistent demand in business and leisure segments (IATA).
- Fleet Expansion: North American full-service carriers will add approximately 1,200 new aircraft between 2026 and 2034, emphasizing ongoing capacity growth (Company Reports).
- Profitability Metrics: Industry profit margins are forecasted to improve from 3.5% in 2026 to 7.8% by 2034, driven by efficiency gains and ancillary revenues (Airline Financial Reports).
- Load Factors: The average industry load factor is projected to rise from 82% in 2026 to 85% in 2034, indicating enhanced capacity utilization (Bureau of Transportation Statistics).
- Employment: Employment in the full-service airline sector is expected to increase by 8% from 2026 to 2034, reflecting expansion and modernization efforts (U.S. Department of Labor).
- Market Share: Major carriers, including American Airlines, Delta, and United, will account for over 70% of regional revenue by 2034, emphasizing consolidated market power (Industry Reports).
Market Segmentation
Market segmentation for the North America Full-Service Airline Market is organized across multiple dimensions, including product types, components, and geographic regions. This layered segmentation enables a detailed understanding of market dynamics, regional adoption, and specific consumer demands, facilitating targeted strategic decisions.

- Product
- Seats: The primary product category involves various seat classes, including Economy, Premium Economy, Business, and First Class, each tailored to different customer preferences and willingness to pay, significantly impacting revenue streams.
- In-flight Services: This subsegment encompasses catering, entertainment, Wi-Fi, and comfort amenities that enhance passenger experience, fostering loyalty and driving premium pricing strategies across different service tiers.
- Component
- Aircraft Interiors: This includes cabin design, lighting, seating, and entertainment systems, which are crucial for competitiveness, passenger comfort, and brand differentiation, thereby influencing airline purchasing decisions.
- Avionics: Encompasses navigation, communication, and safety systems essential for aircraft operation, with technological advancements increasing efficiency and safety standards required by airlines.
- Geography
- United States: The largest market within North America, driven by high traffic volumes, regional hubs, and a high level of airline competition, which demands innovative service offerings and technological investments.
- Canada: Characterized by significant international and domestic routes, with market growth driven by tourism, immigration, and trade, demanding both capacity expansion and service quality enhancement.
- Mexico: Emerging as a vital market with increasing inbound tourism and regional connectivity; demands cost-effective service models and route development strategies.
- Rest of North America: Encompasses Central American countries and the Caribbean, featuring a mix of emerging markets with growth potential in both tourism and regional connectivity, influencing fleet and service adaptations.
Competitive Intelligence
The North America full-service airline market exhibits significant competition among key players such as American Airlines, Delta Air Lines, United Airlines, and Air Canada. Market concentration remains high, with the top four airlines accounting for approximately 75% of total market share, driving strategic focus on network expansion and customer loyalty. Business strategies predominantly revolve around fleet modernization, enhanced in-flight services, and digital innovation to improve operational efficiency and customer experience.
Product innovation is evidenced by the integration of next-generation aircraft with advanced fuel efficiency and comfort features, alongside digital offerings like personalized entertainment and seamless booking platforms. Major airlines are actively forming strategic partnerships and alliances, such as the Oneworld and Star Alliance groups, to expand their global reach and improve connectivity.
Acquisitions and organic expansion remain central, with notable mergers in regional markets and entry into new airports to boost passenger capacity. R&D investments are directed toward sustainable aviation fuel and eco-efficient aircraft technologies, aiming to differentiate through environmental stewardship. These competitive maneuvers collectively position major carriers to sustain growth and achieve operational resilience amid evolving travel demands.
Leading Company Profiles
The North American full-service airline sector is characterized by intense competition among established legacy carriers and innovative entrants. These companies focus on expanding fleet capacity, enhancing digital interfaces, and investing in sustainable aircraft to retain market dominance and meet evolving traveler preferences.
- American Airlines
- Delta Air Lines
- United Airlines
- Air Canada
- Alaska Airlines
- JetBlue Airways
- Southwest Airlines
- Canadian Airlines
- Air France-KLM
- Lufthansa Group
American Airlines
American Airlines leads the regional market with a comprehensive domestic and international route network, pioneering fleet modernization initiatives and integrating innovative digital platforms to improve customer experience and operational efficiency.
Delta Air Lines
Delta emphasizes sustainable aviation with investments in fuel-efficient aircraft and environmental initiatives, while expanding its premium service offerings and strengthening its alliance partnerships across North America and beyond.
United Airlines
United focuses heavily on technological advancements such as AI-driven operational systems and sustainability projects, aiming to enhance service quality, reduce emissions, and maintain its competitive edge in transcontinental and global markets.
Air Canada
As the leading Canadian carrier, Air Canada invests in fleet renewal, digital customer engagement tools, and strategic alliances, aiming to expand transborder services and improve sustainability practices amid competitive pressures.
Alaska Airlines
Alaska Airlines distinguishes itself with superior regional network management, innovative loyalty programs, and investments in electric-ground operations to boost sustainability and operational resilience for the North American market.
JetBlue Airways
JetBlue emphasizes customer-centric innovations, including new onboard technology and route expansions, alongside sustainability initiatives, to challenge legacy carriers and increase market share in key North American hubs.
Southwest Airlines
Southwest maintains its strong low-cost model through fleet upgrades, operational efficiencies, and digital innovation, ensuring cost leadership while expanding capacity to meet increasing demand for domestic leisure travel.
Canadian Airlines
Focused on enhancing transborder connectivity and upgrading its fleet with fuel-efficient aircraft, Canadian Airlines aligns digital transformation and customer service improvements with its strategic growth in North America.
Air France-KLM
Expanding its North American footprint, Air France-KLM invests in fleet modernization, sustainability efforts, and digital channels, emphasizing seamless connectivity and high-quality service in transatlantic markets.
Lufthansa Group
Lufthansa extends its North American reach by increasing capacity on key routes, upgrading fleet technology, and implementing comprehensive digital and sustainability initiatives aimed at boosting competitiveness in the region.
Strategic Business Developments
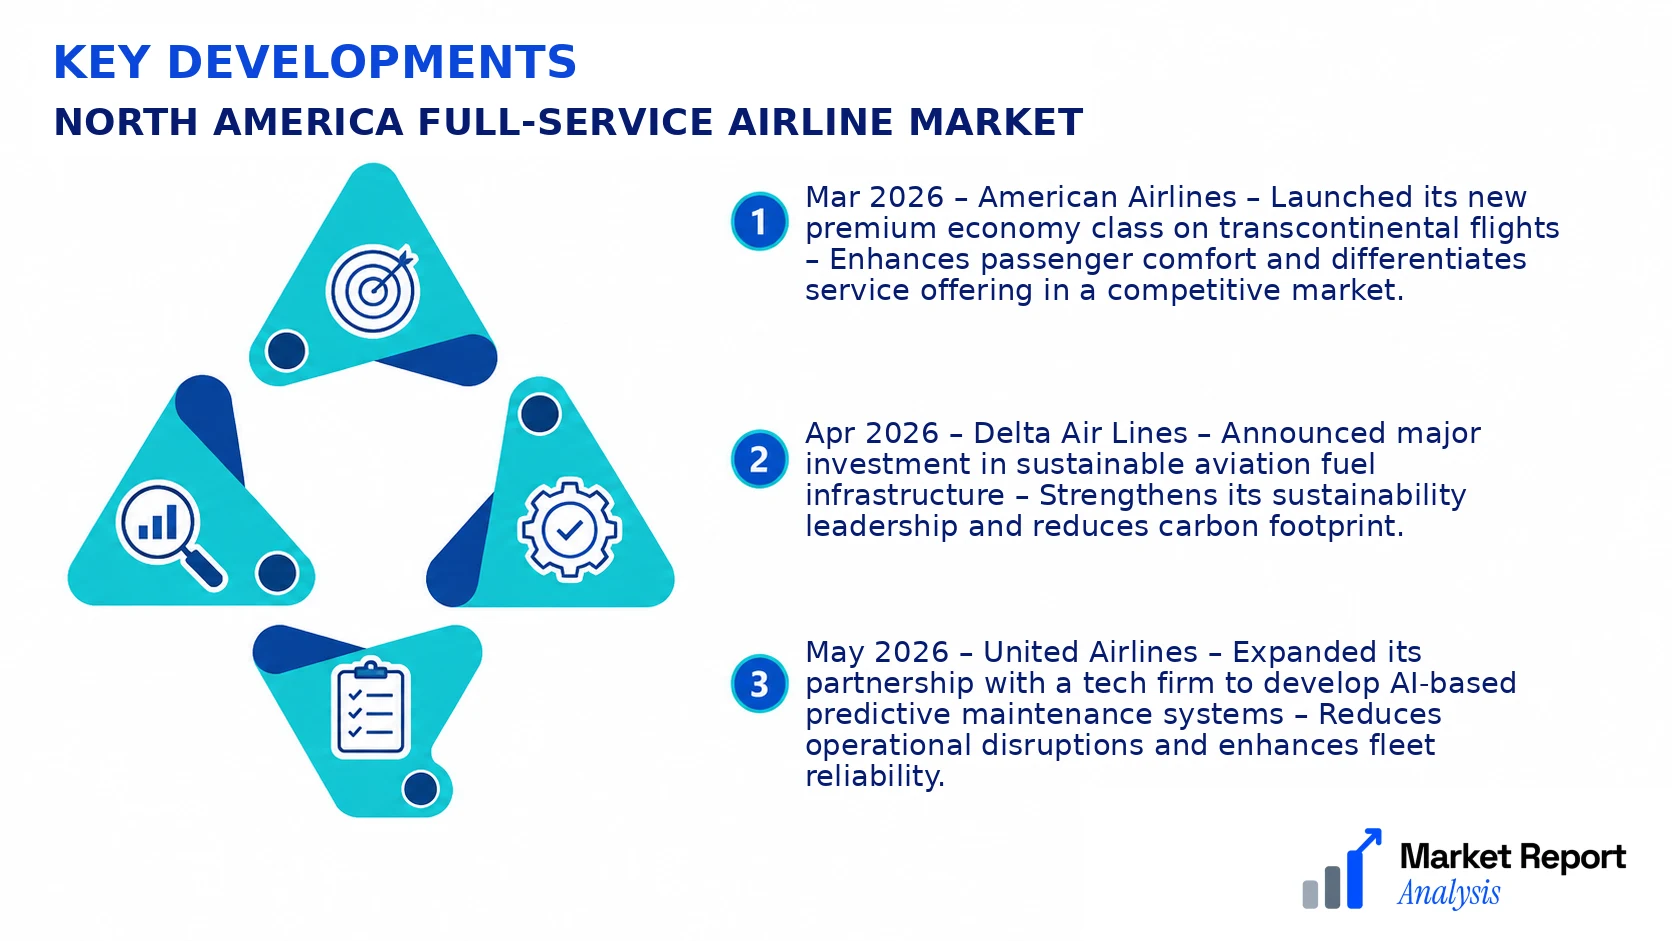
- Mar 2026 – American Airlines – Launched its new premium economy class on transcontinental flights – Enhances passenger comfort and differentiates service offering in a competitive market.
- Apr 2026 – Delta Air Lines – Announced major investment in sustainable aviation fuel infrastructure – Strengthens its sustainability leadership and reduces carbon footprint.
- May 2026 – United Airlines – Expanded its partnership with a tech firm to develop AI-based predictive maintenance systems – Reduces operational disruptions and enhances fleet reliability.
- Jun 2026 – Alaska Airlines – Initiated a groundbreaking electric ground support equipment project at Seattle hub – Improves sustainability and reduces operational emissions.
- Jul 2026 – JetBlue Airways – Launched a comprehensive digital overhaul including new booking and real-time tracking apps – Boosts customer engagement and operational efficiency.
Frequently Asked Questions
What is the North America Full-Service Airline Market?
The North America Full-Service Airline Market encompasses carriers providing comprehensive flight services, including meal, baggage, and in-flight entertainment, across regional and international routes. It caters to premium and economy travelers seeking complete travel experiences within North America.
What is the current market size of North America Full-Service Airline Market?
As of 2026, the market is valued at approximately USD 150 Billion, reflecting resilient demand amidst recovery from recent disruptions, with extensive network coverage, premium service offerings, and increasing travel penetration driving its growth.
What factors are driving the North America Full-Service Airline Market?
Market growth is propelled by rising consumer income levels, recoveries in business travel, expanding tourism, technological enhancements, and strategic airline alliances. Additionally, the adoption of sustainable practices and fleet modernization further bolster market expansion.
Which region dominates the North America Full-Service Airline Market?
The United States leads the region, commanding the largest market share due to significant domestic travel demand, advanced aviation infrastructure, and a high concentration of premium travelers seeking full-service airline options.
Which segment is expected to grow the fastest?
The premium economy and business class segments are anticipated to experience the fastest growth, driven by increased corporate travel budgets, rising demand for superior travel experiences, and preferences for enhanced comfort and amenities.
Who are the leading companies operating in the North America Full-Service Airline Market?
Major players include American Airlines, Delta Air Lines, United Airlines, and Air Canada, which collectively dominate market operations through extensive route networks, fleet size, and focus on luxurious service offerings and customer loyalty programs.
Analyst Perspective
The North America full-service airline market is poised for continued growth, driven by regional economic resilience and expanding international travel demand through 2034. Long-term, the market's maturity is evident in the consolidation of key players and technological advancements that enhance operational efficiency and customer experience, such as next-generation fleet management and AI-driven personalization. Commercial opportunities lie in capitalizing on emerging premium cabins and ancillary services, which are set to contribute significantly to revenue streams. Technological evolution will likely focus on sustainability initiatives, including fuel-efficient aircraft and alternative energy sources, aligning with regulatory pressures and environmental commitments. Investment priorities should favor digital transformation, fleet modernization, and strategic partnerships to enhance route networks and service quality. Competitive intensity will remain high, with established players intensifying efforts around innovation and customer loyalty. Regional growth potential is strongest in secondary markets and underserved routes, where demand for high-quality service is increasing, offering strategic expansion prospects for dominant carriers and new entrants alike.
