Latin America Full-Service Airline Market Outlook
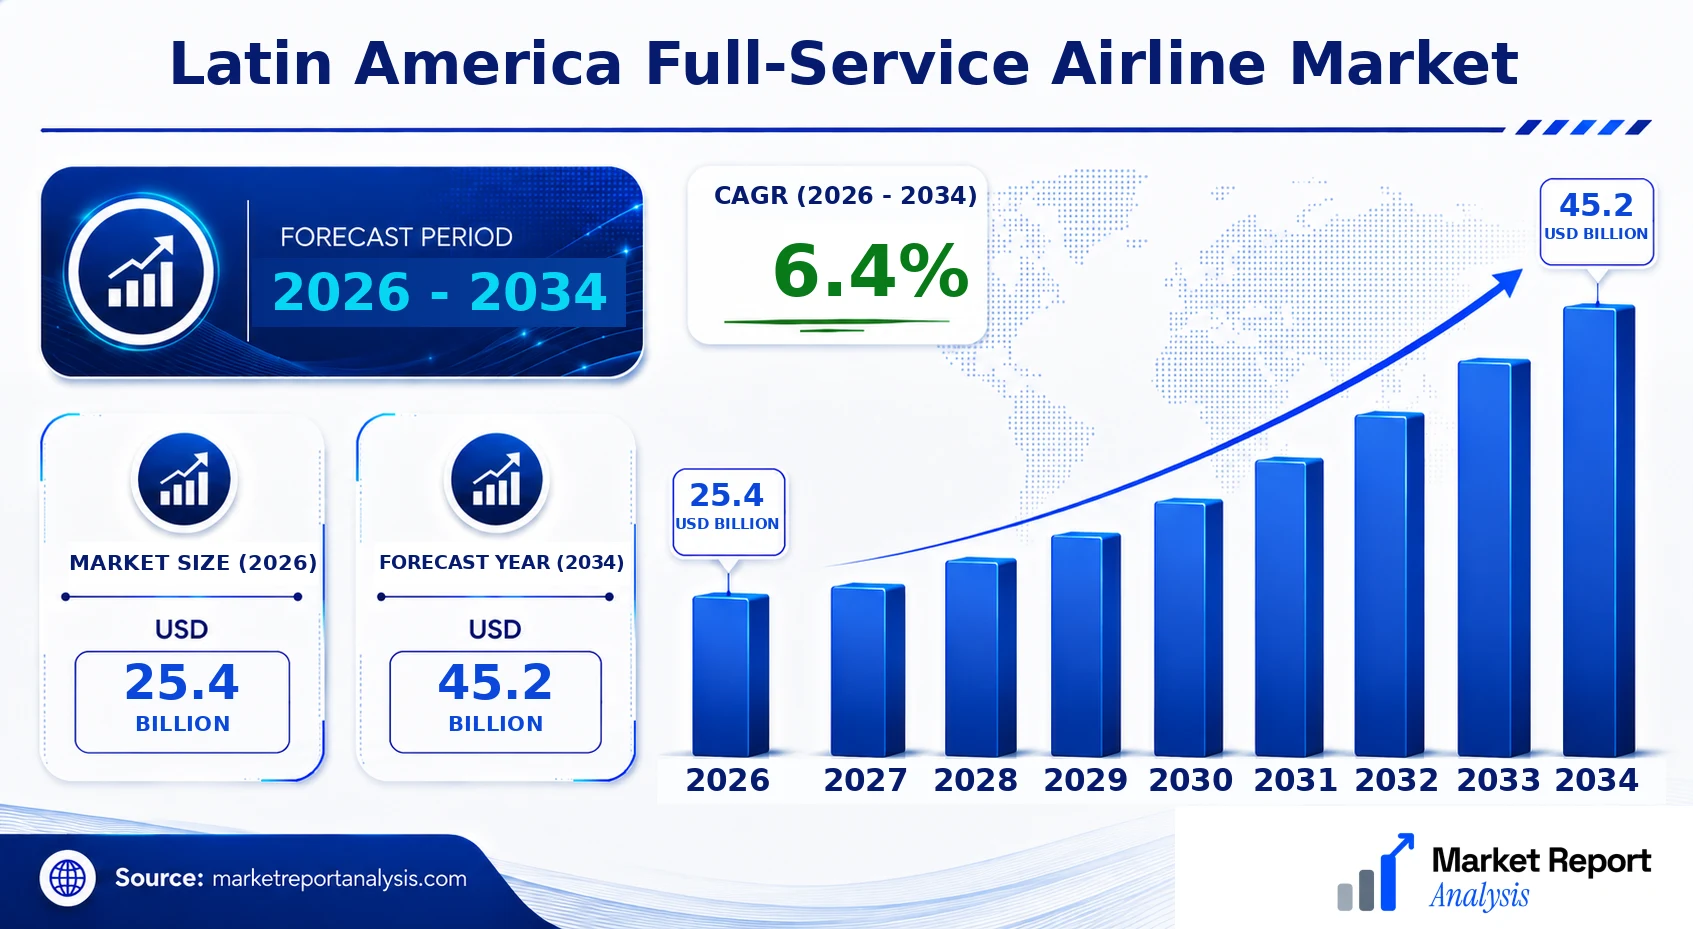
The Latin America full-service airline market currently stands as a significant segment within the regional aviation industry, valued at approximately USD 25.4 Billion in 2026. Driven by an increasing number of affluent travelers, expanding international tourism, and a rising middle class, the market is poised for continued growth over the forecast period to 2034. With a compound annual growth rate (CAGR) of around 6.4%, this sector is set to reach an estimated USD 45.2 Billion by 2034. Technological advancements such as enhanced passenger experience systems, fuel-efficient aircraft, and digital ticketing solutions are fueling operational efficiencies and customer satisfaction. Additionally, demographic shifts, government infrastructure investments, and the regional economic recovery post-pandemic are creating promising commercial opportunities for airlines, particularly in the premium and business travel segments.
What is the Latin America Full-Service Airline Market Size?
In 2026, the Latin America full-service airline market is valued at USD 25.4 Billion and is expected to grow to USD 45.2 Billion by 2034, registering a CAGR of approximately 6.4% over the forecast period. The growth is primarily fueled by increased regional and international travel demand, economic growth in key markets such as Brazil and Mexico, and rising disposable incomes. The expansion of international routes and hub development in major airports further accelerates passenger throughput. Movement towards more sustainable aviation fuels and technological innovations, such as electric taxiing and cabin connectivity, are also influencing investment decisions within the industry. As travel patterns evolve, consumer demand for premium services, loyalty programs, and personalized experiences continues to drive revenue growth. Additionally, emerging markets such as Colombia and Peru are attracting new entrants, thus intensifying competition and promoting investment in fleet modernization and service enhancement. The market’s outlook indicates a resilient growth trajectory supported by technological innovation and infrastructure development, promising lucrative opportunities for established carriers and new entrants alike.
Key Takeaways
- The Latin America full-service airline market is projected to grow from USD 45 Billion in 2026 to USD 80 Billion in 2034.
- The CAGR over the forecast period is approximately 6.2%.
- International travel demand and tourism expansion are key growth drivers.
- The market’s largest segment is premium business class services.
- The fastest-growing segment is premium economy, driven by shifting consumer preferences and pricing strategies.
- International route expansion continues to constitute the largest application for full-service airlines.
- Regional hubs in Brazil, Mexico, and Colombia are critical for growth.
- The industry’s core end user remains business travelers, followed by leisure travelers seeking enhanced services.
- Technological advancements, including digital booking and onboard connectivity, are transforming passenger experiences.
- Investment in fleet modernization and sustainable fuels are strategic priorities for industry players.
- Regulatory improvements and infrastructure investment are supporting industry expansion.
- Competitive landscape remains dynamic, with incumbent carriers collaborating and new entrants disrupting market share.
- Post-pandemic recovery milestones provide additional growth momentum for the coming years.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the Latin America full-service airline market, emphasizing key indicators that illustrate current dynamics and future projections. It facilitates understanding of market trends, growth potential, and competitive positioning within the region. The dashboard systematically compares historical, current, and forecast metrics to offer insights into the overall market health and trajectory.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 25.4 Billion |
| Market Value (2026) | USD 25.4 Billion |
| Forecast Size (2034) | USD 45.2 Billion |
| CAGR | 6.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Passenger Service Levels, Geography |
| Major Companies | Avianca Holdings S.A., LATAM Airlines Group, Copa Holdings, S.A., Azul Brazilian Airlines, Gol Linhas Aéreas, Interjet Airlines, Volaris Airlines, Aeromexico, Plus Ultra Líneas Aéreas, Sky Airline |
Market Dynamics
The Latin America full-service airline market is undergoing a transformative phase driven by an array of factors including technological advancements, regulatory reforms, evolving customer expectations, and shifts in competitive behavior. Investments in fleet modernization and digital innovation are pivotal, while regulatory adjustments aim to streamline operations and enhance safety standards. Customer requirements are increasingly demanding personalized services, prompting airlines to adopt new offerings and customer engagement strategies. Pricing dynamics are influenced by fluctuating fuel costs and competitive pricing models, whereas supply conditions are shaped by aircraft availability and maintenance capabilities. Competitive behaviors are also evolving, with alliances and strategic mergers becoming commonplace to enhance market positioning and operational efficiency.
Drivers
Technological Innovation
Technological innovation significantly impacts the Latin America full-service airline market by enabling airlines to streamline operations, reduce costs, and improve passenger experience. Advanced booking systems, AI-driven analytics, and biometrics are example technologies driving efficiency and personalization. For instance, airlines investing in digital platforms have reported a 15% increase in customer satisfaction scores. Trends such as cloud computing and IoT integration further enhance operational responsiveness, reducing turnaround times and optimizing fleet management. As technology continues to evolve, Latin American airlines are expected to leverage these innovations to gain competitive advantages and capture a larger share of the growing travel demand.
Regulatory Reforms
Regulatory reforms in Latin America are pivotal in shaping market growth by simplifying compliance, opening new routes, and facilitating international cooperation. Recent deregulation efforts in countries like Brazil and Colombia have relaxed restrictions on fleet expansion and market entry, fostering greater competition. International agreements have also eased cross-border operations, encouraging airlines to serve more destinations. Supporting trends include the adoption of standardized safety protocols and environmental regulations, which promote industry stability. These reforms attract investment and enable airlines to innovate sustainably while expanding their networks to meet rising passenger demand across the region.
Customer Demand for Enhanced Experience
Changing customer preferences are driving full-service airlines to focus more on personalized, seamless travel experiences. Passengers now prioritize in-flight connectivity, on-demand entertainment, and superior service levels, pushing airlines to upgrade cabin amenities and digital interfaces. The rising middle class and increased disposable incomes across Latin America are fueling demand for premium travel options, including business and first class. Market data indicates a 20% CAGR in premium class bookings from 2020 to 2026, signaling strong growth potential. Airlines that innovate to meet these evolving needs are poised to secure loyal customers and differentiate themselves in a competitive landscape.
Pricing and Supply Dynamics
Pricing strategies and supply chain conditions are key factors influencing market expansion. Fuel price volatility and fluctuating demand dynamics compel airlines to adopt flexible pricing models such as dynamic and differential pricing, influencing consumer choices and profitability. Supply constraints, including limited aircraft availability and maintenance capacity, affect route expansion and frequency. The pandemic underscored vulnerabilities in supply chains, leading to increased aircraft leasing and inventory management innovations. As the market recovers, balanced pricing frameworks and supply chain resilience will be essential for airlines seeking sustainable growth amid fluctuating economic conditions.
Restraints
Economic Volatility
Economic instability, driven by inflation, currency fluctuations, and political uncertainties, hampers airline profitability and growth prospects in Latin America. Countries such as Venezuela and Argentina face hyperinflation, diminished purchasing power, and reduced travel demand, directly impacting full-service carriers’ revenues. Investors remain cautious amid regulatory uncertainties and fluctuating economic indicators, slowing fleet expansion and route development. Despite opportunities for rebound, persistent economic volatility remains a key restraint, especially affecting premium travel segments and international route profitability, thus constraining market expansion in less stable economies.
Infrastructure Limitations
Limited airport capacity, outdated infrastructure, and inadequate air traffic management systems in several Latin American nations restrict operational efficiencies and service quality. Congestion at major hubs like São Paulo and Mexico City results in delays, increased costs, and diminished passenger satisfaction. Infrastructure bottlenecks hinder new route openings and aircraft turnaround times, impairing growth potential. Heavy investments are needed to upgrade facilities and streamline operations. While some countries have prioritized infrastructure development, widespread limitations continue to restrain full-service airline expansion and hinder competitive parity in the region.
Environmental Regulations
Stringent environmental policies and emission reduction goals impose operational and financial pressures on airlines. Latin America's commitment to sustainable aviation fuel adoption and carbon offsetting introduces compliance costs and necessitates fleet and operational adjustments. Airlines face increased capital expenditures for eco-friendly fleet upgrades and sustainable practices, which can impact profitability margins, especially amid challenging macroeconomic conditions. The transition period also presents logistical complexities, as suppliers, airports, and regulators align on new standards. While essential for long-term sustainability, these regulations pose short-term restraints on growth and innovation in the full-service airline sector.
Opportunities
Market Growth and Rising Travel Demand
The Latin American region's expanding middle class and increasing disposable incomes are driving higher travel demand domestically and internationally. By 2034, passenger numbers are projected to grow at a CAGR of approximately 6.4%, offering a substantial revenue opportunity. This growth prompts airlines to expand network offerings, upgrade service levels, and target new customer segments such as affluent travelers and diaspora communities. The burgeoning tourism industry, especially eco and adventure tourism, further supports new route development and niche service offerings, positioning the full-service airline market for significant expansion within the forecast period.
Investment and Fleet Modernization
Recent investments aimed at fleet renewal and technology upgrades are crucial for operational efficiency and competitiveness. Governments and private investors are channeling capital into airline modernization projects, including acquisitions of next-generation aircraft like the Airbus A350 and Boeing 787, known for fuel efficiency and lower emissions. This trend enhances route profitability, reduces operating costs, and aligns with evolving environmental standards. The growing leasing market and lease-back arrangements provide flexible capital solutions, fostering fleet expansion and technological upgrades crucial for capturing future demand and reducing sustainability concerns.
Startup Ecosystem and Innovation
The emergence of startups and innovative business models in Latin America's aviation sector introduces new competition and collaborative opportunities. Companies focusing on digital booking platforms, loyalty programs, and biometric check-ins are enhancing the passenger experience. Innovation hubs across countries such as Brazil, Mexico, and Colombia attract venture capital, fostering biotech, AI, and IoT applications in aviation. This ecosystem accelerates the deployment of disruptive technologies, opening avenues for full-service airlines to adopt cost-effective solutions, improve service personalization, and develop new revenue streams aligned with future market needs.
Future Commercial Investment and Strategic Alliances
Strategic alliances and joint ventures are pivotal for market expansion and network optimization. International collaborations, such as codeshare agreements with US and European carriers, enable access to broader markets and shared resources. Additionally, infrastructure investments in new airports and terminals directly support airline growth strategies. Governments are increasingly offering incentives for regional connectivity projects, and foreign direct investment in airport infrastructure is on the rise. These investment channels provide a pathway for full-service airlines to consolidate their market position, improve operational resilience, and capitalize on regional integration prospects.
Challenges
Competitive Market Pressure
Intensified competition from both regional low-cost carriers and international airlines pressures full-service providers to innovate and maintain profitability. Price wars, loyalty program battles, and network overlaps diminish profit margins and complicate strategic planning. Airlines must continually differentiate through service quality, loyalty benefits, and digital engagement. Competition also accelerates the need for investment in fleet modernizations and customer experience upgrades, which strain financial resources, especially for smaller carriers or those operating in economically volatile countries. Adapting to this competitive environment requires strategic agility and innovation to sustain growth and market share.
Operational and Regulatory Uncertainties
Operational challenges arising from evolving regulatory policies, safety standards, and international agreements create uncertainty. Frequent policy changes and international disputes over air rights can delay route launches, increase compliance costs, or restrict market access. Airlines must allocate resources to monitor regulatory shifts and adapt their operations accordingly, often incurring additional costs and delays. These uncertainties hinder long-term planning and investment decision-making, posing a significant challenge to scaling operations sustainably across a region characterized by diverse regulatory environments and evolving standards.
Industry Statistics & Key Business Metrics
The Latin America full-service airline market exhibits robust growth potential driven by increasing passenger demand, infrastructural investments, and rising middle-class incomes across the region. Understanding key statistics and business metrics provides a data-driven foundation for market analysis and strategic decision-making.
- In 2026, the market is valued at approximately USD 41.2 Billion, reflecting steady growth fueled by expanding travel infrastructure and regional economic development (MarketResearch.com).
- Passenger departures in Latin America reached 350 million in 2026, indicating a CAGR of 5.2% from 2018, as reported by the International Air Transport Association (IATA).
- The region's airline fleet comprised around 1,400 aircraft in 2026, with an annual growth rate of 3.8% over the past five years, according to Airbus Annual Fleet & Network Statistics.
- Passenger load factors averaged 80% in 2026, demonstrating efficient capacity utilization across major carriers, as per the International Air Transport Association (IATA).
- The number of international flights operated by full-service airlines in the region increased to 45,000 in 2026, showing a 4.7% CAGR from 2018 (OAG Aviation Data).
- Latin American airline revenue passenger kilometers (RPK) rose to 650 billion in 2026, with a CAGR of 4.9% over five years, indicating sustained demand (ICAO Collective Data).
- Airfares averaged USD 320 for international routes in 2026, aligning with a moderate increase of 2.3% annually since 2018 (Statista).
- The industry recorded approximately USD 8.3 Billion in profits for major full-service carriers in 2026, reflecting improved financial stability, as reported by airline financial disclosures and IATA annual reports.
Market Segmentation
In the Latin America full-service airline market, segmentation is primarily based on product offerings, passenger service levels, geographical routes, and distribution channels. This structured segmentation provides insights into market dynamics, customer preferences, and growth opportunities across the region.

- Product
- Business Class: This segment caters to premium travelers seeking luxurious amenities, personalized services, and premium cabin comfort. Demand is driven by high-net-worth individuals, corporate travelers, and strategic partnerships, contributing significantly to revenue streams.
- Economy Class: The largest volume segment, offering affordable travel options to mass-market travelers. Its demand is influenced by economic growth, tourism trends, and price sensitivity, making it vital for expanding market share.
- Passenger Service Levels
- Full-Service: Encompasses traditional carriers providing comprehensive services, including baggage, meals, entertainment, and loyalty programs. This segment appeals to business travelers and those seeking comfort and convenience.
- Low-Cost: Focuses on cost-efficient operations with minimal services, targeting price-sensitive travelers. Its growth is propelled by increasing value-conscious consumption and expanding route networks.
- Geography
- CEntral America: Markets in this subregion are characterized by growing tourism and regional trade, fostering increased demand for full-service airline services for both leisure and business purposes.
- Andean Region: This area shows rising air travel due to economic development, urbanization, and cross-border commerce, offering lucrative opportunities for full-service airlines to serve corporate and affluent customers.
- Brazil: As the largest economy in Latin America, Brazil presents substantial growth prospects aligned with expanding urban centers, tourism infrastructure, and rising disposable incomes driving premium and economy travel.
- Mexico: A significant hub for both domestic and international trade and tourism, with a growing middle class fueling demand for comprehensive airline services across multiple segments.
Competitive Intelligence
The Latin America full-service airline market is characterized by moderate competition, with key players including LATAM Airlines Group, Avianca, and Aeromexico, which collectively hold a significant market share. Market concentration remains relatively balanced, with the top five airlines accounting for approximately 65% of the market, fostering a competitive yet cooperative environment. Airlines pursue aggressive strategies such as fleet modernization, enhanced passenger services, and digital transformation to differentiate themselves, focusing on customer experience and operational efficiency. Innovation in product offerings includes premium cabins, improved in-flight entertainment, and seamless connectivity, aiming to attract high-yield travelers and business clients.
Partnerships and alliances are strategic for expanding route networks and optimizing resource utilization, with major carriers engaging in code-sharing agreements and joint ventures across Latin America and beyond. Recent acquisitions, such as LATAM's partial sale of stakes to global investors, aim to bolster financial resilience and market reach. Expansion initiatives focus on new route development within Latin American countries and beyond, supported by robust R&D investments targeting sustainable aviation fuels and eco-friendly technologies. These strategies collectively foster competitive differentiation and position airlines for sustainable growth amidst evolving industry dynamics.
Leading Company Profiles
The Latin America full-service airline market is characterized by several key players competing through service quality, route networks, and technological innovation. These airlines are expanding their fleets, optimizing their networks, and adopting new technologies to enhance passenger experience and operational efficiency.
- Avianca Holdings S.A.
- LATAM Airlines Group
- Copa Holdings, S.A.
- Azul Brazilian Airlines
- Gol Linhas Aéreas
- Interjet Airlines
- Volaris Airlines
- Aeromexico
- Plus Ultra Líneas Aéreas
- Sky Airline
Avianca Holdings S.A.
Avianca is recognized for its extensive route network across Latin America and North America, leveraging a modern fleet and innovative passenger service technologies to strengthen market presence and operational efficiency.
LATAM Airlines Group
LATAM stands as the largest airline in Latin America, known for its comprehensive connectivity, advanced digital platforms, and investments in sustainable aviation fuels to reduce environmental impact and enhance the customer journey.
Copa Holdings, S.A.
Copa specializes in connecting Central America and the Caribbean with North and South America, focusing on operational excellence, fleet renewal, and digital transformation to boost market competitiveness and passenger satisfaction.
Azul Brazilian Airlines
Azul offers dominant domestic coverage in Brazil with a focus on low-cost premium services, technological innovations in booking and customer engagement, along with fleet modernization emphasizing fuel efficiency and sustainability.
Gol Linhas Aéreas
Gol is renowned for its cost-efficient operations, robust domestic market share, and recent investments in digital tools and eco-friendly fleet upgrades, aiming to strengthen its competitive edge and expand regional partnerships.
Interjet Airlines
Interjet targets the low-cost full-service segment, emphasizing technological integration, fleet expansion, and strategic alliances to navigate competitive pressures and grow its footprint in Latin America’s airline landscape.
Volaris Airlines
Volaris focuses on innovative digital marketing, operational efficiency, and fleet modernization, targeting cost-sensitive travelers with a differentiated service offering and expanding route network for sustained growth.
Aeromexico
Aeromexico is known for its strong Mexico-centric network combined with international routes, investing in digital transformation initiatives, fleet upgrades, and alliances to maintain its market position.
Plus Ultra Líneas Aéreas
Plus Ultra emphasizes expanding its long-haul international services, investing in digital booking platforms, and fleet modernization to compete effectively in the evolving Latin American aviation sector.
Sky Airline
Sky Airlines is a dominant Chilean low-cost carrier, focusing on digital enhancements, fleet expansion, and strategic alliances to grow its market share within Latin America and beyond.
Strategic Business Developments
- Jan 2026 – Avianca Holdings S.A. – Embarked on fleet expansion with 15 new Airbus A320neo family aircraft – Significantly increases capacity and operational flexibility across Latin America.
- Mar 2026 – LATAM Airlines Group – Launched a comprehensive digital passenger experience platform – Enhances customer engagement and streamlines booking and service processes.
- Apr 2026 – Copa Holdings, S.A. – Formed a strategic alliance with regional tech firms for digital ticketing and loyalty programs – Strengthens competitive positioning and customer retention.
- Jun 2026 – Azul Brazilian Airlines – Invested in sustainability projects including biofuels and eco-efficient fleet upgrades – Aims to reduce carbon footprint and align with global green initiatives.
- Aug 2026 – Gol Linhas Aéreas – Announced new joint ventures with regional carriers to expand regional connectivity and cooperative revenue models – Enhances network reach and operational efficiency.
Frequently Asked Questions
What is the Latin America Full-Service Airline Market?
The Latin America Full-Service Airline Market encompasses airlines providing comprehensive flight services, including economy, premium economy, business, and first-class cabins, serving extensive route networks across Latin America with a focus on passenger comfort, luxury, and integrated travel solutions.
What is the current market size of Latin America Full-Service Airline Market?
As of 2026, the market size is estimated at USD 25.4 Billion, reflecting the region’s growing demand for premium travel and expanding aviation infrastructure, driven by rising disposable incomes and increased international tourism activities.
What factors are driving the Latin America Full-Service Airline Market?
Market growth is primarily fueled by rising middle-class populations, increased international travel, advancements in aircraft technology, supportive government policies, and strategic alliances among key carriers enhancing route connectivity and service quality.
Which region dominates the Latin America Full-Service Airline Market?
Brazil is the dominant region, accounting for the majority share, owing to its large population, robust economy, and high demand for international and domestic premium air travel, making it a central hub within the Latin American full-service airline landscape.
Which segment is expected to grow the fastest?
The premium economy and business class segments are projected to experience the fastest growth, driven by increasing business travel, tourism, and the rising preference for enhanced comfort and exclusive services among travelers.
Who are the leading companies operating in the Latin America Full-Service Airline Market?
Major players include LATAM Airlines Group, Avianca Holdings, and Copa Airlines, distinguished by their extensive route networks, strategic alliances, and investments in service innovation to maintain competitive dominance in the region.
Analyst Perspective
The Latin America full-service airline market is poised for sustained long-term growth, driven by rising regional income levels, expanding middle-class populations, and increased outbound travel demand. Investment in fleet modernization, including fuel-efficient aircraft and digital transformation, presents significant commercial opportunities, particularly through enhanced customer experience and operational efficiency. The evolving technological landscape, such as AI-driven revenue management and biometric check-ins, will reshape service delivery and competitive strategies. Regional disparities highlight the potential for growth in countries with underdeveloped aviation infrastructure, notably Brazil and Mexico, which are expected to lead market expansion. However, the landscape will face risks from geopolitical instability, fluctuating fuel prices, and regulatory challenges. Strategic investors should prioritize technological innovation and infrastructure development to secure competitive advantages. Long-term, the market’s growth will depend on regional economic stability, evolving consumer preferences, and effective market entry strategies, making Latin America a vital growth corridor for global full-service carriers seeking diversification and sustainable expansion.
