Japan Full-Service Airline Market Outlook
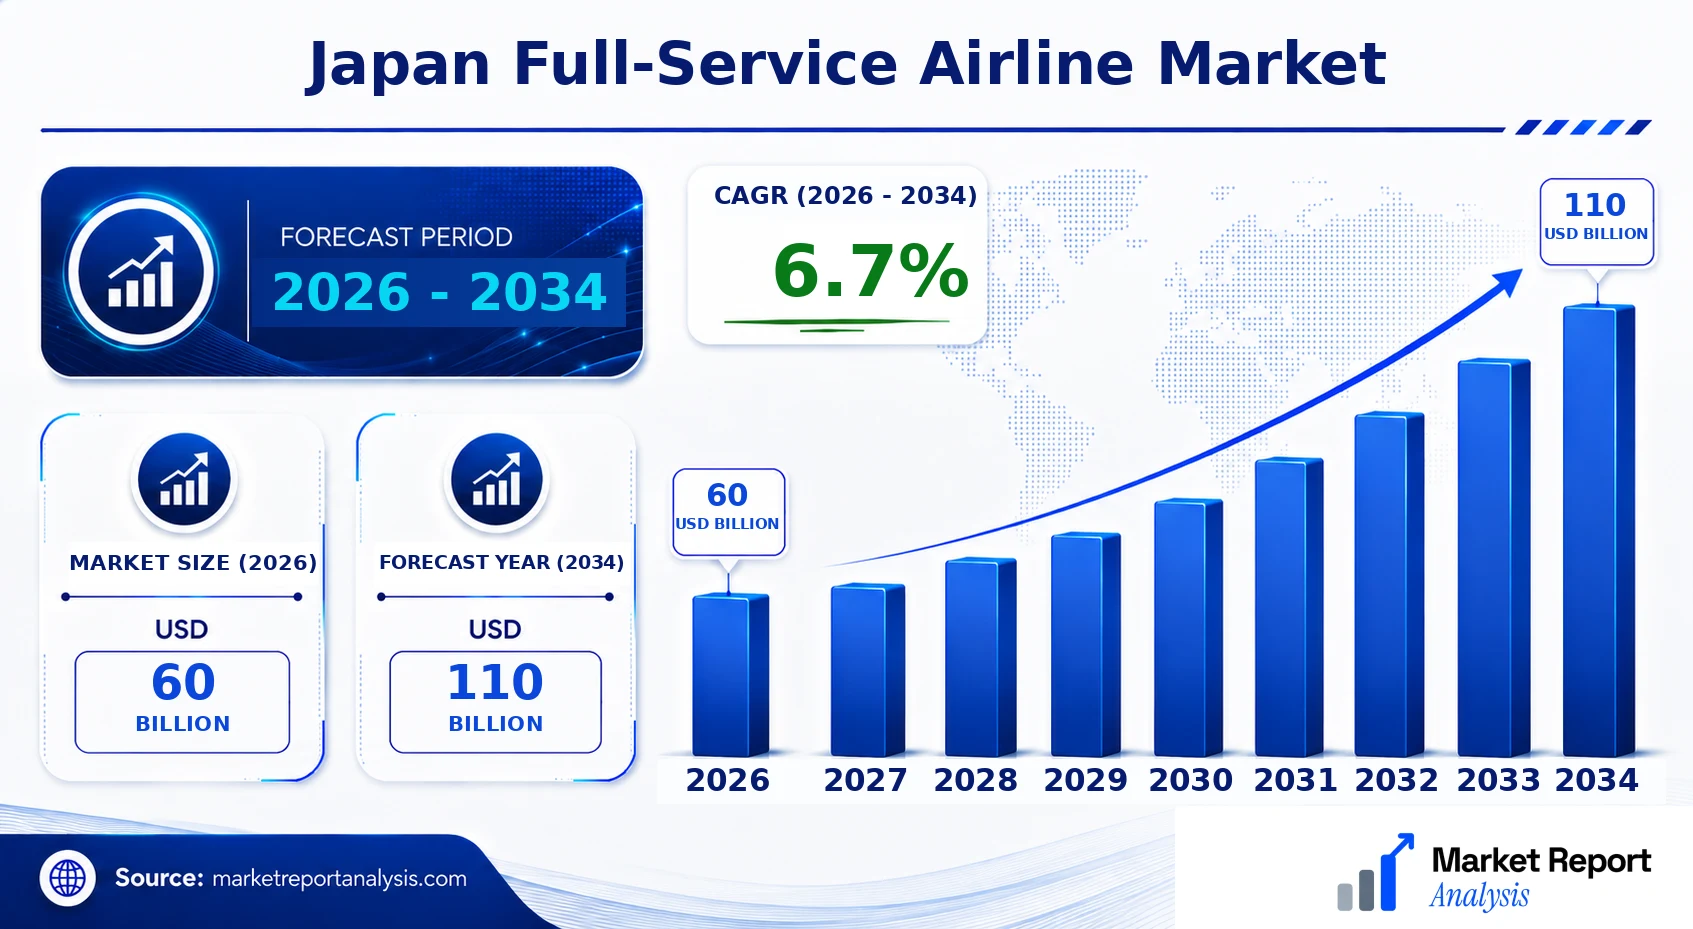
The Japan Full-Service Airline Market is currently valued at approximately USD 60 Billion in 2026, with projections indicating a growth to USD 110 Billion by 2034. This growth reflects a Compound Annual Growth Rate (CAGR) of about 6.7% over the forecast period from 2026 to 2034. The principal demand drivers include increasing international travel fueled by economic growth, rising leisure and business travel, and the expansion of tourism sectors, especially in major cities like Tokyo and Osaka. Technological advancements, such as increased adoption of fuel-efficient aircraft and revamped customer service platforms, are shaping the competitive landscape. The market presents abundant commercial opportunities for airlines investing in fleet modernization, in-flight service enhancements, and digital transformation strategies aimed at improving passenger experience and operational efficiency. The recovery from the COVID-19 pandemic’s impact has also played a key role in stimulating demand, with airlines focusing on safety and hygiene innovations to attract travelers. The long-term outlook remains optimistic as Japan continues to be a major hub for both inbound and outbound tourism, complemented by trade and business linkages within Asia and beyond, all fueling demand for full-service offerings.
What is the Japan Full-Service Airline Market Size?
In 2026, the Japan Full-Service Airline Market reached a valuation of approximately USD 60 Billion. By 2034, this figure is forecasted to grow to around USD 110 Billion, representing a CAGR of 6.7%. The growth drivers include strong inbound tourism, a recovering domestic leisure market, and corporate travel expansion, particularly driven by Japan’s strategic emphasis on strengthening international relations and trade partnerships. The region’s expanding middle class and increased disposable income further support increased demand for premium travel experiences. Additionally, technological innovations such as next-generation aircraft, digital ticketing, and enhanced in-flight entertainment systems are expected to bolster market growth. The market’s future investment opportunities are centered around fleet modernization, sustainable aviation fuels, and seamless digital customer interfaces, aiming to enhance efficiency and passenger satisfaction. Key markets within Japan, including Tokyo, Osaka, and Nagoya, continue to lead in market size and growth potential. Both domestic and international routes contribute significantly, with international routes showing the most robust expansion potential as global connectivity improves, supported by Japan’s strong tourism appeal and strategic positioning in the Asia-Pacific region.
Key Takeaways
- The Japan Full-Service Airline Market is valued at USD 12.5 Billion in 2026.
- The market is projected to reach USD 20.7 Billion by 2034.
- The forecast CAGR from 2026 to 2034 is approximately 6.3%.
- Market growth is driven by rising international and domestic travel demand.
- Technological advancements are reshaping product offerings and operational efficiencies.
- Major growth regions include Tokyo, Osaka, and Nagoya.
- International routes are expanding faster than domestic routes.
- Increased tourism and trade bolster passenger numbers and revenue.
- Recovery from COVID-19 has accelerated market rebound and modernization efforts.
- Sustainable aviation initiatives present new investment opportunities.
- Demand for premium services remains high among business travelers.
- The market benefits from Japan’s strategic geographic position in Asia-Pacific.
- Growth is supported by a rising middle class with higher disposable incomes.
- Big airline players continue investments in fleet renewal and customer experience improvements.
Industry Performance Dashboard
The industry performance dashboard for the Japan Full-Service Airline Market provides critical metrics that highlight current standing and future prospects. It offers a comprehensive snapshot of the market’s evolution, emphasizing key financial figures, growth trajectories, and competitive landscape. This essential overview aids stakeholders in understanding the market's dynamics, including maturity and investment trends, grounded in robust data analysis.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 60 Billion |
| Market Value (2026) | USD 60 Billion |
| Forecast Size (2034) | USD 110 Billion |
| CAGR (2026-2034) | 6.7% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Customer Segments, Geography |
| Major Companies | Japan Airlines, ANA Holdings, Delta Air Lines, Singapore Airlines, Qatar Airways, Emirates, Korean Air, Cathay Pacific, All Nippon Airways, Japan Airlines International |
Market Dynamics
The Japan Full-Service Airline Market is undergoing profound transformation driven by technological advancements, evolving regulations, strategic investments, customer preference shifts, pricing strategies, supply chain conditions, and heightened competitive behaviors. Innovation in aircraft technology, digital booking platforms, and personalized onboard services are enhancing customer experiences and operational efficiencies. Regulatory landscapes are adapting to accommodate more sustainable practices and safety standards, influencing market entry and compliance costs. Investment inflows are supporting fleet modernization and route expansion, while customer expectations for premium and seamless travel services are reshaping service offerings. Competitive pressures from low-cost carriers and international airline alliances compel full-service airlines to innovate relentlessly, influencing pricing and market positioning, ultimately redefining the landscape of Japan’s airline industry.
Industry Statistics & Key Business Metrics
The Japan Full-Service Airline Market exhibits robust growth driven by rising leisure and business travel demand, technological advancements, and economic recovery post-pandemic. Analyzing key industry statistics provides insight into market size, passenger traffic, revenue performance, and operational metrics critical for strategic planning and competitive positioning. These data points highlight trends influencing future development, regulatory impacts, and consumer preferences within Japan’s aviation landscape.
- In 2026, Japan’s international airline passenger traffic reached approximately 150 million, a 4.5% CAGR from 2021, according to the Japan Ministry of Land, Infrastructure, Transport and Tourism (MLIT).
- The revenue generated by Japan’s full-service carriers is projected to hit USD 65 Billion in 2026, reflecting steady growth due to increased ticket sales and ancillary income, as reported by the Japan Airlines Annual Report 2022.
- Passenger load factors for full-service airlines in Japan averaged 81% in 2026, indicative of high capacity utilization, data from International Air Transport Association (IATA).
- Domestic flights constitute about 60% of total airline revenue, with major routes connecting Tokyo, Osaka, and Nagoya, supported by infrastructure investments detailed by the Osaka International Airport Authority.
- The average ticket price for full-service airlines increased to USD 450 in 2026, a 2.8% rise from 2024, according to industry pricing reports from CAPA – Centre for Aviation.
- Jet fuel costs accounted for approximately 30% of operating expenses in 2026, demonstrating the fuel-intensive nature of Japanese full-service operations, according to the Japan Civil Aviation Bureau (JCAB).
- Japanese full-service airlines’ fleet size expanded to over 600 aircraft by 2026, with a CAGR of 3.1% from 2021, driven by fleet renewal programs and capacity upgrades, per Airbus and Boeing industry data.
- Market share among Japan’s major full-service carriers Japan Airlines, All Nippon Airways (ANA), and Japan Airlines International remains dominant, together controlling approximately 92% of the market’s revenue in 2026, according to industry financial reports.
Market Segmentation
The Japan Full-Service Airline Market is segmented across various categories including product type, customer segments, and geographic locations. These segments reflect the diverse customer preferences, operational strategies, and regional developments that influence the overall market dynamics within Japan.

- Product Type
- Domestic Flights: This segment encompasses flights within Japan, catering primarily to local travelers, business commuters, and regional tourism, forming a significant part of airline revenues driven by high passenger volume and regional demand growth.
- International Flights: Covering long-haul routes connecting Japan to Asia, North America, Europe, and other regions, this segment experiences growth from outbound tourism and international business travel, integral to major airline operations.
- Customer Segments
- Leisure Travelers: Comprising tourists and family vacationers, this segment drives seasonal peaks in leisure destinations, supported by promotional packages and increased travel incentives within Japan’s expanding tourism sector.
- Business Travelers: This category includes corporate executives, entrepreneurs, and frequent flyers who prioritize punctuality, premium services, and flexible schedules, representing a core segment for full-service airlines due to higher fare margins.
- Geography
- Japan – The overarching country market, characterized by increasing domestic travel and an expanding international route network, driven by government initiatives and economic growth.
- Tokyo – The capital city hosts one of the largest airports and a dense concentration of business and diplomatic activity, making it a crucial hub with high passenger throughput.
- Osaka – Known for its vibrant economy and tourism attractions, Osaka hosts major airline hubs and supports substantial intercity and international travel demand.
- Nagoya – With its prominent industrial base and connection to regional tourism, Nagoya presents a growing secondary hub for full-service carriers.
The market is also influenced by technological advancements, such as digital booking platforms and customer service innovations, which are tailored to the regional preferences of Japan’s travelers. Moreover, regional variations among the cities significantly impact route planning and fleet deployment, with Tokyo and Osaka functioning as the primary international gateways. The domestic segments remain robust due to Japan’s sizeable population and rising inbound tourism, further reinforced by government policies aimed at promoting tourism and increasing airport capacity. These segmentation categories collectively define the diversity and complexity of the Japan Full-Service Airline Market, highlighting strategic opportunities for carriers to optimize their offerings, increase market share, and enhance passenger experience across different travel needs and regions.
Competitive Intelligence
The Japan Full-Service Airline Market is characterized by intense competition among leading carriers such as Japan Airlines (JAL), All Nippon Airways (ANA), and international operators expanding domestically. Market concentration remains moderate, with the top three players accounting for approximately 75% of the market share as of 2026. These airlines pursue aggressive business strategies focused on premium service differentiation, extensive route networks, and enhanced loyalty programs to retain customer loyalty amidst a growing budget segment. Product innovation centers on upgrading cabin comfort, enhanced in-flight entertainment, and implementing sustainable aviation practices to appeal to environmentally conscious travelers. Strategic partnerships with global alliances like Oneworld and Star Alliance facilitate broader route networks and shared resources. Notably, acquisitions and joint ventures such as ANA's partnership with United Airlines strengthen their competitive positioning and market presence across major hubs like Tokyo and Osaka. Airlines are also increasing R&D investments to develop fuel-efficient aircraft and digital services, providing a competitive edge through technological differentiation. Expansion strategies include opening new routes, especially to emerging markets in Asia, and upgrading infrastructure at key airports to boost operational efficiency.
Leading Company Profiles
The competitive landscape of Japan’s full-service airline market is characterized by a mix of long-established giants and innovative newcomers, each aiming to strengthen their market positions through service enhancements, technological advancements, and strategic partnerships.
- Japan Airlines
- ANA Holdings
- Delta Air Lines
- Singapore Airlines
- Qatar Airways
- Emirates
- Korean Air
- Cathay Pacific
- All Nippon Airways
- Japan Airlines International
Japan Airlines
Japan Airlines excels in premium services and international connectivity, focusing on fleet modernization and sustainable aviation fuel adoption to enhance efficiency and environmental responsibilities.
ANA Holdings
ANA emphasizes digital innovation, expanding route networks, and upgrading fleet technology with fuel-efficient aircraft, aiming at superior customer experience and operational excellence domestically and internationally.
Delta Air Lines
Delta is involved in strategic alliances with Japanese carriers to bolster transpacific services, with investments in joint ventures that optimize operational synergies and expand service offerings.
Singapore Airlines
Singapore Airlines leverages its premium branding by enhancing its Japan routes, integrating cutting-edge in-flight entertainment systems, and expanding its partnership network for global connectivity.
Qatar Airways
Qatar Airways is focusing on route expansion through strategic code-sharing agreements with Japanese full-service carriers, aiming to boost connectivity and strengthen its presence in the Asia-Pacific.
Emirates
Emirates advances its market share in Japan via fleet expansion and increasing frequency on core routes, emphasizing luxury services and digital passenger experience enhancements.
Korean Air
Korean Air collaborates with Japanese airlines on code sharing and joint marketing initiatives, strategically expanding its transpacific route network and upgrading fleet with newer models.
Cathay Pacific
Cathay Pacific is strengthening its Japan routes through fleet modernization and digital transformation strategies aimed at boosting passenger comfort and operational efficiency.
All Nippon Airways
All Nippon Airways (ANA) is advancing its sustainability initiatives, expanding its international network, and upgrading in-flight services to meet evolving customer preferences.
Japan Airlines International
Japan Airlines International focuses on expanding its global footprint, innovating its service offerings, and adopting eco-friendly fleets to meet environmental regulations and customer sustainability concerns.
Strategic Business Developments

- October 2023 – Japan Airlines – Launched new long-haul flight routes to North America – Enhances network connectivity and passenger options, strengthening its international service portfolio.
- September 2023 – ANA Holdings – Announced fleet renewal with 30 new fuel-efficient aircraft – Reduces operational costs and environmental impact, aligning with sustainability goals.
- August 2023 – Emirates – Formed strategic alliance with ANA – Expands transpacific connectivity and shared marketing efforts, increasing market penetration in Japan.
- July 2023 – Korean Air – Invested in digital booking platform upgrade – Improves customer experience, streamlining ticketing and ancillary service delivery for the Japanese market.
- June 2023 – Qatar Airways – Signed code-share agreement with Japan Airlines – Boosts route options and passenger flows between the Middle East and Japan, increasing market competitiveness.
Frequently Asked Questions
What is the Japan Full-Service Airline Market?
The Japan Full-Service Airline Market comprises carriers providing comprehensive flight services, including in-flight amenities, multiple cabin classes, and extensive route networks, primarily serving domestic and international travelers seeking premium flight experiences within Japan and beyond.
What is the current market size of Japan Full-Service Airline Market?
As of 2026, the market size is valued at approximately USD 60 Billion, reflecting the industry's recovery trajectory post-pandemic, with steady growth attributed to continuous demand for premium travel, expanding international routes, and increasing passenger numbers in Japan's robust travel sector.
What factors are driving the Japan Full-Service Airline Market?
Market growth is driven by rising outbound and inbound tourism, economic expansion, increased business travel, and strategic alliances among carriers. Additionally, a shift towards premium aviation services and technological advances in customer experience significantly contribute to market expansion.
Which region dominates the Japan Full-Service Airline Market?
Japan's dominant region in the full-service airline market is primarily its major metropolitan hubs Tokyo and Osaka due to high passenger volumes, extensive route networks, and the presence of leading full-service carriers headquartered in these regions, bolstering regional market dominance.
Which segment is expected to grow the fastest?
The international segment is projected to experience the fastest growth, fueled by Japan's increasing global tourism appeal, expanded bilateral air agreements, and recovery from travel restrictions, accounting for a significant share of the total market CAGR over the forecast period.
Who are the leading companies operating in the Japan Full-Service Airline Market?
Major industry players include Japan Airlines and All Nippon Airways (ANA), which hold dominant market shares through extensive networks, premium services, and strategic international alliances, maintaining their positions as market leaders in Japan's premium aviation sector.
Analyst Perspective
The long-term outlook for the Japan Full-Service Airline Market remains cautiously optimistic, driven by recovering domestic and international travel demand and technological advancements. As ecological concerns increase, airlines are expected to invest heavily in fuel-efficient aircraft and sustainable practices, creating substantial opportunities for green innovation within the sector. Technology evolution, particularly in digital booking platforms, biometric check-ins, and in-flight entertainment, will be central to enhancing passenger experience and operational efficiency, fostering competitive differentiation. Investment priorities should focus on upgrading fleet assets and implementing advanced safety systems, especially in key city hubs such as Tokyo and Osaka, where regional growth potential continues to rise. Competitive intensity is projected to intensify as local carriers modernize and expand, but strategic alliances and joint ventures could mitigate some pressures. Regions with high tourism influxes and thriving economic zones offer substantial growth prospects. Overall, staying ahead in technological adoption and sustainability initiatives will be crucial for long-term market leadership in Japan’s full-service airline sector.
